
 Hardfacing Rods Market | 2026-2036
Hardfacing Rods Market Size, Share, and Industry Trends Forecast 2026-2036
Hardfacing Rods Market Insights
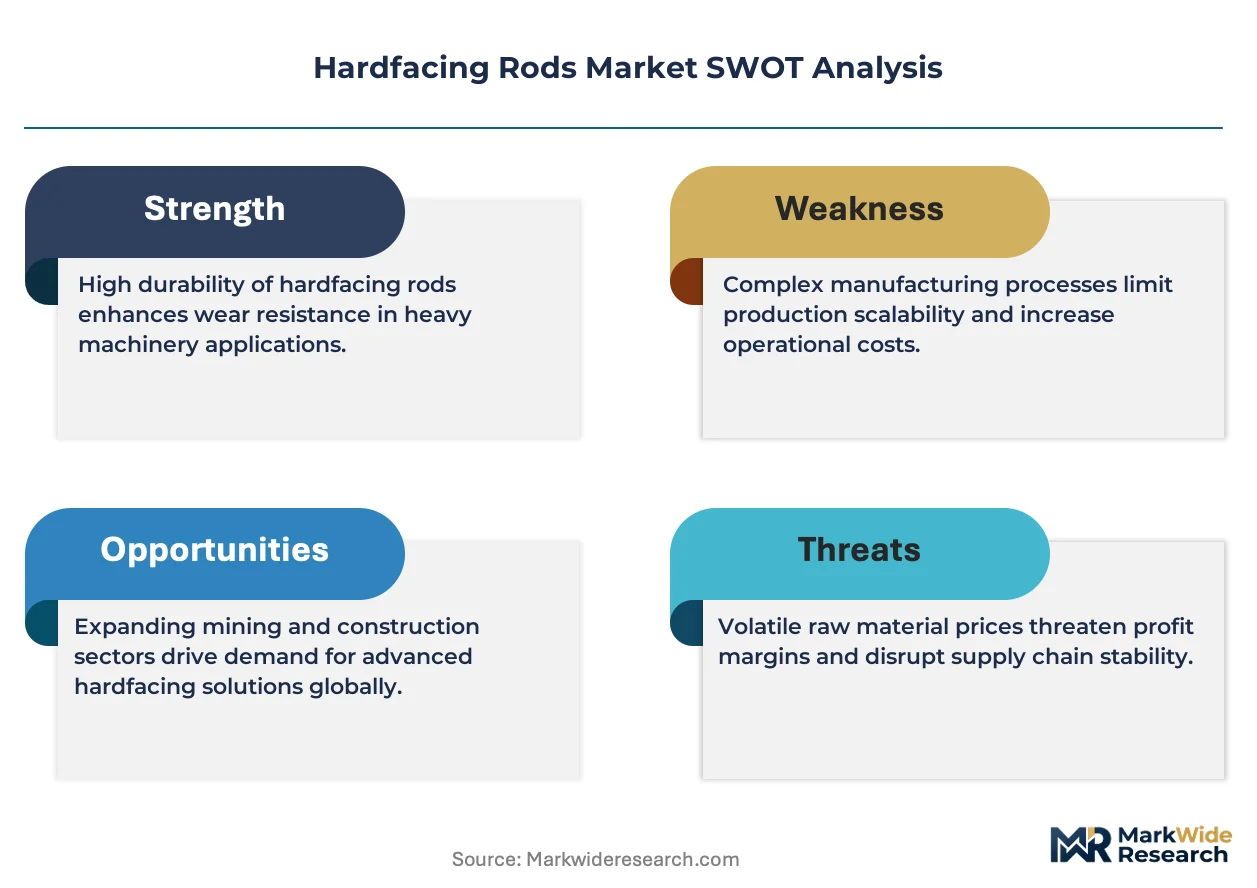
AWS A5.13 classification for surfacing welding electrodes is reorganizing competitive entry barriers for hardfacing rod suppliers. Kennametal Inc. leverages its carbide metallurgy heritage to dominate premium mining applications. The Lincoln Electric Company anchors North American distribution through integrated welding equipment channels. ESAB competes across European shipyards with flux-cored formulations certified to offshore standards.
Hardfacing rods are consumable filler metals, typically 2.5–5.0 mm in diameter, deposited by shielded metal arc welding or gas metal arc welding to rebuild worn surfaces with wear-resistant alloys containing chromium, tungsten, or vanadium carbides. Their primary purpose extends service life of high-abrasion components in earthmoving, mineral processing, and oil extraction equipment. Flux-cored rods command the largest volume share across mining equipment applications due to deposition efficiency advantages in field repair conditions. Carbide-based material compositions capture premium pricing in oil and gas directional drilling tools where extreme gouging resistance justifies higher alloy costs.
AWS A5.13 and ISO 14700 govern rod classification and mechanical property verification, while OSHA permissible exposure limits for hexavalent chromium constrain welding fume management investments. EPA hazardous air pollutant standards for manganese emissions are pressuring fabricators toward low-manganese formulations or enhanced local exhaust ventilation. Stakeholders must monitor evolving alloy substitution patterns as REACH authorization lists in Europe restrict cobalt compound usage in certain cobalt-based rod formulations.
Market Dynamics
AWS A5.13 classification revisions are forcing suppliers to recertify entire product portfolios, compressing margins for mid-tier manufacturers while locking in incumbent advantages for those with pre-positioned metallurgical laboratories.
Growth Catalysts
- Permian Basin drill bit reconditioning cycles:Oilfield services corridors in Texas and New Mexico generate continuous demand for chromium carbide overlays on directional drilling tools.
- REACH authorization pressure on cobalt compounds:European fabricators are accelerating substitution trials toward iron-based alternatives, expanding addressable markets for compliant rod formulations.
- Flux-cored deposition efficiency:Mining maintenance crews in Pilbara iron ore operations favor field-deployable wire formats over stick electrodes for pit-side repairs.
Market Restraints
- Ferroalloy price volatility:Tungsten and vanadium feedstock costs swing with Chinese export quota decisions, squeezing formulation margins.
- Hexavalent chromium exposure limits:OSHA permissible exposure standards mandate capital-intensive local exhaust ventilation, raising barrier-to-entry for small fabrication shops.
- Plasma-transferred arc overlay competition:Mechanized PTA systems threaten manual SMAW rod applications in high-volume mining equipment rebuild facilities.
Strategic Opportunities
- Chilean copper mine electrification:Battery-electric haul truck fleets require novel wear-resistant materials for lighter chassis components.
- EU Green Deal carbon border adjustments:Low-carbon smelting certifications create premium positioning for rod producers with Scope 3 verified supply chains.
- Drone-assisted weld monitoring:Remote inspection protocols enable predictive maintenance contracts linking rod suppliers directly to equipment uptime guarantees.
Industry Challenges
- Welding procedure qualification bottlenecks:AWS D1.1 certification timelines stretch 12-18 months for new alloy compositions, delaying product commercialization.
- Interoperability with legacy SMAW power sources:Next-generation flux-cored wires demand inverter-based welding machines that many field repair crews have not yet deployed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hardfacing Rods Market |
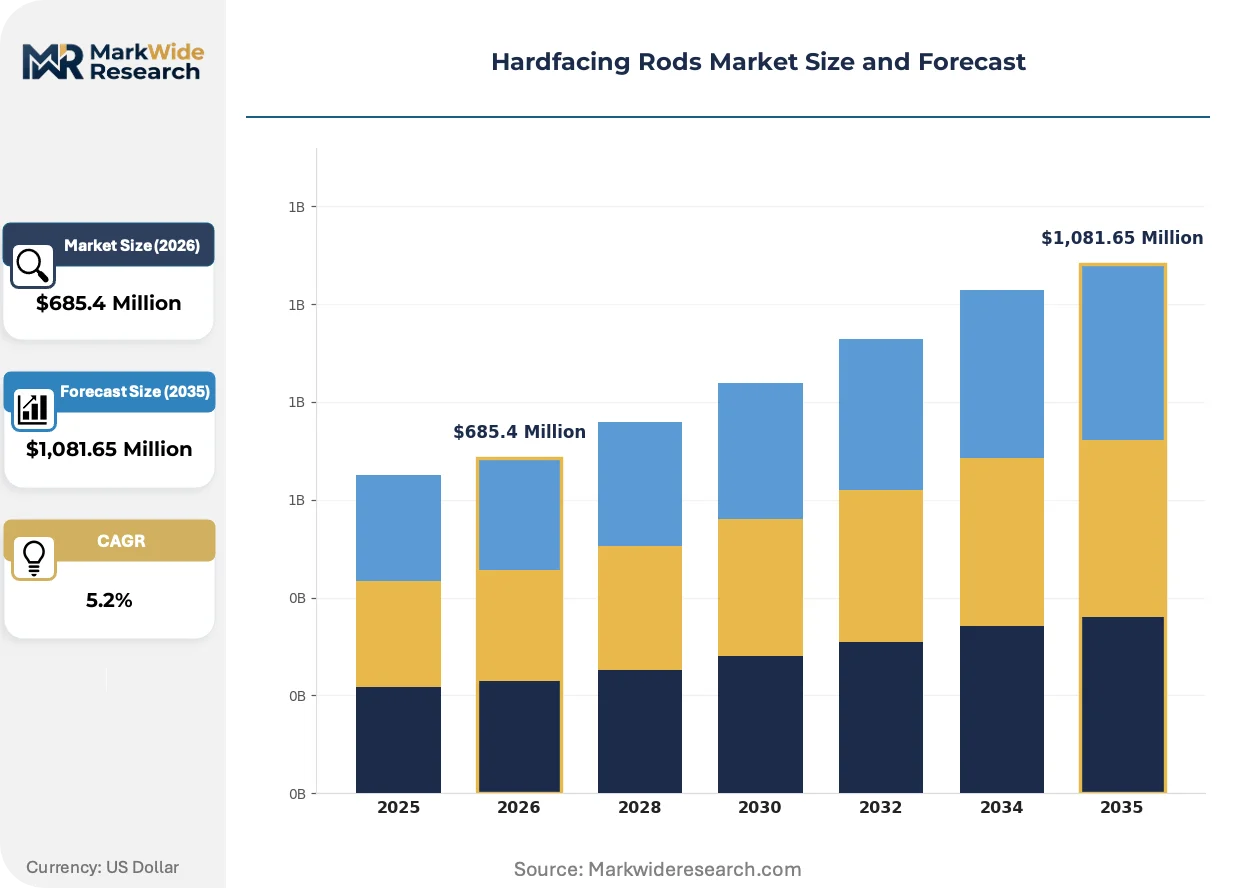
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,081.65 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flux-Cored, Solid Wire, Composite, Strip Electrodes Application: Mining Equipment, Construction Tools, Agriculture Implements, Metal Fabrication Industry Vertical: Oil & Gas, Marine Engineering, Power Generation, Heavy Machinery Material Composition: Nickel-Based, Cobalt-Based, Iron-Based, Carbide-Based |
| Companies Covered | Kennametal Inc., The Lincoln Electric Company, ESAB, Castolin Eutectic, Waldun, Illinois Tool Works Inc., Stellite Technologies, Welding Alloys Group, Haynes International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hardfacing Rods Market Trends and Innovations
Metallurgical formulation science is converging with digital weld monitoring, enabling real-time alloy deposition control that was previously impossible in field repair environments.
Metal-cored wire technology is miniaturizing carbide particle distribution to sub-micron scales, achieving hardness gradients previously reserved for laser cladding. Mining equipment rebuilders in Western Australia are adopting these formulations for crusher liner repairs. The technology is miniaturizing the performance gap between manual field repairs and shop-based precision overlay systems.
EPA hazardous air pollutant standards for manganese emissions are compelling fabricators toward low-manganese formulations or enhanced fume extraction infrastructure. Smaller job shops face disproportionate compliance costs. North American structural steel contractors are consolidating purchasing around suppliers with pre-certified low-manganese portfolios.
Maintenance procurement teams are unbundling consumable supply from equipment OEM service contracts, creating direct purchasing relationships with rod manufacturers. Mine site maintenance managers now specify AWS A5.13 classifications independently of original equipment supplier recommendations. This pattern concentrates in Australian iron ore and Chilean copper operations where in-house welding engineering capabilities are most mature.
Hardfacing Rods Market Segmentation
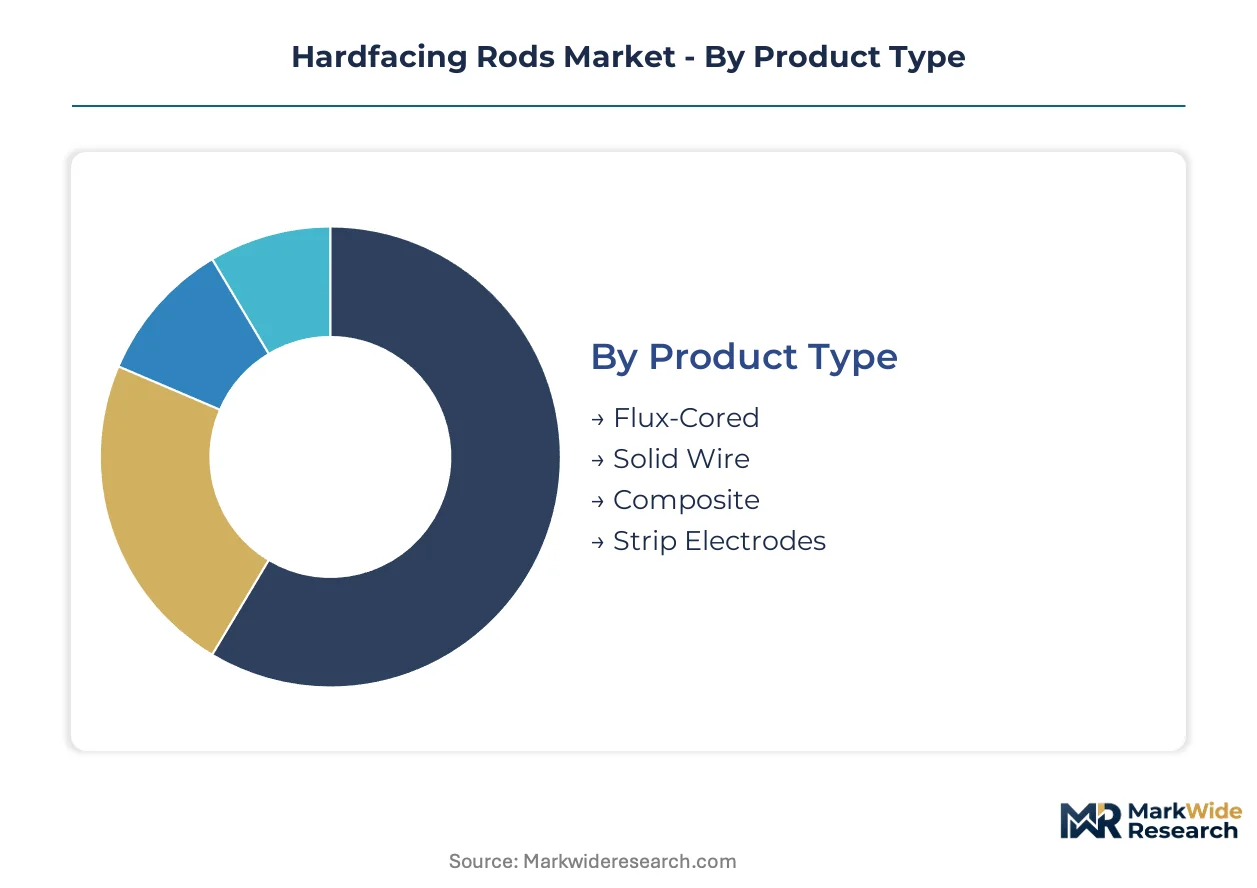
Hardfacing rod procurement patterns diverge sharply between field repair crews and shop-based rebuild facilities. Channel configuration—direct mill supply versus welding distributor networks—shapes which formulations reach which end-users.
Product Type:
Flux-cored and solid wire formats flow through distinct channel architectures, with field-deployable products favoring welding supply distributors while precision formulations move direct to OEM rebuild centers.
- Flux-Cored:Tubular wire construction with mineral flux core enables all-position welding without external shielding gas. Pilbara iron ore maintenance crews specify these for pit-side crusher repairs where wind disrupts gas-shielded processes. Deposition efficiency advantages justify 15-20% price premiums over stick electrodes in Australian mining procurement.
- Solid Wire:Homogeneous alloy construction requires external shielding gas but delivers cleaner weld metal with lower fume generation. Shop-based rebuild facilities in Permian Basin oilfield services corridors favor these for automated reconditioning cells where ventilation systems capture manganese emissions.
- Composite:Encapsulated carbide particles in ductile matrix combine abrasion resistance with impact toughness.
- Strip Electrodes:Wide flat cross-sections deposit broad surfacing layers in single passes for large crusher jaws.
Flux-cored dominates installed base. Solid wire is where expansion concentrates.
Application:
Cost tier stratification separates premium-certified consumables for regulated industries from economy formulations in general fabrication.
- Mining Equipment:Extreme abrasion environments on haul truck bodies and shovel buckets demand chromium carbide overlays with 58-62 HRC hardness. Chilean copper concentrators specify AWS A5.13 certified rods for SAG mill liner repairs under 12-month uptime guarantees.
- Construction Tools:Impact loading on hydraulic breaker bits and bucket teeth requires tungsten carbide composites balancing hardness with fracture resistance. Korean tunneling contractors drive specification toward iron-based formulations as cobalt prices fluctuate.
- Agriculture Implements:Soil abrasion on plowshares and cultivator points favors economical iron-based hardfacing for seasonal repair cycles.
- Metal Fabrication:General-purpose wear pads and guides accept lower alloy content with shorter service life expectations.
Mining equipment commands premium pricing tiers. Construction tools are climbing the fastest.
Industry Vertical:
Customer type segmentation separates specification-driven buyers with in-house welding engineers from price-sensitive procurement teams.
- Oil & Gas:Directional drilling tool reconditioning demands carbide-based formulations certified to NACE MR0175 for sour service compatibility. Permian Basin independent operators now specify rods independently of OEM service contracts.
- Marine Engineering:Saltwater corrosion resistance drives nickel-based selections for dredge pump impellers and cutter heads.
- Power Generation:Coal pulverizer rolls and boiler tube shields require high-temperature oxidation resistance in cobalt-based formulations.
- Heavy Machinery:General earthmoving equipment rebuilders balance performance against inventory simplification across mixed fleets.
Oil & gas anchors specification complexity. Power generation faces substitution pressure from renewable capacity additions.
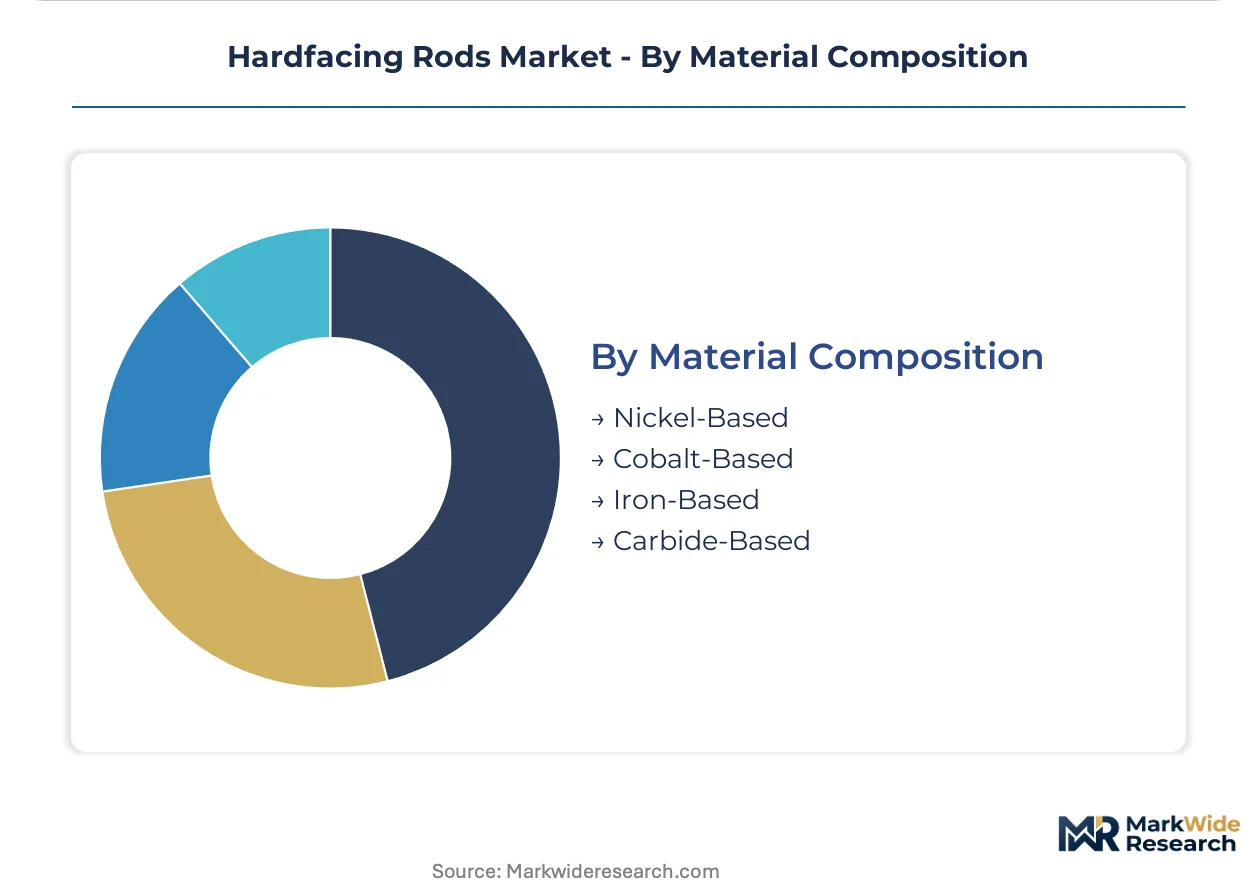
Material Composition:
Supply concentration in ferroalloy feedstocks shapes margin structures across chemistry families.
- Carbide-Based:Tungsten and chromium carbide particles in metallic matrix deliver extreme abrasion resistance for drill bit cutting structures. Chinese export quota decisions on tungsten concentrates directly impact formulation costs for Permian Basin reconditioning shops.
- Iron-Based:Martensitic and austenitic iron alloys offer cost-effective wear resistance without strategic material dependencies. European fabricators accelerate trials here as REACH authorization lists constrain cobalt compound usage.
- Nickel-Based:Corrosion-resistant matrices protect against chemical attack in marine and chemical processing environments.
- Cobalt-Based:Superior hot hardness retention serves valve seats and forging dies in high-temperature applications.
Carbide-based holds premium positioning. Iron-based is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Incentive structures for domestic manufacturing and critical mineral processing are redirecting hardfacing rod procurement patterns across major industrial economies. National mining codes and environmental compliance frameworks now determine supplier qualification timelines more than raw material availability alone.
United States
Permian Basin oilfield service corridors in Texas and New Mexico drive continuous consumption for drill bit reconditioning cycles. OSHA hexavalent chromium exposure limits mandate capital-intensive ventilation upgrades for fabrication shops. Houston-area rebuild facilities now specify low-manganese formulations to preempt EPA hazardous air pollutant enforcement.
Australia
Pilbara iron ore maintenance crews favor flux-cored wire formats for pit-side crusher repairs where wind disrupts gas-shielded processes. The country's national mining regulator emphasizes surface equipment uptime guarantees under 12-month performance contracts. Western Australian operations concentrate procurement authority with site-based welding engineers rather than OEM service channels.
Chile
Copper concentrators specify AWS A5.13 certified rods for SAG mill liner repairs under stringent uptime commitments. Battery-electric haul truck electrification programs are creating specification demand for novel wear-resistant materials on lighter chassis components. Antofagasta and Calama maintenance hubs unbundle consumable supply from equipment OEM contracts.
Germany
Ruhr Valley fabrication clusters face REACH authorization pressure on cobalt compounds, accelerating substitution trials toward iron-based alternatives. ECHA restriction proposals on tungsten carbide dust exposure are reshaping workshop ventilation investments. Düsseldorf-area distributors consolidate purchasing around suppliers with pre-certified low-manganese portfolios.
China
Tungsten concentrate export quota decisions directly impact formulation costs for international reconditioning shops dependent on Chinese ferroalloy feedstocks. The Ministry of Ecology and Environment enforces dual carbon goals that constrain smelter energy intensity for carbide production. Zhengzhou and Changsha manufacturing clusters supply domestic mining equipment rebuilders with cost-optimized iron-based formulations.
Hardfacing Rods Market Competitive Landscape
Player mix skews toward integrated welding equipment manufacturers and specialized carbide metallurgy houses. Market structure concentrates around three to five dominant suppliers with pre-positioned metallurgical laboratories capable of AWS A5.13 recertification cycles. Strategic archetypes include diversified industrial conglomerates with captive distribution networks, pure-play hardfacing specialists with deep alloy formulation heritage, and regional fabricators competing on formulation flexibility. Dominant competitive moves encompass backward integration into ferroalloy sourcing and technology licensing agreements for metal-cored wire miniaturization.
Among integrated welding equipment manufacturers, The Lincoln Electric Company and Illinois Tool Works Inc. occupy positions anchored through distributor network control. ESAB represents the European specialist archetype with offshore-certified flux-cored formulations. Kennametal Inc. exemplifies the carbide metallurgy heritage model, while Castolin Eutectic and Welding Alloys Group sit within the formulation-flexibility tier serving maintenance procurement teams directly.
| Leading Market Players |
|---|
| Kennametal Inc. |
| The Lincoln Electric Company |
| ESAB |
| Castolin Eutectic |
| Waldun |
| Illinois Tool Works Inc. |
| Stellite Technologies |
| Welding Alloys Group |
| Haynes International, Inc. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Pilbara iron ore operators and Australian welding distributors lock in both ferroalloy supply access and eighteen-month price visibility, insulating large mining maintenance crews from spot market volatility in tungsten concentrate markets. These arrangements concentrate procurement power with site-based welding engineers who bypass OEM service channels entirely.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with AWS A5.13 compliance commanding fifteen to twenty percent premiums over uncertified formulations in Australian mining procurement. Three-tier pricing structure across premium carbide-based, standard iron-based, and economy chromium formulations reflects deposition efficiency differentials and fume generation profiles. Cost compression in the economy tier is intensifying because Chinese export quota decisions on ferroalloy feedstocks squeeze formulation margins for mid-tier manufacturers. Small fabrication shops in North America exhibit the highest price sensitivity due to capital-intensive ventilation upgrades mandated by OSHA hexavalent chromium exposure limits.
Supply Chain Analysis
Strategic stockpile preferences dominate among Permian Basin oilfield services corridors, where drill bit reconditioning cycles demand uninterrupted carbide rod availability despite Chinese tungsten concentrate export volatility. Supply draws from China for ferroalloy feedstocks, Australia for chromium mining operations, and Germany for precision flux-cored wire manufacturing. Single-source vulnerability concentrates in Zhengzhou and Changsha smelting clusters where Ministry of Ecology and Environment dual carbon goals constrain energy intensity for carbide production. Distribution runs through welding supply distributors for field-deployable formats and direct mill supply for OEM rebuild centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in maintenance procurement teams unbundling consumable supply from equipment OEM contracts, creating direct purchasing relationships with rod manufacturers across Australian iron ore and Chilean copper operations.
For Market Incumbents: Shield premium positioning through backward integration into ferroalloy sourcing and pre-positioned AWS A5.13 metallurgical laboratories capable of rapid recertification cycles. Plasma-transferred arc overlay systems threaten manual SMAW rod applications in high-volume mining equipment rebuild facilities, demanding defensive technology licensing agreements for metal-cored wire miniaturization. For New Entrants and Emerging Players: Anchor in Chilean copper concentrator maintenance hubs where battery-electric haul truck electrification programs create specification demand for novel wear-resistant materials on lighter chassis components. The most penetrable segment sits with construction tools applications where Korean tunneling contractors accelerate substitution trials toward iron-based formulations as cobalt prices fluctuate, favoring direct sales relationships with site welding engineers over distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward formulation-flexibility specialists with deep alloy heritage and established REACH-compliant portfolios capable of capturing European substitution demand away from cobalt-based formulations. Long-term viability hinges on Scope 3 verified supply chains positioning for EU Green Deal carbon border adjustments. The signal to watch is AWS D1.1 structural welding code revision timelines compressing competitive entry barriers for certified consumables.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferroalloy Sourcing | Captive tungsten concentrate supply from Chinese export quota exposure stabilizes margin structures for Permian Basin reconditioning shops. |
| AWS A5.13 Metallurgical Laboratory Investment | Pre-positioned certification capabilities lock in incumbent advantages during twelve-to-eighteen-month recertification timelines for new alloy compositions. |
| Low-Manganese Formulation Portfolio Expansion | Pre-certified portfolios capture North American structural steel contractor consolidation around EPA hazardous air pollutant compliance. |
| Metal-Cored Wire Miniaturization Licensing | Sub-micron carbide particle distribution technology bridges performance gaps between manual field repairs and shop-based precision overlay systems. |
| Drone-Assisted Weld Monitoring Partnership | Remote inspection protocols enable predictive maintenance contracts linking rod suppliers directly to equipment uptime guarantees in Western Australian operations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with maintenance directors at Pilbara iron ore operations, welding engineers at Chilean copper concentrators, procurement leads at Permian Basin oilfield services firms, and aftermarket service heads at heavy equipment OEMs; and secondary validation through AWS certification databases, EPA hazardous air pollutant enforcement records, ECHA REACH authorization lists, and Chinese Ministry of Ecology and Environment dual carbon policy disclosures. Bottom-up triangulation across product-type volume estimates and top-down reconciliation against end-use industry expenditure patterns anchored the analytical framework.
Across the analysis window, the forecasting framework modeled hardfacing rod demand through segmentation dimensions spanning product format, material composition, application severity, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis and maintenance budget trajectories at named mining operations. Industry-specific inputs incorporated drill bit reconditioning frequency in Permian Basin directional drilling and SAG mill liner repair intervals under Chilean copper concentrator uptime guarantees.
Material uncertainties — ferroalloy export quota decisions, OSHA hexavalent chromium exposure limit revisions, and plasma-transferred arc overlay adoption rates — sit outside the modeled envelope. Forecasts reflect assumptions around maintenance procurement unbundling velocity and AWS D1.1 code revision implementation timelines. Revision becomes warranted when REACH authorization pressure on cobalt compounds accelerates beyond modeled substitution trial velocities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Metal Based Safety Gratings Market
Industrial Materials
Global Melamine Faced Chipboard (MFC) Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
Lip Seals Market
Industrial Materials
High Pressure Braided Tubing (HPBT) Market
Industrial Materials
Industrial Anti-Fatigue Mat Market
Industrial Materials
Wood Shavings Market
Industrial Materials
Plain Bearing Market
Industrial Materials
Global High Pressure Seals Market
Industrial Materials
Plastic Injection Mold Market
Industrial Materials
Industrial Wax Market
Industrial Materials
Continuous Mesh Belt Furnaces Market
Industrial Materials
Global Industrial Dust Collector Market
Industrial Materials
Global Melamine Market
Industrial Materials
Couplings Market