
 US Nitrile Gloves Market | 2026-2036
US Nitrile Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
US Nitrile Gloves Market Insights
Healthcare procurement is bifurcating from bulk commodity purchasing toward contract-grade specification buying. Medline Industries controls extensive domestic distribution networks serving integrated delivery networks. Kimberly-Clark Corporation differentiates through synthetic formulation R&D and hospital-branded glove programs. Cardinal Health anchors its position via direct-to-system contracting with the largest US hospital chains.
Nitrile gloves are synthetic rubber hand protection devices formulated from acrylonitrile-butadiene copolymer, offering puncture resistance superior to latex and chemical protection against oils, solvents, and biological hazards; they serve critical functions in infection control, occupational safety, and contamination prevention across medical and industrial environments. Examination gloves dominate volume flows through healthcare supply chains, while industrial gloves command wider margins due to specialized chemical resistance ratings and longer wear-cycle requirements. FDA Approved certification functions as a non-negotiable market gate for medical applications, whereas ISO Certified status opens access to laboratory and research institution procurement channels where quality management system validation carries contractual weight.
FDA medical device regulations and ASTM D6319 standards govern barrier performance claims, while OSHA bloodborne pathogen mandates drive baseline demand in clinical settings. The Environmental Protection Agency scrutinizes manufacturing effluent from nitrile production facilities, adding compliance costs that favor scaled domestic producers. Stakeholders must monitor how domestic content requirements in federal healthcare procurement evolve against Southeast Asian manufacturing cost advantages.
Market Dynamics
FDA enforcement of ASTM D6319 barrier performance standards is compressing supplier margins while hospital procurement consolidation in the Southeast concentrates buying power among integrated delivery networks.
Growth Catalysts
- OSHA Bloodborne Pathogen Standard:Federal mandates for universal precautions in clinical settings sustain baseline demand across outpatient clinics, dental practices, and long-term care facilities.
- Acrylonitrile-butadiene formulation advances:Thinner-walled gloves achieving equivalent puncture resistance reduce raw material consumption per unit while maintaining protection ratings.
- Atlanta-Charlotte distribution cluster:Proximity to major hospital networks and medical supply wholesalers accelerates inventory velocity and reduces fulfillment lead times.
Market Restraints
- Acrylonitrile monomer price volatility:Petrochemical feedstock exposure ties glove production costs to crude oil futures and refinery capacity utilization.
- Southeast Asian manufacturing concentration:Malaysia and Thailand host dominant nitrile glove capacity, exposing US buyers to ocean freight disruptions and currency fluctuations.
- Thick-walled glove substitution:Vinyl alternatives compete for low-risk examination applications where tactile sensitivity requirements are minimal.
Strategic Opportunities
- Texas Gulf Coast petrochemical corridor:Proximity to butadiene and acrylonitrile production enables backward integration into synthetic rubber supply chains.
- Industrial chemical handling applications:Laboratory research institutions and pharmaceutical manufacturing facilities require specialized chemical permeation resistance beyond standard medical grades.
- Federal domestic content preferences:VA and DOD procurement guidelines increasingly weight US-manufactured inventory in contract award criteria.
Industry Challenges
- FDA 510(k) clearance timelines:Medical device premarket notification reviews extend 12-18 months for novel glove formulations or manufacturing process changes.
- Cleanroom-compatible production retrofitting:Semiconductor and biotechnology end-uses require ISO 14644 Class 7 or better manufacturing environments, demanding significant facility capital expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Nitrile Gloves Market |
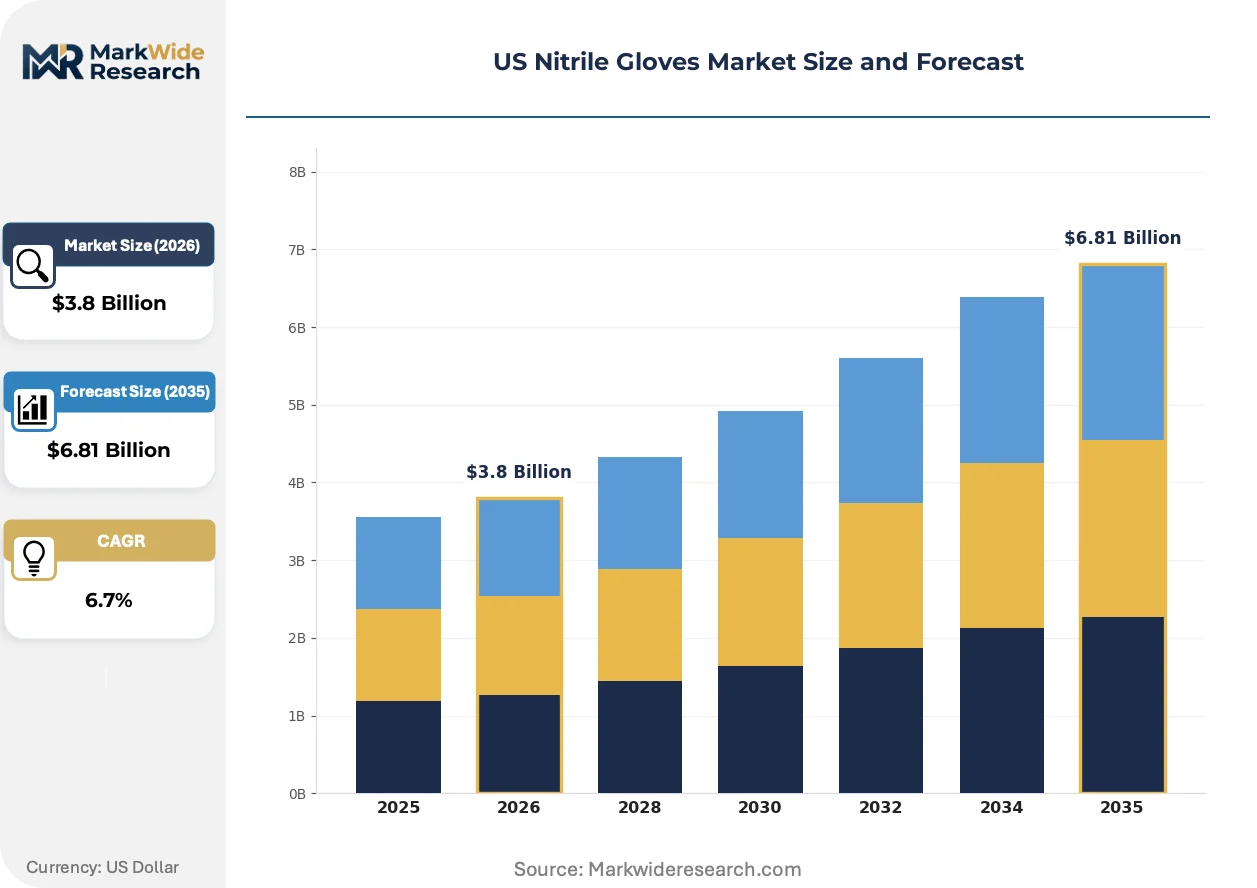
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Examination Gloves, Industrial Gloves, Surgical Gloves, Specialty Gloves End User: Healthcare Facilities, Laboratories, Food Services, Manufacturing Certification: FDA Approved, ISO Certified, CE Marked, AAMI Level Size: Small, Medium, Large, Extra Large |
| Companies Covered | Ansell Ltd., Top Glove Corporation Bhd, Hartalega Holdings Berhad, Supermax Corporation Berhad, Kimberly-Clark Corporation, Cardinal Health, Medline Industries, Inc., Ammex Corporation, Superior Gloves, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Nitrile Gloves Market Trends and Innovations
Synthetic rubber chemistry and federal procurement policy are restructuring how gloves move from polymer production to clinical use, with three developments commanding strategic attention.
Chlorinated surface treatment technology is decomposing the traditional powdered-glove residual market by eliminating the need for cornstarch or synthetic donning agents. Ambulatory surgery centers and dermatology practices are converting to polymer-coated chlorinated gloves at accelerated rates. This shift is decomposing historical revenue streams for donning powder suppliers while compressing allergen liability exposure for healthcare employers.
FDA guidance on powder-free medical gloves is tightening enforcement thresholds for particulate residue limits in examination-grade products. Manufacturers must validate surface treatment consistency across production lots to maintain 510(k) clearance status. Southeast-based hospital systems are now requiring third-party powder-free certification documentation in request-for-proposal specifications.
Direct-to-system contracting is displacing traditional distributor-mediated purchasing for high-volume integrated delivery networks. Cardinal Health and Medline Industries are restructuring field sales organizations to support embedded inventory management programs. This pattern concentrates most visibly in North Carolina and Georgia, where hospital consolidation has created multi-facility purchasing entities exceeding ten million units annually.
US Nitrile Gloves Market Segmentation
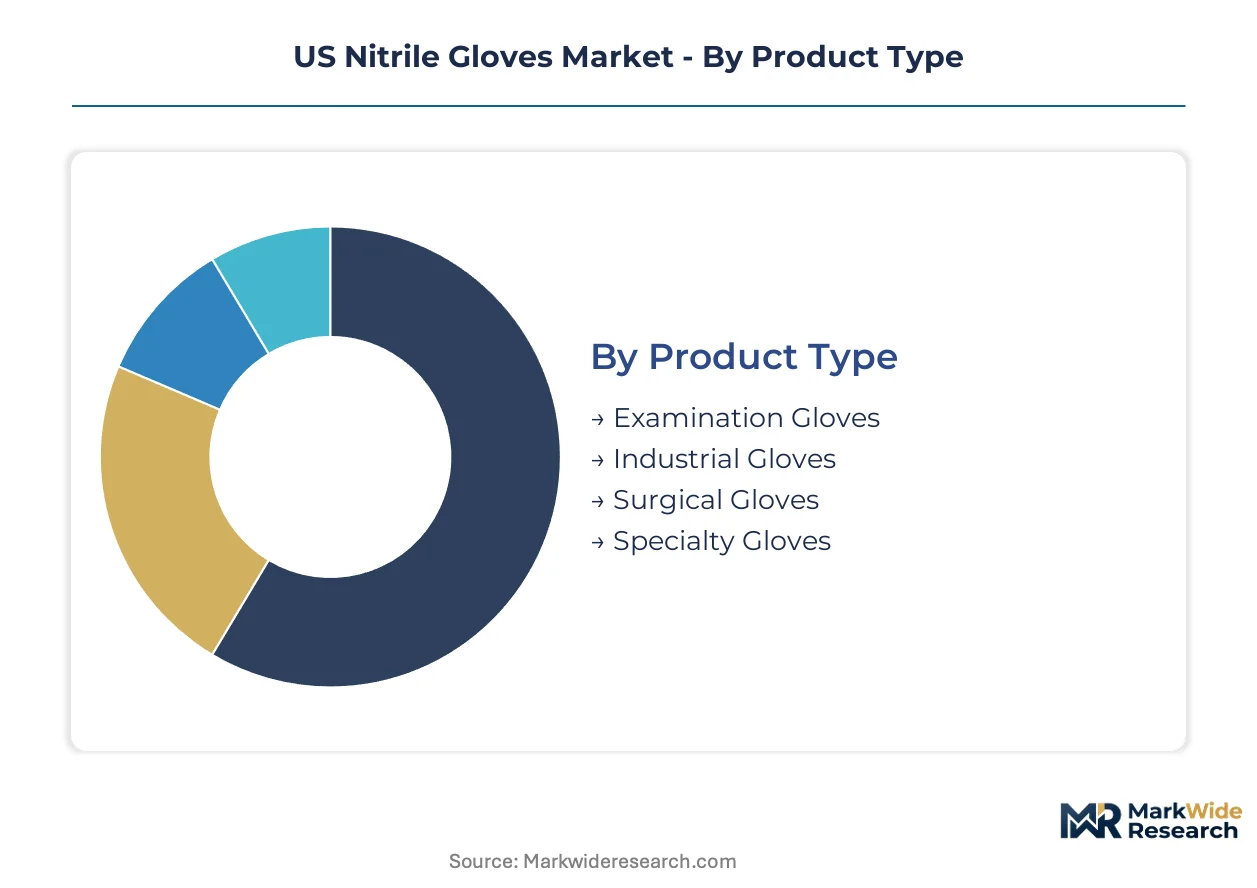
Nitrile glove procurement splits across performance tiers and regulatory thresholds that determine pricing power. Hospital supply chains, industrial safety managers, and federal procurement officers each operate under distinct specification regimes that reshape supplier economics.
Product Type:
Margin pools concentrate in specialty formulations where chemical resistance ratings command premium positioning over commodity examination grades.
- Examination Gloves:Thin-walled acrylonitrile-butadiene copolymer construction designed for tactile sensitivity in patient contact. Demand concentrates in Southeast hospital networks where outpatient clinic expansion and Atlanta-Charlotte distribution proximity accelerate inventory turns. OSHA bloodborne pathogen mandates sustain baseline volume through dental practices and long-term care facilities.
- Industrial Gloves:Thicker-walled synthetic rubber with enhanced puncture resistance and chemical permeation ratings per ASTM standards. Manufacturing facilities in Texas and Louisiana drive procurement for petrochemical handling applications where solvent exposure risks dominate safety protocols.
- Surgical Gloves:Sterile, anatomically curved formulations meeting AAMI barrier performance thresholds. Operating room suites in academic medical centers specify these for invasive procedures.
- Specialty Gloves:Cleanroom-compatible or chemotherapy-rated variants for biotechnology and oncology applications. FDA 510(k) clearance requirements extend development timelines.
Examination gloves hold installed capacity. Industrial gloves are rotating up the share rankings.
End User:
Volume concentration tracks healthcare facility expansion, though laboratory and food service segments present margin expansion opportunities through specialized certification requirements.
- Healthcare Facilities:Hospitals, outpatient clinics, nursing homes, and ambulatory surgery centers consuming examination and surgical grades. Integrated delivery networks in Georgia and North Carolina consolidate purchasing power through direct-to-system contracts.
- Laboratories:Research institutions and diagnostic facilities requiring ISO-certified quality management system validation. Chemical handling protocols in pharmaceutical development drive demand for industrial-grade chemical resistance.
- Food Services:Commercial kitchens and processing plants using powder-free examination gloves for allergen control. FDA food contact substance regulations govern surface treatment compliance.
- Manufacturing:Automotive, electronics, and chemical production facilities specifying puncture-resistant industrial grades. OSHA personal protective equipment standards mandate provision for exposed workers.
Healthcare facilities anchor procurement volume. Laboratories are expanding most quickly as R&D facility construction accelerates.
Certification:
Regulatory gatekeeping determines market access, with FDA medical device clearance functioning as the dominant commercial threshold for domestic healthcare procurement.
- FDA Approved:Medical device premarket notification under 510(k) pathway for examination and surgical applications. Hospital procurement departments treat this as non-negotiable for patient contact uses.
- ISO Certified:Quality management system validation per ISO 13485 or ISO 9001 standards. Laboratory and research institution contracts increasingly require documented quality system adherence.
- CE Marked:European conformity marking for products distributed in EU markets. US-based exporters maintain dual certification for international revenue streams.
- AAMI Level:Association for the Advancement of Medical Instrumentation barrier performance ratings for surgical gloves. Level 3 and 4 specifications dominate academic medical center purchasing.
FDA Approved certification commands pricing premiums. ISO Certified status is gaining share fastest among non-clinical procurement channels.
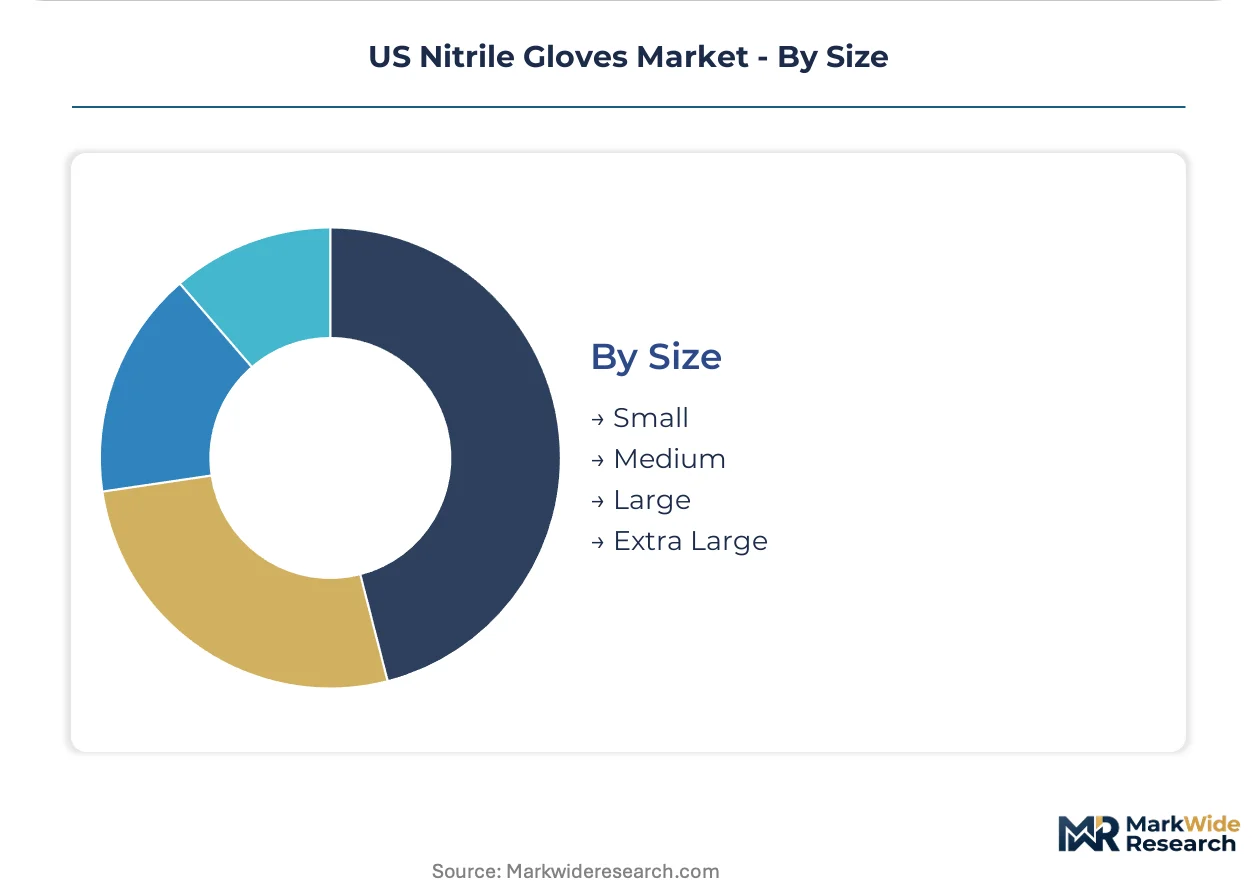
Size:
SKU proliferation across hand dimensions fragments production scheduling, with medium and large sizes absorbing disproportionate volume share.
- Small:Pediatric applications and smaller-handed healthcare workers. Limited SKU representation in bulk procurement contracts.
- Medium:Standard fit for majority of clinical and industrial users. Production lines optimize around this dimension for inventory efficiency.
- Large:Male-dominated industrial workforce preference. Manufacturing and chemical handling applications skew toward this specification.
- Extra Large:Specialized industrial applications and specific healthcare worker demographics. Lower volume, higher per-unit pricing.
Medium size holds installed capacity. Large size is rotating up the share rankings as industrial procurement expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian and Thai production corridors supply the bulk of US healthcare procurement, with Southeast Asian manufacturing clusters feeding Atlantic and Gulf Coast distribution hubs.
Southeast
Georgia and North Carolina hospital networks drive concentrated demand through Atlanta-Charlotte procurement corridors. OSHA bloodborne pathogen mandates sustain baseline volume across ambulatory surgery centers and long-term care facilities. The FDA's ASTM D6319 enforcement compresses supplier margins as integrated delivery networks consolidate purchasing power in this corridor.
Texas Gulf Coast
Petrochemical handling applications in Houston and Beaumont manufacturing complexes generate industrial-grade procurement. Proximity to butadiene and acrylonitrile production enables backward integration opportunities for domestic synthetic rubber supply chains. The EPA scrutinizes manufacturing effluent from nitrile production facilities, adding compliance costs that favor scaled producers in this corridor.
Mid-Atlantic
Philadelphia and Baltimore hospital systems anchor examination-grade consumption through distributor-mediated channels. VA procurement guidelines increasingly weight US-manufactured inventory in contract award criteria. Federal domestic content preferences create procurement friction against Southeast Asian cost advantages in this region.
Midwest
Chicago and Detroit manufacturing facilities specify puncture-resistant industrial grades for automotive and chemical production applications. OSHA personal protective equipment standards mandate provision for exposed workers in heavy industrial settings. Inventory velocity accelerates through centralized distribution serving dispersed manufacturing footprints across Ohio and Michigan.
West Coast
California biotechnology and semiconductor cleanrooms require ISO 14644 Class 7 or better manufacturing environments for specialty glove procurement. FDA 510(k) clearance requirements extend development timelines for chemotherapy-rated variants serving oncology applications. The region's laboratory research institutions drive ISO-certified quality management system validation requirements.
US Nitrile Gloves Market Competitive Landscape
Player mix skews toward diversified healthcare conglomerates with established distribution infrastructure. Market structure concentrates around three to four integrated supply chain operators controlling direct-to-system contracting channels. Strategic archetypes include petrochemical-integrated manufacturers, distributor-mediate volume players, and specialty formulation specialists. Competitive moves center on backward integration into synthetic rubber feedstocks and embedded inventory management programs with multi-facility hospital systems.
Among Malaysia-based producers, Top Glove Corporation Bhd and Hartalega Holdings Berhad exemplify the petrochemical-integrated archetype with captive acrylonitrile-butadiene supply chains. Within the US distributor tier, Cardinal Health and Medline Industries occupy positions anchored by direct contracting relationships with integrated delivery networks. Ansell Ltd. represents the specialty formulation vector with differentiated synthetic rubber chemistry capabilities.
| Leading Market Players |
|---|
| Ansell Ltd. |
| Top Glove Corporation Bhd |
| Hartalega Holdings Berhad |
| Supermax Corporation Berhad |
| Kimberly-Clark Corporation |
| Cardinal Health |
| Medline Industries, Inc. |
| Ammex Corporation |
| Superior Gloves |
| Others |
Pricing and Supply Chain Analysis
Chlorinated surface treatment substitution for cornstarch-based donning agents is redrawing procurement economics while compressing allergen liability premiums and rerouting specification requirements through Southeast hospital networks.
Pricing Analysis
Thinner-walled formulation advances versus legacy thick-walled construction versus cleanroom-compatible next-generation variants define the technology-generation pricing gap. Three-tier pricing structure across premium specialty grades, standard examination tiers, and economy vinyl-competitive levels dominates transaction flows. Cost compression in standard examination grades intensifies because Malaysian capacity expansion outpaces US demand growth. Ambulatory surgery centers exhibit highest price sensitivity while oncology and semiconductor cleanroom buyers absorb premium positioning.
Supply Chain Analysis
Malaysia and Thailand anchor nitrile glove manufacturing, feeding Atlantic and Gulf Coast distribution corridors through ocean freight lanes. Acrylonitrile monomer, butadiene feedstock, and chlorinated surface treatment chemicals constitute critical input dependencies. Single-source vulnerability concentrates in Southeast Asian production corridors exposed to maritime chokepoint disruptions. Distribution runs through Atlanta-Charlotte hospital network clusters and Texas petrochemical corridor manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US nitrile gloves market sits in early-cycle expansion as outpatient clinic construction and ambulatory surgery center proliferation extend baseline OSHA-mandated consumption beyond traditional hospital settings.
For Market Incumbents: Fortify direct-to-system contracting relationships with Georgia and North Carolina integrated delivery networks before procurement consolidation hardens. Accelerate backward integration into Texas Gulf Coast petrochemical feedstocks to offset acrylonitrile price volatility. Lock in FDA 510(k) clearance portfolios against tightening ASTM D6319 enforcement thresholds. For New Entrants and Emerging Players: Embedded inventory management services represent the service-layer gap where Cardinal Health and Medline field organizations under-serve mid-tier regional hospital systems. Target Texas and Louisiana industrial chemical handling applications where specialized permeation resistance ratings command wider margins. Pursue VA and DOD procurement channels through domestic manufacturing qualification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed distributor-mediate volume players lacking direct-to-system contracting infrastructure. Five-to-ten-year viability hinges on capturing procurement consolidation tailwinds rather than commodity volume exposure. Watch for FDA domestic content guidance expansion as inflection indicator for US manufacturing asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | Captive acrylonitrile-butadiene supply from Texas Gulf Coast corridor insulates margin compression from crude oil futures volatility. |
| Direct-to-System Contracting Expansion | Embedded inventory management programs with Atlanta-Charlotte hospital networks displace traditional distributor intermediation. |
| FDA 510(k) Clearance Portfolio Investment | Premarket notification validation for powder-free chlorinated formulations secures non-negotiable hospital procurement access. |
| Cleanroom-Compatible Production Retrofitting | ISO 14644 Class 7 manufacturing environments unlock California biotechnology and semiconductor specialty glove demand. |
| Domestic Content Certification Pursuit | VA and DOD procurement guideline alignment captures federal healthcare contract award preference weighting. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement directors, GPO contracts managers, biomedical engineers, and industrial safety officers; and secondary validation through FDA 510(k) clearance databases, hospital supply chain procurement records, OSHA enforcement documentation, and customs import trade data. Bottom-up volume modeling triangulated against top-down market sizing from petrochemical feedstock consumption patterns.
Across the analysis window, the forecasting framework modeled demand by product type tier, end-user facility category, certification requirement level, and regional procurement cluster density. CAGRs derived from segment-level demand elasticity coefficients applied to baseline OSHA-mandated consumption floors. Acrylonitrile monomer price forecasting and hospital construction pipeline data fed specialty-grade premium retention assumptions.
Underlying assumptions cover continued OSHA bloodborne pathogen standard enforcement, stable Southeast Asian manufacturing capacity utilization, and unaltered FDA medical device regulatory pathways, with deviation risk concentrated in federal domestic content mandate expansion and ocean freight corridor disruptions. Recalibration cycles align with material shifts in petrochemical feedstock pricing and hospital network merger activity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Carboxylated Nitrile Rubber Market
Rubber
Synthetic Polyisoprene Rubber Market
Rubber
Rubber Block Market
Rubber
Liquid Polybutadiene Market
Rubber
Oil Saver Rubber Market
Rubber
Global Rubber Process Oil Market
Rubber
Recycled Elastomers Market
Rubber
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Rubber
Tire and Rubber Lubricants Market
Rubber
Rubber Seal Plugs Market
Rubber
Rubber Compound Market
Rubber
Pre-Dispersed Rubber Chemicals Market
Rubber
Global Rubber Vulcanization Market
Rubber
Isoprene Rubber (IR) Latex Market
Rubber
Chloro-Sulfonated Polyethylene Market
Rubber
Rubber Foam Materials Market