
 Plastics in Electrical and Electronics Market | 2026-2036
Plastics in Electrical and Electronics Market Size, Share, and Industry Trends Forecast 2026-2036
Plastics in Electrical and Electronics Market Analytics
Polyamide is realigning metal-to-plastic conversion ratios in high-voltage connector architectures. BASF SE leverages its Ultramid portfolio to dominate automotive-grade electrical housings requiring thermal endurance above 150°C. SABIC sustains competitive positioning through captive supply of modified polyphenylene ether resins for telecommunications infrastructure. Covestro AG specializes in halogen-free polycarbonate blends that meet stringent flame-retardancy thresholds without sacrificing dimensional stability.
Plastics in electrical and electronics encompass thermoplastic and thermoset polymers formulated with fillers, flame retardants, and stabilizers to achieve dielectric strength typically exceeding 15 kV/mm, thermal deformation resistance, and UL 94 V-0 ignition ratings for component protection. These materials serve primarily as insulating barriers, structural housings, and substrate carriers that prevent electrical shorting while enabling miniaturization. Polycarbonate leads among product types due to its optical clarity and impact resistance in consumer device housings, while ABS competes aggressively on cost in mass-market appliance enclosures. Injection molding anchors volume production for circuit boards and connectors, though 3D printing is gaining traction for rapid prototyping of custom insulator geometries in telecommunications equipment.
REACH and RoHS frameworks in Europe restrict hazardous substance content in electrical plastics, compelling reformulation across supply chains serving EU export markets. The EPA and FAA in the United States impose parallel flammability and emissions standards that shape material qualification protocols for aerospace and industrial electronics. China's GB standards and MIIT directives enforce comparable technical benchmarks for domestic appliance and automotive electronics manufacturing. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate compliance-driven material switches and qualification timelines.
Market Dynamics
REACH restrictions on halogenated flame retardants are forcing wholesale reformulation of polymer compounds across European-bound supply chains, redirecting R&D investment toward phosphorus-based and nitrogen-based alternatives while compressing qualification timelines for housing and substrate materials.
Growth Catalysts
- Consumer electronics miniaturization:Smartphone and laptop manufacturers demand thinner-walled flame-retardant housings that maintain UL 94 V-0 ratings, pulling specialized engineering resins into high-volume assembly lines.
- REACH RoHS compliance mandates:European restrictions on hazardous substances create captive demand for halogen-free polycarbonate blends and polyamide formulations that satisfy dielectric strength thresholds above 15 kV/mm.
- China electronics cluster concentration:Shenzhen and Dongguan manufacturing hubs source captive volumes of PCB substrate resins and connector-grade polymers, anchoring regional compounding capacity expansion.
Market Restraints
- Engineering resin feedstock volatility:Bisphenol A and caprolactam price swings compress margin predictability for compounders serving appliance and automotive electrical segments.
- Specialized additive supply concentration:Phosphorus-based flame retardant production concentrates among limited European and Asian chemical suppliers, creating qualification bottlenecks for new entrants.
- Metal-to-plastic conversion ceiling:High-voltage architectures above 800V retain metal housings due to thermal runaway containment requirements, capping addressable volume in EV power electronics.
Strategic Opportunities
- India electronics manufacturing expansion:PLI scheme incentives for mobile phone and component production create virgin demand for ABS and polycarbonate housing materials in Noida and Chennai corridors.
- Telecommunications infrastructure buildout:5G base station deployments require modified polyphenylene ether resins with dimensional stability across temperature cycling, opening specialty compounder niches.
- EU Green Deal circularity mandates:Recycled-content thresholds for electrical plastics drive investment in chemical recycling streams for polycarbonate recovery from end-of-life consumer devices.
Industry Challenges
- Flame-retardant formulation expertise scarcity:Compounders struggle to recruit polymer chemists capable of balancing halogen-free ignition performance with melt-flow characteristics required for thin-wall injection molding.
- UL certification timeline compression:New material qualifications for electrical housings face 12-18 month testing cycles that misalign with OEM product refresh schedules, forcing speculative pre-qualification investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastics in Electrical and Electronics Market |
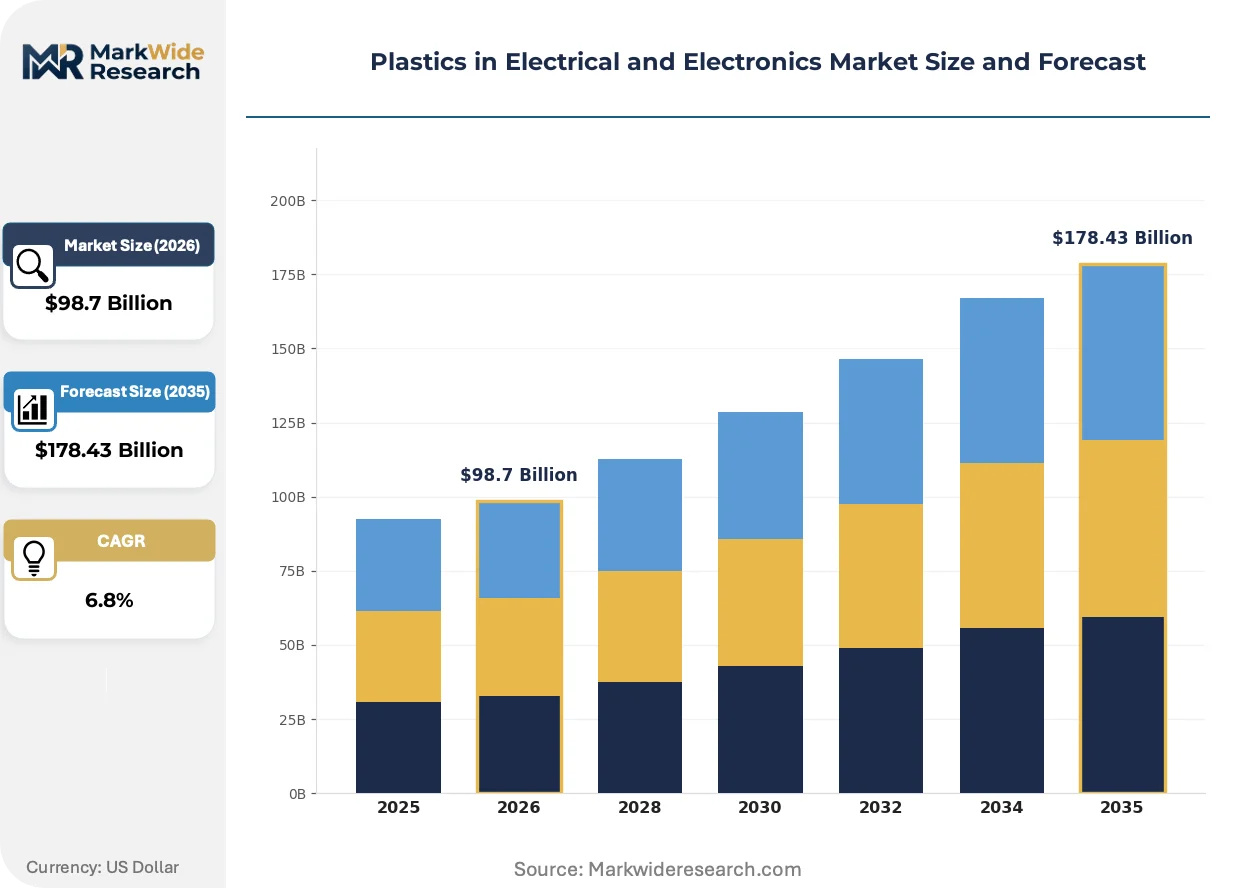
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, PVC, Polypropylene, ABS Application: Circuit Boards, Insulators, Connectors, Housings Technology: Injection Molding, Blow Molding, 3D Printing, Thermoforming End User: Consumer Electronics, Automotive, Telecommunications, Industrial Equipment |
| Companies Covered | DuPont, Mitsubishi Chemical Group Corporation, BASF SE, Solvay, Celanese Corporation, Covestro AG, LG Chem, Trinseo S.A., SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastics in Electrical and Electronics Market Evolving Landscape
Material science advances and regulatory stringency are converging to reshape competitive positioning in electrical plastics, with sustainability mandates and performance requirements pulling formulation strategies in divergent directions.
Bio-based polyamide feedstocks derived from castor oil are overtaking petroleum-derived equivalents in connector and cable tie applications where automotive OEMs specify renewable content thresholds. European Tier-1 suppliers have accelerated adoption curves from pilot to production volumes within 24-month windows. This transition is compressing incumbent compounders' margin structures while opening premium pricing tiers for certified sustainable material streams.
REACH authorization requirements for halogenated flame retardants are eliminating legacy additive packages from EU-bound electrical housings by 2026 deadlines. Compounders serving export markets must maintain dual formulation inventories or commit fully to phosphorus-based alternatives. Consumer electronics OEMs with European distribution footprints face the most acute compliance pressure, driving consolidated procurement specifications toward halogen-free baselines across all geographies.
Telecommunications equipment buyers are consolidating supplier panels for custom insulator geometries, displacing fragmented distributor networks with direct compounding relationships. 3D printing qualification for rapid prototyping has shortened design iteration cycles from weeks to days, compressing traditional mold-based sampling revenue for injection molders. This pattern concentrates most visibly in Nordic markets where Ericsson and Nokia supply chains prioritize agile material development partnerships.
Plastics in Electrical and Electronics Market Segmentation
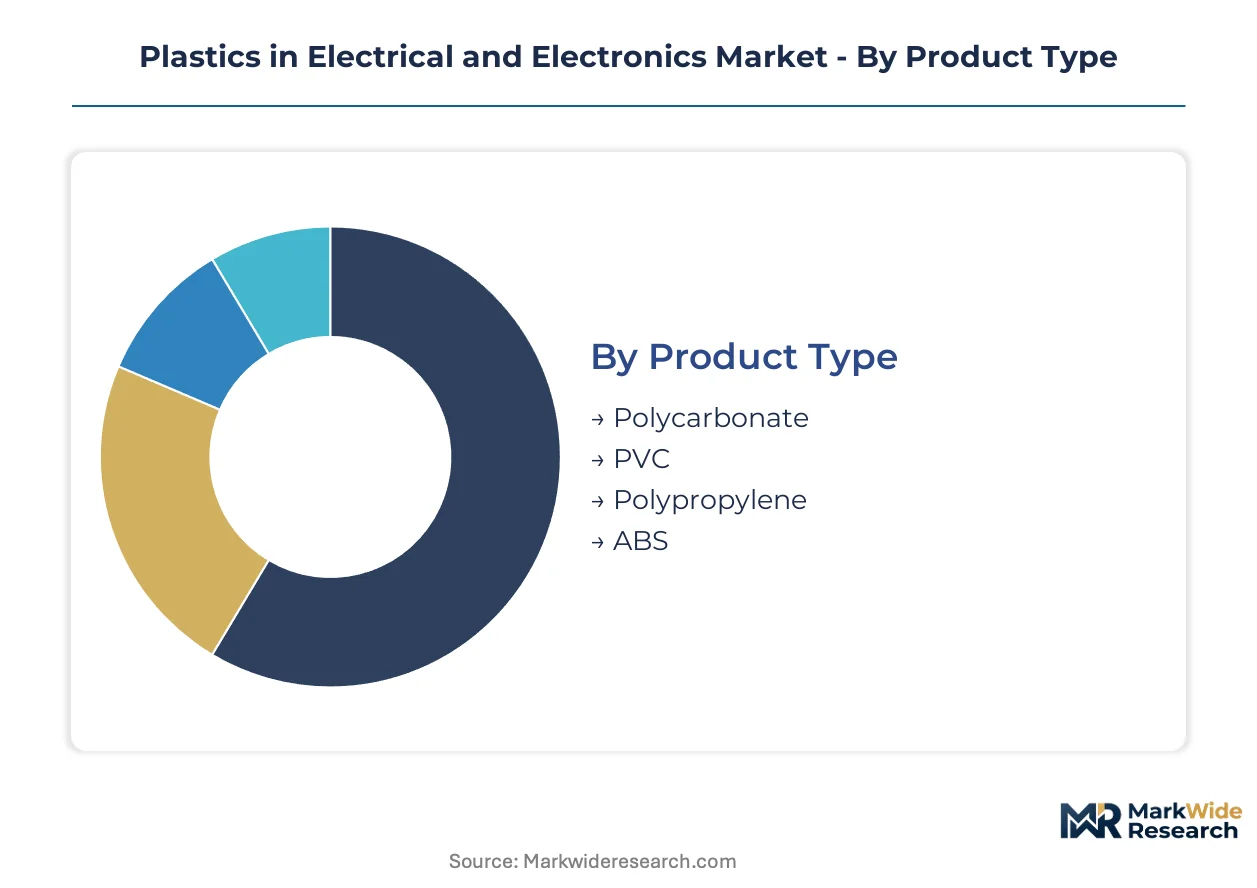
Material selection in electrical plastics hinges on balancing dielectric performance, flame-retardancy ratings, and processing economics. Each segmentation dimension reveals distinct buyer priorities that reshape supplier relationships and formulation investments across the value chain.
Product Type:
Cost sensitivity and performance thresholds diverge sharply between commodity resins and engineering-grade alternatives.
- Polycarbonate:Amorphous thermoplastic delivering optical clarity above 90% light transmission combined with inherent flame-retardancy without halogenated additives. Smartphone and laptop manufacturers in Shenzhen and Dongguan specify polycarbonate for display bezels and battery housings where UL 94 V-0 ratings must coexist with aesthetic surface finishes.
- ABS:Terpolymer of acrylonitrile, butadiene, and styrene offering impact resistance above 200 J/m at substantially lower resin cost than engineering alternatives. Mass-market appliance producers in India source ABS for control panel enclosures where dielectric strength requirements stay below 15 kV/mm and cost-per-part dominates procurement decisions.
- Polypropylene:Semi-crystalline polymer with density below 1 g/cm³ enabling lightweight cable insulation and wire jacketing for automotive harnesses.
- PVC:Chlorinated polymer with established compounding infrastructure for legacy electrical conduit and low-voltage insulation in building wire applications.
Polycarbonate leads volumes today; polypropylene is gaining share fastest in automotive lightweighting programs.
Application:
Functional requirements separate commodity housing demand from precision substrate applications where dimensional tolerances dictate resin selection.
- Housings:Structural enclosures requiring impact resistance above 50 kJ/m² and surface aesthetics suitable for consumer-facing devices. Flame-retardant polycarbonate and ABS blends dominate smartphone, laptop, and appliance chassis production, with REACH-compliant halogen-free formulations capturing European-bound supply chains.
- Connectors:Precision-molded interfaces demanding thermal deformation resistance above 150°C and creep resistance under mechanical load. Polyamide compounds with glass fiber reinforcement above 30% by weight serve high-voltage automotive and industrial connector architectures undergoing metal-to-plastic conversion.
- Circuit Boards:Substrate materials requiring dielectric constant stability across temperature and humidity cycling for PCB laminates and embedded component carriers.
- Insulators:Dielectric barriers for switchgear and distribution equipment where tracking resistance and arc containment determine material qualification.
Housings anchor current resin consumption; connectors show the steepest expansion trajectory as electrification multiplies interface counts per vehicle and device.
Technology:
Volume scale and geometric complexity determine processing method selection, with prototyping speed increasingly influencing development-phase supplier relationships.
- Injection Molding:Dominant high-volume process achieving cycle times below 30 seconds for multi-cavity tools producing connector housings and PCB substrates. Telecommunications infrastructure manufacturers in Nordic markets specify injection-molded modified polyphenylene ether resins for base station insulators requiring dimensional stability across -40°C to 85°C operational envelopes.
- 3D Printing:Additive fabrication enabling rapid iteration of custom insulator geometries without hard tooling investment. Ericsson and Nokia supply chains have compressed design validation cycles from weeks to days using selective laser sintering of flame-retardant polyamide powders for telecommunications prototyping.
- Blow Molding:Hollow-part formation for cable conduit and protective enclosure bellows in industrial electrical applications.
- Thermoforming:Sheet-based shaping for equipment enclosures and interior liners where wall thickness uniformity is secondary to cost minimization.
Injection molding commands absolute volume leadership; 3D printing is climbing the fastest as OEMs consolidate agile development partnerships.
End User:
Regulatory exposure and qualification timelines fragment demand patterns across customer verticals, with automotive and consumer electronics imposing the most stringent material certification requirements.
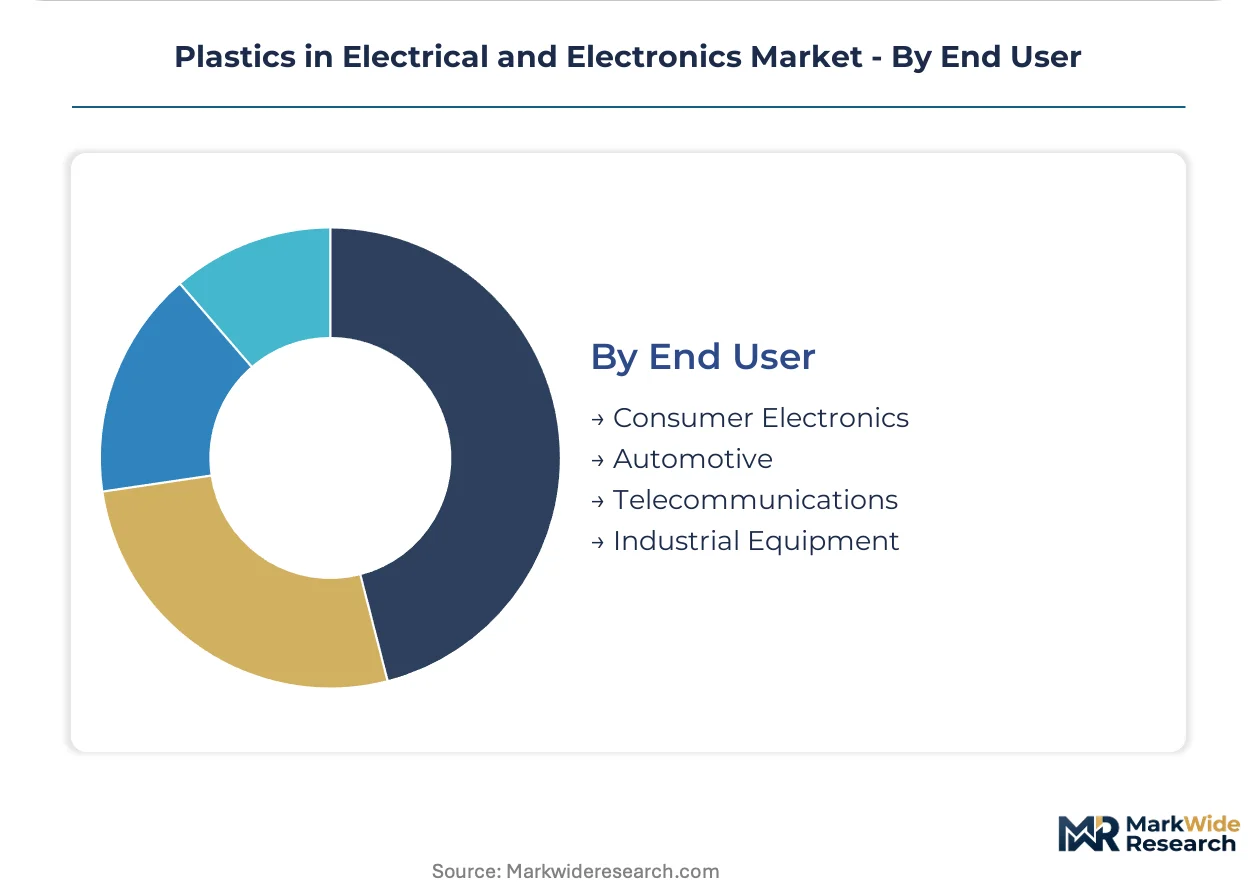
- Consumer Electronics:Smartphone, laptop, and wearable manufacturers demanding UL 94 V-0 flame-retardancy in wall thicknesses below 1.0 mm for miniaturized housings. REACH and RoHS compliance mandates in Europe redirect procurement specifications toward halogen-free polycarbonate blends and phosphorus-based flame-retardant systems.
- Automotive:OEMs and Tier-1 suppliers specifying thermal endurance above 150°C for under-hood electrical components and high-voltage connector architectures. BASF Ultramid polyamide compounds dominate battery module housings and charging inlet assemblies where metal-to-plastic conversion reduces assembly weight.
- Telecommunications:5G base station and fiber optic infrastructure builders requiring modified polyphenylene ether resins with low dielectric loss and dimensional stability across temperature cycling.
- Industrial Equipment:Factory automation and power distribution manufacturers sourcing ABS and polycarbonate for control enclosures and switchgear housings with less stringent thermal requirements than automotive or telecommunications applications.
Consumer electronics drives absolute resin volumes; automotive is expanding most quickly as electrification multiplies electrical component counts per vehicle platform.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and Dongguan electronics clusters anchor plastics demand for PCB substrates and connector assemblies, with China sourcing specialized engineering resins at volumes unmatched elsewhere. Regulatory divergence between REACH in Europe, EPA standards in the United States, and China's GB directives fragments qualification timelines for compounders serving multiple export markets. Regional manufacturing concentration shapes material procurement patterns across four critical geographies.
China
Consumer electronics miniaturization drives demand for flame-retardant polycarbonate in smartphone and laptop housings. MIIT directives enforce GB standards for domestic appliance and automotive electronics manufacturing. Shenzhen and Dongguan manufacturing hubs source captive volumes of PCB substrate resins and connector-grade polymers, anchoring regional compounding capacity expansion.
United States
Telecommunications infrastructure buildout requires modified polyphenylene ether resins for 5G base station insulators. The EPA and FAA impose parallel flammability and emissions standards that shape material qualification protocols for aerospace and industrial electronics. Nordic supply chains serving Ericsson and Nokia prioritize agile material development partnerships with US-based compounders.
Germany
Automotive OEMs specify thermal endurance above 150°C for under-hood electrical components and high-voltage connector architectures. REACH restrictions on halogenated flame retardants force wholesale reformulation of polymer compounds across European-bound supply chains. BASF SE leverages its Ultramid portfolio to dominate automotive-grade electrical housings requiring thermal endurance above 150°C.
India
PLI scheme incentives for mobile phone and component production create virgin demand for ABS and polycarbonate housing materials. BIS standards enforce technical benchmarks for domestic appliance manufacturing. Noida and Chennai corridors emerge as electronics manufacturing expansion zones sourcing flame-retardant polymer housings for smartphones and laptops.
Plastics in Electrical and Electronics Market Competitive Landscape
Global majors compete with regional champions across formulation expertise and captive supply chain control. The vendor base stratifies between integrated resin producers, specialized compounders, and distributor networks serving fragmented appliance segments. Three archetypes dominate: petrochemical-backed resin suppliers with backward integration into monomer feedstocks; independent compounders with flame-retardant formulation IP; and regional distributors with logistics advantages in emerging manufacturing corridors. Competitive moves concentrate on M&A to secure additive technology capabilities and capacity expansion in China and India electronics clusters.
Among petrochemical-backed resin suppliers, BASF SE, SABIC, and Covestro AG occupy positions defined by captive feedstock access and halogen-free formulation portfolios. BASF SE exemplifies the integrated archetype through its Ultramid polyamide compounds. SABIC represents Middle Eastern petrochemical scale applied to modified polyphenylene ether resins. Covestro AG anchors the European specialty position with polycarbonate blends meeting stringent flame-retardancy thresholds.
| Leading Market Players |
|---|
| DuPont |
| Mitsubishi Chemical Group Corporation |
| BASF SE |
| Solvay |
| Celanese Corporation |
| Covestro AG |
| LG Chem |
| Trinseo S.A. |
| SABIC |
| Others |
Value Network & Pricing Analysis
Specialized polymer chemists concentrated in Germany's Rhine-Ruhr industrial corridor command wage premiums that widen spreads between premium halogen-free formulations and economy-grade ABS alternatives. Labor-cost differentials between European formulation centers and Asian compounding hubs directly shape three-tier pricing structures across the electrical plastics value chain.
Pricing Analysis
Input-cost pass-through from bisphenol A and caprolactam volatility dominates pricing dynamics for polycarbonate and polyamide grades. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified halogen-free compounds from commodity ABS and legacy PVC alternatives. Cost compression in standard-grade polycarbonate is intensifying because Shenzhen electronics assemblers negotiate volume contracts exceeding ten thousand metric tons annually. Mass-market appliance producers in India exhibit highest price sensitivity, while automotive Tier-1 suppliers in Germany accept premium positioning for thermal endurance above 150°C.
Supply Chain Analysis
Workforce availability for flame-retardant formulation expertise concentrates in Germany, Japan, and the United States, constraining capacity expansion timelines for new entrants. Raw material dependencies center on Saudi Arabian petrochemical feedstocks for polyphenylene ether precursors, Chinese caprolactam for polyamide polymerization, and Belgian phosphorus-based additive packages. Single-source vulnerability in phosphorus flame-retardant production creates qualification bottlenecks when European suppliers prioritize domestic automotive allocations. Distribution runs through regional compounding facilities in Dongguan, Noida, and Detroit that serve captive electronics manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Plastics in Electrical and Electronics Market functions as a stable compounder where regulatory-driven material refresh cycles ensure consistent replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Anchor formulation leadership through captive supply of phosphorus-based flame-retardant additives and accelerated UL pre-qualification investments. Defensive consolidation should prioritize backward integration into specialty additive production and capacity expansion in India's Noida corridor to capture PLI-scheme electronics manufacturing growth. Threats from bio-based polyamide substitutes and REACH authorization timelines compress margin predictability for legacy halogenated portfolios. For New Entrants and Emerging Players: The 40-60% price-point gap between premium halogen-free polycarbonate and economy ABS grades opens viable entry space for mid-tier compounders. White-space targets include telecommunications infrastructure prototyping services using 3D-printed flame-retardant polyamide and recycled-content polycarbonate streams for EU Green Deal compliance. India's Chennai electronics corridor represents the most penetrable geography, with direct OEM compounding relationships displacing fragmented distributor networks as the preferred go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among independent compounders with flame-retardant formulation IP but limited geographic footprint. Long-term viability across the analysis window hinges on chemical recycling capabilities for polycarbonate recovery and halogen-free certification depth. Acquisition target archetype: mid-scale European compounders with REACH-compliant portfolios and underutilized capacity in automotive electrical segments. The signal to watch is MIIT directive acceleration in China mandating domestic halogen-free adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Additives | Secures supply continuity for REACH-compliant formulations serving European automotive OEMs. |
| Capacity Expansion in India Electronics Corridors | Captures PLI-scheme driven demand from Noida and Chennai smartphone manufacturing clusters. |
| Chemical Recycling Infrastructure Investment | Enables EU Green Deal circularity compliance for post-consumer polycarbonate recovery streams. |
| UL Pre-Qualification Acceleration Programs | Compresses 12-18 month testing cycles to align with OEM product refresh schedules. |
| Direct OEM Compounding Partnerships | Displaces fragmented distributor networks in Nordic telecommunications equipment supply chains. |
Research Methodology
Direct dialogue with polymer compounding plant managers, procurement leads at consumer electronics OEMs, flame-retardant additive technical directors, and distribution channel partners grounded qualitative insights. Secondary validation drew from ECHA REACH authorization databases, UL certification registries, SEC 10-K filings of listed chemical producers, and customs trade data for engineering resin imports. Bottom-up and top-down triangulation reconciled facility-level capacity assessments with end-use demand aggregation across automotive, consumer electronics, and telecommunications verticals.
Bottom-up volume modeling tracked resin consumption by product type, application, and end-use industry across the projection horizon. Segmentation dimensions included material grade tier, flame-retardant chemistry type, processing technology, and regional manufacturing hub concentration. CAGRs were derived from regression analysis of historical consumption patterns against electronics production indices and automotive electrical content per vehicle trajectories. Forecast inputs incorporated REACH authorization timelines, MIIT directive implementation schedules, and PLI scheme incentive disbursement rates.
Caveats apply where REACH authorization delays, phosphorus additive supply disruptions, or EV high-voltage architecture metal-retention decisions could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and electronics manufacturing cluster expansion rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Heavy Gauge and Thin Gauge Thermoformed Plastics Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
Diamond Wire Market
Industrial Materials
Global Industrial Fastener Seal Market
Industrial Materials
Industrial Films Market
Industrial Materials
Global Cenospheres Market
Industrial Materials
Gypsum Plaster Market
Industrial Materials
Food Grade Nylon Market
Industrial Materials
Wood Fiber Insulation Market
Industrial Materials
Flat Scroll Spring Market
Industrial Materials
Wood Protein Market
Industrial Materials
Industrial Furnaces Market
Industrial Materials
Industrial Couplings Market
Industrial Materials
Solid Surface Materials Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
Mesh Nozzle Plates Market