
 Industrial Heaters Market | 2026-2036
Industrial Heaters Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Heaters Market Analysis
A shortage of certified thermal systems engineers is redrawing competitive boundaries across the industrial heaters landscape. Chromalox leverages its captive supply of alloy-sheathed heating elements to sustain margins in high-temperature process lines. Watlow Electric Manufacturing Company anchors North American demand through deep vertical integration into sensor-integrated thermal loops.
Industrial heaters are electro-mechanical or combustion-based thermal devices engineered to deliver controlled heat transfer within specified temperature ranges, typically constructed from nickel-chromium alloys, stainless steel sheaths, or ceramic cores for durability under thermal cycling. Electric heaters convert electrical resistance into radiant or conductive thermal energy for process heating, drying, and melting operations across manufacturing floors. Gas-fired heaters retain dominance in heavy-process applications where BTU density requirements exceed electrical infrastructure capacity, while infrared technology leads growth in food processing lines demanding rapid, zone-controlled surface heating without convective contamination.
EPA emissions standards and the EU Green Deal framework are forcing fuel-switching investments from combustion-based to electric and induction systems across OECD manufacturing bases. OSHA thermal safety protocols and IEC 60519 standards for electroheat installation shape product certification requirements and market access thresholds. Stakeholders must weigh stranded asset risk in gas-fired installed bases against the capital intensity of induction retrofits as regulatory timelines compress.
Market Dynamics
Electric heater retrofits in German chemical processing and US petrochemical corridors are compressing replacement cycles as EPA and EU Green Deal emissions deadlines approach. Fuel-switching capital commitments now dominate capital expenditure planning across OECD manufacturing bases.
Growth Catalysts
- EPA emissions benchmarks:US chemical processors face mandated NOx reduction timelines that favor electric resistance and induction alternatives over gas-fired combustion systems.
- EU Green Deal industrial decarbonization:German steel and ceramics manufacturers access transition financing for electrode boiler and infrared panel installations.
- Precision manufacturing clusters:Japanese automotive component suppliers deploy zone-controlled induction heating for thermal uniformity in drivetrain hardening operations.
Market Restraints
- Nickel-chromium alloy supply concentration:Russian and Indonesian ore processing dominance creates input cost volatility for resistance element manufacturers.
- Electrical infrastructure capacity gaps:Heavy-process facilities in Texas and Louisiana lack grid upgrade timelines matching EPA compliance deadlines.
- Induction frequency converter technical limits:Power electronics thermal management constraints cap output ranges in large-scale melting applications.
Strategic Opportunities
- South Korean battery gigafactory expansion:Lithium-ion electrode drying lines require precision infrared tunnel systems with ±2°C zone control.
- US Inflation Reduction Act clean manufacturing credits:Section 48C tax incentives offset capital costs for electric process heat installations.
- Digital twin convergence with thermal loops:Sensor-embedded heaters feeding predictive maintenance platforms command premium positioning in pharmaceutical freeze-drying.
Industry Challenges
- Certified thermal systems engineer scarcity:IEC 60519 compliance auditing requires specialized expertise concentrated among retiring workforce cohorts.
- Legacy gas-fired asset stranding:Book-value write-downs complicate financing for parallel electric infrastructure builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Heaters Market |
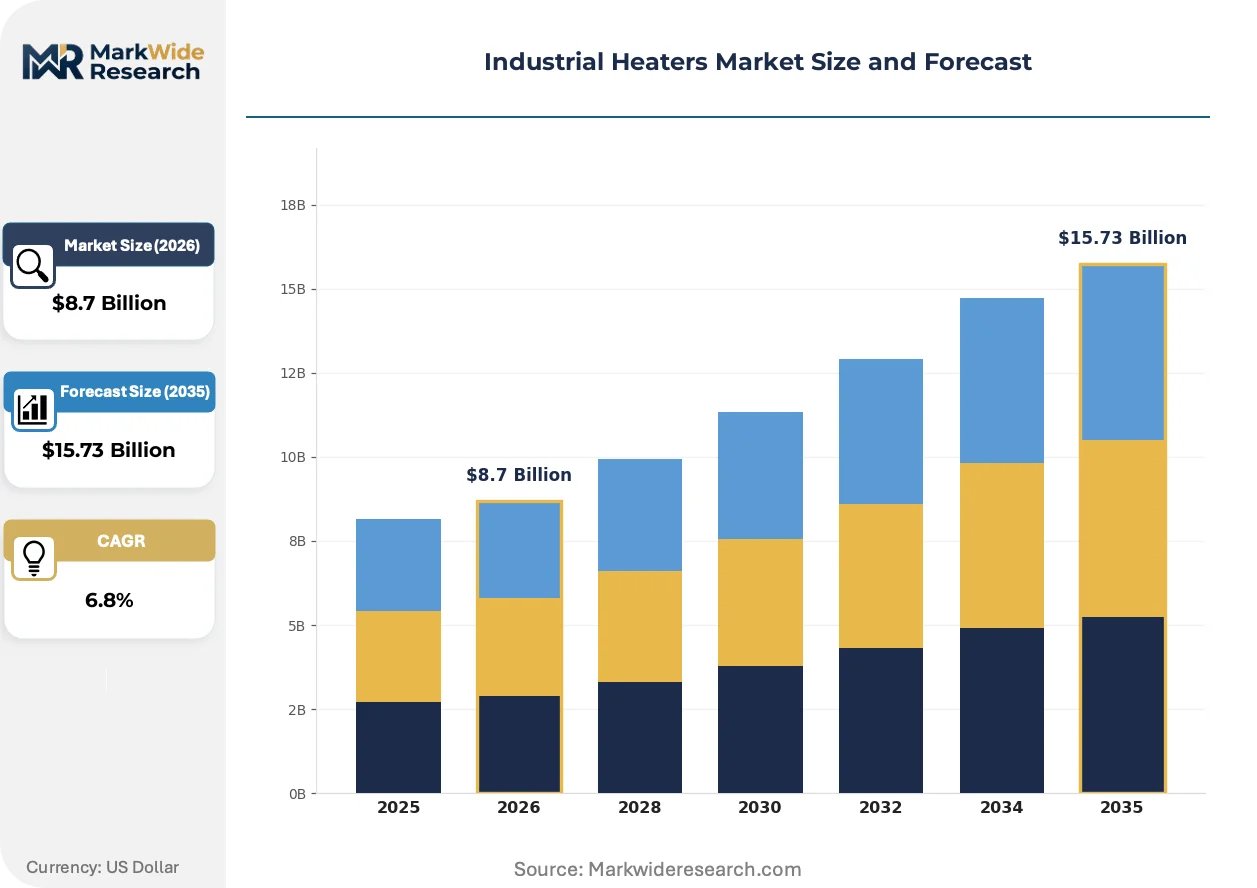
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Heaters, Gas-fired Heaters, Infrared Heaters, Oil-filled Heaters End User: Manufacturing, Food Processing, Oil & Gas, Textile Technology: Convection, Radiant, Conductive, Induction Application: Heating, Drying, Melting, Process Heating |
| Companies Covered | Chromalox, Watlow Electric Manufacturing Company, Wattco, Tempco, Omega Engineering, Excel Heaters, Elmatic Ltd., Dragon Power Electric Co. Ltd., Dalton Electric Heating Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Heaters Market Emerging Trajectories
Silicon carbide heating elements and solid-state induction power supplies are compressing equipment footprints while expanding temperature precision ranges. Regulatory emissions accounting now extends to Scope 3 supply chain thermal inputs.
Silicon carbide ceramic heating cores sustain operating temperatures above 1600°C in continuous sintering furnaces. Aerospace ceramic matrix composite manufacturers in South Carolina and Alabama adopt these elements for thermal processing cycles exceeding 200 hours. The technology is miniaturizing furnace chamber geometries while maintaining throughput, enabling floor-space reductions of 30-40% in greenfield installations.
EU F-Gas Regulation phase-down schedules accelerate refrigerant-based heat pump displacement in industrial process lines below 100°C. Food processors in Denmark and the Netherlands retrofit ammonia absorption and CO2 transcritical systems for pasteurization and evaporation duties. Dairy cooperatives report compliance cost premiums of 15-25% against unabated gas-fired steam, absorbed through operational efficiency gains and carbon border adjustment hedging.
Asset-as-service contracting now dominates heater procurement in pharmaceutical lyophilization and semiconductor wafer processing. Original equipment manufacturers retain ownership of thermal systems, charging per-dried-kilogram or per-wafer-processed fees. This model concentrates in Switzerland and Singapore, where precision manufacturers prioritize uptime guarantees over capital ownership and maintenance labor absorption.
Industrial Heaters Market Segmentation
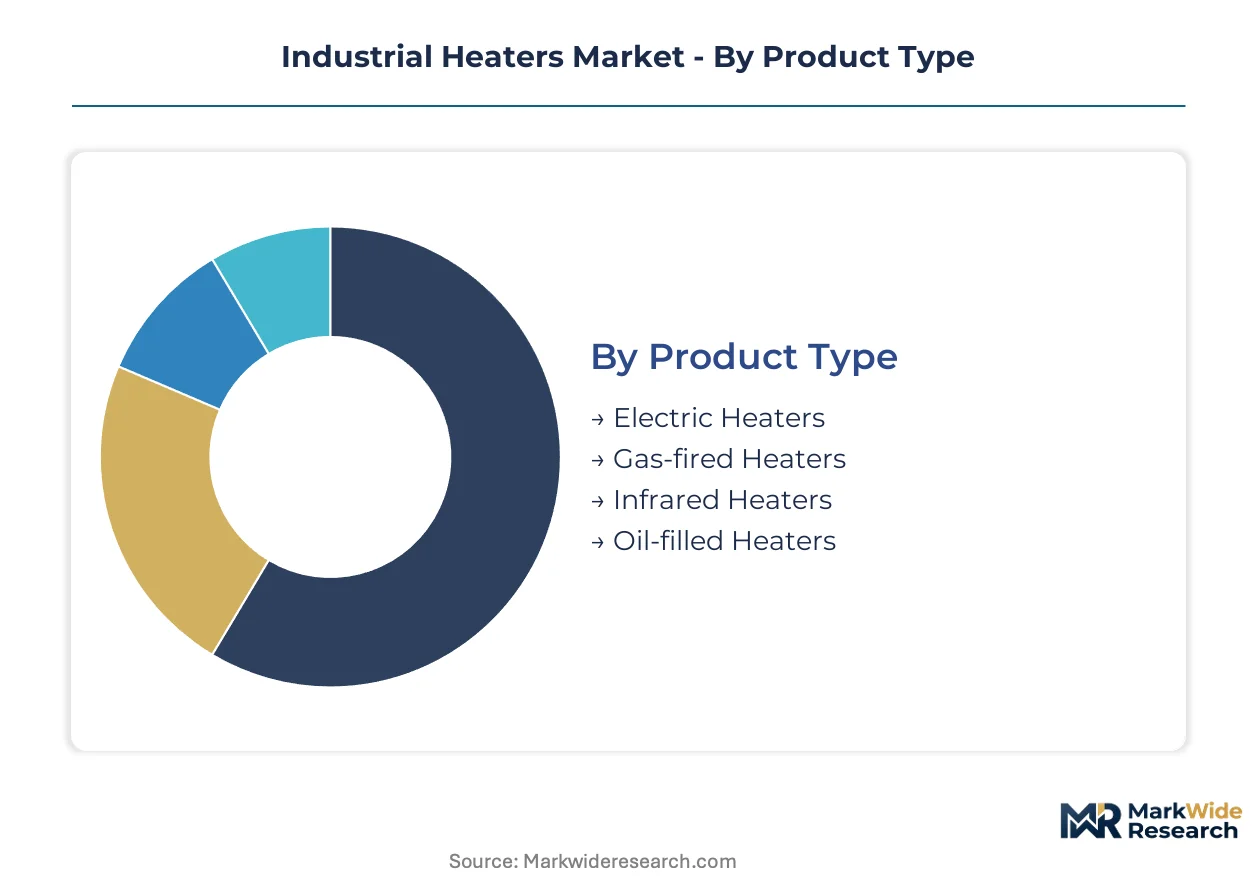
EPA and EU Green Deal emissions frameworks are fragmenting procurement patterns across heater categories. Regulators now distinguish combustion from electric systems in carbon accounting, forcing end-users to rebalance technology portfolios against compliance timelines.
Product Type:
EPA emissions benchmarks and EU Green Deal thresholds split certification pathways between combustion and electric systems.
- Electric Heaters:Resistance and electrode boiler configurations convert grid power to process heat without stack emissions. German chemical processors and US petrochemical operators deploy these systems to meet NOx reduction mandates where grid capacity permits.
- Gas-fired Heaters:Forced-draft and radiant-tube burners deliver high-BTU density for heavy-process loads. Texas and Louisiana refineries retain these systems where electrical infrastructure upgrades lag EPA compliance deadlines.
- Infrared Heaters:Ceramic and quartz element systems provide zone-controlled radiant energy for surface heating without convective contamination.
- Oil-filled Heaters:Thermal fluid circulation systems serve remote or off-grid process sites lacking natural gas pipeline access.
Electric heaters handle the majority of new capital deployment; infrared systems are gaining share fastest on precision manufacturing demand.
End User:
Cost tier stratification separates premium precision applications from commodity thermal loads.
- Manufacturing:Automotive drivetrain hardening and aerospace ceramic matrix composite sintering demand ±2°C thermal uniformity. Japanese component suppliers and South Carolina aerospace clusters specify induction and silicon carbide systems for cycles exceeding 200 hours.
- Food Processing:Pasteurization, evaporation, and freeze-drying lines require hygienic surface heating without contamination risk. Danish and Dutch dairy cooperatives retrofit ammonia absorption and CO2 transcritical heat pumps under EU F-Gas Regulation phase-down schedules.
- Oil & Gas:Upstream extraction and midstream processing rely on high-capacity combustion systems for bulk heating duties.
- Textile:Drying and finishing operations use convection and infrared tunnel configurations for continuous fabric processing.
Manufacturing commands the premium pricing tier; food processing is expanding most quickly on decarbonization financing access.
Technology:
Application temperature range and thermal uniformity requirements determine technology selection.
- Convection:Forced-air and natural-circulation systems transfer heat through fluid movement. Textile drying tunnels and general space heating applications favor these configurations for capital efficiency.
- Radiant:Electromagnetic wave emission delivers surface heating without intermediate fluid. Food processing lines and paint curing operations specify infrared radiant panels for rapid response and zone control.
- Conductive:Direct contact heat transfer through heated surfaces serves melting and pressing operations.
- Induction:Electromagnetic field generation heats ferrous workpieces directly. South Korean battery gigafactory electrode drying and Japanese automotive hardening operations deploy solid-state power supplies for precision thermal loops.
Convection retains the largest installed base; induction is climbing the fastest on precision manufacturing and electrification mandates.
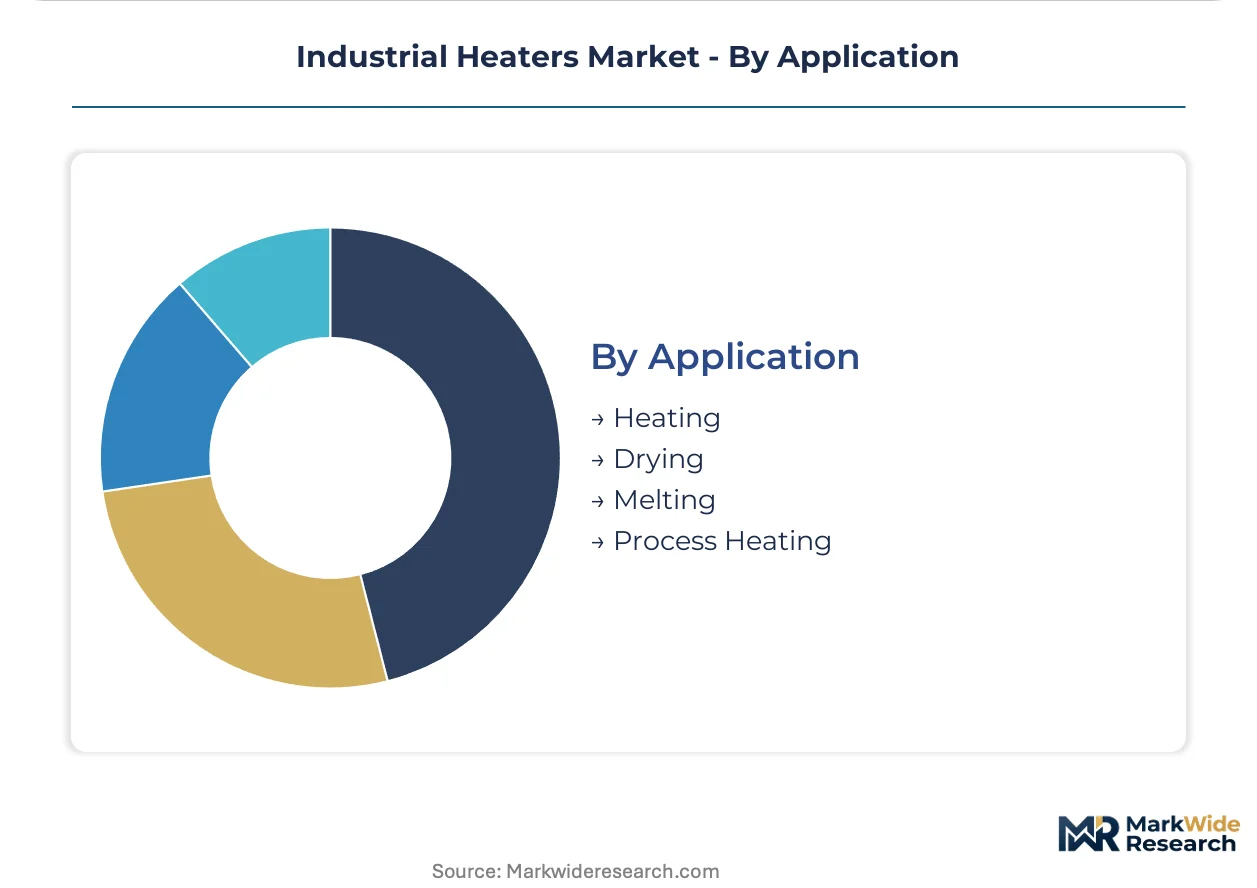
Application:
Volume scale and process criticality differentiate procurement specifications across thermal duties.
- Heating:General process and space warming applications span the full technology spectrum. Facility heating loads in manufacturing plants prioritize energy efficiency and emissions compliance.
- Drying:Moisture removal operations in food, pharmaceutical, and battery electrode production demand controlled airflow and temperature precision. South Korean lithium-ion gigafactories specify infrared tunnel systems with ±2°C zone control for electrode coating lines.
- Melting:High-temperature phase change for metals and glass requires sustained thermal intensity.
- Process Heating:Integrated thermal loops for chemical reaction, distillation, and polymerization anchor refinery and chemical plant operations.
Drying applications absorb the most specialized equipment investment; process heating is expanding most quickly on fuel-switching retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial heater deployment patterns diverge sharply by geography. German chemical processors favor electric resistance retrofits under EU Green Deal financing, while US Gulf Coast operators retain gas-fired systems amid grid capacity constraints. Asian manufacturing clusters prioritize precision induction for automotive and battery production.
United States
Petrochemical corridors in Texas and Louisiana face compressed EPA compliance timelines for NOx reductions. The Inflation Reduction Act's Section 48C clean manufacturing credits offset capital costs for electric process heat installations. Houston-area refineries navigate stranded asset risk in legacy gas-fired bases against parallel infrastructure build requirements.
Germany
Ruhr Valley steel and ceramics manufacturers access transition financing for electrode boiler deployments. EU Green Deal industrial decarbonization mandates accelerate fuel-switching investments. Bavarian precision engineering clusters specify zone-controlled infrared systems for thermal uniformity in automotive component hardening.
China
Yangtze River Delta chemical processors expand electric heater fleets under national dual carbon goals. MIIT energy efficiency standards tighten allowable emissions intensity for process heat. Shanghai-area battery gigafactories deploy precision drying tunnels for lithium-ion electrode production.
Japan
Chubu region automotive suppliers deploy solid-state induction power supplies for drivetrain hardening operations. METI technology roadmaps prioritize electromagnetic heating efficiency gains. Nagoya manufacturing clusters demand ±2°C thermal uniformity for 200-hour continuous sintering cycles.
South Korea
Busan-Ulsan battery manufacturing corridors absorb specialized infrared tunnel systems for electrode coating lines. National industrial competitiveness programs fund precision thermal equipment upgrades. Daegu-Gyeongbuk textile clusters retrofit convection drying systems for energy efficiency compliance.
Industrial Heaters Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in industrial heaters. Chromalox and Watlow Electric Manufacturing Company occupy positions with captive alloy supply and sensor-integrated thermal loops respectively. Mid-cap regional fabricators compete on customization velocity and local service density. Competitive moves concentrate on backward integration into resistance element production and geographic expansion through distribution partnerships.
Among North American manufacturers, Chromalox exemplifies the vertically integrated archetype with in-house production of alloy-sheathed heating elements. Watlow Electric Manufacturing Company occupies a position anchoring sensor-integrated thermal systems. Tempco represents the specialist tier competing on application engineering responsiveness.
| Leading Market Players |
|---|
| Chromalox |
| Watlow Electric Manufacturing Company |
| Wattco |
| Tempco |
| Omega Engineering |
| Excel Heaters |
| Elmatic Ltd. |
| Dragon Power Electric Co. Ltd. |
| Dalton Electric Heating Co., Inc. |
| Others |
Supply Flow & Price Mechanics
Silicon carbide ceramic heating cores displacing traditional nickel-chromium resistance elements in high-temperature furnace applications are simultaneously shifting procurement geography toward Japanese and South Korean ceramic manufacturers while compressing pricing premiums for legacy alloy-based systems. This substitution dynamic redistributes value capture upstream and forces incumbent resistance element producers into defensive cost repositioning.
Pricing Analysis
Long-term offtake agreements dominate procurement for precision manufacturing applications, while spot purchasing persists in commodity facility heating. Three-tier pricing structure across premium, standard, and economy levels separates IEC 60519-certified systems with predictive maintenance integration from basic resistance units. Cost compression in economy-tier convection heaters is intensifying because Indonesian nickel ore export restrictions feed alloy input volatility. Pharmaceutical freeze-drying operators show least price sensitivity; textile drying cooperatives in emerging manufacturing clusters absorb maximum budget pressure.
Supply Chain Analysis
Indonesia and Russia anchor nickel-chromium alloy feedstock for resistance element production; Japan and Germany concentrate silicon carbide ceramic core manufacturing. Supply chains draw from Chinese rare earth processing for induction frequency converters and South Korean power electronics assembly. Single-source vulnerability in Russian nickel refining exposes European heater manufacturers to sanction-driven input disruption. Distribution runs through regional fabrication centers with OEM direct sales for precision applications and distributor networks for replacement parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified thermal systems engineering capacity is contracting faster than replacement training pipelines can replenish, concentrating pricing power with incumbent service organizations and fragmenting competitive dynamics across installation and compliance auditing segments.
For Market Incumbents: Compound captive alloy supply advantages through backward integration into nickel-chromium sheathing production, insulating margin structures from Indonesian ore volatility. Accelerate sensor-embedded heater development to capture digital twin convergence premiums before mid-tier competitors achieve IEC 60519 compliance certification. Defend position against induction technology substitution by embedding resistance systems within integrated thermal loop architectures that raise switching costs for precision manufacturing buyers. For New Entrants and Emerging Players: Differentiate on asset-as-service contracting capabilities for pharmaceutical and semiconductor precision applications, where uptime guarantees outweigh capital ownership preferences. Target South Korean battery gigafactory corridors for electrode drying tunnel installations, where demand absorption outpaces incumbent service capacity. Penetrate through predictive maintenance platform integration rather than equipment-only positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional fabrication specialists holding dense installed base service relationships but lacking digital capability investment. Frame long-term viability around electrification mandate durability and regulatory compliance service intensity rather than equipment shipment cyclicality. Watch EPA NOx reduction timeline acceleration and EU Green Deal enforcement stringency as inflection signals for electric retrofit demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Sheathing | Captive nickel-chromium supply insulates Chromalox and Watlow from Indonesian ore export volatility. |
| Sensor-Embedded Heater Development | Predictive maintenance integration commands pharmaceutical freeze-drying premiums in Switzerland and Singapore. |
| Asset-as-Service Contracting Model | Per-wafer-processed pricing concentrates ownership risk with OEMs while guaranteeing precision manufacturer uptime. |
| Induction Frequency Converter Partnership | Solid-state power supply alliances enable Japanese automotive suppliers to achieve ±2°C thermal uniformity. |
| Regional Fabrication Center Expansion | Local service density in Busan-Ulsan battery corridors captures South Korean gigafactory electrode drying demand. |
Methodological Framework
Initial hypotheses were tested against primary input from plant engineers at chemical processing facilities, thermal systems procurement leads at automotive OEMs, aftermarket service heads at regional heater distributors, and IEC 60519 compliance auditors, then refined against secondary validation from SEC 10-K filings of listed industrial equipment manufacturers, customs trade data for nickel-chromium alloy imports, EPA enforcement action databases, and EU ETS emissions accounting disclosures. Bottom-up demand modeling across end-use segments triangulated with top-down macroeconomic scenario analysis.
Variance decomposition across technology substitution rates, regulatory compliance deadline shifts, and raw material input cost trajectories structured the analytical framework over the projection horizon. Segmentation dimensions modeled include heater product category, end-use industry, heat transfer technology, application temperature range, and regional regulatory cluster. CAGRs were derived from installed base replacement cycle compression and greenfield capital expenditure patterns. Forecast inputs incorporated EPA NOx reduction timeline probability distributions and EU Green Deal transition financing availability.
Material uncertainties — nickel supply disruption from Indonesian export policy shifts, grid infrastructure upgrade delays in US Gulf Coast petrochemical corridors, and induction frequency converter thermal management breakthroughs — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement continuity and electrification financing access. Recalibration cycles align with material shifts in EPA enforcement stringency and EU carbon border adjustment implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Elastomeric Couplings Market
Industrial Materials
Pultrusion Products Market
Industrial Materials
Grouting Materials Market
Industrial Materials
Wood Shavings Market
Industrial Materials
Global Melamine Faced Chipboard (MFC) Market
Industrial Materials
Europe Wood Activated Carbon Market
Industrial Materials
Flat Scroll Spring Market
Industrial Materials
Industrial Furnaces Market
Industrial Materials
Global Cast Acrylic Sheet Market
Industrial Materials
Wood Protein Market
Industrial Materials
Wire Mesh Market
Industrial Materials
Lip Seals Market
Industrial Materials
Warehouse Drums and Barrels Market
Industrial Materials
Magnet Rings Market
Industrial Materials
Global Medical Plastics Extrusion Market
Industrial Materials
Industrial Brushes Market