
 Isotropic Graphite Market | 2026-2036
Isotropic Graphite Market Size, Share, and Industry Trends Forecast 2026-2036
Isotropic Graphite Market Analysis
Silicon carbide is expanding its displacement of conventional silicon substrates in power electronics, elevating crucible-grade isotropic graphite to a critical-process material. Toyo Tanso Co. Ltd. anchors Japanese supply chains through captive needle coke refining and precision machining capabilities. SGL Carbon differentiates via backward integration into carbon fiber precursors and specialized graphitization furnaces. Fangda Carbon New Material Co. Ltd. dominates volume production of coarse-grain electrodes while navigating quality upgrades for semiconductor-grade specifications.
Isotropic graphite is a synthetic carbon material manufactured through cold isostatic pressing of fine petroleum coke or pitch coke powders followed by graphitization above 2800°C, yielding uniform thermal and electrical conductivity in all axial directions. Its primary purpose centers on high-temperature process equipment where thermal shock resistance and dimensional stability govern yield rates. High-purity grades command premium positioning in semiconductor crystal pulling applications where metallic impurity thresholds sit below 5 ppm. Energy storage applications, particularly lithium-ion battery anode substrates, represent the fastest-expanding consumption pool though margin structures remain compressed against electronics-grade benchmarks. Fine grain categories sustain mature demand profiles in electrical discharge machining electrodes across Japanese and German toolmaking sectors.
Japan's METI enforces JIS standards governing graphite purity classifications for nuclear and semiconductor end-uses, creating certification barriers for non-domestic suppliers. China's SAMR and MIIT coordinate GB standards alignment with dual carbon targets, restricting high-emission graphitization capacity expansions in Shandong and Henan provinces. The EU REACH framework and F-Gas Regulation indirectly shape isotropic graphite demand by accelerating heat pump and electric compressor adoption that relies on SiC power modules. Stakeholders must monitor crucible recycling economics and synthetic graphite life-cycle assessments as downstream OEMs embed Scope 3 carbon accounting into supplier qualification protocols.
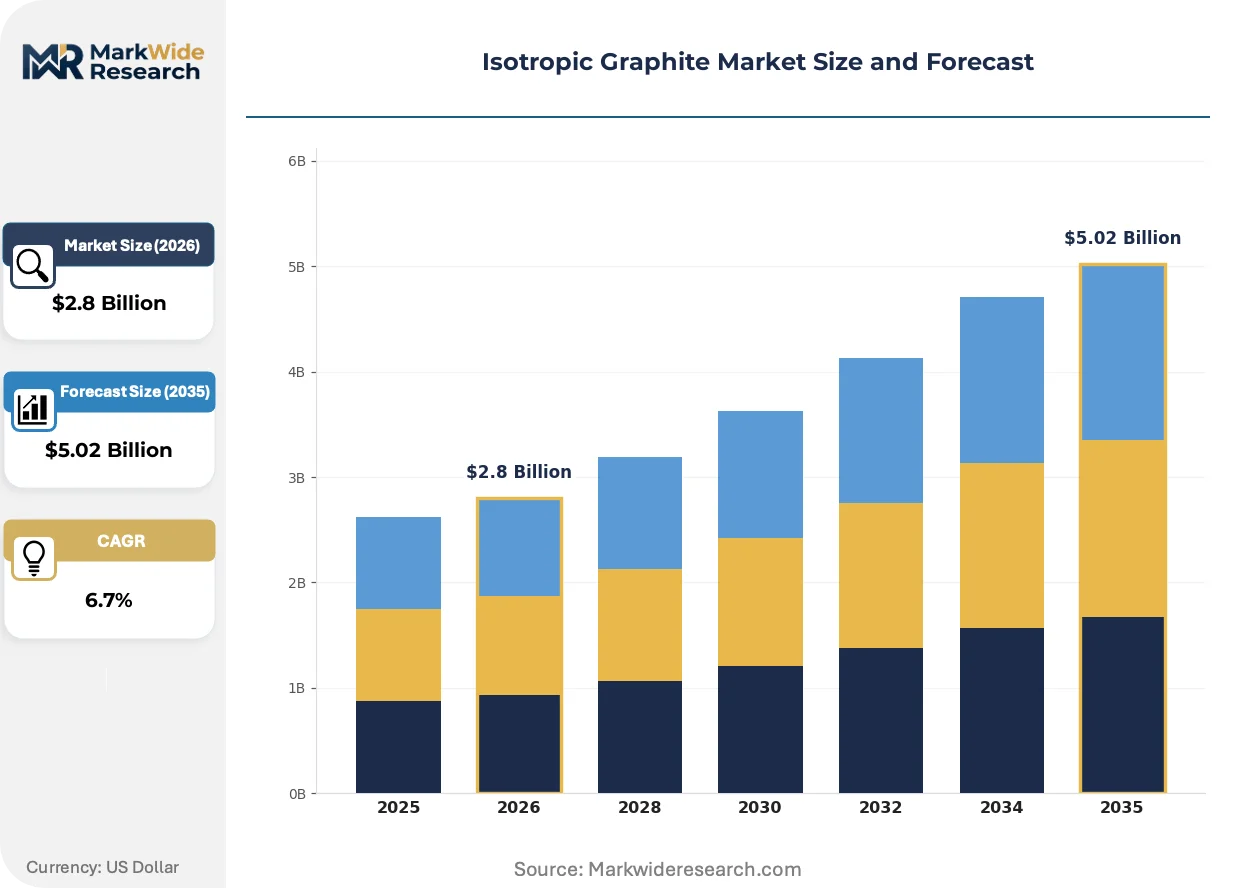
Market Dynamics
Silicon carbide substrate manufacturing is concentrating demand for ultra-high-purity isotropic graphite crucibles, creating supply bottlenecks at graphitization furnace capacity while semiconductor foundries qualify second-source suppliers.
Growth Catalysts
- Silicon carbide crystal pulling:Power electronics manufacturers in Taiwan and South Korea are expanding SiC epitaxy capacity, multiplying crucible consumption per wafer against silicon equivalents. Automotive inverter programs at Hyundai and Toyota accelerate qualification timelines.
- Dual carbon targets:China's MEE emissions standards are shuttering antiquated graphitization capacity in Shandong, concentrating output at compliant facilities with captive needle coke supply. GB standard alignment favors synthetic graphite over mined alternatives in carbon accounting protocols.
- Heat pump electrification:The EU F-Gas Regulation is accelerating SiC power module deployment in residential compressors, indirectly lifting crucible-grade graphite specifications through module manufacturer tier-one supplier requirements.
Market Restraints
- Needle coke supply concentration:Premium feedstock for semiconductor-grade graphite concentrates among Japanese and US petroleum coke refiners, exposing crucible manufacturers to price volatility when coker maintenance cycles tighten spot markets.
- Graphitization energy intensity:Furnace operations above 2800°C consume 6-8 MWh per tonne, rendering capacity expansion economically marginal where industrial electricity tariffs exceed renewable-powered Chinese benchmarks.
- Metallic impurity floors:Current purification technology achieves 3-5 ppm total ash content for nuclear and semiconductor specifications, but sub-ppm thresholds required for next-generation SiC boule growth remain technically elusive without secondary halogen treatment.
Strategic Opportunities
- Crucible recycling infrastructure:Spent semiconductor crucibles retain 85% carbon purity, creating feedstock arbitrage for secondary graphitization in India where BIS standards for recycled carbon materials are formalizing quality tiers.
- Solid-state battery anode substrates:Lithium-metal and sulfide electrolyte cell architectures require dimensionally stable current collectors, positioning fine-grain isotropic graphite as a silicon-anode alternative with superior cycle-life characteristics.
- EU Green Deal carbon border adjustments:Scope 3 accounting requirements for imported graphite products are incentivizing European OEMs to qualify low-emission graphitization sources, creating premium pricing tiers for renewable-powered production.
Industry Challenges
- Precision machining workforce scarcity:Crucible dimensional tolerances of ±0.1 mm for SiC crystal growth require machinists trained on five-axis CNC graphite centers, a skill pool concentrated in Japan's Nagoya and Germany's Bavaria industrial corridors.
- Extended qualification protocols:Semiconductor foundry crucible approval spans 18-24 months of crystal yield validation, locking supplier relationships and delaying revenue recognition for capacity expansions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isotropic Graphite Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Purity, Fine Grain, Coarse Grain, Synthetic Application: Electronics, Aerospace, Automotive Components, Energy Storage End User: Manufacturers, Research Institutions, Energy Sector, Automotive OEMs Distribution Channel: Direct Sales, Online Retail, Distributors, Future Contracts |
| Companies Covered | Toyo Tanso Co. Ltd., Tokai Carbon Co. Ltd., Mersen SA, SGL Carbon, GrafTech International, Nippon Carbon Co. Ltd., Ibiden Co. Ltd., Fangda Carbon New Material Co. Ltd., Poco Graphite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isotropic Graphite Market Emerging Trajectories
Cold isostatic pressing and graphitization process control is unifying quality tiers across regional supply bases while regulatory carbon accounting and buyer consolidation reshape competitive differentiation.
Near-net-shape isostatic pressing is unifying dimensional consistency across coarse and fine grain categories, enabling crucible manufacturers to reduce machining waste by 30% while maintaining thermal shock resistance. Korean and Japanese SiC wafer producers are adopting these preforms for 200mm boule growth, compressing the cost gap between standard and premium graphite grades.
Japan's METI JIS H 7212 purity classification revision is tightening metallic impurity thresholds for nuclear-grade isotropic graphite, forcing non-domestic suppliers to invest in secondary purification or accept market exclusion. The standard's 2024 amendment extends certification requirements to semiconductor crucible applications, accelerating supplier consolidation around Tokyo and Osaka industrial clusters.
Long-term offtake contracting is displacing spot purchasing for crucible-grade material as silicon carbide wafer manufacturers secure volume commitments ahead of 2025-2026 fab ramp schedules. This concentration of procurement authority at tier-one SiC substrate producers in Taiwan and Germany is compressing margin structures for graphite converters lacking backward integration into needle coke or graphitization capacity.
Isotropic Graphite Market Segmentation
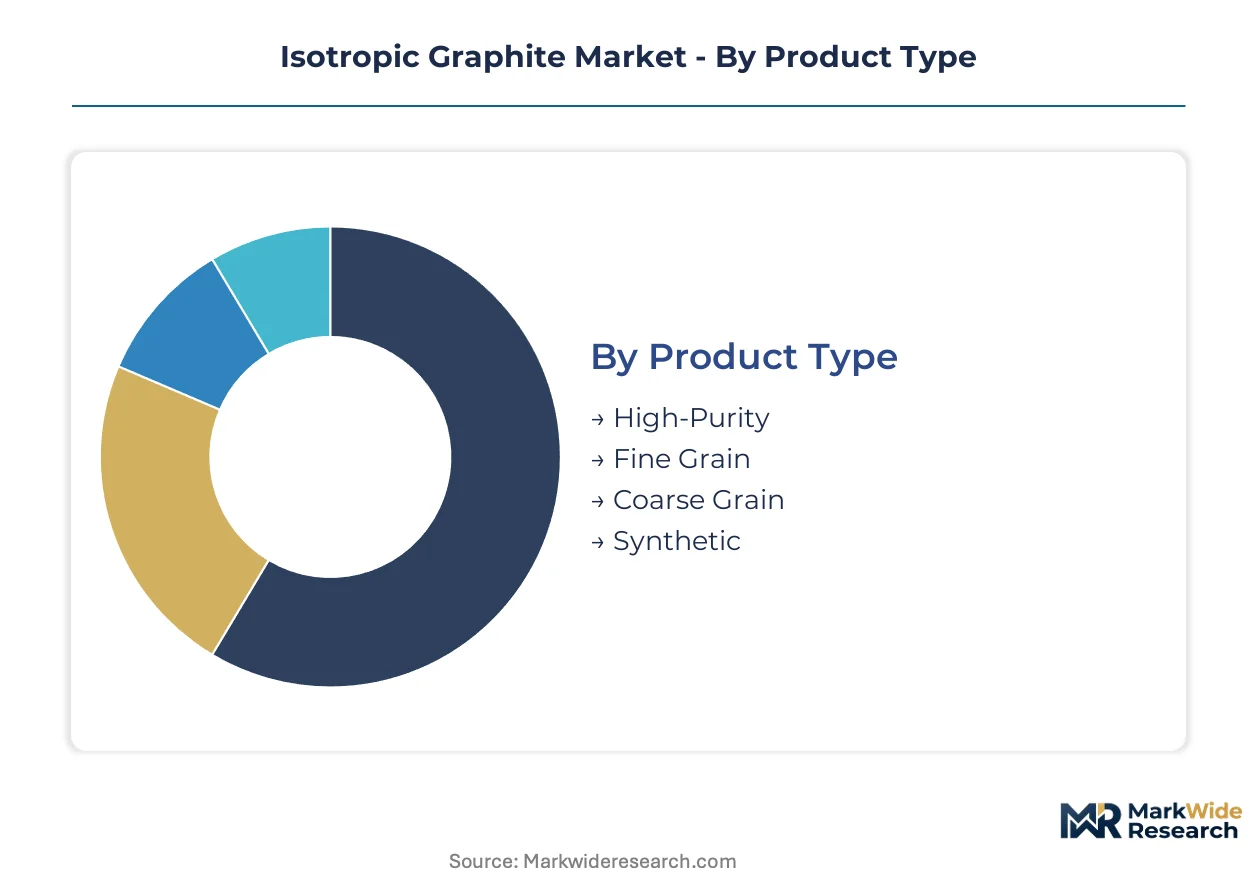
Isotropic graphite supply chains fragment across purity grades and grain structures, with each tier commanding distinct qualification protocols and margin profiles. Semiconductor foundries, automotive inverter programs, and solid-state battery developers source from overlapping but non-substitutable product categories.
Product Type:
Needle coke refining capacity and graphitization furnace availability concentrate supply of premium grades in Japan and select Chinese facilities with captive energy supply.
- High-Purity:Total metallic impurity content below 5 ppm, achieved through secondary halogen treatment and extended graphitization cycles above 3000°C. Semiconductor crucible manufacturers in Taiwan and South Korea qualify this grade for silicon carbide boule growth, where metallic contamination degrades crystal lattice integrity.
- Fine Grain:Particle size distribution below 20 microns enables precision machining to ±0.05 mm tolerances for electrical discharge machining electrodes. Japanese toolmakers in Nagoya and German mold-making clusters sustain mature demand despite slower volume expansion.
- Coarse Grain:Cost-optimized for metallurgical applications and aluminum smelting electrodes where thermal shock resistance outweighs dimensional precision requirements.
- Synthetic:Manufactured from petroleum coke or pitch coke precursors rather than mined graphite, aligning with China's dual carbon accounting protocols and EU Scope 3 emissions tracking.
High-Purity absorbs the bulk of installed capacity; Synthetic is expanding most quickly.
Application:
End-use demand stratifies by thermal management intensity and purity thresholds, with power electronics and next-generation batteries driving specification upgrades.
- Electronics:Silicon carbide substrate manufacturing consumes ultra-high-purity crucibles for physical vapor transport crystal growth. Taiwan-based foundries and German automotive tier-one suppliers enforce 18-24 month qualification timelines that lock supplier relationships.
- Energy Storage:Lithium-ion battery anode substrates and emerging solid-state cell architectures require dimensionally stable current collectors. Fine-grain isotropic graphite competes with silicon anodes on cycle-life performance in Korean and Chinese cell manufacturing.
- Aerospace:Thermal protection systems and rocket nozzle components utilize medium-purity grades where ablation resistance governs material selection.
- Automotive Components:Brake systems and sealing applications in high-performance vehicles employ coarse-grain formulations with compressed graphite for friction stability.
Electronics commands premium pricing tiers; Energy Storage is climbing the fastest.
End User:
Procurement authority concentrates at integrated manufacturers with backward control over crystal growth and cell assembly operations.
- Manufacturers:Semiconductor foundries and graphite component fabricators in Japan's Osaka industrial corridor and China's Yangtze River Delta dominate volume procurement. Long-term offtake contracting now displaces spot purchasing for crucible-grade material.
- Automotive OEMs:Hyundai and Toyota inverter programs accelerate SiC module qualification, indirectly lifting graphite specifications through tier-one supplier requirements.
- Research Institutions:National laboratories and university consortia source small-batch high-purity material for next-generation reactor and battery chemistry validation.
- Energy Sector:Utility-scale battery integrators and nuclear operators specify certified grades under JIS H 7212 and emerging BIS recycled carbon standards.
Manufacturers absorb the bulk of installed capacity; Automotive OEMs is expanding most quickly.
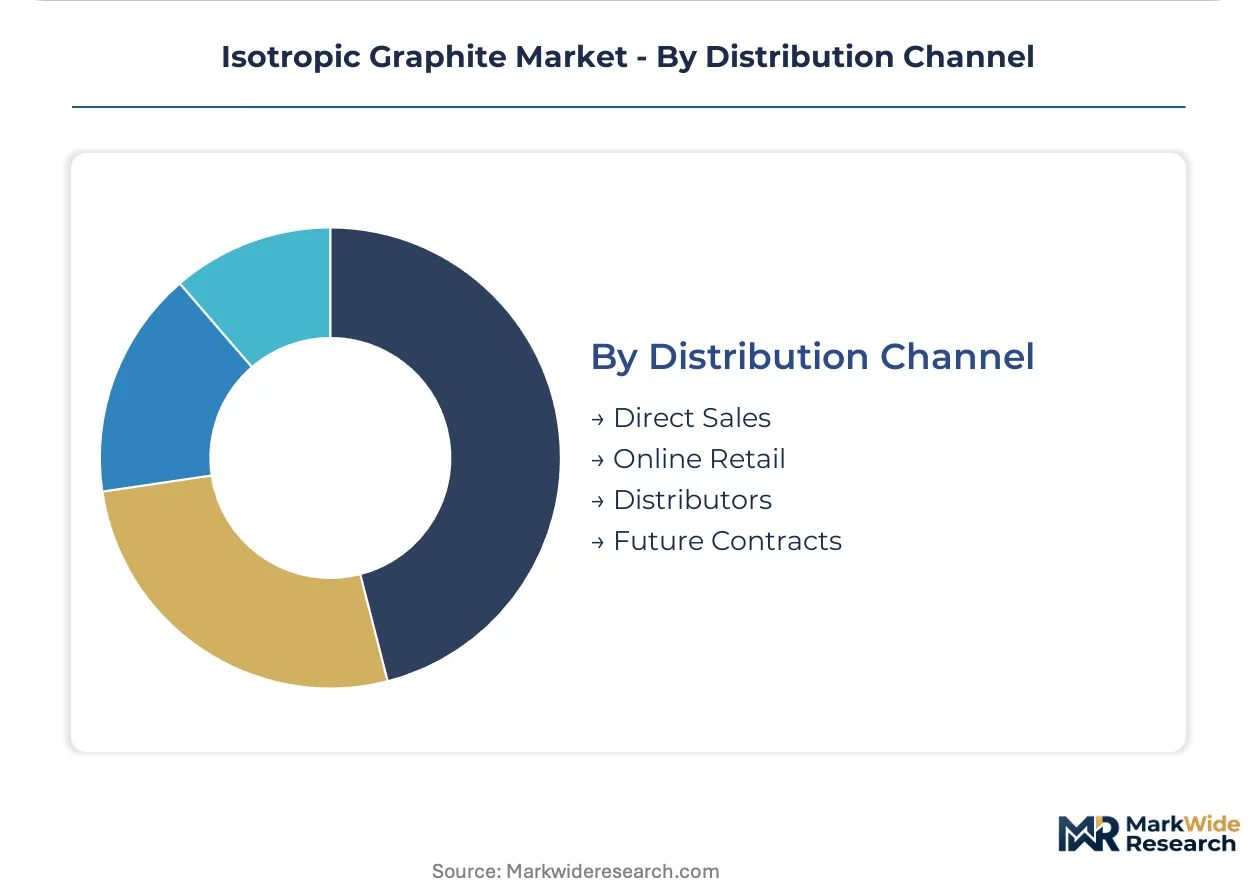
Distribution Channel:
Channel selection correlates with batch size, certification requirements, and the buyer's technical integration capabilities.
- Direct Sales:High-purity semiconductor crucibles and aerospace-grade material move through mill-direct relationships with dedicated quality engineering support. Toyo Tanso and SGL Carbon maintain field technical service teams at major SiC wafer producers.
- Distributors:Coarse-grain electrodes and standard EDM grades flow through regional industrial distributors in Germany's Bavaria and Japan's Kyushu manufacturing clusters.
- Future Contracts:Long-term supply agreements with price adjustment mechanisms now cover 60-70% of crucible-grade volume as silicon carbide wafer manufacturers secure commitments ahead of fab ramp schedules.
- Online Retail:Limited to small-batch research quantities and replacement EDM electrodes where technical specification is standardized.
Direct Sales absorbs the bulk of installed capacity; Future Contracts is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones and Japan's Kyushu industrial corridor concentrate isotropic graphite demand through semiconductor foundry clustering and captive needle coke refining infrastructure.
China
Silicon carbide wafer manufacturers in the Yangtze River Delta and Pearl River Delta are scaling crucible procurement for 200mm boule growth. MEE emissions standards are shuttering antiquated graphitization capacity in Shandong and Henan provinces. Compliant facilities with captive needle coke supply in Jiangsu and Zhejiang provinces are absorbing displaced output.
Japan
METI JIS H 7212 purity classifications govern nuclear and semiconductor-grade material, creating certification barriers for non-domestic suppliers. The 2024 amendment extends requirements to crucible applications. Tokyo and Osaka industrial clusters host precision machining capabilities for ±0.1 mm dimensional tolerances.
South Korea
Automotive inverter programs at Hyundai and domestic SiC epitaxy expansion are multiplying crucible consumption per wafer. MFDS coordinates with industry on material traceability standards. Busan-Ulsan manufacturing corridors concentrate graphite component fabrication for power module supply chains.
Taiwan
Semiconductor foundries are qualifying second-source crucible suppliers amid supply bottlenecks at graphitization furnace capacity. The Hsinchu Science Park anchors silicon carbide substrate manufacturing. Extended 18-24 month qualification timelines lock supplier relationships.
Germany
EU F-Gas Regulation accelerates SiC power module deployment in residential heat pump compressors, indirectly lifting graphite specifications. ECHA REACH framework shapes Scope 3 carbon accounting for imported materials. Bavaria's industrial corridor sustains mature demand for electrical discharge machining electrodes.
Isotropic Graphite Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with high-purity crucible supply consolidating around backward-integrated needle coke refiners while coarse-grain electrode production fragments among volume converters. Three archetypes dominate: captive feedstock operators with in-house graphitization, precision machining specialists serving semiconductor foundries, and scale-driven converters of petroleum coke precursors. Competitive moves center on long-term offtake contracting for crucible-grade material and secondary purification investments for sub-5 ppm metallic impurity thresholds.
Among Japanese specialists, Toyo Tanso Co. Ltd. and Tokai Carbon Co. Ltd. exemplify the captive feedstock archetype through integrated needle coke refining capabilities. SGL Carbon occupies a position bridging European automotive tier-one requirements with specialized graphitization infrastructure. Fangda Carbon New Material Co. Ltd. represents the volume-driven Chinese converter segment navigating quality upgrades toward semiconductor-grade specifications.
| Leading Market Players |
|---|
| Toyo Tanso Co. Ltd. |
| Tokai Carbon Co. Ltd. |
| Mersen SA |
| SGL Carbon |
| GrafTech International |
| Nippon Carbon Co. Ltd. |
| Ibiden Co. Ltd. |
| Fangda Carbon New Material Co. Ltd. |
| Poco Graphite |
| Others |
Supply Flow & Price Mechanics
Needle coke spot price volatility cascades through semiconductor-grade isotropic graphite tiers, compressing margins for converters lacking captive feedstock while amplifying pricing power for Japanese refiners with integrated coker operations.
Pricing Analysis
Short lead-time premiums of 15-25% apply to crucible-grade material for silicon carbide foundries facing furnace maintenance cycles, while spot inventory of coarse-grain electrodes trades at discounts to contract benchmarks. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified semiconductor crucibles from industrial EDM grades and metallurgical electrodes. Cost compression in standard-grade material is intensifying because Chinese synthetic graphite capacity expansions are flooding coarse-grain segments. Automotive OEM procurement teams exhibit highest price sensitivity through tier-one supplier negotiations, whereas semiconductor foundries prioritize yield consistency over unit cost.
Supply Chain Analysis
Regional distribution centers in Osaka, Nagoya, and Busan maintain 60-90 day crucible inventories for just-in-time delivery to silicon carbide wafer producers, with hub-and-spoke patterns radiating from graphitization clusters. Geographic supply concentration centers on Japan, China, and South Korea, where needle coke refining and precision machining capabilities overlap. Raw material dependencies draw from petroleum coker byproducts, pitch coke precursors, and secondary carbon feedstocks. Single-source vulnerability concentrates at Japanese needle coke refiners supplying ultra-high-purity grades. Distribution runs through mill-direct relationships for certified material and regional industrial distributors for standard electrodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isotropic graphite supply chains are consolidating around backward integration into needle coke refining, with players racing to secure captive feedstock as qualification timelines lock supplier relationships.
For Market Incumbents: Anchor market position through secondary halogen purification investments for sub-5 ppm metallic impurity thresholds under revised JIS H 7212 standards. Deepen upstream control over needle coke supply by acquiring distressed coker capacity in Jiangsu province before MEE compliance deadlines shutter competitors. Threat from Chinese synthetic graphite converters upgrading toward semiconductor specifications demands preemptive certification barriers. For New Entrants and Emerging Players: Direct-to-foundry digital procurement platforms offer white-space entry for small-batch crucible qualification, bypassing entrenched distributor relationships. Target India's emerging silicon carbide substrate manufacturing through BIS-aligned recycled carbon material tiers. Solid-state battery anode substrate development presents the most penetrable application segment with less entrenched supplier lock-in. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision machining specialists with five-axis CNC graphite capabilities in Japan's Nagoya industrial corridor as extended qualification timelines strain working capital. Long-term viability hinges on exposure to semiconductor-grade certification rather than commoditized electrode segments. Watch for inflection when silicon carbide wafer manufacturers announce second-source qualification completions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Needle Coke Refining | Captive feedstock supply insulates margin structures from petroleum coker price volatility at Japanese refiners. |
| Secondary Halogen Purification Investment | Sub-5 ppm metallic impurity achievement unlocks JIS H 7212 certification for nuclear and semiconductor crucible applications. |
| Long-term Offtake Contracting | Volume commitments with price adjustment mechanisms secure revenue recognition ahead of 18-24 month qualification cycles. |
| Crucible Recycling Infrastructure Buildout | Secondary graphitization of spent semiconductor crucibles creates feedstock arbitrage under formalizing BIS recycled carbon standards. |
| Precision Machining Workforce Development | Five-axis CNC graphite center training programs address ±0.1 mm dimensional tolerance requirements for SiC crystal growth. |
Methodological Framework
Multi-period observation of needle coke price indices, graphitization furnace utilization rates, and semiconductor foundry capex cycles anchored the trend analysis, supplemented by interviews with crucible procurement managers at Taiwan-based SiC wafer producers, METI certification officers, and needle coke refinery operations directors. Secondary validation drew from customs trade data, SEC filings of listed graphite converters, JIS standard revision documents, and MEE emissions compliance disclosures. Bottom-up volume estimates triangulated against top-down market sizing across purity grades and grain structures.
Input-output matrix modeling connected needle coke supply availability to graphitization capacity expansion economics, segmented by high-purity semiconductor-grade, fine-grain EDM-grade, and coarse-grain metallurgical-grade tiers across the analysis window. CAGRs derived from regression of historical price-volume relationships against silicon carbide wafer production forecasts and solid-state battery commercialization timelines. Industry-specific inputs included JIS H 7212 certification adoption rates and MEE-compliant facility commissioning schedules.
The model holds under stable needle coke supply concentration and sustained silicon carbide substrate manufacturing expansion; deviation in Chinese synthetic graphite export policy or abrupt SiC epitaxy demand shifts would revise volume trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Melamine Market
Industrial Materials
Industrial Gaskets Market
Industrial Materials
Vinyl Extrusion Equipment Market
Industrial Materials
Steel Wire Rope and Plastic Rope Market
Industrial Materials
Global Graphite Electrode Rod Market
Industrial Materials
Paint Knife Market
Industrial Materials
Industrial Drum Market
Industrial Materials
Gravity Die Casting Market
Industrial Materials
Natural Industrial Absorbents Market
Industrial Materials
Industrial Pails and Drums Market
Industrial Materials
Extruders Market
Industrial Materials
Petrochemical Fasteners Market
Industrial Materials
Industrial Films Market
Industrial Materials
Food Grade Nylon Market
Industrial Materials
Metal Stamping Market
Industrial Materials
Wear-Resistant Welding Wire Market