

High Performance Random Packing Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Random Packing Market Insights
Polypropylene is hardening its position against metal in corrosive service applications across water treatment and chemical processing. Koch-Glitsch leverages its deep distillation engineering heritage to anchor large-format plastic packing contracts in North American refineries. Sulzer competes through integrated column internals portfolios that extend beyond random packing into structured alternatives and distributor systems.
High performance random packing consists of engineered geometric elements—typically rings, saddles, or specialized shapes—installed in process columns to maximize gas-liquid contact surface area while minimizing pressure drop, with specific surface areas ranging from 100 to 500 m²/m³ depending on size and material. These packings serve primarily to enhance mass transfer efficiency in separation processes across chemical, petrochemical, and environmental applications. Metal packings still dominate high-temperature distillation in refineries, while plastic variants capture growth in scrubbing and stripping applications where corrosion resistance outweighs thermal limits. Ceramic segments occupy margin-rich niches in aggressive acid gas service, particularly within sulfur recovery and halogenated chemical production.
EPA emissions standards tighten allowable volatile organic compound releases from chemical process vents, directly expanding scrubbing system upgrades that consume engineered plastic packings. REACH restrictions on nickel alloys and chromium compounds shape material selection in European chemical plants, accelerating ceramic and composite validation programs. OSHA process safety management requirements mandate column integrity assessments that drive replacement cycles for degraded legacy packings. Stakeholders must monitor how evolving carbon border adjustment mechanisms reshape cost competitiveness between regional packing suppliers and integrated column internals providers.
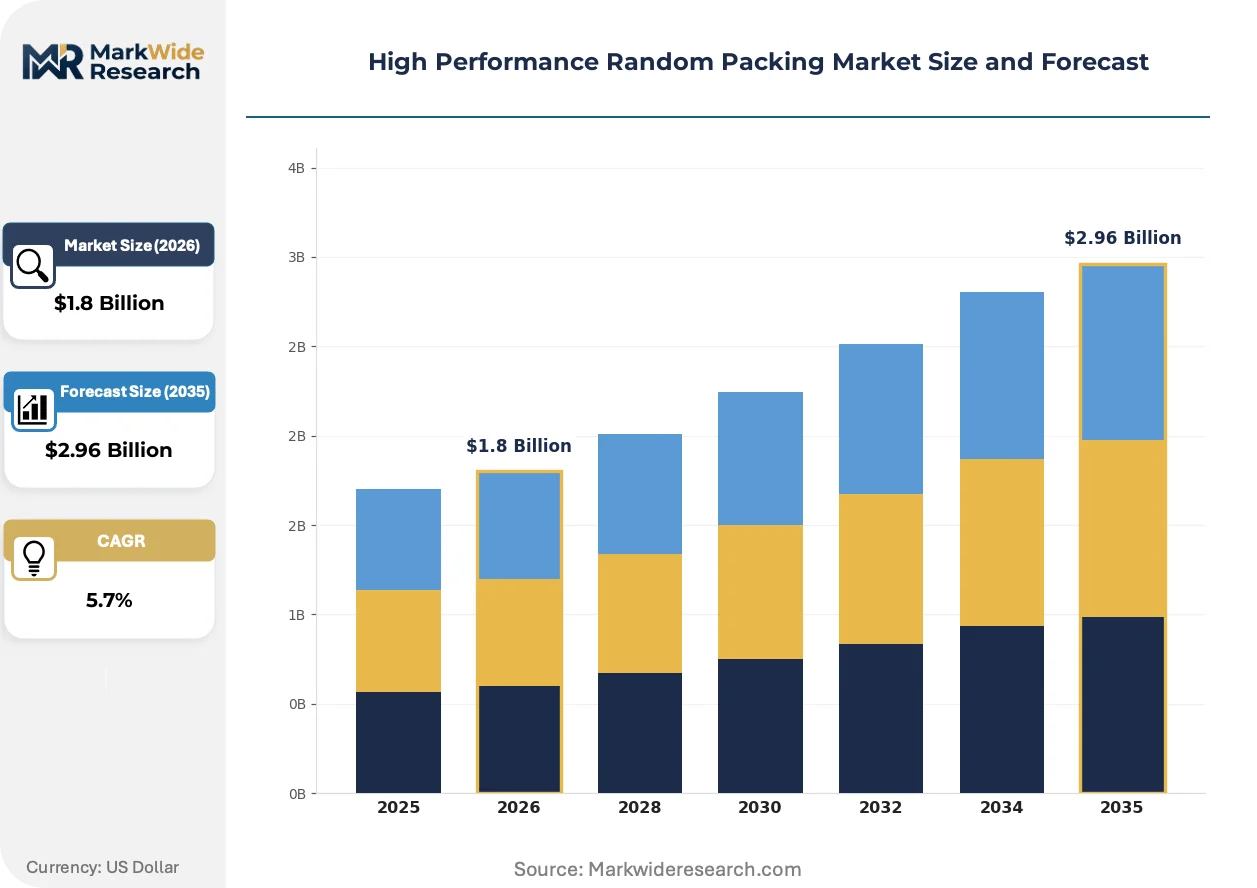
Market Dynamics
Retrofit cycles in aging petrochemical columns are compressing replacement timelines, while REACH-driven material substitution is forcing ceramic and composite packings into service roles historically dominated by nickel alloys.
Growth Catalysts
- EPA Emissions Standards:Tightened volatile organic compound limits on chemical process vents mandate scrubbing system upgrades across US Gulf Coast refineries.
- China Chemical Expansion:Distillation capacity additions for specialty polymers and fine chemicals in Jiangsu and Zhejiang provinces drive bulk procurement of high-surface-area plastic packings.
- Corrosion-Resistant Polypropylene:Water treatment facilities facing chlorinated solvent exposure specify thermoplastic random packing over stainless steel to extend column service life.
Market Restraints
- Specialty Alloy Input Costs:Molybdenum and nickel price volatility squeezes margin on high-temperature metal packing production for refinery service.
- Ceramic Supply Concentration:Advanced alumina-silicate manufacturing clusters in Germany and Japan create single-source vulnerability for acid-gas-resistant packings.
- REACH Nickel Alloy Restrictions:ECHA authorization requirements delay validation timelines for legacy metal packing formulations in European sulfur recovery units.
Strategic Opportunities
- India Petrochemical Buildout:Reliance Industries and Indian Oil Corporation expansion projects in Gujarat create first-mover advantage for integrated column internals suppliers.
- Carbon Capture Retrofits:Amine-based post-combustion capture systems at coal-fired power stations specify large-diameter plastic packings for absorber column construction.
- EU Green Deal Funding:Circular economy transition grants support validation of recyclable thermoplastic packings in bio-based chemical production facilities.
Industry Challenges
- Mass Transfer Modeling Expertise:Shortage of chemical engineers proficient in computational fluid dynamics for column internals design extends project commissioning timelines.
- Legacy System Integration:Retrofit projects require custom distributor redesigns to match existing column geometries, complicating specification standardization.
- REACH Pre-registration Burden:Small ceramic packing manufacturers face disproportionate compliance costs relative to revenue for novel composite material certifications.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Random Packing Market Trends and Innovations
Computational design tools and advanced manufacturing are enabling geometric optimization of packing elements previously constrained by conventional molding and metal-forming limitations.
3D-printed lattice packings with variable porosity profiles are integrating into pilot-scale distillation columns at specialty chemical producers seeking tunable pressure-drop characteristics. German engineering contractors specify these geometries for azeotropic separations where conventional Pall rings create excessive liquid maldistribution. The technology is integrating mass transfer modeling directly into fabrication workflows, collapsing the traditional design-prototype-test cycle.
REACH authorization requirements for chromium(VI) compounds in metal surface treatments are accelerating plasma-sprayed ceramic coating adoption on stainless steel substrates. European column internals fabricators face reformulation deadlines that compress validation schedules for acid-service packings. German chemical parks now require coating certifications from ECHA-registered applicators, shifting procurement criteria toward integrated material-coating suppliers.
Engineering-procurement-construction firms are consolidating vendor lists to single-source column internals packages spanning random packing, structured packing, and liquid distributors. Refinery operators in the US Gulf Coast specify integrated performance guarantees rather than component-level procurement, displacing fragmented multi-vendor arrangements. This concentration is most visible in ethylene cracker revamps where lump-sum turnkey contracts transfer operational risk to column internals specialists.
High Performance Random Packing Market Segmentation
Material selection governs thermal limits and corrosion resistance in column service, while application geometry dictates mass transfer efficiency requirements. End-user specifications cascade through size and configuration choices, creating interdependent procurement decisions across chemical process industries.
Material Type:
Buyers weigh capital cost against service life when specifying packing materials for corrosive or high-temperature duty.
- Metal:Stainless steel and specialty alloy packings withstand temperatures exceeding 400°C in refinery fractionation columns. Demand concentrates in US Gulf Coast ethylene crackers where FCCU revamps specify high-void-fraction metal rings for coker fractionator service.
- Plastic:Polypropylene and PVDF formulations resist chlorinated solvents and acid gases in scrubbing applications. Water treatment facilities in Jiangsu province specify thermoplastic packings for VOC recovery systems facing halogenated compound exposure.
- Ceramic:Alumina-silicate structures serve sulfuric acid and nitric acid distillation with thermal stability beyond 1000°C. German chemical parks mandate REACH-compliant ceramic alternatives for nickel-restricted acid gas service.
- Composite:Fiber-reinforced thermoset matrices combine corrosion resistance with structural rigidity for aggressive halogenated chemical production.
- Porcelain:Traditional glazed ceramic packings retain niche positions in food-grade and pharmaceutical distillation where inertness requirements preclude metal ion leaching.
Volume sits with Metal; growth tilts toward Plastic.
Application:
Process thermodynamics and separation difficulty determine which mass transfer operation dominates procurement specifications.
- Distillation:Vapor-liquid equilibrium separations in petrochemical columns require high-surface-area packings with low pressure drop characteristics. Refinery operators in India specify large-diameter metal packings for crude unit atmospheric columns.
- Scrubbing:Gas-liquid contact for pollutant removal drives plastic packing adoption in environmental compliance retrofits. EPA-mandated VOC controls at Texas chemical plants expand engineered plastic ring procurement for vent gas treatment.
- Absorption:Solvent-based capture systems for carbon dioxide and acid gases specify plastic packings with optimized wettability profiles.
- Stripping:Volatile component removal from liquid streams favors high-void-fraction geometries in wastewater and process water treatment.
- Extraction:Liquid-liquid mass transfer operations in specialty chemical production employ structured random packings for phase dispersion control.
Distillation commands installed base; scrubbing climbs the fastest on regulatory compulsion.
Size:
Column diameter and liquid load establish the hydraulic diameter requirements for efficient phase distribution.
- Small:Packings under 25mm suit laboratory and pilot-scale columns with high specific surface area requirements for difficult separations.
- Medium:25-50mm elements balance pressure drop against mass transfer efficiency in mid-scale chemical production columns.
- Large:50-75mm geometries minimize pressure drop in high-capacity refinery fractionators processing heavy hydrocarbon feeds.
- Extra Large:Elements exceeding 75mm address severe fouling service in coker fractionators and heavy oil upgrading units where open structure prevents blockage.
Medium sizes dominate unit shipments; extra large configurations gain share fastest in heavy oil processing expansions.
End User:
Process intensity and regulatory exposure create divergent material specifications across industrial sectors.
- Petrochemical Plants:Ethylene crackers and aromatics complexes drive demand for high-temperature metal packings with integrated column internals packages.
- Chemical Producers:Specialty and fine chemical manufacturers specify corrosion-resistant plastics and ceramics for multi-product batch distillation campaigns.
- Water Treatment:Municipal and industrial wastewater facilities specify polypropylene packings for air stripping of volatile organics and ammonia removal.
- Power Generation:Flue gas desulfurization and carbon capture retrofits at coal-fired stations specify large-diameter plastic packings for absorber column construction.
- Food Processing:Edible oil refining and beverage distillation require FDA-compliant materials with documented extractables profiles.
Petrochemical plants anchor volume; power generation shows steepest expansion trajectory on carbon capture buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical capacity expansions concentrate demand across four distinct national markets, each shaped by local regulatory regimes and industrial cluster development.
China
Jiangsu and Zhejiang provinces drive distillation capacity additions for specialty polymers and fine chemicals. MEE enforcement of dual carbon goals accelerates retrofit timelines for aging aromatic complexes. Yangtze River Delta chemical parks specify high-surface-area plastic packings for multi-product batch campaigns.
United States
Gulf Coast ethylene cracker revamps and FCCU upgrades sustain demand for high-temperature metal packings. EPA emissions standards tighten VOC limits on chemical process vents, mandating scrubbing system retrofits. Texas chemical plants along the Houston Ship Channel expand engineered plastic procurement for vent gas treatment systems.
Germany
REACH authorization requirements for nickel alloys and chromium compounds reshape material selection in chemical parks. ECHA-registered coating applicators now certify plasma-sprayed ceramic alternatives for acid-service columns. Ludwigshafen and Leverkusen chemical clusters validate REACH-compliant ceramic packings for sulfur recovery units.
India
Reliance Industries and Indian Oil Corporation expansion projects in Gujarat create procurement volume for integrated column internals packages. BIS standards for pressure vessel materials influence packing specification protocols. Dahej and Hazira petrochemical complexes specify large-diameter metal packings for crude unit atmospheric columns.
Saudi Arabia
SABIC and downstream derivative projects in Jubail Industrial City drive demand for corrosion-resistant packings in halogenated chemical production. The country's national standards body mandates material traceability for column internals in hydrocarbon service. Ras Al-Khair minerals processing cluster tests fiber-reinforced composite packings for aggressive acid gas environments.
High Performance Random Packing Market Competitive Landscape
Integrated performance guarantees dominate the current landscape as engineering-procurement-construction firms consolidate vendor lists to single-source column internals packages. The supplier base organizes around three archetypes: integrated column internals specialists, material-focused packing fabricators, and regional engineering contractors. M&A activity concentrates among distributors seeking captive manufacturing capacity, while technology licensing agreements proliferate for computational fluid dynamics design tools.
Among Swiss-anchored industrial conglomerates, Sulzer occupies a position exemplifying the integrated portfolio archetype, spanning random packing through structured alternatives and distributor systems. Koch-Glitsch, a US-based entity, represents the distillation engineering heritage segment, anchoring large-format plastic packing contracts in refinery applications. German-origin Raschig GmbH sits within the material-specialist tier, with its nomenclature directly tied to foundational packing geometries.
| Leading Market Players |
|---|
| Sulzer |
| Koch-Glitsch |
| Raschig |
| Munters |
| Finepac |
| RVT Process Equipment |
| MACH Engineering |
| MTE Group |
| Kimre |
| Others |
Pricing and Supply Chain Analysis
Molybdenum price index volatility cascades through specialty alloy supply chains, compressing margins on high-temperature metal packings while reinforcing price premiums on REACH-compliant ceramic alternatives in European chemical parks.
Pricing Analysis
Volume concentrates in standard-grade metal rings for refinery service, while margin pools in ceramic and composite packings for acid-gas applications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale. Pricing pressure stems from nickel and molybdenum input cost swings squeezing mid-tier metal packing producers. Water treatment facilities exhibit highest price sensitivity due to municipal procurement protocols, whereas petrochemical operators prioritize service life over unit cost.
Supply Chain Analysis
Freight cost differentials between German ceramic manufacturing clusters and Asian plastic molding centers reshape regional procurement patterns for column internals. Supply concentrates in Germany, Japan, and China for advanced alumina-silicate and thermoplastic formulations. Raw material flows draw from molybdenum mining operations in Chile, nickel laterite deposits in Indonesia, and polypropylene resin production in the US Gulf Coast. Single-source vulnerability pervades acid-gas-resistant ceramic supply. Distribution runs through engineering-procurement-construction firms consolidating vendor lists for integrated column internals packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where backward control over ceramic raw material processing and captive coating application capacity determines margin defense.
For Market Incumbents: Cement market position through captive supply of REACH-compliant ceramic substrates and plasma-sprayed coating capacity. Acquire ECHA-registered applicators to compress validation timelines for acid-service packings. Defend against integrated column internals specialists by bundling random packing with structured alternatives and distributor systems under single-source performance guarantees.
For New Entrants and Emerging Players: Begin with carbon capture retrofit opportunities at coal-fired power stations specifying large-diameter plastic packings for amine-based absorber columns. Target India's Gujarat petrochemical corridor where Reliance Industries and Indian Oil Corporation expansion projects seek first-mover integrated suppliers. Lead with computational fluid dynamics design capabilities that collapse traditional design-prototype-test cycles.
For Investors and Strategic Acquirers: Distressed-cycle entries favor material-specialist fabricators with ECHA-registered coating certifications in Germany's Ludwigshafen and Leverkusen chemical clusters. Long-term viability hinges on validation timelines for REACH-compliant alternatives displacing legacy nickel alloy packings. Monitor ECHA authorization schedules for chromium(VI) compounds as inflection signal for ceramic coating adoption acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Captive alumina-silicate supply secures margin pools in acid-gas service against REACH-driven substitution. |
| ECHA-Registered Coating Certification | Plasma-sprayed ceramic coating validation compresses procurement cycles in German chemical parks. |
| Integrated Column Internals Packaging | Single-source performance guarantees displace fragmented multi-vendor arrangements in US Gulf Coast refinery revamps. |
| Computational Design Tool Licensing | CFD-integrated fabrication workflows collapse commissioning timelines for 3D-printed lattice packing pilots. |
| Carbon Capture Absorber Specification | Large-diameter plastic packing contracts at coal-fired stations anchor growth in power generation segment. |
Research Methodology
Independent corroboration across plant managers at petrochemical facilities, procurement leads at downstream chemical producers, EPC contractors, and technical R&D directors at packing fabricators underwrites the qualitative findings. Primary interviews combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of listed column internals suppliers, and ECHA authorization databases. Bottom-up shipment data triangulated against top-down capacity estimates across material types and end-use segments.
Comparable-period anchoring to historical retrofit cycles and capacity expansion waves structured the projection horizon. Segmentation dimensions modeled include material grade tier, end-use industry intensity, column diameter configuration, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating molybdenum price index correlations and REACH compliance timeline assumptions. Industry-specific inputs encompass petrochemical cracker revamp schedules and MEE dual carbon goal enforcement patterns in China.
Underlying measurement precision varies by segment; ceramic and composite packings carry tighter precision than metal alternatives due to concentrated supply base visibility. Forecasts reflect assumptions regarding ECHA authorization timelines, nickel alloy substitution rates, and carbon capture buildout velocity. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.