
 Power Plant Lightning Protection Services Market | 2026-2036
Power Plant Lightning Protection Services Market Size, Share, and Industry Trends Forecast 2026-2036
Power Plant Lightning Protection Services Market Outlook
Independent power producers is bifurcating demand away from traditional utility procurement models as distributed generation assets multiply. Ingesco Lightning Solutions leverages its European installation footprint to anchor utility-scale contracts across Iberia and Northern Africa. Scientific Lightning Solutions LLC sustains R&D intensity in advanced strike characterization, while Dehn SE dominates surge protection device manufacturing through captive component production. LightningMaster Corporation competes on emergency response velocity, positioning its mobile assessment teams for rapid-deployment contracts.
Power plant lightning protection services encompass engineered systems that intercept, conduct, and dissipate atmospheric electrical discharges to prevent thermal generation asset damage, turbine control system failure, and substation insulation breakdown. These installations typically integrate air termination networks with impedance-controlled down conductors and low-resistance earth electrode arrays achieving below 10 ohms ground resistance. Installation services currently lead value capture due to capital-intensive tower and substation retrofit cycles, while surge protection device demand accelerates fastest as inverter-based renewable plants proliferate. Maintenance services occupy stable margin pools through recurring inspection contracts tied to IEC 62305 certification renewal cycles.
IEC 62305, NFPA 780, and IEEE 998 standards collectively define product performance thresholds and inspection cadences that determine market access for service providers. The US FAA coordinates with plant operators near airports on electromagnetic interference protocols, while China's GB 50057 governs lightning protection design for fossil and nuclear facilities. Stakeholders must monitor evolving grid code harmonization between IEC and national variants as renewable penetration reshapes protection system specifications.
Market Dynamics
Grid decentralization is fragmenting procurement authority across independent power producers, forcing service providers to rebuild go-to-market architectures around distributed asset clusters rather than centralized utility tenders.
Growth Catalysts
- IEC 62305 Compliance Mandates:Certification renewal cycles for thermal and renewable generation assets are locking in recurring inspection revenue streams across European and Asian markets.
- China's GB 50057 Enforcement:Fossil and nuclear facility operators face intensified design standard audits, expanding engineering service contracts for lightning protection system retrofits.
- Surge Protection Device Proliferation:Inverter-based solar and wind plants require granular transient voltage suppression at multiple DC and AC conversion nodes.
Market Restraints
- Copper and Aluminum Price Volatility:Down conductor and air termination material costs swing with commodity markets, compressing installation margins on fixed-price contracts.
- Captive Component Manufacturing Concentration:Surge protection device production clusters in German and Chinese facilities, creating supply vulnerability for non-integrated service providers.
- Ground Resistance Technical Limits:Rocky or high-resistivity soil conditions in arid regions prevent achievement of sub-10 ohm specifications without expensive deep drilling or chemical enhancement.
Strategic Opportunities
- US Renewable Generation Buildout:Texas, California, and Arizona utility-scale solar complexes lack mature lightning protection infrastructure, opening greenfield installation contracts.
- Smart Grid Convergence:Integration of IoT sensors with conventional air termination networks enables predictive maintenance and remote strike monitoring.
- India's CEA Grid Code Harmonization:Central Electricity Authority mandates for critical infrastructure protection are creating first-mover advantages for certified international contractors.
Industry Challenges
- IEC 62305 Master Inspector Certification Scarcity:Qualified personnel capable of signing off on complex substation and turbine protection designs command premium compensation and extend project timelines.
- Legacy Thermal Fleet Integration Complexity:Aging coal and gas plants require custom retrofit solutions that interface with deteriorating structural steel and obsolete grounding grids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Plant Lightning Protection Services Market |
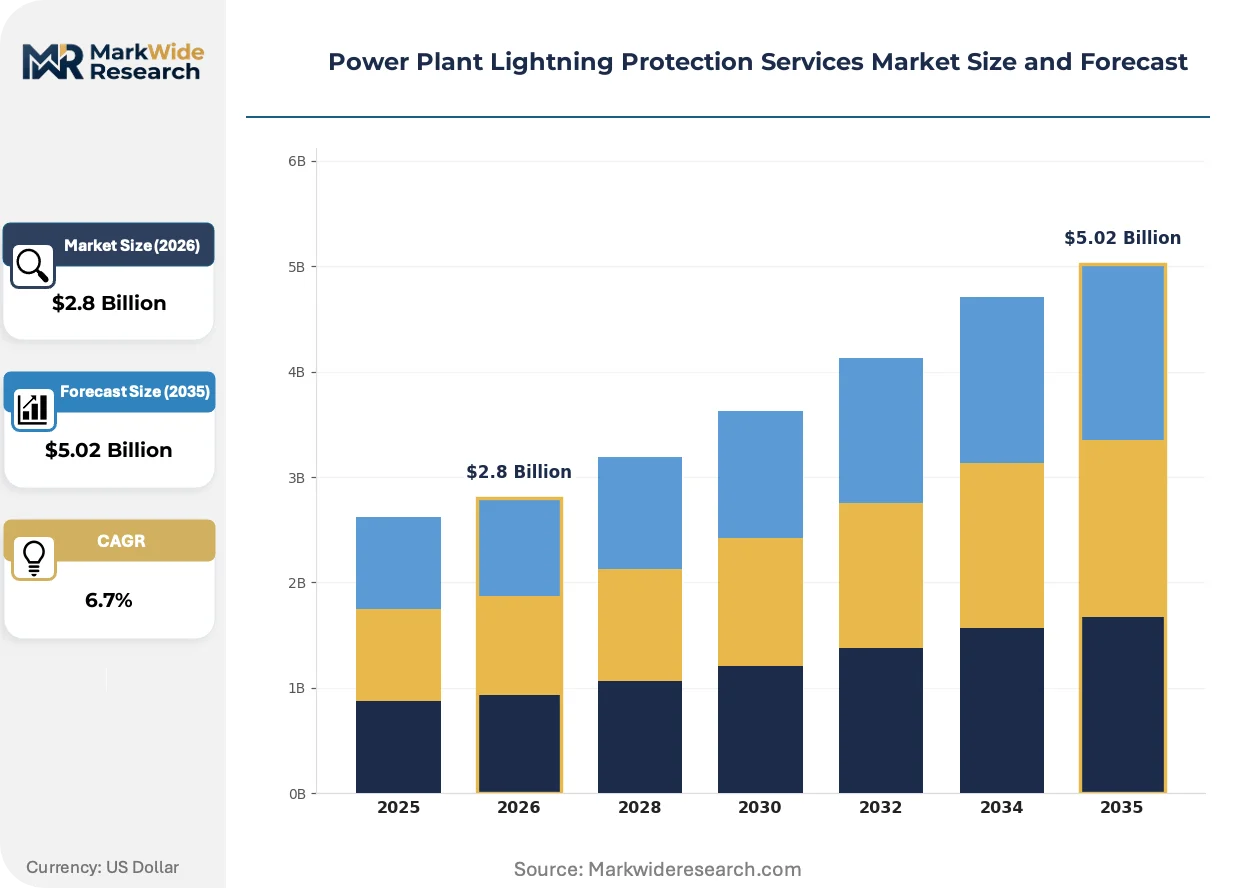
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consultation, Installation, Maintenance, Inspection Technology: Early Streamer Emission, Conventional Rod, Grounding System, Surge Protection Device End User: Utilities, Independent Power Producers, Government Facilities, Industrial Operators Application: Safety Audits, Risk Assessment, Emergency Response, Compliance Verification |
| Companies Covered | Ingesco Lightning Solutions, Scientific Lightning Solutions LLC, LightningMaster Corporation, VFC Group, Lightning Eliminators & Consultants Inc, Dehn SE, Plankton Engineering Pvt Ltd, Brooke Edgley Specialist Technical Services Ltd, Hokushin Telnex Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Plant Lightning Protection Services Market Strategic Shifts
Active monitoring technologies are displacing passive protection paradigms, embedding intelligence into previously static conductor networks while regulatory frameworks harden performance verification requirements.
Early Streamer Emission air terminals are fragmenting market share capture between conventional Franklin rod installations and advanced ionization-based systems. IPP procurement teams in Spain and Morocco are piloting hybrid configurations that combine both technologies across single-site portfolios. The resulting specification confusion is compressing contractor margins as design liability shifts toward performance guarantees rather than code compliance alone.
The EU F-Gas Regulation is forcing refrigerant-dependent surge protection cooling systems toward alternative thermal management architectures. Manufacturers serving continental European markets must redesign enclosure ventilation and heat dissipation pathways. German TSOs and major IPPs are accelerating qualification timelines for SF6-free switchgear protection, creating certification bottlenecks for legacy product lines.
Service unbundling is separating installation, inspection, and emergency response into discrete contract vehicles. US independent power producers now source strike damage assessment through mobile specialist teams rather than original installation contractors. This disintermediation is most pronounced in Texas ERCOT territory, where merchant solar operators prioritize 4-hour response SLAs over single-source accountability.
Power Plant Lightning Protection Services Market Segmentation
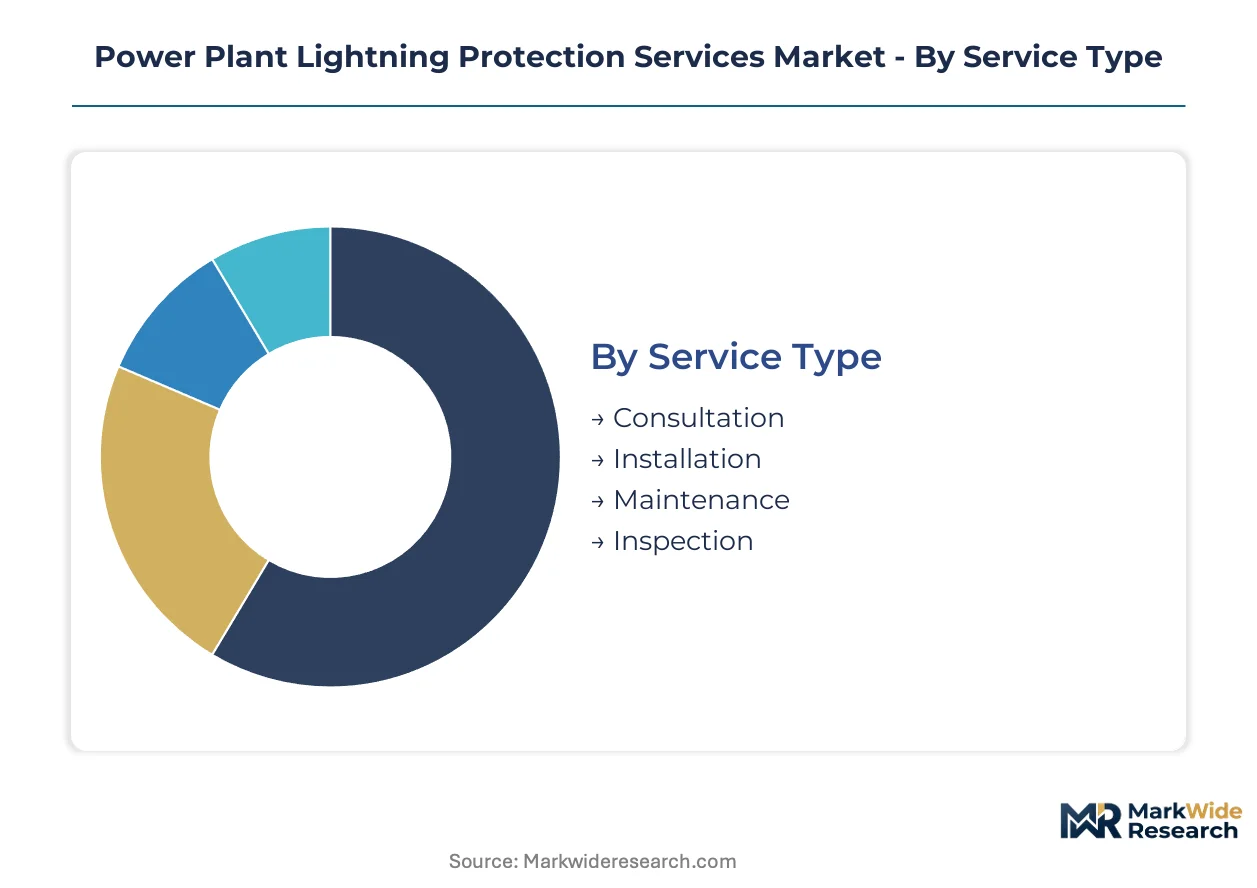
Lightning protection procurement channels bifurcate sharply between capital-intensive installation contracts and recurring inspection revenue streams. Technology selection determines margin profiles, with conventional rod systems commanding commodity pricing while active emission technologies extract premium engineering fees.
Service Type:
Channel economics favor installation and maintenance as anchor revenue pools, while consultation migrates toward specialist engineering firms and inspection concentrates among certified compliance auditors.
- Installation:Tower retrofit and substation grounding grid deployment require specialized rigging crews and impedance testing equipment. Demand concentrates in Texas ERCOT solar complexes and China's GB 50057-mandated nuclear facility upgrades, where capital cycles align with renewable buildout and regulatory enforcement waves.
- Maintenance:Recurring inspection contracts tied to IEC 62305 certification renewal generate stable margin pools through multi-year service agreements. Independent power producers in Spain and Morocco are unbundling these contracts from original installation providers, creating discrete procurement vehicles for mobile assessment teams.
- Consultation:Engineering design and risk modeling services flow through specialist firms with IEC Master Inspector certification.
- Inspection:Compliance verification audits for insurance and regulatory filing requirements concentrate among accredited third-party certifiers.
By volume, Installation leads. By growth pace, Maintenance is ahead.
Technology:
Cost tiers separate passive grounding infrastructure from active emission systems, with surge protection devices occupying a mid-tier price-performance position driven by inverter-density requirements.
- Surge Protection Device:Granular transient voltage suppression modules protect DC and AC conversion nodes in inverter-based solar and wind plants. Procurement accelerates fastest across utility-scale renewable portfolios in Arizona and California, where DC arc fault risks compound lightning-induced overvoltage scenarios.
- Early Streamer Emission:Ionization-based air terminals extend protection radius through controlled streamer advancement, commanding 40-60% premium over conventional rods. Spanish and Moroccan IPPs are piloting hybrid configurations that combine both technologies, compressing contractor margins through performance-guarantee contracting.
- Conventional Rod:Franklin rod networks dominate retrofit economics for aging thermal fleets with budget-constrained capital programs.
- Grounding System:Earth electrode arrays achieving sub-10 ohm resistance face technical limits in rocky or high-resistivity soils.
By deployment scale, Conventional Rod dominates. By margin expansion, Early Streamer Emission is climbing the fastest.
End User:
Customer-type concentration shifts procurement authority from centralized utility tenders toward distributed independent power producer decision-making, fragmenting vendor account management requirements.
- Independent Power Producers:Merchant solar and wind operators in Texas and California prioritize 4-hour emergency response SLAs over single-source accountability, disintermediating original installation contractors for strike damage assessment. Procurement fragmentation accelerates as distributed generation assets multiply across decentralized grid architectures.
- Utilities:Vertically integrated transmission and generation owners maintain centralized tender processes for fleet-wide standardization, favoring vendors with multi-state deployment capability.
- Government Facilities:Public power authorities and military installations impose stringent electromagnetic interference protocols coordinated with FAA near airports.
- Industrial Operators:Cogeneration and captive power plants integrate lightning protection with process safety management systems.
By contract value, Utilities lead. By procurement velocity, Independent Power Producers are gaining share fastest.
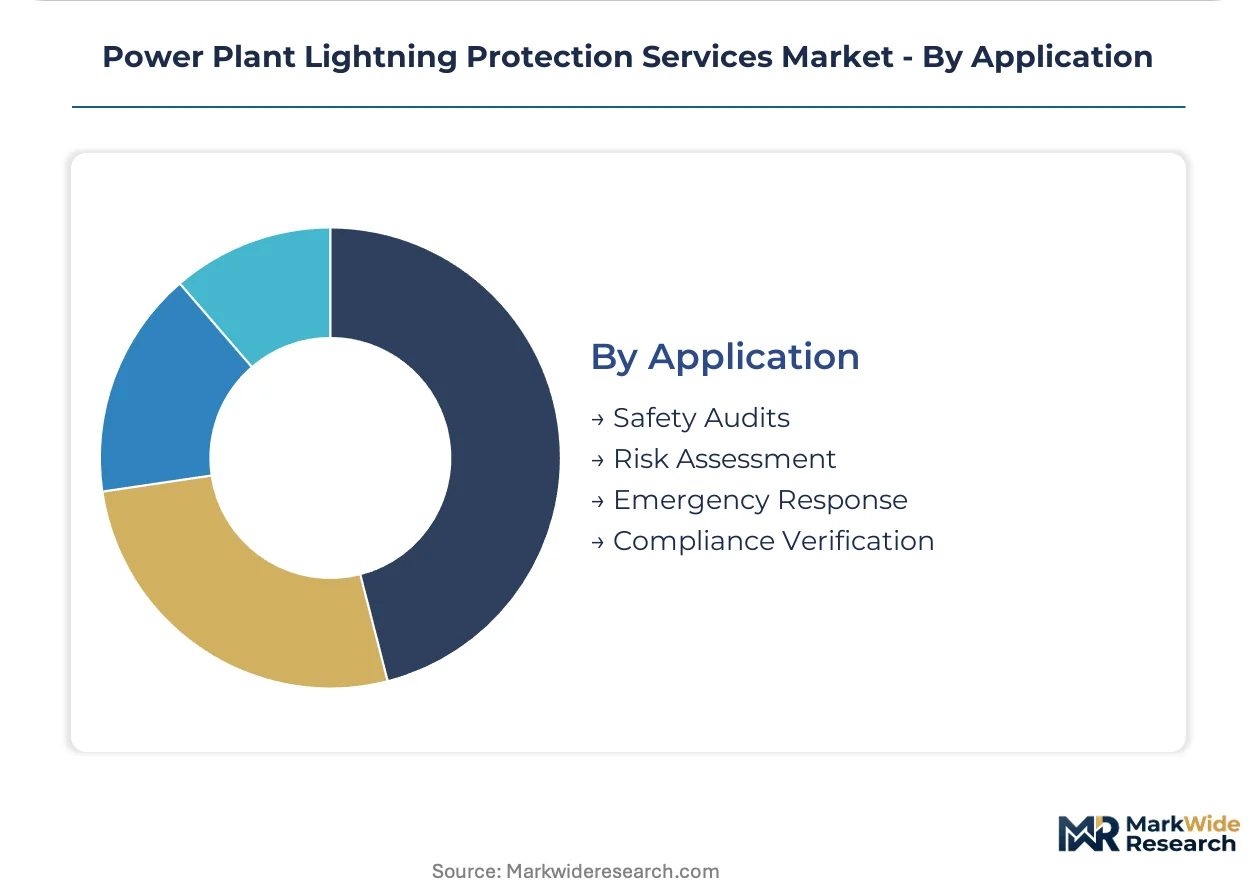
Application:
Maturity gradients separate established safety audit and compliance verification practices from emerging risk quantification and emergency response service lines.
- Risk Assessment:Computational modeling of strike probability and consequence severity informs insurance underwriting and capital planning for utility-scale solar complexes. German TSOs and major IPPs are accelerating qualification timelines for advanced characterization methodologies, creating certification bottlenecks for legacy analytical approaches.
- Emergency Response:Mobile specialist teams deploy post-strike damage assessment within contracted response windows, displacing original installation contractors in US independent power producer procurement. Service unbundling is most pronounced in Texas ERCOT territory, where merchant operators prioritize rapid restoration over vendor continuity.
- Safety Audits:Periodic facility inspections verify air termination integrity and grounding system continuity.
- Compliance Verification:Documentation and certification renewal for IEC 62305 and NFPA 780 mandates.
By service frequency, Safety Audits lead. By expansion trajectory, Emergency Response is steepest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Service provider networks cluster most densely in Germany, China, and the United States, where thermal fleet retrofits and renewable buildouts sustain installation capacity. Copper and aluminum processing infrastructure in these markets anchors material supply chains for conductor fabrication.
United States
Merchant solar operators in Texas and Arizona drive procurement velocity for rapid-response assessment contracts. FAA coordination protocols near airports impose electromagnetic interference standards on facilities in Dallas-Fort Worth and Phoenix corridors. California utility-scale solar complexes lack mature lightning protection infrastructure, opening greenfield installation contracts for specialized rigging crews.
China
GB 50057 enforcement intensifies design standard audits across fossil and nuclear facilities. State Grid Corporation procurement cycles prioritize domestic certification holders for substation grounding grid deployments. Yangtze River Delta manufacturing clusters supply surge protection device components to regional installation contractors.
Germany
EU F-Gas Regulation forces refrigerant-dependent cooling systems toward alternative thermal management architectures. Transmission system operators accelerate qualification timelines for SF6-free switchgear protection. Bavarian and North Rhine-Westphalian industrial zones concentrate captive component manufacturing for surge protection devices.
Spain
Iberian independent power producers pilot hybrid configurations combining conventional rods with ionization-based systems. IEC 62305 certification renewal cycles lock in recurring inspection revenue across Andalusian solar complexes. Madrid-based engineering firms anchor utility-scale contracts extending into Moroccan renewable developments.
India
Central Electricity Authority grid code harmonization creates first-mover advantages for certified international contractors. Maharashtra and Gujarat thermal facilities face intensified compliance verification for aging grounding infrastructure. Telangana and Karnataka solar parks generate demand for granular surge protection at DC conversion nodes.
Power Plant Lightning Protection Services Market Competitive Environment
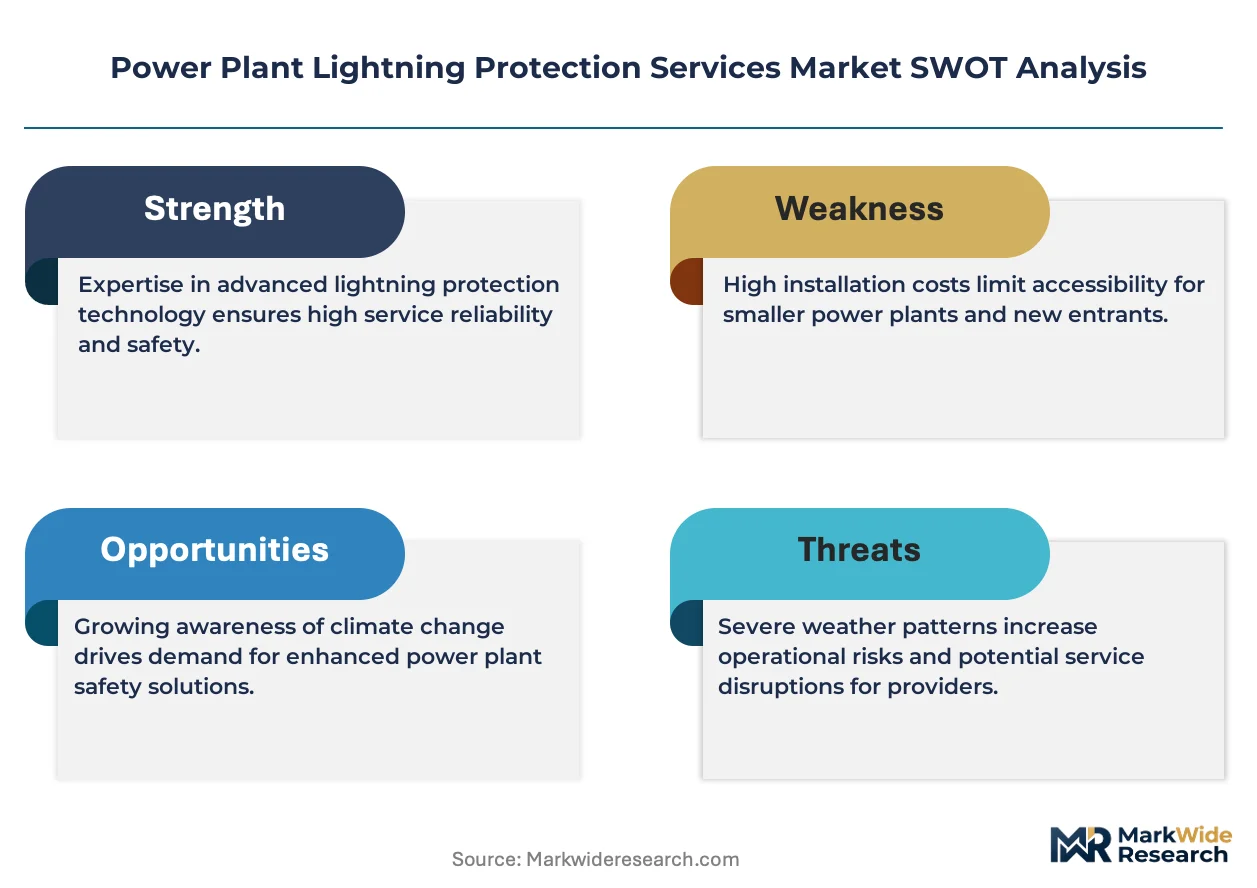
Concentration sits with European surge protection device manufacturers and North American emergency response specialists. The vendor base spans three tiers: integrated component producers controlling captive supply chains, regional installation contractors with certified inspector networks, and mobile assessment teams competing on response velocity. Strategic moves center on geographic expansion into US renewable corridors and technology licensing for active emission systems.
Among European-anchored providers, Dehn SE exemplifies the integrated manufacturing archetype through captive component production. Scientific Lightning Solutions LLC and LightningMaster Corporation occupy positions within the North American specialist tier, with the former representing sustained R&D intensity in strike characterization and the latter anchoring emergency response velocity through mobile deployment capabilities. Ingesco Lightning Solutions sits within the regional installation contractor category, leveraging its Iberian footprint to secure utility-scale contracts.
| Leading Market Players |
|---|
| Ingesco Lightning Solutions |
| Scientific Lightning Solutions LLC |
| LightningMaster Corporation |
| VFC Group |
| Lightning Eliminators & Consultants Inc |
| Dehn SE |
| Plankton Engineering Pvt Ltd |
| Brooke Edgley Specialist Technical Services Ltd |
| Hokushin Telnex Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Captive surge protection device manufacturing in Bavarian industrial zones anchors cost structures across European installation contracts, compressing price floors for non-integrated service providers while amplifying margin leverage for component producers with in-house foundry capacity.
Pricing Analysis
Volume-discount tiering structures separate utility-scale fleet contracts from independent power producer spot procurement, with three-tier pricing stratification across premium IEC Master Inspector-certified designs, standard code-compliant installations, and economy retrofit packages for aging thermal assets. Price differentiation hinges on certification grade and geographic delivery cost, with remote site mobilization premiums adding substantial uplift. Pricing pressure stems from copper and aluminum commodity volatility squeezing fixed-price installation margins. Merchant solar operators in Texas ERCOT territory exhibit highest price sensitivity, while nuclear facility operators under GB 50057 mandates demonstrate lowest sensitivity due to compliance-driven procurement urgency.
Supply Chain Analysis
Germany, China, and the United States anchor surge protection device fabrication and conductor material processing, with Yangtze River Delta clusters feeding component supply to Asian installation contractors and North Rhine-Westphalian facilities serving European demand. Raw material dependencies center on copper rod stock, aluminum alloy extrusions, and zinc oxide varistors for transient suppression modules. Single-source vulnerability concentrates in German captive component manufacturing, where EU F-Gas Regulation compliance bottlenecks threaten qualification timelines. Distribution runs through certified installation contractors with inspector networks, bypassing traditional distributor channels for direct utility and IPP engagement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive advantage through IEC 62305 Master Inspector certification scarcity and multi-year inspection contract lock-in.
For Market Incumbents: Shield installed base relationships by embedding IoT-enabled predictive maintenance into existing air termination networks, creating switching costs that resist unbundling pressures from mobile assessment teams. Deepen upstream control over surge protection device supply through captive foundry investments or exclusive component partnerships, neutralizing margin compression from commodity-exposed installation pricing. Prioritize certification pipeline development to address inspector scarcity extending project timelines. For New Entrants and Emerging Players: Differentiate on emergency response velocity by deploying mobile strike assessment teams with sub-4-hour SLAs in Texas and Arizona utility-scale solar corridors, where merchant operators prioritize speed over vendor continuity. Target India's CEA grid code harmonization window as the most penetrable geography, leveraging first-mover certification advantages before domestic capacity matures. Pursue technology licensing partnerships for Early Streamer Emission systems to bypass R&D capital intensity. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated component manufacturers with captive surge protection device production and established inspector certification pipelines. Long-term viability rests on regulatory compliance entrenchment rather than cyclical installation demand. Acquisition target archetype: regional installation contractors with certified Master Inspector density and renewable corridor geographic positioning. Watch IEC 62305 certification renewal volume as inflection indicator for recurring revenue durability.| Strategic Initiative | Industry Significance |
|---|---|
| Master Inspector Certification Pipeline Investment | Addresses scarce qualified personnel extending project timelines across European and Asian markets. |
| IoT Sensor Integration with Air Termination Networks | Enables predictive maintenance revenue streams and raises switching costs for utility clients. |
| SF6-Free Switchgear Protection Qualification | Aligns with EU F-Gas Regulation mandates and unlocks German TSO procurement channels. |
| Mobile Emergency Response Team Deployment | Captures unbundled strike assessment contracts from Texas ERCOT merchant solar operators. |
| Early Streamer Emission Technology Licensing | Accelerates market entry without R&D capital burden in Spanish and Moroccan IPP pilots. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with IPP procurement directors, utility fleet engineering managers, IEC Master Inspector certification holders, surge protection device manufacturing plant managers, and EPC contractor project leads. Secondary validation drew from IEC 62305 technical committee documentation, GB 50057 enforcement bulletins, FERC interconnection queue data, EIA generation capacity statistics, and customs records for copper and aluminum conductor trade flows. Bottom-up installation contract aggregation triangulated against top-down market sizing from regulatory mandate volume analysis.
Across the analysis window, the forecasting framework modeled value capture by service type, technology category, end-user archetype, and application function, with additional segmentation by regional regulatory cluster and generation asset vintage. CAGRs were derived from regression analysis against renewable buildout pipelines and thermal fleet age profiles. Industry-specific inputs included strike incident frequency databases, grounding system retrofit backlogs, and certification renewal cycle data from notified bodies.
Material uncertainties — commodity price volatility, regulatory enforcement timing shifts, and inspector certification pipeline bottlenecks — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding grid decentralization velocity and renewable penetration trajectories. Recalibration cycles align with material shifts in IEC standard revision schedules and major grid code harmonization events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Russian Federation Power EPC Market
Power Equipment
North America Exhaust Heat Recovery System Market
Power Equipment
SCR Power Controller Market
Power Equipment
United Kingdom Power EPC Market
Power Equipment
G-3 PLC Solutions Market
Power Equipment
Europe SCR Power Controller Market
Power Equipment
Asia-Pacific Gas Turbine Service Market
Power Equipment
North America Power Plant Boiler Market
Power Equipment
Global Hydraulic Power Unit Market
Power Equipment
Natural Gas Turbine Market
Power Equipment
Industrial Power Transmission Drive Belts Market
Power Equipment
US Power EPC Market
Power Equipment
Wind Turbine Equipment Market
Power Equipment
Gas Fixed Power Capacitors Sales Market
Power Equipment
Gas Turbine Compressor Market
Power Equipment
Heavy Duty Gas Turbine Market