
 Induction Heating System Market | 2026-2036
Induction Heating System Market Size, Share, and Industry Trends Forecast 2026-2036
Induction Heating System Market Insights
Modular generator-and-coil bundling is restructuring procurement patterns across metal processing facilities. EFD Induction leverages its Nordic engineering heritage to dominate high-frequency hardening configurations for automotive camshafts. Inductotherm Group anchors global demand through its captive foundry equipment installed base across steel melting operations. Ajax Tocco Magnethermic specializes in custom coil design services that differentiate its offering from standardized generator competitors.
Induction heating systems employ alternating electromagnetic fields—typically operating between 1 kHz and 400 kHz—to generate eddy currents within conductive workpieces, achieving precise, contactless thermal treatment without flame or furnace contamination. The primary industrial purpose centers on localized, repeatable heat zones for hardening, brazing, or melting applications where temperature uniformity directly determines metallurgical outcomes. Induction furnaces currently occupy the largest product category value pool due to sustained steel industry demand for energy-efficient melting capacity. Multi-frequency systems represent the fastest-growing technology segment as manufacturers seek single-platform flexibility across diverse part geometries. Surface treatment applications command premium pricing relative to bulk melting owing to tighter tolerances and aerospace qualification requirements.
FDA oversight of food-contact equipment and EPA emissions standards for industrial thermal processes shape product design requirements in the United States. The EU F-Gas Regulation and REACH chemical restrictions constrain refrigerant and insulation material choices for European-built systems. China's GB energy-efficiency standards and dual carbon goals are forcing domestic furnace upgrades while creating export opportunities for compliant foreign suppliers. Stakeholders must monitor evolving carbon border adjustment mechanisms and their interaction with regional equipment certification regimes.
Market Dynamics
MIIT energy-efficiency mandates for industrial furnaces are forcing replacement cycles across Chinese metal processing facilities, compressing equipment lifespans from fifteen to eight years and redirecting capital toward high-frequency generator platforms.
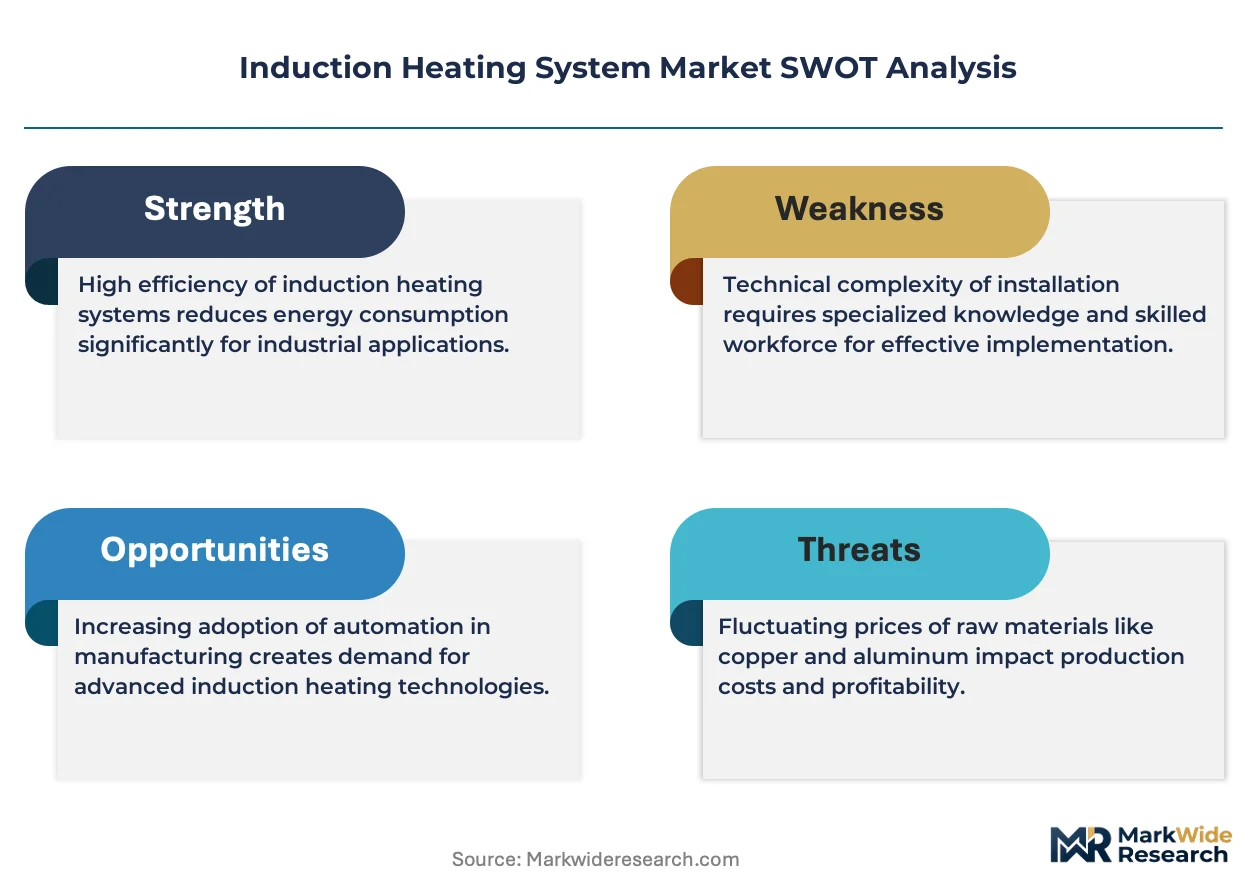
Growth Catalysts
- Automotive drivetrain electrification:OEMs in Germany and Japan are expanding induction hardening lines for electric motor shafts and battery housing components, creating sustained equipment demand.
- EU F-Gas Regulation:Refrigerant phase-down schedules are accelerating furnace retrofits across European foundries, favoring induction systems over gas-fired alternatives.
- Multi-frequency platform adoption:Manufacturers are consolidating hardening and brazing operations onto single-generator systems, reducing floor space requirements and coil inventory costs.
Market Restraints
- Copper and ferrite input volatility:Generator coil assemblies depend on copper winding and ferrite core materials subject to commodity price swings that compress OEM margins.
- High-frequency power electronics concentration:IGBT and MOSFET supply chains concentrate in East Asian semiconductor fabs, exposing European and North American system builders to allocation risk.
- Technical ceiling on thick-section heating:Magnetic flux penetration depth limits restrict induction melting efficiency for steel billets above 150mm diameter, preserving arc furnace dominance in heavy forging.
Strategic Opportunities
- India industrial corridor expansion:PLI scheme incentives for specialty steel and automotive component manufacturing are creating first-mover openings for furnace suppliers in Gujarat and Tamil Nadu.
- Food pasteurization equipment:FDA food-contact certification pathways for induction-based aseptic processing open white space beyond traditional metal treatment applications.
- Digital twin integration:Convergence of electromagnetic simulation software with IoT sensor feeds enables predictive coil maintenance and remote parameter optimization.
Industry Challenges
- Electromagnetic design talent scarcity:Coil geometry optimization requires specialized physics expertise that outpaces vocational training pipeline output in mature manufacturing economies.
- Legacy furnace integration complexity:Retrofitting induction generators into existing material handling lines demands custom mechanical interfaces that extend project timelines.
- REACH compliance documentation:Ceramic insulation and potting compound formulations require extensive chemical substance registration, slowing European product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Induction Heating System Market |
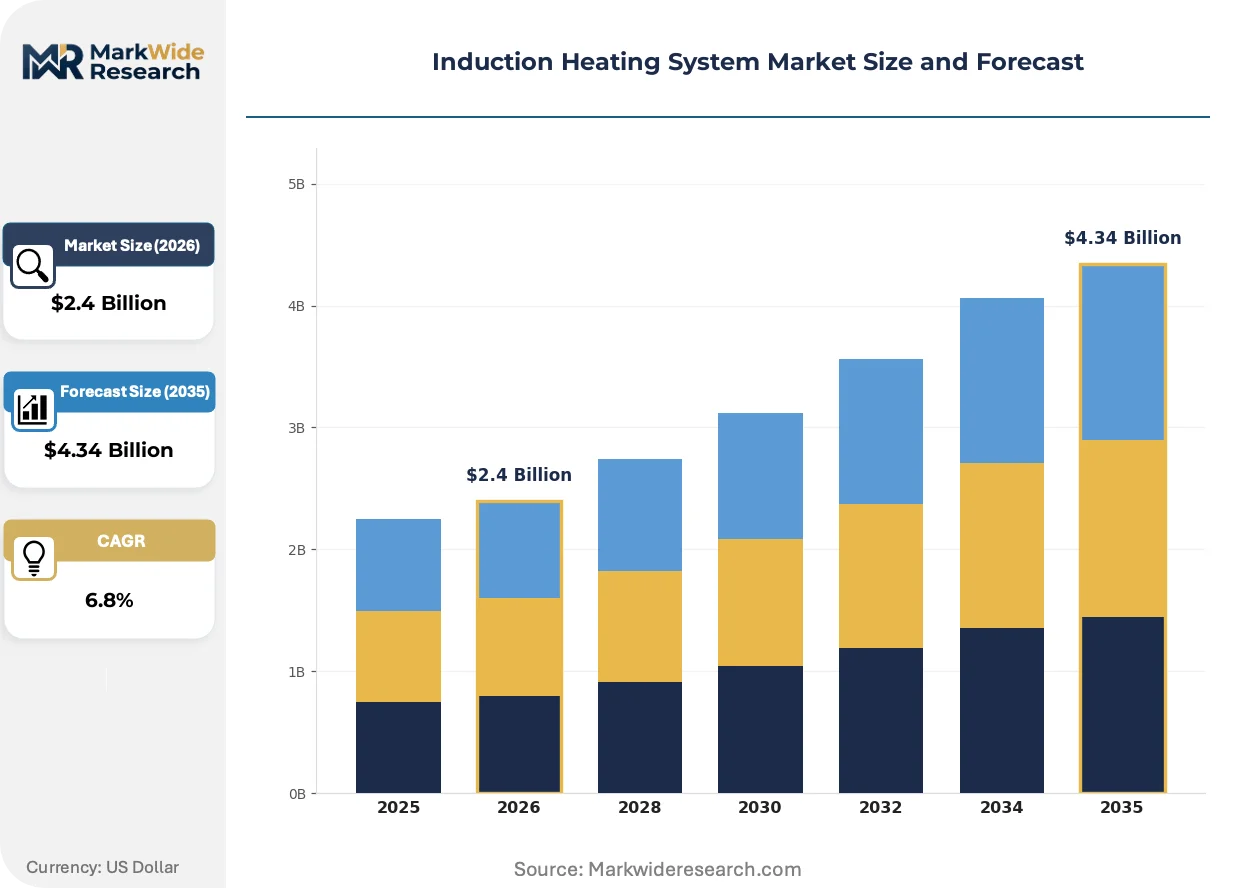
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Induction Cooktops, Induction Furnaces, Induction Hardening Equipment, Induction Heating Generators End User: Manufacturing, Aerospace, Automotive, Food Processing Technology: Electromagnetic Induction, Direct Induction, Multi-Frequency Systems, High-Frequency Heating Application: Metal Processing, Soldering, Melting, Surface Treatment |
| Companies Covered | Inductotherm Group, EFD Induction, Ajax Tocco Magnethermic, Inductoheat, inTEST Corporation, ENRX, Park-Ohio Holdings Corporation, Fuji Electric, Magneforce Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Induction Heating System Market Trends and Innovations
Alternating electromagnetic field systems are fragmenting into componentized architectures that separate power electronics from application-specific coil assemblies, enabling faster reconfiguration and reducing captive spare parts inventory.
Resonant converter topologies are modularizing across automotive supplier shops, allowing a single 200 kW generator chassis to switch between 10 kHz billet heating and 400 kHz gear tooth hardening through software-defined frequency bands. Tier-1 drivetrain manufacturers in Nagoya and Stuttgart are adopting these platforms to consolidate supplier relationships and compress coil changeover times from four hours to forty minutes. The structural consequence is collapsing the traditional separation between melting and surface treatment equipment vendors.
China's GB energy-efficiency standards for industrial thermal equipment are tightening allowable furnace wall heat loss coefficients, forcing domestic foundries to scrap gas-fired crucible systems ahead of depreciation schedules. Compliance deadlines in 2027 and 2030 are creating two waves of replacement demand concentrated in Shanghai and Hebei province. Foreign suppliers with MIIT certification are capturing premium positioning in this upgrade cycle.
Buyer consolidation among automotive OEMs is compressing equipment specification cycles and unbundling after-sales service contracts from initial hardware procurement. Tier-1 suppliers now negotiate separate multiyear maintenance agreements with coil refurbishment specialists rather than captive generator service divisions. This pattern is most visible in Busan and Detroit, where powertrain component manufacturers are centralizing induction hardening operations into shared supplier parks.
Induction Heating System Market Segmentation
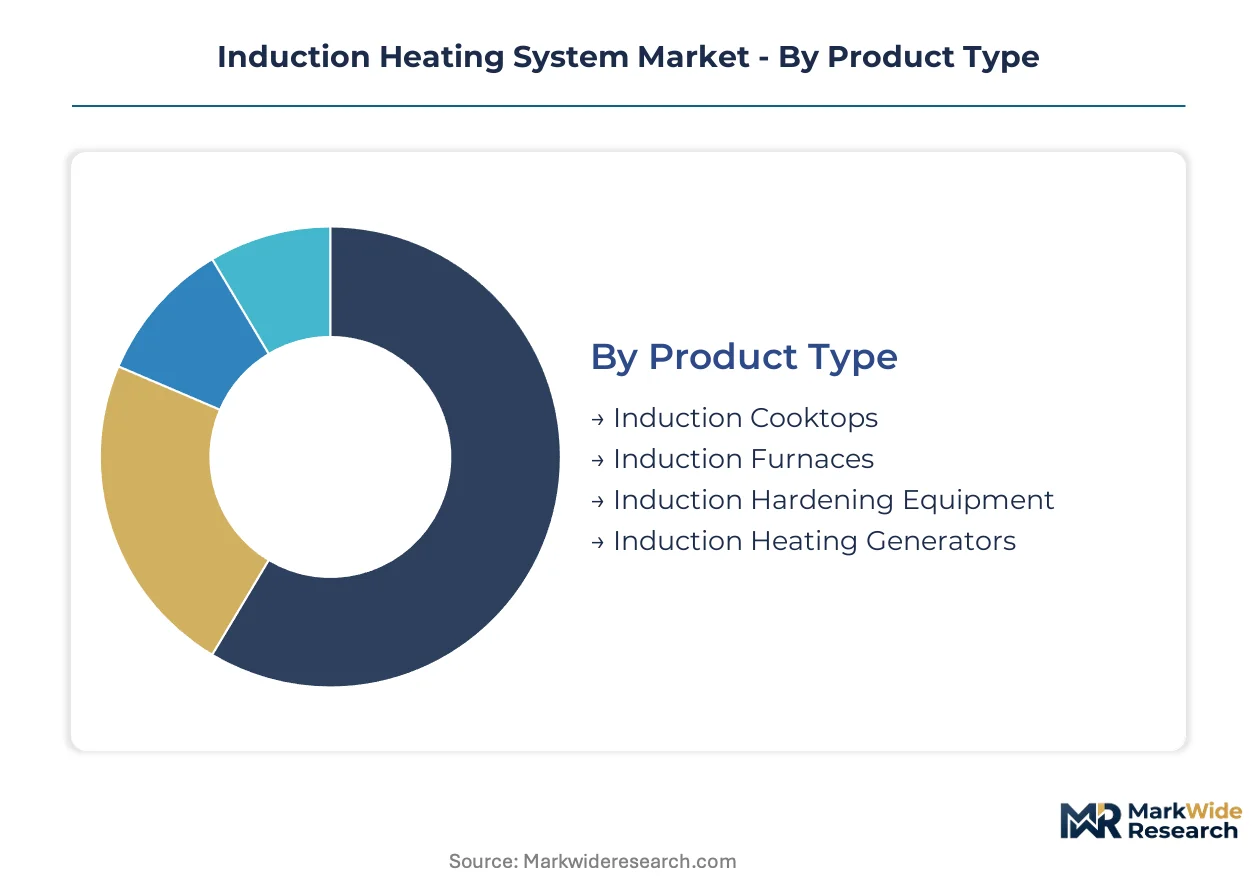
Induction heating system procurement varies sharply by thermal application and regulatory exposure. Equipment buyers face distinct certification burdens across food-contact, aerospace, and automotive end-uses that reshape vendor selection criteria.
Product Type:
FDA food-contact approvals constrain cooktop coil designs, while EPA emissions standards govern furnace refractory materials. MIIT energy-efficiency certifications create tiered market access in China.
- Induction Cooktops:Residential and commercial kitchen installations deploy flat spiral coil configurations beneath ceramic-glass surfaces. Demand clusters in European hospitality retrofit programs driven by EU F-Gas Regulation phase-downs of gas cooking infrastructure.
- Induction Furnaces:Crucible-based melting systems for ferrous and non-ferrous alloys operate at 1-3 kHz frequencies with capacities from 100 kg to 40 tonnes. Chinese steel foundries in Hebei and Jiangsu provinces are replacing gas-fired capacity ahead of dual carbon compliance deadlines.
- Induction Hardening Equipment:Scanning and single-shot coil arrangements for crankshafts, gears, and camshafts require precision frequency control.
- Induction Heating Generators:Power electronics chassis delivering 10-500 kW across variable frequency bands form the modular core of system architectures.
Induction furnaces sit at the top of the volume ranking, with induction hardening equipment climbing the fastest.
End User:
Customer procurement patterns split between capital-intensive metal processors and specification-driven OEMs. Aerospace qualification timelines extend 18-24 months versus 6-9 months for general manufacturing.
- Manufacturing:General metal fabrication shops deploy portable brazing and shrink-fit systems for maintenance and repair operations. Indian industrial corridor expansion under PLI scheme incentives is creating fresh equipment demand in Gujarat and Tamil Nadu.
- Aerospace:Nadcap-accredited heat treatment for turbine blades and landing gear demands multi-frequency platforms with documented thermal uniformity. Surface treatment applications command premium pricing relative to bulk melting owing to tighter tolerances and aerospace qualification requirements.
- Automotive:Tier-1 drivetrain suppliers in Germany and Japan are expanding hardening lines for electric motor shafts and battery housing components.
- Food Processing:Aseptic heating for liquid foods and pasteurization applications requires FDA-validated coil materials and CIP-compatible designs.
Manufacturing captures the largest installed base, with aerospace posting the steepest expansion trajectory.
Technology:
Power electronics architecture determines frequency agility and energy conversion efficiency. Resonant converter topologies are fragmenting legacy distinctions between melting and surface treatment platforms.
- Electromagnetic Induction:Fundamental operating principle using alternating magnetic fields to induce eddy currents in conductive workpieces. Foundational across all product categories with efficiency ratings governed by IEC standards.
- Direct Induction:Workpiece serves as the sole heating element without intermediate susceptor materials, maximizing energy transfer efficiency for ferrous metals.
- Multi-Frequency Systems:Software-defined frequency switching enables single-generator deployment across 10 kHz billet heating and 400 kHz gear tooth hardening. Tier-1 suppliers in Nagoya and Stuttgart are consolidating hardening and brazing operations onto these platforms.
- High-Frequency Heating:100-400 kHz operation for shallow case hardening and thin-section brazing where magnetic flux penetration must remain superficial.
Multi-frequency systems are gaining share fastest, with electromagnetic induction retaining foundational dominance.
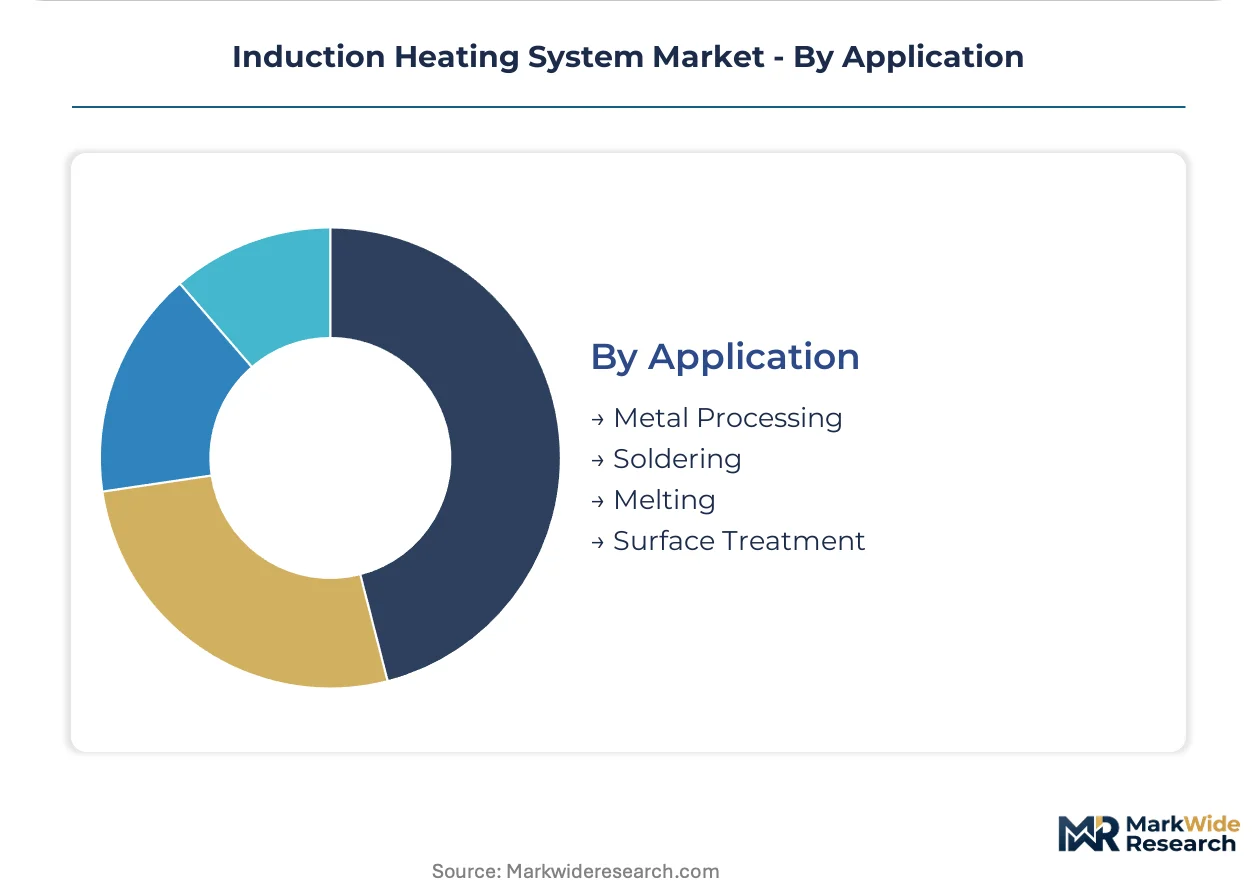
Application:
Process requirements dictate coil geometry, power density, and thermal cycle programming. Surface treatment applications impose the most stringent uniformity specifications.
- Metal Processing:Broad category encompassing forging preheat, annealing, and stress relieving across steel, aluminum, and copper alloys. Chinese MIIT mandates are compressing equipment replacement cycles from fifteen to eight years.
- Soldering:Precision joining of electronic components and HVAC tubing demands localized heating without flux contamination. High-frequency generators with micro-coil configurations serve semiconductor packaging facilities.
- Melting:Bulk liquid metal production for casting and continuous pouring operations. Induction furnaces currently occupy the largest product category value pool due to sustained steel industry demand for energy-efficient melting capacity.
- Surface Treatment:Case hardening, tempering, and coating preparation where temperature uniformity directly determines metallurgical outcomes. REACH compliance documentation for ceramic insulation and potting compounds slows European product introductions.
Melting commands the greatest equipment value, with surface treatment expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Induction heating technology originated in European metallurgical laboratories during the early twentieth century, with German and Swedish engineering firms pioneering the first industrial-scale generators for steel hardening. This Nordic-German technical lineage continues to shape equipment standards and export patterns across contemporary manufacturing corridors.
China
Domestic steel foundries in Hebei and Jiangsu provinces are retiring gas-fired crucible systems ahead of MIIT-mandated efficiency deadlines. GB energy-efficiency standards for industrial thermal equipment are compressing allowable furnace wall heat loss coefficients and forcing replacement cycles from fifteen to eight years. Shanghai and surrounding Yangtze River Delta manufacturing clusters are absorbing the bulk of high-frequency generator imports as local fabricators struggle with power electronics design.
Germany
Automotive OEMs in Stuttgart and Munich are expanding induction hardening lines for electric drivetrain components including motor shafts and battery housings. EU F-Gas Regulation refrigerant phase-down schedules are accelerating furnace retrofits across foundries in North Rhine-Westphalia and Bavaria. The Baden-Württemberg precision engineering belt anchors European demand for multi-frequency platforms serving both billet heating and gear tooth hardening.
United States
EPA emissions standards for industrial thermal processes are constraining refractory material choices in domestic furnace construction. FDA oversight of food-contact equipment is creating certification barriers for induction-based aseptic processing systems targeting dairy and beverage applications. Detroit-area powertrain component manufacturers are centralizing hardening operations into shared supplier parks with unbundled service contracts.
Japan
Tier-1 drivetrain suppliers in Nagoya and Toyota City are consolidating hardening and brazing operations onto single-generator multi-frequency platforms. METI industrial efficiency guidelines are pressuring small and medium foundries to upgrade from legacy resistance heating. The Chubu region's automotive supplier density is driving coil changeover time compression from four hours to forty minutes through resonant converter adoption.
India
PLI scheme incentives for specialty steel and automotive component manufacturing are creating first-mover openings for furnace suppliers in Gujarat and Tamil Nadu. Central Electricity Authority efficiency mandates are beginning to reach industrial thermal equipment categories beyond power generation. The Delhi-Mumbai Industrial Corridor is attracting induction equipment distributors seeking to serve emerging forging and heat treatment clusters.
Induction Heating System Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coil design sophistication and generator frequency agility. The market exhibits tiered concentration with a handful of integrated power electronics and coil specialists commanding specification authority at automotive OEMs, while regional fabricators compete on price for standard melting applications. Three archetypes dominate: Nordic engineering heritage firms with deep automotive hardening expertise, captive foundry equipment builders leveraging installed base lock-in, and custom coil design boutiques differentiating through application-specific geometry optimization. Competitive dynamics center on multi-frequency platform consolidation and the unbundling of after-sales service contracts from initial hardware procurement.
Within the integrated equipment tier, Inductotherm Group and EFD Induction exemplify divergent geographic and technical positioning. Inductotherm Group represents the scale-driven foundry equipment archetype with extensive steel melting installed base. EFD Induction occupies the precision hardening specialist position rooted in Nordic engineering heritage. Ajax Tocco Magnethermic sits within the custom coil design segment, differentiating through application-specific geometry services rather than standardized generator offerings. These three anchors illustrate how procurement patterns are fragmenting between commodity melting capacity and specification-driven surface treatment systems.
| Leading Market Players |
|---|
| Inductotherm Group |
| EFD Induction |
| Ajax Tocco Magnethermic |
| Inductoheat |
| inTEST Corporation |
| ENRX |
| Park-Ohio Holdings Corporation |
| Fuji Electric |
| Magneforce Inc. |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM procurement consolidation across Germany and Japan is compressing equipment specification cycles and forcing generator suppliers to absorb coil customization costs that previously carried separate line-item pricing. This demand-side pressure is reshaping how power electronics chassis and application-specific coil assemblies are bundled, with after-sales service contracts unbundling from initial hardware procurement and creating distinct pricing tiers based on certification grade and geographic service coverage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with premium tiers commanding substantial markups for MIIT-certified systems destined for Chinese steel foundries and Nadcap-accredited aerospace configurations. Price differentiation hinges on frequency agility range and coil geometry optimization depth, with multi-frequency platforms sustaining firmer pricing than single-frequency melting alternatives. Cost compression in economy-tier induction furnaces is intensifying because Chinese domestic fabricators are flooding standard melting capacity with lower-cost IGBT assemblies. Tier-1 automotive suppliers in Stuttgart and Nagoya exhibit lowest price sensitivity due to qualification timelines and line-integration complexity, while general metal fabrication shops in India remain most price-sensitive.
Supply Chain Analysis
Regional distribution centers in Shanghai, Rotterdam, and Chicago anchor hub-and-spoke patterns that position coil refurbishment specialists and spare power electronics modules within forty-eight-hour reach of major automotive supplier parks. Manufacturing concentrates in Germany, China, and Japan, with generator chassis assembly anchored in Baden-Württemberg and high-frequency coil winding concentrated in Nagoya and Shanghai. Copper winding and ferrite core materials draw from Chilean mining operations and East Asian ceramic processing facilities. Single-source vulnerability in IGBT and MOSFET semiconductor fabrication exposes European and North American system builders to allocation risk from Taiwan and South Korean foundries. Distribution runs through direct OEM relationships for premium-tier equipment and regional distributor networks for standard melting applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in multi-frequency platform consolidation and digital twin-enabled predictive maintenance services, with copper input volatility and power electronics scarcity creating pricing power for vertically integrated coil designers.
For Market Incumbents: Anticipate coil geometry talent scarcity by capturing specialized electromagnetic design firms before qualification timelines extend further, and harden supply chains through backward integration into ferrite core processing or captive copper winding operations to offset commodity volatility. MIIT certification requirements in China represent a rising barrier that favors incumbents with established compliance documentation over emerging regional competitors. For New Entrants and Emerging Players: EU F-Gas Regulation refrigerant phase-down schedules in Germany and France open a window for induction furnace retrofits that displace gas-fired alternatives in foundries lacking in-house power electronics expertise. Food pasteurization equipment requiring FDA food-contact certification represents the most penetrable white-space segment, with aseptic processing applications in dairy and beverage operations underserved by traditional metal treatment vendors. A go-to-market angle anchored on CIP-compatible coil designs and documented thermal uniformity can bypass incumbent specification lock-in at dairy processors. For Investors and Strategic Acquirers: Asymmetric upside sits with custom coil design boutiques possessing documented aerospace qualification histories and proprietary electromagnetic simulation capabilities that shorten customer development cycles. Long-term viability over a multi-year horizon favors acquisition targets with installed base density in automotive supplier parks where unbundled service contracts generate recurring revenue streams. The signal to watch is tier-1 drivetrain manufacturer consolidation of hardening and brazing operations onto single-generator platforms, which accelerates replacement demand for flexible frequency architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Frequency Platform Development | Consolidates hardening and brazing operations for Tier-1 suppliers in Nagoya and Stuttgart. |
| Digital Twin Integration | Enables predictive coil maintenance through convergence of electromagnetic simulation with IoT sensor feeds. |
| MIIT Certification Investment | Unlocks premium positioning in Chinese steel foundry replacement cycles ahead of dual carbon deadlines. |
| Custom Coil Design Acquisition | Captures scarce electromagnetic physics expertise that outpaces vocational training pipeline output. |
| Food-Contact Equipment Certification | Opens white space in dairy and beverage aseptic processing beyond traditional metal treatment applications. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at steel foundries, procurement leads at automotive Tier-1 suppliers, aftermarket service heads at induction equipment distributors, and technical R&D directors at power electronics manufacturers with secondary validation against customs trade data, SEC filings from listed industrial equipment vendors, MIIT energy-efficiency certification registries, and IEC efficiency standard documentation. Bottom-up equipment shipment tallies and top-down steel industry capacity investment flows were triangulated to anchor market sizing.
Segment-weighting across product type, end user, technology, and application dimensions shaped the analytical framework over the projection horizon. Induction furnaces versus hardening equipment versus cooktop installations were modeled separately, with frequency band capability and power rating tiers as cross-cutting variables. CAGRs were derived from equipment replacement cycle compression observed in Chinese regulatory filings and automotive supplier capital expenditure disclosures. Forecast inputs included MIIT-mandated efficiency deadline schedules and EU F-Gas Regulation phase-down timelines.
Revisions become necessary when semiconductor allocation constraints intensify, copper price volatility exceeds historical bands, or carbon border adjustment mechanisms alter equipment certification requirements in European markets. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Europe SCR Power Controller Market
Power Equipment
G-3 PLC Solutions Market
Power Equipment
Wind Turbine Gearbox Repair and Refurbishment Market
Power Equipment
China Power EPC Market
Power Equipment
Chad Power EPC Market
Power Equipment
Brazil Power EPC Market
Power Equipment
Heavy Duty Gas Turbine Market
Power Equipment
North America Power Plant Boiler Market
Power Equipment
Kazakhstan Power EPC Market
Power Equipment
Uzbekistan Power EPC Market
Power Equipment
Turbine Governor Market
Power Equipment
Europe Power Rental Market
Power Equipment
Power Equipment Testing Market
Power Equipment
North America SCR Power Controller Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Power Recovery Winches Market