
 Europe Power Rental Market | 2026-2036
Europe Power Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Power Rental Market Intelligence
Equipment leasing channels across Europe are fragmenting as regional rental houses and manufacturer-direct programs compete for fleet loyalty. Aggreko sustains broad geographic coverage through decentralized depot networks. Caterpillar Inc. leverages its engine manufacturing depth to control core component supply. Cummins Inc. differentiates through integrated power system design spanning diesel, gas, and hybrid architectures.
Europe power rental encompasses short-to-medium term provision of mobile generation assets, typically diesel or gas reciprocating engines rated from 20 kVA to 2,000 kVA, deployed where grid connection is unavailable, insufficient, or unreliable. These systems serve construction sites, industrial shutdowns, events, and emergency backup through rapid deployment and scalable modular configurations. Diesel generators still anchor fleet value given energy density and deployment speed, though hybrid systems and solar solutions are gaining fastest as emissions compliance tightens and fuel volatility reshapes total cost of ownership calculations. Prime power applications for remote industrial operations command premium rates, while standby contracts for utilities and commercial facilities provide recurring revenue stability.
EMA, ECHA, and the EU Green Deal shape product standards and market access through emissions thresholds, chemical registration requirements, and decarbonization timelines that filter non-compliant equipment from European fleets. CE marking and the F-Gas Regulation further constrain refrigerant and component choices in temperature-controlled auxiliary systems. Stakeholders must weigh stranded asset risk against the capital intensity of hybrid and gas generator transitions as carbon border adjustments approach implementation.
Market Dynamics
Grid reliability mandates across Northern Europe are forcing data center operators into long-duration standby power contracts, compressing procurement cycles and elevating hybrid generator specifications as the default technical threshold for new fleet deployment.
Growth Catalysts
- EU Green Deal decarbonization timelines:Member states are accelerating diesel-to-gas and hybrid fleet turnover ahead of 2030 emissions benchmarks, expanding addressable rental demand for lower-carbon mobile power systems.
- Construction activity in German industrial clusters:Chemical and automotive plant expansions along the Rhine corridor require modular prime power for grid-constrained greenfield sites.
- F-Gas Regulation refrigerant constraints:Temperature-controlled auxiliary systems must now use compliant cooling architectures, pulling replacement demand through rental channels as legacy equipment phases out.
Market Restraints
- Diesel fuel price volatility:Input cost swings compress rental margin predictability and complicate fixed-rate contract pricing for fleet operators.
- Engine supply concentration in Germany and Japan:Core component sourcing relies on a narrow manufacturing base, exposing lead time risk during capacity crunches.
- Battery energy density limitations:Current lithium-ion configurations cannot sustain multi-day prime power loads without prohibitive weight and footprint penalties.
Strategic Opportunities
- Polish and Romanian data center construction:These markets show underpenetrated standby power rental demand as hyperscale facilities seek alternatives to saturated Frankfurt and Amsterdam corridors.
- EMA and ECHA chemical registration pathways:Streamlined compliance frameworks for alternative fuel additives and synthetic lubricants reduce barrier-to-entry for novel generator technologies.
- Hybrid-diesel and solar-battery convergence:Technology pairing enables fuel consumption reductions that meet tightening municipal emissions codes while preserving deployment flexibility.
Industry Challenges
- CE marking certification timelines:Extended conformity assessment procedures for hybrid architectures delay fleet deployment and tie up working capital in pre-certified inventory.
- Grid synchronization engineering expertise:Scarce technical talent capable of configuring paralleling switchgear and load-sharing protocols constrains operational scaling.
- Legacy diesel fleet stranding risk:Carbon border adjustment mechanisms approaching implementation threaten residual value for non-compliant assets still under depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Power Rental Market |
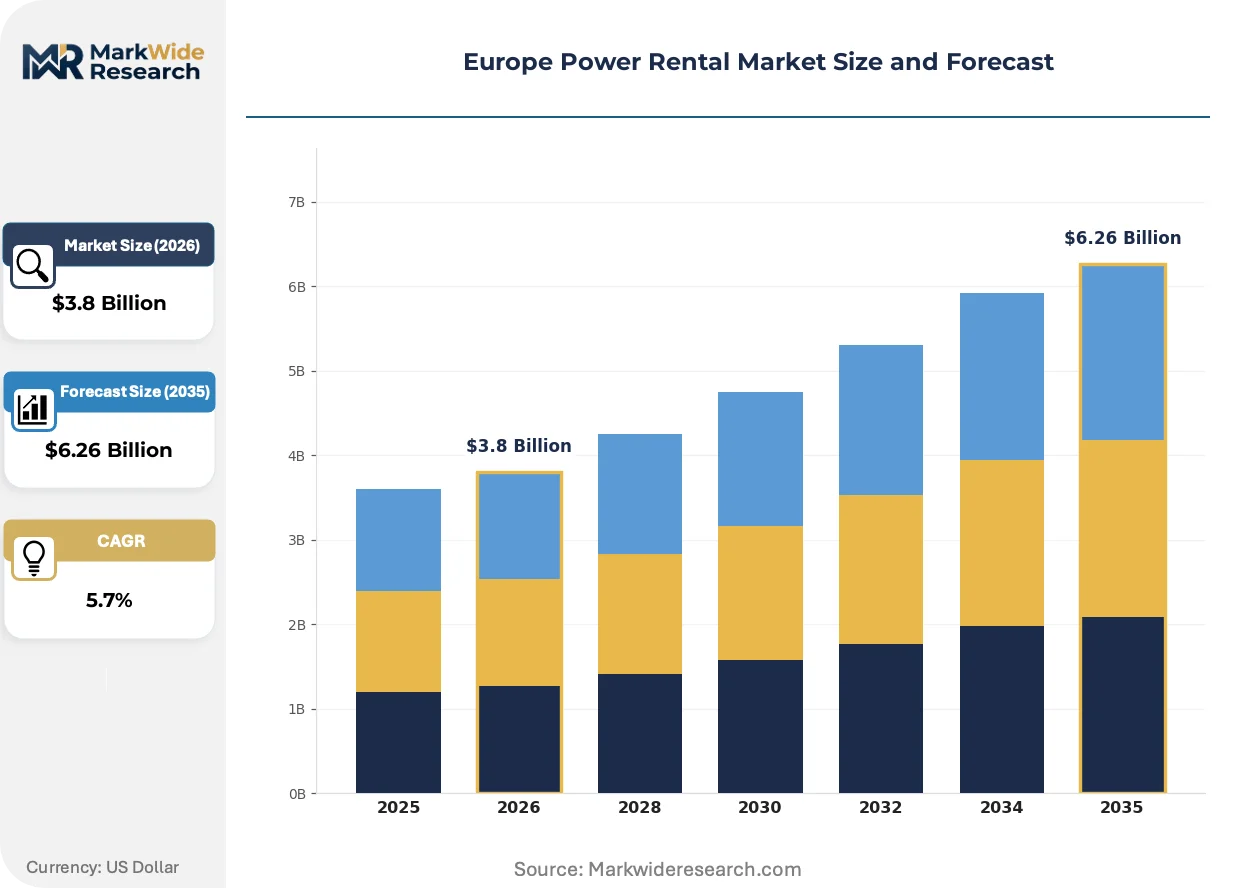
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Standby Power, Prime Power, Peak Shaving, Temporary Power Application: Construction, Events, Industrial, Mining Technology: Diesel Generators, Gas Generators, Hybrid Systems, Solar Solutions End User: Utilities, Commercial, Government, Emergency Services |
| Companies Covered | Atlas Copco, Ashtead Group, Aggreko, Wacker Neuson, Herc Rentals, Caterpillar Inc., Cummins Inc., Kohler Co., United Rentals, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Power Rental Market Strategic Shifts & Innovations
Remote monitoring architectures are reshaping how rental fleets are managed, shifting value capture from equipment availability toward uptime guarantees and predictive maintenance outcomes.
Telematics-enabled generator control is digitizing fleet operations across European rental depots. Real-time fuel consumption, load profiling, and predictive fault detection now come standard on units above 500 kVA. Data center operators in the Netherlands and Ireland are mandating these capabilities in tender specifications. The technology is digitizing traditional rental economics by enabling outcome-based pricing tied to actual runtime reliability rather than day-rate structures.
The EU F-Gas Regulation is compressing refrigerant choices for temperature-controlled auxiliary power systems. Phase-down schedules for hydrofluorocarbons are forcing redesign of generator-mounted HVAC and cooling circuits. German and French rental fleets face the steepest retrofit obligations given their concentration of climate-controlled equipment. Manufacturers are responding with CO2-based and hydrocarbon alternative cooling loops that require modified service protocols and technician retraining.
Consolidated procurement by hyperscale data center operators is concentrating buyer power in standby power rental negotiations. Single-source, multi-year framework agreements are displacing spot rental for critical infrastructure applications. Channel disintermediation is visible in Ireland and Denmark, where operators contract directly with manufacturer service arms for dedicated fleet allocation. This pattern is compressing margins for traditional rental houses while rewarding vertically integrated suppliers with captive engineering resources.
Europe Power Rental Market Segmentation
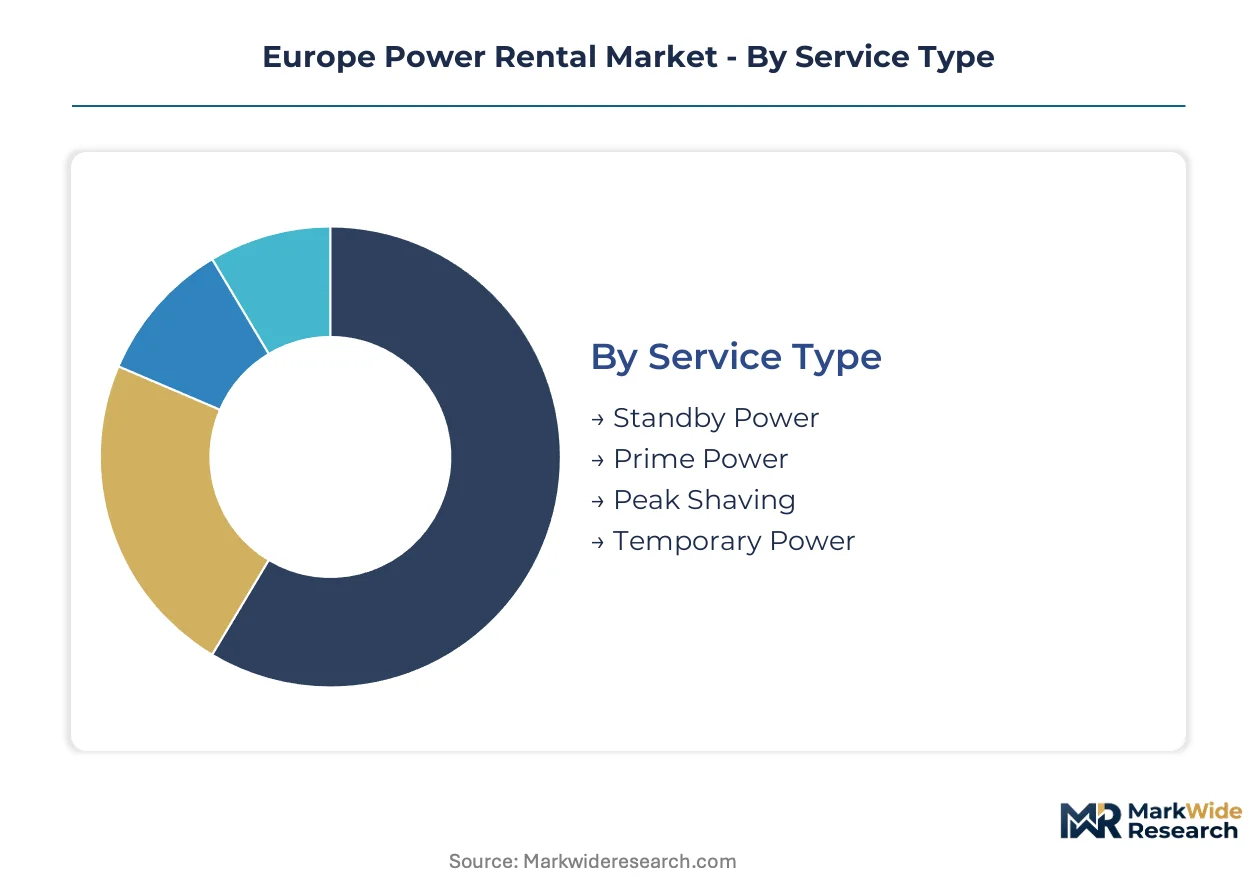
Power rental segmentation in Europe tracks how mobile generation assets align with distinct operational rhythms, regulatory exposure, and capital deployment patterns across industrial and infrastructure verticals. Fleet configuration decisions vary sharply between standby contracts for grid-dependent facilities and prime power deployments for off-grid construction corridors.
Service Type:
Service type segmentation maps directly onto the duration-intensity spectrum of European power demand, from emergency backup through continuous industrial supply.
- Standby Power:Emergency generation systems rated for automatic load transfer within 10-15 seconds, typically contracted under multi-year frameworks by data center operators in Ireland and the Netherlands to satisfy grid reliability mandates. EMA equipment certification and local grid codes determine acceptable response protocols.
- Prime Power:Continuous-duty generators deployed for weeks-to-months at construction sites and industrial shutdowns along Germany's Rhine corridor, where grid extension timelines exceed project schedules. Rental rates command premiums over standby given fuel logistics and maintenance intensity.
- Peak Shaving:Modular units dispatched during grid congestion events to avoid demand charges or capacity shortages, concentrated in French and Italian industrial zones with seasonal load volatility.
- Temporary Power:Rapid-deployment assets for planned outages, events, or disaster response, characterized by short-duration contracts and highest fleet turnover velocity.
The dominant share belongs to Standby Power, while Prime Power is closing the gap fastest as German industrial construction accelerates.
Application:
Application segmentation reveals how sector-specific load profiles and site constraints shape generator specifications across European rental markets.
- Construction:Mobile units from 100-500 kVA powering tower cranes, welding clusters, and site offices at greenfield developments in Poland and Romania. CE marking for construction machinery compatibility drives equipment selection.
- Events:Low-noise, aesthetically enclosed systems for festivals and sporting venues, concentrated in UK and Spanish summer circuits where municipal noise ordinances tighten annually.
- Industrial:High-capacity modular configurations for chemical plant turnarounds and automotive line shutdowns, with German chemical parks representing the densest demand cluster.
- Mining:Heavy-duty prime power for aggregate extraction and processing in Scandinavian and Eastern European operations, where grid remoteness necessitates months-long deployments.
Industrial applications generate the highest revenue per deployed megawatt, though Construction commands the greatest unit volume across European rental fleets.
Technology:
Technology segmentation captures the fleet transition pressure from EU Green Deal emissions timelines and F-Gas refrigerant constraints.
- Diesel Generators:Reciprocating engines dominating fleet value through energy density and deployment speed, though facing residual value risk from carbon border adjustments. German rental houses hold the largest legacy concentrations.
- Gas Generators:Natural gas and biogas systems gaining share in urban environments where NOx limits constrain diesel operation, particularly around London and Paris low-emission zones.
- Hybrid Systems:Diesel-battery or gas-battery configurations reducing fuel consumption by 20-40% for variable-load applications, expanding most quickly in Netherlands data center standby specifications.
- Solar Solutions:PV-battery mobile units for low-load, extended-duration applications, constrained by weather dependency but advancing in Southern European event and construction site deployments.
Diesel Generators retain installed base dominance, yet Hybrid Systems are expanding most quickly as 2030 emissions benchmarks approach.
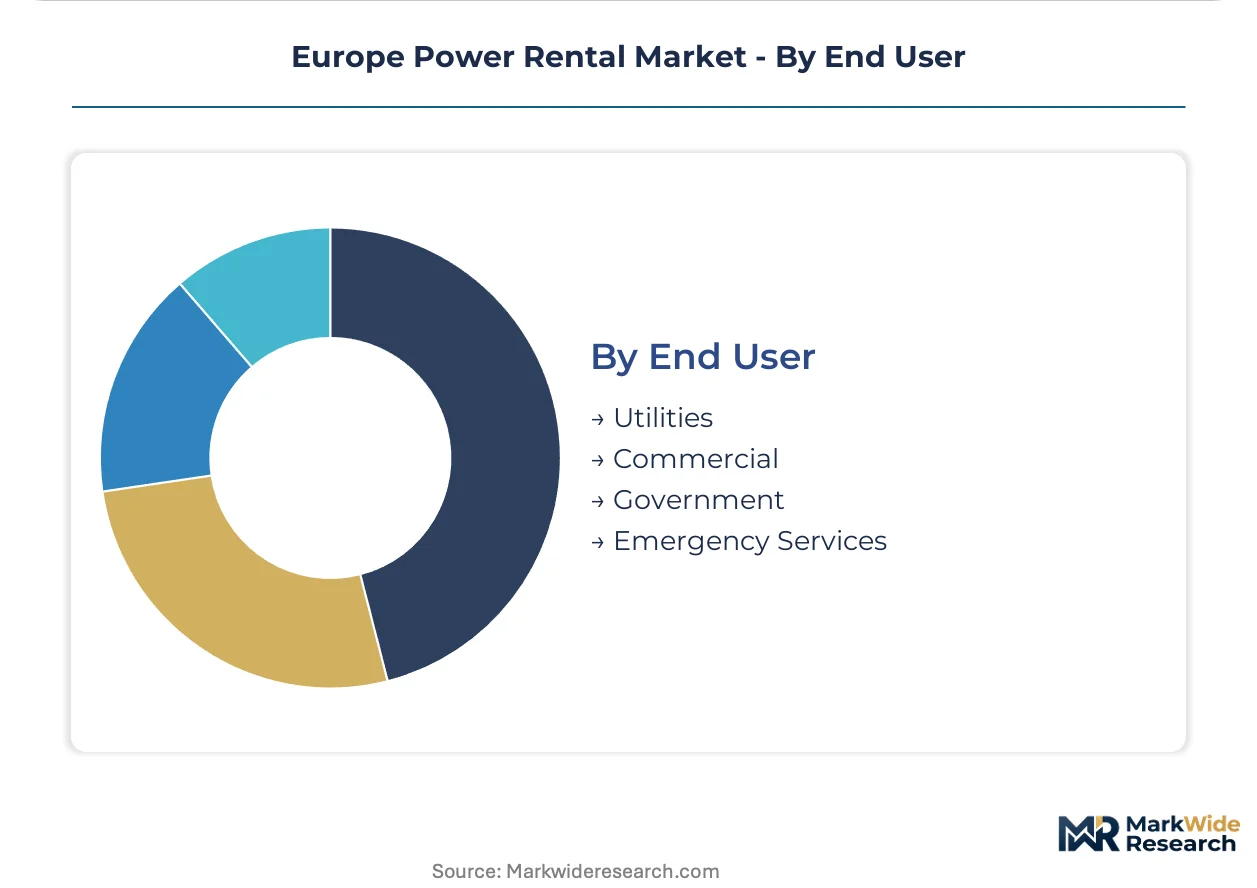
End User:
End user segmentation distinguishes procurement sophistication, contract duration, and technical specification authority across European rental channels.
- Utilities:Transmission and distribution operators contracting grid support and emergency restoration assets, with French and German TSOs driving standardization through framework agreements.
- Commercial:Data center operators, retail chains, and logistics facilities seeking backup power, increasingly mandating telematics and hybrid capability in tender specifications.
- Government:Defense, municipal, and infrastructure agencies with procurement governed by public tender rules, concentrated in UK and Nordic civil contingency programs.
- Emergency Services:Fire, police, and medical response coordination units requiring rapid-deployment mobile power for command centers and field hospitals.
Commercial end users contribute the largest revenue pool, while Utilities demonstrate the steepest contract value growth through multi-year framework structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German rental houses command 15-20% pricing premiums over Polish counterparts due to CE marking density and ECHA compliance infrastructure. Northern European data center clusters absorb premium standby contracts while Southern European construction corridors drive volume deployment.
Germany
Chemical plant expansions along the Rhine corridor and automotive line shutdowns in Baden-Württemberg sustain prime power demand. The F-Gas Regulation forces rapid HVAC retrofit cycles in temperature-controlled auxiliary systems. Munich and Stuttgart industrial clusters anchor the continent's densest rental generator deployment.
United Kingdom
London low-emission zones and municipal noise ordinances accelerate gas generator adoption for events and construction. EMA equipment certification requirements filter non-compliant assets from standby power tenders. The M25 corridor and Scottish renewable construction sites generate contrasting seasonal demand patterns.
Netherlands
Hyperscale data center construction in Amsterdam and Eindhoven compresses procurement cycles for long-duration standby contracts. Grid reliability mandates from national regulators elevate hybrid specifications as default technical thresholds. Rotterdam port expansion and greenhouse horticulture clusters add prime power volume.
Poland
Underpenetrated data center development in Warsaw and Krakow creates standby power rental whitespace as hyperscale operators seek alternatives to saturated Western corridors. EU Green Deal funding accelerates industrial park electrification. Silesian mining operations and Baltic port construction sustain diesel-dominant prime power demand.
France
Nuclear plant maintenance schedules and grid congestion events in Île-de-France drive peak shaving contract velocity. ANSM and CNIL data protection requirements complicate telematics deployment for critical infrastructure applications. Lyon industrial zones and Mediterranean event circuits split demand between heavy-duty and low-noise specifications.
Europe Power Rental Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream on engine supply and paralleling switchgear. The European power rental market structures around three tiers: multinational depot networks with CE marking compliance infrastructure, manufacturer-direct service arms with captive engineering resources, and regional rental houses competing on local response velocity. Two strategic archetypes dominate—vertically integrated engine manufacturers leveraging component control, and asset-light fleet operators optimizing utilization through decentralized logistics. Competitive moves concentrate on hybrid technology licensing partnerships and geographic densification in underpenetrated data center corridors.
Among UK-based rental platforms, Aggreko and Ashtead Group exemplify contrasting scale strategies. Aggreko anchors the multinational depot archetype through decentralized network coverage. Ashtead Group sits within the capital-intensive fleet ownership tier. Caterpillar Inc. represents the manufacturer-direct vector with captive engineering resources.
| Leading Market Players |
|---|
| Atlas Copco |
| Ashtead Group |
| Aggreko |
| Wacker Neuson |
| Herc Rentals |
| Caterpillar Inc. |
| Cummins Inc. |
| Kohler Co. |
| United Rentals |
| Others |
Cost & Logistics Intelligence
Stuttgart's engine manufacturing cluster anchors European generator component supply, with capacity utilization swings rippling through downstream rental pricing power. German rental houses translate CE marking density and ECHA compliance infrastructure into 15-20% premiums over Polish counterparts, while fuel volatility compresses margin predictability across fixed-rate contract portfolios.
Pricing Analysis
The configured-to-order premium spread separates standard diesel generator day-rates from hybrid systems with integrated telematics and predictive maintenance guarantees. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales bundling intensity. Cost compression in economy-tier diesel fleets is intensifying because carbon border adjustment mechanisms threaten residual values for non-compliant assets. Data center operators demonstrate lowest price sensitivity given grid reliability mandate penalties, while construction contractors in Eastern Europe exhibit highest elasticity to fuel-linked rate adjustments.
Supply Chain Analysis
Tariff exposure between Germany and Japan dominates supply chain risk for reciprocating engine cores, with both nations anchoring 80% of prime mover manufacturing for European rental fleets. Component sourcing draws from German casting foundries, Japanese precision machining, and Chinese electrical enclosures. Single-source vulnerability concentrates in 2,000 kVA-class engine blocks from Munich and Nagoya manufacturing lines. Distribution runs through manufacturer-direct service arms in data center corridors and decentralized depot networks for construction site logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid synchronization engineering expertise sits in critically short supply across European rental markets, constraining operational scaling for hybrid fleet deployment and paralleling switchgear configuration. This capability gap separates incumbents with captive technical talent from asset-light competitors dependent on contract engineering.
For Market Incumbents: Pre-empt stranded asset risk by accelerating diesel-to-hybrid fleet turnover ahead of EU Green Deal enforcement timelines. Secure backward integration into battery energy storage systems to control core component supply during lithium-ion procurement crunches. Channel control through multi-year framework agreements with Dutch and Irish data center operators defends against manufacturer-direct disintermediation. For New Entrants and Emerging Players: Polish data center construction whitespace offers the most penetrable standby power rental demand, with Warsaw and Krakow hyperscale facilities seeking alternatives to saturated Frankfurt and Amsterdam corridors. Romanian industrial park electrification under EU Green Deal funding creates prime power volume for modular gas generator deployment. Telematics-enabled outcome-based pricing tied to uptime guarantees rather than day-rate structures provides differentiated go-to-market positioning against legacy rental houses. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated depot networks with hybrid licensing partnerships and CE marking compliance infrastructure. Five-to-ten year viability hinges on fleet carbon intensity trajectories and residual value preservation under tightening emissions benchmarks. Acquisition target archetypes include regional rental houses in underpenetrated Eastern European corridors with established local response velocity. The signal to watch is hyperscale data center procurement consolidation into single-source framework agreements, compressing spot rental margins and rewarding dedicated fleet allocation capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Technology Licensing | Partnerships with battery system specialists enable fuel consumption reductions meeting Dutch municipal emissions codes. |
| Depot Network Densification | Decentralized logistics in Polish and Romanian corridors capture data center construction whitespace before incumbent saturation. |
| Telematics Platform Integration | Real-time load profiling and predictive fault detection satisfy Netherlands tender specifications for critical infrastructure. |
| Backward Integration into Energy Storage | In-house battery system production insulates against lithium-ion supply concentration in Asian manufacturing hubs. |
| CE Marking Fast-Track Program | Streamlined conformity assessment for hybrid architectures reduces working capital tie-up in pre-certified inventory. |
Research Approach
Operator-level perspectives from fleet managers at rental houses, data center infrastructure directors, EPC contractors, and grid synchronization engineers anchored the qualitative base for this study. Primary interviews combined with secondary validation against EMA equipment certification databases, F-Gas Regulation compliance filings, customs trade data for generator imports, and EU Green Deal implementation progress reports. Bottom-up deployment modeling across service type, application, and technology segments triangulated against top-down market sizing from national industrial construction permits and data center power demand forecasts.
Scenario-bracketing framed the analytical approach across the analysis window, with base, upside, and downside cases reflecting divergent EU emissions enforcement timelines and grid reliability mandate adoption rates. Segmentation dimensions modeled include service type intensity, application vertical load profiles, technology fuel source, and end-user procurement sophistication. CAGRs were derived from installed fleet turnover assumptions and replacement demand elasticity to carbon pricing mechanisms. Industry-specific forecast inputs encompassed Rhine corridor chemical plant expansion schedules and Amsterdam-Eindhoven hyperscale construction pipelines.
Practitioners should monitor EU Green Deal implementation pace, carbon border adjustment mechanism rollout, and battery energy density breakthroughs for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Steam Turbine Control System Market
Power Equipment
Gas Fixed Power Capacitors Sales Market
Power Equipment
Power Cables Market
Power Equipment
Global Power Supply Market
Power Equipment
US Power EPC Market
Power Equipment
United Kingdom Power EPC Market
Power Equipment
Induction Heating System Market
Power Equipment
Natural Gas Turbine Market
Power Equipment
Deaerators Market
Power Equipment
North America SCR Power Controller Market
Power Equipment
Nigeria Power EPC Market
Power Equipment
United Arab Emirates Power Market
Power Equipment
Wind Turbine Equipment Market
Power Equipment
Turbine Control Systems Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
G-3 PLC Solutions Market