
 ASEAN Power EPC Market | 2026-2036
ASEAN Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Power EPC Market Outlook
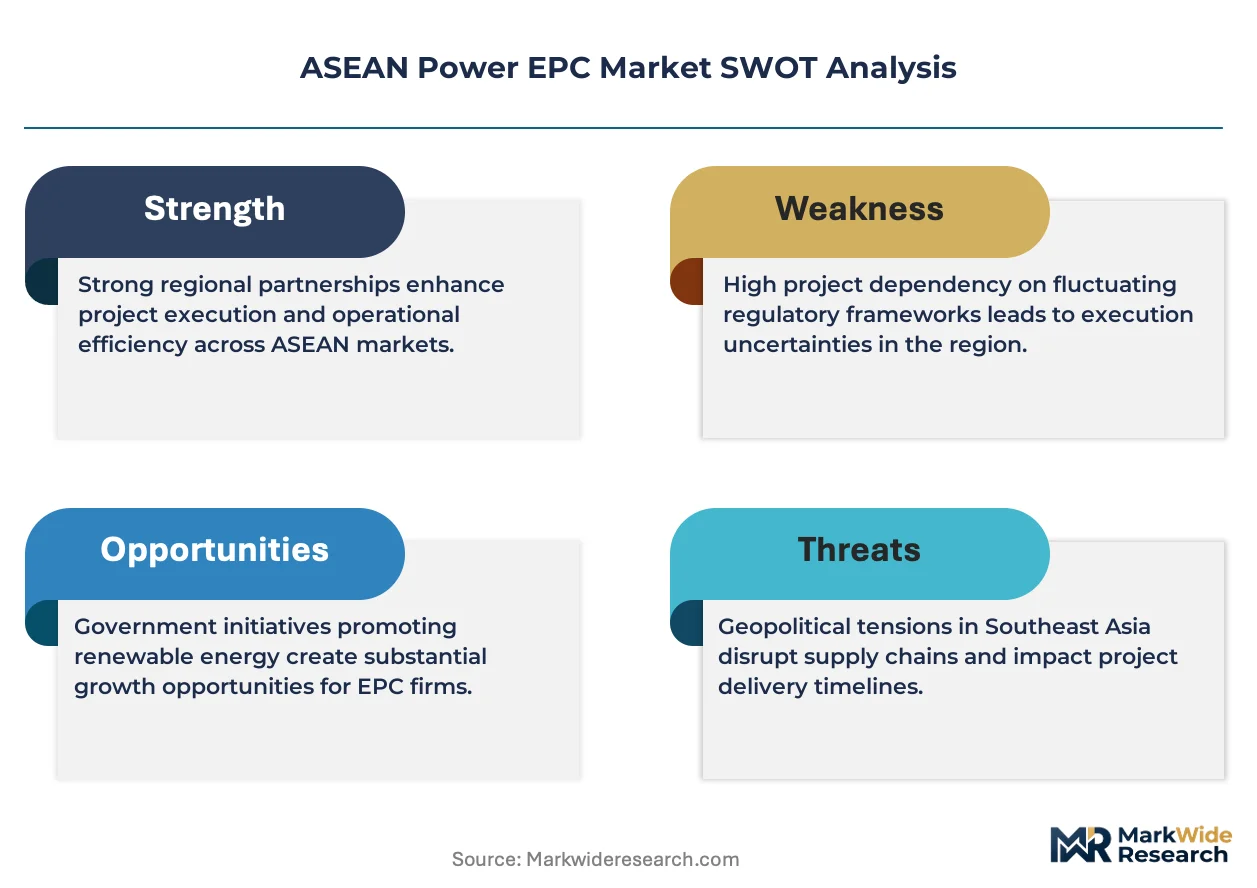
EPC contract margin pools is narrowing from pure construction toward long-term operations and maintenance agreements. Mitsubishi Heavy Industries leverages its integrated turbine-generator manufacturing to capture downstream service revenue across Indonesian coal plant retrofits. Hyundai Engineering sustains competitive positioning through fabrication yard ownership in Vietnam, controlling steel structure supply for combined-cycle projects.
ASEAN Power EPC encompasses the engineering, procurement, and construction of power generation and transmission infrastructure, typically involving turbine installation, switchyard configuration, and grid synchronization within 18-36 month project cycles. The primary purpose is delivering utility-scale electricity assets under lump-sum turnkey contracts with performance guarantees. Hydropower retains the largest installed base across Laos and Myanmar, though solar EPC is expanding fastest as module costs decline and Southeast Asian utilities seek distributed generation alternatives. Commissioning services command premium pricing due to scarcity of certified grid-code specialists who can manage frequency stabilization protocols for variable renewable injection.
Thailand's Department of Energy Business enforces power purchase agreement standards that dictate EPC contractor liability periods and availability guarantees. Vietnam's Ministry of Industry and Trade coordinates national power development planning that directly determines which generation technologies receive construction permits and foreign investment licensing. The Philippines' Energy Regulatory Commission oversees competitive selection rules for transmission and generation projects, shaping how EPC consortia form and bid. Stakeholders must monitor how each ASEAN member state reconciles domestic content requirements with technology transfer demands from Korean and Japanese prime contractors.
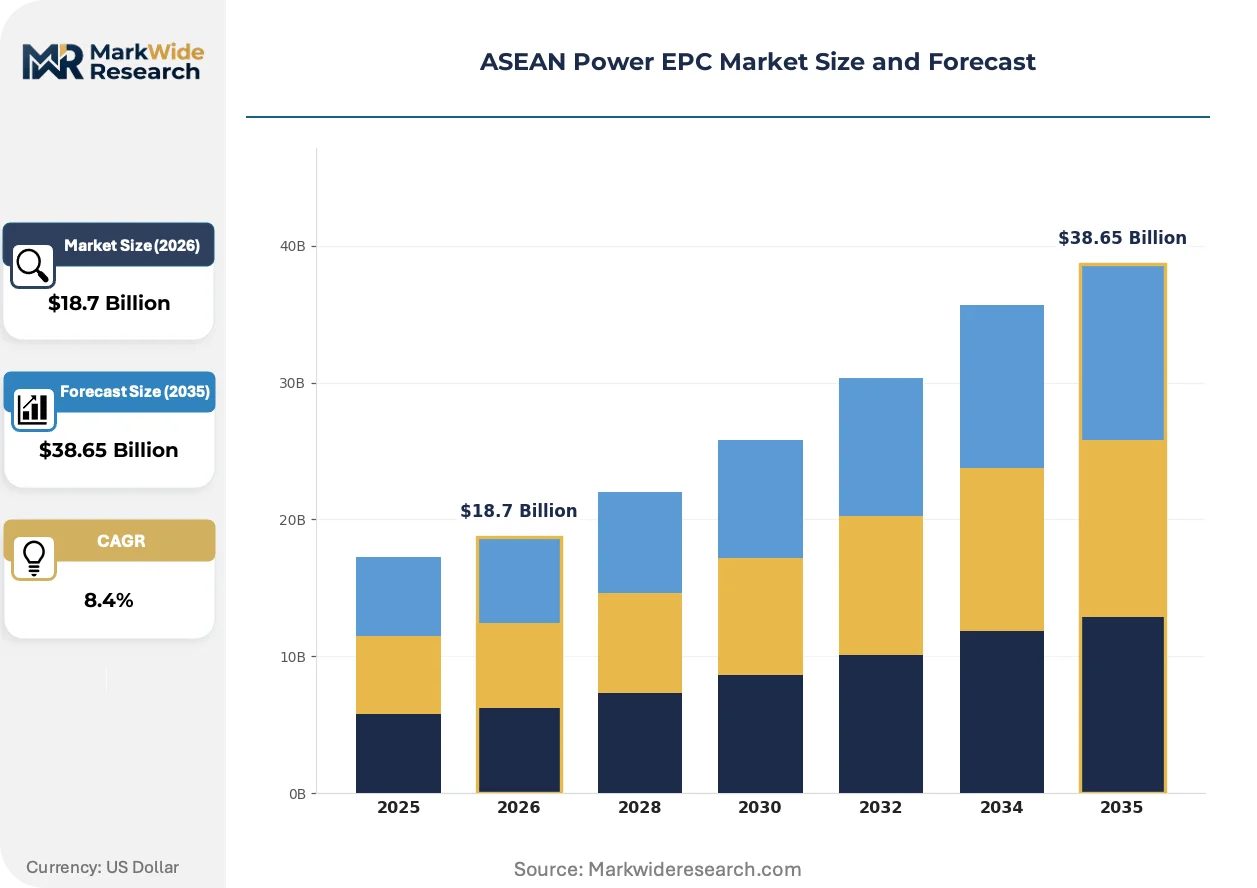
Market Dynamics
The ASEAN Power EPC market is undergoing structural compression as turnkey contractors pivot from pure construction margins toward long-term service revenue streams anchored by performance guarantees and availability contracts.
Growth Catalysts
- Feed-in tariff mechanisms:The Philippines' renewable energy targets mandate guaranteed pricing for solar and wind output, accelerating EPC contract awards for utility-scale projects. Foreign developers partner with local contractors to meet domestic content thresholds.
- Coal-to-gas conversion mandates:Vietnam's power development plan prioritizes combined-cycle gas turbine installations to replace aging coal baseload, concentrating demand for turbine-generator EPC specialists.
- Offshore wind licensing:Vietnam's Ministry of Industry and Trade has opened seabed concessions for 10+ GW of offshore capacity, requiring marine foundation and high-voltage substation EPC capabilities.
Market Restraints
- Steel price volatility:Fabricated steel structures constitute 15-25% of combined-cycle project costs, and regional mill capacity constraints in Vietnam and Indonesia create input cost uncertainty.
- Grid-code certification scarcity:Fewer than 200 engineers across Southeast Asia hold certified qualifications for frequency stabilization protocol implementation, bottlenecking renewable project commissioning.
- Domestic content requirements:Indonesia's local content regulations mandate 35-50% local sourcing for power projects, forcing foreign EPC primes to reconfigure supply chains and partner structures.
Strategic Opportunities
- Laos hydropower export infrastructure:Cross-border transmission EPC contracts linking Lao dams to Thai and Vietnamese grids represent underpenetrated white space for regional contractors.
- Myanmar captive power:Industrial zone developers seek distributed gas and solar EPC solutions as grid reliability remains inconsistent, bypassing centralized utility procurement.
- Battery energy storage integration:Philippine utilities now require 4-hour storage co-location with solar EPC contracts, creating new subsystem specialization opportunities.
Industry Challenges
- Commissioning engineer shortages:Grid synchronization specialists capable of managing variable renewable injection protocols command 3-5x standard EPC salaries, compressing project margins.
- Equipment warranty alignment:Turbine OEMs and EPC contractors dispute liability boundaries for availability guarantee failures, complicating contract structuring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Power EPC Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Construction, Installation, Maintenance, Commissioning End User: Utility Companies, Government Agencies, Independent Power Producers, Industrial Plants Technology: Solar Power, Wind Energy, Hydropower, Biomass Installation Type: Onshore, Offshore, Grid-Connected, Standalone |
| Companies Covered | Mitsubishi Heavy Industries Ltd., Hyundai Engineering Co. Ltd., Sumitomo Corporation, Doosan Heavy Industries & Construction Co., Ltd., Toshiba Corporation, JGC Holdings Corporation, Kawasaki Heavy Industries Ltd., IHI Corporation, Trung Nam Group, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Power EPC Market Strategic Shifts
Modular construction methods and digital twin commissioning are compressing project timelines and reshaping how ASEAN utilities evaluate contractor capabilities beyond traditional lump-sum pricing.
Containerized solar PV balance-of-plant systems are collapsing field installation schedules for distributed generation projects. Philippine commercial and industrial offtakers now specify plug-and-play substation modules that slash civil works duration. This standardization is collapsing the traditional 18-24 month solar EPC cycle toward 12-month execution, favoring contractors with captive electrical switchgear production.
Thailand's Department of Energy Business now mandates digital SCADA integration standards for all new generation assets above 10 MW. This regulatory requirement forces EPC bidders to demonstrate in-house automation engineering capabilities or partner with certified system integrators. The policy is accelerating obsolescence of pure civil-mechanical contractors who lack electrical controls expertise.
Utility procurement departments across Vietnam and the Philippines are unbundling EPC contracts into separate engineering, major equipment, and construction packages. State-owned utilities seek direct relationships with turbine OEMs while outsourcing only balance-of-plant construction. This disintermediation is compressing margins for traditional turnkey primes and rewarding specialized BOP contractors with fabrication yard assets.
ASEAN Power EPC Market Segmentation
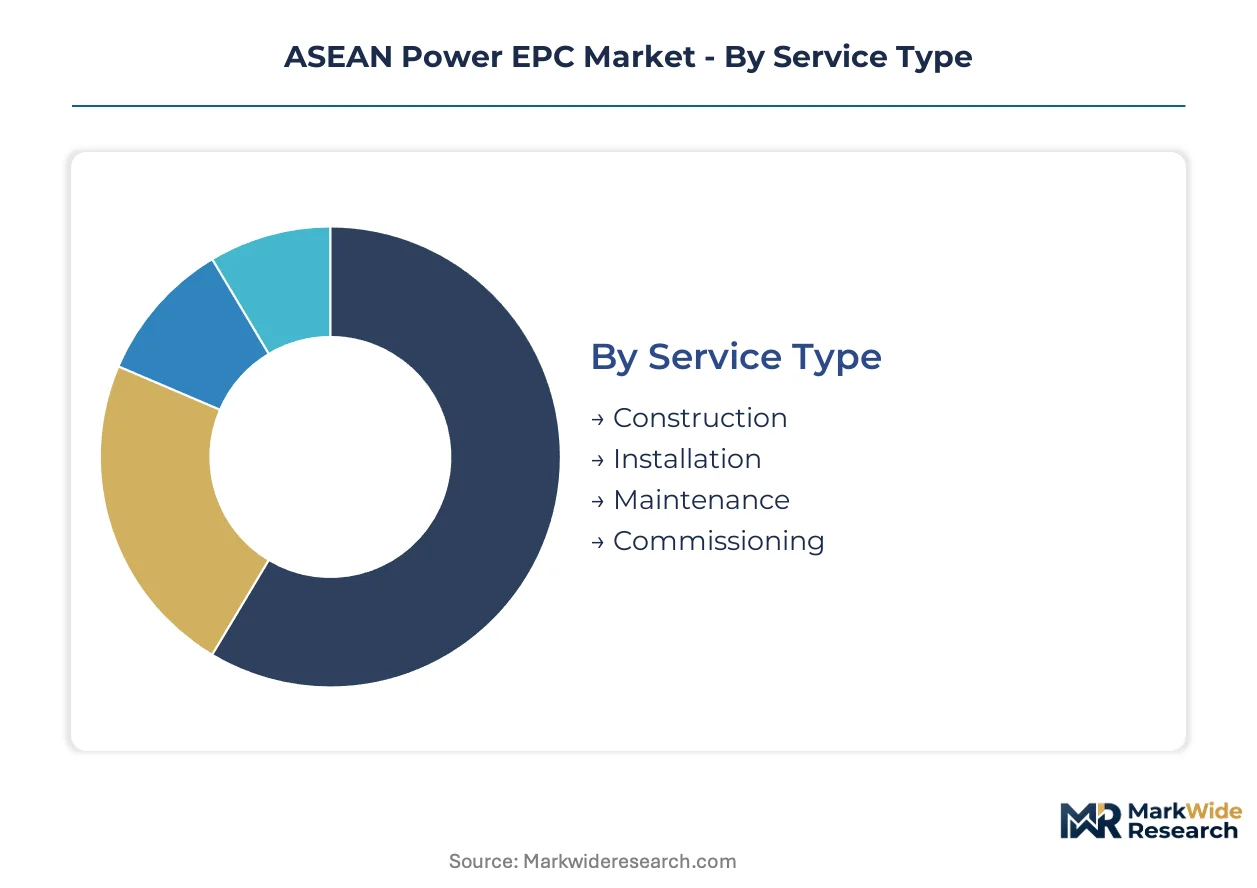
ASEAN Power EPC market segmentation reveals how contract structures align with technology maturity and regulatory frameworks across Southeast Asia. Service specialization determines margin capture, while end-user procurement patterns shape consortium formation and risk allocation.
Service Type:
Contract scope spans discrete execution phases with diverging margin profiles and technical certification requirements.
- Construction:Civil works, structural steel erection, and building envelope completion form the capital-intensive foundation of turnkey projects. Philippine solar farms and Vietnamese combined-cycle plants concentrate demand here, though steel price volatility compresses returns for contractors without captive fabrication assets.
- Installation:Mechanical assembly of turbine-generator sets, cooling systems, and electrical switchyards demands precision alignment within tight outage windows. Grid-connected renewable projects in Thailand and Indonesia favor contractors with integrated module mounting and cabling capabilities.
- Maintenance:Long-term service agreements covering scheduled overhauls, parts replacement, and availability guarantees now generate recurring revenue exceeding original construction margins. Indonesian coal retrofits and Thai gas turbine fleets anchor this segment's expansion.
- Commissioning:Grid synchronization, frequency stabilization protocol implementation, and performance testing require scarce certified specialists. Fewer than 200 engineers across Southeast Asia hold requisite qualifications, creating severe bottlenecks for variable renewable injection projects.
Established volume favors Construction; emerging adoption favors Commissioning.
End User:
Procurement sophistication varies sharply across buyer categories, dictating contract terms and partnership structures.
- Utility Companies:State-owned power developers in Vietnam, Thailand, and the Philippines drive the largest contract awards through competitive bidding with stringent domestic content and technology transfer requirements. Their centralized procurement favors established EPC primes with balance sheet capacity for performance guarantees.
- Government Agencies:Ministry-led rural electrification and transmission backbone projects in Laos and Myanmar emphasize geopolitical financing alignment over pure commercial terms. Contractors must navigate multilateral development bank procurement protocols.
- Independent Power Producers:Private developers under Philippine feed-in tariff and Vietnamese direct power purchase mechanisms seek faster execution with streamlined permitting. Their risk appetite enables alternative contracting structures including engineering-procurement with separate construction management.
- Industrial Plants:Captive power seekers in Thai and Vietnamese manufacturing zones prioritize reliability over scale, driving distributed gas and solar EPC demand outside centralized utility procurement channels.
Contract concentration clusters with Utility Companies; margin expansion potential sits with Industrial Plants.
Technology:
Generation technology selection determines equipment supply chains, civil works intensity, and grid integration complexity.
- Solar Power:Photovoltaic EPC dominates new capacity additions as module costs decline and Southeast Asian utilities pursue distributed generation alternatives. Containerized balance-of-plant systems are collapsing Philippine and Thai project timelines toward 12-month execution cycles.
- Wind Energy:Onshore installations face land constraints and community opposition in densely populated regions, while Vietnam's offshore licensing for 10+ GW demands marine foundation and high-voltage substation capabilities few regional contractors possess.
- Hydropower:Retains the largest installed base across Laos and Myanmar with substantial cross-border transmission EPC opportunities linking dams to Thai and Vietnamese grids. Project finance complexity and environmental permitting extend development timelines.
- Biomass:Agricultural residue and palm oil waste-fired plants serve Indonesian and Thai industrial clusters with localized fuel supply chains. Scale limitations and feedstock logistics constrain growth relative to solar and wind alternatives.
Deployment velocity favors Solar Power; project duration and complexity favor Hydropower.
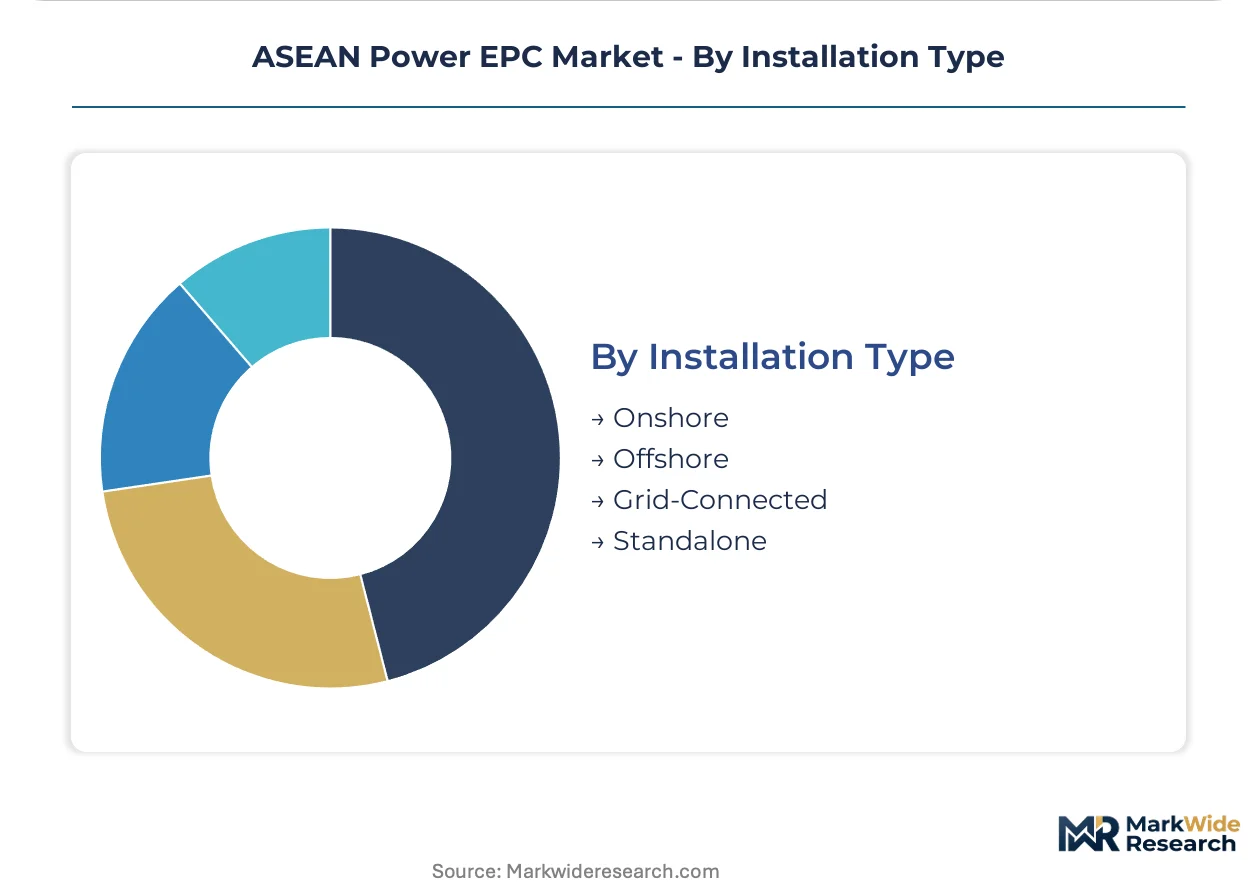
Installation Type:
Siting configuration determines marine logistics requirements, grid connection standards, and offtake contract structures.
- Onshore:Land-based generation dominates current EPC activity with established civil works methodologies and equipment transport infrastructure. Solar and onshore wind projects across Thailand, the Philippines, and Vietnam concentrate procurement here.
- Offshore:Vietnam's seabed concessions require specialized marine construction vessels, jacket foundation fabrication, and subsea cable installation capabilities. High capital barriers limit contractor participation to international primes with dedicated offshore assets.
- Grid-Connected:Synchronization with national transmission networks mandates compliance with each ASEAN member state's grid code, frequency response requirements, and SCADA integration standards. Thailand's Department of Energy Business mandates digital integration for all assets above 10 MW.
- Standalone:Industrial zone captive power and rural microgrids in Myanmar bypass centralized utility infrastructure, favoring modular gas and solar solutions with integrated storage. Procurement sits with private developers rather than state utilities.
Contract flow concentrates in Grid-Connected; capability scarcity defines Offshore.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across ASEAN procurement channels. Philippine feed-in tariff auctions attract cost-focused bidders, while Vietnamese state-owned utilities prioritize technology transfer over lowest cost. Thai industrial zone developers sit between these poles, balancing reliability premiums against capital constraints.
Vietnam
Offshore wind licensing and coal-to-gas conversion dominate EPC demand. The Ministry of Industry and Trade coordinates national power development planning that determines construction permits and foreign investment licensing. Southern coastal provinces concentrate marine foundation fabrication as seabed concessions open for 10+ GW capacity.
Philippines
Renewable energy targets and feed-in tariff mechanisms accelerate solar and wind contract awards. The Energy Regulatory Commission oversees competitive selection rules for transmission and generation projects. Luzon island hosts the densest cluster of utility-scale solar farms under construction.
Thailand
Gas turbine fleet expansion and digital SCADA mandates shape contractor selection. The Department of Energy Business enforces power purchase agreement standards dictating liability periods and availability guarantees. Eastern Economic Corridor industrial zones drive captive power demand for combined-cycle installations.
Indonesia
Coal plant retrofits and local content regulations reconfigure supply chains. Domestic content mandates require 35-50% local sourcing, forcing foreign primes to restructure partnerships. Java-Bali grid interconnection projects concentrate transmission EPC activity around Jakarta.
Laos
Hydropower export infrastructure creates cross-border transmission opportunities. Government agencies coordinate rural electrification emphasizing multilateral development bank procurement alignment. Nam Ngum and Xayaburi dam corridors anchor high-voltage line construction toward Thai borders.
ASEAN Power EPC Market Competitive Environment
Integrated turbine manufacturers and specialized balance-of-plant contractors split the market along equipment-versus-civil fault lines. Japanese and Korean industrial conglomerates anchor the prime contractor tier with captive manufacturing assets. Mid-scale regional players compete on fabrication yard ownership and domestic content compliance. Competitive moves center on long-term service agreement anchoring and marine logistics capability acquisition for offshore wind exposure.
Among Japanese industrial conglomerates, Mitsubishi Heavy Industries Ltd. and Toshiba Corporation exemplify the integrated equipment-manufacturing archetype with downstream service revenue capture. Hyundai Engineering Co. Ltd. represents Korean fabricators leveraging Vietnam-based steel structure supply control. These three anchors demonstrate how prime contractors defend positioning through captive production assets and geographic supply chain placement.
| Leading Market Players |
|---|
| Mitsubishi Heavy Industries Ltd. |
| Hyundai Engineering Co. Ltd. |
| Sumitomo Corporation |
| Doosan Heavy Industries & Construction Co., Ltd. |
| Toshiba Corporation |
| JGC Holdings Corporation |
| Kawasaki Heavy Industries Ltd. |
| IHI Corporation |
| Trung Nam Group |
| Others |
Value Chain & Pricing Dynamics
The Singapore-Johor freight corridor anchors cost dynamics across ASEAN power EPC procurement, where fabrication yard proximity to Vietnamese and Indonesian steel mills creates tiered logistics premiums that separate turnkey primes from balance-of-plant specialists. This corridor's congestion and bunker fuel volatility feed directly into contractor pricing power, with those controlling captive steel supply commanding 15-25% cost advantages on combined-cycle structures.
Pricing Analysis
Long-term service agreements covering availability guarantees and scheduled overhauls now generate lifetime value exceeding original construction margins by substantial multiples. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by contractor certification grade for grid-code compliance and captive fabrication asset ownership. Cost compression in standard-tier solar EPC is intensifying because containerized balance-of-plant systems collapse field installation schedules toward 12-month execution. Independent power producers under Philippine feed-in tariff mechanisms exhibit highest price sensitivity, while Vietnamese state-owned utilities prioritize technology transfer and accept reliability premiums.
Supply Chain Analysis
Tariff exposure between China and Vietnam dominates supply chain risk calculus for steel structures and electrical switchgear components. Fabrication capacity concentrates in Vietnam, Indonesia, and South Korea, with raw material dependencies centering on hot-rolled steel coils, copper conductors, and high-voltage insulators. Single-source vulnerability sits with certified grid-code commissioning engineers, where fewer than 200 qualified specialists across Southeast Asia bottleneck renewable project completion. Distribution runs through state utility procurement departments in Vietnam, Thailand, and the Philippines, with direct OEM relationships increasingly displacing traditional turnkey intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN power EPC represents a service-attach opportunity where maintenance and availability contracts expand faster than hardware construction as utilities prioritize operational continuity over capital expenditure.
For Market Incumbents: Entrench positioning through captive fabrication yard ownership in Vietnamese coastal zones and certified grid-code engineering capabilities that scarce commissioning specialists cannot replicate. Acquire marine logistics assets ahead of Vietnam's 10+ GW offshore wind licensing wave to preempt Korean and Japanese prime contractor expansion. Long-term service agreement anchoring remains the priority lever against margin compression from unbundled procurement. For New Entrants and Emerging Players: Myanmar captive power installations for industrial zone developers represent the most penetrable entry point, bypassing centralized utility procurement channels where established primes dominate. Philippine battery energy storage integration subcontracts offer specialized subsystem entry with lower capital barriers than full turnkey competition. Partner with regional switchgear manufacturers for plug-and-play substation module supply to capture collapsed solar EPC timelines. For Investors and Strategic Acquirers: Vietnam's Ministry of Industry and Trade offshore wind licensing milestones reshape the acquisition landscape toward marine foundation fabrication and high-voltage substation capabilities. Target contractors with Vietnamese domestic content compliance structures and Korean or Japanese technology transfer relationships for five-to-ten year viability. Watch seabed concession award velocity as the signal indicating EPC demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Marine Logistics Capability Acquisition | Vietnam's seabed concessions demand jacket foundation fabrication vessels few regional contractors possess. |
| Long-Term Service Agreement Anchoring | Indonesian coal retrofits and Thai gas turbine fleets generate recurring revenue exceeding construction margins. |
| Captive Fabrication Yard Expansion | Steel structure supply control insulates Hyundai Engineering from regional mill capacity constraints. |
| Grid-Code Certification Investment | Scarce frequency stabilization specialists command 3-5x standard EPC salaries, creating bottleneck premiums. |
| Digital SCADA Integration Partnership | Thailand's Department of Energy Business mandates automation standards above 10 MW capacity thresholds. |
Study Parameters
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against IEA power sector reports, ASEAN energy regulator filings, and project development databases tracking construction permits across Vietnam, Thailand, and the Philippines. Bottom-up project pipeline aggregation and top-down macroeconomic scenario triangulation calibrated market sizing.
Scenario-bracketing across conservative, baseline, and expansion cases framed the analytical approach over the projection horizon. Segmentation dimensions modeled include generation technology, project capacity tier, procurement channel structure, and regulatory framework cluster. CAGRs derived from technology-specific deployment trajectories, with inputs including module cost decline curves, steel price volatility bands, and domestic content compliance thresholds.
Macroeconomic conditions sit as an overlay; deviation in regional currency stability, multilateral development bank lending appetite, or seabed concession award velocity would shift the trajectory. Forecasts reflect documented assumptions regarding technology cost curves and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Wind Turbine Gearbox Repair and Refurbishment Market
Power Equipment
Power Cables Market
Power Equipment
G-3 PLC Solutions Market
Power Equipment
Levant Power Cable Market
Power Equipment
Automatic Power Factor Controller Market
Power Equipment
Power Magnetics for MV AC Drive Market
Power Equipment
Thailand Power Market
Power Equipment
Industrial Gas Turbine Sales Market
Power Equipment
Asia-Pacific Gas Turbine MRO Market
Power Equipment
Global Auxiliary Power Unit Market
Power Equipment
Power Plant Maintenance Market
Power Equipment
US Power EPC Market
Power Equipment
AC Power Sources Market
Power Equipment
Gas Fixed Power Capacitors Sales Market
Power Equipment
SCR Power Controller Market
Power Equipment
Magnetic Bearing Market