
 Industrial Jugs Market | 2026-2036
Industrial Jugs Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Jugs Market Foresight
REACH compliance is realigning material specifications across the European supply base. Berry Global Group leverages its polymer science capabilities to sustain certified product lines, while Amcor Plc anchors its position through food-contact-grade jug portfolios. Graham Packaging Company differentiates via high-volume blow-molding scale for chemical-grade containers.
Industrial jugs are rigid containment vessels engineered from HDPE, PP, or fluoropolymer resins with wall thicknesses calibrated for chemical resistance and UN-certified transport integrity. Their primary purpose centers on safe storage, handling, and dispensing of corrosive, flammable, or consumable liquids in manufacturing and logistics environments. Plastic material types dominate volume due to cost-efficiency and impact durability, though metal variants command premium positioning in solvent-heavy chemical storage. Capacity segmentation tilts toward 5-gallon and 10-gallon formats where bulk intermediate handling meets OSHA ergonomic limits.
EPA regulations govern chemical containment standards in US industrial settings, while REACH and the EU Packaging and Packaging Waste Directive shape material composition and recyclability mandates across Europe. FDA food-contact rules additionally constrain polymer additives for food and beverage end uses. Stakeholders must monitor evolving extended producer responsibility frameworks and polymer traceability requirements that will determine which material platforms retain market access.
Market Dynamics
REACH compliance deadlines are compressing material certification cycles across European supply chains, forcing rapid reformulation of polymer additives and accelerating migration toward fluoropolymer alternatives in solvent-contact applications.
Growth Catalysts
- Chemical manufacturing expansion:India's specialty chemical sector is scaling intermediate bulk container infrastructure to serve pharmaceutical and agrochemical export demand.
- REACH substance restrictions:ECHA's evolving candidate list is redirecting procurement toward pre-certified HDPE and PP resin grades that eliminate downstream compliance risk.
- Fluoropolymer barrier technology:Advanced co-extrusion processes are enabling thinner-wall chemical jugs with equivalent solvent resistance, reducing freight cost per unit.
Market Restraints
- HDPE resin supply concentration:Gulf Coast petrochemical complex disruptions transmit directly to jug converter cost structures with limited alternative sourcing.
- UN certification bottlenecks:Testing laboratory capacity constraints in Germany and the Netherlands extend product launch timelines by four to eight months.
- Steel drum substitution:Refillable stainless steel intermediate bulk containers retain total-cost advantages in closed-loop solvent distribution systems.
Strategic Opportunities
- India's chemical parks:Dedicated manufacturing zones in Gujarat and Maharashtra are consolidating formulators seeking localized packaging supply.
- EU Packaging and Packaging Waste Directive:Recycled content mandates above thirty percent by weight are creating first-mover advantage for converters with secure post-consumer HDPE streams.
- Smart dispensing integration:RFID-enabled jug closures combined with inventory management software are penetrating pharmaceutical manufacturing facilities.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for chemical-resistant barrier layers concentrates among retiring specialists in German and US industrial centers.
- Legacy blow-molding asset base:Multi-layer co-extrusion upgrades require capital deployment that mid-tier converters cannot finance without strategic partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Jugs Market |
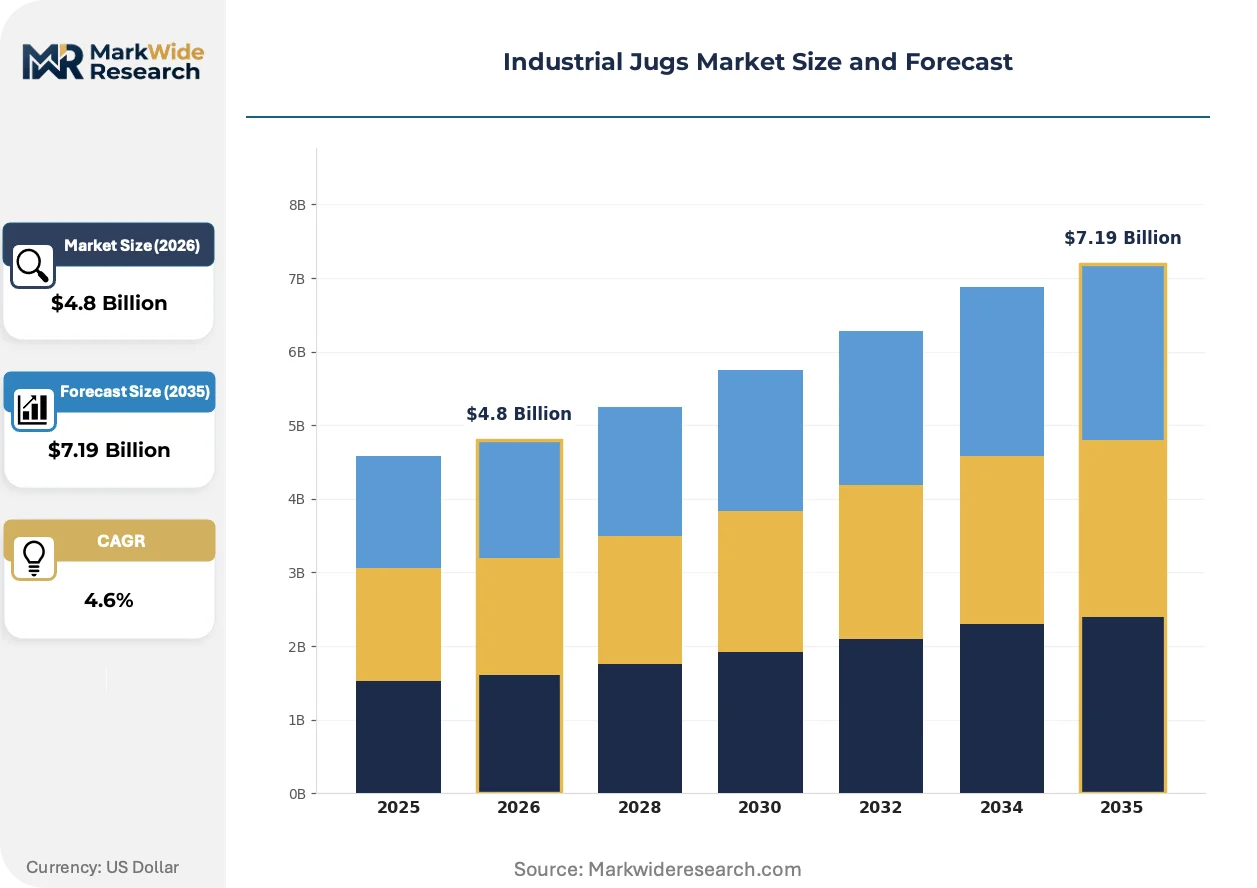
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Glass, Metal, Composite Capacity: 1 Gallon, 5 Gallons, 10 Gallons, 20 Gallons Closure Type: Cap, Spout, Tap, Screw End Use: Chemical Storage, Food & Beverage, Pharmaceuticals, Water Supply |
| Companies Covered | United States Plastic Corporation, MJS Packaging, Berry Global Group, Amcor Plc, ALPLA, Silgan Holdings, Graham Packaging Company, Plastipak Holdings, Greif, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Jugs Market Shifts & Advancements
Material science advances and regulatory stringency are converging to redefine performance benchmarks. Three developments are restructuring competitive positioning across the value chain.
Fluoropolymer-lined HDPE jugs are expanding into high-purity solvent distribution where single-layer containers previously dominated. Pharmaceutical API manufacturers in Switzerland and Singapore are specifying these hybrid constructions to eliminate extractables risk. The technology is compressing addressable market share for unlined metal alternatives in electronic-grade chemical handling.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of conventional barrier coatings. ECHA's 2023 restriction proposal is accelerating converter investment in plasma-treated surface technologies that achieve chemical resistance without fluorinated additives. German chemical distributors are now demanding material declarations that trace fluorine content through three supply tiers.
Consolidated procurement by contract manufacturing organizations is displacing fragmented buyer decision-making. Large pharmaceutical CDMOs in Ireland and Massachusetts are mandating standardized jug specifications across their global facility networks. This concentration is compressing supplier margins while rewarding converters with multi-site certification and unified quality systems.
Industrial Jugs Market Segmentation
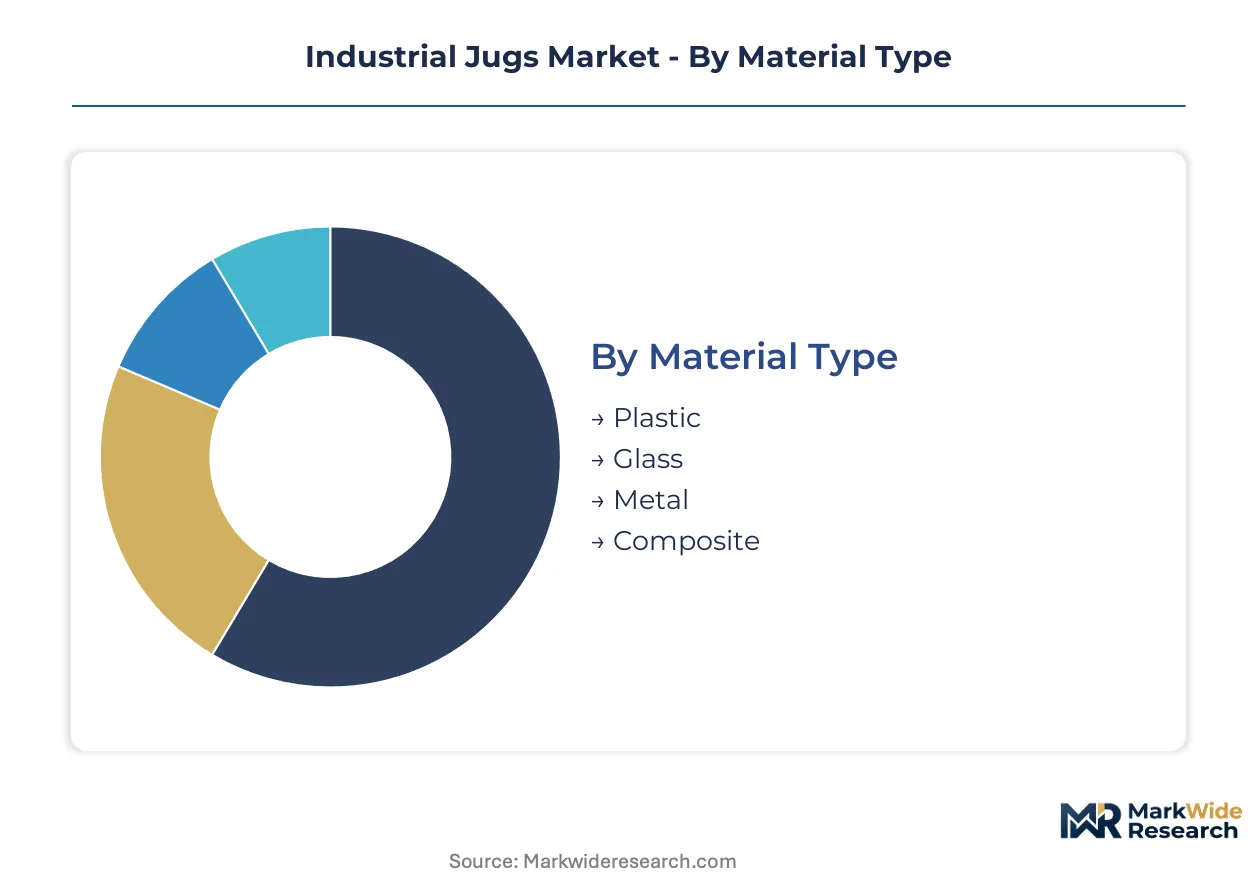
Industrial jug procurement decisions hinge on regulatory alignment across material, capacity, and closure specifications. Each segment carries distinct certification burdens that determine market access and supplier qualification requirements.
Material Type:
UN certification and FDA food-contact approvals segment the material landscape by compliance burden intensity.
- Plastic:HDPE and PP resins dominate volume through cost-efficient blow-molding and inherent chemical resistance. REACH-compliant additive packages from German resin suppliers are becoming mandatory for European chemical distribution.
- Metal:Stainless steel and aluminum variants command premium positioning in solvent-heavy applications requiring spark-resistant containment. UN-certified steel drums retain closed-loop cost advantages in pharmaceutical API logistics.
- Glass:Borosilicate constructions serve high-purity reagent storage where extractables elimination outweighs fragility risk.
- Composite:Fluoropolymer-lined HDPE hybrids are penetrating electronic-grade chemical handling in Singapore and Switzerland.
Leading the category by volume: Plastic. Growing fastest: Composite.
Capacity:
Ergonomic regulations and freight economics split demand across volume tiers with diverging margin profiles.
- 5 Gallons:The ergonomic sweet spot under OSHA lifting limits, this format anchors intermediate bulk handling in manufacturing plants. Indian chemical parks in Gujarat specify this capacity for localized pharmaceutical ingredient distribution.
- 10 Gallons:Bulk efficiency gains drive adoption where forklift access eliminates manual handling constraints. Massachusetts-based pharmaceutical CDMOs are standardizing this format across global facility networks.
- 1 Gallon:Laboratory-scale dispensing and sample transport applications favor this compact footprint.
- 20 Gallons:Drum-scale alternatives for high-volume chemical processors seeking reduced container changeout frequency.
5 Gallons generates the highest unit volume. 10 Gallons shows the steepest expansion trajectory as contract manufacturing consolidation favors format standardization.
Closure Type:
Dispensing precision requirements and tamper-evidence mandates differentiate closure specifications by end-use security needs.
- Screw:Universal threading compatibility and resealability sustain dominance in general chemical storage. German distributors now require torque-verified sealing documentation for hazardous material shipments.
- Spout:Controlled-flow designs serve viscous liquid handling in food-contact and pharmaceutical applications.
- Cap:Standard snap-fit constructions address cost-sensitive water supply and non-hazardous chemical segments.
- Tap:Integrated valve mechanisms enable metered dispensing without container inversion in manufacturing floor environments.
Screw closures command the largest installed base. Tap configurations are climbing the fastest as smart dispensing integration with RFID tracking penetrates pharmaceutical facilities.
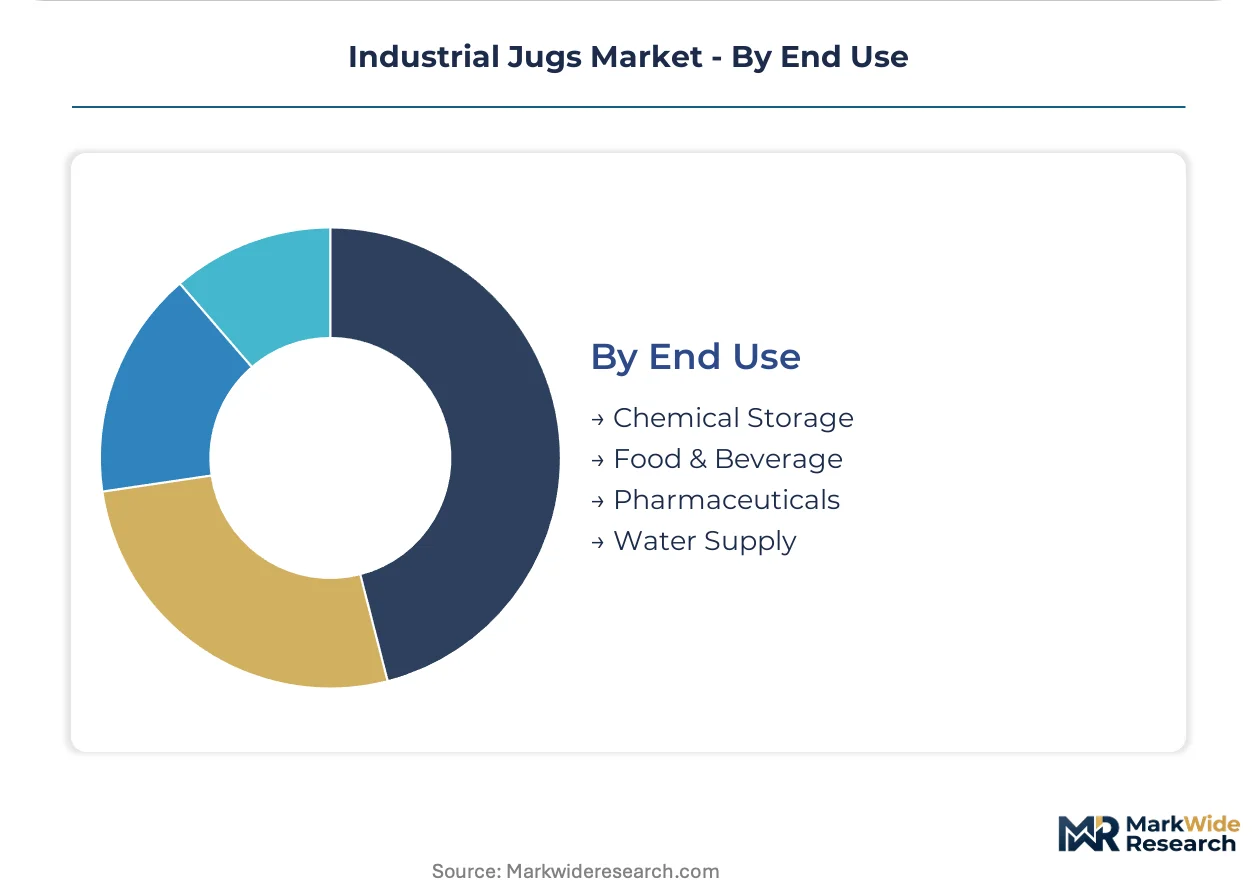
End Use:
Regulatory stringency and contamination risk tolerance stratify end-use segments by material performance requirements.
- Chemical Storage:Corrosive and flammable liquid containment drives demand for UN-certified HDPE and fluoropolymer-lined constructions. EPA standards in the US and REACH in Europe govern material specifications for hazardous substance handling.
- Pharmaceuticals:Extractables testing and FDA validation protocols elevate barrier performance requirements. Swiss and Singaporean API manufacturers are specifying hybrid fluoropolymer-HDPE constructions to eliminate contamination risk.
- Food & Beverage:FDA food-contact rules constrain polymer additive selection, favoring pre-certified resin grades from established suppliers.
- Water Supply:NSF certification and potable water contact approvals define material eligibility for municipal and industrial water handling.
Chemical Storage anchors category volume. Pharmaceuticals is gaining share fastest as high-purity solvent distribution expands in specialty chemical manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, China, and India concentrate procurement for industrial jugs as chemical manufacturing infrastructure scales in each jurisdiction. Regulatory divergence between REACH-mandated Europe and EPA-governed North America shapes distinct material specification requirements across these demand centers.
Germany
Specialty chemical distributors in the Rhine-Ruhr corridor drive demand for UN-certified fluoropolymer-lined containers. ECHA's evolving REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are accelerating converter investment in plasma-treated surface technologies. Testing laboratory capacity constraints in Hamburg and Munich extend certification timelines for new jug formulations.
China
Petrochemical expansion in the Yangtze River Delta and Pearl River Delta sustains bulk intermediate container procurement at scale. MIIT's GB standards for hazardous material packaging align with UN certification requirements for export-oriented chemical manufacturers. Zhejiang and Jiangsu provinces host concentrated blow-molding converter capacity serving both domestic and export markets.
India
Pharmaceutical API manufacturing in Gujarat and Maharashtra generates specialized demand for extractables-tested containment solutions. The CDSCO's tightening validation protocols for pharmaceutical packaging materials elevate barrier performance requirements. Dedicated chemical parks in Dahej and Mundra consolidate formulator demand for localized 5-gallon jug supply.
United States
Gulf Coast petrochemical complex proximity shapes HDPE resin sourcing patterns for jug converters serving chemical storage applications. EPA standards under the Resource Conservation and Recovery Act govern hazardous waste container specifications. Massachusetts-based pharmaceutical contract manufacturing organizations are standardizing 10-gallon formats across their global facility networks.
Switzerland
High-purity solvent distribution for pharmaceutical API manufacturing drives specification of hybrid fluoropolymer-HDPE constructions. Swissmedic's pharmaceutical packaging guidelines exceed baseline EU requirements for extractables testing. Basel's concentrated pharmaceutical manufacturing cluster generates premium-tier demand for contamination-risk-eliminating containment solutions.
Industrial Jugs Market Competitive Landscape
North American producers anchor one tier of supply; European specialists hold certification-intensive segments. The vendor base spans integrated polymer science conglomerates, dedicated blow-molding scale operators, and regional fabrication specialists. Three archetypes dominate: resin-integrated converters with captive material science capabilities, high-volume blow-molding specialists serving chemical-grade specifications, and regional distributors with localized molding assets. Competitive moves concentrate on multi-layer co-extrusion technology licensing and strategic partnerships to access post-consumer HDPE recycling streams.
Within the integrated polymer science tier, Berry Global Group and Amcor Plc exemplify converters leveraging material certification capabilities to sustain REACH-compliant product lines. Graham Packaging Company occupies a position among high-volume blow-molding specialists serving chemical-grade container demand.
| Leading Market Players |
|---|
| United States Plastic Corporation |
| MJS Packaging |
| Berry Global Group |
| Amcor Plc |
| ALPLA |
| Silgan Holdings |
| Graham Packaging Company |
| Plastipak Holdings |
| Greif |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between UN-certified fluoropolymer-lined jugs and commodity HDPE containers manifests in pricing power concentration among German and Swiss converters while supply chains fragment across resin sourcing tiers. REACH-mandated additive packages and ECHA traceability requirements force dual-track procurement strategies that separate premium chemical-grade supply from standard industrial distribution channels.
Pricing Analysis
Volume concentration in 5-gallon and 10-gallon formats compresses margins for commodity HDPE converters serving Indian chemical parks, while fluoropolymer-lined hybrid constructions command sustained premiums from Swiss pharmaceutical API manufacturers. Three-tier pricing structure across premium certification-grade, standard UN-compliant, and economy non-hazardous tiers reflects material composition and testing documentation burdens. Pricing pressure stems from Gulf Coast petrochemical supply volatility transmitting directly to converter cost structures. Contract manufacturing organizations in Massachusetts and Ireland exhibit lowest price sensitivity due to standardized global procurement mandates, while regional Indian formulators face acute cost compression.
Supply Chain Analysis
Closed-loop return flows for refillable stainless steel intermediate bulk containers in pharmaceutical solvent distribution are displacing single-use jug consumption in European closed-loop systems. HDPE resin supply concentrates in US Gulf Coast, German petrochemical complexes, and Middle Eastern feedstock hubs. Converter manufacturing clusters in Zhejiang and Jiangsu provinces draw from these resin streams while serving export markets. Single-source vulnerability persists in fluoropolymer barrier layer formulation expertise concentrated among retiring German polymer chemists. Distribution runs through specialty chemical distributors in the Rhine-Ruhr corridor, direct converter relationships with pharmaceutical CDMOs, and regional fabrication specialists serving localized chemical park demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over REACH-compliant resin additive packages and secure post-consumer HDPE recycling streams determines competitive viability. Players are pursuing backward integration into polymer science capabilities to defend margin positions against certification-intensive European requirements.
For Market Incumbents: Deploy multi-layer co-extrusion technology licensing to mid-tier converters unable to finance capital upgrades independently, capturing revenue from technology transfer while constraining competitor scale. Consolidate procurement relationships with pharmaceutical CDMOs standardizing formats across global facility networks to lock out regional challengers. Steel drum substitution in closed-loop solvent systems and plasma-treated surface technologies eliminating fluorinated additives represent converging substitution threats requiring material science R&D prioritization. For New Entrants and Emerging Players: Direct-to-pharmaceutical-manufacturer digital channels bypassing established specialty chemical distributors offer penetration routes for extractables-tested fluoropolymer-HDPE hybrid constructions. White-space concentrates in India's Dahej and Mundra chemical parks where localized 5-gallon supply lags behind formulator demand growth, and in RFID-enabled smart dispensing integration for pharmaceutical manufacturing facilities. Technical partnership with German testing laboratories can compress UN certification timelines that currently extend product launches. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier converters possessing secure post-consumer HDPE streams given EU Packaging and Packaging Waste Directive recycled content mandates above thirty percent by weight. Long-term viability centers on material certification capabilities rather than blow-molding scale alone, favoring targets with polymer science expertise and multi-site quality systems. Watch ECHA restriction proposals on per- and polyfluoroalkyl substances as inflection indicators that would accelerate plasma-treated surface technology adoption and strand conventional barrier coating assets. Material deviation in REACH substance restriction timelines or Gulf Coast petrochemical supply disruption warrants pause and re-evaluation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Additive Formulation | Captures REACH compliance value that currently concentrates among German resin suppliers. |
| Multi-Site UN Certification Investment | Qualifies converters for pharmaceutical CDMO procurement consolidation across Ireland and Massachusetts networks. |
| Post-Consumer HDPE Recycling Stream Securement | Positions converters ahead of EU Packaging and Packaging Waste Directive recycled content mandates. |
| Plasma-Treated Surface Technology Licensing | Addresses ECHA fluorinated substance restrictions while maintaining chemical resistance performance. |
| RFID-Enabled Smart Dispensing Integration | Penetrates pharmaceutical manufacturing facilities seeking inventory management software compatibility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with plant managers at chemical manufacturing facilities, procurement leads at pharmaceutical CDMOs, distribution channel partners in specialty chemical networks, and technical R&D directors at resin suppliers provided qualitative validation. Bottom-up modeling triangulated against top-down industry association estimates from Cefic and ACC reports, ECHA regulatory databases, and SEC disclosures from listed packaging converters.
Granularity-level modeling operated at material-grade tier, end-use industry segment, packaging format capacity, and regional production hub dimensions across the analysis window. CAGRs derived from regression analysis of historical volume trends adjusted for regulatory inflection points and capacity expansion announcements. Industry-specific forecast inputs included ECHA substance restriction proposal timelines, Indian chemical park development schedules, and pharmaceutical CDMO facility standardization patterns.
The model holds under stable REACH implementation timelines and Gulf Coast petrochemical supply continuity; deviation in ECHA restriction acceleration or resin feedstock disruption would shift volume trajectories. Forecasts incorporate assumptions regarding UN certification laboratory capacity constraints and CDSCO validation protocol evolution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Industrial Bulk Packaging Market
Industrial Packaging
Industrial Filling Machine Market
Industrial Packaging
Transport Racks Market
Industrial Packaging
Middle East and Africa Octabin Market
Industrial Packaging
Insulated Bin Market
Industrial Packaging
Corrugated Octabins Market
Industrial Packaging
Dunnage Racks Market
Industrial Packaging
Bulk Liquid Transport Packaging Market
Industrial Packaging
Industrial Pails Market
Industrial Packaging
Asia-Pacific Warehouse Drums and Barrel Market
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Bulk Packaging Market
Industrial Packaging
Slip Sheets Market
Industrial Packaging
Fiber Drums Market