
 MENA Industrial Packaging Market | 2026-2036
MENA Industrial Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
MENA Industrial Packaging Market Foresight
Market Context with Strategic Players
Saudi Arabia's Eastern Province is tilting the competitive map as Jubail and Ras Al-Khair add chemical processing capacity that demands corrosion-resistant drum and IBC supply. Gulf Packaging Industries leverages its proximity to these clusters to sustain just-in-time delivery contracts with petrochemical majors. Hotpack Global anchors its position through specialized food-grade container lines that serve dairy and edible oil processors across the Gulf. Mauser Packaging Solutions differentiates via reusable steel drum programs that reduce per-trip packaging costs for chemical exporters.
Technical Definition and Structural Segments
MENA industrial packaging encompasses rigid and semi-rigid containment systems engineered to ISO 668 and UN certification standards for the transport, storage, and handling of bulk raw materials, intermediates, and finished goods across manufacturing supply chains. These systems incorporate steel, high-density polyethylene, or laminated corrugated constructions with specified stacking strength, chemical resistance, and tamper-evidence features to prevent contamination, spillage, and product loss during multimodal logistics operations. Drums and containers capture the dominant share of product type revenue, reflecting concentrated petrochemical throughput in Saudi Arabia and the UAE where hazardous material regulations mandate UN-certified packaging. Plastic material demand is outpacing metal in non-hazardous segments, as food and beverage processors adopt lightweight HDPE intermediate bulk containers that reduce freight cost per unit shipped. The chemicals end-use category leads absolute volume, though pharmaceutical-grade packaging commands premium margins as Saudi Arabia's local drug manufacturing capacity expands under Vision 2030 localization targets.
Regulatory Framework and Forward Outlook
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations, UAE's Emirates Authority for Standardization and Metrology (ESMA) packaging mandates, and Gulf Standardization Organization (GSO) harmonized rules for hazardous goods transport collectively shape product certification requirements across the region. These frameworks enforce UN marking, material traceability, and recyclability thresholds that determine market access for both domestic producers and imports from Asia and Europe. Stakeholders must monitor how Egypt's new packaging waste management law and Morocco's industrial ecology programs will extend compliance obligations beyond Gulf markets, reshaping supplier qualification criteria and regional manufacturing location decisions.
Market Dynamics
Petrochemical capacity expansion across the Gulf Cooperation Council is compressing lead times for corrosion-resistant container supply, forcing packaging vendors to co-locate production near Jubail and Ras Al-Khair industrial zones.
Growth Catalysts
- SASO Recyclability Mandates:Saudi Arabia's technical regulations for packaging safety and material traceability are pulling domestic manufacturing investment away from imported containers toward localized drum and IBC production.
- Intermediate Bulk Container Adoption:Food and beverage processors across the Gulf are displacing metal drums with lightweight HDPE IBCs to reduce freight cost per unit shipped in non-hazardous liquid transport.
- Ras Al-Khair Cluster Density:The concentration of chemical processing and export logistics activity in Saudi Arabia's Eastern Province is anchoring demand for UN-certified steel drum supply chains.
Market Restraints
- Steel Price Volatility:Input cost fluctuations for cold-rolled steel are compressing margin stability for drum manufacturers serving price-sensitive construction chemical segments.
- Asian Import Concentration:Supply concentration among Chinese and Indian rigid container exporters exposes MENA distributors to shipping rate spikes and extended certification timelines.
- HDPE Chemical Resistance Limits:Technical constraints on high-density polyethylene performance in solvent-heavy applications prevent full displacement of metal drums in specialty chemical logistics.
Strategic Opportunities
- Egypt Packaging Waste Law:The country's emerging packaging waste management framework will extend compliance obligations beyond Gulf markets, creating first-mover advantage for certified regional producers.
- Reusable Steel Drum Programs:Closed-loop container pooling systems are opening white space in chemical exporter logistics, reducing per-trip packaging costs through deposit-based circulation models.
- Vision 2030 Localization:Saudi Arabia's pharmaceutical manufacturing targets under Vision 2030 are pulling demand for premium-margin pharma-grade containment systems that meet international GMP standards.
Industry Challenges
- UN Certification Talent Gap:Shortage of qualified testing engineers familiar with UN 6A and 6B performance standards is extending product approval timelines for new drum designs.
- Legacy ERP Integration:Container tracking and deposit management systems require capital-intensive integration with petrochemical customer procurement platforms, slowing reusable program rollout.
- Multi-Jurisdiction Compliance:Divergent SASO, ESMA, and GSO certification requirements are fragmenting quality management systems for suppliers serving cross-Gulf contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MENA Industrial Packaging Market |
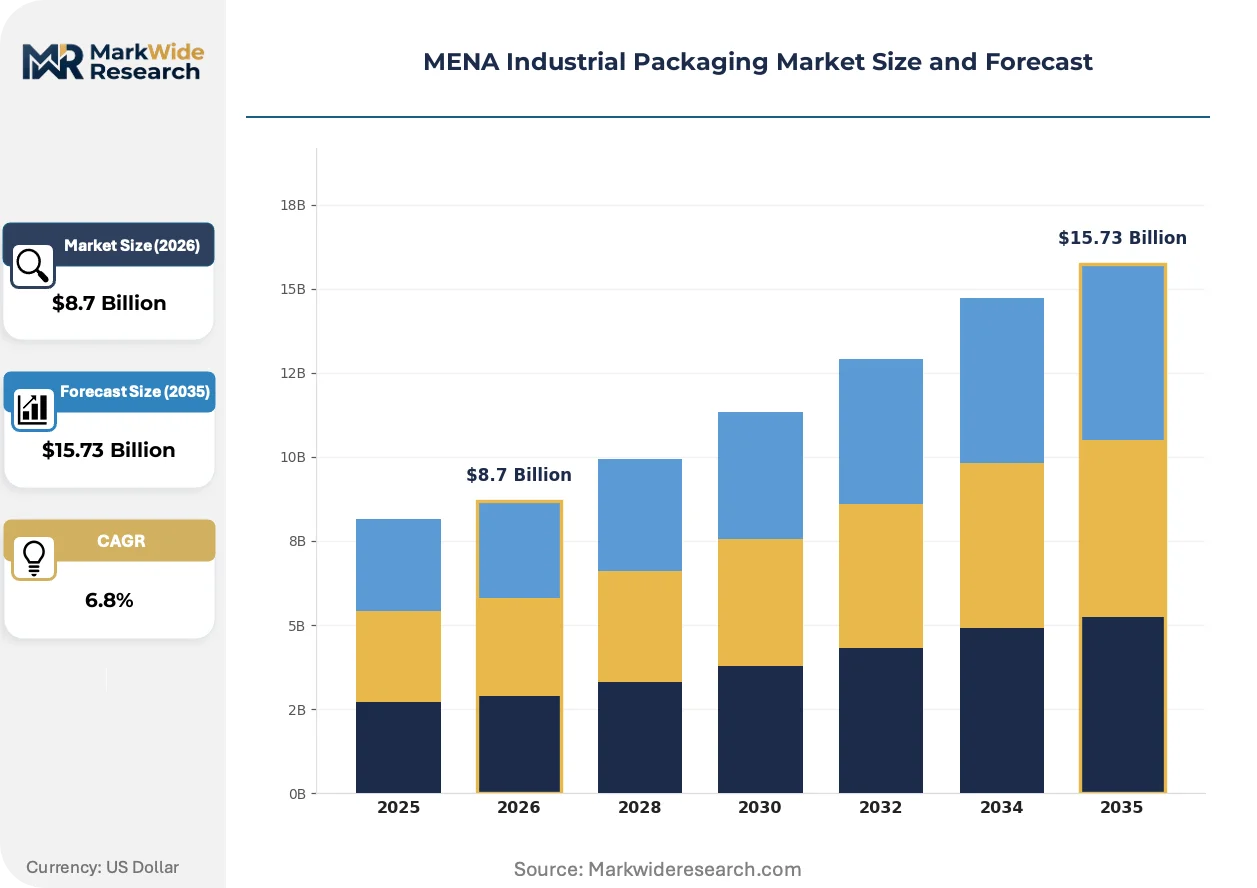
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drums, Containers, Pallets, Bags Material: Plastic, Metal, Wood, Paper End Use: Food & Beverage, Chemicals, Pharmaceuticals, Automotive Distribution Channel: Direct Sales, Wholesalers, Retailers, Online |
| Companies Covered | Gulf Packaging Industries, Hotpack Global, Mauser Packaging Solutions, International Paper Company, Napco National, Middle East Packaging Factory, National Paper Products Company, Smurfit Kappa Group, Arabian Packaging, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MENA Industrial Packaging Market Shifts & Advancements
Container intelligence systems and material science advances are compressing the gap between passive containment and active supply chain visibility, reshaping how industrial buyers evaluate packaging procurement.
RFID-enabled drum and IBC tracking is digitizing asset location and condition monitoring across multimodal chemical logistics. Petrochemical exporters in Jubail Industrial City are piloting sensor-embedded steel drums to monitor temperature and pressure during vessel transit. The technology is digitizing compliance documentation, replacing manual UN inspection records with automated chain-of-custody verification.
Gulf Standardization Organization harmonized rules for hazardous goods transport are tightening material traceability requirements across Saudi Arabia, UAE, and Kuwait. The framework mandates batch-level tracking for steel and plastic containers used in chemical export, forcing manufacturers to retool quality systems. Drum producers serving Aramco supply chains are most affected, accelerating investment in laser-etched serialization equipment.
Buyer consolidation among integrated petrochemical majors is compressing vendor lists and extending contract durations for approved packaging suppliers. Long-term framework agreements with Saudi Basic Industries Corporation and Abu Dhabi National Oil Company are displacing spot purchasing in drum and IBC procurement. The shift is most visible in Saudi Arabia's Eastern Province, where three buyers now account for the majority of hazardous container volume.
MENA Industrial Packaging Market Segmentation
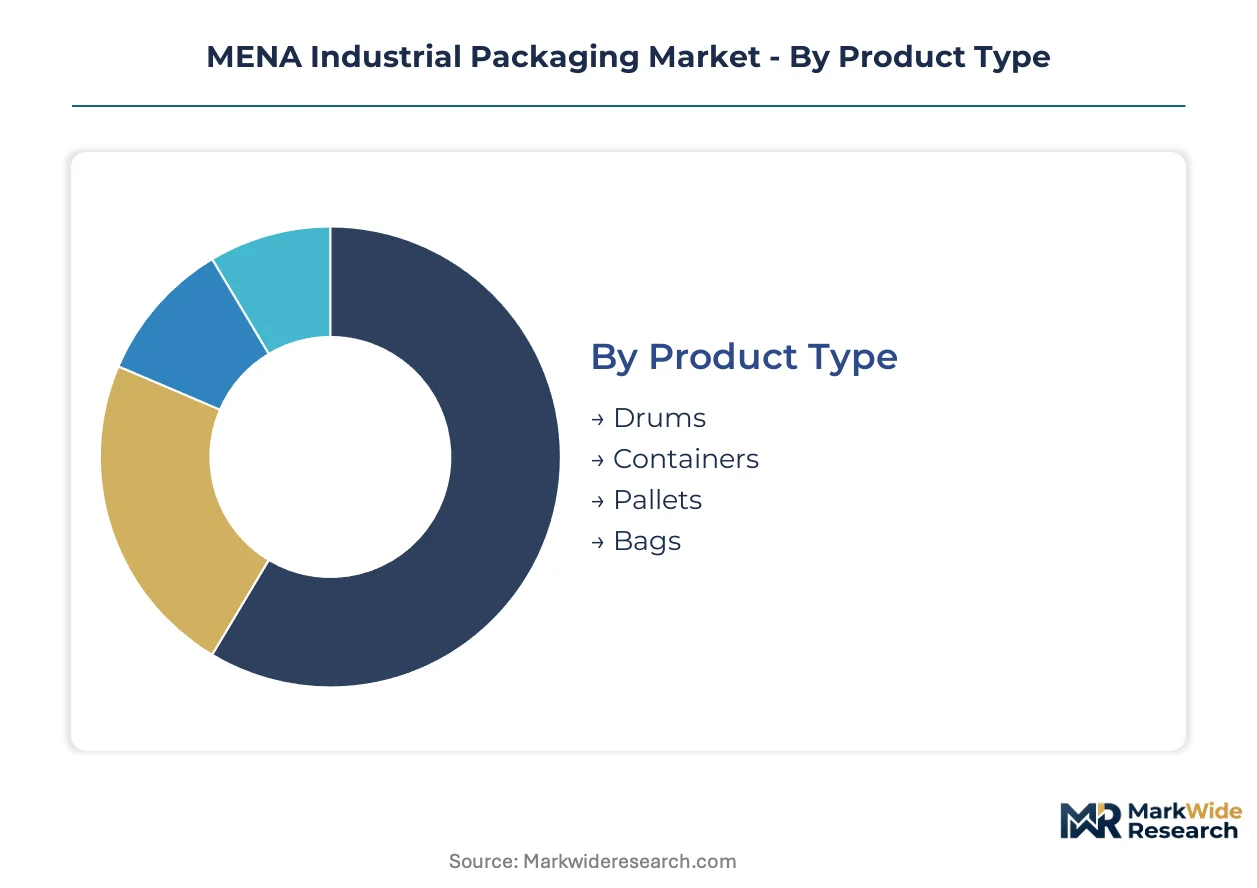
Segmentation in MENA industrial packaging reveals how petrochemical logistics, food safety mandates, and pharmaceutical localization are fragmenting demand across incompatible technical specifications. Buyers in Saudi Arabia's Eastern Province and the UAE's Jebel Ali corridor operate under divergent certification requirements that reshape supplier qualification criteria.
Product Type:
Cost tier differentiation separates commodity container procurement from engineered containment systems with UN certification.
- Drums:Steel and HDPE constructions engineered to UN 6A and 6B performance standards for hazardous liquid transport. Demand clusters in Jubail Industrial City where SABIC and Aramco affiliates require corrosion-resistant steel drum supply with just-in-time delivery contracts.
- Containers:Intermediate bulk containers ranging from 275-gallon caged totes to foldable bulk boxes for dry solids. Food processors across the Gulf are displacing metal with lightweight HDPE IBCs to reduce freight cost per unit in non-hazardous liquid logistics.
- Pallets:Wooden block pallets and plastic slip sheets for unitized load handling in automated warehouse environments. Pharmaceutical distributors in Riyadh and Jeddah specify hygienic plastic pallet pools to prevent contamination in GMP-compliant facilities.
- Bags:Multi-wall paper and woven polypropylene sacks for dry bulk powders and granules. Cement and construction chemical producers in the UAE favor laminated PP bags with moisture barriers for humid port conditions.
Drums command the established base. The steepest expansion runs through containers.
Material:
Application chemistry dictates material selection, with solvent resistance and recyclability thresholds filtering supplier options.
- Plastic:High-density polyethylene and polypropylene formulations with specified melt flow indices for blow-molded drum production. HDPE demand is outpacing metal in food-grade applications where SASO recyclability mandates favor polymer recovery streams.
- Metal:Cold-rolled steel with epoxy-phenolic interior coatings for corrosive chemical containment. Ras Al-Khair petrochemical exporters specify steel drums for solvent-heavy intermediates where HDPE chemical resistance limits prevent polymer substitution.
- Wood:Heat-treated timber pallets compliant with ISPM-15 phytosanitary standards for international shipment. Egyptian agricultural exporters rely on wooden crate construction for fresh produce air freight to European markets.
- Paper:Kraft multi-wall constructions with polyethylene moisture barriers for dry bulk packaging. Moroccan phosphate and fertilizer processors source regional paper bag supply to reduce import dependency.
Metal holds the dominant revenue share. Plastic is climbing the fastest on food safety and recyclability alignment.
End Use:
Customer type maturity separates price-sensitive commodity buyers from premium-margin regulated segments.
- Chemicals:UN-certified containment for hazardous raw materials, intermediates, and finished petrochemical products. Saudi Arabia's Eastern Province anchors absolute volume with Jubail and Ras Al-Khir clusters driving drum and IBC procurement.
- Food & Beverage:Food-grade HDPE IBCs and aseptic bag-in-box systems for edible oils, dairy, and juice concentrates. Hotpack Global and regional dairy processors in Almarai's supply chain specify EU-compliant food contact materials.
- Pharmaceuticals:GMP-compliant containment with batch-level traceability for active pharmaceutical ingredients and finished drug products. Vision 2030 localization targets are pulling demand for premium-grade packaging as Saudi drug manufacturing capacity expands.
- Automotive:Returnable totes and corrosion-inhibiting VCI films for component logistics. Assembly plants in Morocco's Tangier Automotive City require specialized dunnage for just-in-sequence parts delivery.
Chemicals generates the volume base. Pharmaceuticals offers the steepest margin expansion trajectory.
Distribution Channel:
Supply concentration shapes channel economics, with direct relationships dominating large-volume hazardous material procurement.
- Direct Sales:Long-term framework agreements between drum manufacturers and integrated petrochemical majors. Aramco and ADNOC procurement platforms are displacing spot purchasing with approved vendor lists extending contract durations.
- Wholesalers:Regional distributors stocking standard drum and container sizes for construction chemical and lubricant blenders. Wholesalers in Jebel Ali Free Zone serve re-export markets across East Africa and Central Asia.
- Retailers:Hardware and industrial supply chains for small-volume packaging in maintenance and repair operations. Retail penetration remains limited to non-hazardous segments with lower certification barriers.
- Online:B2B platforms for standardized pallet and bag procurement with transparent pricing. Digital channels are gaining traction in wood and paper segments where specification standardization reduces pre-sale engineering.
Direct sales captures the contract value. Online is expanding most quickly in commoditized segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SASO technical regulations anchor Saudi Arabia's dominant position in MENA industrial packaging demand. The kingdom's Eastern Province concentrates petrochemical throughput that drives UN-certified container procurement across the Gulf.
Saudi Arabia
Jubail Industrial City and Ras Al-Khair anchor the densest chemical processing cluster in the region. SASO mandates for packaging safety and recyclability tighten compliance requirements for both imported and locally manufactured industrial containers. Eastern Province petrochemical exporters specify corrosion-resistant steel drums and HDPE intermediate bulk containers for hazardous material logistics.
United Arab Emirates
ESMA packaging mandates govern container certification for chemical exporters operating through Jebel Ali Free Zone. Dubai and Abu Dhabi serve as re-export hubs for drum and IBC supply chains reaching East Africa and Central Asia. Jebel Ali's logistics concentration supports wholesaler networks stocking standard container sizes for construction chemical blenders.
Egypt
Emerging packaging waste management legislation will extend compliance obligations beyond Gulf markets for regional producers. Cairo and Alexandria anchor demand for wooden crate construction serving agricultural air freight to European markets. The country's phosphate and fertilizer processors source regional paper bag supply to reduce import dependency.
Morocco
Industrial ecology programs reshape supplier qualification criteria for packaging serving Tangier Automotive City assembly plants. The country's national pharmaceutical regulator aligns with international GMP standards as local drug manufacturing capacity expands. Casablanca-Rabat corridor demand concentrates in returnable totes and corrosion-inhibiting films for just-in-sequence parts delivery.
Kuwait
Gulf Standardization Organization harmonized rules for hazardous goods transport enforce material traceability requirements across Kuwaiti chemical export operations. Shuaiba Industrial Area petrochemical facilities require UN-certified steel drum supply chains with specified stacking strength. The emirate's construction chemical segment drives demand for moisture-barrier laminated bags in humid port conditions.
MENA Industrial Packaging Market Competitive Landscape
Regional specialists and multinational packaging groups split the market between localized production and imported supply chains. Saudi Arabia's Eastern Province concentration favors vendors with proximity to Jubail and Ras Al-Khair industrial zones. Three archetypes dominate: GCC-based drum manufacturers with just-in-time delivery contracts, European multinationals with reusable container programs, and Asian exporters serving price-sensitive commodity segments. Capacity co-location near petrochemical clusters and certification harmonization across SASO-ESMA-GSO frameworks represent the dominant competitive moves.
Within the regional specialist tier, Gulf Packaging Industries and Napco National exemplify proximity-based supply strategies anchored to Eastern Province demand. Among multinational operators, Mauser Packaging Solutions occupies a position emphasizing reusable steel drum circulation models. Hotpack Global sits within the food-grade specialization vector serving dairy and edible oil processors across Gulf markets. These three named entities represent distinct strategic postures without exhausting the competitive field.
| Leading Market Players |
|---|
| Gulf Packaging Industries |
| Hotpack Global |
| Mauser Packaging Solutions |
| International Paper Company |
| Napco National |
| Middle East Packaging Factory |
| National Paper Products Company |
| Smurfit Kappa Group |
| Arabian Packaging |
| Others |
Supply & Pricing Matrix
Chinese cold-rolled steel and Indian HDPE resin exporters anchor upstream supply, concentrating margin capture among drum manufacturers with backward integration into polymer compounding or steel coating operations. SASO certification tiers fragment buyer willingness-to-pay, with petrochemical majors absorbing premium pricing for UN-certified containers while construction chemical blenders squeeze commodity drum suppliers.
Pricing Analysis
Saudi Arabia commands a 15-20% price premium over Egyptian and Moroccan markets for identical UN-certified steel drum specifications. Three-tier pricing structure across premium, standard, and economy levels separates Aramco-approved vendors with full traceability from regional wholesalers stocking unbranded imports. Pricing pressure stems from Asian import concentration in non-hazardous segments, with Chinese HDPE drum exporters undercutting Gulf manufacturers on freight-normalized landed cost. Construction chemical blenders exhibit highest price sensitivity, while pharmaceutical-grade packaging buyers prioritize GMP compliance over unit economics.
Supply Chain Analysis
Gulf Standardization Organization harmonized rules for hazardous goods transport enforce material traceability requirements that restrict unverified Asian drum imports from petrochemical supply chains. Manufacturing concentrates in Saudi Arabia's Eastern Province, China's Zhejiang corridor, and India's Gujarat chemical belt. Raw material dependencies center on cold-rolled steel from Chinese state-owned mills, HDPE resin from SABIC and Borouge, and epoxy-phenolic coatings from European specialty chemical suppliers. Single-source vulnerability runs through Shanghai-Ningbo port congestion affecting steel drum component lead times. Distribution runs through direct sales frameworks with Jubail petrochemical majors, supplemented by Jebel Ali wholesaler networks serving East African re-export markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across incompatible certification regimes creates niche opportunities for specialized container producers. Vision 2030 pharmaceutical localization and Egypt's emerging waste management framework are pulling demand in divergent technical directions that favor focused players over generalists.
For Market Incumbents: Harden SASO-ESMA-GSO certification harmonization efforts to reduce quality system duplication costs across cross-Gulf contracts. Deepen backward integration into HDPE compounding or steel coil coating to insulate margin pools from Chinese raw material price volatility. Defensive capacity addition in Ras Al-Khair industrial zone protects just-in-time delivery positioning against emerging Egyptian competitors. For New Entrants and Emerging Players: Egypt's underpenetrated pharmaceutical packaging segment offers lowest competitive density among MENA growth corridors. Target GMP-compliant containment systems for Cairo-Alexandria drug manufacturing clusters where local supply remains import-dependent. Wholesaler partnerships with Jebel Ali distributors provide fastest route to East African re-export markets without direct Aramco vendor list qualification. For Investors and Strategic Acquirers: Capital is best deployed toward regional drum manufacturers with captive UN certification capabilities and established petrochemical customer relationships. Long-term viability hinges on positioning for reusable container pooling models that reduce per-trip packaging costs through deposit-based circulation. Watch for Egyptian packaging waste law implementation timelines as inflection indicator for compliance-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into HDPE Compounding | SABIC polymer supply agreements reduce raw material cost volatility for Eastern Province drum producers. |
| Reusable Steel Drum Program Launch | Closed-loop pooling systems cut per-trip packaging costs for Jubail petrochemical exporters. |
| GMP Certification Investment | SFDA alignment opens premium-margin pharmaceutical containment demand under Vision 2030 targets. |
| Laser-Etched Serialization Deployment | Batch-level traceability satisfies Gulf Standardization Organization material tracking mandates for Aramco supply chains. |
| Jebel Ali Distribution Partnership | Free zone logistics concentration enables East African re-export without direct Gulf petrochemical vendor qualification. |
Research Methodology
A spread of perspectives from petrochemical procurement directors, drum manufacturing plant managers, SASO certification engineers, and Jebel Ali wholesale distributors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with downstream buyers and upstream container producers, validated against customs trade data, Gulf Petrochemicals and Chemicals Association reports, SEC filings from multinational packaging groups, and SASO technical regulation documentation. Bottom-up volume estimates from individual plant capacities and top-down demand models from petrochemical throughput statistics were triangulated to constrain forecast ranges.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by product type, material chemistry, end-use industry, and distribution channel. Pharmaceutical-grade, food-grade, and hazardous chemical containment tiers were separately projected given divergent certification requirements and margin structures. CAGRs were derived from capacity expansion announcements, localization policy targets, and substitution elasticities between metal and polymer containers. Forecast inputs incorporated SABIC and Borouge resin supply outlooks, Jubail Industrial City master plan throughput projections, and Egyptian pharmaceutical manufacturing capacity buildout schedules.
Practitioners should monitor SASO recyclability mandate enforcement intensity and Egyptian packaging waste law finalization for early signals of regulatory-driven demand shifts. Forecasts reflect assumptions regarding Gulf petrochemical capacity expansion continuity and Asian import tariff stability. Material shifts in GSO-ESMA certification harmonization timelines or HDPE chemical resistance breakthroughs would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Industrial Jugs Market
Industrial Packaging
Insulated Bin Market
Industrial Packaging
Cone Bottom Tank Market
Industrial Packaging
Dunnage Racks Market
Industrial Packaging
Global Dunnage Packaging Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Asia-Pacific Warehouse Drums and Barrel Market
Industrial Packaging
Indonesia Industrial Packaging Market
Industrial Packaging
Dunnage Air Bags Market
Industrial Packaging
Dunnage Trays Market
Industrial Packaging
Fiber Drums Market
Industrial Packaging
Bulk Packaging Market
Industrial Packaging
Industrial Bulk Packaging Market
Industrial Packaging
Industrial Packaging Market
Industrial Packaging
Industrial Pails Market
Industrial Packaging
Corrugated Automotive Packaging Market