
 Indonesia Industrial Packaging Market | 2026-2036
Indonesia Industrial Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Industrial Packaging Market Insights
Maintenance contracts for reusable intermediate bulk container fleets is shifting how packaging value gets captured in Indonesian chemical and agricultural supply chains. Greif Inc. leverages its global refurbishment network to sustain recurring revenue from palm oil exporters operating across Sumatra and Kalimantan. Mauser Packaging Solutions Holding Company anchors its position through captive washing and reconditioning facilities near Surabaya's port complex. SCHÜTZ GmbH & Co. KGaA differentiates via specialized barrier coatings for corrosive chemical transport in humid tropical conditions.
Indonesia industrial packaging encompasses engineered containment systems designed to protect bulk commodities through multimodal logistics, typically constructed from high-density polyethylene, corrugated fiberboard, or cold-rolled steel with specified load-bearing ratings and UN certification for hazardous materials. Flexible packaging dominates volume in food and beverage applications where lightweight moisture barriers reduce shipping costs for instant noodle and snack producers. Rigid containers command premium margins in chemicals and pharmaceuticals due to stringent UN and Ministry of Health leak-test requirements. Corrugated boxes occupy the largest installed base across electronics assembly clusters in Batam and Jakarta, though margin compression from recycled pulp cost volatility pressures converters.
Indonesia's Ministry of Industry enforces SNI national standards on packaging recyclability, while the Ministry of Environment mandates extended producer responsibility frameworks that reshape material selection across plastic-intensive segments. The country's national pharmaceutical regulator requires child-resistant and tamper-evident closures for drug distribution, elevating specification barriers for local converters. Stakeholders must monitor how BIS-equivalent certification timelines and provincial waste management ordinances interact to determine which material platforms—paper, plastic, or metal—gain preferential access to Java's densest manufacturing corridors.
Market Dynamics
Indonesia's Ministry of Industry mandates on recycled content are compressing virgin resin demand while expanding reconditioning infrastructure across Java's manufacturing corridor. This regulatory pressure intersects with palm oil export growth to reshape how packaging value gets captured in chemical and agricultural supply chains.
Growth Catalysts
- Export-Oriented Food Processing:Indonesian palm oil and coconut product exporters are scaling intermediate bulk container fleets to meet international shipping standards. This drives demand for UN-certified HDPE and steel containment systems with barrier coatings.
- SNI National Standards:The Ministry of Industry's recyclability mandates are accelerating material substitution toward post-consumer recycled content. Converters investing in SNI-compliant lines gain preferential access to Jakarta and Surabaya industrial zones.
- Humid Climate Engineering:Specialized corrosion-resistant coatings for tropical chemical transport are expanding addressable market in agrochemical and pharmaceutical distribution. This technical specification tier creates margin separation from commodity packaging.
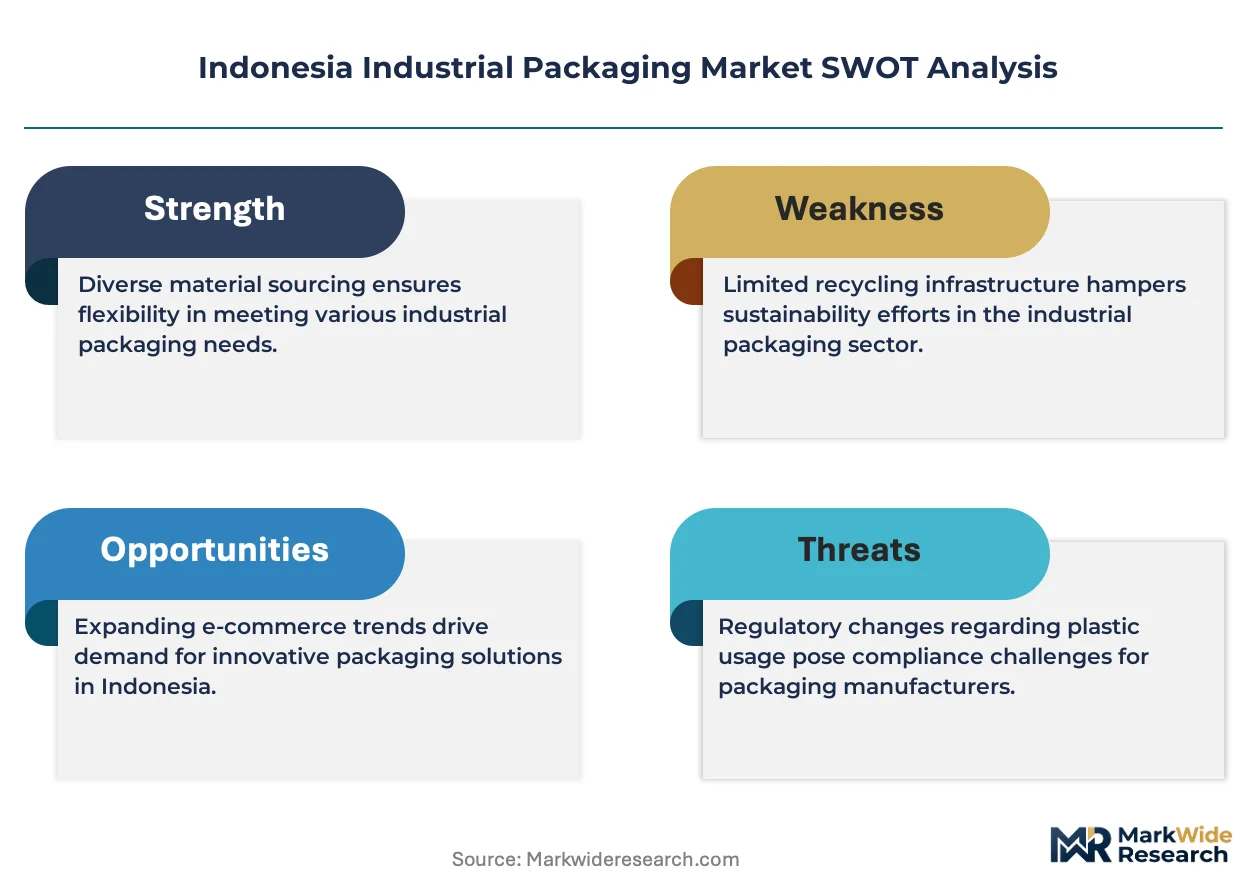
Market Restraints
- Recycled Pulp Volatility:Corrugated converters serving Batam electronics clusters face margin compression from fluctuating recovered fiber costs. This input instability pressures box producers to absorb price swings or lose volume to plastic alternatives.
- Java-Centric Supply Concentration:Manufacturing gravity concentrates in Surabaya and Jakarta corridors, leaving Sumatra and Kalimantan with higher logistics costs and longer replenishment cycles. Geographic imbalance limits national market penetration.
- Extended Producer Responsibility Friction:The Ministry of Environment's EPR frameworks impose compliance costs on plastic-intensive segments before adequate collection infrastructure exists. This regulatory-material mismatch slows adoption in outer island provinces.
Strategic Opportunities
- Kalimantan Industrial Expansion:Mining and smelter investments in East Kalimantan are creating demand for bulk chemical packaging with shorter supply lines than Java-based converters currently serve. Local washing and reconditioning facilities could capture this white space.
- Barrier Coating Convergence:Multilayer flexible films combining moisture protection with oxygen scavenging are penetrating instant noodle and snack export segments. This technology-material convergence opens premium positioning beyond commodity polyethylene.
- Maintenance Contract Penetration:Fleet management services for reusable IBCs remain underdeveloped outside palm oil corridors. Chemical distributors in Surabaya's port complex represent untapped demand for turnkey container pooling.
Industry Challenges
- UN Certification Bottlenecks:Hazardous material testing capacity concentrates in Jakarta, creating 12-16 week approval timelines for Kalimantan and Sulawesi converters. This geographic certification asymmetry delays product launches.
- Legacy Equipment Integration:Mid-tier corrugated plants retrofitting for SNI compliance face downtime costs and skilled technician scarcity. Workforce gaps in automated line maintenance slow modernization programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Industrial Packaging Market |
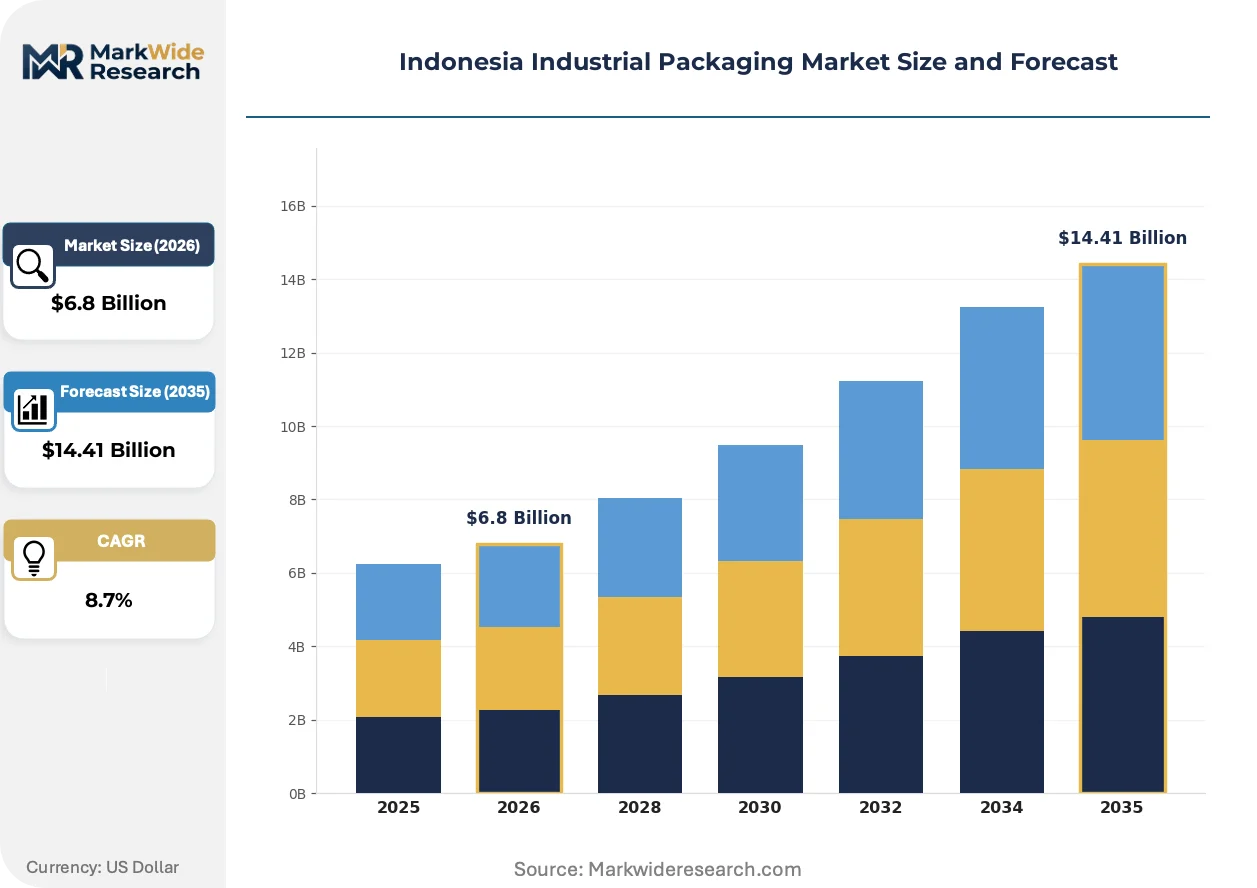
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Containers, Corrugated Boxes, Blister Packs Material: Plastic, Paper, Metal, Glass End User: Food & Beverage, Pharmaceuticals, Chemicals, Electronics Packaging Type: Sealed Pouches, Bottles, Cartons, Tubs |
| Companies Covered | Greif Inc., Mauser Packaging Solutions Holding Company, SCHÜTZ GmbH & Co. KGaA, Time Technoplast Ltd., PTT Global Chemical Public Company Limited, PT Kadujaya, PT Novo Complast Indonesia, PT Plastpack Indonesia, PT Mitra Indo Plast, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Industrial Packaging Market Trends and Innovations
Material science advances and regulatory tightening are converging to redefine performance specifications across Indonesia's industrial packaging value chain. Three developments are actively reshaping competitive positioning and investment priorities.
Multilayer coextruded barrier films are absorbing moisture-sensitive food export volumes previously handled by rigid containers. Instant noodle producers in West Java are adopting these structures at scale to reduce shipping weight and cube utilization. This technology is absorbing margin from traditional steel drum and IBC segments in non-hazardous applications.
Indonesia's Ministry of Industry is tightening SNI-equivalent standards alignment with BIS certification timelines for imported packaging machinery. This regulatory convergence is forcing converters to pre-qualify equipment suppliers against dual compliance frameworks. Pharmaceutical and chemical segments are responding by consolidating supplier relationships with vendors holding concurrent SNI and ISO 9001 accreditation.
Maintenance-based contracting is displacing transactional container sales in palm oil and chemical corridors. Exporters operating across Sumatra are unbundling capital expenditure from operational packaging costs through fleet leasing arrangements. This procurement evolution concentrates most visibly in Surabaya's port-adjacent industrial zones where logistics providers bundle washing, tracking, and replacement services.
Indonesia Industrial Packaging Market Segmentation
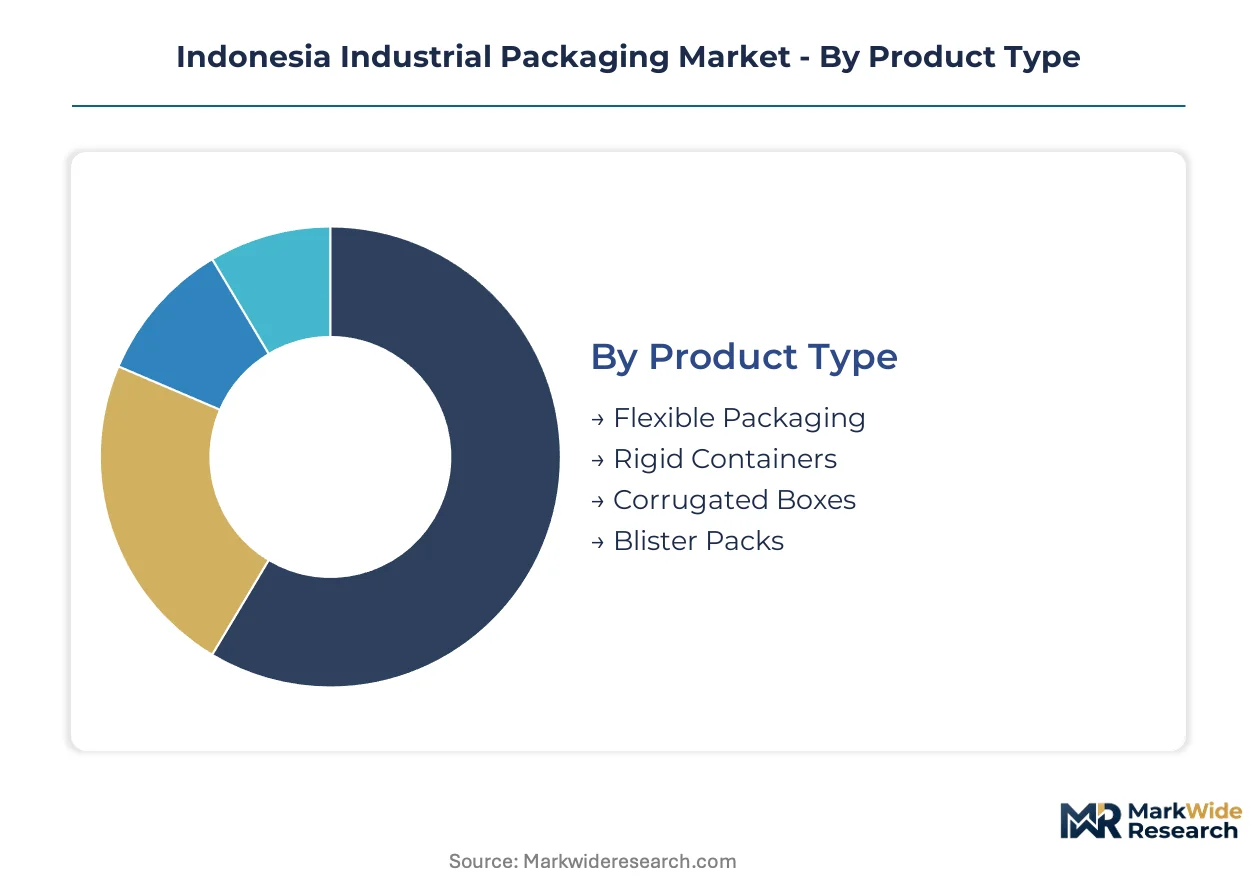
Indonesia's industrial packaging landscape fragments across material platforms and end-use specifications that determine compliance burdens and margin capture. Understanding these divides reveals where SNI mandates and tropical climate engineering create competitive separation.
Product Type:
Flexible packaging operates as standalone lightweight systems for moisture-sensitive exports, while rigid containers embed into multimodal logistics chains requiring UN certification.
- Flexible Packaging:Multilayer coextruded films combine polyethylene barriers with oxygen scavenging for instant noodle producers in West Java. Demand concentrates in food export corridors where weight reduction offsets ocean freight costs, though SNI recyclability mandates are forcing material redesign toward mono-polymer structures.
- Rigid Containers:HDPE and steel intermediate bulk containers with specialized corrosion-resistant coatings serve palm oil exporters across Sumatra and Kalimantan. Surabaya's port-adjacent industrial zones drive fleet leasing adoption, compressing capital expenditure into operational contracts.
- Corrugated Boxes:Recycled fiberboard dominates electronics assembly clusters in Batam and Jakarta, facing margin pressure from pulp cost volatility.
- Blister Packs:Thermoformed PVC and aluminum laminates serve pharmaceutical distribution with child-resistant closure integration required by the national pharmaceutical regulator.
Corrugated boxes lead volumes today; flexible packaging is gaining share fastest.
Material:
Cost tiers separate virgin resin from recycled feedstock, with regulatory preference reshaping procurement across Java's manufacturing corridor.
- Plastic:High-density polyethylene and polypropylene formulations dominate chemical containment, with post-consumer recycled content mandates from the Ministry of Industry accelerating reconditioning infrastructure investment.
- Paper:Recycled pulp-based corrugated board serves electronics and consumer goods, though price volatility pressures converters to absorb swings or lose share to plastic alternatives.
- Metal:Cold-rolled steel drums and IBC cages command premium margins in hazardous chemical transport, with UN certification requirements limiting supplier pools.
- Glass:Borosilicate and soda-lime containers retain niche pharmaceutical and premium food applications where inertness outweighs fragility and weight penalties.
Plastic leads volumes today; paper faces the steepest margin compression.
End User:
Application severity determines specification intensity, from food-grade moisture barriers to pharmaceutical leak-test protocols.
- Food & Beverage:Palm oil and coconut product exporters in Sumatra and Kalimantan drive intermediate bulk container fleet expansion, with international shipping standards dictating UN-certified containment systems.
- Pharmaceuticals:The national pharmaceutical regulator mandates child-resistant and tamper-evident closures, elevating specification barriers and consolidating supplier relationships toward SNI-ISO dual-accredited converters.
- Chemicals:Agrochemical distributors in Surabaya's port complex demand corrosion-resistant coatings for humid tropical transport, creating margin separation from commodity packaging.
- Electronics:Batam and Jakarta assembly clusters consume corrugated volume for component protection, with ESD-grade specifications in semiconductor subsegments.
Food & Beverage leads volumes today; Pharmaceuticals is climbing the fastest.
Packaging Type:
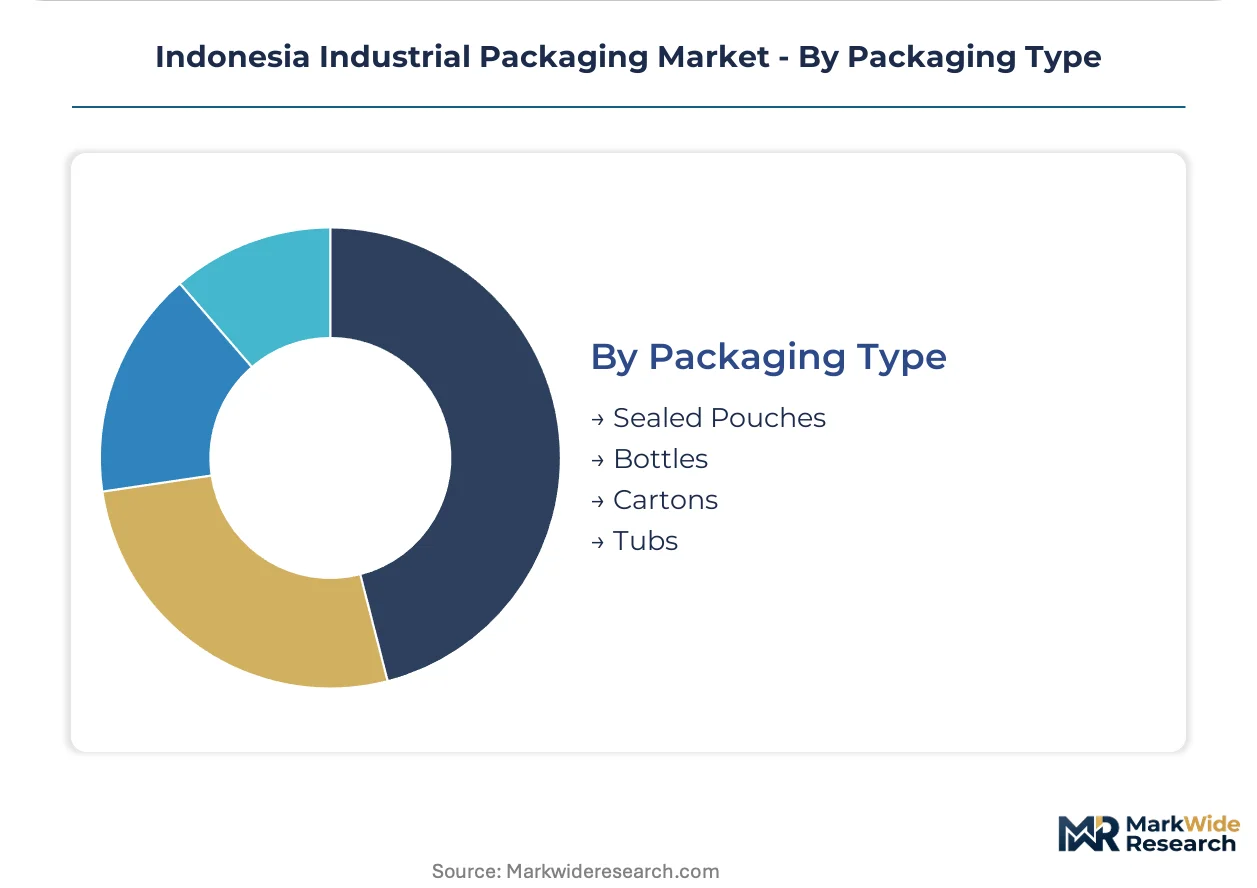
Volume scale separates high-velocity pouch formats from durable reusable systems, with replenishment cycles dictating logistics economics.
- Sealed Pouches:Multilayer flexible structures with resealable zippers penetrate snack export segments, absorbing volumes from rigid alternatives where barrier performance permits.
- Bottles:HDPE and PET containment serves chemical and pharmaceutical liquids, with blow-molding capacity concentrating in Java's manufacturing corridor.
- Cartons:Folding cartonboard for consumer goods faces substitution pressure from flexible films in weight-sensitive applications.
- Tubs:Injection-molded PP containers retain food service and industrial lubricant applications where stack strength matters.
Bottles lead volumes today; sealed pouches are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Java's dense certification infrastructure and outer islands' compliance cost gaps is redirecting packaging investment toward sub-regions with lighter SNI enforcement timelines. Production migrates where Ministry of Industry mandates intersect with port access and raw material proximity.
Java
Surabaya's port-adjacent industrial zones anchor fleet leasing adoption for palm oil exporters, while Jakarta's manufacturing corridor concentrates UN-certified HDPE blow-molding capacity. The Ministry of Industry's SNI recyclability mandates bite hardest here, accelerating converter consolidation toward dual-accredited suppliers. Batam electronics clusters absorb corrugated volume despite recycled pulp volatility pressuring margins.
Sumatra
Palm oil export growth across Riau and North Sumatra drives intermediate bulk container fleet expansion, with international shipping standards dictating barrier-coated containment systems. The national pharmaceutical regulator's child-resistant closure requirements reach this island through distributor networks rather than local production. Medan's industrial zones remain underserved by reconditioning infrastructure compared to Java.
Kalimantan
Mining and smelter investments in East Kalimantan create demand for bulk chemical packaging with shorter supply lines than Java-based converters currently serve. Extended producer responsibility frameworks from the Ministry of Environment impose compliance costs before adequate collection infrastructure exists. Local washing and reconditioning facilities represent white space opportunity.
Sulawesi
Nickel processing corridors in Southeast Sulawesi generate corrosive chemical transport demand suited to specialized barrier coatings. UN certification testing capacity concentrates in Jakarta, creating approval timeline delays for local converters. Makassar's port functions as logistics hub without matching packaging production depth.
Bali and Eastern Islands
Tourism-driven food service packaging absorbs flexible film volumes, though scale constraints limit converter investment. Provincial waste management ordinances vary in alignment with national EPR frameworks, creating compliance fragmentation. Denpasar's distribution networks pull product from Java rather than cultivating local supply.
Indonesia Industrial Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with rigid container markets consolidating around global refurbishment networks while flexible packaging remains fragmented among regional converters. Three archetypes dominate: global fleet managers with captive service infrastructure, SNI-accredited local specialists serving pharmaceutical compliance tiers, and undifferentiated corrugated producers absorbing pulp cost volatility. M&A activity concentrates on reconditioning facility acquisition, while portfolio diversification drives investment into multilayer barrier film capacity.
Among global fleet managers, Greif Inc. and Mauser Packaging Solutions Holding Company exemplify the maintenance-contract archetype, with their refurbishment networks anchoring recurring revenue capture in chemical and agricultural supply chains. SCHÜTZ GmbH & Co. KGaA occupies a position within the barrier-coating specialization tier, representing engineering-intensive positioning for humid tropical applications. These three entities sit alongside Indonesian converters such as PT Kadujaya and PT Plastpack Indonesia, which exemplify the SNI-compliance-focused local specialist archetype serving Ministry of Health mandates.
| Leading Market Players |
|---|
| Greif Inc. |
| Mauser Packaging Solutions Holding Company |
| SCHÜTZ GmbH & Co. KGaA |
| Time Technoplast Ltd. |
| PTT Global Chemical Public Company Limited |
| PT Kadujaya |
| PT Novo Complast Indonesia |
| PT Plastpack Indonesia |
| PT Mitra Indo Plast |
| Others |
Pricing and Supply Chain Analysis
Captive washing and reconditioning infrastructure anchors both supply position and pricing power for fleet managers serving palm oil exporters across Sumatra and Kalimantan. This vertical integration into service-layer assets compresses competitor margins while locking in recurring revenue streams through maintenance contracts.
Pricing Analysis
Distributor margins for UN-certified HDPE intermediate bulk containers widen where SNI-accredited converters hold regional exclusivity in Surabaya's port complex. Three-tier pricing structure across premium barrier-coated, standard corrosion-resistant, and economy non-certified tiers separates chemical distributors from commodity food exporters. Cost compression in corrugated segments is intensifying because recycled pulp volatility pressures Batam electronics cluster suppliers. Palm oil exporters demonstrate lowest price sensitivity due to international shipping compliance mandates, while instant noodle producers absorb flexible film premiums for moisture barrier performance.
Supply Chain Analysis
Dual-sourcing requirements from agrochemical distributors in Java's manufacturing corridor mandate multi-supplier qualification for HDPE resin and cold-rolled steel cage components. Geographic supply concentration draws from Saudi Arabia for virgin polyethylene feedstock, China for specialty barrier coating chemicals, and domestic Java-based reconditioning capacity. Single-source vulnerability concentrates in UN certification testing infrastructure anchored exclusively in Jakarta. Distribution runs through port-adjacent logistics providers bundling container pooling, washing, and replacement services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's industrial packaging market functions as a regulatory compounder where Ministry of Industry SNI recyclability mandates are accelerating material substitution and converter consolidation. The Ministry of Environment's extended producer responsibility frameworks impose compliance costs that reshape competitive positioning across plastic-intensive segments.
For Market Incumbents: Cement fleet leasing penetration in Surabaya's chemical corridors through captive washing facility expansion before regional competitors replicate Mauser's port-adjacent infrastructure model. Acquire SNI-ISO dual-accredited local specialists in pharmaceutical blister pack segments to defend against Greif's global refurbishment network expansion. Barrier coating R&D investment represents the critical lever for humid tropical performance differentiation.
For New Entrants and Emerging Players: The price-point gap between premium barrier-coated IBCs and economy non-certified alternatives opens white-space targeting for mid-tier chemical distributors in East Kalimantan mining corridors. Kalimantan-based reconditioning facilities remain underserved compared to Java's saturated infrastructure. Target Sulawesi nickel processing clusters with corrosion-resistant coating specialization as the go-to-market angle, bypassing Jakarta certification bottlenecks through technical partnership arrangements.
For Investors and Strategic Acquirers: Roll-up economics work for SNI-accredited corrugated converters because Ministry of Industry mandates are forcing sub-scale Batam and Jakarta plants into distressed divestiture. The five-to-ten-year viability window favors platform consolidation around dual-certification capability. Acquisition target archetype: mid-tier flexible film producers with mono-polymer redesign capacity for instant noodle export segments. Watch Ministry of Environment EPR enforcement timelines in outer island provinces as the inflection indicator for plastic-intensive segment reconfiguration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reconditioning Infrastructure | Captive washing facilities near Surabaya's port complex lock in palm oil exporter maintenance contracts against Greif's global network. |
| SNI-ISO Dual Certification Investment | Pharmaceutical regulator mandates on child-resistant closures consolidate supplier relationships toward accredited converters. |
| Barrier Coating R&D Expansion | Specialized corrosion resistance for humid tropical conditions separates agrochemical packaging from commodity polyethylene tiers. |
| Kalimantan Production Footprint Establishment | East Kalimantan mining and smelter investments create localized demand for bulk chemical packaging with shorter supply lines. |
| Mono-Polymer Flexible Film Redesign | Ministry of Industry recyclability mandates force material substitution toward SNI-compliant structures for instant noodle exports. |
Research Methodology
Multiple input streams — structured interviews with plant managers at Surabaya reconditioning facilities, procurement leads at palm oil exporters, distribution channel partners in Jakarta's manufacturing corridor, and technical R&D directors at barrier coating specialists — were reconciled against customs and trade data, Ministry of Industry SNI compliance filings, SEC disclosures from global fleet managers, and regional pulp price indices. Bottom-up volume estimates from individual converter capacity and top-down demand aggregation from end-use sector shipments were cross-validated through triangulation.
Historical shipment trajectories were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include material platform, end-use severity tier, packaging format durability, and regional regulatory enforcement cluster. CAGRs were derived from slope analysis of normalized adoption curves, with forecast inputs incorporating Ministry of Environment EPR implementation pace and palm oil export volume corridors.
Caveats apply where Ministry of Industry SNI certification timeline acceleration or provincial waste management ordinance fragmentation could materially shift the outlook. Deviation in recycled pulp cost volatility or UN certification testing capacity expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Global Dunnage Packaging Market
Industrial Packaging
Corrugated Automotive Packaging Market
Industrial Packaging
Global Industrial Wooden Crates Market
Industrial Packaging
Overpack Drum Market
Industrial Packaging
Corrugated Bulk Bins Market
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Cone Bottom Tank Market
Industrial Packaging
Bulk Packaging Market
Industrial Packaging
Nestable Drums Market
Industrial Packaging
Fiber Drums Market
Industrial Packaging
Slip Sheets Market
Industrial Packaging
Industrial Filling Machine Market
Industrial Packaging
Middle East and Africa Octabin Market
Industrial Packaging
Industrial Chemical Packaging Market
Industrial Packaging
Industrial Plastic Bags Market
Industrial Packaging
Industrial Jugs Market