
 Slip Sheets Market | 2026-2036
Slip Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Slip Sheets Market Analytics
Market Context
Modular unit-load configurations are expanding as warehouse operators unbundle pallet-and-sheet combinations into standalone slip-sheet systems for high-velocity SKUs. WestRock Company leverages its integrated containerboard and converting footprint to supply calibrated paperboard grades for automated push-pull equipment. International Paper Company sustains geographic dominance across North American corrugated networks, ensuring consistent fiber sourcing for multi-wall slip sheet production. Georgia-Pacific LLC specializes in coated kraft variants that resist moisture in cold-chain pharmaceutical distribution.
Technical Definition and Segment Structure
Slip sheets are thin, flat platforms—typically 0.5 to 2.0 mm in caliper—manufactured from kraft paperboard, oriented polypropylene, or laminated fiber-composite substrates, designed to support unitized loads while enabling forklift-free handling via push-pull or rollerfork attachments. Their primary purpose is to eliminate pallet mass, recover vertical cube in containerized shipping, and streamline reverse logistics in closed-loop supply chains. Paperboard thickness grades dominate mature food and beverage applications where one-way export and retail-ready display requirements converge, while plastic variants lead in electronics and automotive sectors where washdown compatibility and dimensional stability under humidity stress command premium positioning. Composite and fiber formulations are gaining traction in pharmaceutical cold chain as thermal insulation properties and controlled friction coefficients meet validated handling protocols.
Regulatory Framework and Outlook
The US EPA's sustainable materials management program and California's extended producer responsibility regulations are tightening constraints on single-use pallet alternatives, directly elevating fiber-based slip sheet specifications in domestic procurement. EU REACH and F-Gas Regulation compliance requirements are reshaping plastic substrate formulations, particularly for pharmaceutical and electronics end uses where chemical transparency and halogen-free claims determine market access. Stakeholders must monitor evolving ISO 8611 and ASTM D1185 mechanical test standards as automated handling speeds increase and equipment OEMs demand tighter caliper tolerances and coefficient-of-friction windows.
Market Dynamics
Automotive OEMs in Germany have standardized push-pull handling systems, forcing substrate suppliers to recalibrate fiberboard grades for dimensional tolerances below 0.3 mm variance.
Growth Catalysts
- California EPR frameworks:Extended producer responsibility regulations mandate fiber-based alternatives to single-use pallets, accelerating procurement specification changes in West Coast distribution networks.
- Push-pull equipment penetration:Third-party logistics providers are retrofitting forklift fleets with rollerfork attachments, creating installed-base demand for calibrated slip sheet grades.
- Food and beverage cube optimization:Refrigerated transport operators recover 15-20 cm vertical clearance per container layer, converting pallet mass into sellable cargo volume.
Market Restraints
- Containerboard input volatility:Kraft linerboard prices fluctuate with OCC recovery rates, compressing converter margins on multi-wall slip sheet contracts.
- Push-pull equipment capex:Automated handling systems require $45,000-$80,000 per forklift conversion, limiting adoption among mid-cap warehouse operators.
- EU F-Gas compliance friction:Plastic substrate formulations face reformulation costs for halogen-free certification, delaying market access for polypropylene variants in pharmaceutical cold chain.
Strategic Opportunities
- India pharmaceutical export corridor:CDSCO cold-chain validation protocols create demand for fiber-composite slip sheets with thermal insulation coefficients matching validated shipping containers.
- Automotive battery logistics:Lithium-ion cell manufacturers require electrostatic-dissipative substrates, opening premium positioning for coated kraft variants with carbon-black loading.
- US EPA sustainable materials procurement:Federal supply chain mandates prioritize fiber-based unit-load platforms in defense and postal logistics networks.
Industry Challenges
- Coefficient-of-friction calibration:Automated push-pull systems demand ±0.05 COF tolerances, requiring substrate converters to install inline testing equipment.
- ISO 8611 test protocol alignment:Equipment OEMs and substrate suppliers dispute bending stiffness measurement methods, delaying specification standardization.
- Reverse logistics integration:Closed-loop supply chains struggle to recover and inspect fiber-based slip sheets at downstream nodes, contaminating recycled fiber streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Slip Sheets Market |
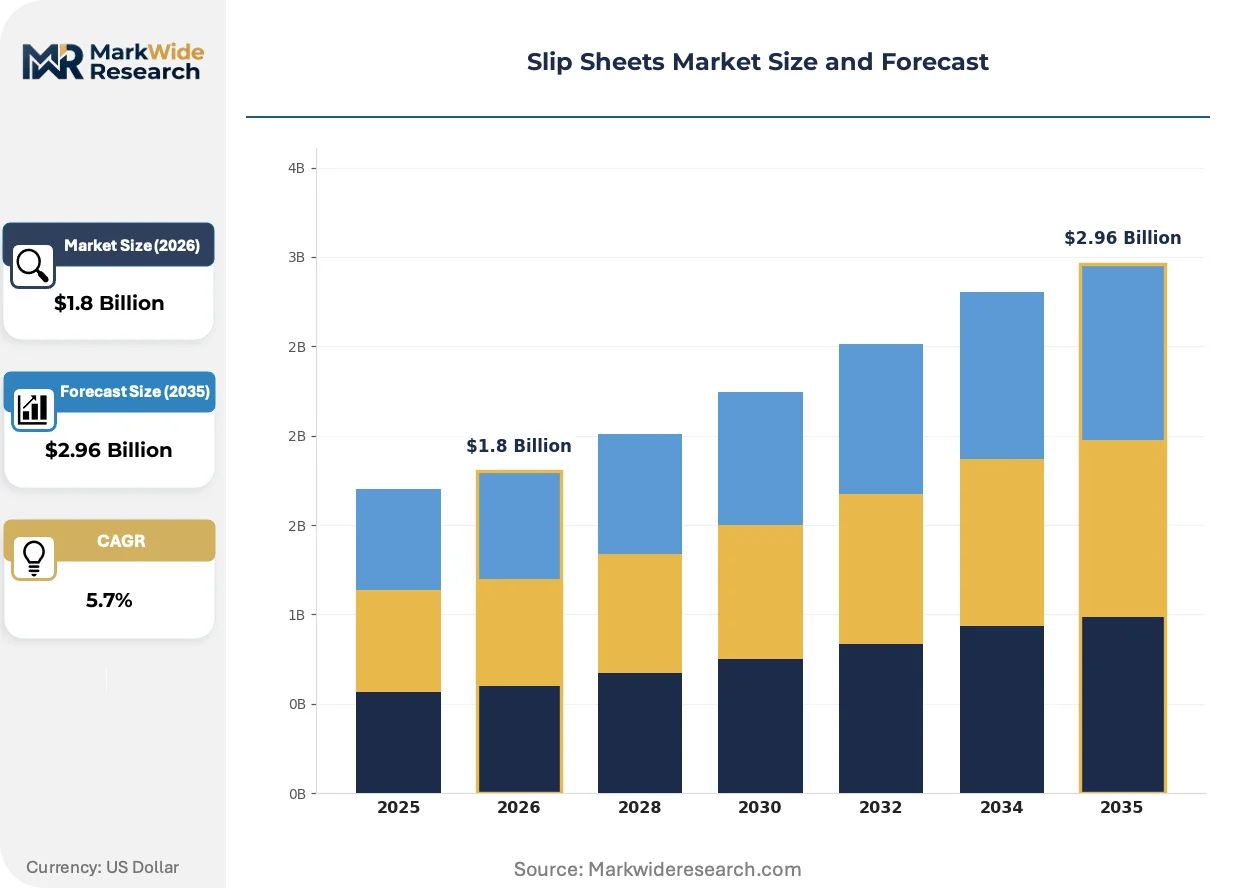
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paperboard, Composite, Fiber End Use Industry: Food & Beverage, Pharmaceuticals, Electronics, Automotive Shape: Square, Rectangular, Custom, Round Thickness: Thin, Medium, Thick, Extra Thick |
| Companies Covered | WestRock Company, International Paper Company, Smurfit Kappa Group, Badger Paperboard, Inc., DS Smith Plc, Georgia-Pacific LLC, Signode Industrial Group, RTS Packaging, LLC, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Slip Sheets Market Evolving Landscape
Material science advances and handling automation are compressing substrate caliper tolerances while expanding application scope beyond traditional food and beverage logistics.
Multi-ply fiber-composite laminates with oriented strand reinforcement are overtaking solid fiberboard in pharmaceutical cold-chain applications. Biologics distributors in Germany and Switzerland specify these substrates for validated thermal shipping containers. The technology is overtaking conventional paperboard in premium positioning by enabling simultaneous moisture resistance and controlled biodegradation timelines.
REACH Annex XVII restrictions on persistent organic pollutants are forcing polypropylene substrate reformulations across European electronics logistics. Compounders must eliminate legacy flame-retardant chemistries by 2026 compliance deadlines. Medical device manufacturers in Ireland and the Netherlands are accelerating qualification of fiber-composite alternatives to avoid supply interruption.
Consolidated procurement through fourth-party logistics providers is compressing supplier bases for substrate converters. Amazon and DHL Supply Chain now specify single-source slip sheet programs across multi-country warehouse networks. German automotive tier-one suppliers have adopted similar centralized buying, displacing regional converter relationships in favor of continental contracts with integrated paperboard producers.
Slip Sheets Market Segmentation
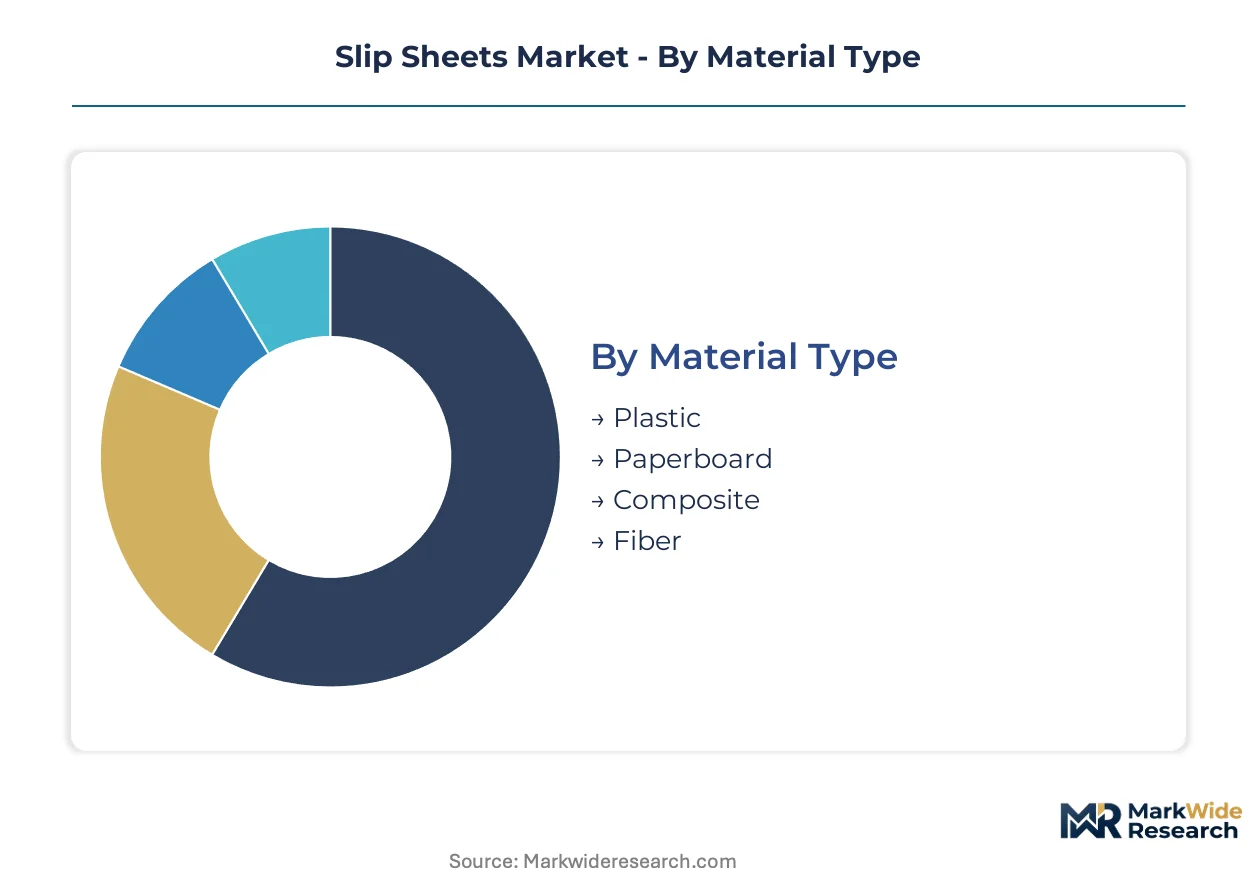
Segmentation in slip sheets reflects divergent handling requirements across automated and manual supply chains. Material selection drives equipment compatibility and regulatory compliance, while end-use specifications determine load-bearing tolerances and environmental performance standards.
Material Type:
Buyers differentiate primarily by equipment interface requirements and sustainability mandates rather than unit cost alone.
- Plastic:Polypropylene and high-density polyethylene formulations deliver dimensional stability under humidity stress and washdown compatibility for pharmaceutical and electronics cold chains. REACH Annex XVII compliance is forcing reformulation of legacy flame-retardant chemistries, delaying market access for some compounders.
- Paperboard:Multi-ply kraft linerboard dominates food and beverage logistics where one-way export and retail-ready display requirements converge. California's extended producer responsibility frameworks and US EPA sustainable materials management priorities are elevating fiber-based procurement specifications in domestic distribution networks.
- Composite:Fiber-composite laminates with oriented strand reinforcement enable controlled biodegradation timelines alongside moisture resistance. Biologics distributors in Germany and Switzerland specify these substrates for validated thermal shipping containers.
- Fiber:Natural fiber substrates from agricultural residues serve cost-sensitive agricultural export corridors with minimal handling automation.
Paperboard leads volumes today; composite formulations are gaining share fastest.
End Use Industry:
Application-specific load profiles and regulatory exposure shape procurement specifications across sectors.
- Food & Beverage:Refrigerated transport operators recover 15-20 cm vertical clearance per container layer by eliminating pallet mass. One-way export programs and retail-ready display requirements drive standardization on calibrated paperboard grades.
- Pharmaceuticals:CDSCO cold-chain validation protocols in India and thermal insulation coefficient requirements in European biologics distribution create demand for fiber-composite substrates with controlled friction properties. FDA and EMA handling validation standards govern substrate selection.
- Electronics:Electrostatic-dissipative requirements for lithium-ion battery logistics and halogen-free certification mandates under EU F-Gas Regulation are reshaping substrate specifications. REACH compliance deadlines are accelerating qualification of fiber-based alternatives.
- Automotive:German OEMs and tier-one suppliers have standardized push-pull handling systems, forcing substrate suppliers to maintain dimensional tolerances below 0.3 mm variance. Centralized procurement through fourth-party logistics providers is compressing regional supplier bases.
Food and beverage anchors volume; pharmaceutical applications show the steepest expansion trajectory.
Shape:
Container geometry and racking infrastructure determine form factor selection more than material cost.
- Square:Standardized footprints align with ISO container dimensions and automated warehouse racking systems. Dominant in intermodal freight and high-velocity distribution centers.
- Rectangular:Optimized for retail-ready display pallets and specialized automotive component racks. Common in European third-party logistics networks.
- Custom:Engineered geometries for irregular automotive body panels, aerospace components, and oversized pharmaceutical equipment. Requires close coordination with push-pull equipment OEMs on friction coefficient calibration.
- Round:Niche positioning for cylindrical drum handling and rotational molding applications in chemical logistics.
Square configurations dominate unit volumes; custom shapes command premium positioning.
Thickness:
Load weight and handling frequency determine caliper selection, with automated systems demanding tighter tolerances.
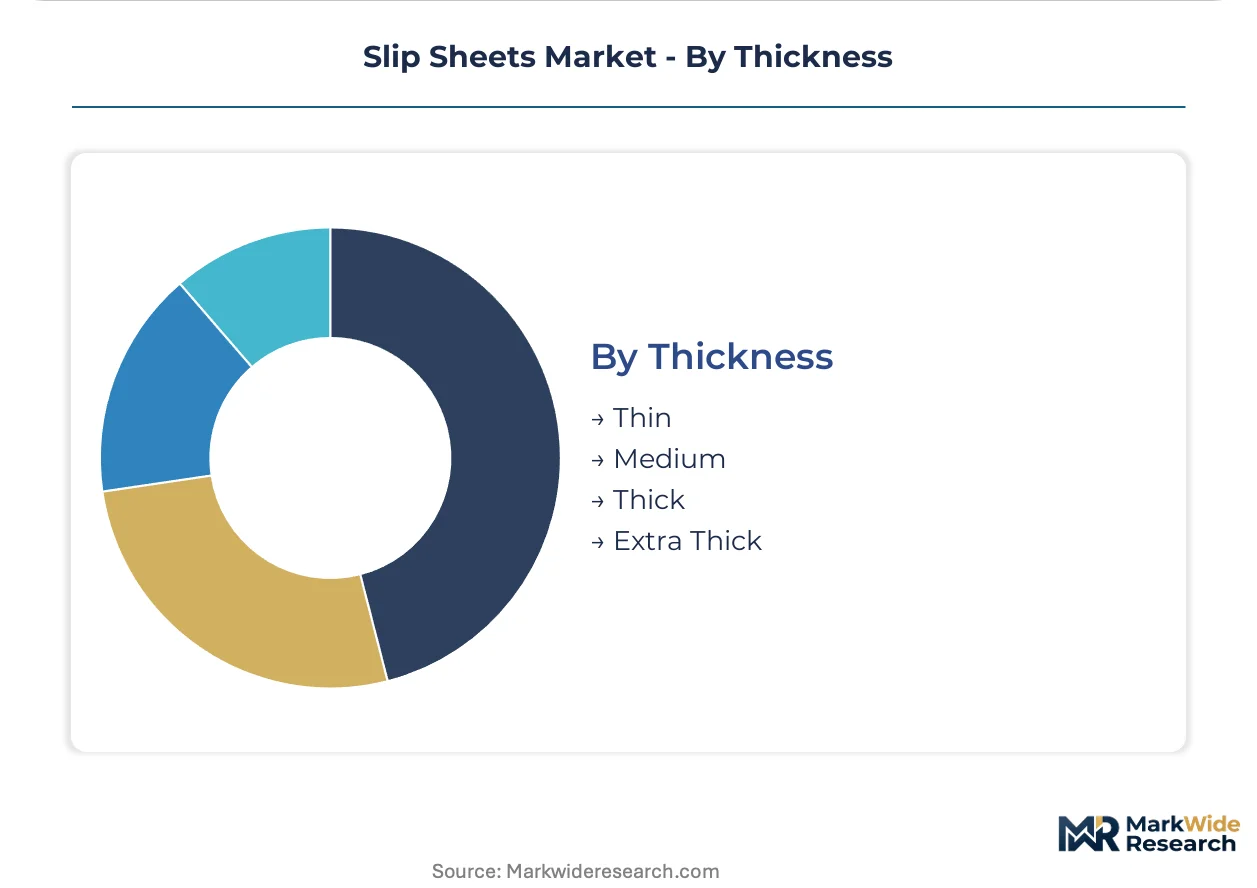
- Thin:0.5-0.8 mm calipers serve lightweight consumer goods and single-use export applications where minimal unit cost outweighs durability requirements. Limited to manual handling environments.
- Medium:0.8-1.2 mm specifications balance cost and performance for mainstream food and beverage distribution. Compatible with rollerfork attachments in third-party logistics fleets.
- Thick:1.2-1.6 mm grades support automotive battery modules and dense pharmaceutical shipments. Push-pull equipment OEMs specify these calipers for loads exceeding 1,000 kg.
- Extra Thick:1.6-2.0 mm and above for heavy machinery, steel coil, and construction materials where point-load distribution is critical. Requires specialized handling attachments.
Medium thickness captures the largest share; extra thick grades are climbing fastest on battery logistics demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Slip sheet handling systems originated in post-war German automotive logistics, where push-pull equipment manufacturers pioneered unit-load standardization for dense component flows. This engineering heritage established dimensional tolerances and friction coefficients that still govern global substrate specifications today. Demand patterns now diverge across regulatory environments and automation maturity levels.
Germany
Automotive OEMs in Stuttgart and Wolfsburg operate fully standardized push-pull networks, requiring fiberboard suppliers to maintain caliper variance below 0.3 mm. The KBA enforces transport packaging regulations that favor returnable systems, compressing regional converter margins. Bavarian logistics clusters around Munich anchor continental procurement contracts for tier-one battery suppliers.
United States
West Coast refrigerated transport operators recover 15-20 cm vertical clearance per container layer, converting pallet elimination into sellable cargo volume. California's extended producer responsibility frameworks mandate fiber-based alternatives in state procurement networks. Georgia-Pacific's integrated kraft operations in the Southeast supply coated grades for pharmaceutical cold-chain distribution.
India
Pharmaceutical exporters in Hyderabad and Ahmedabad face CDSCO cold-chain validation protocols that create demand for fiber-composite substrates with thermal insulation coefficients matching validated shipping containers. The PLI scheme for logistics infrastructure accelerates automated handling adoption. Maharashtra-based 3PL providers retrofit forklift fleets with rollerfork attachments for generic drug distribution.
Switzerland
Biologics distributors in Basel specify multi-ply fiber-composite laminates for validated thermal shipping containers. Swissmedic handling validation standards govern substrate selection for temperature-sensitive therapeutics. The country's precision logistics sector maintains friction coefficient tolerances of ±0.05 for automated push-pull systems.
China
Electronics manufacturers in Shenzhen and Dongguan demand electrostatic-dissipative substrates for lithium-ion battery module handling. MIIT standards for green logistics promote fiber-based unit-load platforms in domestic distribution networks. Yangtze River Delta 3PL providers centralize procurement through fourth-party logistics contracts.
Slip Sheets Market Competitive Landscape
Premium-margin players sit above commodity-margin players across substrate calibration capabilities and integrated fiber sourcing. The market structures around three tiers: integrated containerboard producers with captive kraft supply, specialized converters serving automated handling equipment OEMs, and regional fabricators competing on unit cost for manual handling applications. Consolidated procurement through Amazon and DHL Supply Chain compresses supplier bases, while automotive tier-one suppliers displace regional relationships with continental contracts.
Among integrated North American producers, WestRock Company and International Paper Company exemplify the scale-driven archetype with containerboard-to-converting footprints. Georgia-Pacific LLC occupies a position within the specialty-coated segment. Smurfit Kappa Group represents European integrated capacity. These anchors reflect competitive positioning across fiber sourcing security, equipment calibration partnerships, and regulatory compliance breadth rather than product-specific differentiation.
| Leading Market Players |
|---|
| WestRock Company |
| International Paper Company |
| Smurfit Kappa Group |
| Badger Paperboard, Inc. |
| DS Smith Plc |
| Georgia-Pacific LLC |
| Signode Industrial Group |
| RTS Packaging, LLC |
| Sonoco Products Company |
| Others |
Value Network & Pricing Analysis
Automated push-pull equipment calibration is compressing substrate tolerances below 0.3 mm variance while simultaneously concentrating procurement power among integrated containerboard producers with captive kraft supply. This technical transition elevates cost barriers for regional converters while rewarding scale-driven players with inline testing infrastructure and equipment OEM partnerships.
Pricing Analysis
Contract-based long-term offtake agreements with tier-one automotive and pharmaceutical buyers dominate premium tiers, while spot purchasing governs commodity paperboard grades for food and beverage exporters. Price differentiation hinges on caliper precision certification and volume scale, with California EPR compliance adding regulatory cost layers to fiber-based specifications. Cost compression in medium-grade paperboard is intensifying because OCC recovery rate volatility feeds directly into linerboard input costs. Mid-cap warehouse operators exhibit highest price sensitivity due to push-pull conversion capex burdens, whereas German automotive OEMs prioritize dimensional stability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Amazon and DHL Supply Chain, while regional distributors serve manual handling applications in agricultural export corridors. Supply concentrates in the United States, Germany, and China, with integrated producers in the Southeast US and Bavarian logistics clusters anchoring continental procurement. Raw material dependencies center on kraft linerboard, oriented polypropylene resin, and carbon-black conductive coatings for electrostatic-dissipative grades. Single-source vulnerability runs through specialized push-pull equipment OEMs whose friction coefficient specifications govern substrate qualification. Distribution runs through fourth-party logistics providers consolidating multi-country warehouse networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where California's extended producer responsibility frameworks and US EPA sustainable materials mandates are structurally elevating fiber-based procurement specifications.
For Market Incumbents: To counter margin compression from consolidated buyer procurement power, deepen captive fiber sourcing through backward integration into OCC recovery networks and install inline coefficient-of-friction testing equipment to meet push-pull OEM calibration demands. Secure long-term offtake agreements with German automotive tier-one suppliers before continental contract consolidation displaces regional relationships. For New Entrants and Emerging Players: Capture the India pharmaceutical export corridor by qualifying fiber-composite substrates against CDSCO cold-chain validation protocols, where incumbent penetration remains limited. Target electrostatic-dissipative formulations for lithium-ion battery logistics as automotive electrification accelerates substrate specification changes. Partner with Maharashtra-based 3PL providers retrofitting rollerfork fleets to bypass direct OEM sales cycle barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional converters lacking equipment calibration partnerships but possessing established food and beverage customer relationships. Long-term viability favors integrated producers with containerboard-to-converting footprints and regulatory compliance breadth across REACH, F-Gas, and EPA frameworks. Watch for push-pull equipment OEMs tightening friction coefficient tolerances below ±0.05 as the inflection signal for substrate converter consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into OCC Recovery | Secures linerboard input cost stability against volatile recovery rates. |
| Inline COF Testing Equipment Installation | Enables qualification for German automotive push-pull calibration standards. |
| Fiber-Composite Substrate Qualification | Opens CDSCO-compliant positioning in India pharmaceutical cold-chain exports. |
| Long-Term Offtake Agreement Expansion | Defends share against Amazon and DHL Supply Chain procurement consolidation. |
| Electrostatic-Dissipative Formulation Development | Captures lithium-ion battery logistics premium as automotive electrification accelerates. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory filings and trade databases. Primary interviews engaged substrate converters, push-pull equipment OEMs, pharmaceutical logistics managers, and automotive tier-one procurement leads. Secondary sources included US EPA sustainable materials program documentation, EU REACH Annex XVII substance restrictions, CDSCO cold-chain validation guidelines, and containerboard producer SEC disclosures. Bottom-up modeling of substrate volumes by material grade and thickness tier triangulated against top-down containerboard capacity utilization estimates.
Granularity-level modeling operated at material type, end-use industry, and regional regulatory cluster dimensions throughout the forecast period. Segment-level CAGRs derived from equipment penetration curves, regulatory compliance deadlines, and substrate substitution elasticities in food and beverage logistics. Forecast inputs incorporated push-pull forklift retrofit adoption rates, California EPR implementation timelines, and pharmaceutical cold-chain validation protocol expansions.
Underlying measurement precision varies by segment; paperboard thickness grades carry tighter precision than emerging composite formulations due to established ASTM D1185 test protocols. Forecasts reflect assumptions regarding equipment OEM tolerance specifications, regulatory enforcement consistency, and fiber input cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Nestable Drums Market
Industrial Packaging
Overpack Drum Market
Industrial Packaging
Anti-Static Reel Racks Market
Industrial Packaging
Corrugated Octabins Market
Industrial Packaging
Cone Bottom Tank Market
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Bulk Packaging Market
Industrial Packaging
Indonesia Industrial Packaging Market
Industrial Packaging
Industrial Packaging Market
Industrial Packaging
MENA Industrial Packaging Market
Industrial Packaging
Dunnage Trays Market
Industrial Packaging
Insulated Bin Market
Industrial Packaging
Industrial Bulk Packaging Market
Industrial Packaging
Industrial Jugs Market
Industrial Packaging
Rigid IBC Market
Industrial Packaging
Asia-Pacific Warehouse Drums and Barrel Market