
 Light Resistant Containers Market | 2026-2036
Light Resistant Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Light Resistant Containers Market Foresight
Pharmaceutical manufacturers is redrawing procurement priorities across the light resistant containers value chain as biologic drug portfolios expand. Gerresheimer AG anchors European supply through specialized molded glass capacity for injectable therapies. Amcor plc leverages multilayer polymer expertise to compete in high-barrier flexible and rigid formats for oral solid doses. Schott AG dominates tubular glass segments where borosilicate durability meets pharmacopeial light transmission limits.
Light resistant containers are engineered enclosures designed to block or filter ultraviolet and visible light wavelengths, typically incorporating amber coloration, UV-absorbing additives, or opaque metallic substrates to maintain product integrity. These containers employ controlled light transmission values, often below 10 percent at wavelengths between 290 and 450 nanometers, to prevent photodegradation of active pharmaceutical ingredients, vitamins, and photochemical reagents. Glass bottles lead pharmaceutical applications where USP and EP compliance mandates precise spectral protection, while polyethylene drums capture volume in chemical handling where cost and impact resistance outweigh optical precision. Composite totes represent the fastest-expanding structural pocket as multilayer coextrusion merges aluminum barrier films with polymer structural layers for agrochemical and specialty chemical bulk transport.
The US FDA enforces stability testing protocols under ICH Q1B guidelines that classify drug substances by photosensitivity, directly mandating protective packaging validations for new drug applications. The European Medicines Agency extends these requirements through its own stability guidelines while REACH and EU Packaging Waste Directive frameworks constrain material choices and recyclability obligations for suppliers operating across member states. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP light transmission standards, as divergence in test methods and acceptance criteria continues to fragment qualification requirements and complicate global container specifications.
Market Dynamics
The US FDA's ICH Q1B stability testing mandates are compelling pharmaceutical manufacturers to validate protective packaging for every photosensitive drug submission, creating a structural pull that cascades through raw material sourcing, converter capacity, and qualification timelines.
Growth Catalysts
- Biologic Portfolio Expansion:Pharmaceutical pipelines are concentrating on monoclonal antibodies and mRNA therapies that degrade under visible light, requiring amber glass and multilayer polymer barriers from fill-finish through distribution.
- REACH and EU Packaging Waste Directive:European recyclability mandates are accelerating rPET and bio-based polymer development for opaque containers, pushing converters to redesign material stacks without sacrificing light-blocking performance.
- Agrochemical Bulk Transport:Photoreactive herbicide formulations are driving demand for composite intermediate bulk containers that merge aluminum barrier films with structural polyethylene totes.
Market Restraints
- Borosilicate Glass Supply Concentration:Tubular glass capacity clusters in Germany and China, leaving North American pharmaceutical clients exposed to transatlantic shipping delays and tariff volatility.
- Multilayer Coextrusion Complexity:Achieving sub-10% light transmission across 290-450 nanometers requires 5-7 layer structures that strain converter technical capabilities and inflate scrap rates.
- Metal-Substitute Competition:Stainless steel drums with interior coatings are capturing chemical handling volume where optical precision matters less than mechanical durability and reuse cycles.
Strategic Opportunities
- Indian Pharmaceutical Manufacturing:CDSCO's alignment with ICH stability guidelines is creating first-mover advantage for container suppliers qualifying amber molded glass capacity near Hyderabad and Ahmedabad clusters.
- Cell and Gene Therapy Cold Chain:Cryogenic storage requirements below minus 150 degrees Celsius are opening demand for light-resistant containers that maintain spectral protection through thermal cycling.
- Digital Printing Integration:Inline UV-cured decoration on amber bottles is enabling lot-level traceability without secondary labeling, compressing packaging line footprints for contract manufacturers.
Industry Challenges
- Pharmacopeial Harmonization Delays:Divergent USP, EP, and JP light transmission test methods force container suppliers to maintain three parallel qualification protocols, extending validation timelines by 8-14 months.
- Specialized Blow Molding Talent Scarcity:Multilayer extrusion blow molding for high-barrier pharmaceutical bottles requires technicians trained in both polymer rheology and cleanroom protocols, a combination concentrated at fewer than twelve technical institutes globally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Resistant Containers Market |
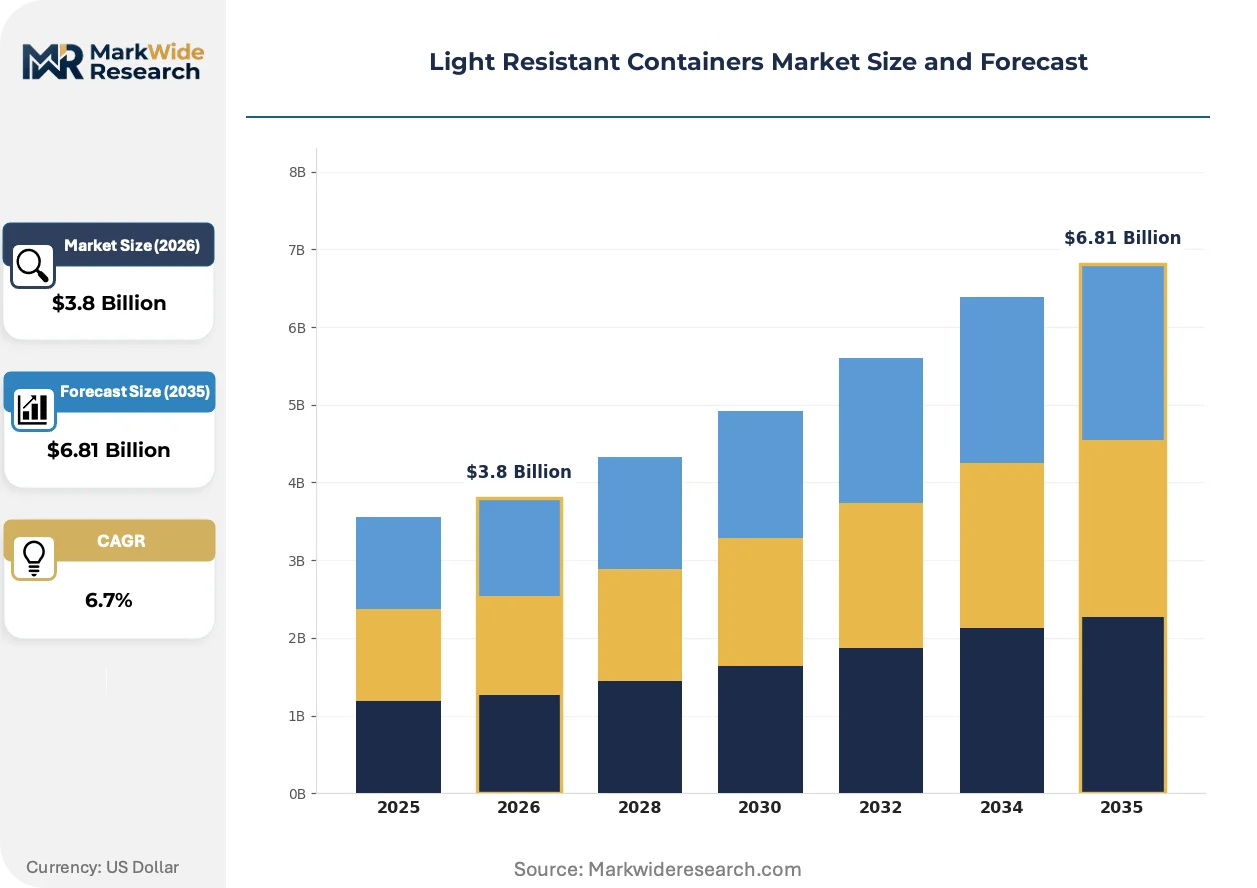
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Container Type: Drums, Jars, Bottles, Totes Material: Polyethylene, Glass, Metal, Composite Application: Pharmaceuticals, Food & Beverages, Chemicals, Cosmetics End User: Manufacturers, Distributors, Retailers, Laboratories |
| Companies Covered | Amcor plc, Gerresheimer AG, Berry Global Group, O-I Glass, Schott AG, Huhtamaki, Klöckner Pentaplast, Sonoco Products Company, Alpha Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Resistant Containers Market Shifts & Advancements
Container engineering is pivoting from passive light blocking toward active spectral management, with material scientists embedding wavelength-selective absorbers and smart indicators that signal exposure breaches.
Multilayer coextrusion is fragmenting the traditional glass-polymer dichotomy in pharmaceutical packaging. Five- to seven-layer structures combining EVOH barriers with UV-absorbing tie layers now achieve pharmacopeial light transmission limits at half the weight of amber glass. Contract manufacturers in Germany and New Jersey are qualifying these formats for oral solid dose lines previously reserved for molded glass. The technology is fragmenting converter margins as polymer specialists capture volume from established glasshouses.
EMA's 2023 revision to stability testing guidelines now explicitly requires light protection validation for biosimilar applications, extending ICH Q1B principles to follow-on biologics. This regulatory expansion is forcing European generic manufacturers to upgrade from clear to amber primary packaging for products previously marketed in transparent containers. The guideline is compressing qualification timelines as ANDA holders race to meet reference product stability profiles.
Buying patterns among pharmaceutical procurement functions are consolidating supplier relationships around integrated primary-secondary packaging providers. Large molecule manufacturers in Massachusetts and North Carolina are awarding sole-source contracts to converters capable of delivering pre-sterilized, pre-labeled amber vials and syringes. This consolidation is displacing discrete component sourcing and compressing the vendor base serving fill-finish operations.
Light Resistant Containers Market Segmentation
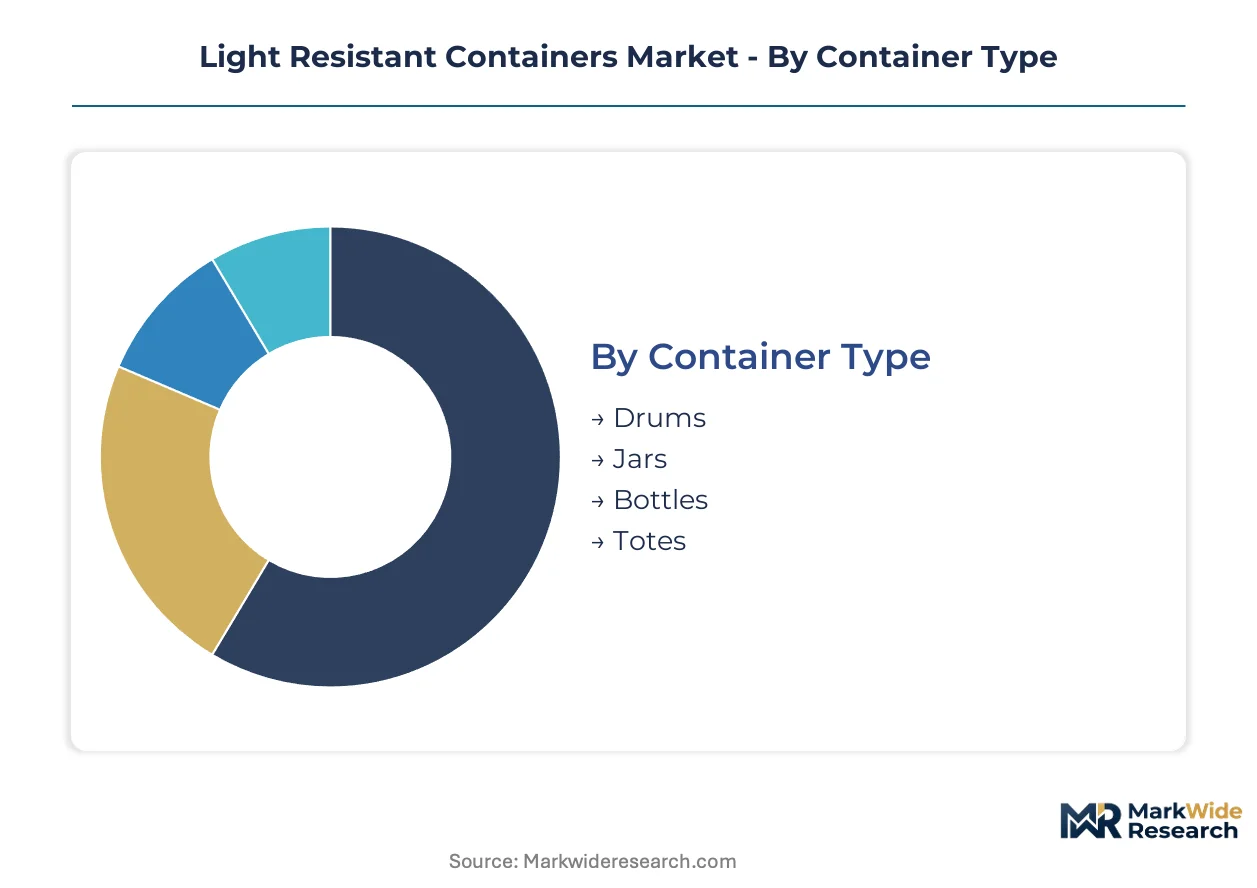
Segmentation in the light resistant containers market reveals how material science, regulatory compliance, and end-use requirements fragment purchasing patterns across pharmaceutical, chemical, and food supply chains. Container buyers prioritize spectral protection specifications, cold chain compatibility, and qualification timelines differently depending on their product portfolios and geographic regulatory exposure.
Container Type:
Margin pools concentrate in bottles and totes where pharmaceutical and agrochemical volumes command premium pricing for validated light-blocking performance.
- Bottles:Amber glass and multilayer polymer bottles dominate pharmaceutical fill-finish operations, with molded glass capturing injectable biologics and coextruded polymers gaining share in oral solid doses. German manufacturers anchor European supply for borosilicate tubular glass, while New Jersey contract manufacturers qualify polymer alternatives to compress line changeover times.
- Totes:Composite intermediate bulk containers merge aluminum barrier films with polyethylene structural layers, serving photoreactive herbicide formulations in agricultural chemical distribution. Demand clusters in Midwest US grain belt logistics and Brazilian soy belt transport corridors where UV degradation risks compound during extended field storage.
- Drums:High-density polyethylene drums with carbon black masterbatch dominate chemical handling where cost and impact resistance outweigh optical precision.
- Jars:Wide-mouth amber glass jars serve topical pharmaceutical creams and cosmetic formulations requiring spatula access under controlled light conditions.
The dominant share belongs to bottles, while totes are closing the gap fastest.
Material:
Cost tier stratification separates commodity polymer volumes from premium glass and composite structures where qualification investments create switching barriers.
- Glass:Borosilicate and soda-lime amber glass deliver sub-10% light transmission at 290-450 nanometers, meeting USP and EP pharmacopeial limits for photosensitive drug substances. Schott AG and Gerresheimer AG anchor specialized tubular and molded capacity in Germany, supplying fill-finish operations across Massachusetts, North Carolina, and Swiss pharmaceutical clusters.
- Composite:Multilayer coextrusion combining EVOH barriers, UV-absorbing tie layers, and aluminum films achieves pharmacopeial protection at reduced weight versus glass. Technical complexity limits qualified converters to fewer than twelve global sites capable of cleanroom-compliant pharmaceutical production.
- Polyethylene:HDPE and LDPE with UV-stabilizing additives capture chemical and food applications where cost sensitivity dominates specification requirements.
- Metal:Stainless steel drums with interior epoxy coatings serve reuse-intensive chemical logistics where mechanical durability exceeds optical precision needs.
Glass commands the revenue concentration, though composite materials are expanding most quickly through polymer converter technical upgrades.
Application:
Customer type determines specification intensity, with pharmaceutical buyers imposing validation burdens that chemical and food purchasers rarely replicate.
- Pharmaceuticals:Monoclonal antibodies, mRNA therapies, and biosimilars mandate amber primary packaging validated under ICH Q1B stability protocols. FDA and EMA submissions require documented light transmission data, forcing container suppliers to maintain parallel USP, EP, and JP qualification protocols.
- Chemicals:Photoreactive agrochemicals and specialty reagents drive composite tote and drum specifications where transport durability and UV protection balance against unit economics.
- Food & Beverages:Vitamins, natural colorants, and light-sensitive nutraceuticals require amber glass or opaque polymer barriers, though regulatory validation burdens fall below pharmaceutical thresholds.
- Cosmetics:Premium skincare and fragrance packaging employs amber glass for aesthetic differentiation and ingredient stability, with shorter qualification cycles than drug applications.
Pharmaceuticals retain the specification leadership, while chemicals are gaining share fastest through agrochemical bulk transport expansion.
End User:
Supply concentration patterns diverge between captive pharmaceutical manufacturing and distributed chemical distribution networks.
- Manufacturers:Large molecule drug producers in Massachusetts and North Carolina consolidate supplier relationships around integrated primary-secondary packaging providers capable of delivering pre-sterilized, pre-labeled amber vials and syringes.
- Distributors:Chemical and agrochemical logistics operators specify composite totes and drums for bulk photoreactive material transport, with procurement decisions weighted toward lease-return programs and fleet standardization.
- Retailers:Pharmacy chains and cosmetic retailers source finished amber bottles and jars through contract packagers, with limited direct container specification influence.
- Laboratories:Research institutions and diagnostic facilities purchase small-volume amber glassware and polymer containers through scientific supply distributors, prioritizing catalog breadth over custom qualification.
Manufacturers control the premium volume, while distributors are climbing the fastest as agrochemical bulk logistics expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German borosilicate glass exports flow predominantly to Massachusetts and North Carolina pharmaceutical clusters, while Chinese tubular glass capacity supplies Indian generic drug manufacturers expanding under CDSCO's ICH-aligned stability mandates.
United States
FDA's ICH Q1B enforcement compels amber packaging validation for every photosensitive drug submission. Massachusetts biotech corridors and North Carolina fill-finish operations consolidate procurement around pre-sterilized, pre-labeled container systems. Domestic converters in New Jersey qualify multilayer polymer alternatives to compress line changeover times.
Germany
EMA stability guidelines and REACH recyclability mandates shape converter R&D priorities simultaneously. Gerresheimer AG and Schott AG anchor specialized tubular and molded glass capacity serving European pharmaceutical clients. Baden-Württemberg technical institutes train the scarce multilayer extrusion blow molding technicians combining polymer rheology with cleanroom protocols.
India
CDSCO's alignment with ICH guidelines creates first-mover advantage for container suppliers qualifying amber molded glass near Hyderabad and Ahmedabad pharmaceutical manufacturing clusters. Domestic generic producers upgrade packaging to meet ANDA stability requirements for US export markets. Local converter technical capabilities lag European standards, opening partnership opportunities.
China
NMPA pharmacopeial standards and dual carbon goals constrain material choices for domestic pharmaceutical packaging. Tubular glass capacity concentrates in coastal provinces supplying both domestic biologic manufacturers and export markets. Yangtze River Delta converters develop rPET opaque containers under tightening EU Packaging Waste Directive export compliance pressures.
Brazil
ANVISA stability testing requirements extend ICH principles to Latin American pharmaceutical registrations. São Paulo state agrochemical formulators drive composite intermediate bulk container demand for photoreactive herbicide distribution. Local logistics operators specify lease-return programs for aluminum-barrier totes serving soy belt transport corridors.
Light Resistant Containers Market Competitive Landscape
Listed leaders compete with private specialists across qualification-intensive pharmaceutical segments. The vendor base concentrates around three strategic archetypes: integrated glasshouses with captive borosilicate supply, multilayer polymer converters leveraging coextrusion technical barriers, and diversified packaging conglomerates spanning primary-secondary integration. Capacity expansion and strategic partnerships dominate competitive moves as qualification timelines extend validation backlogs.
Within the integrated glasshouse tier, Gerresheimer AG and Schott AG exemplify European-centered supply architectures serving fill-finish operations with pharmacopeial-compliant molded and tubular formats. Amcor plc occupies a position among diversified packaging conglomerates spanning flexible and rigid barrier technologies across oral solid dose applications. These three anchors represent distinct competitive vectors: German glass specialization, multilayer polymer technical integration, and global scale-driven portfolio breadth.
| Leading Market Players |
|---|
| Amcor plc |
| Gerresheimer AG |
| Berry Global Group |
| O-I Glass |
| Schott AG |
| Huhtamaki |
| Klöckner Pentaplast |
| Sonoco Products Company |
| Alpha Packaging |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements with German glasshouses lock in borosilicate supply access and price visibility for North American pharmaceutical fill-finish operations, insulating buyers from transatlantic shipping volatility while fixing conversion cost baselines across multi-year procurement cycles.
Pricing Analysis
Multilayer polymer coextrusion versus molded amber glass versus next-generation bio-based barrier materials creates a three-tier pricing structure across premium, standard, and economy levels. Certification grade under ICH Q1B protocols and cleanroom compliance status drive price differentiation, with USP-validated borosilicate vials commanding substantial premiums over EP-only qualified alternatives. Cost compression in polymer converter tiers is intensifying because technical talent scarcity limits qualified capacity expansion. Chemical distributors exhibit highest price sensitivity, while cell and gene therapy manufacturers prioritize qualification speed over unit cost.
Supply Chain Analysis
Borosilicate sand refinement capacity in Germany and China controls upstream material flow for pharmaceutical glass production. Tubular glass manufacturing draws from soda ash, boron compounds, and specialized furnace equipment as critical inputs. Single-source vulnerability concentrates in Baden-Württemberg technical institutes training multilayer extrusion technicians combining polymer rheology with cleanroom protocols. Distribution runs through integrated primary-secondary packaging providers delivering pre-sterilized, pre-labeled systems direct to Massachusetts and North Carolina fill-finish operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent container suppliers face substitution pressure from stainless steel drum systems with interior coatings capturing chemical handling volume where reuse cycles outweigh optical precision requirements.
For Market Incumbents: Fortify qualification moats by deepening backward integration into captive borosilicate sand sourcing and expanding molded glass capacity near Hyderabad pharmaceutical clusters. EMA's 2023 biosimilar stability guideline expansion creates defensive validation backlog advantages against polymer converter entrants lacking parallel USP-EP-JP protocol experience. For New Entrants and Emerging Players: Differentiate on cryogenic-compatible composite formats for cell and gene therapy cold chains below minus 150 degrees Celsius, where glass thermal cycling failures open technical white space. Indian CDSCO-aligned stability mandates present the most penetrable regulatory entry point for amber molded glass qualification partnerships with domestic generic manufacturers targeting US ANDA submissions. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors multilayer polymer converters with cleanroom-certified pharmaceutical capacity over commodity chemical packaging generalists. Long-term viability hinges on pharmacopeial harmonization resolution compressing parallel qualification burdens. Watch EMA-FDA joint guidance development on light transmission test method alignment as the critical inflection signal for validation timeline normalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Supply | Gerresheimer and Schott AG secure captive raw material access against sand export restrictions. |
| Multilayer Coextrusion Capacity Expansion | New Jersey converters qualify EVOH-UV barrier structures for oral solid dose lines previously glass-dependent. |
| Pre-Sterilized Pre-Labeled System Integration | Amcor plc captures sole-source contracts from Massachusetts biotech manufacturers consolidating vendor bases. |
| Cryogenic Thermal Cycling Validation | Composite developers target cell therapy storage protocols where glass fracture risk excludes incumbent formats. |
| Indian Manufacturing Cluster Partnership | European glasshouses establish Hyderabad joint ventures to serve CDSCO-compliant generic export production. |
Research Methodology
Cross-validation between regulatory filing databases and converter capacity disclosures anchors the qualitative findings in this analysis. Primary interviews with pharmaceutical packaging procurement directors, multilayer extrusion technical managers, regulatory affairs specialists at fill-finish operations, and CDSCO compliance officers combined with secondary validation from FDA submission records, EMA stability guideline revisions, USP and EP pharmacopeial standards, and trade customs data. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates across the analysis window.
Sensitivity analysis on borosilicate glass supply disruption scenarios and polymer converter qualification timeline compression informs the projection framework. Segmentation dimensions modeled include container material type, pharmaceutical application intensity, chemical versus drug end-use, and regional regulatory cluster alignment. CAGRs derive from installed capacity expansion schedules cross-referenced with ICH Q1B mandate enforcement intensity and biologic pipeline concentration by therapeutic modality.
The analysis sits within stated boundaries; outcomes outside sustained ICH guideline harmonization delays or abrupt REACH recyclability mandate acceleration would require recalibration. Forecasts reflect assumptions on pharmacopeial test method convergence, multilayer coextrusion technical talent pipeline development, and transatlantic logistics cost stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Container Stacking Machine Market
Containers
Compartment Trays Market
Containers
Corrugated Open-Head Drums Market
Containers
Concentrate Containers Market
Containers
Pails Market
Containers
Child-Resistant Containers Market
Containers
Cubitainer Market
Containers
HDPE Bottles Market
Containers
Lab Storage Container Market
Containers
Laboratory Sample Container Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Corrugated Bin Boxes Market
Containers
Soup Containers Market
Containers
Thin Wall Containers Market
Containers
EPS Shippers Market
Containers
Lift-Off Lid Box Market