
 Lightweight Food Container Market | 2026-2036
Lightweight Food Container Market Size, Share, and Industry Trends Forecast 2026-2036
Lightweight Food Container Market Foresight
Foodservice distribution channels are tilting toward direct procurement partnerships with packaging converters. Amcor plc leverages its global film and rigid plastics footprint to anchor supply contracts with multinational quick-service chains. Berry Global Inc. specializes in thermoformed containers for prepared meals, competing on customization speed rather than commodity volume. Tetra Pak dominates aseptic carton formats for ambient-ready food applications, sustaining R&D intensity in fiber-based barrier technologies.
Lightweight food containers are engineered structures with wall thicknesses typically below 0.5 millimeters, formed through injection molding, thermoforming, or die-cutting processes to minimize material use while preserving barrier integrity against moisture, oxygen, and mechanical stress. Their primary purpose is to reduce logistics cost and post-consumer waste mass in prepared food and beverage distribution. Plastic containers lead unit volume due to polypropylene's heat tolerance and sealability, though biodegradable containers represent the fastest-expanding margin pool as compostable plastics command price premiums in regulated channels. Aluminum trays occupy a mature position in institutional catering, where recyclability claims support contract renewals but volume growth remains flat.
The EU Green Deal and REACH framework restrict certain polystyrene grades in member states, redirecting formulation investment toward polypropylene and compostable alternatives. FDA food contact notification requirements in the United States govern migration limits for recycled content incorporation, slowing but not blocking circular material adoption. China's SAMR enforces GB standards for plastics in food contact, creating compliance friction for imported biopolymer formulations. Stakeholders must monitor evolving extended producer responsibility schemes across these jurisdictions to anticipate material cost shifts and qualification timelines.
Market Dynamics
EU Green Deal restrictions on polystyrene are redirecting converter investment toward polypropylene and compostable alternatives, restructuring raw material procurement across Southeast Asian manufacturing corridors.
Growth Catalysts
- EU Green Deal packaging mandates:Cross-border material standards tighten, compelling quick-service restaurants to scale biodegradable procurement and opening premium margin pools for certified converters.
- Food delivery platform concentration:Vietnam's domestic aggregators consolidate order volume, creating dedicated supply contracts that anchor capacity utilization for Ho Chi Minh City converters.
- Thermoforming speed advantages:Customization velocity in prepared-meal formats displaces commodity rigid plastics, rewarding converters with rapid tool-change capabilities.
Market Restraints
- Biopolymer input cost volatility:PLA and PHA resin prices fluctuate with agricultural feedstock harvests, compressing margins for compostable container specialists.
- Chinese import friction:SAMR GB standards for food-contact plastics create qualification delays for European biopolymer formulations entering mainland manufacturing.
- Aluminum tray substitution ceiling:Institutional catering contracts favor recyclability claims but volume growth stagnates as heat-seal flexibility limits format expansion.
Strategic Opportunities
- Vietnam export corridor expansion:Converters near Ho Chi Minh City serve both domestic delivery platforms and EU buyers seeking ASEAN-origin compliant supply.
- Aseptic carton barrier R&D:Fiber-based moisture and oxygen barriers converge with ambient-ready food applications, opening shelf-stable prepared meal segments.
- Extended producer responsibility schemes:Deposit-return frameworks in EU member states create closed-loop material flows that reward vertically integrated recyclers.
Industry Challenges
- Migration testing talent scarcity:FDA food contact notification protocols require specialized analytical chemists; qualified personnel concentrate in legacy polymer hubs.
- Multi-jurisdiction certification lag:Simultaneous EU REACH, FDA, and SAMR qualification timelines extend product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lightweight Food Container Market |
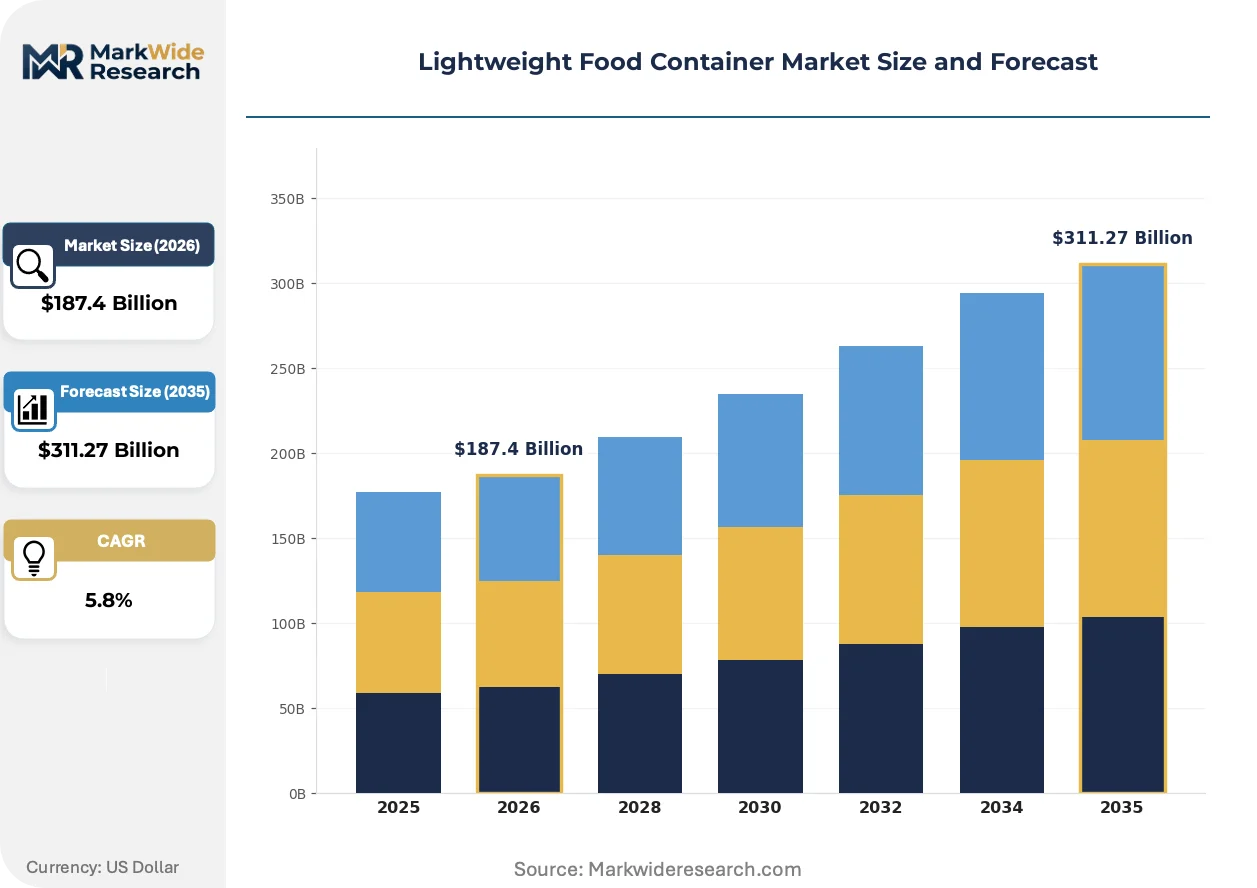
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic Containers, Aluminum Trays, Paper Boxes, Biodegradable Containers End User: Restaurants, Takeaway Services, Food Delivery Platforms, Catering Services Material: Polypropylene, Polystyrene, Bamboo Fiber, Compostable Plastics Size: Small Containers, Medium Containers, Large Containers, Extra Large Containers |
| Companies Covered | Amcor plc, Berry Global Inc., Ardagh Group, Silgan Holdings Inc., Plastipak Holdings, Inc., Sonoco Products Company, Graham Packaging Company, Ball Corporation, Tetra Pak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lightweight Food Container Market Shifts & Advancements
Active barrier engineering and digital production control are compressing development cycles while regulatory fragmentation forces parallel compliance investments across multiple jurisdictions.
Thermoformed polypropylene containers with sub-0.5 millimeter wall thickness are digitizing quality assurance protocols through inline vision systems. Quick-service chains in Southeast Asia deploy these systems to verify seal integrity at line speeds exceeding 400 units per minute. Real-time defect detection is digitizing supplier scorecards, compressing audit cycles from quarterly to continuous monitoring.
REACH framework restrictions on styrenic polymers redirect formulation R&D toward certified compostable alternatives. European converters face material requalification costs that favor larger players with dedicated regulatory affairs teams. Prepared meal segments targeting German and French retail channels accelerate polypropylene and PLA blend adoption to preempt enforcement windows.
Direct procurement partnerships between foodservice operators and packaging converters disintermediate traditional distribution layers. Quick-service chains in Vietnam negotiate volume commitments with Ho Chi Minh City thermoformers, bypassing regional wholesalers. This channel consolidation concentrates bargaining power with buyers possessing dedicated supply chain analytics functions.
Lightweight Food Container Market Segmentation
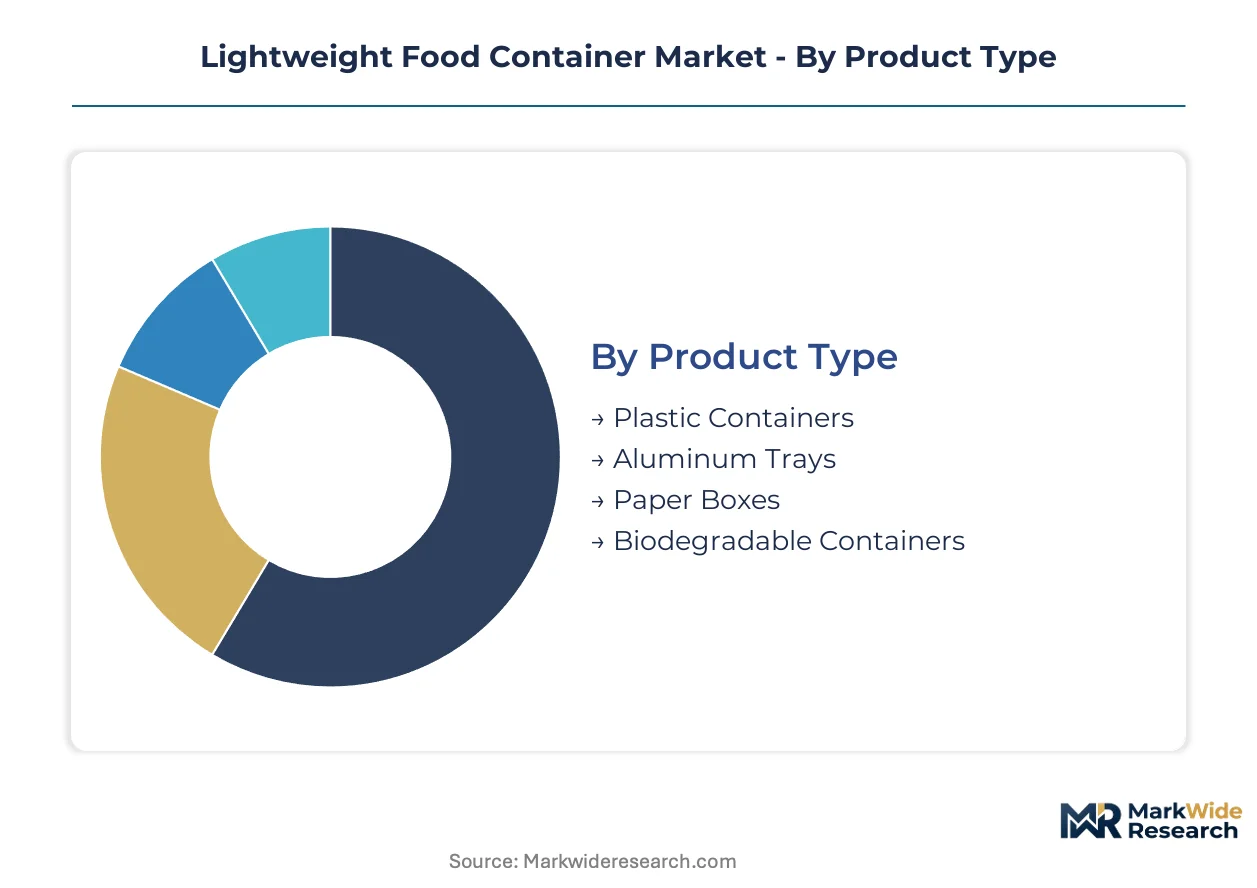
Lightweight food container demand fragments across material chemistry, thermal performance, and disposal pathways. Procurement decisions hinge on heat tolerance, seal integrity, and compliance with evolving extended producer responsibility frameworks.
Product Type:
Cost tier determines converter margin structure and capital intensity across forming technologies.
- Plastic Containers:Polypropylene and polystyrene formulations dominate unit economics through injection molding and thermoforming efficiency. Quick-service chains in Vietnam's Ho Chi Minh City corridor anchor volume contracts for thin-wall designs below 0.5 millimeters. Heat-seal compatibility with modified atmosphere packaging sustains share in prepared meal distribution.
- Biodegradable Containers:PLA and PHA biopolymers command price premiums in EU-regulated channels where the Green Deal restricts conventional plastics. Certification costs and agricultural feedstock volatility compress margins for specialists without backward integration into resin supply. German and French retail channels accelerate qualification timelines.
- Aluminum Trays:Recyclability claims support institutional catering contract renewals. Heat-seal flexibility limitations constrain format expansion beyond oven-ready applications.
- Paper Boxes:Fiber-based barriers compete in ambient-ready segments where moisture resistance requirements moderate. Inline coating technologies narrow performance gaps with plastic alternatives.
Plastic containers hold installed capacity. Biodegradable containers are rotating up the share rankings.
End User:
Customer procurement sophistication shapes contract terms and technical specification depth.
- Food Delivery Platforms:Vietnam's domestic aggregators consolidate order volume into dedicated supply agreements with thermoforming converters. Real-time quality monitoring via inline vision systems replaces quarterly supplier audits with continuous scorecard updates. Platform analytics functions concentrate bargaining power in direct procurement negotiations.
- Restaurants:Independent operators prioritize unit cost and minimum order flexibility over customization velocity. Regional distributors retain relevance through fragmented demand aggregation.
- Takeaway Services:Speed of service requirements favor pre-formed container stock with standardized lid compatibility. Limited cold chain infrastructure in Southeast Asian markets elevates importance of ambient stability claims.
- Catering Services:Volume predictability supports longer-term converter contracts. Oven-to-table thermal performance specifications differentiate procurement from disposable delivery formats.
Food delivery platforms extract steepest price concessions. Catering services offer margin stability through contract duration.
Material:
Regulatory jurisdiction dictates permissible chemistries and migration testing burdens.
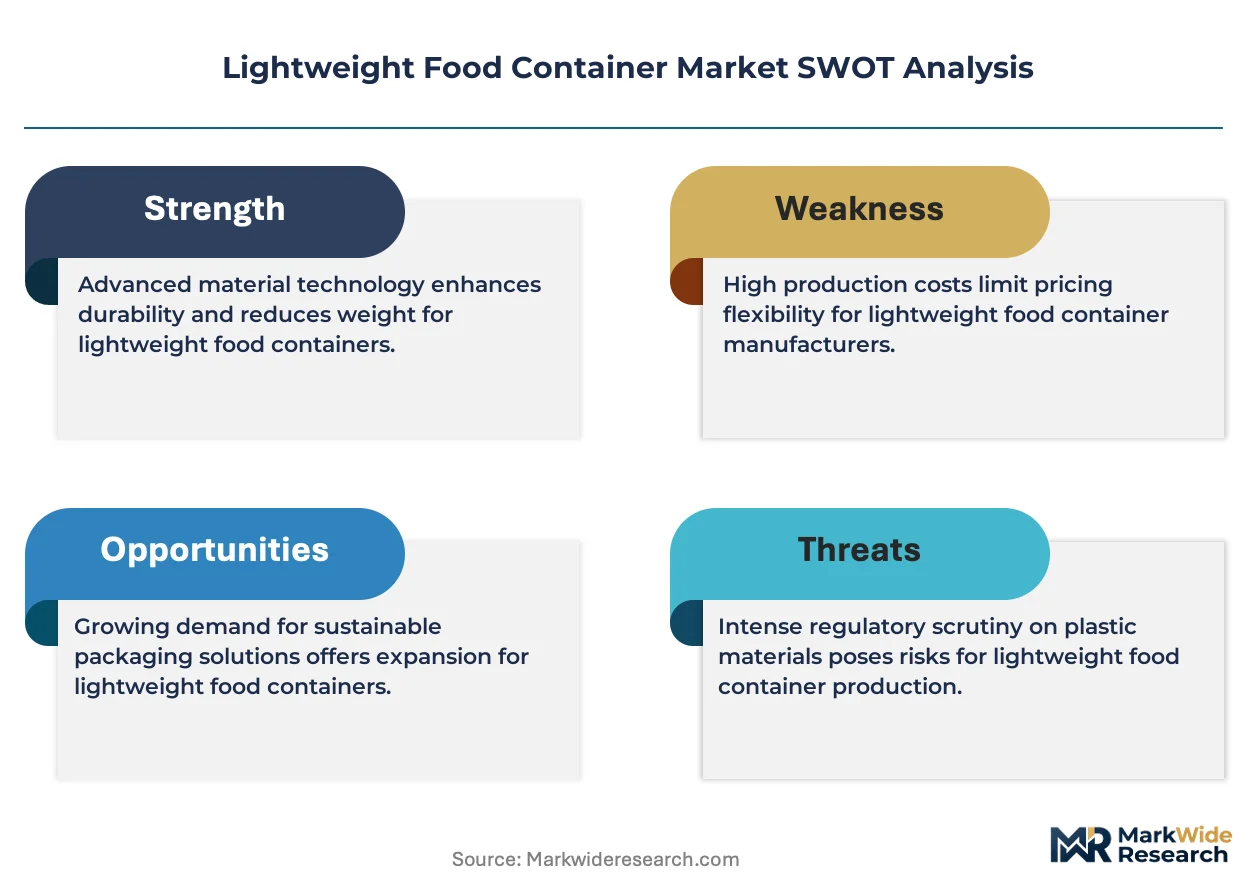
- Polypropylene:Heat tolerance above 120°C enables microwave-safe positioning across quick-service and retail channels. REACH framework restrictions on styrenic polymers redirect formulation R&D toward expanded polypropylene grades. European converters face material requalification costs favoring players with dedicated regulatory affairs teams.
- Compostable Plastics:PLA and PHA formulations require industrial composting infrastructure availability to validate environmental claims. SAMR GB standards in China create qualification delays for European biopolymer formulations entering mainland manufacturing. Certification fragmentation across EU, FDA, and Chinese notification protocols extends launch windows.
- Polystyrene:EU Green Deal restrictions on certain grades redirect investment toward alternative formulations. Legacy installed base in Southeast Asian markets sustains residual demand pending enforcement alignment.
- Bamboo Fiber:Natural fiber positioning commands premium pricing in sustainability-marketed segments. Supply concentration in Chinese processing regions exposes buyers to export documentation variability.
Polypropylene holds installed capacity. Compostable plastics are rotating up the share rankings.
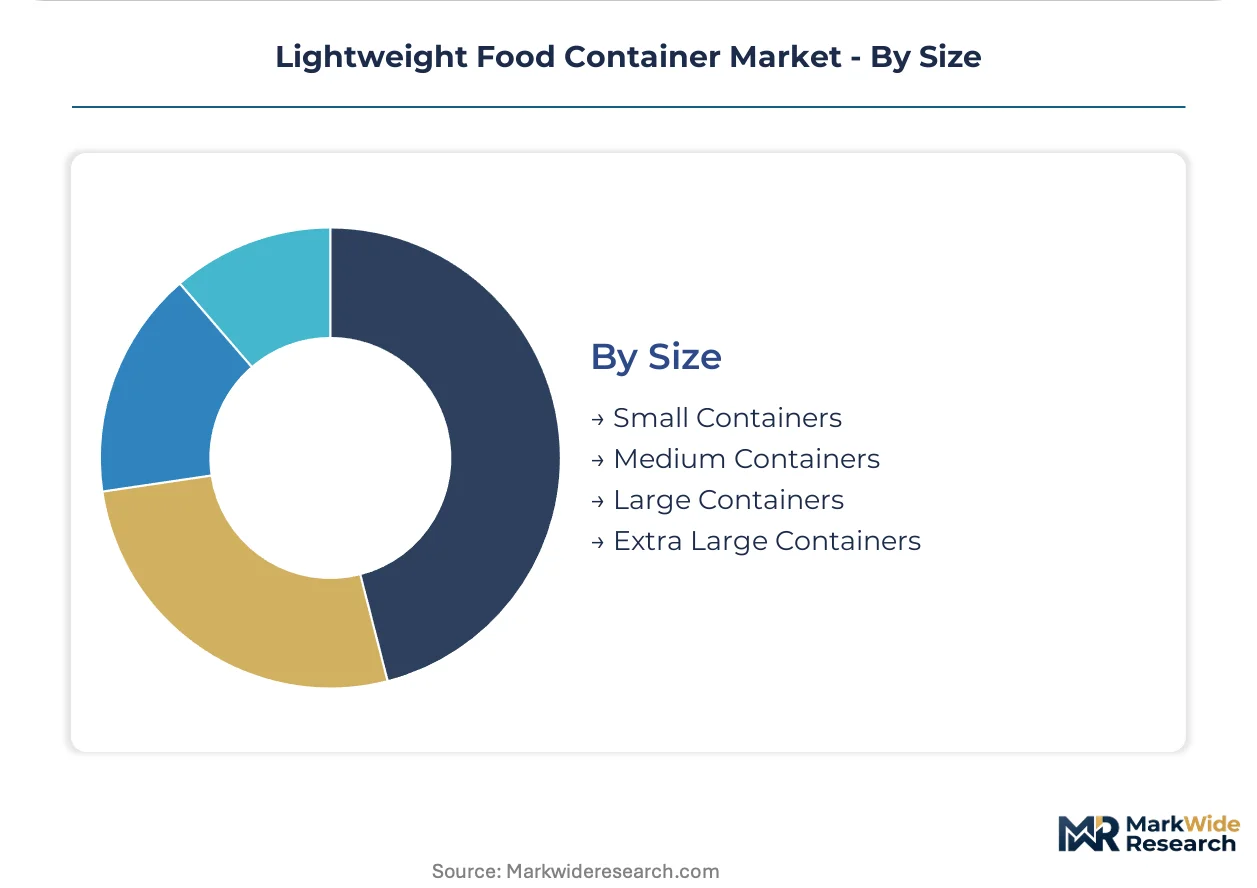
Size:
Volume throughput and logistics cube efficiency segment procurement behavior.
- Small Containers:Single-serve portions dominate sauce and condiment applications. Nestability ratios determine pallet density and freight cost allocation.
- Medium Containers:Standard meal portions concentrate demand in food delivery and takeaway channels. Lid interchangeability across diameter specifications reduces inventory complexity for operators.
- Large Containers:Family-size and sharing formats expand in Southeast Asian aggregator platforms. Structural rigidity requirements increase wall thickness specifications.
- Extra Large Containers:Catering and institutional volumes prioritize stack stability over material minimization. Reusable container substitution pressure intensifies at this scale threshold.
Medium containers hold installed capacity. Large containers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Europe's biopolymer import gateway, while Vietnam's Cai Mep-Thi Vai deepwater complex anchors Southeast Asian export capacity for EU-bound food packaging.
Germany
Quick-service chains accelerate polypropylene and PLA blend procurement to preempt EU Green Deal enforcement windows. ECHA's REACH framework restricts styrenic polymer grades, redirecting converter R&D toward certified compostable alternatives. Thermoforming specialists in North Rhine-Westphalia face material requalification costs that favor larger players with dedicated regulatory affairs teams.
Vietnam
Domestic food delivery platforms consolidate order volume into dedicated supply agreements with Ho Chi Minh City thermoformers. SAMR GB standards in China create qualification friction for European biopolymer formulations, redirecting some ASEAN sourcing toward Vietnamese converters. The manufacturing corridor near Cai Mep-Thi Vai serves both domestic aggregators and EU buyers seeking compliant ASEAN-origin supply.
United States
Modified atmosphere packaging demand sustains polypropylene container share in prepared meal distribution. FDA food contact notification protocols govern migration limits for recycled content incorporation, slowing but not blocking circular material adoption. Midwest injection molding clusters concentrate capacity for thin-wall designs below 0.5 millimeters.
France
Retail channels accelerate compostable plastic qualification timelines ahead of extended producer responsibility scheme expansions. ANSM food contact material oversight converges with EU Green Deal packaging mandates. Lyon-based converters specialize in thermoformed prepared meal formats competing on customization velocity.
China
SAMR enforces GB standards for plastics in food contact, creating compliance friction for imported biopolymer formulations. Domestic converters in the Yangtze River Delta region leverage captive resin supply to offset PLA and PHA price volatility. Shanghai-area thermoformers supply both domestic food delivery platforms and export buyers navigating multi-jurisdiction certification requirements.
Lightweight Food Container Market Competitive Landscape
On the supply side, the industry is consolidating around converters with dedicated regulatory affairs capabilities and rapid tool-change thermoforming assets. Tiered competitive positioning separates global film and rigid plastics specialists from regional customization-focused thermoformers. Three archetypes dominate: multinational material science conglomerates with global footprint leverage, mid-cap specialists competing on formulation speed, and regional converters anchored in Vietnam's export corridor. Dominant competitive moves include backward integration into resin supply and strategic partnerships with food delivery platforms to bypass traditional distribution layers.
Among the multinational material science tier, Amcor plc and Berry Global Inc. exemplify contrasting strategic positions. Amcor leverages its global film and rigid plastics footprint to anchor supply contracts with multinational quick-service chains. Berry Global occupies a position within the thermoformed container specialization vector, competing on customization speed for prepared meal formats rather than commodity volume. Tetra Pak represents the aseptic carton format anchor, sustaining R&D intensity in fiber-based barrier technologies for ambient-ready food applications.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global Inc. |
| Ardagh Group |
| Silgan Holdings Inc. |
| Plastipak Holdings, Inc. |
| Sonoco Products Company |
| Graham Packaging Company |
| Ball Corporation |
| Tetra Pak |
| Others |
Supply & Pricing Matrix
Overcapacity in Vietnam's Ho Chi Minh City thermoforming corridor compresses spot pricing for thin-wall polypropylene containers while simultaneously pressuring converters to absorb biopolymer feedstock volatility. This utilization dynamic concentrates bargaining power with food delivery platforms that consolidate volume into multi-year direct procurement agreements.
Pricing Analysis
Volume-discount tiering structures separate certified compostable premiums from commodity polypropylene baselines, with EU Green Deal compliance tiers commanding additional certification markups. Price differentiation rests on migration testing documentation depth and REACH framework qualification status. Pricing pressure stems from PLA and PHA resin volatility tied to agricultural harvest cycles. Food delivery platforms exhibit highest price sensitivity through consolidated tender processes, while institutional catering contracts show lowest sensitivity due to longer-term thermal performance specifications.
Supply Chain Analysis
EU export-control restrictions on certain styrenic polymer grades redirect material flows toward Vietnamese and Chinese converters with alternative formulation capabilities. Geographic supply concentration centers on Vietnam, China, and Germany, with raw material dependencies spanning polypropylene resin, PLA/PHA biopolymers, and aluminum sheet stock. Supply chain risk manifests through SAMR GB standard qualification delays for European biopolymer formulations entering Chinese manufacturing. Distribution runs through direct procurement partnerships that disintermediate traditional regional wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lightweight food container market functions as a regulatory-moat industry where EU Green Deal entrenchment creates switching costs through multi-jurisdiction certification requirements. Extended producer responsibility schemes deepen this structural advantage for incumbents with dedicated compliance infrastructure.
For Market Incumbents: Build regulatory-affairs moats by embedding ECHA REACH and FDA food contact notification expertise into product development workflows. Threats from emerging Vietnamese converters with rapid tool-change capabilities intensify margin pressure in commodity thermoforming segments. Capacity addition in the Cai Mep-Thi Vai corridor anchors ASEAN supply security. Certification investment in industrial composting infrastructure partnerships validates environmental claims for EU retail channels.
For New Entrants and Emerging Players: Pursue white-space positioning in aseptic carton barrier technologies for ambient-ready prepared meals, where fiber-based moisture resistance gaps persist. The most penetrable segment sits in medium-format biodegradable containers for German and French retail channels facing extended producer responsibility scheme expansions. Go-to-market execution hinges on direct platform partnerships with Vietnam's domestic food delivery aggregators that bypass legacy distribution markups.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap thermoforming specialists with backward integration into resin supply and established multi-jurisdiction qualification track records. Long-term viability across the analysis window favors converters with captive biopolymer sourcing that insulates margins from agricultural feedstock volatility. The signal to watch is SAMR GB standard harmonization progress that would accelerate European biopolymer entry into Chinese manufacturing corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive PLA and PHA sourcing insulates margins from agricultural feedstock harvest volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous EU REACH, FDA, and SAMR qualification compresses product launch windows for competitors. |
| Direct Platform Partnership Formation | Food delivery platform alliances in Vietnam bypass traditional wholesaler markups and anchor volume. |
| Rapid Tool-Change Capability Expansion | Thermoforming customization velocity displaces commodity rigid plastics in prepared meal segments. |
| Industrial Composting Infrastructure Partnership | Closed-loop material flows validate environmental claims under EU extended producer responsibility schemes. |
Research Methodology
Desk research of trade customs data, ECHA REACH registration databases, and FDA food contact notification filings preceded structured interviews with thermoforming plant managers, quick-service chain procurement directors, biopolymer R&D leads, and food delivery platform supply chain analysts. Secondary validation drew from converter capacity announcements, EU Green Deal implementation timelines, and SAMR GB standard update circulars. Bottom-up demand modeling across delivery platform order volumes triangulated with top-down material flow analysis.
Assumption sets held EU Green Deal enforcement timelines and SAMR GB standard stability fixed while varying biopolymer feedstock cost trajectories and food delivery platform consolidation rates across the projection horizon. Segmentation dimensions modeled include material chemistry tier, thermal performance specification, disposal pathway compliance, and regional regulatory cluster. CAGRs derived from installed capacity utilization trends and substitution elasticity estimates for compostable alternatives. Industry-specific forecast inputs encompassed PLA resin price series and inline vision system adoption curves for quality assurance digitization.
Sensitivities concentrate around SAMR GB standard revision timing, EU extended producer responsibility scheme rollout pace, and Vietnamese manufacturing corridor electricity cost trajectories. Forecasts reflect documented assumptions regarding regulatory enforcement alignment and platform procurement concentration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Coffee Capsules and Pod Packaging Market
Food Packaging
Microwaveable Liquid Food Packaging Market
Food Packaging
Pet Beverage Packaging Market
Food Packaging
Cake Box Market
Food Packaging
Probiotics Packaging Market
Food Packaging
PVDC Coating Food Packaging Market
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
Wooden Cutlery Market
Food Packaging
Foam Food Container Market
Food Packaging
Eco-Friendly Tea Packaging Market
Food Packaging
APAC Frozen Food Packaging Market
Food Packaging
Transparent Food Packaging Market
Food Packaging
North America Food Packaging Market
Food Packaging
Reclosable Food Packaging Market
Food Packaging
Meal Kit Packaging Market
Food Packaging
Cornstarch Packaging Market