
 Asia-Pacific Flexible Plastic Packaging Market | 2026-2036
Asia-Pacific Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Flexible Plastic Packaging Market Insights
India's Plastic Waste Management Rules is decoupling small-scale converters from established supply chains by mandating extended producer responsibility compliance that favors capital-rich operators. Amcor Plc leverages integrated film extrusion and converting assets across Australia and China to sustain cost advantages under these rules. UFlex Limited anchors its position through backward integration into polymer compounding and printing cylinder manufacturing in India. SCG Packaging dominates Thai flexible packaging through captive resin supply and regional logistics networks.
Asia-Pacific flexible plastic packaging encompasses polymer-based materials manufactured through blown or cast film extrusion, typically ranging from 20 to 150 microns in thickness, engineered to provide moisture, oxygen, and light barrier protection for consumer and industrial goods. The primary commercial purpose centers on reducing material usage, transportation cost, and shelf-space requirements versus rigid alternatives while preserving product integrity across distribution temperatures. Polyethylene films occupy the largest volume share due to cost efficiency in commodity food bags and stretch wrap applications, while bioplastics represent the fastest-expanding material category as brand owners in Japan and South Korea pursue carbon reduction commitments. Pouches capture expanding margin pools in retort and spouted formats for ready-to-eat meals and infant nutrition, displacing traditional metal cans and glass jars.
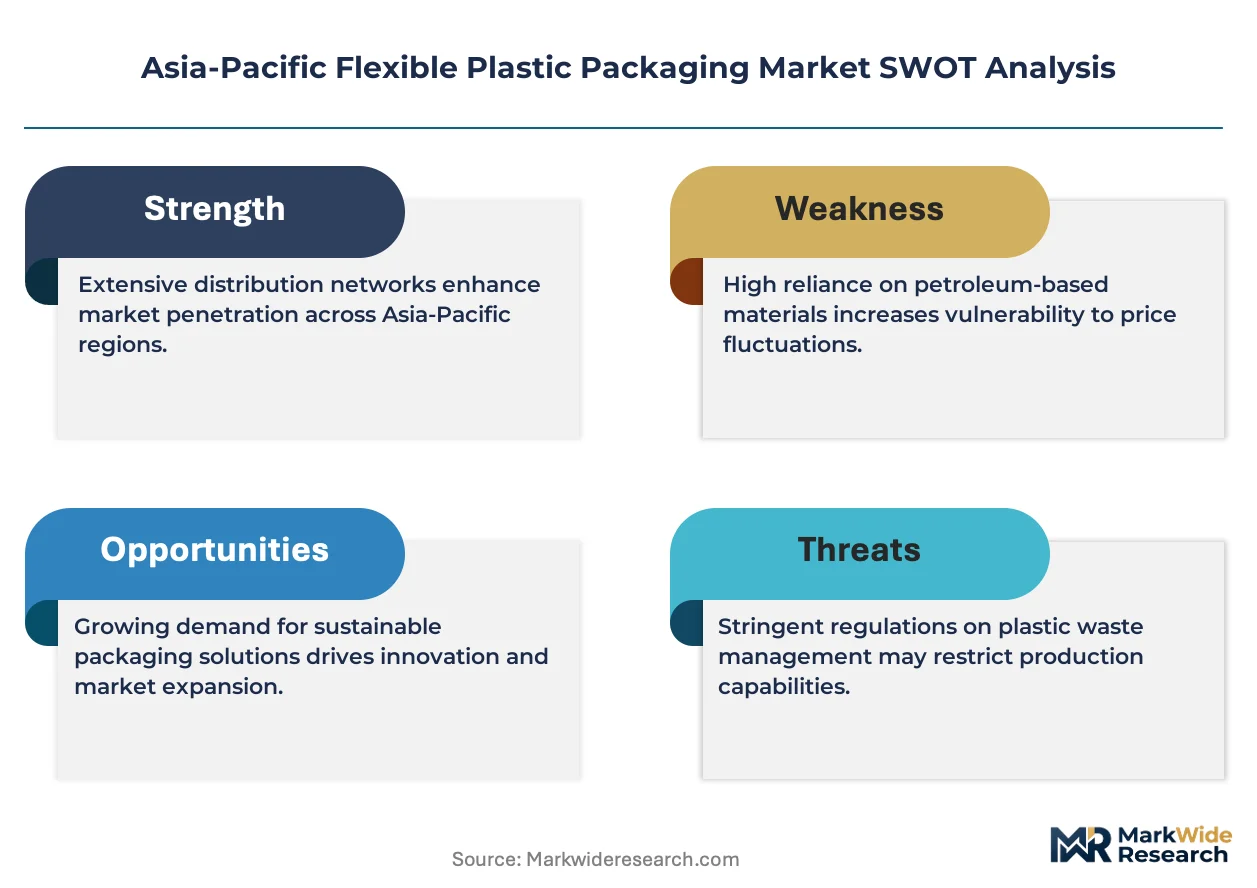
China's MEE enforces GB standards for recyclable packaging design that restrict non-separable multilayer constructions in major municipal jurisdictions. Japan's METI promotes mono-material flexible packaging through its Resource Circulation Strategy for Plastics, creating specification pull from food exporters serving Japanese retail. India's BIS certification requirements for food-contact plastics add testing cost layers that filter out informal competitors. Stakeholders must monitor enforcement variance across provincial environmental bureaus and prefectural governments to anticipate compliance cost trajectories and capacity relocation incentives.
Market Dynamics
India's Plastic Waste Management Rules are forcing capital reallocation toward EPR-compliant infrastructure, decoupling small converters from resin suppliers and redirecting volume toward integrated film extruders with captive recycling capacity.
Growth Catalysts
- High-barrier pouch specification:Southeast Asian food processors are scaling retort-capable pouch procurement for shelf-stable proteins, displacing metal can formats in ambient distribution channels.
- MEE recyclable design mandates:China's GB standards for separable multilayer constructions are accelerating converter investment in mono-material extrusion lines across the Yangtze River Delta cluster.
- Bioplastics carbon commitments:Brand owners in Japan and South Korea are specifying PLA and bio-PE films to meet Scope 3 reduction targets in food and personal care packaging.
Market Restraints
- Resin price volatility:Ethylene and propylene feedstock costs swing with naphtha-cracker margins in Singapore and South Korea, compressing converter gross margins on fixed-price annual contracts.
- Multilayer technical lock-in:Existing high-barrier films using EVOH and metallized layers cannot meet China's new separability requirements without full line replacement.
- BIS certification friction:India's food-contact testing protocols add 8-12 week approval timelines that filter informal competitors from formal retail supply chains.
Strategic Opportunities
- Vietnam manufacturing expansion:Converters are relocating blown film capacity to Binh Duong province to serve ASEAN export demand while evading China's environmental compliance cost escalation.
- Chemical recycling feedstock:Pyrolysis-based plastic waste processing is creating certified circular polymer streams for flexible packaging in Japan's Kansai industrial corridor.
- E-commerce pouch formats:Stand-up pouches with reseal zippers are capturing parcel-packaging demand from corrugated boxes in China's domestic retail fulfillment networks.
Industry Challenges
- Mono-material conversion engineering:Converters lack polymer science talent to reformulate barrier properties without EVOH layers, delaying product recertification.
- Legacy printing cylinder obsolescence:Rotogravure systems configured for multilayer substrates require complete re-tooling for thinner mono-material films, stranding capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Flexible Plastic Packaging Market |
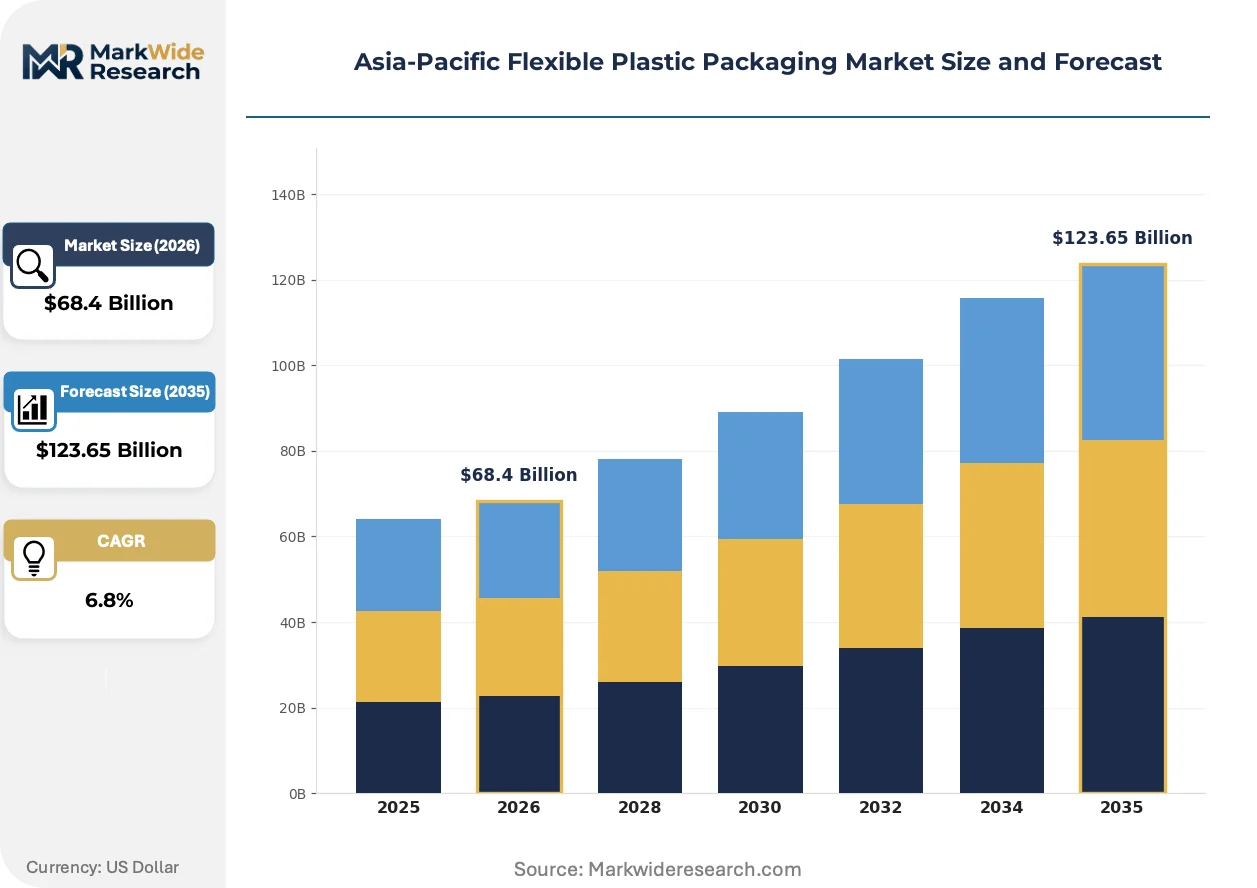
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Pouches, Films, Liners Material: Polyethylene, Polypropylene, PVC, Bioplastics End User: Food, Healthcare, Personal Care, Industrial Technology: Extrusion, Printing, Lamination, Coating |
| Companies Covered | Amcor Plc, UFlex Limited, Huhtamaki India Ltd., SCG Packaging (SCGP), TOPPAN Inc., Sonoco Products Company, Sealed Air Corporation, Mondi plc, Huhtamaki Oyj, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Flexible Plastic Packaging Market Trends and Innovations
Active barrier technologies and regulatory design mandates are compressing the viable technology set for flexible packaging, while procurement centralization among retail chains is rewriting converter-customer contracting norms.
Digital printing is absorbing short-run customization demand from rotogravure for seasonal food promotions and private-label variants. Japanese confectionery brands are adopting HP Indigo and Fujifilm inkjet systems for 5,000-50,000 unit production lots. This technology is absorbing margin previously captured by cylinder engraving houses and enabling just-in-time label-to-pouch workflows that compress working capital cycles.
Japan's METI Resource Circulation Strategy for Plastics is mandating mono-material flexible packaging specifications for imported food products by 2030. Japanese retail chains are transmitting these requirements upstream to Southeast Asian suppliers through technical audit protocols. Thai and Indonesian converters serving Aeon and Seven-Eleven Japan are re-engineering laminate structures to eliminate PET/PE/Al foil combinations.
Centralized procurement by supermarket chains is consolidating supplier panels and unbundling technical service from material supply. Woolworths Australia and Dairy Farm Asia are implementing direct-to-converter tendering for private-label flexible packaging, displacing traditional merchant broker networks. This pattern concentrates most visibly in Australia's retail sector, where two chains control 65% of food packaging specification authority.
Asia-Pacific Flexible Plastic Packaging Market Segmentation
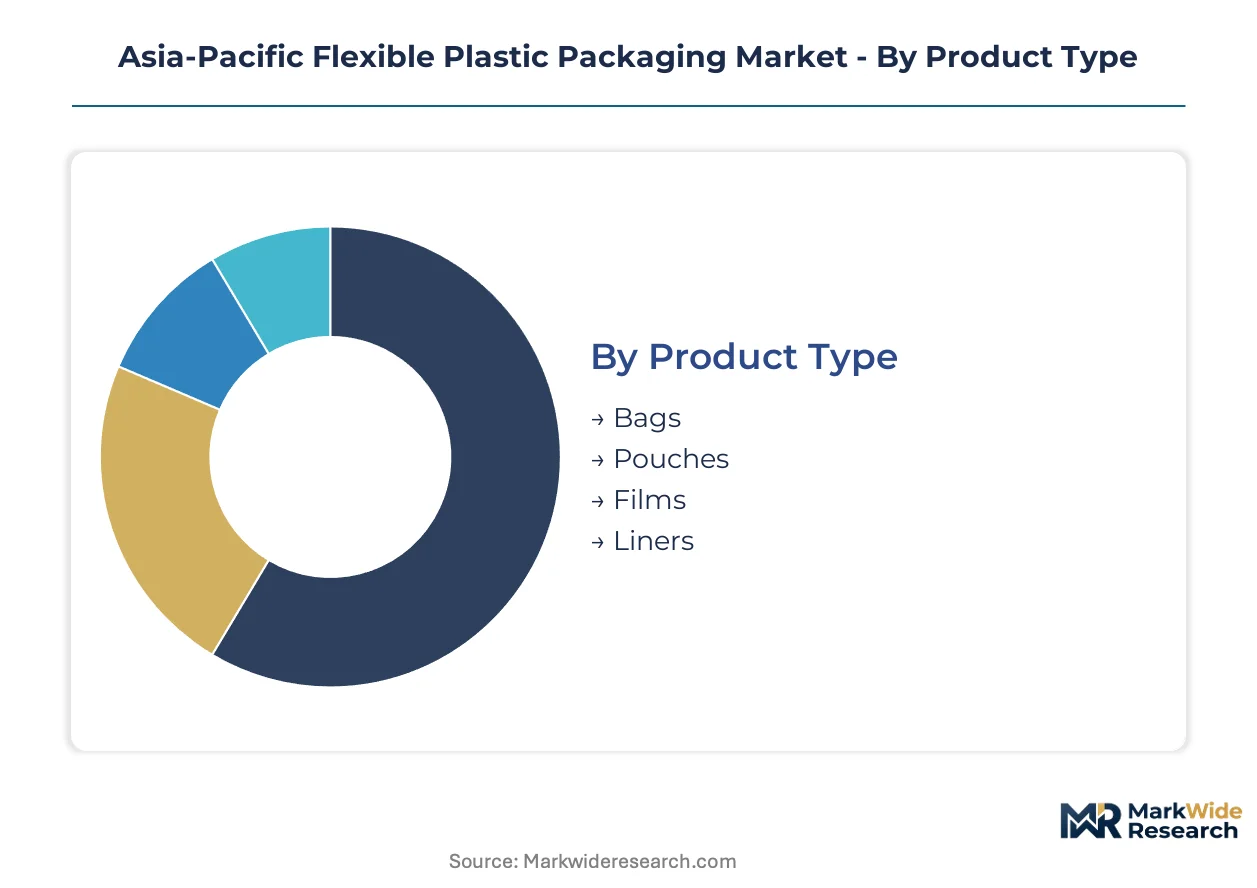
Flexible plastic packaging buyers in Asia-Pacific prioritize barrier performance, recyclability compliance, and line-speed compatibility when selecting formats and materials. Segmentation reveals where capital investment concentrates across converter operations and which specifications command pricing premiums in procurement negotiations.
Product Type:
Volume buyers select formats based on filling-line retrofit costs and shelf-visibility requirements versus distribution durability.
- Bags:Side-seal and bottom-gusset configurations dominate commodity food and agricultural applications across India's informal retail channels. Converters in Vietnam's Binh Duong province supply polyethylene bags for ASEAN rice and fertilizer export markets where cost minimization overrides premium features.
- Pouches:Retort-capable and spouted formats displace metal cans in Southeast Asian shelf-stable protein distribution. Thailand's SCG Packaging and China's Yangtze River Delta converters capture margin pools from Japanese retail chains specifying mono-material recyclable structures under METI guidelines.
- Films:Cast and blown extrusion outputs serve stretch wrap and lidding applications for Australian fresh produce logistics.
- Liners:Bulk container and drum inserts protect industrial chemicals and food ingredients during maritime shipping from Chinese port clusters.
Pouches lead on scale; bioplastics-compatible pouch formats lead on momentum.
Material:
Raw material selection tracks regulatory pressure on recyclability and brand-owner carbon reduction commitments across the region.
- Polyethylene:LDPE and LLDPE films occupy the largest volume position due to cost efficiency in commodity food bags and stretch wrap. China's MEE recyclable design mandates are forcing converters toward mono-material PE constructions that eliminate incompatible multilayer barriers.
- Bioplastics:PLA and bio-PE films are climbing fastest as Japanese and South Korean food and personal care brand owners pursue Scope 3 emission targets. UFlex Limited's polymer compounding operations in India supply certified bio-based resins for export-compliant packaging.
- Polypropylene:Cast PP films provide clarity and moisture barrier for snack food and confectionery lidding in high-humidity Southeast Asian climates.
- PVC:Shrink film and blister pack applications persist in pharmaceutical and industrial sectors despite recyclability constraints.
Polyethylene dominates procurement tonnage; bioplastics commands the steepest expansion trajectory.
End User:
Customer concentration in modern retail chains is consolidating specification authority and unbundling technical service from material supply.
- Food:Processors across Southeast Asia scale high-barrier pouch procurement for shelf-stable proteins and ready-to-eat meals. Woolworths Australia and Dairy Farm Asia implement direct-to-converter tendering for private-label flexible packaging, displacing traditional merchant broker networks.
- Healthcare:Sterile barrier films and blister packaging for pharmaceutical distribution face India's BIS certification requirements that add testing cost layers filtering informal competitors.
- Personal Care:Stand-up pouches with reseal zippers capture demand from rigid bottles in China's domestic e-commerce fulfillment networks.
- Industrial:Heavy-duty sacks and container liners serve construction chemicals and agricultural inputs across Indonesian and Vietnamese manufacturing zones.
Food commands volume concentration; healthcare drives specification complexity.
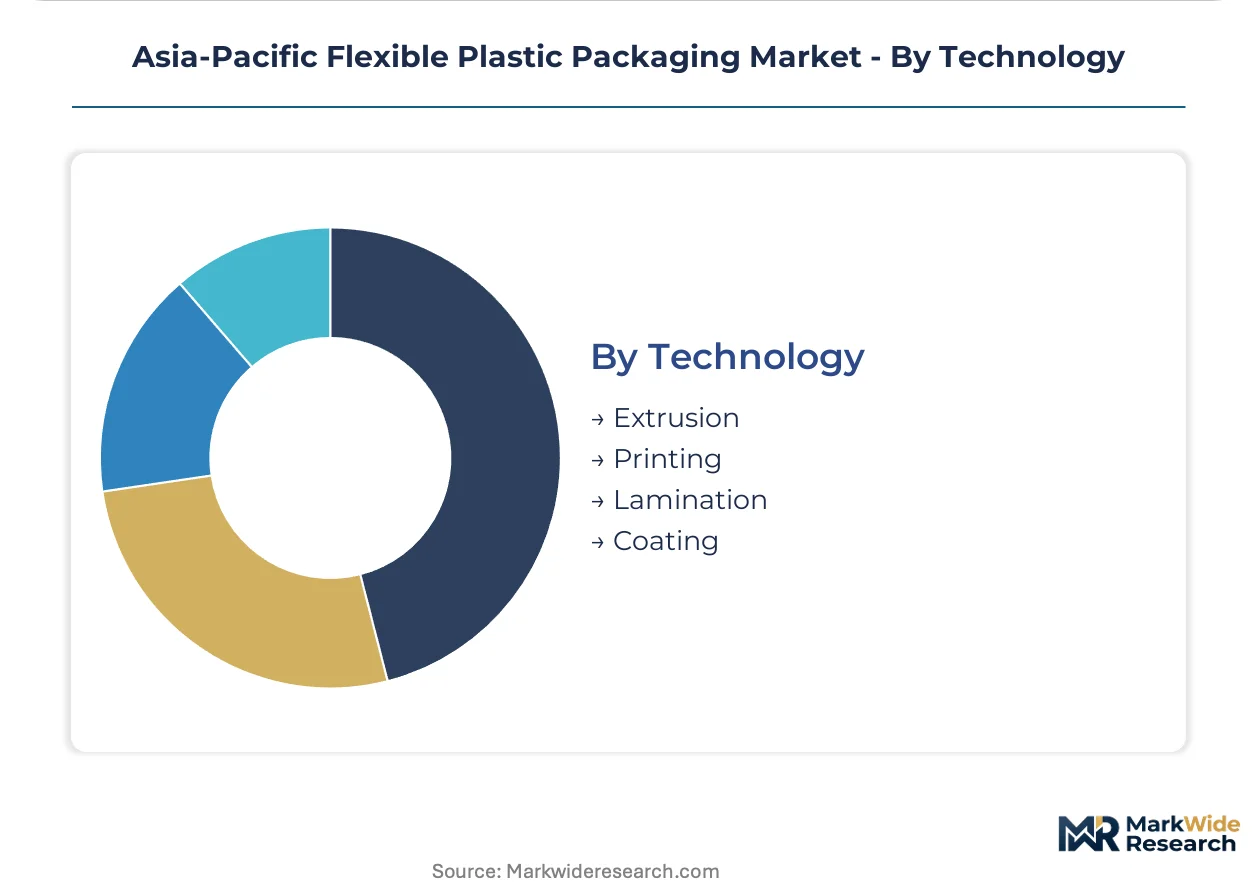
Technology:
Equipment investment priorities reflect regulatory mandates on separable multilayer constructions and shorter production runs for private-label variants.
- Extrusion:Blown and cast film lines are the foundational manufacturing stage across the Yangtze River Delta and Thailand's Eastern Economic Corridor. Amcor Plc leverages integrated extrusion assets across Australia and China to sustain cost advantages under India's EPR compliance rules.
- Printing:Digital inkjet systems absorb short-run customization demand from rotogravure for seasonal promotions. Japanese confectionery brands adopt HP Indigo and Fujifilm platforms for 5,000-50,000 unit lots, compressing working capital cycles.
- Lamination:Adhesive and extrusion lamination lines bond multilayer structures, though China's GB standards on separability are accelerating converter investment in mono-material alternatives.
- Coating:Barrier coatings and metallization provide oxygen and moisture protection for retort applications in ambient distribution channels.
Extrusion anchors capital deployment; digital printing gains share fastest in short-run segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer science talent concentrates in the Yangtze River Delta, Mumbai-Pune corridor, and Bangkok's Eastern Economic Corridor, anchoring converter operations that serve both domestic retail and export channels across the region.
China
Food processors in the Yangtze River Delta are scaling mono-material pouch procurement to meet MEE recyclable design mandates. GB standards for separable multilayer constructions are forcing converter investment in PE-only extrusion lines. Suzhou and Ningbo host the densest clusters of film extruders serving Japanese retail export specifications.
India
EPR compliance requirements under Plastic Waste Management Rules are redirecting volume toward integrated operators with captive recycling infrastructure. BIS certification timelines for food-contact applications filter informal competitors from formal retail supply chains. Gujarat's polymer compounding belt and Maharashtra's converting corridor concentrate backward-integrated capacity.
Japan
METI's Resource Circulation Strategy for Plastics is mandating mono-material specifications for imported food packaging by 2030. Brand owners in the Kansai industrial corridor are specifying PLA and bio-PE films for Scope 3 reduction targets. Osaka-based converters are re-engineering laminate structures to eliminate metallized barriers for ASEAN suppliers.
Thailand
SCG Packaging's captive resin supply anchors flexible packaging production across the Eastern Economic Corridor. Converters serving Aeon and Seven-Eleven Japan are eliminating PET/PE/Al foil combinations to pass technical audit protocols. Binh Duong province across the border in Vietnam is absorbing relocated blown film capacity from Chinese environmental compliance cost escalation.
Australia
Woolworths and Coles control 65% of food packaging specification authority through centralized procurement tendering. Direct-to-converter contracting for private-label flexible packaging is displacing traditional merchant broker networks. Melbourne and Sydney converters are investing in digital printing for short-run seasonal promotions.
Asia-Pacific Flexible Plastic Packaging Market Competitive Landscape
The competitive structure tilts toward integrated film extruders with captive recycling capacity and regional logistics networks. Capital requirements for EPR compliance and mono-material line conversion are consolidating procurement relationships around operators with backward-integrated polymer compounding. Two archetypes dominate: multinational converters with integrated extrusion assets across multiple countries, and regional specialists leveraging captive resin supply and domestic distribution density. Competitive moves center on capacity relocation to Vietnam and Indonesia to evade China's environmental compliance costs, and chemical recycling partnerships to secure certified circular polymer feedstock.
Among Asia-Pacific-based converters, Amcor Plc, UFlex Limited, and SCG Packaging exemplify the integrated archetype. Amcor's Australian and Chinese extrusion assets sustain cost advantages under India's EPR rules. UFlex anchors its position through in-house polymer compounding and printing cylinder manufacturing in India. SCG Packaging dominates Thai flexible packaging through captive resin supply and regional logistics networks serving Japanese retail chains.
| Leading Market Players |
|---|
| Amcor Plc |
| UFlex Limited |
| Huhtamaki India Ltd. |
| SCG Packaging (SCGP) |
| TOPPAN Inc. |
| Sonoco Products Company |
| Sealed Air Corporation |
| Mondi plc |
| Huhtamaki Oyj |
| Others |
Pricing and Supply Chain Analysis
Centralized procurement by Woolworths Australia and Dairy Farm Asia is unbundling technical service from material supply, forcing converters to absorb specification engineering costs or surrender margin to retain volume.
Pricing Analysis
The bundled-vs-unbundled service split is rewriting contract economics across Asia-Pacific flexible packaging. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with EPR-compliant integrated operators commanding premium positioning. Cost compression in commodity polyethylene bags is intensifying because Vietnam-based converters are undercutting Yangtze River Delta pricing for ASEAN rice export markets. Informal competitors in India's unorganized sector exhibit highest price sensitivity, while Japanese retail chains specifying mono-material structures under METI guidelines show least sensitivity.
Supply Chain Analysis
Dual-sourcing requirements from Japanese retail chains are forcing Southeast Asian converters to qualify secondary film extruders, fragmenting volume concentration. Raw material supply draws from naphtha-cracker outputs in Singapore and South Korea, bioplastic resin streams from Japan's Kansai corridor, and recycled polymer feedstock from India's Gujarat compounding belt. Single-source vulnerability concentrates in metallized barrier film supply from Chinese port clusters. Distribution runs through regional logistics networks anchored by SCG Packaging's captive resin infrastructure and UFlex's polymer compounding operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a regulatory compounder where India's Plastic Waste Management Rules and China's MEE recyclable design mandates are accelerating demand migration toward EPR-compliant integrated operators.
For Market Incumbents: Hedge against margin erosion from Vietnam-based cost competition by securing captive recycling capacity and backward integration into polymer compounding. Amcor Plc's integrated extrusion assets across Australia and China demonstrate how regional logistics density defends position against informal competitors filtered by BIS certification timelines. Prioritize mono-material line conversion to meet METI's 2030 specifications for Japanese retail access. For New Entrants and Emerging Players: Japanese retail technical audit protocols offer a channel partner route for Southeast Asian converters lacking legacy multilayer infrastructure. White-space targets include bio-PE film supply for South Korean brand-owner Scope 3 commitments and chemical recycling feedstock partnerships in Japan's Kansai industrial corridor. The most penetrable segment is Vietnam's Binh Duong province, where relocated Chinese capacity has not yet saturated ASEAN export demand. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing captive resin supply and domestic distribution density. Long-term viability hinges on EPR compliance infrastructure and mono-material conversion capability, with acquisition targets clustering around integrated film extruders in India's Maharashtra converting corridor. The signal to watch is enforcement variance across China's provincial environmental bureaus, which will determine capacity relocation incentives and feedstock cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-material Line Conversion | MEE's GB standards on separable multilayer constructions are stranding legacy EVOH barrier capacity across Yangtze River Delta converters. |
| Backward Integration into Polymer Compounding | UFlex Limited's in-house resin operations demonstrate how captive supply secures margin under India's EPR compliance cost escalation. |
| Chemical Recycling Partnership | Pyrolysis-based plastic waste processing in Japan's Kansai corridor is creating certified circular polymer streams for flexible packaging. |
| Capacity Relocation to Vietnam | Binh Duong province is absorbing blown film capacity from Chinese environmental compliance cost escalation while serving ASEAN export demand. |
| Digital Printing Platform Investment | HP Indigo and Fujifilm inkjet systems are compressing working capital cycles for Japanese confectionery brands' seasonal promotion runs. |
Research Methodology
Multiple input streams — primary interviews with film extrusion plant managers, polymer compounding technical directors, and retail procurement leads at Woolworths and Dairy Farm Asia; secondary validation through customs trade data, BIS certification registries, and MEE enforcement disclosures; plus SEC filings from listed packaging converters — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation anchored volume and value outputs across the analysis window, with segmentation dimensions spanning product type, material category, end-use vertical, and technology platform. CAGRs were derived from modeled substitution rates of metal cans by retort pouches, EPR compliance cost pass-through elasticities, and bioplastic specification trajectories in Japanese and South Korean brand-owner procurement.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to enforcement variance across China's provincial environmental bureaus, naphtha-cracker margin volatility in Singapore and South Korea, and METI's technical audit protocol evolution for ASEAN suppliers. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flexible Packaging
Stretch Packaging Market
Flexible Packaging
Flexible Containers Market
Flexible Packaging
Africa Flexible Packaging Market
Flexible Packaging
North America Flexible Packaging Market
Flexible Packaging
Litho Laminated Packaging Market
Flexible Packaging
APAC Flexible Packaging Market
Flexible Packaging
Kenya Flexible Packaging Market
Flexible Packaging
Multilayer Flexible Packaging Market
Flexible Packaging
Brazil Flexible Plastic Packaging Market
Flexible Packaging
Canada Flexible Packaging Market
Flexible Packaging
Global Breathable Films Market
Flexible Packaging
Argentina Flexible Plastic Packaging Market
Flexible Packaging
Thermoforming Packaging Market
Flexible Packaging
Flexible Bottle Market
Flexible Packaging
Germany Flexible Plastic Packaging Market
Flexible Packaging
Global Flexible Plastic Packaging Market