
 Fiber Drums Market | 2026-2036
Fiber Drums Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Drums Market Intelligence
The integration of advanced barrier coatings and plastic-lined composites is reconfiguring the performance capabilities of traditional fiber drums, allowing them to handle a wider range of semi-liquids and sensitive chemicals. Greif, Inc. leverages its global manufacturing footprint to serve multinational chemical clients. Mauser Packaging Solutions competes with a diverse portfolio of rigid and composite packaging, while Sonoco Products Company differentiates through its deep expertise in paper science and sustainable materials.
Fiber drums are composite shipping containers constructed from multiple layers of wound Kraft paper or corrugated fiberboard, often sealed with steel or fiber lids. Their primary function is the secure transport and storage of dry, granular, and semi-solid materials. The chemicals and pharmaceuticals industries represent the largest end-user segments, demanding high-purity packaging solutions. Open head designs with capacities above 60 liters dominate industrial applications for their ease of filling and emptying bulk powders.
Compliance with UN recommendations for the transport of dangerous goods is a critical market access requirement for chemical applications. Regulations from the US FDA and the European Union's REACH framework govern material safety for pharmaceutical and food-grade products. Consequently, producers must navigate the trade-off between incorporating higher-performance liners and meeting sustainability mandates for full recyclability.
Market Dynamics
The central dynamic is the push for sustainability, driven by regulations like the EU Green Deal, which favors recyclable materials while demanding higher performance for sensitive applications in pharmaceuticals and chemicals.
Growth Catalysts
- Regulatory Alignment:The EU Green Deal and similar global initiatives favor paper-based, recyclable packaging, creating a supportive policy environment for fiber drums over less sustainable alternatives.
- Pharmaceutical Demand:The need for contamination-free, single-use containers for transporting active pharmaceutical ingredients and excipients supports adoption of high-purity fiber drums.
- Chemical Sector Needs:Germany's concentrated chemical industry requires compliant packaging for powders and granular materials, sustaining strong regional demand for UN-rated drums.
Market Restraints
- Substitution Threat:Rigid plastic drums and intermediate bulk containers (IBCs) offer superior performance for many liquids and aggressive chemicals, limiting fiber drum applications.
- Input Cost Volatility:Fluctuations in the global price of Kraft paper, the primary raw material, directly impact manufacturer margins and create pricing instability for end-users.
- Performance Limitations:Standard fiber drums possess inherent moisture sensitivity, restricting their use in humid climates or for water-based products without costly specialized liners.
Strategic Opportunities
- Emerging Applications:The growing battery sector creates an opportunity for specialized fiber drums designed for the safe transport of hazardous materials like lithium-ion battery components.
- Smart Packaging Integration:Incorporating RFID or QR code technology into drum lids and bodies enables enhanced traceability, a key requirement for pharmaceutical and food-grade supply chains.
- Geographic Expansion:Underpenetrated markets in India and Southeast Asia offer significant growth potential as their domestic chemical and pharmaceutical manufacturing capabilities expand.
Industry Challenges
- Recycling Infrastructure Gaps:The challenge of separating composite drums with plastic liners or metal components from the pure fiber waste stream complicates recyclability claims and processes.
- Compliance Complexity:Adhering to divergent international standards for dangerous goods transport, such as UN recommendations and specific national deviations, requires significant regulatory expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Drums Market |
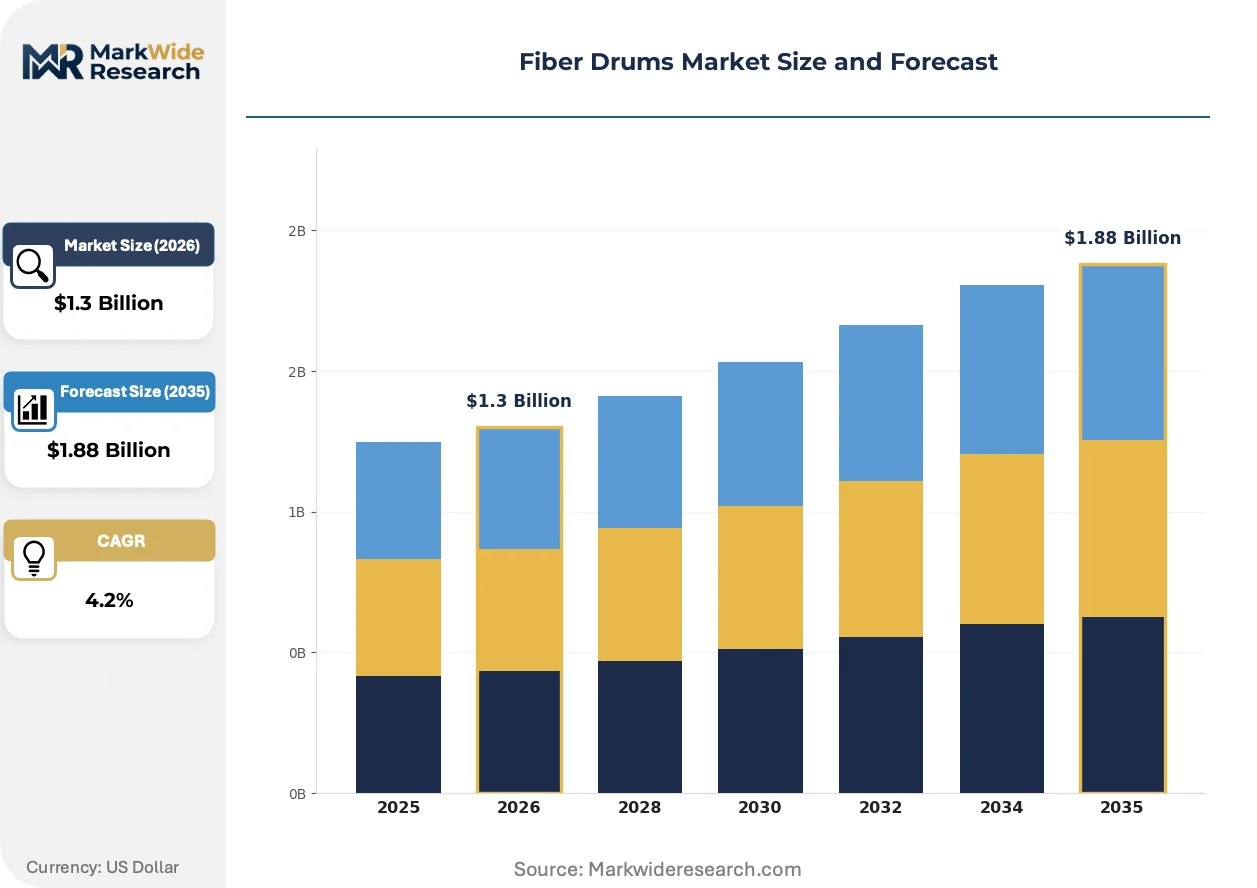
| Market Size in 2026 | $1.3 Billion |
| Market Size in 2035 | $1.88 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed Head, Open Head, Metal-Poly Lined, Plastic-Lined, Mason Lined Capacity: 10-20 Liters, 21-40 Liters, 41-60 Liters, Above 60 Liters Material: Kraft Paper, Corrugated Fiberboard, Phenolic Resin, Polyethylene, Aluminum Lining End User: Chemicals Industry, Agrochemical Sector, Food & Beverages, Pharmaceuticals, Paints & Coatings |
| Companies Covered | Snyder Industries, C.L. Smith, Greif, Inc., Industrial Container Services, Smurfit Kappa, Mauser Packaging Solutions, Fibrestar Drums Limited, Enviro-Pak, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Drums Market Strategic Shifts & Innovations
Material science advancements are expanding the addressable market for fiber drums. Innovations in barrier technologies and composite structures enable these containers to meet performance requirements previously exclusive to plastic and metal packaging.
Advanced multi-layer barrier coatings serve as a critical performance-enhancing technology. The specialty chemical and food ingredient sectors are adopting these to protect sensitive contents from moisture and oxygen ingress. This innovation is collapsing the functional divide separating fiber drums from more robust rigid packaging formats for semi-solid goods.
European Union directives, specifically the REACH framework, mandate stringent documentation of material safety. This creates an industrial requirement for packaging that guarantees product purity and prevents chemical leaching from the container. The pharmaceuticals segment is most affected, requiring drum suppliers to provide extensive validation data for all product-contact materials.
A shift in buyer behavior is evident as procurement teams in food and pharmaceutical sectors prioritize supply chain transparency. This change elevates the importance of certifications, like those from the Forest Stewardship Council (FSC), over lowest-cost sourcing. This is most pronounced in North America and Europe, where brand reputation is tied to sustainable sourcing.
Fiber Drums Market Segmentation
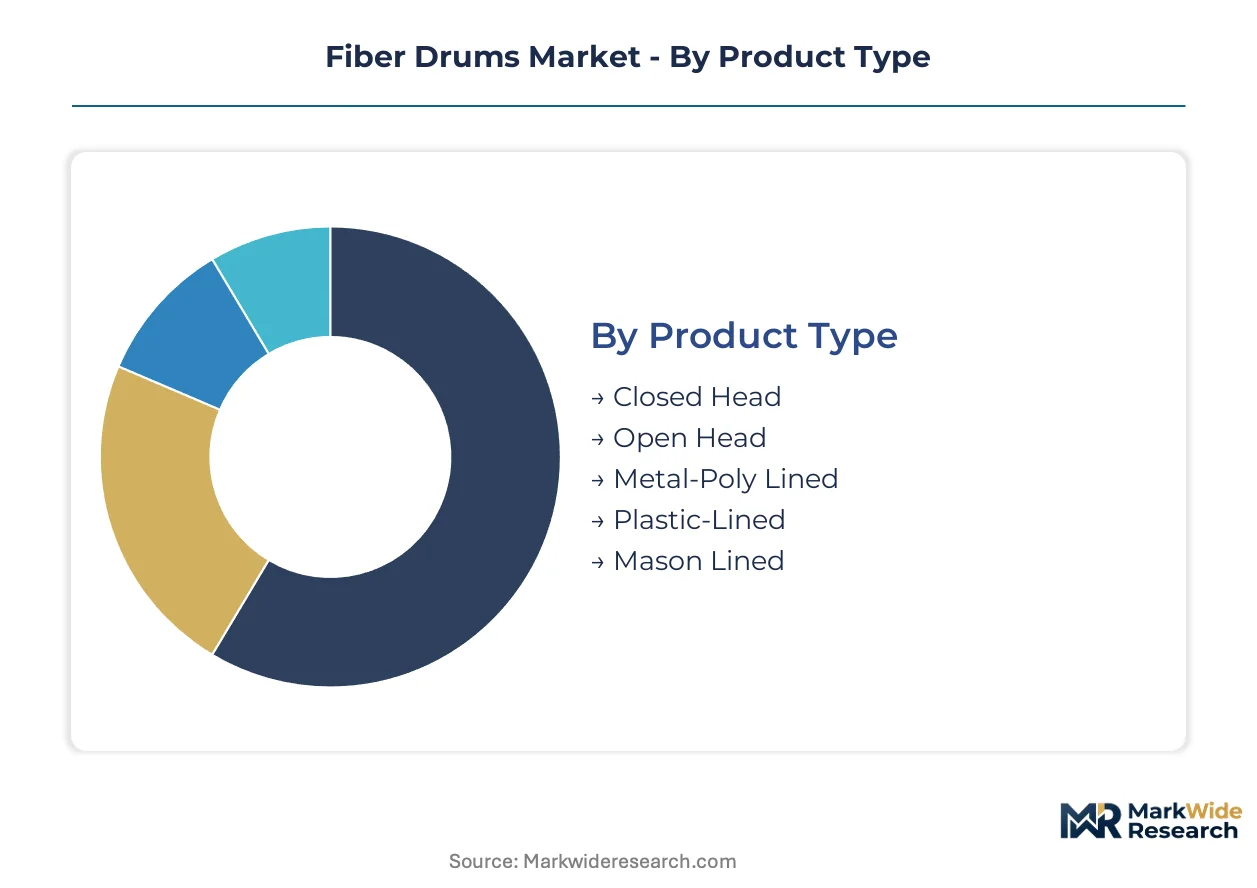
Understanding the varied requirements across end-user industries is critical for navigating the fiber drums market. The market segments based on product type, capacity, material, and end user, each presenting distinct performance demands and regulatory compliance needs. These classifications help clarify where innovation in barrier technologies and sustainable materials is most impactful.
Product Type:
The turnover rate for different fiber drum product types varies significantly, driven by application and reusability profiles. Single-use containers often exhibit faster cycle times compared to specialized, higher-value drums designed for multiple trips or extended storage.
- Closed Head:These drums feature a permanently affixed top, typically with small openings for filling and dispensing, suited for non-volatile liquids or semi-solids where product integrity is paramount.
- Open Head:These drums feature a removable lid, secured by a lever-lock or bolt ring, facilitating easy filling and emptying of bulk powders and granular materials in industrial settings. Demand for these designs is particularly strong in the chemicals industry for efficient material handling.
- Metal-Poly Lined:These drums integrate a metal layer and polymer lining within the fiberboard structure, providing enhanced barrier properties against moisture, oxygen, and chemical permeation. The pharmaceuticals sector increasingly adopts these for active pharmaceutical ingredients requiring stringent purity.
- Plastic-Lined:Fiber drums incorporating internal plastic liners offer improved moisture resistance and chemical compatibility compared to standard fiberboard. These are frequently used for food ingredients and some specialty chemicals where direct product contact with fiber is undesirable.
- Mason Lined:Featuring an internal lining of masonite or similar hardboard, these drums provide additional structural rigidity and impact resistance. They serve applications requiring robust packaging for dense or abrasive materials.
Open Head designs dominate the installed base for bulk industrial applications. Metal-Poly Lined drums are where expansion concentrates due to rising demand for enhanced barrier performance.
Capacity:
The market's volume distribution is heavily skewed towards larger capacity fiber drums, reflecting their primary use in industrial bulk material transport. Smaller capacities serve niche applications requiring precise batching or specialized handling.
- 10-20 Liters:These smaller drums typically serve laboratory applications, specialty chemical samples, or high-value pharmaceutical excipients requiring precise quantities.
- 21-40 Liters:This mid-range capacity supports intermediate batch sizes for chemical formulations or food ingredients where larger volumes are impractical.
- 41-60 Liters:Drums in this capacity range are widely employed for semi-bulk quantities of powders and granules across various industrial sectors. They find significant use in the paints and coatings industry for pigment and additive transport.
- Above 60 Liters:These large-capacity drums represent the core of industrial fiber drum applications, facilitating the efficient transport and storage of bulk materials. The chemicals industry relies heavily on these for raw material and finished product logistics, particularly for UN-rated goods.
The segment for drums Above 60 Liters accounts for the largest share of market volume. The 41-60 Liters segment is experiencing consistent growth, driven by manufacturing scale-up in emerging markets.
Material:
The cost structure of fiber drums is primarily influenced by the choice and layering of materials, with advanced barrier components adding to the overall expense. Basic Kraft paper drums offer the lowest initial cost, while composite structures command a premium.
- Kraft Paper:This forms the foundational structural component of most fiber drums, providing inherent strength and recyclability.
- Corrugated Fiberboard:Used for enhanced rigidity and cushioning, corrugated fiberboard layers contribute to the drum's structural integrity.
- Phenolic Resin:Applied as a coating or impregnant, phenolic resin provides chemical resistance and improved barrier properties for specific contents.
- Polyethylene:This polymer is extensively used for internal liners and coatings, offering moisture protection and chemical inertness. The pharmaceuticals industry mandates high-purity polyethylene liners for product contact.
- Aluminum Lining:Incorporating aluminum foil within the drum structure creates a superior barrier against moisture and oxygen, crucial for highly sensitive chemicals and food ingredients.
Kraft Paper remains the most widely utilized base material due to its cost-effectiveness and sustainability profile. Polyethylene-based materials are seeing increased investment for their functional versatility in barrier applications.
End User:
The customer type for fiber drums dictates specific compliance, purity, and performance requirements, influencing material selection and design. Industries handling sensitive or hazardous materials drive demand for specialized solutions.
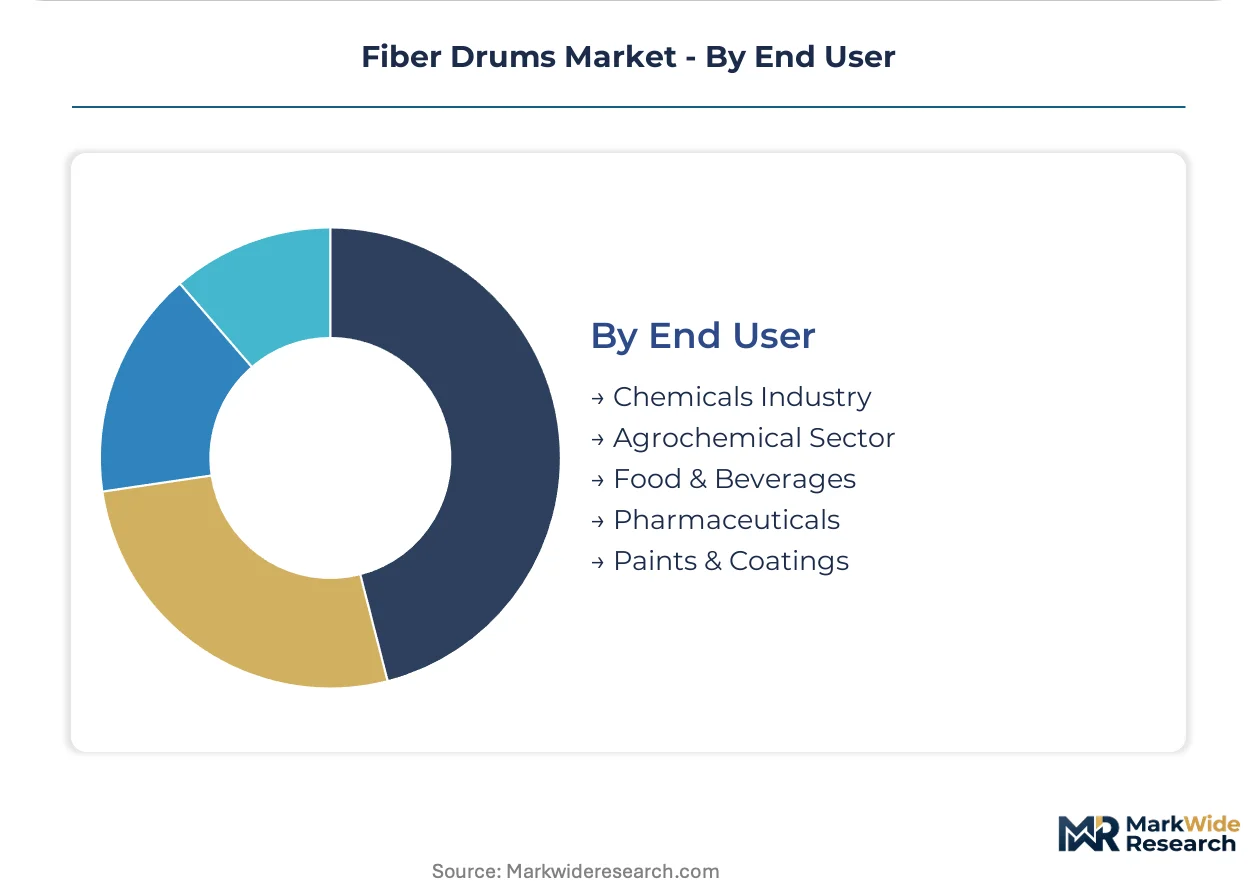
- Chemicals Industry:This sector requires robust, UN-rated fiber drums for the safe transport of powders, granules, and some semi-solid chemical compounds. Germany's chemical manufacturing clusters are a significant demand center for these compliant solutions.
- Agrochemical Sector:Fiber drums are used for packaging pesticides, fertilizers, and other agricultural chemicals, often requiring moisture-resistant and durable containers.
- Food & Beverages:This segment demands food-grade fiber drums with stringent purity standards and effective moisture barriers to protect ingredients like spices, flours, and food additives.
- Pharmaceuticals:The pharmaceutical industry mandates high-purity, contamination-free fiber drums for active pharmaceutical ingredients (APIs) and excipients. Compliance with US FDA and EU REACH regulations is critical for these applications.
- Paints & Coatings:Fiber drums transport pigments, resins, and other raw materials for paint and coating formulations, emphasizing durability and protection from moisture.
The Chemicals Industry represents the largest consumer of fiber drums due to its vast material handling needs. The Pharmaceuticals segment possesses the steepest expansion trajectory, driven by strict purity and transport requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The concentration of buyer archetypes, particularly in the chemicals and pharmaceuticals industries, significantly influences the geographic distribution of fiber drum demand. Regulatory frameworks and established manufacturing clusters create distinct regional requirements for specialized packaging solutions. This market's trajectory is closely tied to industrial expansion in key global economies.
United States
Demand for fiber drums in the United States stems from the pharmaceuticals industry's need for high-purity API transport and the food sector's requirement for compliant ingredient packaging. US FDA regulations dictate material safety and purity standards for product-contact surfaces. Pharmaceutical manufacturing hubs in the Northeast Corridor and Mid-Atlantic states drive consistent demand for specialized fiber drums.
Germany
Germany's robust chemical and pharmaceutical manufacturing clusters generate substantial demand for UN-rated fiber drums. The EU Green Deal actively promotes the adoption of recyclable packaging materials, favoring fiber-based solutions. The Rhine-Ruhr industrial region, a major chemical production area, relies on these drums for secure and compliant transport of granular materials.
India
India's expanding chemical and pharmaceutical manufacturing capabilities are creating significant growth potential for fiber drums. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for industrial packaging, guiding local production. Western India, particularly Gujarat, with its strong chemical and pharmaceutical hubs, represents a key growth region for industrial packaging.
China
China's vast industrial output, encompassing chemicals, food ingredients, and pharmaceuticals, drives substantial volume in the fiber drums market. National GB standards enforce packaging safety and environmental compliance for various industrial goods. The Yangtze River Delta region, a major manufacturing and export hub, exhibits high consumption of bulk industrial packaging.
France
France's specialty chemicals and cosmetics industries require high-performance fiber drums for sensitive ingredients and finished products. The European Union's REACH framework imposes strict material safety and chemical registration requirements, impacting packaging choices. The "Chemical Valley" near Lyon, a significant chemical production area, utilizes fiber drums for diverse applications.
Fiber Drums Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a dynamic market structure for fiber drums. The market exhibits a tiered consolidation, with a few large integrated manufacturers alongside numerous regional and niche providers. Strategic archetypes include global packaging conglomerates, specialized barrier technology innovators, and sustainable materials developers. Dominant competitive moves involve geographic expansion into emerging markets and portfolio diversification to address new end-user requirements.
Global packaging conglomerates, such as Greif, Inc. and Mauser Packaging Solutions, exemplify the broad-spectrum approach, leveraging extensive manufacturing footprints and diverse product portfolios to serve multinational clients. Sonoco Products Company occupies a position as a material science innovator, focusing on paper-based solutions and sustainable packaging advancements. These companies collectively anchor the market's supply side, offering a range of solutions from standard industrial drums to high-performance barrier containers.
| Leading Market Players |
|---|
| Snyder Industries |
| C.L. Smith |
| Greif, Inc. |
| Industrial Container Services |
| Smurfit Kappa |
| Mauser Packaging Solutions |
| Fibrestar Drums Limited |
| Enviro-Pak |
| Sonoco Products Company |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta region, a major manufacturing and export hub, drives significant industrial output, influencing global fiber drum pricing through its sheer production capacity. This concentration of production capacity creates pricing leverage for major suppliers operating in these areas.
Pricing Analysis
Cost-plus contract patterns, often indexed to global Kraft paper prices, characterize much of the fiber drums market. Price differentiation stems from UN-rated certifications for hazardous goods and the volume scale of large industrial orders. Pricing softness reflects input cost volatility for raw materials like Kraft paper and polyethylene. Chemical industry buyers exhibit higher price sensitivity compared to pharmaceutical clients prioritizing material purity and regulatory compliance.
Supply Chain Analysis
Material safety regulations, particularly the EU's REACH framework for chemical substances, establish de facto controls limiting the flow of non-compliant fiber drum components. China, India, and Germany serve as primary manufacturing centers for fiber drums and their essential raw materials. Supply chain dependencies include Kraft paper, high-purity polyethylene, and steel for closures. Commodity price volatility for these key inputs poses a significant structural risk. Distribution largely occurs via direct sales channels to major chemical and pharmaceutical end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fiber drums market experiences a shift in buyer power, driven by the increasing consolidation among pharmaceutical and chemical procurement teams. This dynamic forces suppliers to adapt their offerings and service models.
For Market Incumbents: Insulate core market share by investing in advanced barrier coating R&D, countering the substitution threat from rigid plastic drums. Diversify product portfolios to include specialized UN-rated drums for hazardous materials and high-purity liners for pharmaceuticals. Expand manufacturing footprints into emerging markets like India to leverage growing chemical and pharmaceutical production. Attaining stringent certifications, such as US FDA and EU REACH compliance, strengthens competitive positioning.
For New Entrants and Emerging Players: Build out niche capabilities in specialized barrier technologies for emerging applications like lithium-ion battery components. Target underpenetrated markets in Southeast Asia by offering cost-effective, UN-rated solutions for regional chemical manufacturers. The 41-60 liter segment offers accessible entry points for new manufacturers scaling up production. A strong go-to-market angle involves emphasizing sustainable materials and integrated smart packaging solutions for enhanced traceability.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized barrier technology innovators and sustainable materials developers within the fiber drums market. Long-term viability is strong, driven by regulatory tailwinds like the EU Green Deal and sustained demand from the pharmaceuticals sector. Acquisition targets should focus on companies with proprietary expertise in advanced liners or composite structures. The signal to watch is the increasing market penetration of fully recyclable, high-performance fiber drum solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Emerging Markets | Addresses growing chemical and pharmaceutical demand in India and Southeast Asia. |
| Advanced Barrier Coating R&D | Enhances performance capabilities for sensitive chemicals, reducing plastic substitution threats. |
| Sustainable Material Sourcing Certification | Meets procurement teams' demands for FSC-certified paper and supports EU Green Deal objectives. |
| Smart Packaging Technology Integration | Improves supply chain traceability for pharmaceutical and food-grade products. |
| UN-Rated Product Portfolio Diversification | Captures demand from Germany's chemical industry for hazardous material transport. |
Research Approach
A standing panel of chemical plant managers, pharmaceutical procurement leads, packaging engineers, and raw material suppliers provided ongoing calibration for market trends. This approach combined in-depth primary interviews with rigorous secondary validation from customs data, industry association reports, and company financial filings. Bottom-up data aggregation and top-down market sizing ensured comprehensive and accurate market representation across all segments.
Scenario-bracketing framing informed the quantitative projection of the fiber drums market across the analysis window. The analytical framework modeled segmentation dimensions including product type, capacity, material, end user, and regional regulatory compliance needs. Compound annual growth rates were derived from historical data extrapolation, coupled with end-user industry growth projections. Key forecast inputs included global Kraft paper price trends and industrial output indices for chemicals and pharmaceuticals.
The forecast holds incumbent behavior within observed patterns; aggressive moves by large packaging conglomerates or specialized barrier technology innovators would shift outcomes. Projections reflect current regulatory environments and anticipated material science advancements. Significant changes in global trade policies or disruptive innovations in alternative packaging materials represent key risk factors. Material shifts in sustainable packaging mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Packaging
Insulated Drum Covers Market
Industrial Packaging
Global Industrial Wooden Crates Market
Industrial Packaging
Insulated Bin Market
Industrial Packaging
Industrial Bulk Packaging Market
Industrial Packaging
Nestable Drums Market
Industrial Packaging
Corrugated Octabins Market
Industrial Packaging
Industrial Chemical Packaging Market
Industrial Packaging
Bulk Liquid Transport Packaging Market
Industrial Packaging
Overpack Drum Market
Industrial Packaging
Pallet Scales Market
Industrial Packaging
Corrugated Bulk Bins Market
Industrial Packaging
Global Dunnage Packaging Market
Industrial Packaging
Industrial Jugs Market
Industrial Packaging
Industrial Pails Market
Industrial Packaging
Cone Bottom Tank Market
Industrial Packaging
Industrial Packaging Market