
 Mrna Sequencing Market | 2026-2036
Mrna Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Mrna Sequencing Market Outlook
The EU Green Deal's push for sustainable biomanufacturing is restructuring procurement criteria across European sequencing facilities. Illumina, Inc. dominates high-throughput instrument placements in clinical translation networks. Thermo Fisher Scientific Inc. leverages its reagent supply chain to sustain pricing power in consumables. QIAGEN competes through sample-to-insight workflow integration that reduces hands-on laboratory time.
mRNA sequencing quantifies transcript abundance, maps alternative splicing events, and detects post-transcriptional modifications through reverse transcription followed by massively parallel sequencing, typically generating 20-50 million reads per sample for differential expression analysis. Drug development applications anchor current revenue as pharmaceutical sponsors sequence patient tumors to stratify immunotherapy responders. Personalized medicine represents the fastest-expanding application segment, with oncology clinics adopting transcriptomic profiling to guide treatment selection. Academic institutions remain the largest end-user category, though diagnostic laboratories are capturing margin pools as reimbursement codes for RNA-based tests expand.
The FDA regulates mRNA sequencing devices as in vitro diagnostics under 21 CFR Part 820 quality system requirements, while the EMA's In Vitro Diagnostic Regulation imposes conformity assessment burdens on European kit suppliers. ISO 15189 accreditation standards for diagnostic laboratories directly shape instrument purchasing specifications and service contract terms. Stakeholders must monitor how CMS coverage determinations for transcriptome-based oncology tests reshape the addressable clinical market versus research-only spending.
Market Dynamics
NIH funding concentration in the United States is restructuring competitive positioning, as academic procurement budgets flow toward translational programs while diagnostic laboratories capture margin pools through expanding reimbursement codes for RNA-based oncology tests.
Growth Catalysts
- Immunotherapy stratification:Pharmaceutical sponsors sequence patient tumors to identify transcriptomic signatures predicting responder populations, embedding mRNA sequencing into clinical trial protocols.
- ISO 15189 accreditation expansion:Diagnostic laboratories pursuing accreditation upgrade sequencing platforms to meet quality system specifications, driving instrument replacement cycles.
- Biotech clustering:Concentrated R&D hubs in Boston and San Diego generate network effects that accelerate protocol standardization and reagent demand.
Market Restraints
- Consumables cost structure:Library preparation kits and sequencing reagents constitute 60-70% of per-sample expenditure, creating margin pressure for high-throughput facilities.
- Supply concentration:Critical flow cell and polymerase supply chains concentrate among single-source suppliers, exposing procurement teams to allocation risk.
- Technical read-length limitations:Short-read platforms struggle with full-length transcript reconstruction, fragmenting alternative splicing analysis across multiple assays.
Strategic Opportunities
- Long-read platform convergence:Integration of Pacific Biosciences and Oxford Nanopore Technologies workflows with existing short-read infrastructure enables complete isoform characterization.
- Single-cell resolution expansion:Droplet-based microfluidics combined with mRNA sequencing opens addressable market in developmental biology and immune profiling.
- EU Green Deal procurement criteria:European sequencing facilities restructuring vendor selection around sustainable biomanufacturing standards create first-mover advantage for certified reagent suppliers.
Industry Challenges
- Bioinformatics pipeline complexity:Laboratories struggle to recruit computational biologists capable of deploying differential expression workflows at production scale.
- CMS coverage determination lag:Transcriptome-based oncology tests face protracted reimbursement review timelines, compressing diagnostic laboratory revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mrna Sequencing Market |
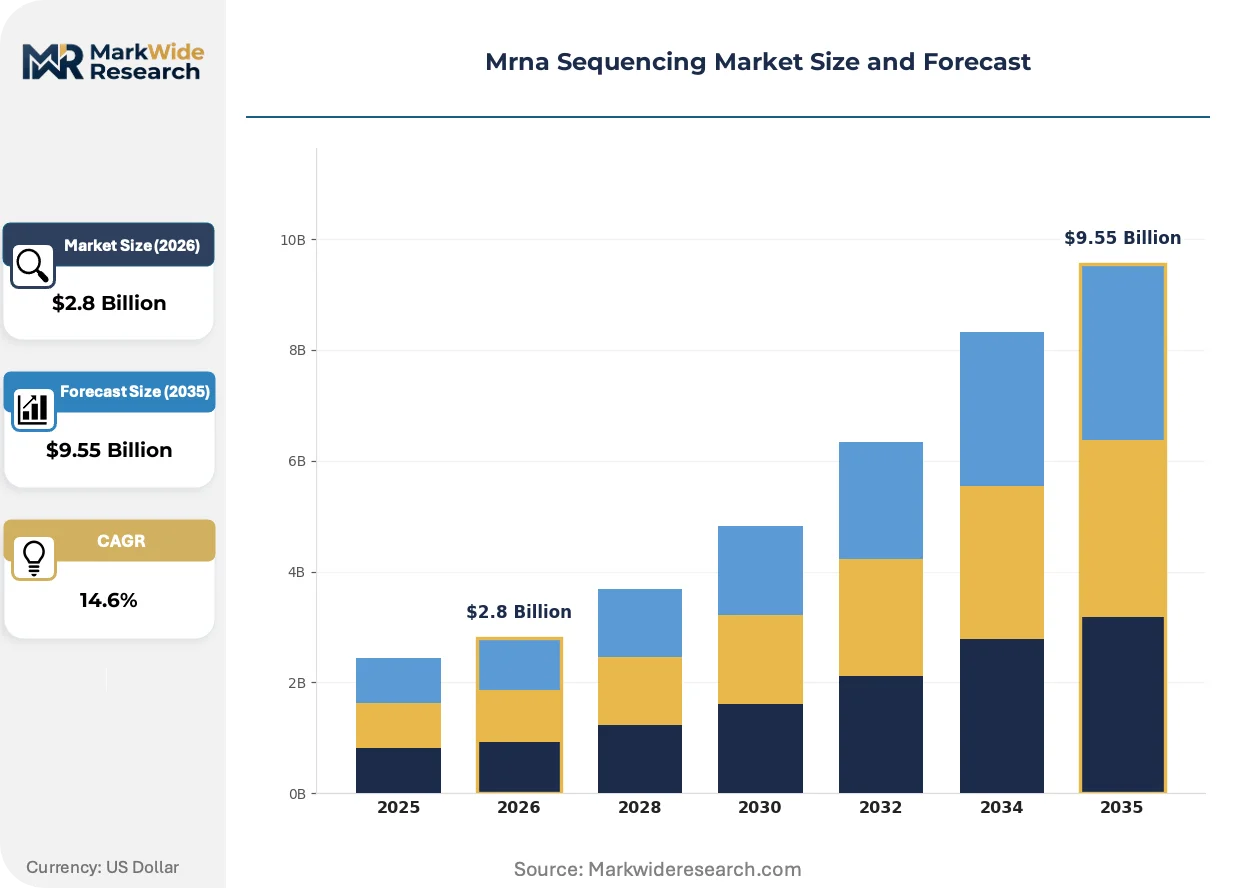
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Analyzers, Software Technology: Next-Generation Sequencing, Microarray, Sanger Sequencing, PCR End User: Biotechnology Companies, Academic Institutions, Diagnostic Laboratories, Contract Research Organizations Application: Drug Development, Personalized Medicine, Genetic Research, Disease Diagnosis |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific Inc., QIAGEN, F. Hoffmann-La Roche Ltd, Takara Bio Inc., Oxford Nanopore Technologies, Agilent Technologies, Inc., BGI Group, PerkinElmer, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mrna Sequencing Market Strategic Shifts
Platform miniaturization and cloud-native analysis pipelines are compressing the capital-to-insight timeline, while regulatory frameworks on both sides of the Atlantic reshape quality benchmarks for clinical translation.
Direct RNA sequencing is expanding into epitranscriptomic analysis, detecting m6A and pseudouridine modifications without reverse transcription artifacts. Academic core facilities in Germany and the Netherlands are adopting these workflows for stem cell differentiation studies. The technology is expanding into applications previously requiring antibody-based enrichment, consolidating assay steps and reducing sample input requirements.
The FDA's evolving guidance on nucleic acid-based diagnostics under 21 CFR Part 820 is elevating design control documentation burdens for sequencing platform manufacturers. Instrument vendors must now submit comprehensive risk management files prior to clinical trial authorization. This regulatory tightening most affects mid-tier suppliers lacking dedicated quality assurance infrastructure, forcing consolidation toward established players with regulatory affairs capacity.
Service unbundling is fragmenting the traditional platform-reagent-software bundle. Diagnostic laboratories now procure sequencing capacity through independent service contracts while sourcing consumables through group purchasing organizations. This purchasing pattern shift is most visible in the United States, where hospital network consolidation has created procurement leverage that extracts standalone pricing for reagent volumes.
Mrna Sequencing Market Segmentation
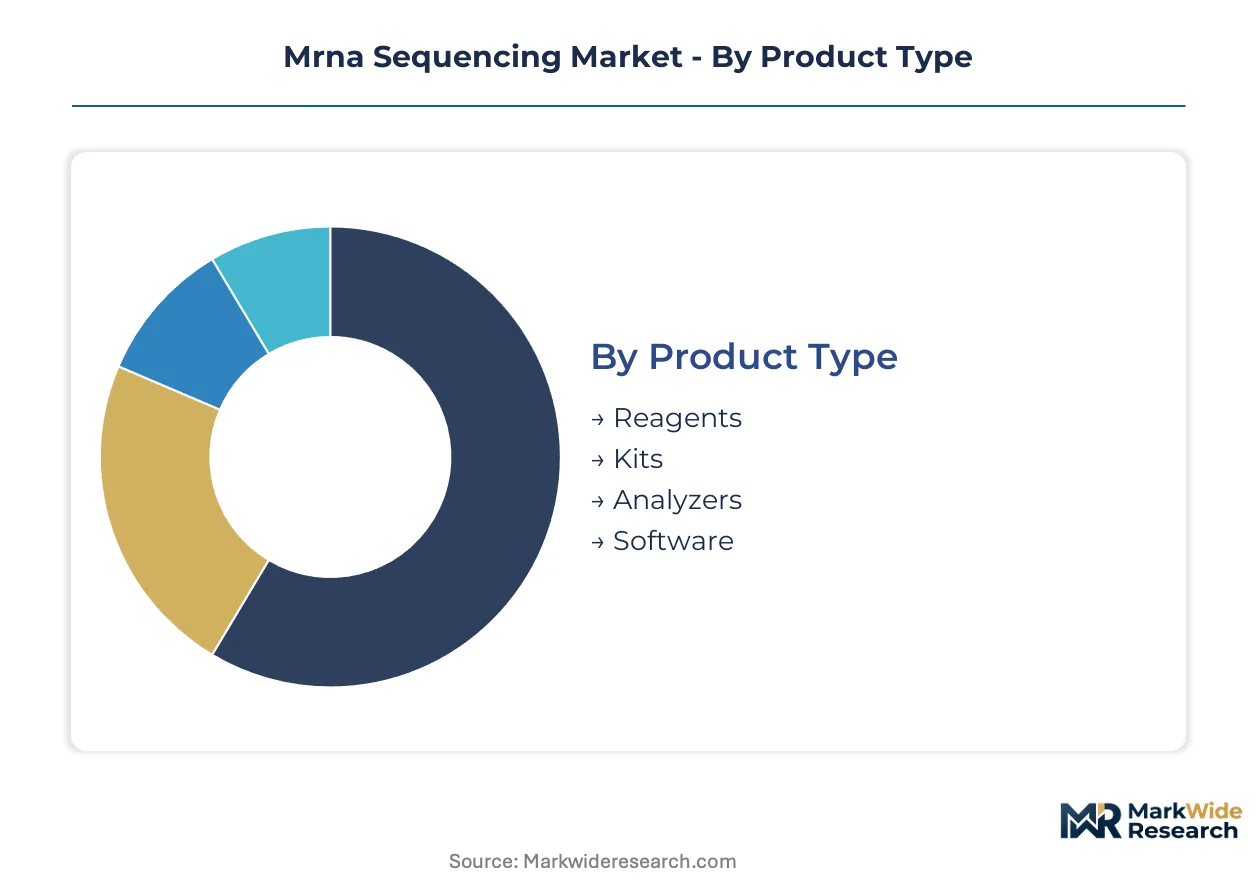
mRNA sequencing segments fragment across laboratory workflow stages, from consumable inputs through analytical outputs. Each category exhibits distinct procurement patterns, margin structures, and vendor concentration dynamics that reshape competitive positioning.
Product Type:
Standardization dominates high-volume consumables while analyzers demand customization for specific throughput and accuracy specifications.
- Reagents:Enzyme preparations, nucleotides, and buffers constitute the recurring cost base for every sequencing run. Academic core facilities in the United States negotiate annual supply contracts indexed to NIH grant cycles, creating predictable procurement rhythms that favor incumbent suppliers with validated quality systems.
- Kits:Library preparation workflows bundle enzymes, adapters, and purification reagents into protocol-specific configurations. Diagnostic laboratories pursuing ISO 15189 accreditation specify kits with comprehensive documentation packages, embedding vendor selection into quality management systems.
- Analyzers:Capital equipment spans benchtop units to production-scale clusters.
- Software:Bioinformatics pipelines for alignment, quantification, and variant calling.
Leading the category by volume: Reagents. Growing fastest: Software.
Technology:
Cost tiers separate established platforms from emerging modalities, with capital intensity and per-run economics driving adoption curves.
- Next-Generation Sequencing:Massively parallel short-read platforms generate 20-50 million reads per sample through reversible terminator chemistry. Pharmaceutical sponsors in Boston and San Diego biotech clusters embed these workflows into clinical trial protocols for immunotherapy stratification.
- Microarray:Hybridization-based transcript quantification offers lower per-sample cost for targeted gene panels. Contract research organizations leverage microarrays for high-volume screening where full transcriptome coverage is unnecessary.
- Sanger Sequencing:First-generation capillary electrophoresis for targeted validation.
- PCR:Amplification-based quantification preceding sequencing workflows.
Next-Generation Sequencing commands the installed base. Long-read convergence is climbing the fastest as Pacific Biosciences and Oxford Nanopore workflows integrate with existing infrastructure.
End User:
Customer type determines purchasing authority, with consolidated hospital networks extracting pricing leverage distinct from fragmented academic procurement.
- Biotechnology Companies:Venture-funded drug developers sequence patient tumors to stratify immunotherapy responders. Boston and San Diego clusters generate network effects that accelerate protocol standardization and concentrate reagent demand among preferred suppliers.
- Academic Institutions:Core facilities support translational research programs across multiple principal investigators. NIH funding concentration in the United States directs procurement budgets toward platforms with demonstrated publication track records.
- Diagnostic Laboratories:Clinical service providers capture margin pools through expanding reimbursement codes for RNA-based oncology tests.
- Contract Research Organizations:Outsourced service providers manage variable sequencing demand for pharmaceutical sponsors.
Academic Institutions maintain the largest installed base. Diagnostic Laboratories are gaining share fastest as CMS coverage determinations expand for transcriptome-based tests.
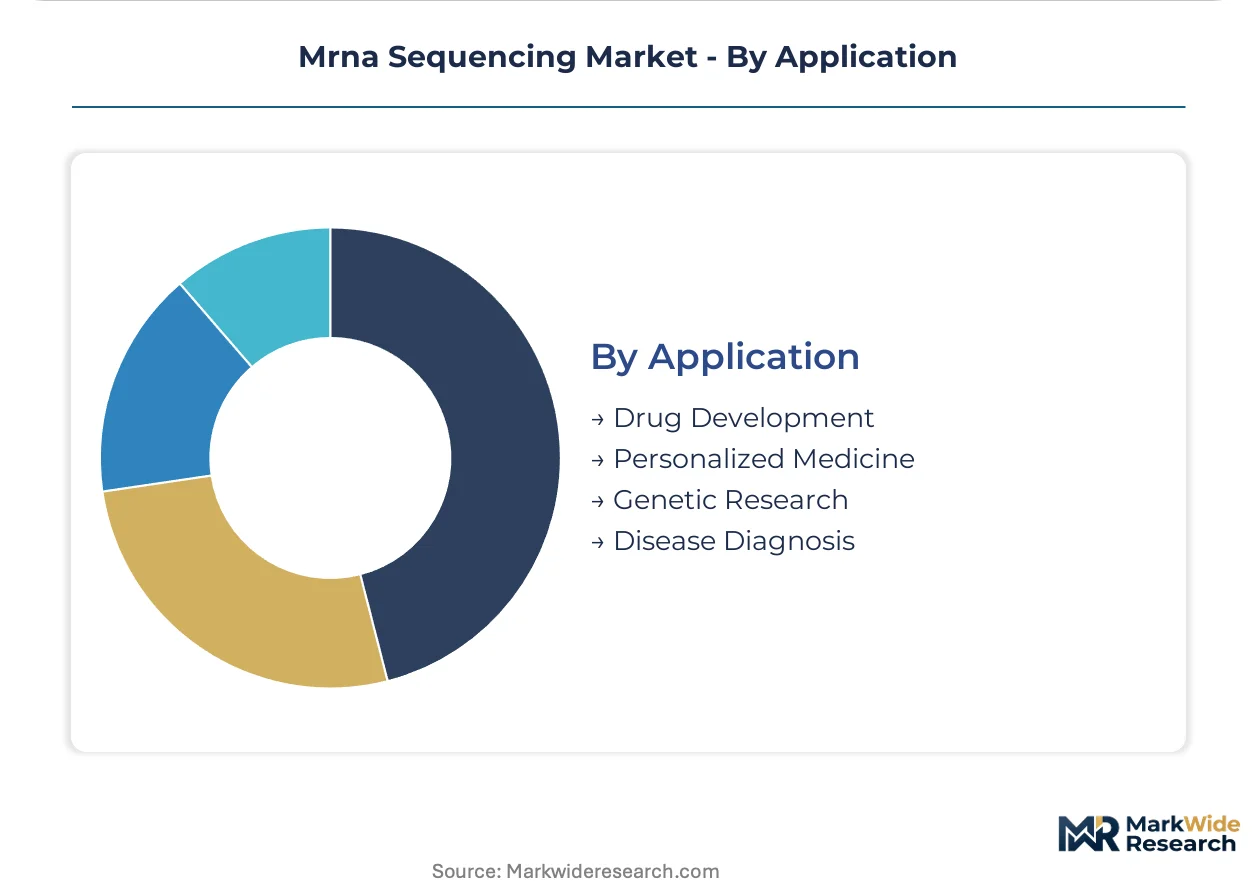
Application:
Maturity gradients separate established research applications from clinical translation, with regulatory clearance timelines shaping revenue recognition patterns.
- Drug Development:Pharmaceutical sponsors embed mRNA sequencing into clinical trial protocols for patient stratification and biomarker discovery. FDA guidance on nucleic acid-based diagnostics under 21 CFR Part 820 elevates documentation burdens for platform manufacturers serving this segment.
- Personalized Medicine:Oncology clinics adopt transcriptomic profiling to guide treatment selection. The EMA's In Vitro Diagnostic Regulation imposes conformity assessment requirements on European kit suppliers targeting this application.
- Genetic Research:Fundamental biology studies of gene expression regulation.
- Disease Diagnosis:Clinical identification of pathological transcript signatures.
Drug Development anchors current revenue. Personalized Medicine shows the steepest expansion trajectory as reimbursement infrastructure matures for RNA-based clinical tests.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston and San Diego anchor North American sequencing procurement, with NIH funding flows concentrating instrument placements across translational research networks. European facilities restructure vendor selection around EU Green Deal criteria, while Asia-Pacific clusters scale domestic platform capabilities.
United States
NIH grant cycles direct academic core facility procurement toward platforms with validated publication track records. The FDA's 21 CFR Part 820 quality system requirements reshape instrument purchasing specifications for diagnostic laboratories pursuing clinical translation. Boston's biotech corridor generates network effects that accelerate protocol standardization and concentrate reagent demand.
Germany
Academic core facilities in Heidelberg and Munich adopt direct RNA sequencing workflows for stem cell differentiation studies. The EU Green Deal's sustainable biomanufacturing standards restructure procurement criteria across sequencing facilities. The country's national pharmaceutical regulator imposes conformity assessment burdens on kit suppliers targeting clinical applications.
China
Domestic platform manufacturers scale production capacity to reduce dependence on imported flow cells and polymerase reagents. The National Medical Products Administration elevates documentation requirements for nucleic acid-based diagnostic devices. Beijing-Tianjin-Hebei biotech clusters concentrate R&D investment in transcriptomic profiling for oncology applications.
United Kingdom
Oncology clinics in London and Cambridge adopt transcriptomic profiling to guide immunotherapy treatment selection. The Medicines and Healthcare products Regulatory Agency aligns with evolving FDA guidance on sequencing platform quality benchmarks. The Southeast England life sciences corridor attracts venture-funded drug developers sequencing patient tumors for responder stratification.
Japan
Pharmaceutical sponsors embed mRNA sequencing into clinical trial protocols for biomarker discovery and patient stratification. The Pharmaceuticals and Medical Devices Agency regulates sequencing devices as in vitro diagnostics with stringent design control documentation. The Kanto region's academic medical centers expand procurement for personalized medicine applications.
Mrna Sequencing Market Competitive Environment
Premium-margin players sit above commodity-margin players across reagent supply chain control and regulatory affairs capacity. Illumina dominates high-throughput instrument placements in clinical translation networks, while Thermo Fisher leverages consumables pricing power. Three archetypes define competitive positioning: integrated platform-reagent vendors, specialized workflow integrators, and emerging long-read technology developers. Consolidation pressures concentrate among mid-tier suppliers lacking dedicated quality infrastructure, while strategic partnerships and technology licensing dominate competitive moves.
Within the integrated platform tier, Illumina, Inc. and Thermo Fisher Scientific Inc. exemplify archetypes built on instrument installed base and reagent supply chain scale. QIAGEN occupies a position representing workflow integration specialists that reduce laboratory hands-on time. These three companies anchor the competitive structure, with Oxford Nanopore Technologies and Pacific Biosciences sitting within the emerging long-read convergence segment.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific Inc. |
| QIAGEN |
| F. Hoffmann-La Roche Ltd |
| Takara Bio Inc. |
| Oxford Nanopore Technologies |
| Agilent Technologies, Inc. |
| BGI Group |
| PerkinElmer, Inc. |
| Others |
Value Chain & Pricing Dynamics
Diagnostic laboratory consolidation across United States hospital networks extracts standalone reagent pricing through group purchasing organization leverage, compressing margins for consumable suppliers while embedding multi-year service contracts for instrument uptime guarantees.
Pricing Analysis
Throughput-based pricing anchors commercial arrangements, with per-run costs scaling inversely with annual contract volumes. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15189-accredited diagnostic laboratories from research core facilities and emerging economy entrants. Price differentiation hinges on quality system documentation depth and geographic delivery reliability. Pricing pressure stems from consumables constituting sixty to seventy percent of per-sample expenditure, forcing high-throughput facilities toward annual supply contracts indexed to NIH grant cycles. Academic core facilities exhibit highest price sensitivity; pharmaceutical sponsors in Boston and San Diego clusters prioritize protocol standardization over unit cost minimization.
Supply Chain Analysis
Refurbished flow cell remanufacturing programs in California and Singapore extend consumable lifecycles while reducing hazardous waste disposal costs under EU Green Deal criteria. Critical enzyme and polymerase production concentrates in the United States, Germany, and China, with flow cell manufacturing anchored in Singapore and San Diego. Raw material dependencies span photolithography-grade glass substrates, recombinant DNA polymerases, and fluorophore-labeled nucleotides. Single-source vulnerability pervades high-throughput instrument optical subassemblies, exposing procurement teams to allocation risk during demand surges. Distribution runs through direct vendor-to-laboratory contracts for instruments, while consumables flow via specialized life science distributors and group purchasing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mRNA sequencing market reads as a cost-of-compliance story where FDA 21 CFR Part 820 quality system documentation burdens erect barrier-to-entry moats favoring established players with dedicated regulatory affairs infrastructure.
For Market Incumbents: Extend platform-reagent bundling into outcome-based service contracts that guarantee turnaround times and data quality metrics, locking out mid-tier competitors lacking quality assurance depth. Deepen backward integration into flow cell polymerase production to reduce single-source exposure while capturing margin pools from consumables. Prioritize ISO 15189 accreditation support programs for diagnostic laboratory customers, embedding vendor selection into quality management system dependencies. For New Entrants and Emerging Players: Long-read convergence workflows represent the most penetrable technology wedge, as Pacific Biosciences and Oxford Nanopore integration gaps create white-space for workflow specialists reducing hands-on laboratory time. Target European sequencing facilities restructuring procurement around EU Green Deal sustainable biomanufacturing certification, where first-mover advantage awaits certified reagent suppliers. Pursue academic core facility adoption through publication-grade validation datasets, leveraging NIH funding concentration to establish reference customer footprints before clinical translation expansion. For Investors and Strategic Acquirers: Distressed-cycle entries favor workflow integration specialists with ISO 13485 quality infrastructure in Germany and the Netherlands, where EMA In Vitro Diagnostic Regulation conformity assessment burdens compress valuations for undercapitalized kit suppliers. Five-to-ten year viability hinges on regulatory affairs capacity scaling faster than compliance cost inflation. Monitor CMS coverage determination timelines for transcriptome-based oncology tests as the critical inflection signal distinguishing research-only revenue from addressable clinical market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Long-Read Platform Convergence | Integration of Pacific Biosciences and Oxford Nanopore workflows enables complete isoform characterization for immunotherapy stratification. |
| ISO 15189 Accreditation Support | Diagnostic laboratories pursuing accreditation upgrade sequencing platforms, embedding vendor selection into quality management systems. |
| EU Green Deal Certification | European sequencing facilities restructure vendor selection around sustainable biomanufacturing standards for reagent procurement. |
| Single-Cell Resolution Expansion | Droplet-based microfluidics combined with mRNA sequencing opens addressable market in developmental biology applications. |
| Cloud-Native Pipeline Development | Platform miniaturization and cloud-native analysis pipelines compress capital-to-insight timelines for diagnostic laboratories. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews across sequencing platform manufacturers, diagnostic laboratory directors, academic core facility managers, and pharmaceutical biomarker discovery leads. FDA 510(k) submissions, EMA technical documentation, and NIH RePORTER grant databases supplied demand-side validation. Bottom-up instrument placement counts and top-down consumable revenue estimates underwent triangulation against trade customs data for flow cell and reagent import volumes.
Data-stream reconciliation across procurement database extracts, hospital capital expenditure disclosures, and vendor reported instrument placements shaped the analytical framework across the analysis window. Segmentation dimensions spanned product type, technology modality, end-user category, application maturity, and regional regulatory cluster. CAGRs derived from weighted average of historical placement trajectories and reimbursement code expansion timelines. Industry-specific forecast inputs incorporated CMS coverage determination pipelines and EMA In Vitro Diagnostic Regulation implementation phases.
Several conditions sit outside the modeled scope, including emergent direct RNA sequencing platforms without commercial scale validation and single-cell multi-omic integration workflows still in protocol development. Forecasts reflect assumptions regarding reimbursement code expansion velocity and regulatory clearance timeline stability. Practitioners should monitor FDA guidance evolution on nucleic acid-based diagnostics and CMS national coverage determination schedules for early signals of clinical market expansion or contraction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Kearns-Sayre Syndrome Market
Genomics
Cytogenetic Systems Market
Genomics
US Direct-To-Consumer Genetic Testing Market
Genomics
DNA Diagnostics Market
Genomics
Apolipoprotein Test Market
Genomics
Global Nucleic Acid Labeling Market
Genomics
Sequencing Electrophoresis Systems Market
Genomics
Molecular Biomarkers for Cancer Detection Market
Genomics
Genetic Material Market
Genomics
Mendelian Disorders Testing Market
Genomics
China Genetic Testing Market
Genomics
Europe Digital PCR Market
Genomics
US Genetic Testing Market
Genomics
Pharmacogenomics Technology Market
Genomics
Omics Lab Services Market
Genomics
NGS-Based RNA-Sequencing Market