
 Microbial Seed Treatment Market | 2026-2036
Microbial Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Seed Treatment Market Foresight
Biostimulant-grade inoculant specifications is collapsing the gap between commodity seed treatments and premium biological platforms. BASF SE leverages its microbial strain library to sustain leadership in rhizobia-based nitrogen fixation products. Syngenta Group anchors its position through integrated seed-applied biological pipelines that complement its chemistry portfolio. Bayer AG differentiates by controlling proprietary carrier formulations that extend microbial viability on treated seed.
Microbial seed treatment applies living microorganisms—primarily bacteria such as Bacillus, Pseudomonas, and Bradyrhizobium species, or fungi including Trichoderma—to seeds through coating, inoculation, or soaking processes to enhance nutrient uptake, suppress soil-borne pathogens, or fix atmospheric nitrogen. The bacteria segment dominates current volume as growers prioritize nitrogen-fixing inoculants for legume and cereal systems, while fungi-based treatments are capturing expanding margin pools in specialty vegetable and high-value crop applications. Coating as a treatment method leads commercial deployment due to equipment compatibility with existing seed handling infrastructure, though inoculation retains structural importance in markets where on-farm application flexibility commands premium positioning.
The EPA regulates microbial seed treatment products under the Federal Insecticide, Fungicide, and Rodenticide Act, requiring efficacy and non-target organism safety data that shapes product development timelines and market access costs. The EU's F-Gas Regulation and broader Farm to Fork targets under the EU Green Deal are redirecting agricultural input subsidies toward biological alternatives, tightening standards for chemical seed treatment residues. Stakeholders must monitor how evolving biopesticide registration pathways in Brazil and Argentina reshape competitive entry barriers across the Americas.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing chemical pesticide tolerance thresholds per hectare, redirecting subsidy flows toward biological seed treatment platforms and restructuring competitive positioning across agricultural input supply chains.
Growth Catalysts
- EU F-Gas Regulation:The regulation tightens restrictions on synthetic fumigants used in seed storage, pushing growers toward microbial alternatives for pest suppression.
- Soybean expansion in Brazil:Frontier agricultural zones in Mato Grosso and Goiás are concentrating demand for Bradyrhizobium inoculants as primary nitrogen fixation infrastructure.
- Biostimulant specification convergence:Premium biological platforms are absorbing commodity seed treatment volume as performance benchmarks collapse into unified efficacy standards.
Market Restraints
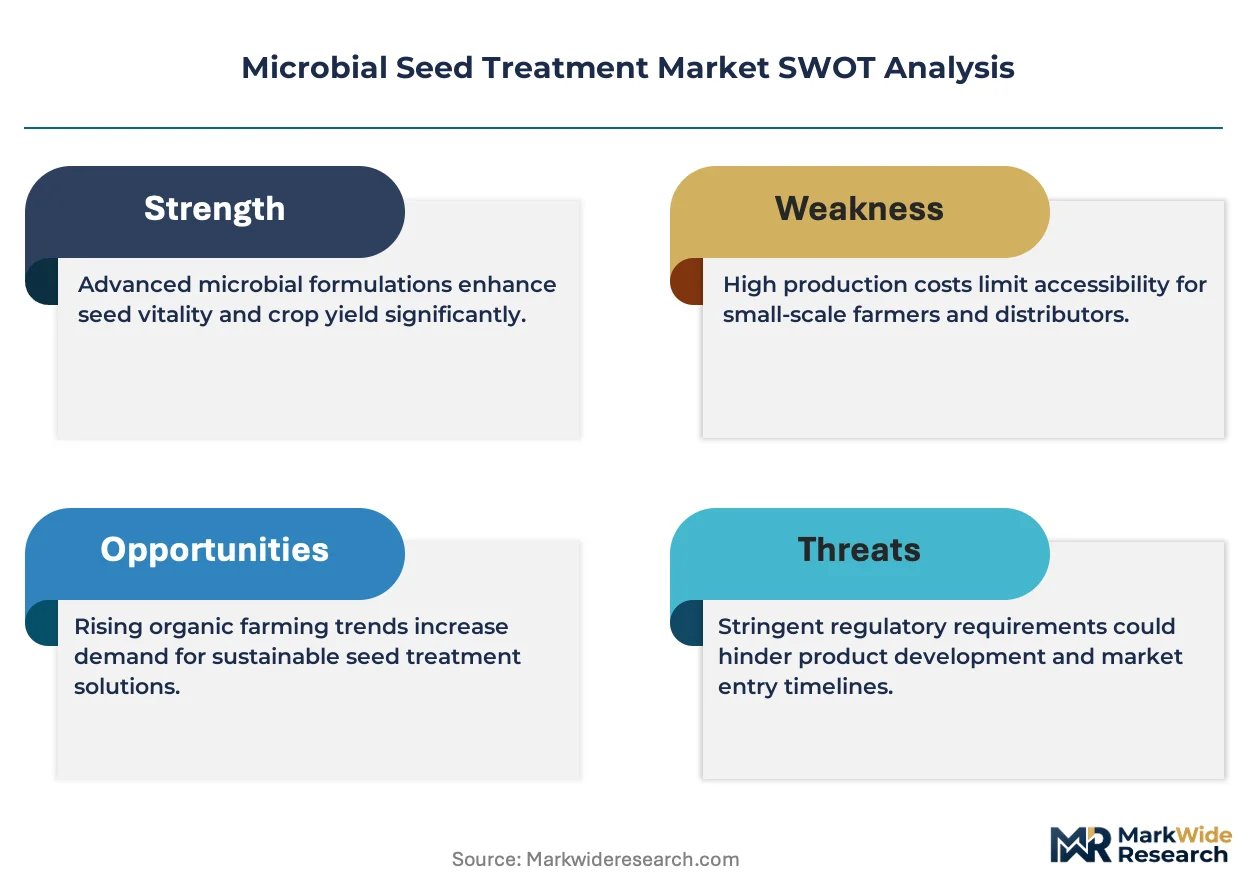
- Live culture shelf-life volatility:Formulation chemistry limits extend microbial viability on treated seed to 6-12 months, constraining inventory management flexibility for distributors.
- Strain patent concentration:Proprietary rhizobia and Bacillus strain libraries remain concentrated among three multinational agrochemical conglomerates, limiting independent developer access.
- Temperature-sensitive logistics:Cold chain requirements for high-titer inoculants inflate last-mile distribution costs in tropical soybean belts.
Strategic Opportunities
- Argentina biopesticide registration pathway:Streamlined regulatory review timelines for microbial products are opening competitive entry for mid-scale biological developers.
- Drone-based seed inoculation:Aerial application systems are emerging as a channel innovation for on-farm microbial treatment in irregular terrain where ground equipment fails.
- Carbon credit monetization:Nitrogen-fixing inoculants qualify for soil carbon sequestration protocols under emerging agricultural offset frameworks.
Industry Challenges
- Microbiologist talent scarcity:Strain characterization and fermentation scale-up expertise pools remain shallow relative to synthetic chemistry talent markets.
- Seed treater equipment incompatibility:Legacy coating infrastructure designed for synthetic chemistries damages live cell viability through shear stress and desiccation exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Seed Treatment Market |
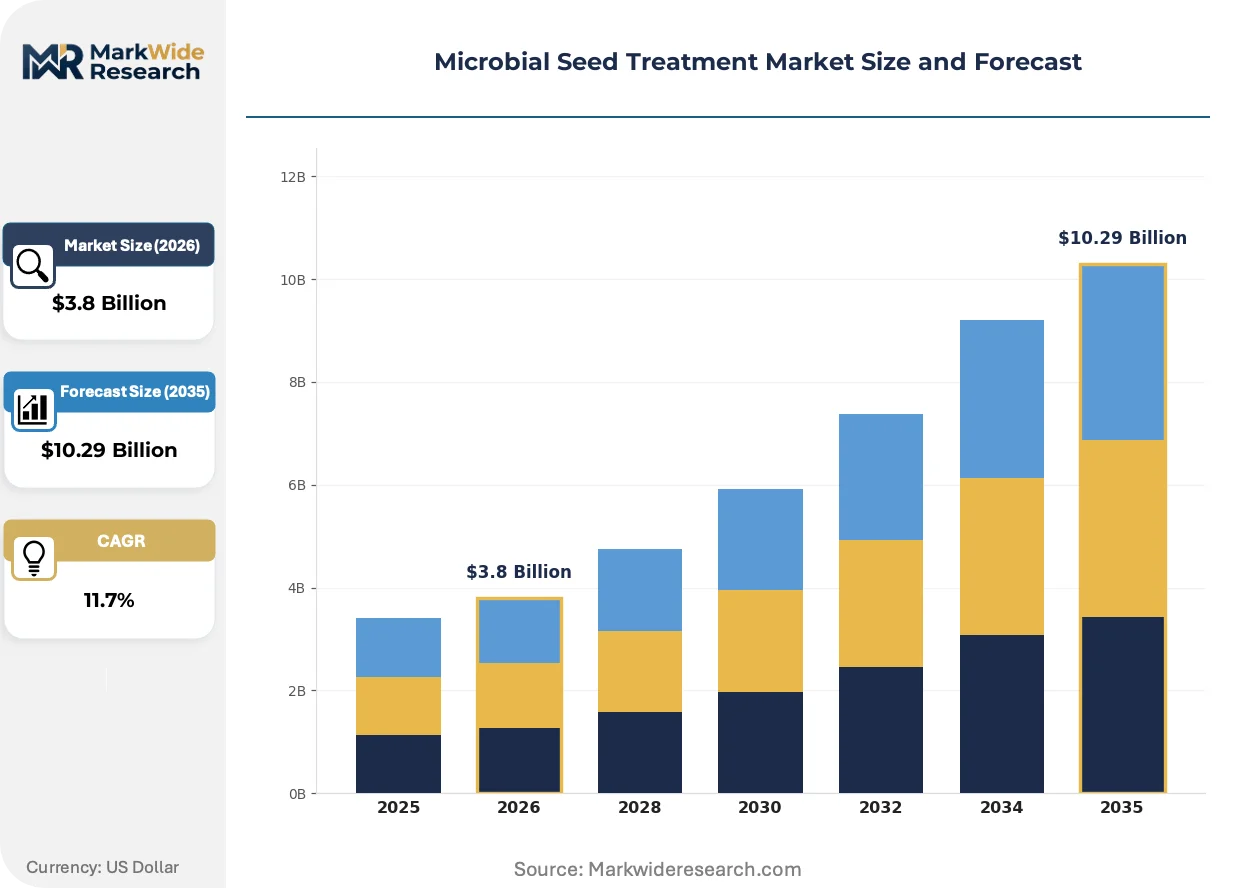
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacteria, Fungi, Protozoa, Others Application: Cereals, Pulses, Oilseeds, Vegetables Treatment Method: Inoculation, Coating, Drenching, Soaking End User: Farmers, Agricultural Cooperatives, Research Institutions, Seed Companies |
| Companies Covered | BASF SE, Syngenta Group, Bayer AG, Corteva Agriscience, Novonesis, UPL, FMC Corporation, Valent BioSciences, Koppert, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Seed Treatment Market Shifts & Advancements
Formulation science is decomposing the historical trade-off between microbial survival duration and seed handling compatibility, enabling biological platforms to penetrate row-crop segments previously reserved for synthetic chemistry.
Encapsulation technology is decomposing the barrier between laboratory strain viability and field performance consistency. Polymer-based microencapsulation systems shield Bradyrhizobium and Trichoderma cells from desiccation and UV exposure during seed storage. North American corn and soybean operations are adopting these formulations at accelerating rates. The technology is decomposing price premiums between commodity and premium biological tiers by standardizing shelf-life performance.
The EPA's biopesticide registration framework under FIFRA is compressing approval timelines for microbial seed treatments relative to synthetic chemical reviews. The industrial consequence is a faster product development cycle for biological developers, though efficacy data requirements for non-target organism safety remain stringent. Seed treatment platforms targeting specialty vegetable markets are responding by front-loading toxicology investment to secure early-mover positioning.
Buyer concentration among integrated grain processors is compressing supplier negotiation leverage for independent microbial developers. Large-scale corn ethanol and soybean crush facilities are consolidating procurement decisions at the elevator level, bundling seed treatment specifications with grain delivery contracts. This pattern is most visible across the US Corn Belt, where processor-driven agronomic protocols now dictate inoculant selection criteria.
Microbial Seed Treatment Market Segmentation
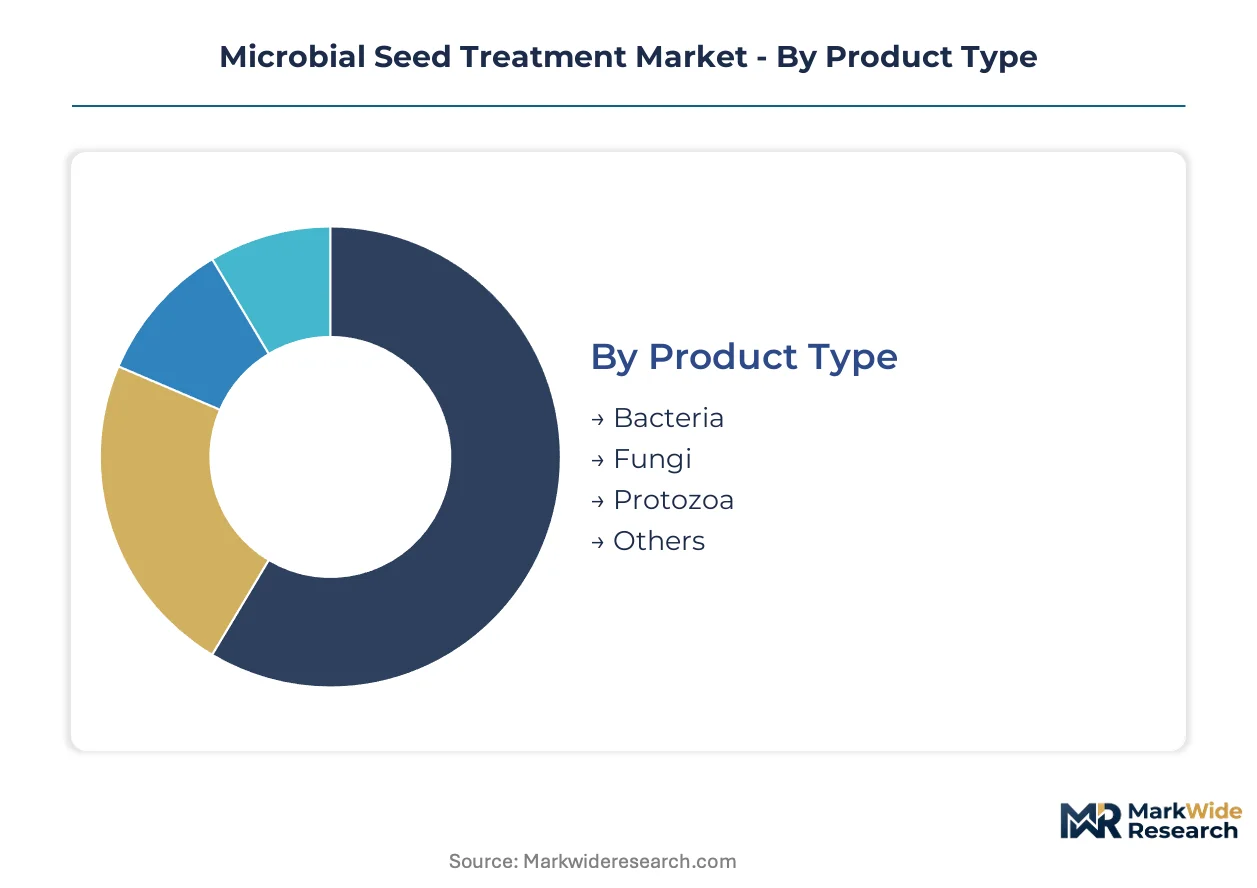
Microbial seed treatment segmentation reveals how biological platforms fragment across technical specifications, crop systems, and distribution channels. Each dimension carries distinct regulatory, logistical, and performance requirements that reshape supplier positioning.
Product Type:
EPA biopesticide registration pathways under FIFRA apply differential data requirements across microbial taxonomies, accelerating bacteria approvals while fungi navigate extended toxicology review.
- Bacteria:Live bacterial cultures—primarily Bacillus, Pseudomonas, and Bradyrhizobium species—dominate commercial volume through nitrogen fixation and pathogen suppression functions. Demand concentrates in Brazilian soybean frontiers where Bradyrhizobium inoculants serve as primary nitrogen infrastructure, constrained by cold chain logistics costs in tropical distribution networks.
- Fungi:Trichoderma-based formulations penetrate specialty vegetable and high-value crop applications through induced systemic resistance mechanisms. Adoption accelerates in North American organic vegetable operations where residue tolerance thresholds sit below synthetic chemistry limits, though fermentation scale-up expertise pools remain shallow relative to bacterial platforms.
- Protozoa:Niche biocontrol agents targeting soil-dwelling pest complexes occupy limited commercial deployment.
- Others:Algae and yeast-derived biostimulants occupy emerging specification tiers without standardized efficacy benchmarks.
Established volume favors bacteria; emerging adoption favors fungi.
Application:
End-use crop value tiers determine formulation investment intensity and margin capture potential.
- Cereals:Corn and wheat systems drive bulk inoculant consumption across North American row-crop operations. Procurement concentrates at elevator level where integrated grain processors bundle seed treatment specifications with delivery contracts, compressing independent developer negotiation leverage.
- Oilseeds:Soybean expansion in Brazil's Mato Grosso and Goiás frontiers anchors Bradyrhizobium demand. The EU Green Deal's Farm to Fork residue restrictions redirect European rapeseed growers toward biological alternatives, though temperature-sensitive logistics inflate last-mile costs.
- Pulses:Lentil and chickpea systems in Canadian prairies sustain rhizobia-specific formulation demand.
- Vegetables:Specialty crop premiums justify encapsulation technology investments for shelf-life extension.
Row-crop cereals and oilseeds anchor volume scale; vegetable applications command margin premiums.
Treatment Method:
Equipment compatibility and on-farm flexibility dictate channel economics across application modalities.
- Coating:Polymer and peat-based seed coatings integrate with existing treater infrastructure across commercial seed facilities. North American corn and soybean operations deploy these formulations at accelerating rates as encapsulation technology standardizes shelf-life performance between commodity and premium tiers.
- Inoculation:On-farm liquid application retains structural importance in irregular terrain where ground equipment fails. Drone-based aerial systems are emerging as channel innovation for Mato Grosso soybean operations, though pilot-scale validation remains incomplete.
- Drenching:Nursery and transplant operations in vegetable propagation facilities utilize soil-drench protocols.
- Soaking:Pre-plant immersion methods persist in smallholder legume systems with limited mechanization.
Coating dominates commercial throughput; inoculation captures flexibility premiums.
End User:
Buyer scale and technical capability determine service intensity and formulation customization requirements.
- Seed Companies:Integrated seed-chemistry platforms—BASF, Syngenta, Bayer—control proprietary strain libraries and carrier formulations. These entities bundle biological treatments with genetic trait packages, extending microbial viability through controlled-environment application infrastructure.
- Farmers:Direct procurement concentrates in large-scale operations with captive seed treatment equipment. US Corn Belt ethanol and soybean crush facility protocols now dictate inoculant selection criteria at the elevator level.
- Agricultural Cooperatives:Regional buying groups aggregate demand across membership bases with variable technical sophistication.
- Research Institutions:Public breeding programs and university extension networks generate strain characterization data without commercial scale-up capacity.
Seed company integration favors proprietary platform control; farmer direct procurement favors application flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances for microbial inoculants tilt toward surplus positions in fermentation-capable economies while deficit markets concentrate in frontier agricultural zones lacking domestic strain development infrastructure.
Brazil
Bradyrhizobium demand concentrates in Mato Grosso and Goiás soybean frontiers where nitrogen fixation infrastructure replaces synthetic fertilizer imports. ANVISA maintains streamlined biopesticide registration pathways that compress approval timelines relative to synthetic chemistry reviews. São Paulo state anchors domestic fermentation capacity for rhizobia strain production.
United States
EPA biopesticide registration under FIFRA accelerates microbial seed treatment approvals while the Corn Belt's integrated ethanol and soybean crush facilities bundle inoculant specifications with grain delivery contracts. Iowa and Illinois sustain the highest treatment application volumes through elevator-level procurement consolidation.
Germany
The EU Green Deal's Farm to Fork strategy redirects subsidy flows toward biological alternatives as EFSA tightens residue tolerance thresholds for chemical seed treatments. Bavaria and Baden-Württemberg concentrate formulation R&D infrastructure for encapsulation technologies that extend microbial viability.
Argentina
Soybean expansion in Buenos Aires and Córdoba provinces sustains Bradyrhizobium demand despite currency volatility constraining import-dependent supply chains. The national agricultural regulator operates accelerated review timelines for microbial products that open competitive entry for mid-scale biological developers. Rosario's grain export corridor anchors treatment distribution logistics.
India
Pulses cultivation in Maharashtra and Madhya Pradesh drives rhizobia-specific formulation demand for lentil and chickpea systems. The PLI scheme for agrochemical manufacturing incentivizes domestic fermentation capacity expansion for nitrogen-fixing inoculants. Gujarat's specialty chemical clusters host emerging encapsulation technology providers.
Microbial Seed Treatment Market Competitive Landscape
Concentration sits with integrated agrochemical conglomerates controlling proprietary strain libraries and carrier formulation intellectual property. Three multinational entities anchor volume leadership through backward integration into fermentation infrastructure and captive seed treatment application networks. Specialist biological developers occupy mid-tier positions by licensing strain access or partnering with seed companies for distribution reach. Dominant competitive moves include M&A activity targeting fermentation scale-up capabilities and strategic partnerships with grain processors to secure procurement protocol inclusion.
Within the integrated agrochemical tier, BASF SE and Syngenta Group exemplify archetypes combining genetic trait packages with microbial treatment bundling. Bayer AG occupies a position emphasizing proprietary carrier formulations that extend microbial viability on treated seed. Among independent biological specialists, Novonesis represents the fermentation-scale archetype with industrial biotechnology infrastructure applicable to agricultural inoculant production. Valent BioSciences and Koppert sit within the crop protection specialist tier, leveraging existing distribution relationships with specialty vegetable growers to penetrate high-margin application segments.
| Leading Market Players |
|---|
| BASF SE |
| Syngenta Group |
| Bayer AG |
| Corteva Agriscience |
| Novonesis |
| UPL |
| FMC Corporation |
| Valent BioSciences |
| Koppert |
| Others |
Supply & Pricing Matrix
EPA biopesticide registration under FIFRA gates both supply qualification and price differentiation simultaneously, as registration tier determines which microbial developers can access premium formulation segments versus commodity inoculant tiers. The regulatory barrier compresses independent developer margins while rewarding integrated conglomerates with proprietary strain libraries and controlled-environment application infrastructure.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in microbial seed treatment markets. Price differentiation rests on certification grade—EPA-registered biopesticide tier versus state-level biostimulant specification—and volume scale commitments from integrated grain processors. Cost compression in the economy tier is intensifying because Brazilian and Argentine distributors are consolidating procurement at the elevator level. Smallholder cooperatives in India's pulse belts exhibit the highest price sensitivity, while North American ethanol facility operators demonstrate the least due to bundled agronomic protocol requirements.
Supply Chain Analysis
Brazil and the United States anchor global fermentation capacity for Bradyrhizobium and Bacillus strain production, with Germany sustaining encapsulation technology R&D infrastructure. Raw material dependencies center on specific growth media substrates, polymer carrier chemistries, and cold-chain logistics equipment. Single-source vulnerability concentrates in tropical last-mile distribution networks where temperature-sensitive inoculants face viability loss. Distribution runs through integrated seed-chemistry platforms that bundle biological treatments with genetic trait packages at the commercial seed facility level.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Deep strain characterization expertise and fermentation scale-up capability pools remain shallow relative to synthetic chemistry talent markets, constraining competitive entry and acquisition target availability. This capability scarcity rewards early movers who secure microbiologist talent pipelines and captive fermentation infrastructure.
For Market Incumbents: Shield proprietary strain libraries through patent thickets around rhizobia and Bacillus taxonomies while accelerating encapsulation technology investment to extend microbial viability windows. The threat of streamlined biopesticide registration pathways in Argentina and Brazil enabling mid-scale biological developer entry demands preemptive capacity addition in São Paulo state fermentation facilities. Channel control through grain processor procurement protocol inclusion remains the critical defensive lever. For New Entrants and Emerging Players: ANVISA's accelerated biopesticide review timelines in Brazil create entry velocity for developers lacking legacy EPA registration portfolios. White-space concentrates in drone-based aerial inoculation systems for Mato Grosso soybean operations and carbon credit monetization protocols for nitrogen-fixing inoculants. The most penetrable segment is mid-scale vegetable operations in North American organic markets where residue tolerance thresholds sit below synthetic chemistry limits. A licensing partnership with established seed treater equipment manufacturers offers the fastest go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across encapsulation technology providers as polymer-based microencapsulation systems standardize shelf-life performance between commodity and premium tiers. Long-term viability over the next decade favors developers with backward integration into fermentation infrastructure rather than strain licensing models. Acquisition target archetypes include mid-scale Brazilian biological developers with ANVISA registration portfolios and Indian fermentation specialists benefiting from PLI scheme incentives. The signal to watch is grain processor procurement protocol consolidation at the elevator level across the US Corn Belt.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Acquisition | Proprietary Bradyrhizobium and Bacillus collections lock in nitrogen fixation market positioning against generic competitors. |
| Encapsulation Technology Licensing | Polymer microencapsulation systems from Bavarian R&D clusters extend microbial viability beyond 12-month thresholds. |
| Grain Processor Partnership | Elevator-level procurement protocol inclusion at Iowa and Illinois ethanol facilities secures volume offtake commitments. |
| Fermentation Capacity Expansion | São Paulo state production infrastructure captures Brazilian soybean frontier demand while reducing import dependency. |
| Carbon Credit Protocol Development | Soil carbon sequestration qualification for nitrogen-fixing inoculants opens premium pricing in agricultural offset frameworks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with seed company R&D directors, fermentation facility managers, grain processor agronomists, and agricultural cooperative procurement leads. Secondary validation drew from EPA biopesticide registration databases, ANVISA approval filings, EU Farm to Fork strategy documents, and customs trade data for microbial inoculant imports. Bottom-up strain-level production estimates were triangulated against top-down crop acreage treatment rates across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning microbial taxonomy, crop system value tier, treatment method equipment compatibility, and end-user scale classification. CAGRs were derived from trend extrapolation of acreage treatment penetration rates and per-hectare inoculant dosage intensities. Forecast inputs incorporated EU Green Deal subsidy redirection trajectories and Brazilian soybean frontier expansion cadence.
Underlying assumptions cover regulatory pathway stability and cold-chain logistics cost trajectories, with deviation risk concentrated in biopesticide registration timeline compression and grain processor procurement consolidation velocity. Recalibration cycles align with material shifts in EPA registration framework amendments and ANVISA review procedure updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
Microbial Identification Panels Market
Industrial Microbiology
Microbiology Culture Market
Industrial Microbiology
Molecular Microbiology Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Bacterial Amylase Market
Industrial Microbiology
Microbial API Market
Industrial Microbiology
Europe Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Microbial Bioreactors Market
Industrial Microbiology
Global Starter Culture Market
Industrial Microbiology
Benzoate-Free Enzymes Market
Industrial Microbiology
Galactosidase Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
B-Glucuronidase Enzymes Market
Industrial Microbiology
Microbial-Derived Fiber Market