
 Microbial Bioreactors Market | 2026-2036
Microbial Bioreactors Market Size, Share, and Industry Trends Forecast 2026-2036
Microbial Bioreactors Market Foresight
Single-use specification upgrades is reorganizing competitive dynamics in microbial bioreactors. Sartorius AG leverages its Biohit platform portfolio to dominate upstream single-use processing. Thermo Fisher Scientific anchors North American supply through integrated bioproduction workflows. Merck KGaA differentiates via membrane-aerated bioreactor technology for high-cell-density cultures.
Microbial bioreactors are closed vessels designed to maintain controlled environmental conditions for microbial cell cultivation, typically operating at volumes from laboratory-scale milliliters to production-scale thousands of liters with precise regulation of dissolved oxygen, pH, temperature, and agitation speed. Their primary purpose spans biopharmaceutical protein expression, industrial enzyme manufacturing, and biofuel fermentation processes. Stirred tank systems occupy the largest installed base due to operational familiarity and scale flexibility, while fed-batch technology sustains the dominant revenue share in biopharmaceutical applications where product titer optimization drives equipment selection. Continuous processing represents the fastest-growing technology segment as manufacturers pursue steady-state operation for cost reduction.
FDA process analytical technology guidelines and EMA good manufacturing practice standards for biologics production shape equipment validation requirements and data integrity protocols across manufacturing facilities. ISO 14644 cleanroom classifications and ASME bioprocessing equipment standards further constrain design specifications for commercial-scale installations. Stakeholders must evaluate whether hybrid processing architectures or fully continuous platforms align with emerging regulatory expectations for real-time release testing.
Market Dynamics
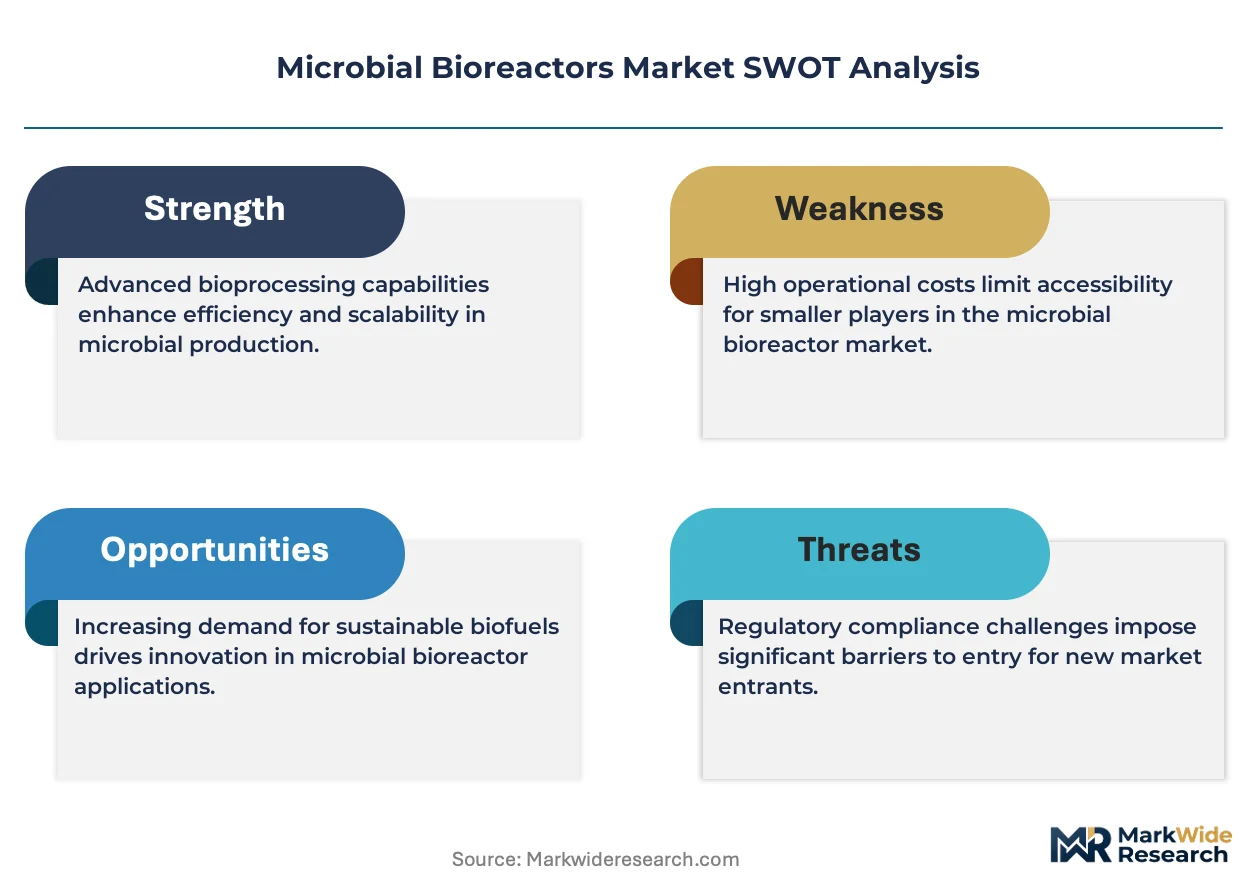
Single-use bioreactor specifications are forcing incumbent stainless-steel vendors to reengineer product architectures or cede upstream processing contracts to disposable specialists. This technology pivot compresses equipment replacement cycles and redistributes margin pools across the supply base.
Growth Catalysts
- FDA Process Analytical Technology:Mandatory real-time quality monitoring drives replacement of legacy batch-control systems with sensor-integrated bioreactor platforms in US biologics facilities.
- High-cell-density fermentation:Microbial expression systems achieve gram-per-liter titers previously requiring mammalian platforms, expanding addressable indications for bacterial hosts.
- China biologics manufacturing clusters:NMPA streamlined approval pathways for biosimilars attract contract manufacturing investment to Suzhou and Shanghai biotechnology zones.
Market Restraints
- Single-use film supply concentration:Three suppliers control medical-grade polymer resin production, exposing bioreactor manufacturers to input cost volatility and allocation constraints.
- ASME bioprocessing equipment certification:Pressure vessel standards impose 18-24 month validation timelines that delay commercial-scale stainless-steel installations.
- Continuous processing skill scarcity:Steady-state operation requires metabolic flux control expertise concentrated among academic and specialized contract research organizations.
Strategic Opportunities
- India contract development market:CDSCO manufacturing-linked incentives and 10-year tax holidays for biologics production attract microbial platform investments to Hyderabad and Bengaluru.
- Cell-free protein synthesis:Convergence of synthetic biology and continuous flow chemistry enables extract-based biomanufacturing without live culture constraints.
- EU Green Deal industrial biotech mandate:Renewable chemical production quotas create dedicated offtake for bio-based platform molecules from engineered microbial hosts.
Industry Challenges
- Bioprocess data scientist scarcity:Multivariate statistical process control and machine learning model deployment require hybrid skill sets rare in traditional fermentation engineering.
- Legacy distributed control system integration:Brownfield facilities face protocol translation complexity when retrofitting single-use sensors into 1990s-era automation architectures.
- Cross-contamination validation protocols:Campaign changeover documentation for multiproduct facilities consumes 15-20% of available production capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microbial Bioreactors Market |
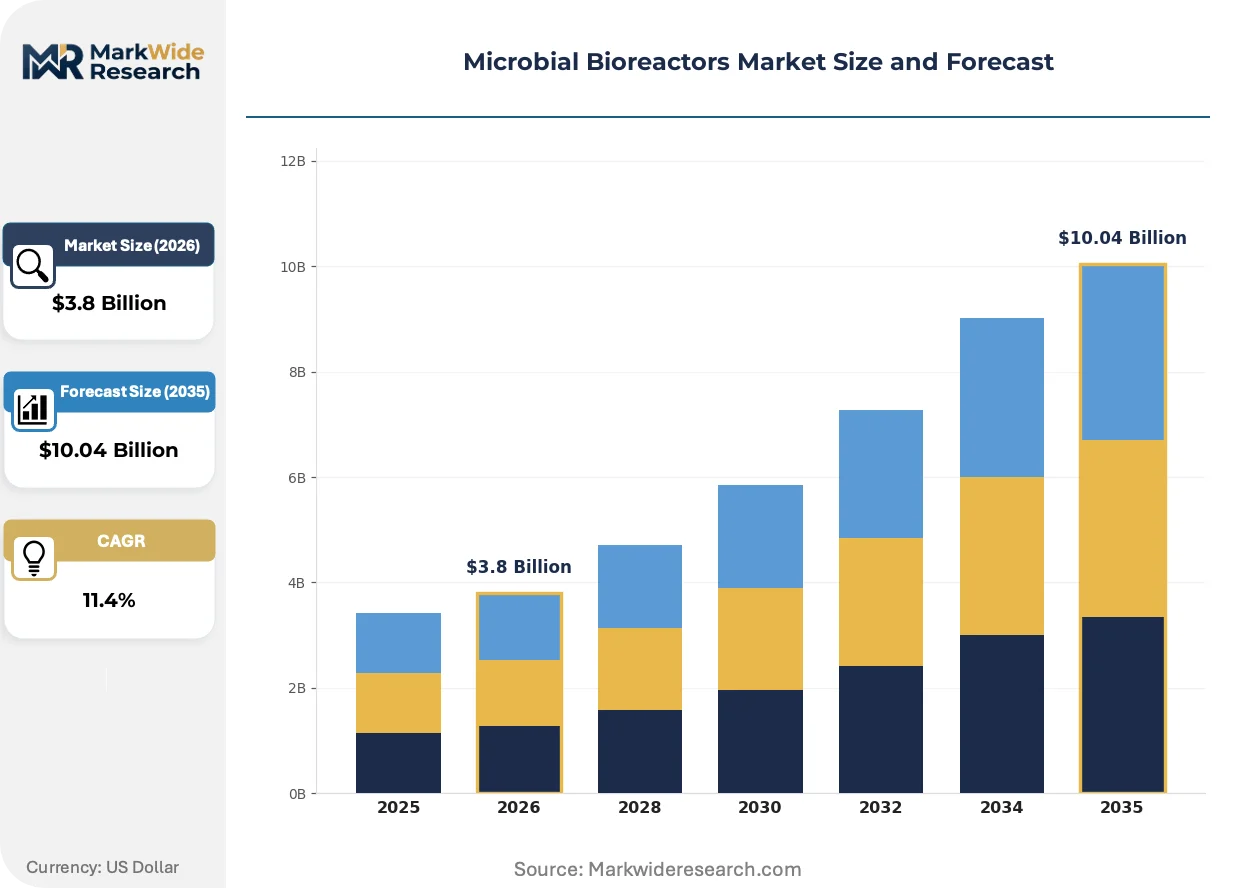
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stirred Tank, Fixed Bed, Airlift, Bubble Column Technology: Batch, Continuous, Fed-Batch, Hybrid End User: Biotechnology Firms, Pharmaceutical Companies, Research Institutions, Food Industry Application: Biopharmaceuticals, Enzyme Production, Biofuels, Waste Treatment |
| Companies Covered | Sartorius AG, Thermo Fisher Scientific Inc., Merck KGaA, Danaher Corporation, Eppendorf AG, Infors AG, Applikon Biotechnology, Solaris Biotechnology Srl, m2p-labs GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microbial Bioreactors Market Shifts & Advancements
Process intensification architectures are collapsing the boundary between upstream and downstream unit operations, compressing facility footprints and redefining capital deployment patterns for microbial manufacturing.
Perfusion-enabled microbial cultivation is fragmenting the traditional fed-batch paradigm. High-cell-density retention systems achieve steady-state operation at 200+ grams per liter dry cell weight. Contract manufacturers in Germany and Massachusetts adopt these platforms for enzyme and API production. The technology is fragmenting equipment vendor specialization boundaries as mixing, separation, and cell retention functions consolidate into integrated skid designs.
EMA's revised Annex 1 sterile manufacturing guidelines mandate closed-system processing for all aseptic operations effective August 2023. This regulatory compression accelerates demand for pre-sterilized single-use bioreactor assemblies with validated barrier integrity. European vaccine and biosimilar producers requalify open stainless-steel vessels ahead of enforcement deadlines, redirecting capital toward disposable platform investments.
Biopharmaceutical procurement teams now unbundle equipment purchase from validation service contracts, creating competitive tension between original equipment manufacturers and specialized commissioning consultancies. Large molecule developers in the United States and Switzerland separately source bioreactor hardware, automation integration, and protocol execution. This disaggregation compresses OEM service margins while elevating niche validation providers with platform-specific regulatory track records.
Microbial Bioreactors Market Segmentation
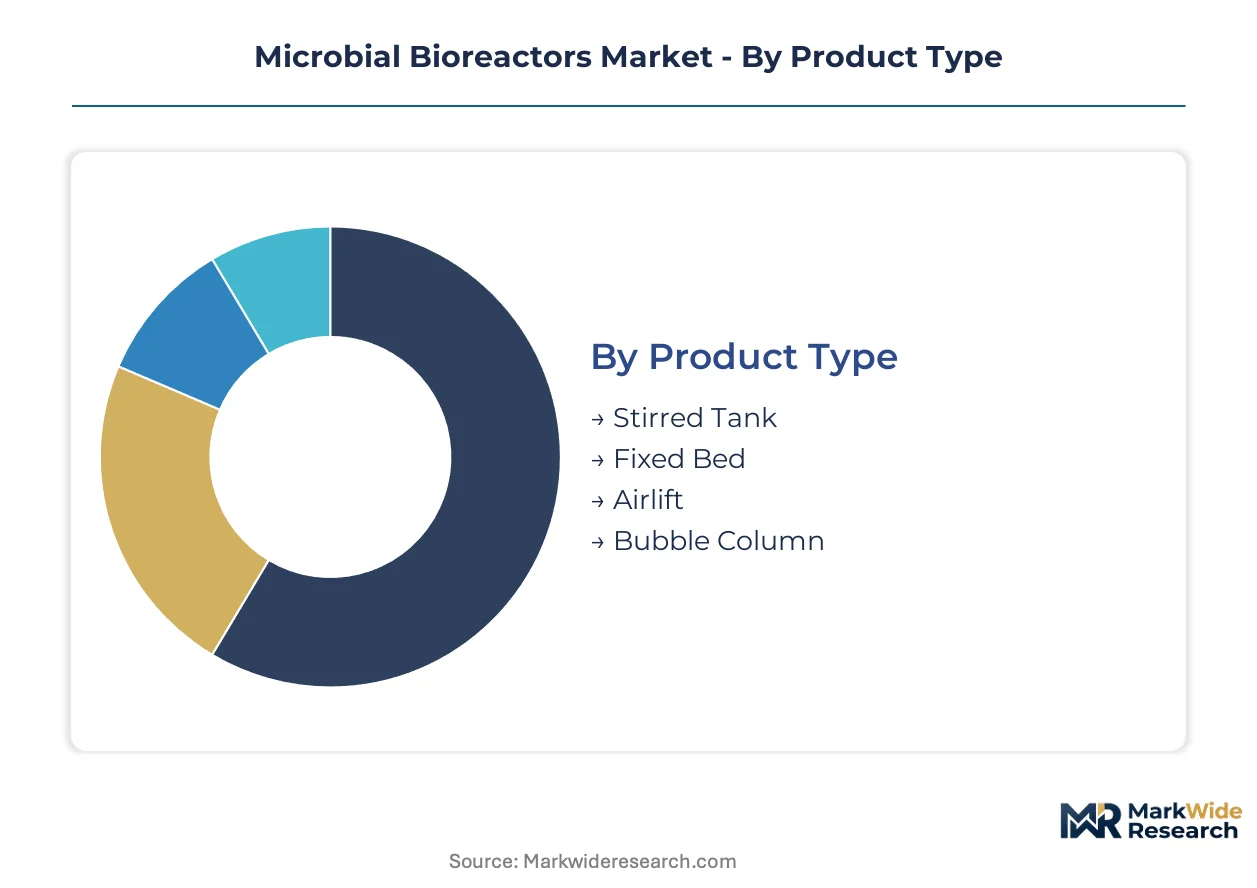
Equipment selection in microbial bioreactors follows distinct procurement pathways. Pharmaceutical manufacturers prioritize validated platforms with regulatory documentation, while research institutions optimize for flexibility and capital efficiency. Understanding these channel dynamics enables targeted positioning across divergent customer workflows.
Product Type:
Original equipment manufacturers route stirred tank and airlift systems through direct sales teams serving large-scale pharmaceutical accounts, while fixed bed and bubble column platforms flow increasingly through distribution partners targeting research and food industry segments.
- Stirred Tank:Mechanical agitation systems dominate commercial-scale installations with proven scalability from 50-liter pilot to 20,000-liter production vessels. Pharmaceutical manufacturers in Germany and the United States specify these platforms for monoclonal antibody precursor fermentation, driven by regulatory familiarity and extensive vendor service networks.
- Airlift:Gas-driven circulation eliminates mechanical seals, reducing contamination risk in extended perfusion campaigns. Biotechnology firms in Massachusetts and Swiss biotech clusters adopt these systems for high-cell-density microbial cultures, constrained by oxygen transfer limitations at extreme scale.
- Fixed Bed:Immobilized cell matrices suit continuous enzyme production with minimal shear stress on filamentous organisms.
- Bubble Column:Simple cylindrical geometry offers capital cost advantages for bulk biofuel fermentation with lower mixing energy requirements.
By volume, stirred tank leads. By growth pace, airlift is ahead.
Technology:
Cost tier differentiation separates mature batch infrastructure from premium continuous platforms, with fed-batch occupying the mid-tier investment band where most capacity expansion currently concentrates.
- Fed-Batch:Intermittent nutrient feeding extends culture duration while maintaining substrate below inhibitory concentrations. This modality captures dominant revenue share across biopharmaceutical applications in the United States and China, where product titer optimization justifies extended campaign timelines and sophisticated process analytical technology integration.
- Continuous:Steady-state operation with constant inflow and harvest achieves higher volumetric productivity and smaller facility footprints. Contract manufacturers in Germany and emerging biotechnology zones in India deploy perfusion-enabled continuous platforms, constrained by metabolic flux control expertise scarcity and complex regulatory validation pathways.
- Batch:Complete sterilization between campaigns remains standard for multiproduct facilities with frequent changeover requirements.
- Hybrid:Combinations of batch seed trains with continuous production vessels balance operational familiarity with intensification benefits.
Fed-batch commands installed base dominance. Continuous platforms are climbing the fastest.
End User:
Customer type determines specification rigor, with pharmaceutical companies demanding extensive qualification documentation that research institutions and food producers often waive.
- Pharmaceutical Companies:GMP-compliant systems with validated automation and comprehensive batch records support commercial biologics manufacturing. These buyers in the United States, Germany, and Switzerland drive specification upgrades toward single-use and continuous platforms, constrained by legacy distributed control system integration complexity in brownfield facilities.
- Biotechnology Firms:Agile development organizations prioritize rapid platform deployment and scale flexibility for pipeline candidates. Emerging companies in China's Suzhou and Shanghai biotechnology zones favor configurable skid-mounted systems, balancing speed-to-clinic against later commercial transfer requirements.
- Research Institutions:Academic and government laboratories emphasize capital efficiency and multi-purpose utility across diverse microbial hosts.
- Food Industry:Enzyme and additive producers optimize for throughput economics with less stringent sterile processing requirements.
Pharmaceutical companies anchor premium segment revenue. Biotechnology firms are expanding most quickly.
Application:
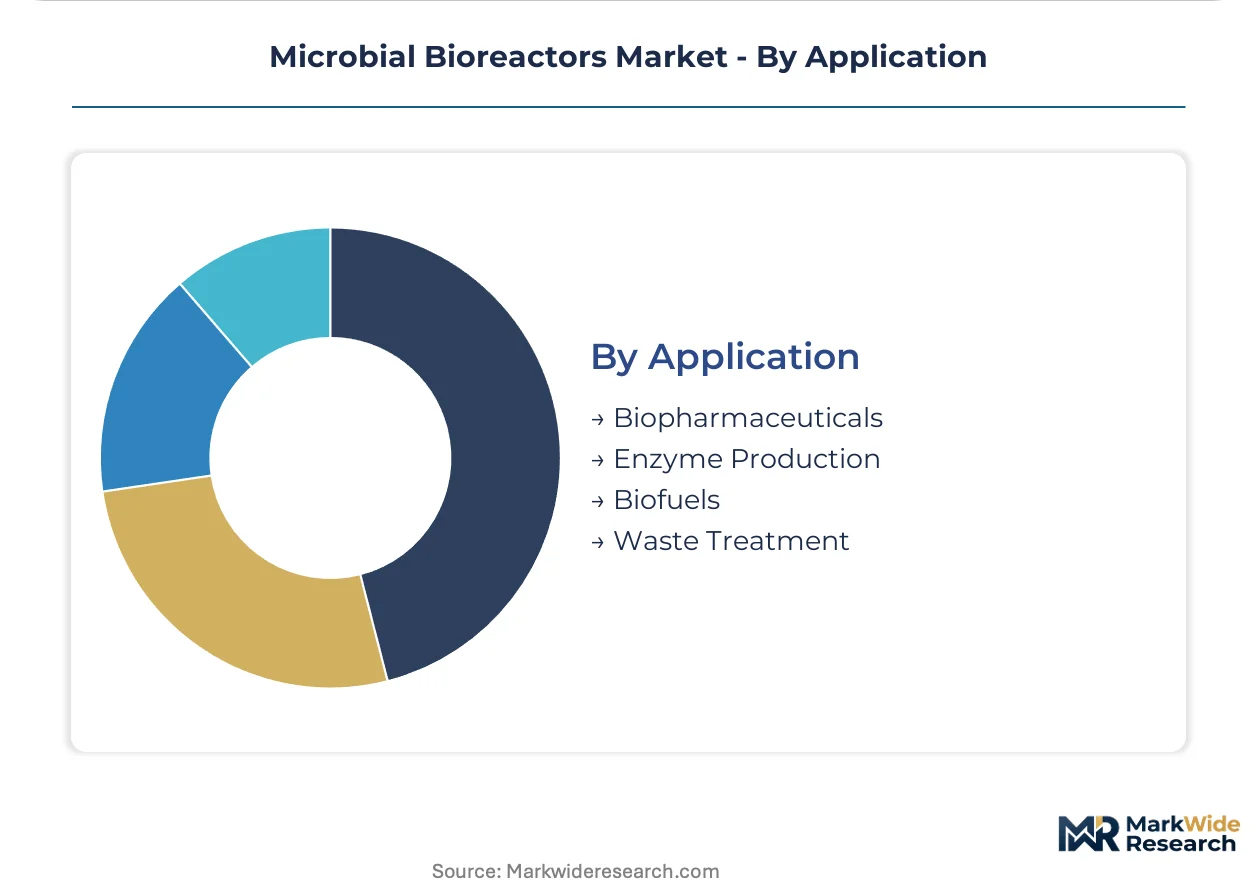
Application maturity shapes margin profiles, with biopharmaceuticals commanding premium pricing against commoditized biofuel and waste treatment segments.
- Biopharmaceuticals:Recombinant protein and vaccine antigen production demands precise environmental control and extensive contamination prevention. This segment concentrates demand in the United States and Germany, where FDA and EMA guidelines for process analytical technology and sterile manufacturing reshape equipment specifications toward closed-system single-use architectures.
- Enzyme Production:Industrial biocatalyst manufacturing for detergents, textiles, and food processing operates at substantially larger scale with lower unit value. Producers in Denmark and the Netherlands deploy specialized high-cell-density fermentation platforms, constrained by oxygen transfer limitations at the extreme cell densities required for economic viability.
- Biofuels:Cellulosic ethanol and advanced biofuel fermentation prioritizes feedstock flexibility and capital cost minimization.
- Waste Treatment:Anaerobic digestion and bioremediation applications tolerate broader operational windows with reduced instrumentation requirements.
Biopharmaceuticals lead by value contribution. Enzyme production is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in microbial bioreactors tilt toward net imports in emerging biologics manufacturing zones while established production clusters in Germany and the United States supply validated equipment to contract manufacturers in Asia. Trade flows concentrate specialized single-use assemblies and sensor-integrated platforms from Western fabricators to facilities in China and India.
United States
FDA process analytical technology mandates drive replacement of legacy batch-control systems with sensor-integrated platforms. The 21 CFR Part 11 electronic records framework shapes data integrity protocols for commercial biologics facilities. Greater Boston and San Francisco biotechnology clusters anchor demand for perfusion-enabled continuous processing systems among emerging biotech developers.
Germany
EMA Annex 1 sterile manufacturing guidelines accelerate facility requalification toward closed-system single-use architectures. The country's national pharmaceutical regulator enforces strict validation timelines for pressure vessel certifications. Bavaria and North Rhine-Westphalia concentrate contract manufacturing investment in high-cell-density fermentation platforms for enzyme production.
China
NMPA streamlined biosimilar approval pathways attract foreign direct investment into biologics manufacturing capacity. Dual carbon goals and renewable chemical production quotas create dedicated offtake for engineered microbial hosts. Suzhou and Shanghai biotechnology zones emerge as contract manufacturing hubs importing validated single-use assemblies from European suppliers.
India
CDSCO manufacturing-linked incentives and 10-year tax holidays for biologics production draw microbial platform investments. The country's national pharmaceutical regulator harmonizes good manufacturing practice standards with WHO prequalification requirements. Hyderabad and Bengaluru anchor contract development and manufacturing organization expansion for export-oriented biopharmaceutical production.
Switzerland
Swissmedic guidelines for biologics production align with EMA standards while permitting accelerated access pathways for innovative therapies. The country's pharmaceutical regulator emphasizes real-time release testing and continuous manufacturing validation. Basel and Zurich biotech clusters demand premium single-use platforms with integrated process analytical technology for monoclonal antibody precursor fermentation.
Microbial Bioreactors Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and regulatory documentation capabilities. Tier-one diversified life science conglomerates anchor premium segments through integrated bioproduction workflows. Mid-scale equipment fabricators occupy standard-tier positioning with configurable skid-mounted systems. Technology licensing and strategic distribution partnerships constitute the dominant competitive moves as vendors seek geographic coverage without direct sales infrastructure.
Among Germany-based diversified suppliers, Sartorius AG and Eppendorf AG exemplify tier-one positioning through upstream single-use processing portfolios. Thermo Fisher Scientific Inc. anchors North American supply chain integration. These three entities represent contrasting archetypes: Sartorius occupies membrane-aerated specialization, Eppendorf exemplifies laboratory-to-production scalability, and Thermo Fisher embodies workflow integration across analytical and bioproduction domains.
| Leading Market Players |
|---|
| Sartorius AG |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Danaher Corporation |
| Eppendorf AG |
| Infors AG |
| Applikon Biotechnology |
| Solaris Biotechnology Srl |
| m2p-labs GmbH |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with medical-grade polymer suppliers lock in both film allocation and price visibility for bioreactor manufacturers confronting single-use demand surges. These arrangements transfer input cost volatility risk downstream while constraining spot-market flexibility for smaller fabricators without offtake coverage.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium validated systems, standard configurable platforms, and economy research-grade vessels. Price differentiation rests on FDA certification tier and automation integration depth, with pharmaceutical manufacturers in Germany and Switzerland least sensitive to premium positioning. Cost compression in standard-tier skids intensifies as Chinese contract manufacturers scale membrane-aerated alternatives. Research institutions and food enzyme producers exhibit highest price sensitivity, prioritizing capital efficiency over qualification documentation.
Supply Chain Analysis
Inventory lead times for medical-grade polymer films stretch 16-20 weeks, constraining bioreactor assembly schedules and amplifying working capital requirements for single-use specialists. Supply concentrates in the United States, Germany, and China, with film resin production anchored in Texas and Bavaria while final assembly clusters in Suzhou and Shanghai. Raw material dependencies span fluoropolymer films, platinum-cured silicone tubing, and gamma-sterilization services. Single-source vulnerability in gamma irradiation capacity poses structural risk. Distribution runs through direct OEM sales teams for pharmaceutical accounts and specialized distribution partners targeting research segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Metabolic flux control expertise scarcity constrains continuous processing adoption, creating asymmetric returns for stakeholders who secure this capability ahead of regulatory validation requirements for real-time release testing.
For Market Incumbents: Secure exclusive offtake agreements with medical-grade polymer resin suppliers to defend against input allocation constraints threatening single-use platform margins. Deepen backward integration into gamma-sterilization capacity to reduce dependency on third-party irradiation chokepoints. Prioritize sensor-integrated platform R&D to maintain specification leadership against emerging Chinese competitors with cost-optimized alternatives. For New Entrants and Emerging Players: Anchor in India's CDSCO-linked manufacturing incentives and 10-year tax holidays for biologics production, where validation service bundling remains underdeveloped relative to hardware supply. Target contract development organizations in Hyderabad and Bengaluru with skid-mounted configurable platforms priced below German and US incumbents. Pursue validation partnership models that separate equipment purchase from protocol execution, mirroring procurement disaggregation trends among large molecule developers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among validation service providers with platform-specific regulatory track records, suggesting superior cash-flow quality relative to pure hardware OEMs. Acquisition focus should center on mid-scale fabricators with membrane-aerated specialization and established EMA documentation libraries. Monitor NMPA biosimilar approval velocity as inflection indicator for Chinese contract manufacturing capacity expansion and associated equipment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Film Supply | Captive resin access insulates margin structure from medical-grade allocation constraints during demand surges. |
| Continuous Processing Platform Certification | EMA real-time release testing validation opens premium pricing tier for steady-state microbial cultivation systems. |
| Validation Service Unbundling | Separate protocol execution contracts capture procurement disaggregation among US and Swiss large molecule developers. |
| India Manufacturing Footprint Expansion | CDSCO incentives and tax holidays attract microbial platform investments to Hyderabad and Bengaluru clusters. |
| Sensor-Integrated Single-Use Development | FDA process analytical technology mandates drive replacement demand for legacy batch-control architectures. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with bioprocess engineers, regulatory affairs leads at pharmaceutical manufacturers, contract manufacturing procurement directors, and single-use platform engineering specialists; and secondary validation through FDA 510(k) filings, EMA scientific advice outcomes, NMPA biosimilar approval databases, and ASME bioprocessing equipment certification records. Bottom-up equipment shipment estimates triangulated against top-down biologics capacity expansion announcements across the United States, Germany, and China.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation by product type, technology modality, end-user archetype, and application with regional regulatory cluster overlays. CAGRs derived from weighted capacity expansion pipelines and technology substitution curves. Industry-specific forecast inputs incorporated perfusion adoption rates among contract manufacturers and single-use penetration assumptions in brownfield stainless-steel retrofit scenarios.
Decision-makers should treat outputs as directional under assumptions of sustained FDA process analytical technology enforcement and stable medical-grade polymer supply allocation; material deviation in regulatory timelines or input cost volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Lactobacillus Strains Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Global Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Global Microbial Fermentation Technology Market
Industrial Microbiology
Bacillus Coagulans Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
Microbial-Derived Fiber Market
Industrial Microbiology
Middle East Feed Probiotics Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Global Microbial Identification Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Microbial Culture Market
Industrial Microbiology
Microbial Biosurfactants Market