
 Europe Microbial Based Biological Seed Treatment Market | 2026-2036
Europe Microbial Based Biological Seed Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Microbial Based Biological Seed Treatment Market Foresight
CE marking under the EU Fertilising Products Regulation is rotating market access eligibility for biological seed treatment manufacturers. BASF SE leverages its strain development pipeline to sustain leadership in bacterial formulations for European row crops. Bayer AG anchors its position through integrated seed health platforms that span microbial discovery to distribution. Novozymes A/S competes on enzyme-microbe synergy, occupying a distinct niche in biocatalytic seed enhancement technologies.
Microbial based biological seed treatment encompasses living microorganisms—bacteria, fungi, yeasts, or algae—applied to seeds to improve germination, nutrient acquisition, or pathogen resistance through colonization of the rhizosphere or systemic induced resistance. These formulations typically contain 10^6 to 10^9 colony-forming units per gram and are stabilized through proprietary carriers or encapsulation to maintain viability through storage and sowing. Liquid formulation technology leads European manufacturing due to compatibility with existing seed treating equipment, while coated seeds capture expanding margin pools as integrated delivery systems gain traction among large-scale farmers. Bacterial products dominate volume, though fungal segments show accelerated development against soil-borne pathogens in vegetable production systems.
EMA and EFSA jointly shape European biological seed treatment standards through parallel assessments of microbial strain safety and residue profiles under evolving EU sustainable use frameworks. The EU Green Deal and national implementations of the Farm to Fork strategy tighten chemical pesticide thresholds, directly expanding addressable demand for certified biological alternatives. REACH compliance and emerging CSRD reporting obligations add compliance layers that favor established manufacturers with dedicated regulatory affairs capacity. Stakeholders must monitor strain patent cliffs and national subsidy program revisions to time portfolio transitions effectively.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is compressing chemical pesticide thresholds across member states, forcing a structural pivot toward certified biological alternatives in cereal and vegetable seed systems. This regulatory compression is redrawing competitive positioning around strain patent portfolios and CE marking velocity.
Growth Catalysts
- Farm to Fork Mandates:The EU Green Deal tightens residue limits for synthetic pesticides, expanding addressable demand for microbial seed treatments in French wheat and German maize production corridors.
- Precision Agriculture Corridors:Germany's Rhine-Main and Bavarian farming clusters are integrating liquid biological formulations with variable-rate seeding equipment, pulling compatible product development.
- Rhizosphere Colonization Science:Advances in strain selection for systemic induced resistance are improving establishment reliability under abiotic stress, reducing perceived performance risk among risk-averse growers.
Market Restraints
- Strain Viability Logistics:Cold chain requirements for formulations containing 10^6 to 10^9 CFU per gram elevate distribution costs and limit shelf life in Southern Europe's warmer storage environments.
- REACH Compliance Burden:ECHA registration processes for novel microbial strains extend time-to-market by 18-36 months, favoring incumbents with dedicated regulatory affairs infrastructure.
- Chemical Treatment Substitution:Neonicotinoid restrictions have intensified, yet residual chemical seed treatment capacity in Eastern European supply chains delays full biological conversion.
Strategic Opportunities
- Vegetable Production Systems:Fungal segment development against soil-borne pathogens in Spanish and Italian protected horticulture remains underpenetrated relative to bacterial dominance in row crops.
- CSRD Reporting Tailwinds:Emerging corporate sustainability reporting obligations are creating procurement preference for certified biological inputs among integrated food processors and cooperatives.
- Encapsulation-Convergence:Synergy between biocatalytic enzyme platforms and microbe stabilization technologies is opening premium positioning for integrated seed health delivery systems.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Parallel EMA and EFSA assessment expertise is concentrated among a narrow specialist cohort, constraining portfolio expansion timelines for mid-scale manufacturers.
- Legacy Equipment Compatibility:Retrofitting existing seed treating infrastructure for biological liquid formulations requires capital deployment that smaller agricultural service providers struggle to prioritize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Microbial Based Biological Seed Treatment Market |
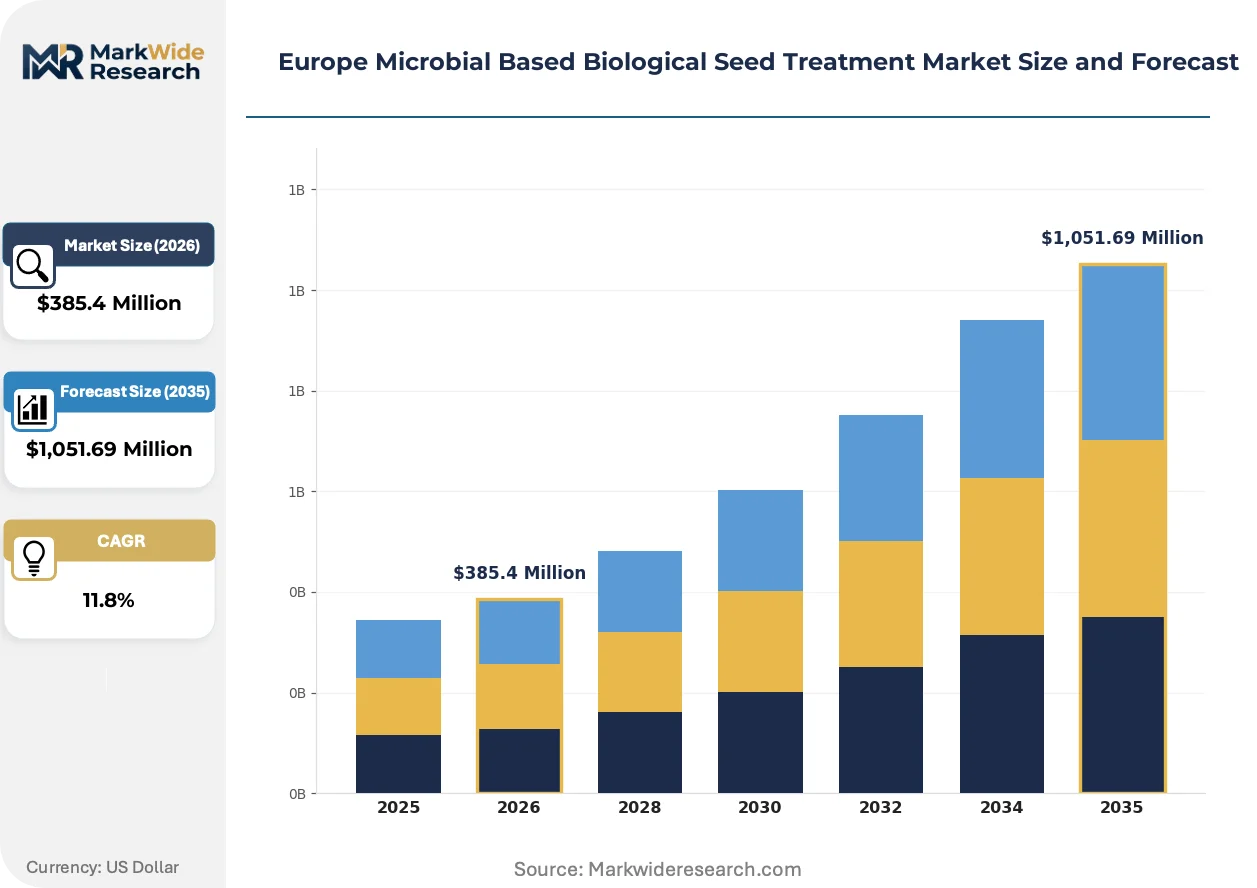
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,051.69 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial, Fungal, Yeast, Algal Application: Crops, Vegetables, Fruits, Ornamental Plants Technology: Liquid Formulation, Granular Formulation, Powder Formulation, Coated Seeds End User: Farmers, Agricultural Cooperatives, Seed Distributors, Research Institutions |
| Companies Covered | BASF SE, Bayer AG, Syngenta Crop Protection AG, Novozymes A/S, Corteva Agriscience, UPL, FMC Corporation, Koppert, Germains Seed Technology, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Microbial Based Biological Seed Treatment Market Shifts & Advancements
Formulation chemistry and regulatory architecture are decomposing traditional barriers between biological efficacy and operational convenience. Three developments are compressing the gap between laboratory performance and field-scale deployment.
Encapsulation technology is decomposing the viability-storage tradeoff that has constrained microbial seed treatment adoption. Coated seed systems with proprietary carrier matrices are penetrating large-scale farming operations in France and Germany. This stabilization advance is compressing margin pools toward integrated delivery systems and away from standalone liquid formulations.
CE marking under the EU Fertilising Products Regulation is rotating market access eligibility quarterly as strain dossiers advance through EMA-EFSA parallel review. Manufacturers with dedicated regulatory capacity are capturing shelf space faster than competitors reliant on third-party registration support. Vegetable seed segments show the most pronounced responsiveness to certification velocity.
Cooperative procurement collectives in the Netherlands and Denmark are consolidating biological input purchasing through multi-year supply agreements. Traditional distributor networks face compression as farmer-owned buying groups negotiate direct manufacturer relationships. This channel restructuring is most visible in cereal seed systems where volume concentration justifies dedicated formulation runs.
Europe Microbial Based Biological Seed Treatment Market Segmentation
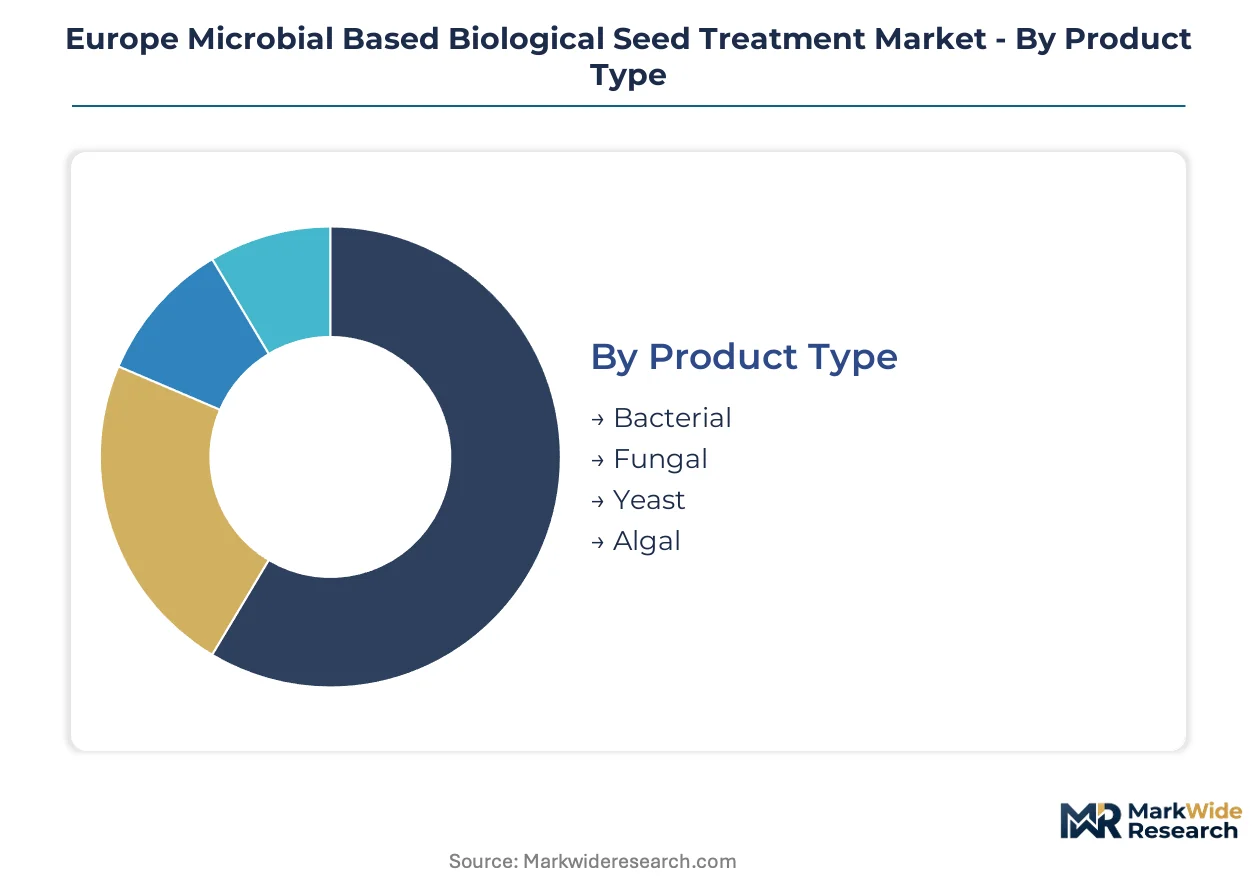
Segmentation reveals how microbial seed treatments flow through divergent channel economics. Product type determines manufacturing scale requirements. Technology choice locks in equipment compatibility and margin structure. Application and end-user dimensions expose where biological conversion is penetrating fastest versus where chemical legacy persists.
Product Type:
Bacterial formulations move through high-volume liquid channels into German precision agriculture corridors. Fungal and algal alternatives concentrate in specialized distributor networks serving protected horticulture.
- Bacterial:These formulations contain 10^6 to 10^9 CFU per gram of rhizosphere-colonizing species such as Bacillus and Pseudomonas. French cereal growers are expanding adoption for wheat establishment as EU Green Deal residue limits tighten. Cold chain logistics constrain Southern European distribution.
- Fungal:Trichoderma and mycorrhizal preparations target soil-borne pathogens through systemic induced resistance. Spanish and Italian vegetable production systems show accelerated development where bacterial dominance in row crops has not penetrated. Encapsulation advances are improving establishment reliability.
- Yeast:Saccharomyces-based biostimulants occupy niche positioning in organic certification tiers. Demand concentrates among Dutch cooperative procurement collectives.
- Algal:Cyanobacterial and microalgal extracts deliver phytohormone signaling for abiotic stress tolerance. Italian protected horticulture trials are evaluating field-scale viability.
Bacterial products dominate installed base. Fungal is where expansion concentrates.
Application:
Cost tier segmentation separates commodity cereal systems from premium horticulture. Margin structure in vegetables justifies formulation complexity that row crop economics cannot support.
- Crops:Wheat and maize seed treatment in France and Germany anchors volume demand. CE marking velocity under EU Fertilising Products Regulation determines manufacturer shelf space capture. Farm to Fork mandates are compressing chemical substitution timelines.
- Vegetables:Tomato, pepper, and cucurbit systems in Spanish Almería and Italian Po Valley greenhouses command premium positioning. Fungal segment development against Pythium and Phytophthora remains underpenetrated relative to bacterial row crop dominance.
- Fruits:Vineyard and orchard applications in Bordeaux and Piedmont focus on replant disease suppression. Strain patent cliffs are timing portfolio transitions for established manufacturers.
- Ornamental Plants:Bulb and bedding plant propagation in Dutch Aalsmeer corridor drives small-batch formulation demand. Research institutions anchor technical specification setting.
Crops generate the highest absolute volume. Vegetables deliver steepest expansion trajectory.
Technology:
Volume concentration favors liquid compatibility with existing treating infrastructure. Margin pools are compressing toward integrated coated seed systems as large-scale farmers demand operational convenience.
- Liquid Formulation:Suspension concentrates and emulsifiable concentrates dominate European manufacturing. Compatibility with variable-rate seeding equipment in Germany's Rhine-Main cluster pulls product development. Shelf life limitations under warm storage constrain Southern European penetration.
- Granular Formulation:Carrier-based delivery systems enable broadcast application without specialized treating equipment. Eastern European supply chains retain residual capacity here.
- Powder Formulation:Dust and wettable powder formats persist in organic certification tiers where synthetic binder restrictions apply. Dutch cooperative procurement is consolidating purchasing through multi-year agreements.
- Coated Seeds:Proprietary encapsulation matrices with integrated biocatalytic enzymes are penetrating large-scale farming operations. Bayer AG and BASF SE compete on integrated seed health platform completeness.
Liquid formulation leads manufacturing volume. Coated seeds is where margin expansion concentrates.
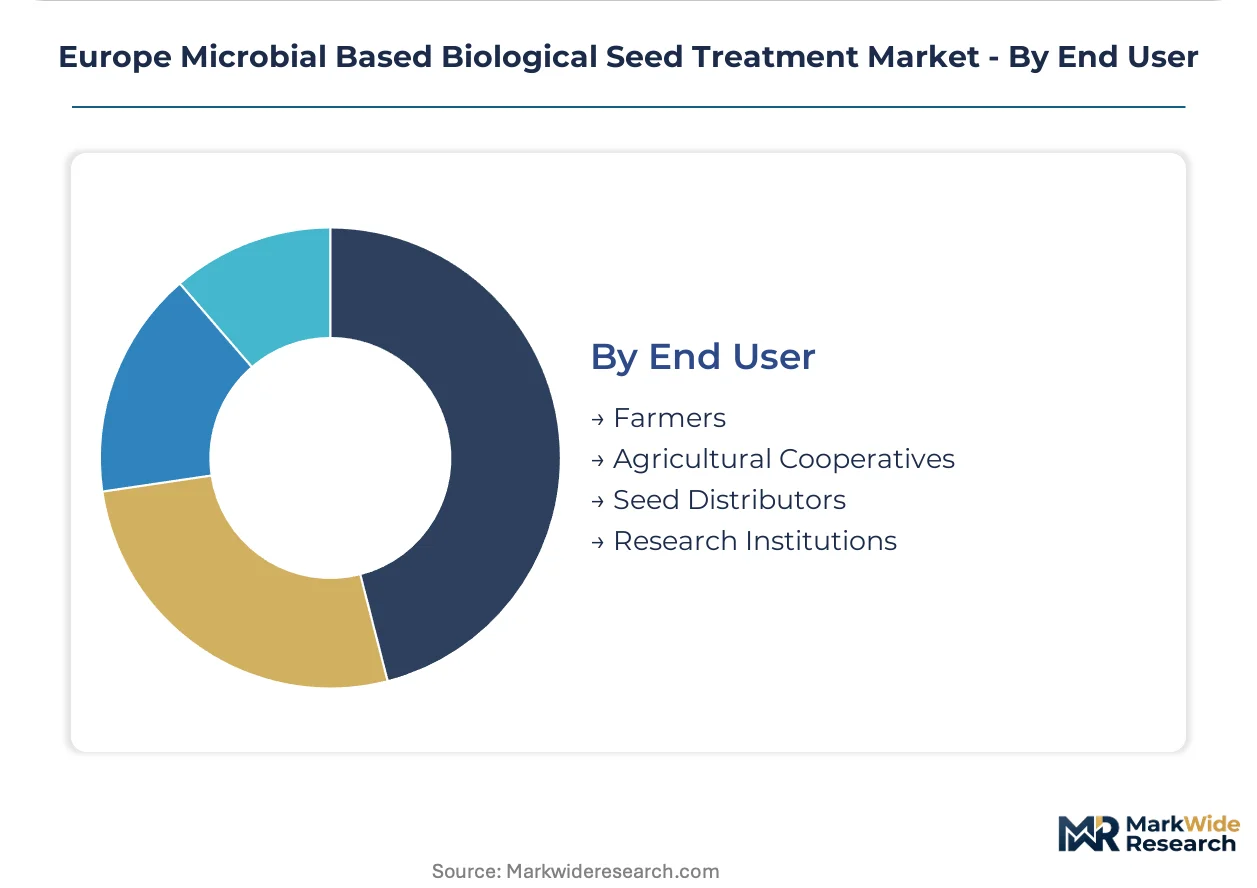
End User:
Customer type determines purchasing consolidation intensity. Farmer-owned buying groups are compressing traditional distributor networks in cereal systems where volume justifies direct manufacturer relationships.
- Farmers:Large-scale French cereal growers and German maize producers drive adoption through precision agriculture integration. Perceived performance risk under abiotic stress remains the primary adoption barrier.
- Agricultural Cooperatives:Dutch and Danish buying groups are consolidating biological input purchasing through multi-year supply agreements. Channel restructuring is most visible where volume concentration supports dedicated formulation runs.
- Seed Distributors:Regional networks in Poland and Romania face compression as procurement collectives negotiate direct access. Legacy equipment retrofitting requirements strain smaller service provider capital deployment.
- Research Institutions:INRAE in France and Wageningen University in the Netherlands anchor strain selection science and regulatory dossier preparation. Parallel EMA and EFSA assessment expertise concentrates here.
Farmers dominate absolute demand. Agricultural cooperatives is where purchasing consolidation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale cereal growers and precision agriculture adopters concentrate purchasing power across Northern and Western Europe. Cooperative buying groups in the Netherlands and Denmark are consolidating procurement, while French and German farm clusters drive volume demand for bacterial inoculants.
Germany
Rhine-Main and Bavarian farming clusters integrate liquid biological formulations with variable-rate seeding equipment. ECHA registration processes under REACH extend time-to-market for novel strains, favoring established manufacturers. Precision agriculture corridors in Hesse and Lower Saxony pull compatible product development from suppliers with dedicated regulatory capacity.
France
Cereal growers in the Paris Basin and Champagne regions expand bacterial inoculant adoption for wheat establishment as EU Green Deal residue limits tighten. INRAE anchors strain selection science and regulatory dossier preparation near Versailles. Bordeaux vineyard applications focus on replant disease suppression through fungal segment development.
Netherlands
Farmer-owned buying groups consolidate biological input purchasing through multi-year supply agreements in the Randstad and Brabant regions. Dutch cooperative procurement compresses traditional distributor networks where volume justifies dedicated formulation runs. Aalsmeer corridor drives small-batch demand for ornamental plant propagation systems.
Spain
Almería greenhouse operations command premium positioning for tomato, pepper, and cucurbit seed treatments against soil-borne pathogens. Warm storage environments in Andalusia constrain shelf life for formulations requiring cold chain logistics. Fungal segment development remains underpenetrated relative to bacterial dominance in Northern European row crops.
Italy
Po Valley protected horticulture trials evaluate cyanobacterial and microalgal extracts for abiotic stress tolerance in vegetable production. Piedmont orchard applications target replant disease suppression alongside vineyard systems near Turin. Strain patent cliffs are timing portfolio transitions as national subsidy program revisions approach.
Europe Microbial Based Biological Seed Treatment Market Competitive Landscape
Player mix skews toward integrated agrochemical conglomerates with dedicated microbial discovery pipelines. Market structure concentrates around three tiers: global conglomerates with seed health platforms, specialized enzyme-microbe synergy providers, and regional formulation specialists serving protected horticulture. Dominant competitive moves include M&A activity targeting strain patent portfolios and capacity expansion for encapsulation-convergent delivery systems.
Within the integrated platform tier, BASF SE, Bayer AG, and Novozymes A/S exemplify divergent strategic positioning. BASF SE represents the strain development archetype with bacterial formulation leadership for European row crops. Bayer AG anchors the integrated seed health platform model spanning microbial discovery through distribution infrastructure. Novozymes A/S occupies the biocatalytic enzyme-microbe synergy niche, distinct from competitors focused on standalone microbial inoculants.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| Syngenta Crop Protection AG |
| Novozymes A/S |
| Corteva Agriscience |
| UPL |
| FMC Corporation |
| Koppert |
| Germains Seed Technology |
| Others |
Supply & Pricing Matrix
Capacity utilization at German encapsulation facilities shapes both supply concentration and price floors for coated seed systems across Northern Europe. Liquid formulation manufacturers in the Rhine-Main corridor face margin compression as large-scale French cereal growers consolidate purchasing through cooperative procurement collectives.
Pricing Analysis
Cost-plus contracts with rapeseed oil indexation dominate bacterial formulation procurement between Dutch cooperative buying groups and established manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked encapsulated products from liquid concentrates and unformulated technical grades. Price differentiation hinges on certification velocity under EU Fertilising Products Regulation and cold chain logistics bundling. Pricing pressure stems from Eastern European chemical seed treatment residual capacity. Smaller Polish seed distributors exhibit highest price sensitivity; German precision agriculture adopters show lowest.
Supply Chain Analysis
Inventory lead times for fungal strain mother cultures extend through ECHA registration review periods, tethering production planning to regulatory dossier preparation timelines. Manufacturing concentrates in Germany, France, and the Netherlands. Raw material inputs draw from rapeseed oil carriers, proprietary polymer encapsulation matrices, and cryopreservation stabilizers. Single-source vulnerability concentrates in specialized regulatory affairs talent pools. Distribution runs through cooperative procurement collectives in the Netherlands and Denmark alongside traditional seed distributor networks in Poland and Romania.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment. CE marking velocity under EU Fertilising Products Regulation creates switching costs that lock in manufacturer-buyer relationships across multi-year supply agreements.
For Market Incumbents: Secure strain patent portfolio extensions ahead of cliff expirations to block generic microbial formulation entry. Deepen backward integration into encapsulation matrix production to defend margin position against input cost volatility. Prioritize dedicated regulatory affairs capacity expansion to accelerate EMA-EFSA parallel assessment throughput. For New Entrants and Emerging Players: Service-layer gaps in fungal segment technical support for Spanish and Italian protected horticulture offer white-space entry points. Target underpenetrated vegetable seed systems in Almería and Po Valley greenhouses where bacterial row crop dominance has not reached. Pursue direct procurement relationships with Dutch cooperative buying groups as channel wedge. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers with multi-year cooperative supply agreements and dedicated formulation runs. Long-term viability favors vertically integrated platforms spanning strain discovery through distribution infrastructure. Monitor national subsidy program revisions as inflection signal for portfolio transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Capacity Expansion | Coated seed systems capture premium positioning in French and German large-scale farming operations. |
| Strain Patent Portfolio Acquisition | Pre-cliff expiration purchases block generic competition in bacterial formulation segments. |
| Regulatory Affairs Infrastructure Buildout | Dedicated EMA-EFSA expertise accelerates CE marking velocity for vegetable seed entrants. |
| Cooperative Procurement Partnership | Multi-year supply agreements with Dutch and Danish buying groups compress distributor margins. |
| Biocatalytic Enzyme Integration | Synergy platforms with Novozymes A/S occupy distinct positioning in seed health delivery systems. |
Research Methodology
A standing panel of seed treatment formulation scientists, regulatory affairs directors at agrochemical conglomerates, procurement managers at Dutch agricultural cooperatives, and precision agriculture equipment specialists provided ongoing calibration throughout data collection. Primary interview insights combined with secondary validation from EMA strain safety assessments, EFSA residue profile submissions, EU Fertilising Products Regulation CE marking databases, and Cefic agrochemical trade statistics. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Consistency checks validated projection outputs against external benchmarks including customs trade flows and cooperative procurement disclosure patterns. Segmentation modeling spanned microbial product type, application crop category, formulation technology, and end-user archetype across the analysis window. CAGRs derived from fitted growth curves applied to base-year volume estimates. Industry-specific forecast inputs incorporated Farm to Fork mandate implementation timelines and national subsidy program revision schedules.
Underlying assumptions cover regulatory compression trajectories for chemical pesticide thresholds, with deviation risk concentrated in ECHA registration timeline extensions and strain viability logistics breakthroughs. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Microbiome Sample Preparation Technology Market
Industrial Microbiology
Lactobacillus Strains Market
Industrial Microbiology
Automated Microbial Detection Systems Market
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
Global Microbial Testing Market
Industrial Microbiology
Real Time Continuous Microbiological Monitoring Systems Market
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
Microbiomes Market
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Automated Microbiology Market
Industrial Microbiology
Bacterial Amylase Market
Industrial Microbiology
Industrial Microbiology Market
Industrial Microbiology
Eubiotics Market
Industrial Microbiology
Anti-Microbial Anti-Fungal Test Market
Industrial Microbiology
Lipase Market
Industrial Microbiology
Microbial Protein Used in Feed Market