
 Benzoate-Free Enzymes Market | 2026-2036
Benzoate-Free Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Benzoate-Free Enzymes Market Analytics
Multi-source enzyme procurement is hardening as food manufacturers diversify away from single-supplier benzoate-dependent systems. Novonesis Group leverages its fermentation scale to anchor supply security for North American bakery clients. DSM-Firmenich competes through integrated biotechnology platforms that sustain consistent enzyme activity without benzoate stabilization. Kerry Group plc differentiates via application-specific formulation services that dominate clean-label meat and dairy segments.
Benzoate-free enzymes are protein catalysts produced via submerged fermentation or solid-state fermentation, typically stabilized through glycerol, sorbitol, or trehalose matrices rather than sodium benzoate or potassium benzoate salts, and function to accelerate biochemical reactions in food processing, pharmaceutical synthesis, and biomass conversion. Proteases lead product type demand due to their ubiquity in meat tenderization and dairy protein modification, while amylases capture expanding share in gluten-free bakery applications where benzoate exclusion intersects with allergen management protocols. Food and beverage applications occupy the dominant margin pool, though pharmaceutical-grade enzyme demand is accelerating as injectable and biologic formulations face heightened preservative scrutiny.
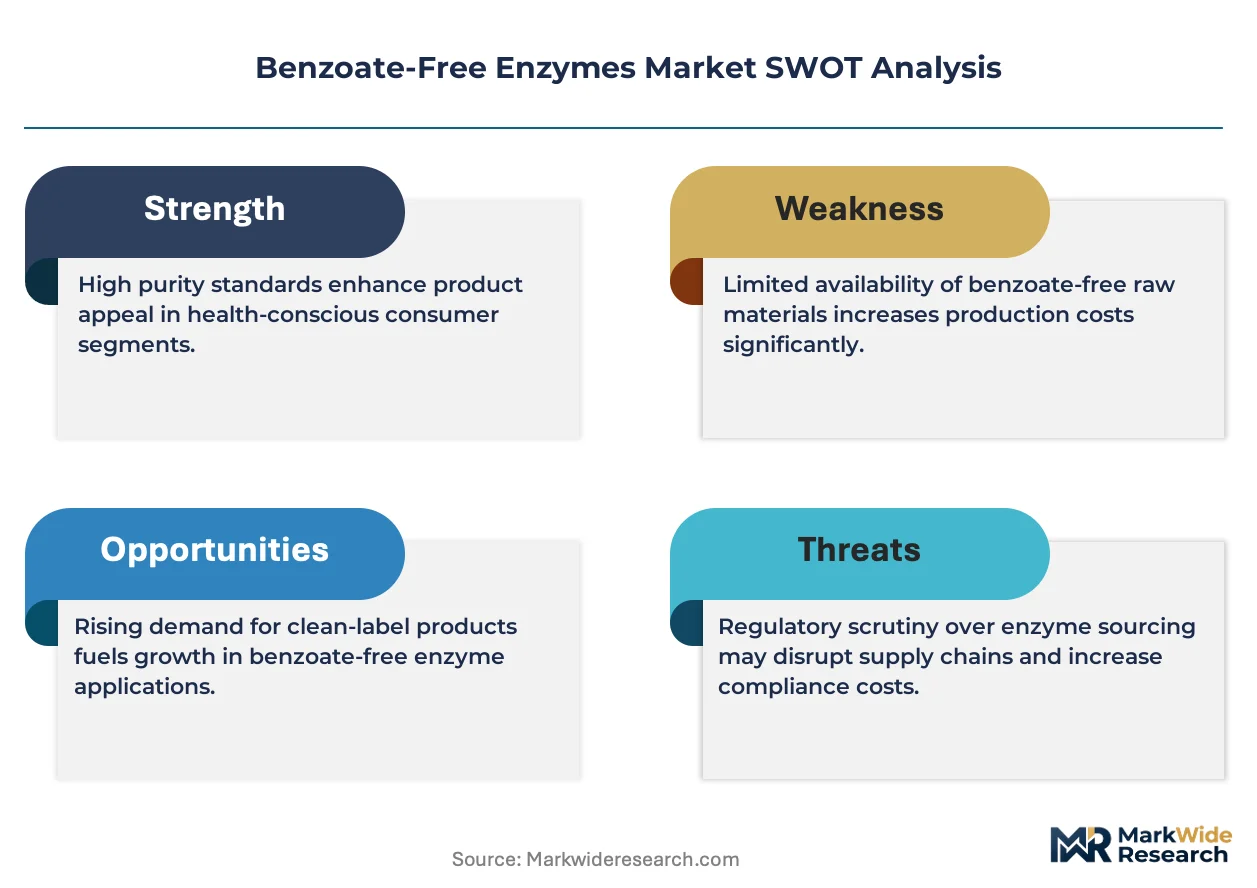
The U.S. FDA's GRAS notification program and the EPA's oversight of industrial biotechnology facilities shape domestic manufacturing compliance costs, while the EU's REACH regulation and EFSA evaluations of enzymatic food additives constrain formulation choices across European supply chains. Stakeholders must monitor evolving preservative-free certification standards from ISO and WHO guidelines, as these frameworks increasingly determine market access for enzyme suppliers serving multinational food and pharmaceutical manufacturers. Procurement teams should evaluate supplier qualification against emerging dual-carbon and circular-economy mandates that will tighten feedstock traceability requirements.
Market Dynamics
Clean-label mandates from retail chains and foodservice operators are compressing formulation timelines, forcing enzyme suppliers to validate benzoate-free stabilization protocols under accelerated shelf-life testing regimens that previously relied on synthetic preservative buffers.
Growth Catalysts
- EU REACH restrictions on benzoate derivatives:The ECHA's evolving substance evaluations are eliminating conventional preservative pathways, redirecting R&D expenditure toward trehalose and polyol stabilization matrices.
- Gluten-free bakery expansion:Allergen-management protocols in North American and European commercial baking are converging with benzoate exclusion requirements, doubling addressable demand for amylase systems.
- Pharmaceutical injectable formulations:Biologic drug manufacturers face heightened preservative scrutiny from FDA and EMA, opening specification windows for pharmaceutical-grade enzyme excipients.
Market Restraints
- Trehalose feedstock volatility:Corn-derived carbohydrate supply fluctuations in the U.S. Midwest directly compress margin stability for fermentation-based enzyme producers.
- Single-source fermentation capacity:Concentrated bioreactor infrastructure in Denmark and the Netherlands creates geographic vulnerability for North American procurement teams.
- Protease thermal stability limitations:Meat processing applications above 55°C require enzyme engineering that remains cost-prohibitive at commercial scale.
Strategic Opportunities
- India FSSAI clean-label enforcement:Emerging regulatory alignment with EU standards is opening formulation reformulation cycles in dairy processing hubs around Gujarat and Punjab.
- Solid-state fermentation technology:Convergence with precision agriculture waste streams enables localized enzyme production with reduced cold-chain dependency.
- Direct-to-manufacturer digital platforms:Biotech ingredient marketplaces are disintermediating traditional distributor networks for mid-scale food processors.
Industry Challenges
- Enzyme activity assay standardization:Absence of harmonized ISO methods for benzoate-free formulation validation extends customer qualification timelines by 4-8 months.
- Legacy ERP integration:Food manufacturers' existing inventory systems lack lot-traceability fields for multi-stabilizer enzyme certificates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzoate-Free Enzymes Market |
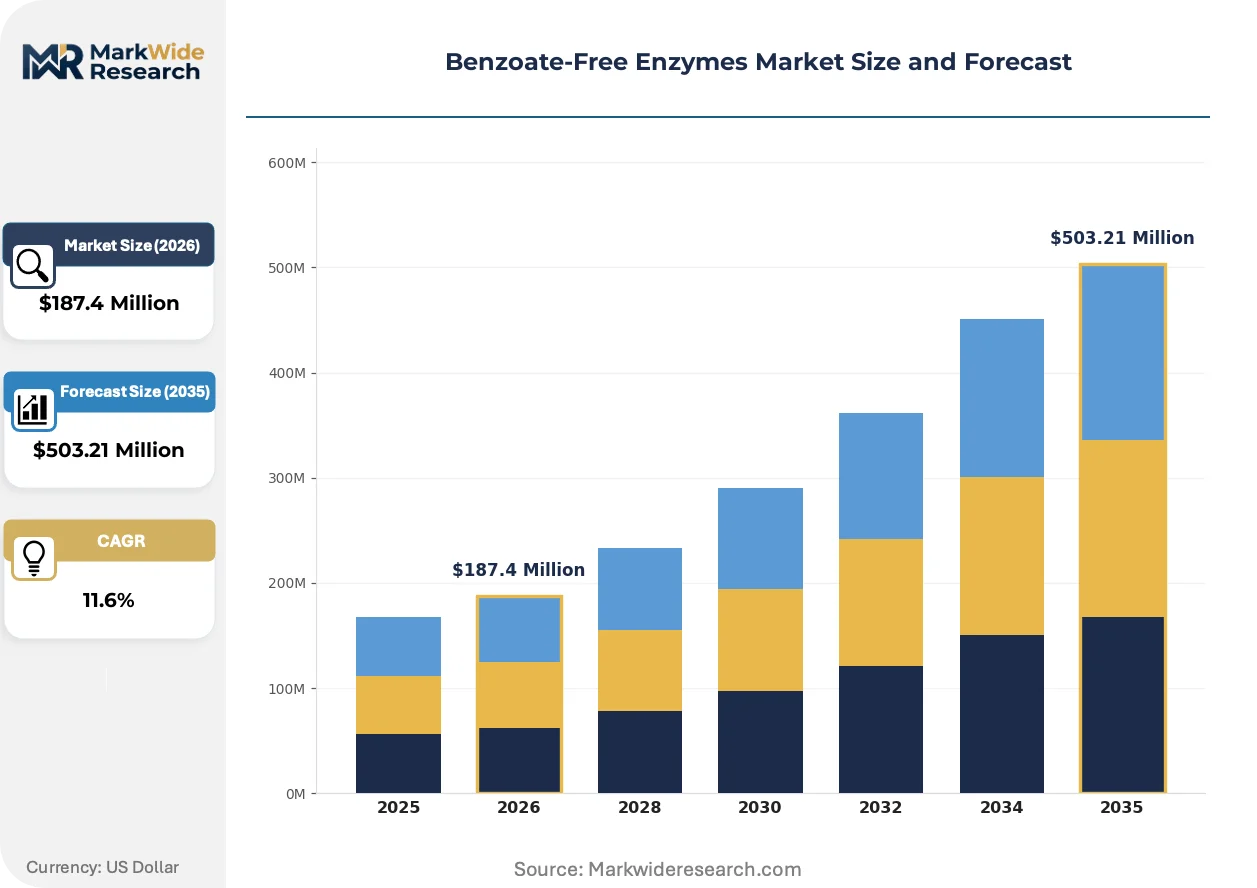
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Amylases, Lipases, Cellulases Application: Food & Beverage, Pharmaceuticals, Biofuels, Animal Feed End User: Food Manufacturers, Pharmaceutical Companies, Biofuel Producers, Livestock Feeders Distribution Channel: Online, Distributors, Direct Sales, Retail |
| Companies Covered | Novonesis Group, DSM-Firmenich, International Flavors & Fragrances Inc., AB Enzymes, Kerry Group plc, Amano Enzyme Inc., BASF SE, Advanced Enzyme Technologies Ltd., DuPont de Nemours Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzoate-Free Enzymes Market Evolving Landscape
Bioprocess engineering advances are collapsing the cost differential between synthetic-stabilized and clean-label enzyme systems, eroding the historical 15-30% premium that constrained mass-market penetration.
Cell-free enzyme synthesis is rewriting production economics by eliminating fermentation batch variability and enabling on-demand manufacturing for specialized protease blends. Contract research organizations in Germany and Massachusetts are deploying continuous-flow biocatalysis for meat and dairy enzyme applications. The technology is compressing minimum order quantities from metric-ton scales to kilogram lots, fragmenting procurement concentration among regional food processors.
EFSA's 2023 updated guidance on enzymatic food additives is tightening toxicological data requirements for novel stabilization matrices. The regulation is forcing suppliers to commission 90-day feeding studies for trehalose-glycerol combinations that previously relied on constituent safety approvals. Small and mid-cap enzyme formulators in Southern Europe face compliance cost barriers that favor integrated biotechnology platforms with in-house toxicology capabilities.
Retail chain private-label specifications are consolidating purchasing authority away from individual food manufacturers toward centralized technical teams at Kroger, Tesco, and Carrefour. These buyers now mandate benzoate-free certification as a condition of supplier qualification, compressing adoption timelines for contract manufacturers serving multiple retail channels. The shift is most visible in U.S. Pacific Northwest organic dairy clusters where co-packing facilities must maintain dual formulation capabilities.
Benzoate-Free Enzymes Market Segmentation
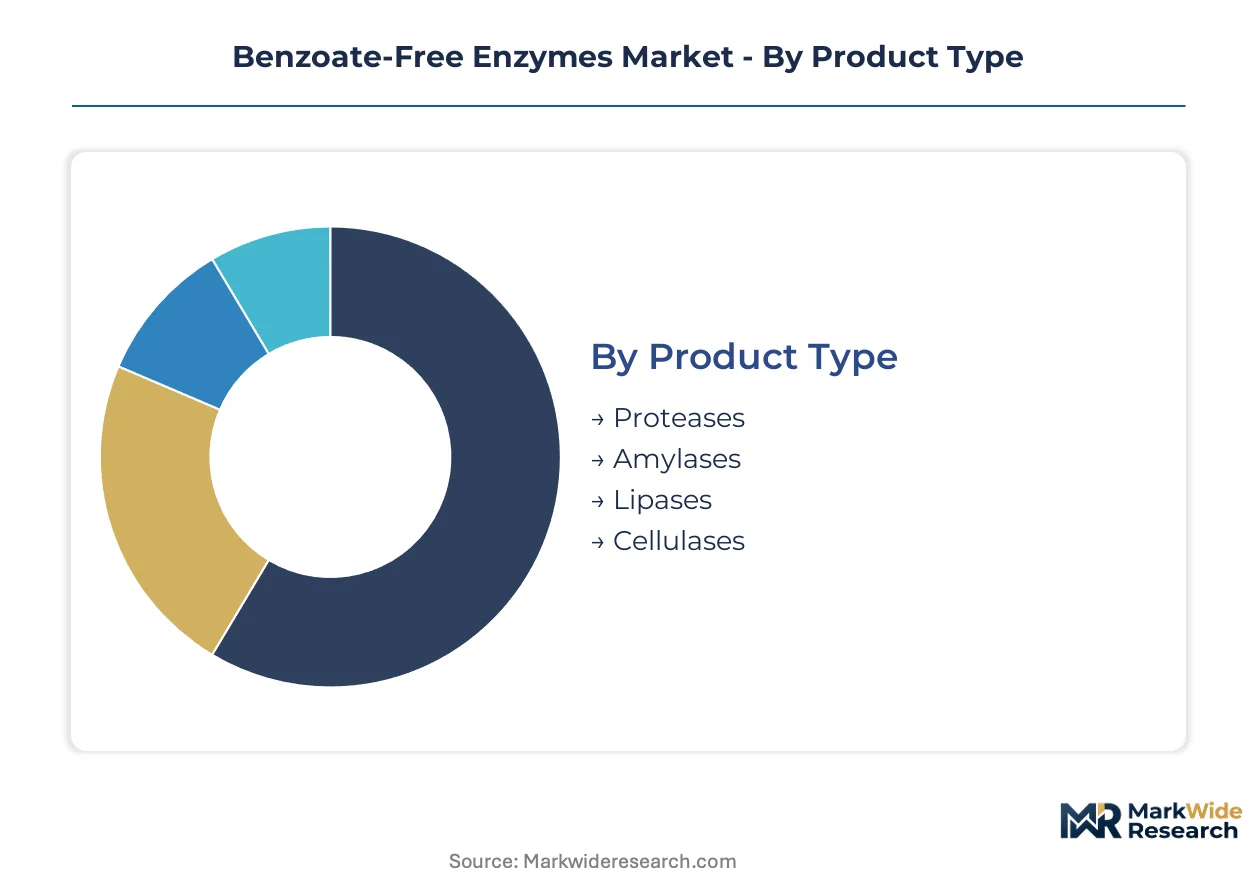
Benzoate-free enzyme procurement varies sharply by stabilization chemistry, end-use regulatory burden, and supply chain configuration. Specification requirements for pharmaceutical-grade trehalose matrices diverge fundamentally from food-grade polyol systems, creating distinct margin pools and qualification timelines across segment boundaries.
Product Type:
Stabilization chemistry and thermal tolerance separate commercial viability across enzyme classes, with fermentation yield and downstream processing costs determining competitive positioning.
- Proteases:These protein-cleaving enzymes utilize glycerol-trehalose stabilization matrices to maintain activity in meat tenderization and dairy protein modification. Demand concentrates in Germany's food processing belt, where clean-label meat processors face compressed formulation timelines from retail chain mandates.
- Amylases:Carbohydrate-hydrolyzing enzymes stabilized through sorbitol-glycerol blends enable gluten-free bakery applications where benzoate exclusion intersects with allergen management protocols. North American commercial baking clusters around the U.S. Pacific Northwest drive specification reformulation as private-label buyers consolidate purchasing authority.
- Lipases:Ester-bond cleaving enzymes deployed in dairy flavor development and oil modification.
- Cellulases:Cell wall-degrading enzymes finding niche adoption in biomass conversion and specialized textile processing.
Mature deployment sits with proteases in conventional meat and dairy processing. Newer deployment is concentrated in amylases serving reformulating gluten-free bakery operations.
Application:
Regulatory scrutiny intensity and preservative-free certification requirements fragment addressable demand across end-use sectors.
- Food & Beverage:Enzyme systems for baking, brewing, and dairy processing face the most compressed adoption timelines as retail chains mandate benzoate-free certification. The EU's REACH restrictions on benzoate derivatives redirect R&D expenditure toward trehalose stabilization in German and Dutch formulation centers.
- Pharmaceuticals:Injectable and biologic drug manufacturers face heightened preservative scrutiny from FDA and EMA, opening specification windows for pharmaceutical-grade enzyme excipients with documented toxicological profiles.
- Biofuels:Cellulase and amylase applications in ethanol production prioritize cost efficiency over clean-label positioning.
- Animal Feed:Phytase and protease supplementation for livestock nutrition operates under less stringent preservative restrictions.
Margin concentration favors pharmaceutical applications with extended qualification timelines. Volume expansion is climbing the fastest in food and beverage as retail specifications harden.
End User:
Procurement sophistication and technical qualification capabilities separate buyer tiers, with multinational manufacturers driving standard-setting for contract manufacturers.
- Food Manufacturers:Large-scale processors with in-house formulation teams dominate clean-label enzyme procurement, leveraging direct supplier relationships to bypass traditional distribution. U.S. Pacific Northwest organic dairy co-packers must maintain dual formulation capabilities to serve multiple retail channels.
- Pharmaceutical Companies:Biologic drug manufacturers require documented trehalose-glycerol toxicological data under EFSA's updated enzymatic food additive guidance, favoring integrated biotechnology platforms with in-house capabilities.
- Biofuel Producers:Industrial-scale ethanol operations prioritize fermentation yield and supply security over stabilization chemistry specifications.
- Livestock Feeders:Regional feed mills source through distributor networks with limited technical specification leverage.
Technical specification authority concentrates with pharmaceutical companies. Procurement volume is expanding most quickly among mid-scale food manufacturers responding to retail chain mandates.
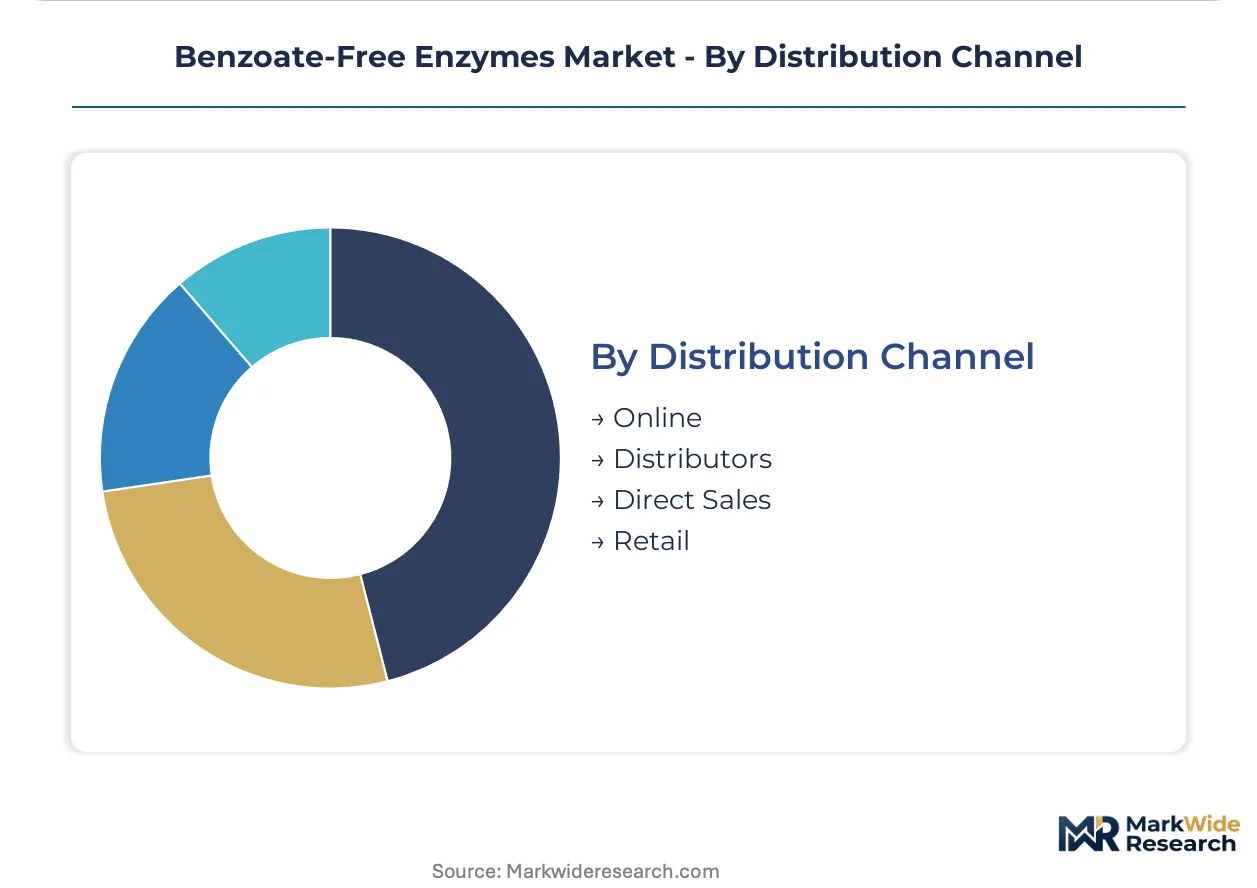
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic proximity to fermentation capacity.
- Direct Sales:Large-volume food and pharmaceutical manufacturers contract directly with Novonesis Group and DSM-Firmenich for trehalose-stabilized protease and amylase systems, securing supply allocation from concentrated bioreactor infrastructure in Denmark and the Netherlands.
- Distributors:Regional chemical and ingredient distributors serve mid-scale processors lacking technical qualification teams, though legacy ERP integration challenges extend customer onboarding timelines.
- Online:Biotech ingredient marketplaces are disintermediating traditional networks for kilogram-scale orders, compressing minimum order quantities through cell-free enzyme synthesis offerings.
- Retail:Limited to small-scale research and development procurement.
Established volume flows through direct sales relationships. Channel experimentation is gaining share fastest in online platforms serving fragmented regional processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food manufacturers in Germany and the United States drive the bulk of specification reformulation for benzoate-free enzyme systems, with procurement teams in both markets accelerating qualification timelines under tightening retail mandates.
United States
Clean-label dairy processors in the Pacific Northwest cluster around Seattle and Portland are retrofitting formulation lines to eliminate sodium benzoate from enzyme stabilization. The FDA's evolving GRAS notification program is compressing supplier validation cycles for trehalose-based alternatives. Oregon-based organic co-packers now maintain dual inventory systems to serve both conventional and preservative-free retail channels.
Germany
Meat processors in Bavaria and North Rhine-Westphalia are converting tenderization lines to glycerol-stabilized protease systems ahead of ECHA's substance evaluation deadlines. REACH restrictions on benzoate derivatives are redirecting R&D expenditure toward polyol matrices at formulation centers in Frankfurt and Munich. The country's centralized bioreactor infrastructure in Hamburg anchors supply security for pan-European bakery clients.
India
Dairy cooperatives in Gujarat and Punjab are initiating enzyme procurement cycles as FSSAI clean-label enforcement converges with EU export standards. The regulator's tightening preservative specifications are forcing reformulation at processing hubs around Anand and Ludhiana. Regional enzyme distributors are building technical service capabilities to support mid-scale paneer and ghee manufacturers.
Netherlands
Integrated biotechnology platforms concentrated in the Randstad region supply trehalose-stabilized amylase systems to gluten-free bakery operations across Northern Europe. EFSA's updated enzymatic food additive guidance is extending toxicological data requirements for novel stabilization combinations. Rotterdam-area fermentation facilities are expanding capacity to offset geographic concentration risk for North American procurement teams.
Japan
Specialty enzyme formulators in the Kansai region around Osaka are developing pharmaceutical-grade excipient systems for injectable biologics facing heightened preservative scrutiny. METI's industrial biotechnology incentives are accelerating cell-free synthesis pilot programs at research consortia in Kyoto. Domestic food manufacturers are adopting benzoate-free certification standards aligned with EU REACH frameworks to maintain export competitiveness.
Benzoate-Free Enzymes Market Competitive Landscape
Capacity expansion dominates the current landscape as fermentation-based producers scale trehalose-stabilized output to capture reformulation cycles in North American and European food processing. The vendor base separates into three distinct tiers: integrated biotechnology platforms with in-house toxicology capabilities, mid-scale specialists in solid-state fermentation technology, and regional distributors serving fragmented processors lacking technical qualification teams. M&A activity and strategic partnerships between enzyme suppliers and precision agriculture waste stream operators represent the primary competitive vectors reshaping supply security.
Among integrated biotechnology platforms, Novonesis Group and DSM-Firmenich occupy positions exemplifying the scale-driven archetype, with fermentation infrastructure concentrated in Denmark and the Netherlands anchoring supply allocation for large-volume food and pharmaceutical manufacturers. Kerry Group plc represents the application-specific formulation specialist, occupying a position within the service-differentiated tier that dominates clean-label meat and dairy segments through technical partnership models rather than commodity supply.
| Leading Market Players |
|---|
| Novonesis Group |
| DSM-Firmenich |
| International Flavors & Fragrances Inc. |
| AB Enzymes |
| Kerry Group plc |
| Amano Enzyme Inc. |
| BASF SE |
| Advanced Enzyme Technologies Ltd. |
| DuPont de Nemours Inc. |
| Others |
Value Network & Pricing Analysis
Corn futures volatility in the U.S. Midwest cascades through trehalose feedstock costs into three distinct pricing tiers for benzoate-free enzymes, compressing margins for fermentation-dependent suppliers while rewarding integrated biotechnology platforms with captive carbohydrate sourcing.
Pricing Analysis
Volume concentration sits with pharmaceutical-grade trehalose-stabilized proteases commanding premium positioning, while commodity amylases for gluten-free bakery face cost compression from corn-derived polyol feedstock fluctuations. Price differentiation separates ISO-certified pharmaceutical excipients from food-grade polyol systems, with EFSA toxicological documentation requirements widening the certification premium. Pricing pressure stems from trehalose supply volatility as ethanol demand competes for corn starch feedstocks. Mid-scale food manufacturers exhibit highest price sensitivity, lacking volume leverage to secure long-term offtake agreements with Danish and Dutch fermentation hubs.
Supply Chain Analysis
Cold-chain freight costs for temperature-sensitive enzyme shipments from Denmark and the Netherlands to North American dairy processors add 12-18% to delivered costs, incentivizing regional solid-state fermentation investments. Supply concentrates in Denmark, the Netherlands, and Germany, with Hamburg and Rotterdam anchoring pan-European distribution. Raw material dependencies center on corn-derived trehalose, pharmaceutical-grade glycerol, and precision fermentation feedstocks. Single-source bioreactor vulnerability in the Randstad region creates geographic concentration risk for procurement teams. Distribution runs through direct sales relationships for large-volume pharmaceutical and food manufacturers, with regional distributors serving fragmented mid-scale processors lacking technical qualification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell-free enzyme synthesis is displacing submerged fermentation as the dominant production paradigm, collapsing minimum order quantities and fragmenting procurement concentration among regional food processors previously locked into metric-ton supply agreements.
For Market Incumbents: Lock in trehalose feedstock security through backward integration into corn processing or long-term supply agreements with U.S. Midwest agricultural cooperatives, while accelerating toxicology documentation capabilities to defend pharmaceutical-grade certification premiums against emerging cell-free synthesis competitors. Capacity expansion in Gujarat and Punjab addresses FSSAI enforcement cycles threatening EU export compliance for Indian dairy cooperatives. For New Entrants and Emerging Players: Enter via solid-state fermentation technology converging with precision agriculture waste streams, targeting kilogram-scale orders through biotech ingredient marketplaces disintermediating traditional distributor networks. India's dairy processing hubs around Anand and Ludhiana present the most penetrable geography, with regional distributors lacking technical service capabilities to support mid-scale paneer and ghee manufacturers facing reformulation mandates. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale solid-state fermentation specialists with established regional feedstock partnerships in India and Southeast Asia, where FSSAI alignment with EU standards is compressing formulation timelines for incumbent distributors. Cell-free synthesis platform maturation in German and Massachusetts research consortia signals inflection toward on-demand manufacturing economics. Long-term viability across the analysis window favors integrated biotechnology platforms with in-house toxicology capabilities over commodity fermentation operators exposed to trehalose feedstock volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Trehalose Feedstock | Captive corn starch processing in the U.S. Midwest insulates margin stability against ethanol demand competition. |
| Cell-Free Synthesis Platform Deployment | Continuous-flow biocatalysis in Massachusetts and Germany compresses minimum order quantities to kilogram scales. |
| Pharmaceutical-Grade Toxicology Investment | In-house 90-day feeding study capabilities satisfy EFSA's tightened enzymatic food additive guidance requirements. |
| Solid-State Fermentation Expansion | Precision agriculture waste stream integration enables localized production with reduced cold-chain dependency. |
| Direct-to-Manufacturer Digital Platform Launch | Biotech ingredient marketplaces disintermediate traditional distributors for mid-scale food processor procurement. |
Research Methodology
Document review covered FDA GRAS notification filings, EFSA enzymatic food additive guidance updates, and REACH substance evaluation records, complemented by interviews with fermentation technology directors, pharmaceutical formulation scientists, food manufacturer procurement leads, and regional enzyme distributors across Germany, the United States, and India. Secondary validation drew from customs trade data, SEC filings of integrated biotechnology platforms, and FSSAI regulatory circulars. Bottom-up enzyme volume modeling triangulated against top-down clean-label ingredient spending patterns.
Historical capacity utilization rates cross-referenced against expert panel inputs on reformulation timeline compression established the analytical framework across the projection horizon. Segmentation dimensions modeled include stabilization chemistry, application regulatory burden, end-user procurement sophistication, and geographic fermentation capacity concentration. CAGRs derived from enzyme adoption curve analysis in gluten-free bakery and pharmaceutical injectable segments, with feedstock cost indices and retail chain specification mandates as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained corn price volatility or accelerated ECHA substance evaluation schedules. Forecasts reflect assumptions on regulatory alignment timelines and cell-free synthesis cost reduction curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Microbial Cell Banking Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
North America Microbial Protein Market
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Ripening Cultures Market
Industrial Microbiology
Global Microbial Protein Market
Industrial Microbiology
Freeze-Dried Microbial Food Culture Market
Industrial Microbiology
B-Glucuronidase Enzymes Market
Industrial Microbiology
Microbial Therapeutic Products Market
Industrial Microbiology
Lactobacillus Strains Market
Industrial Microbiology
Global Microbial Identification Market
Industrial Microbiology
Automated Microbiology Market
Industrial Microbiology
Global Microbial Based Biological Seed Treatment Market
Industrial Microbiology
Microbial Biosurfactants Market