
 Industrial Microbiology Testing Services Market | 2026-2036
Industrial Microbiology Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Microbiology Testing Services Market Analytics
The EU's updated Annex 1 GMP guidelines for sterile manufacturing is consolidating the competitive landscape by raising the capital and technical thresholds for microbiology testing operations. Charles River Laboratories leverages its extensive laboratory network across multiple European jurisdictions to anchor its position in sterility assurance testing. Eurofins Scientific competes through specialized consulting and certification services that help pharmaceutical clients navigate evolving regulatory interpretations. Merck KGaA differentiates by combining rapid microbial detection technologies with traditional culturing methods, extending its service portfolio beyond conventional offerings.
Industrial microbiology testing services encompass the analytical evaluation of microbial contamination, sterility, and bioburden in manufacturing environments, raw materials, and finished products using techniques such as membrane filtration, direct inoculation, and ATP bioluminescence assays with detection thresholds as low as one colony-forming unit per sample. These services ensure product safety, batch release compliance, and environmental monitoring across regulated manufacturing sectors. PCR-based molecular identification and rapid testing technologies are capturing expanding share as pharmaceutical clients prioritize shorter turnaround times for contamination investigations, while traditional culturing methods retain dominance in official compendial testing where regulatory acceptance remains most established. Quality control applications generate the largest revenue pool due to recurring batch-release obligations, though compliance testing services command premium pricing as regulatory inspection intensity escalates.
FDA enforcement of current Good Manufacturing Practice requirements shapes demand for comprehensive environmental monitoring programs in United States pharmaceutical facilities. EMA's harmonized GMP standards across EU member states create cross-border service opportunities for testing providers holding multi-site accreditations. ISO 17025 laboratory accreditation functions as a de facto market-access requirement for contract microbiology services serving multinational pharmaceutical clients. Stakeholders must monitor how regulatory convergence between FDA and EMA inspection protocols reshapes the geographic distribution of testing capacity investments.
Market Dynamics
Pharmaceutical outsourcing of sterility validation is compressing turnaround times and elevating technical thresholds for contract microbiology laboratories. The EU's updated Annex 1 GMP guidelines for sterile manufacturing are forcing facility upgrades and specialized capability investments across the testing services value chain.
Growth Catalysts
- EMA harmonized GMP standards:Cross-border accreditation requirements are consolidating demand toward multi-site laboratory networks capable of serving multinational pharmaceutical clients under unified compliance frameworks.
- PCR-based molecular identification:Pharmaceutical manufacturers are adopting rapid microbial detection to accelerate contamination investigations and reduce batch release timelines for parenteral drug production.
- Germany's parenteral drug monitoring:The national pharmaceutical regulator enforces stringent microbiological surveillance requirements that drive specialized third-party validation demand from domestic and neighboring facilities.
Market Restraints
- ISO 17025 accreditation costs:Multi-site laboratory networks face substantial capital requirements for equipment calibration, personnel certification, and audit maintenance across jurisdictions.
- Traditional culturing method dependency:Regulatory acceptance of rapid testing technologies remains limited in official compendial testing, constraining full portfolio conversion.
- Specialized technician scarcity:Skilled microbiologists capable of operating both ATP bioluminescence assays and membrane filtration systems command premium compensation in concentrated pharmaceutical clusters.
Strategic Opportunities
- FDA-EMA inspection protocol convergence:Harmonized enforcement approaches create openings for testing providers to standardize quality systems across Atlantic pharmaceutical supply chains.
- Environmental monitoring program expansion:United States pharmaceutical facilities face intensified current Good Manufacturing Practice enforcement, driving recurring service contracts for comprehensive contamination surveillance.
- Rapid detection-traditional culturing integration:Service portfolios combining ATP bioluminescence with membrane filtration methods capture clients seeking both speed and regulatory defensibility.
Industry Challenges
- Legacy LIMS integration complexity:Rapid microbial detection platforms require substantial data architecture reconfiguration to interface with established laboratory information management systems.
- Annex 1 facility revalidation timelines:Pharmaceutical manufacturers face compressed windows to achieve compliance with revised EU sterile manufacturing guidelines, straining validation resource availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Microbiology Testing Services Market |
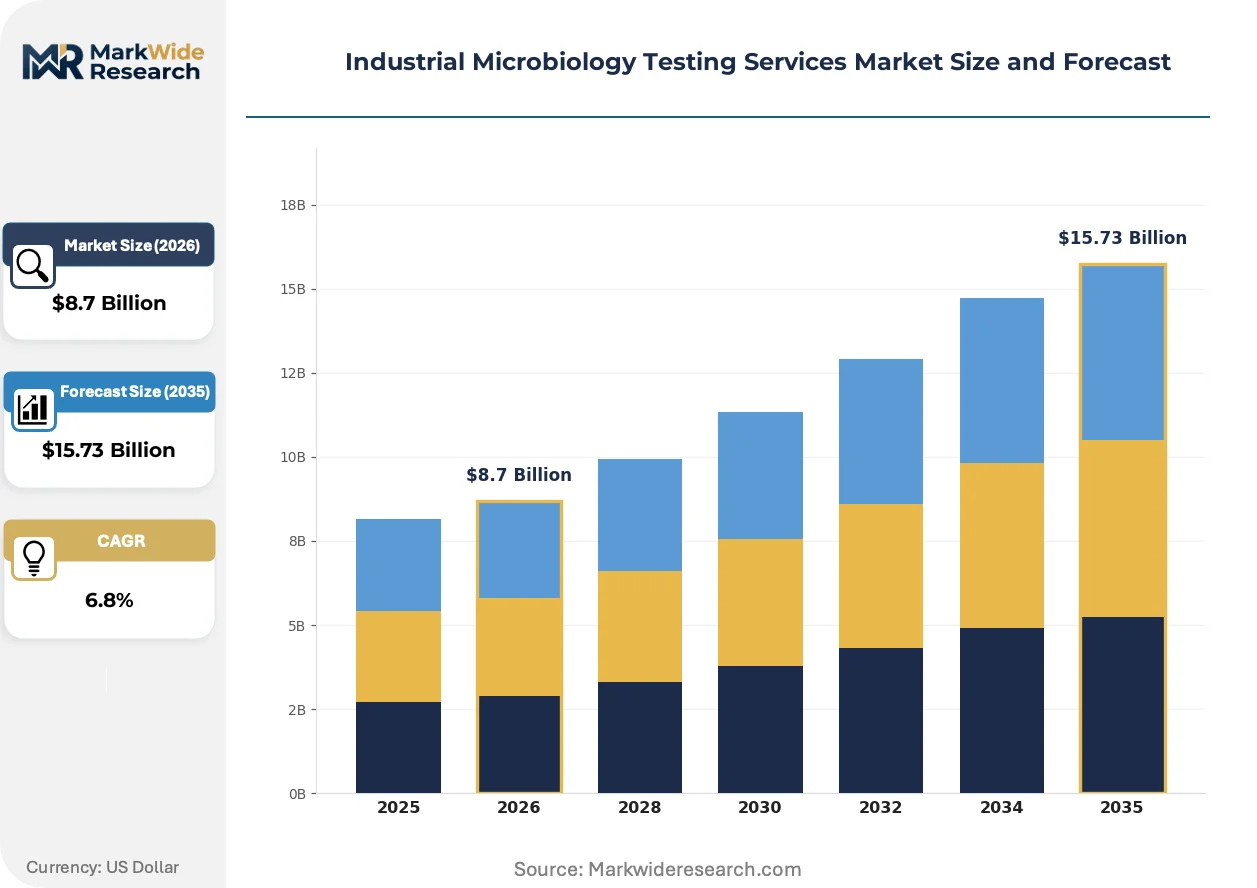
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Testing, Consulting, Training, Certification End User: Pharmaceuticals, Food & Beverage, Cosmetics, Biotechnology Application: Quality Control, Research & Development, Compliance Testing, Process Validation Technology: PCR, Culturing, Sequencing, Rapid Testing |
| Companies Covered | Charles River Laboratories, Eurofins Scientific, Merck KGaA, STERIS, Intertek Group Plc, TÜV SÜD, Spectro Analytical Labs Pvt. Ltd., Pace Analytical Services, Biotech Testing Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Microbiology Testing Services Market Evolving Landscape
Automation and molecular diagnostics are restructuring competitive advantage in microbiology testing, compressing analytical timelines while expanding detection sensitivity. Service differentiation now hinges on regulatory navigation capabilities alongside technical performance.
ATP bioluminescence assays are electrifying environmental monitoring protocols by delivering same-day contamination alerts versus traditional culturing's multi-day incubation periods. Pharmaceutical quality control departments are prioritizing these rapid methods for in-process testing while retaining conventional approaches for final batch release documentation. The technology is electrifying competitive positioning among contract laboratories capable of offering dual-method validation packages.
REACH chemical safety assessments are extending microbiological evaluation requirements to raw material suppliers serving pharmaceutical and cosmetic manufacturers. The regulation mandates contamination screening across broader supply chain tiers, pushing testing demand upstream from finished product manufacturers to ingredient processors. German chemical and pharmaceutical clusters are experiencing the most acute capacity constraints as suppliers rush to secure accredited laboratory partnerships.
Pharmaceutical procurement departments are unbundling sterility testing from full-service quality contracts to engage specialized microbiology providers on standalone validation programs. This disintermediation of integrated quality services is fragmenting incumbent relationships and opening direct contracting channels for niche testing laboratories. The pattern is most pronounced among mid-cap parenteral drug manufacturers in the United States seeking ISO 17025-accredited partners independent of their primary contract manufacturing organizations.
Industrial Microbiology Testing Services Market Segmentation
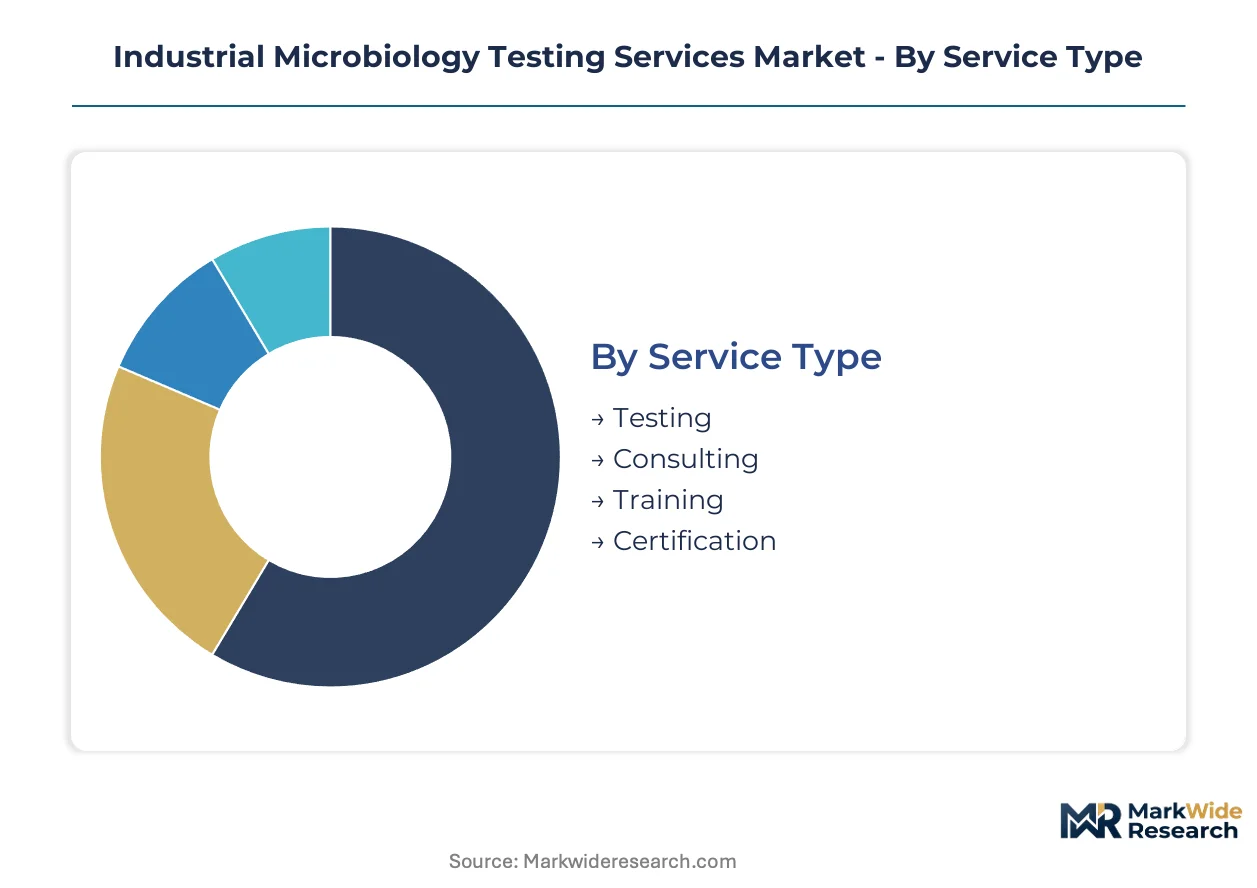
Industrial microbiology testing services fragment across technical capabilities, regulatory applications, and end-use sectors. Each segmentation axis reveals distinct pricing power, customer concentration, and capability requirements that shape competitive positioning.
Service Type:
Volume concentration sits with routine analytical work. Premium capture belongs to advisory and assurance services.
- Testing:Analytical evaluation of microbial contamination, sterility, and bioburden using membrane filtration, direct inoculation, and ATP bioluminescence assays. German pharmaceutical facilities generate concentrated demand due to national parenteral drug monitoring requirements that mandate third-party validation.
- Consulting:Regulatory navigation support for Annex 1 GMP compliance, facility design qualification, and contamination control strategy development. EMA harmonized standards across EU member states drive cross-border advisory contracts from multinational pharmaceutical clients.
- Training:Personnel certification programs for aseptic technique, cleanroom behavior, and rapid detection platform operation.
- Certification:ISO 17025 accreditation support and GMP compliance attestation for laboratory networks.
Mature deployment sits with Testing. Newer deployment is concentrated in Consulting.
End User:
Customer concentration clusters around regulated manufacturing with batch-release obligations. Margin expansion tracks toward emerging bioprocessing applications.
- Pharmaceuticals:Sterility assurance, endotoxin detection, and environmental monitoring for parenteral drug production. FDA enforcement of current Good Manufacturing Practice requirements in United States facilities sustains recurring contract demand for comprehensive contamination surveillance programs.
- Biotechnology:Cell culture contamination screening, mycoplasma detection, and rapid microbial methods for bioreactor monitoring. PCR-based molecular identification is climbing the fastest as cell therapy manufacturers prioritize shortened batch release timelines.
- Food & Beverage:Pathogen screening, spoilage organism detection, and shelf-life stability testing.
- Cosmetics:Preservative efficacy testing and raw material bioburden evaluation under REACH chemical safety assessments.
Established revenue concentration sits with Pharmaceuticals. Emerging capacity investment targets Biotechnology.
Application:
Recurring revenue pools align with compliance-mandated activities. Discretionary spending concentrates in innovation support functions.
- Quality Control:Routine batch-release testing, raw material qualification, and in-process monitoring using compendial methods. Quality control applications generate the largest revenue pool due to recurring obligations across pharmaceutical manufacturing sites.
- Compliance Testing:Regulatory inspection preparation, deficiency response validation, and GMP gap remediation. Compliance testing services command premium pricing as EMA and FDA inspection intensity escalates across sterile manufacturing facilities.
- Research & Development:Method development, validation protocol design, and technology transfer support for new product introductions.
- Process Validation:Cleaning validation, sterilization cycle qualification, and environmental monitoring program establishment.
Contract maturity sits with Quality Control. Accelerating procurement activity centers on Compliance Testing.
Technology:
Regulatory acceptance determines method selection. Speed-to-result drives technology substitution patterns.
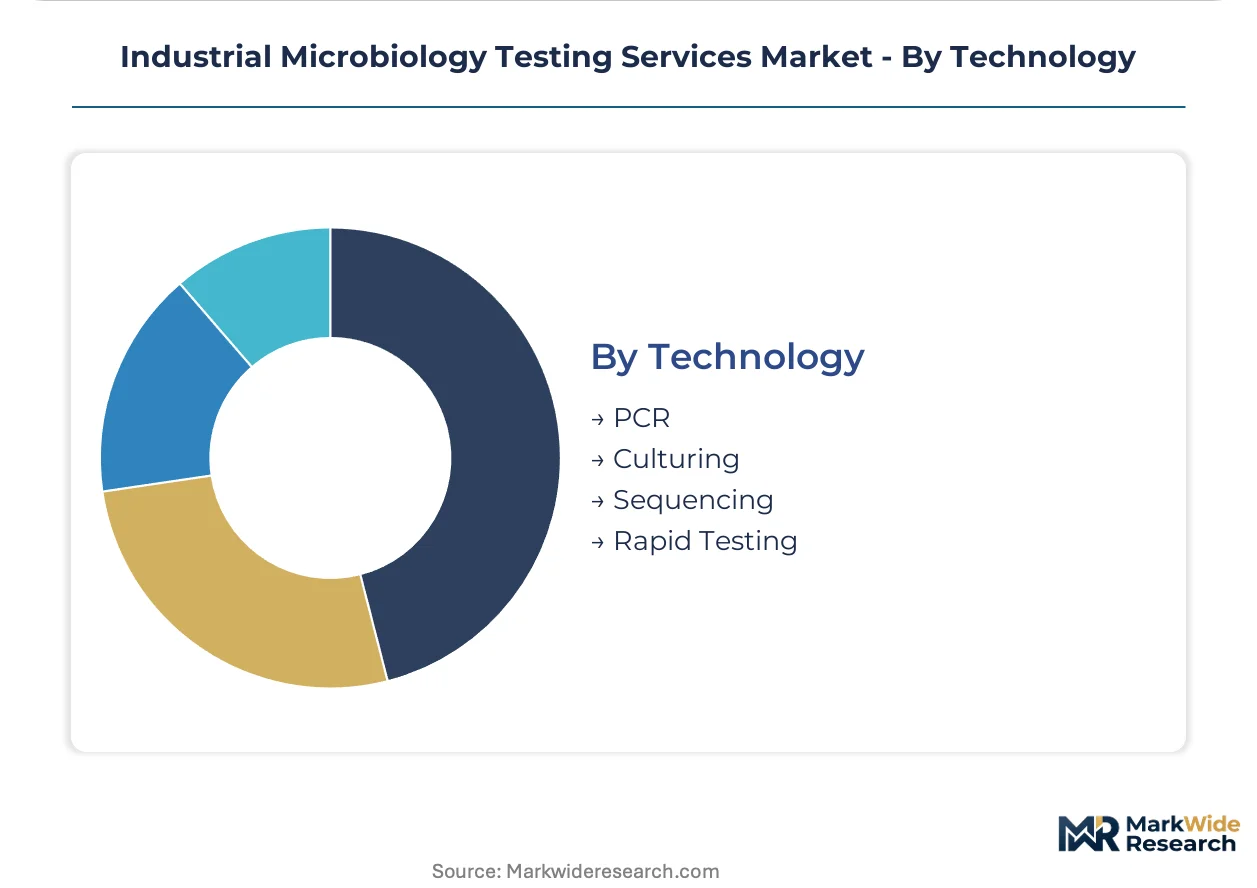
- Culturing:Traditional growth-based detection using membrane filtration and direct inoculation with incubation periods spanning multiple days. Regulatory acceptance remains most established in official compendial testing where pharmacopeial methods dominate batch documentation requirements.
- Rapid Testing:ATP bioluminescence assays delivering same-day contamination alerts for environmental monitoring and in-process control. Pharmaceutical quality control departments prioritize these methods for preliminary screening while retaining conventional approaches for final release documentation.
- PCR:Polymerase chain reaction-based molecular identification for species-level microbial characterization and accelerated contamination investigations.
- Sequencing:Next-generation and Sanger sequencing for strain typing, source tracking, and microbial identification in complex contamination events.
Established regulatory defensibility sits with Culturing. Fastest capability expansion targets Rapid Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical clusters concentrate testing demand through specialized economic zones supporting parenteral drug manufacturing. The country's stringent regulatory environment creates sustained validation requirements across sterile production facilities.
United States
FDA enforcement of current Good Manufacturing Practice requirements drives recurring environmental monitoring contracts for pharmaceutical facilities. The agency's inspection protocols intensify compliance burdens for sterile manufacturers. Boston-Cambridge biotech corridors generate concentrated demand for rapid microbial detection services as cell therapy developers accelerate batch release timelines.
Germany
The national pharmaceutical regulator enforces Europe's most rigorous microbiological surveillance standards for parenteral drug production. EMA harmonized GMP standards create cross-border service opportunities for multi-site laboratory networks. Frankfurt-Rhine-Main pharmaceutical clusters strain local testing capacity as manufacturers rush to meet Annex 1 compliance deadlines.
Switzerland
Swissmedic's stringent sterile manufacturing oversight elevates third-party validation requirements for domestic biologics producers. The country's dual-track regulatory alignment with both EU and international standards attracts multinational quality contracts. Basel's concentrated pharma headquarters generate premium-priced advisory demand for contamination control strategy development.
United Kingdom
Post-Brexit regulatory divergence from EMA standards creates specialized consulting demand for dual-compliance navigation. The Medicines and Healthcare products Regulatory Agency maintains rigorous GMP enforcement across sterile manufacturing sites. Southeast England pharmaceutical corridors sustain environmental monitoring program expansion as facilities adapt to independent inspection protocols.
India
CDSCO's escalating GMP inspection intensity for export-oriented pharmaceutical manufacturers drives ISO 17025 accreditation demand among domestic testing laboratories. The country's contract research organization clusters expand microbiology capabilities to capture outsourced validation work. Hyderabad-Visakhapatnam pharmaceutical corridors concentrate rapid method adoption as generic injectable producers target shortened batch release cycles.
Industrial Microbiology Testing Services Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the testing services value chain. The market structure reflects moderate consolidation around multi-site laboratory networks holding cross-border accreditations. Three archetypes dominate: integrated life science conglomerates with captive testing divisions, independent contract laboratories with geographic scale, and niche specialists in rapid detection technologies. Competitive dynamics center on M&A activity consolidating regional laboratory networks and strategic partnerships embedding testing providers within pharmaceutical supply chains.
Within the integrated conglomerate tier, Charles River Laboratories and Merck KGaA exemplify scale-driven positioning through extensive European laboratory footprints. Eurofins Scientific represents the independent contract laboratory archetype, occupying a position defined by specialized consulting capabilities. These three entities anchor competitive intensity around regulatory navigation expertise and multi-jurisdiction accreditation breadth.
| Leading Market Players |
|---|
| Charles River Laboratories |
| Eurofins Scientific |
| Merck KGaA |
| STERIS |
| Intertek Group Plc |
| TÜV SÜD |
| Spectro Analytical Labs Pvt. Ltd. |
| Pace Analytical Services |
| Biotech Testing Services |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up contract laboratory networks anchor supply consolidation across European pharmaceutical corridors, tightening pricing discipline through ISO 17025 accreditation scarcity and cross-border capability bundling. This ownership pattern concentrates bargaining power with multi-site operators while fragmenting price-sensitive spot buyers into secondary vendor tiers.
Pricing Analysis
Lead-time-driven pricing stratification separates expedited sterility validation at premium rates from standard-batch queue positioning for routine environmental monitoring contracts. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments, with FDA-inspected facilities commanding tier-one positioning. Price erosion runs through economy-tier routine testing as automated platforms compress analytical labor content. Mid-cap parenteral drug manufacturers exhibit acute price sensitivity, whereas cell therapy developers prioritize turnaround velocity over unit cost.
Supply Chain Analysis
Domestic-content mandates under EU procurement directives reshape sourcing toward accredited laboratory networks with established European footprints, displacing offshore alternatives for GMP-critical validation services. Equipment and consumable supply concentrates in Germany, Switzerland, and the United States, with membrane filtration apparatus and rapid detection platforms drawing from specialized precision manufacturing clusters. Single-source vulnerability sits with ATP bioluminescence reagent suppliers concentrated in German chemical corridors. Distribution runs through direct contractual relationships between pharmaceutical quality departments and accredited testing providers, bypassing traditional distributor intermediaries for compliance-critical services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ATP bioluminescence assays are displacing legacy culturing methods across environmental monitoring applications, compressing analytical timelines while demanding new capital deployment and technician retraining across contract laboratory networks.
For Market Incumbents: Hedge rapid method obsolescence risk by maintaining dual-method validation capabilities that preserve regulatory defensibility while capturing speed-sensitive segments. Prioritize backward integration into rapid detection reagent supply to secure margin control over consumable-intensive service lines. Reinforce multi-site accreditation breadth under EMA harmonized standards to defend against regional specialists consolidating adjacent jurisdictions. For New Entrants and Emerging Players: Mid-cap biotechs with accelerated cell therapy pipelines represent the most penetrable buyer archetype, as these manufacturers prioritize turnaround velocity over established vendor relationships and tolerate premium pricing for expedited contamination investigations. Target standalone sterility validation contracts unbundled from integrated quality services, particularly among United States parenteral drug manufacturers seeking ISO 17025-accredited partners independent of primary contract manufacturing organizations. Deploy PCR-based molecular identification capabilities as the lead wedge for initial engagement, converting speed advantages into broader environmental monitoring program expansion. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional laboratory networks with pending Annex 1 revalidation backlogs in Germany and Switzerland, where compliance deadline pressure creates acquisition opportunities below replacement cost. Long-term viability hinges on automation-enabled scale economics and regulatory navigation expertise rather than commodity analytical capacity. Monitor FDA-EMA inspection protocol convergence announcements as the critical inflection signal for cross-border consolidation feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Rapid Detection Platform Deployment | ATP bioluminescence integration compresses environmental monitoring timelines for pharmaceutical batch release. |
| Multi-Site Accreditation Expansion | EMA harmonized GMP standards enable cross-border service delivery from unified laboratory networks. |
| Regulatory Consulting Capability Buildout | Annex 1 compliance advisory captures premium pricing from manufacturers facing facility revalidation deadlines. |
| PCR-Based Molecular Identification Investment | Species-level microbial characterization accelerates contamination investigations for cell therapy producers. |
| Backward Integration into Reagent Supply | In-house production of ATP bioluminescence consumables secures margin control and supply continuity. |
Research Methodology
Independent corroboration across regulatory affairs directors at contract testing organizations, quality control executives at parenteral drug manufacturers, and accreditation auditors from German and Swiss competent authorities underwrites the qualitative findings. Primary interviews with laboratory operations managers, pharmaceutical procurement leads, and rapid detection platform engineers combined with secondary validation from FDA warning letter databases, EMA inspection deficiency reports, ISO 17025 accreditation registries, and pharmacopeial method revision notices. Bottom-up service line analysis and top-down market sizing triangulate volume estimates across the projection horizon.
Rate-of-change decomposition separates volume growth from pricing dynamics across service type, end user, application, and technology segmentation dimensions, with additional modeling of regulatory enforcement intensity as an industry-specific demand driver. CAGRs derive from regression analysis of historical accreditation expansion patterns and pharmaceutical outsourcing ratios, cross-referenced with Annex 1 implementation timelines and FDA inspection frequency trends. Forecast inputs incorporate PCR platform adoption curves, automation capital deployment cycles, and technician labor market tightness in concentrated pharmaceutical clusters.
Revisions become necessary when FDA-EMA inspection protocol divergence or convergence accelerates, when rapid detection technologies achieve pharmacopeial recognition, or when major accreditation bodies revise ISO 17025 competency requirements. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and technology substitution elasticities. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Asia-Pacific Biotechnology Market
Biotechnology Services
Cell Lysis and Dissociation Market
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
Global Eukaryotic Expression Systems Market
Biotechnology Services
Recombinant Factor C Assay Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market
Biotechnology Services
DNA and RNA Sample Preparation Market
Biotechnology Services
Cell Line Development Services Market
Biotechnology Services
Global Downstream Processing Market
Biotechnology Services
Plasmid DNA Preparation Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
Biologics CDMO Market
Biotechnology Services
TSG6 Antibody Market
Biotechnology Services
Cdna Synthesis Market
Biotechnology Services
Electrophoresis Market