
 Lactobacillus Strains Market | 2026-2036
Lactobacillus Strains Market Size, Share, and Industry Trends Forecast 2026-2036
Lactobacillus Strains Market Analysis
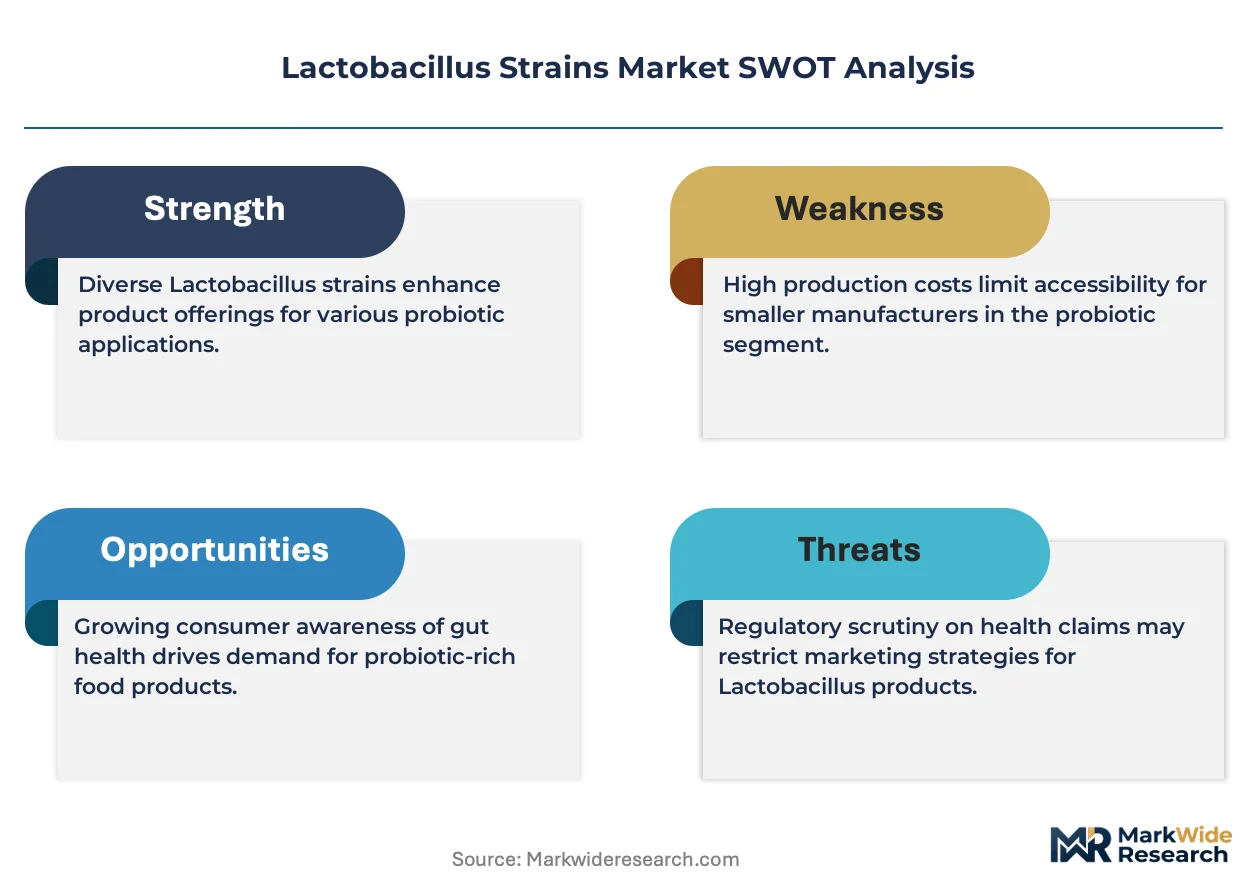
Single-strain unbundling is pivoting toward multi-strain bundled formulations, giving buyers flexibility to match specific health claims with targeted microbiome outcomes. Novonesis Group leverages its enzymology heritage to anchor high-throughput strain screening capabilities. Chr. Hansen specializes in clinically documented strains for dairy applications, while DuPont competes through extensive intellectual property around gastrointestinal resilience.
Lactobacillus strains comprise live bacterial cultures, predominantly facultative anaerobes with optimal growth between 30°C and 40°C and colony-forming unit counts typically standardized at 10^9 CFU per serving, cultivated through controlled fermentation and cryoprotection for viability retention in finished products. Fermented dairy maintains the largest revenue footprint among product types due to entrenched consumption habits and refrigerated distribution infrastructure, while dietary supplements capture the fastest expansion as direct-to-consumer channels reduce traditional retail friction. Gut health dominates application demand, though immune support formulations are gaining structural share as post-antibiotic recovery protocols expand in clinical settings.
FDA GRAS notifications and EFSA qualified health claims frame strain-specific market access, with EMA and national pharmacovigilance systems increasingly scrutinizing live biotherapeutic classifications for non-food applications. China's NMPA and SAMR enforce GB standards for probiotic labeling and viable count verification, creating compliance thresholds that favor producers with in-house analytical laboratories. Stakeholders must weigh strain patent expiration timelines against emerging CRISPR-edited chassis platforms that could reset competitive moats.
Market Dynamics
Whole-genome sequencing is compressing strain characterization timelines from months to weeks, forcing producers to rebuild quality assurance protocols around nucleotide-level identity verification rather than phenotypic screening.
Growth Catalysts
- EFSA Qualified Health Claims:Strain-specific dossiers enabling structure-function statements accelerate regulatory clearance for immune and digestive positioning across EU member states.
- Fermented Dairy Infrastructure:Cold-chain investments in tier-two Chinese cities expand distribution reach for live-culture products requiring strict temperature maintenance.
- CRISPR-Edited Chassis Platforms:Precision genome editing is creating next-generation strains with enhanced acid tolerance and bile salt resistance for gastrointestinal delivery.
Market Restraints
- Lyophilization Input Volatility:Trehalose and skim milk powder prices fluctuate with dairy commodity cycles, squeezing cryoprotection margins for bulk strain suppliers.
- Single-Source Fermentation Capacity:Contract manufacturing concentrates in Danish and French facilities, creating geographic concentration risk for North American brand owners.
- Viability Decay Technical Ceiling:Colony-forming unit degradation in ambient-stable formats limits shelf-life claims to 18-24 months despite market pressure for 36-month stability.
Strategic Opportunities
- Post-Antibiotic Recovery Protocols:Hospital formulary inclusion for Clostridioides difficile prevention creates clinical channel expansion beyond retail nutrition.
- Direct-to-Consumer Microbiome Testing:At-home stool analysis kits paired with strain-matched recommendations unlock personalized subscription revenue models.
- China GB Standards Alignment:NMPA and SAMR labeling harmonization favors producers with in-house viable count verification laboratories.
Industry Challenges
- Strain Bank Curation Expertise:PhD-level taxonomists capable of whole-genome phylogenetic analysis command premium compensation, constraining mid-tier R&D expansion.
- GRAS Notification Timelines:FDA pre-market safety consultations for novel strains extend 18-24 months, delaying revenue recognition for discovery pipelines.
- Multi-Strain Compatibility Validation:Synergistic and antagonistic interaction mapping requires extensive in vitro and clinical testing, inflating formulation development costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactobacillus Strains Market |
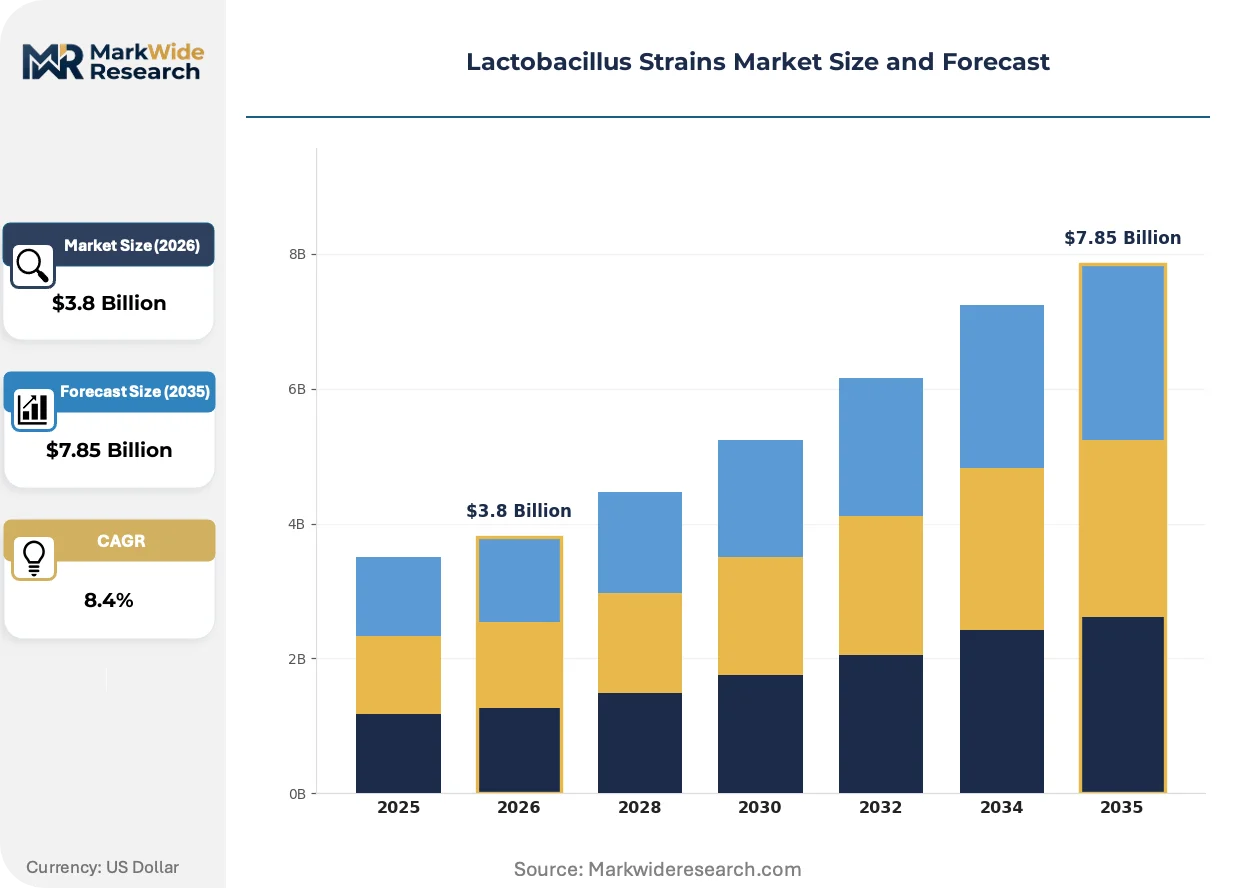
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotic Capsules, Fermented Dairy, Dietary Supplements, Functional Foods Application: Gut Health, Immune Support, Nutritional Supplementation, Food Preservation Delivery Mode: Powder, Liquid, Tablet, Softgel End User: Healthcare Providers, Retail Customers, Food Manufacturers, Nutraceutical Companies |
| Companies Covered | Novonesis Group, Chr. Hansen, DuPont, International Flavors & Fragrances, Lallemand, DSM-firmenich, Kerry Group, BioGaia, Yakult Honsha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactobacillus Strains Market Emerging Trajectories
Strain-level transparency is becoming a non-negotiable purchase criterion as buyers demand nucleotide identity verification beyond genus-level labeling. This shift is rewiring competitive advantage toward genomic documentation capabilities.
Single-molecule real-time sequencing is overtaking traditional 16S rRNA methods for strain authentication. Dairy processors in the Netherlands and Germany now require whole-genome maps for supplier qualification. This technology is compressing quality control cycles from quarterly batch testing to continuous in-line monitoring.
China's GB 7718 and GB 28050 standards for probiotic labeling enforce viable count verification at production and expiration dates. SAMR enforcement actions against mislabeled CFU claims have intensified since 2023. Domestic Chinese producers with captive analytical laboratories capture preferential shelf placement in tier-one retail.
Subscription-based microbiome optimization programs are displacing one-time supplement purchases. Direct-to-consumer platforms in the United States and United Kingdom pair at-home testing with strain-matched monthly shipments. This model concentrates highest adoption among urban consumers aged 28-42 seeking preventive health protocols.
Lactobacillus Strains Market Segmentation
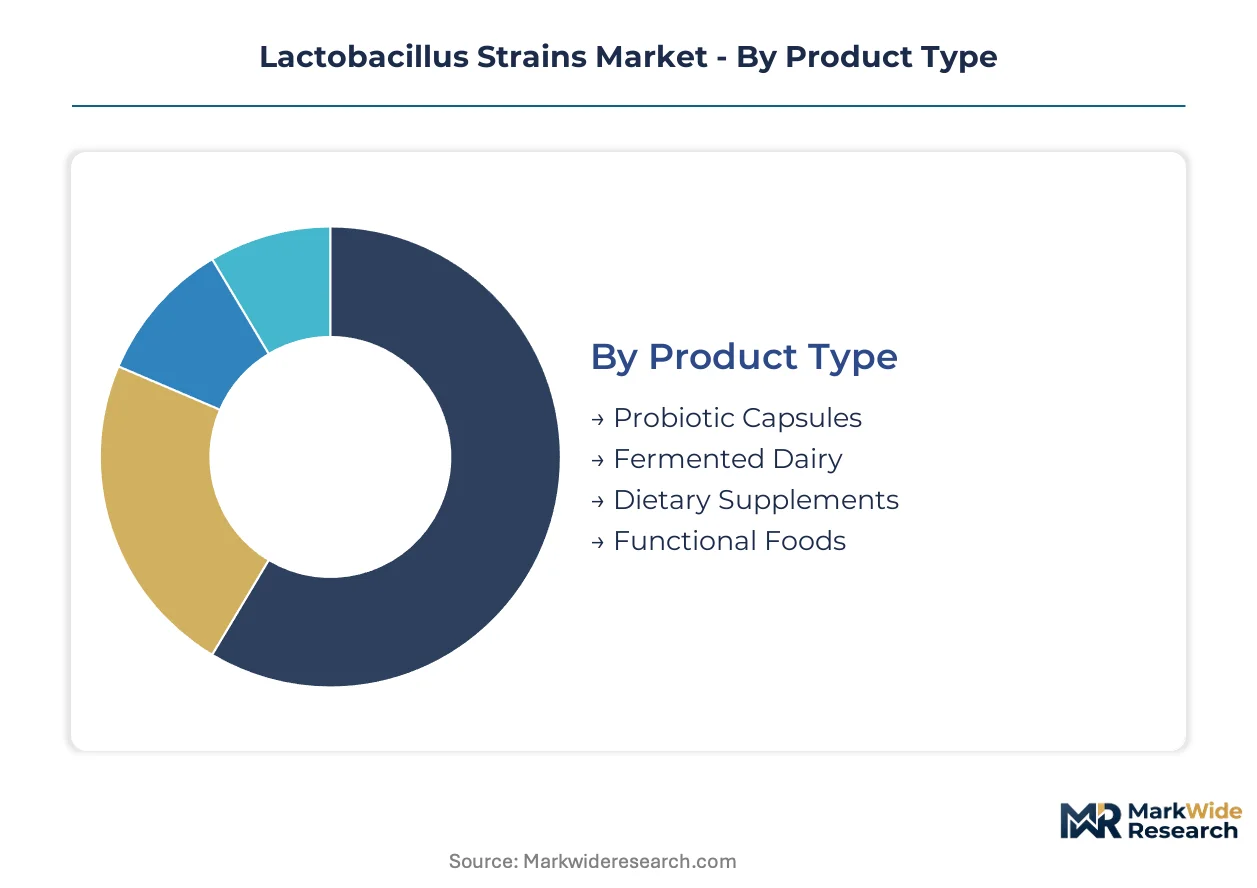
Strain suppliers configure manufacturing assets around specific formulation formats, with cryoprotection requirements and stability profiles varying sharply across delivery modes. Product type selection determines regulatory pathway complexity and margin structure for finished goods producers.
Product Type:
Supply concentrates in facilities capable of high-throughput fermentation coupled with specialized drying infrastructure for viability retention.
- Fermented Dairy:Live cultures integrated into yogurt, kefir, and cheese matrices at 10^6 to 10^9 CFU per gram. Cold-chain dependence in tier-two Chinese cities and German retail networks sustains demand for refrigerated formats despite ambient-stable alternatives. Margin pressure from dairy commodity cycles compresses cryoprotection budgets.
- Dietary Supplements:Freeze-dried strains encapsulated with trehalose or microcrystalline cellulose carriers for shelf-stable distribution. Direct-to-consumer channels in the United States and United Kingdom reduce retail friction and enable subscription revenue models. EFSA qualified health claims and FDA GRAS notifications frame competitive positioning.
- Probiotic Capsules:Hard-shell gelatin or hydroxypropyl methylcellulose enclosures protecting acid-sensitive strains from gastric degradation.
- Functional Foods:Strains incorporated into non-dairy beverages, cereals, and snack matrices targeting preventive nutrition positioning.
Fermented dairy absorbs the bulk of installed capacity; dietary supplements are expanding most quickly.
Application:
Clinical validation depth determines reimbursement eligibility and hospital formulary access across target indications.
- Gut Health:Strains selected for bile salt resistance and acid tolerance to survive gastrointestinal transit. Post-antibiotic recovery protocols in clinical settings and irritable bowel syndrome management drive prescription and over-the-counter demand. Whole-genome sequencing verifies strain identity for therapeutic claims.
- Immune Support:Immunomodulatory strains documented for cytokine modulation and respiratory infection prophylaxis. Pediatric and elderly populations in Japan and South Korea show concentrated adoption of clinically substantiated formulations. EMA scrutiny of live biotherapeutic classifications creates regulatory friction for non-food positioning.
- Nutritional Supplementation:General wellness positioning without disease-specific claims, relying on structure-function statements.
- Food Preservation:Bacteriocin-producing strains extending shelf life through competitive exclusion of spoilage organisms.
Gut health commands the deepest clinical evidence base; immune support is climbing the fastest as post-pandemic preventive protocols institutionalize.
Delivery Mode:
Moisture sensitivity and oxygen exposure tolerance dictate packaging format selection and stability testing protocols.
- Powder:Sachet and bulk formats for beverage fortification and infant formula applications requiring reconstitution.
- Liquid:Ready-to-drink shots and concentrates with shorter shelf life but superior bioavailability claims.
- Tablet:Compressed formulations with enteric coatings for targeted intestinal release.
- Softgel:Oil-suspended strains in gelatin or plant-based shells for lipid-soluble co-delivery.
Powder formats dominate industrial-scale procurement; liquid delivery is gaining share fastest in premium direct-to-consumer channels.
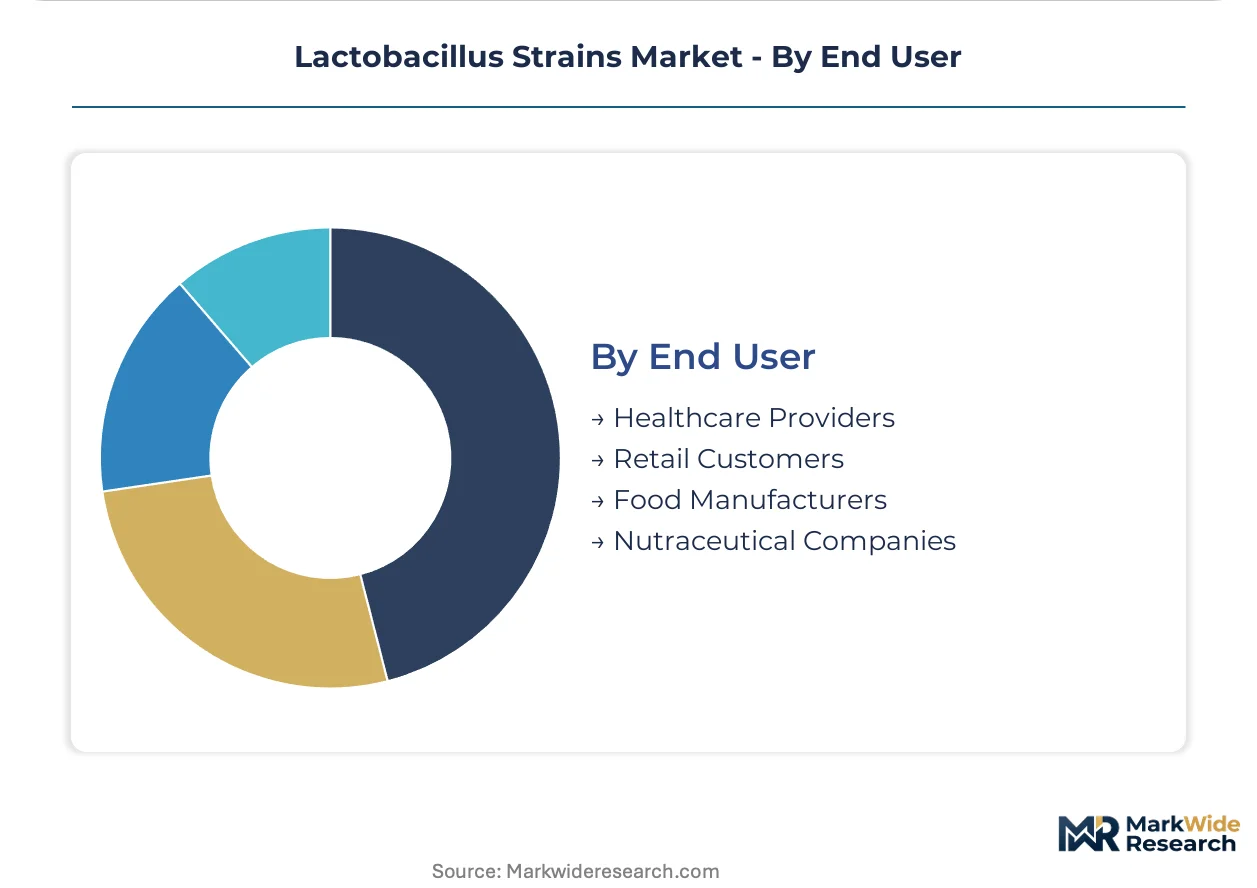
End User:
Procurement sophistication varies from institutional tender processes to algorithmic e-commerce replenishment.
- Food Manufacturers:Dairy processors and beverage companies requiring strain documentation for supplier qualification audits.
- Nutraceutical Companies:Contract manufacturers and brand owners sourcing bulk strains for encapsulation and tableting.
- Healthcare Providers:Hospital systems and clinics incorporating live biotherapeutics into infection prevention protocols.
- Retail Customers:Individual consumers purchasing through pharmacies, supermarkets, and online platforms.
Food manufacturers anchor volume procurement; healthcare providers are deepening fastest as clinical evidence accumulates for specific indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hengqin Free Trade Zone and Yangtze River Delta special economic corridors concentrate probiotic strain manufacturing through tax incentives and streamlined NMPA registration pathways. These zones anchor Asia-Pacific capacity expansion while European fermentation clusters leverage Denmark's biotech industrial parks.
China
Tier-one and tier-two cities drive domestic consumption deepening as preventive nutrition protocols institutionalize post-pandemic. SAMR and NMPA enforce GB 7718 and GB 28050 standards for viable count verification at production and expiration dates. Shanghai and Beijing host captive analytical laboratories that capture preferential retail shelf placement through compliance speed.
United States
Direct-to-consumer microbiome testing platforms unlock personalized subscription revenue models among urban consumers aged 28-42. FDA GRAS notification timelines extend 18-24 months for novel strains, delaying revenue recognition for discovery pipelines. Greater Boston and San Diego biotech clusters concentrate CRISPR-edited chassis platform development for next-generation acid tolerance.
Germany
Dairy processors in Bavaria and North Rhine-Westphalia now require whole-genome maps for supplier qualification beyond genus-level labeling. EFSA qualified health claims enable structure-function statements for immune and digestive positioning across EU member states. Cologne and Munich anchor high-throughput strain screening capabilities through enzymology heritage integration.
Japan
Pediatric and elderly populations show concentrated adoption of clinically substantiated immunomodulatory formulations for respiratory infection prophylaxis. METI and PMDA scrutinize live biotherapeutic classifications for non-food applications, creating regulatory friction. Tokyo and Osaka metropolitan areas sustain entrenched consumption habits through refrigerated distribution infrastructure for fermented dairy.
Denmark
Contract manufacturing concentrates in Danish fermentation facilities, creating geographic concentration risk for North American brand owners seeking single-source capacity. EMA pharmacovigilance systems increasingly monitor live biotherapeutic classifications. Copenhagen's biotech industrial parks specialize in clinically documented strains for dairy applications through cold-chain investments.
Lactobacillus Strains Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across strain characterization and formulation development. The vendor base stratifies into three tiers: global enzyme and ingredient conglomerates with cross-category R&D budgets, dedicated probiotic houses with strain bank depth, and regional contract fermenters serving private-label demand. Strategic moves concentrate on M&A for strain portfolio expansion and backward integration into captive fermentation capacity.
Among the diversified conglomerates, Novonesis Group and International Flavors & Fragrances exemplify archetypes leveraging enzymology heritage and flavor science integration respectively. Chr. Hansen occupies a position representing the dedicated probiotic specialist tier with documented dairy application focus. These three entities anchor competitive dynamics through differential emphasis on genomic documentation capabilities versus formulation flexibility.
| Leading Market Players |
|---|
| Novonesis Group |
| Chr. Hansen |
| DuPont |
| International Flavors & Fragrances |
| Lallemand |
| DSM-firmenich |
| Kerry Group |
| BioGaia |
| Yakult Honsha |
| Others |
Supply Flow & Price Mechanics
China's dual carbon goals gate qualified supply and premium-tier pricing access for Lactobacillus strain producers, as carbon-intensive fermentation processes face emissions audits that favor facilities with renewable energy certificates. NMPA and SAMR enforcement of GB standards for viable count verification creates compliance thresholds that separate premium-priced strains with genomic documentation from commodity-grade alternatives.
Pricing Analysis
Margin tightening in standard-grade strains reflects trehalose and skim milk powder cost volatility tied to dairy commodity cycles. Three-tier pricing structure across premium, standard, and economy levels differentiates by whole-genome sequencing certification and clinical documentation depth. Food manufacturers show highest price sensitivity due to compressed cryoprotection budgets, while healthcare providers accept premium positioning for hospital formulary inclusion.
Supply Chain Analysis
Regional distribution centers in Denmark and Germany anchor hub-and-spoke patterns for European cold-chain delivery of live-culture products. Manufacturing concentrates in Denmark, France, and China, with fermentation capacity drawing from trehalose cryoprotectants, skim milk powder carriers, and specialized bioreactor equipment. Single-source concentration in Danish facilities creates geographic vulnerability for North American brand owners. Distribution runs through refrigerated logistics networks with temperature-validated last-mile protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Whole-genome sequencing is displacing phenotypic screening as the dominant quality assurance technology, forcing producers to rebuild competitive positioning around nucleotide-level strain authentication capabilities.
For Market Incumbents: Anchor defensive positioning through backward integration into captive fermentation capacity in China's Yangtze River Delta special economic corridors. Deepen strain bank curation expertise by recruiting PhD-level taxonomists capable of phylogenetic analysis, as CRISPR-edited chassis platforms threaten to reset patent-based competitive moats. For New Entrants and Emerging Players: Enter via direct-to-consumer microbiome testing platforms paired with strain-matched subscription models in the United States and United Kingdom. Target urban consumers aged 28-42 seeking preventive health protocols, leveraging at-home stool analysis kits as the primary go-to-market angle. For Investors and Strategic Acquirers: FDA GRAS notification timeline compression is the leading indicator that regulatory velocity is improving for novel strain commercialization. Prioritize acquisition targets with in-house analytical laboratories and documented EFSA qualified health claims, watching for EMA pharmacovigilance guidance on live biotherapeutic classifications as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CRISPR-Edited Chassis Platform Development | Precision genome editing creates next-generation strains with enhanced acid tolerance for gastrointestinal delivery. |
| Captive Fermentation Capacity Expansion | In-house bioreactor infrastructure in China's Hengqin Free Trade Zone reduces single-source geographic concentration risk. |
| Whole-Genome Sequencing Integration | Nucleotide-level identity verification compresses quality control cycles from quarterly testing to continuous monitoring. |
| Direct-to-Consumer Subscription Launch | Algorithmic replenishment models paired with at-home microbiome testing unlock recurring revenue streams. |
| Hospital Formulary Partnership | Clinical channel expansion for post-antibiotic recovery protocols builds reimbursement-eligible demand beyond retail. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving fermentation facility managers, regulatory affairs specialists at strain suppliers, dairy processor procurement leads, and hospital formulary directors. FDA GRAS notifications, EFSA qualified health claims databases, China's NMPA registration records, and SAMR enforcement actions provided structured secondary validation. Bottom-up strain volume estimates triangulated against top-down market sizing.
Granularity-level modeling tracked product type, application, delivery mode, and end user across the projection horizon, with geographic clustering at country level for China, the United States, Germany, Japan, and Denmark. CAGRs derived from segment-level growth trajectory analysis incorporating cold-chain infrastructure expansion rates, regulatory clearance velocity, and subscription model adoption curves. Strain patent expiration timelines and CRISPR platform development milestones informed competitive dynamics assumptions.
Revisions become necessary when EMA pharmacovigilance guidance on live biotherapeutics materializes, when China's GB standards enforcement intensity shifts, or when dairy commodity price volatility exceeds historical bands. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Ripening Cultures Market
Industrial Microbiology
Bacterial Amylase Market
Industrial Microbiology
Molecular Microbiology Market
Industrial Microbiology
Microbial Cell Banking Market
Industrial Microbiology
Global Starter Culture Market
Industrial Microbiology
Microbial Therapeutic Products Market
Industrial Microbiology
Benzoate-Free Enzymes Market
Industrial Microbiology
Automated Microbial Detection Systems Market
Industrial Microbiology
Cultured Dextrose Market
Industrial Microbiology
Specialty Cultures Market
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Microbial Culture Market
Industrial Microbiology
Microbial Coagulants Market
Industrial Microbiology
Lactic Acid Bacteria Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
Microbiology Culture Market