
 Mesophilic Bacteria Market | 2026-2036
Mesophilic Bacteria Market Size, Share, and Industry Trends Forecast 2026-2036
Mesophilic Bacteria Market Analytics
Plant-based fermentation substrates are recalibrating input economics for mesophilic culture manufacturers. DSM-Firmenich AG leverages its integrated biotechnology platform to secure strain development pipelines. Lallemand Inc. anchors North American supply through captive yeast and bacteria production facilities. Chr. Hansen Holding A/S differentiates via specialized dairy culture portfolios with documented performance under ISO-compliant quality systems.
Mesophilic bacteria are microorganisms that thrive at moderate temperatures of 20°C to 45°C, typically comprising Lactococcus, Lactobacillus, and Streptococcus genera used in controlled fermentation processes. These organisms metabolize sugars to produce lactic acid, ethanol, or other metabolites essential for food preservation, flavor development, and probiotic functionality. Starter cultures command the largest share of product-type revenue due to entrenched dairy industry reliance on standardized fermentation inoculants. Probiotic cultures represent the fastest-expanding category as functional food and nutraceutical formulators seek clinically validated strains. Within applications, dairy products absorb the majority of volume while fermented foods capture expanding margin pools through craft and artisan positioning.
EMA guidelines on microbial quality and EFSA safety assessments shape strain approval timelines and commercialization pathways for European suppliers. REACH compliance requirements for culture media components and downstream processing chemicals filter market access for non-European producers. FDA GRAS notifications and USDA organic certification standards create parallel compliance obligations for cultures entering North American food channels. Stakeholders must weigh regulatory harmonization progress against regional strain registration costs when allocating R&D and commercial resources.
Market Dynamics
EU Green Deal implementation is forcing mesophilic culture manufacturers to reconfigure fermentation media sourcing and downstream processing chemistry, compressing legacy supply relationships while opening certified-bioinput channels.
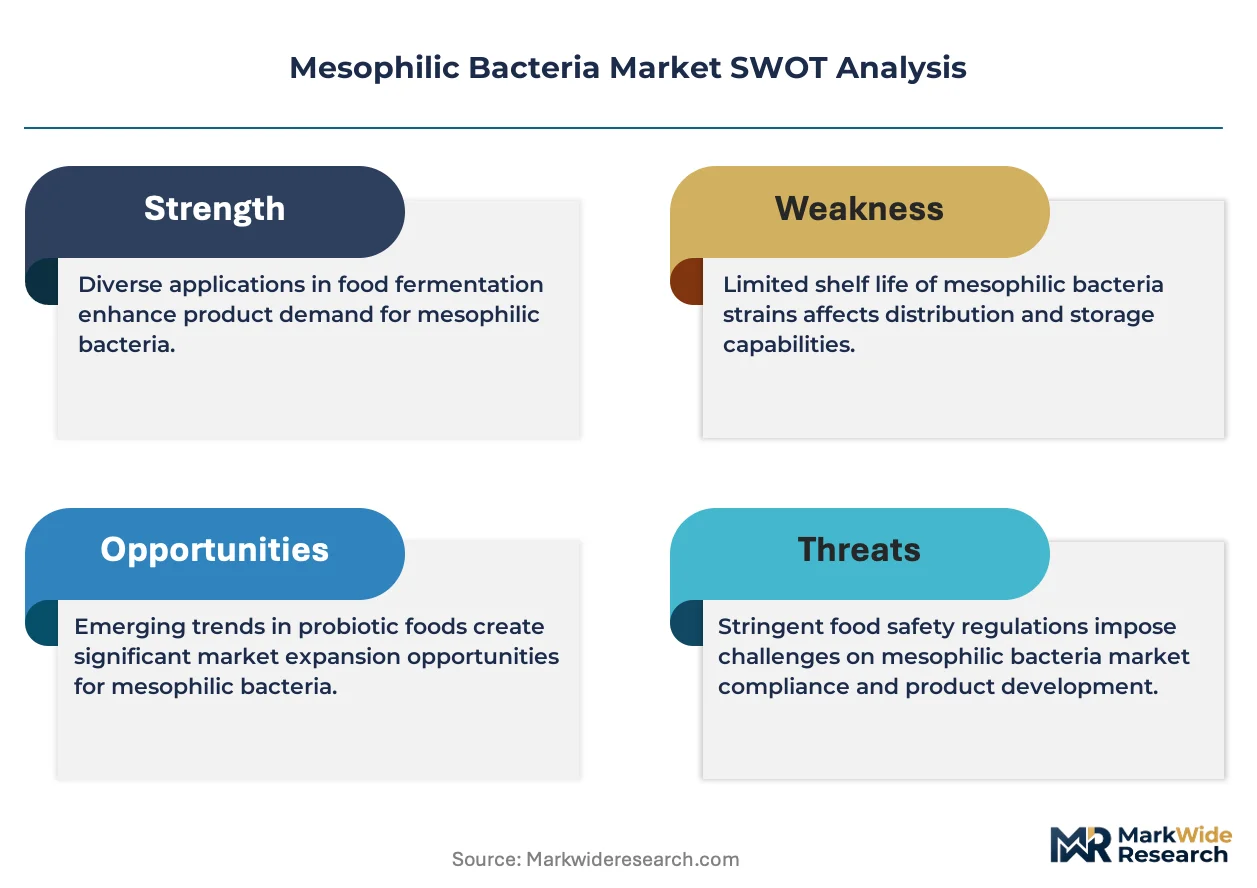
Growth Catalysts
- REACH-compliant culture media:ECHA registration pathways for novel fermentation substrates are unlocking plant-derived peptone alternatives. Food processors in the Netherlands are piloting these inputs at commercial scale.
- Fermented beverage expansion:Craft kombucha and kefir producers are contracting dedicated starter culture volumes. This segment pulls specialized Lactobacillus strains with documented flavor compound profiles.
- EFSA health claim validation:Strain-specific probiotic dossiers are clearing novel food pathways faster than generic culture approvals. German dairy cooperatives are prioritizing EFSA-backed strains for premium positioning.
Market Restraints
- Phosphate buffer cost volatility:Downstream processing relies on food-grade phosphate salts concentrated in Moroccan and Chinese supply. Price swings compress margin on standard-grade cultures.
- Strain bank concentration:Public culture collections in France and Germany control reference strain access for commercial derivative development. Licensing terms favor incumbent manufacturers.
- Organic acid substitution:Chemical acidulants in processed foods compete with fermentation-derived preservation. Cost-sensitive applications in Eastern European meat processing are switching.
Strategic Opportunities
- Precision fermentation platforms:Cell-free enzyme production is converging with traditional culture manufacturing. Danish biotechnology parks are attracting contract development investment.
- Swiss nutraceutical channel:Swissmedic's streamlined strain notification for supplements creates faster commercialization than EU novel food routes. Probiotic formulators are establishing Geneva-based regulatory subsidiaries.
- Carbon-negative fermentation:EU Emissions Trading System incentives for bio-based processes are subsidizing anaerobic digester integration. French dairy clusters are capturing methane for on-site energy.
Industry Challenges
- Phage resistance engineering:Virulent Lactococcus lactis phages in industrial cheese vats demand continuous strain rotation. R&D teams face compressed development cycles against evolving phage populations.
- ISO 22000 certification backlog:Third-party audit capacity constraints are extending food safety management system approvals. Smaller culture houses are queuing 8-12 months for initial certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mesophilic Bacteria Market |
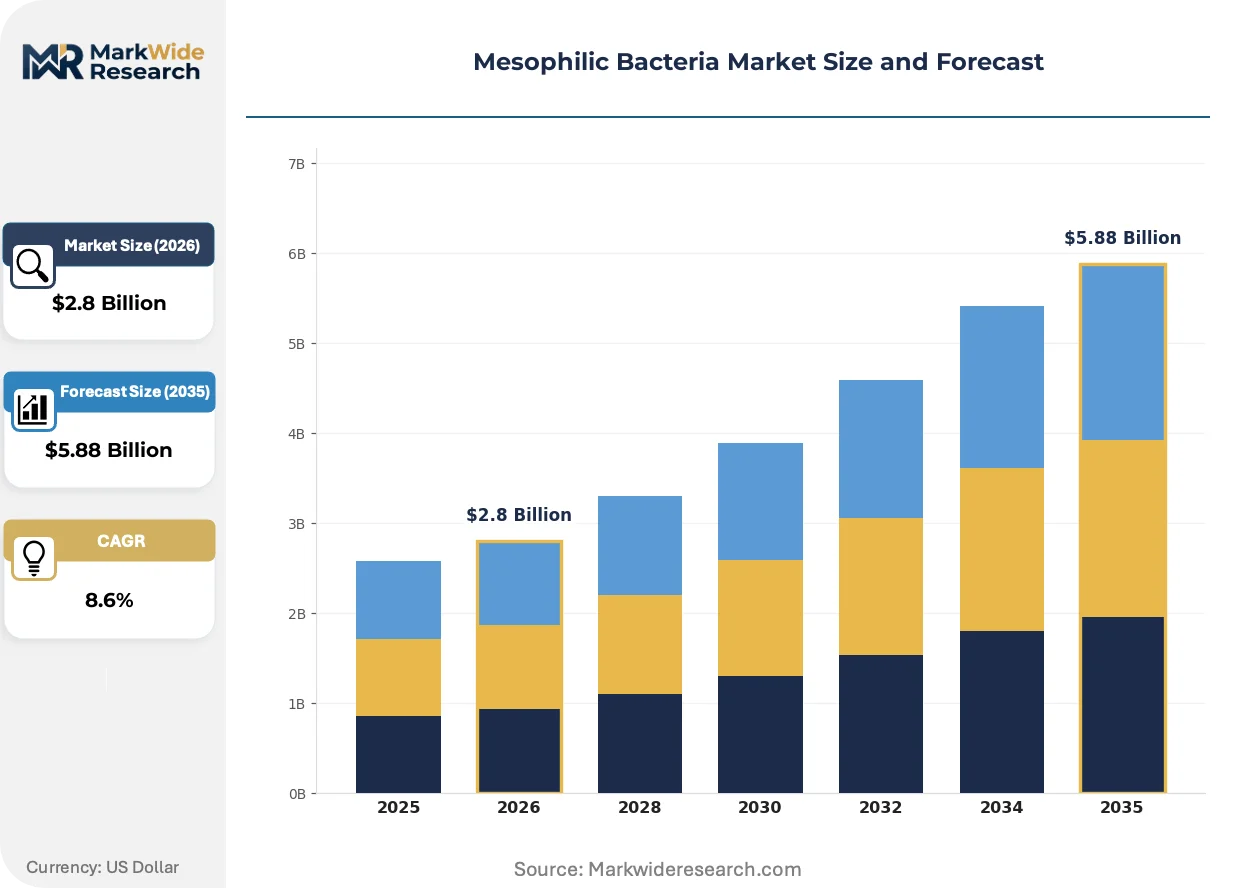
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Culture, Freeze-Dried Culture, Starter Culture, Probiotic Culture End Use Industry: Food Processing, Biotechnology, Pharmaceuticals, Agriculture Application: Dairy Products, Fermented Foods, Biofuels, Animal Feed Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Lallemand Inc., CSK, Chr. Hansen Holding A/S, Lactina, BDF Ingredients, DuPont de Nemours, Inc., Sacco System S.R.L., LB Bulgaricum, DSM-Firmenich AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mesophilic Bacteria Market Evolving Landscape
Digital strain characterization and automated bioprocess control are compressing development timelines while enabling precision matching of culture performance to specific fermentation matrices.
Multi-omics screening platforms are converging with machine learning-guided strain selection. Dairy culture suppliers are deploying these tools to predict acidification kinetics in complex milk substrates. The technology is converging with traditional phenotypic screening to halve strain optimization cycles.
REACH authorization requirements for residual processing chemicals are tightening purity specifications on imported culture media components. Non-European suppliers face reformulation costs or market exclusion. German fermentation houses are accelerating in-house peptone production to secure supply.
Direct contracting between artisan food producers and specialized culture houses is displacing distributor-mediated supply. French farmhouse cheese makers are sourcing heritage strains through regional cooperative networks. This pattern concentrates in protected designation of origin clusters where traceability commands premium positioning.
Mesophilic Bacteria Market Segmentation
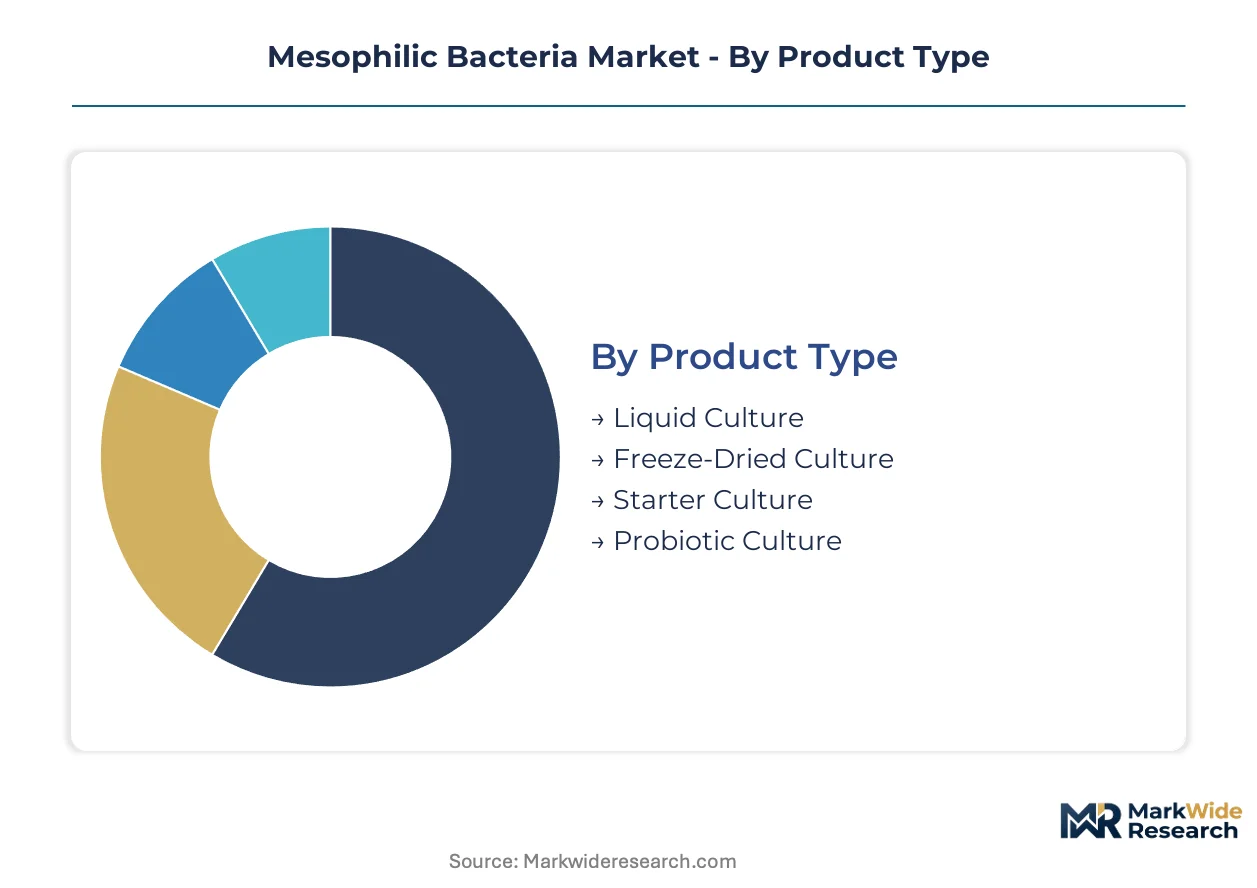
Mesophilic bacteria suppliers configure production lines around physical format and functional specification tiers. Each segment carries distinct fermentation economics, regulatory pathways, and customer procurement rhythms that shape portfolio prioritization.
Product Type:
Upgrade cycles in industrial fermentation favor formats that reduce handling labor and extend shelf stability without sacrificing viability.
- Liquid Culture:Active cell suspensions in buffered media deliver immediate inoculation capacity for large-scale dairy operations. German cheese cooperatives favor tanker-delivered volumes to eliminate rehydration steps and reduce phage exposure during processing.
- Freeze-Dried Culture:Lyophilized preparations achieve multi-year stability at ambient temperatures, cutting cold chain costs for export shipments. French culture houses report rising demand from African and Middle Eastern dairy startups lacking refrigerated distribution infrastructure.
- Starter Culture:Standardized strain blends with documented acidification kinetics dominate contract volumes for commodity cheese and yogurt production.
- Probiotic Culture:Clinically validated strains command premium positioning in functional food and nutraceutical channels, with EFSA dossier requirements filtering supplier participation.
Starter Culture sits at the top of the volume ranking, with Probiotic Culture climbing the fastest.
End Use Industry:
Customer procurement sophistication varies sharply across sectors, with biotechnology and pharmaceutical buyers imposing stricter documentation and audit protocols than food processors.
- Food Processing:Dairy, meat, and plant-based fermentation operations consume the bulk of commercial culture volumes. Netherlands-based ingredient suppliers are consolidating strain supply contracts to secure year-round availability for seasonal cheese production peaks.
- Biotechnology:Enzyme manufacturers and precision fermentation platforms require high-purity, genetically characterized strains with full provenance documentation. Danish biotech parks are attracting dedicated culture supply partnerships.
- Pharmaceuticals:Live biotherapeutic products and microbiome therapeutics demand GMP-compliant production with batch-level release testing.
- Agriculture:Silage inoculants and soil microbiome products utilize lower-cost strains with less stringent purity specifications.
Food Processing absorbs the greatest share of standard-grade volumes, while Biotechnology posts the steepest expansion trajectory.
Application:
Application selection determines strain performance requirements, with dairy demanding rapid acidification and biofuels prioritizing robustness in inhibitory substrate conditions.
- Dairy Products:Cheese, yogurt, and fermented milk production rely on mesophilic cultures for controlled acidification and flavor compound generation. Italian protected designation of origin clusters specify heritage strains with documented regional performance.
- Fermented Foods:Sauerkraut, kimchi, and craft beverage producers seek specialized Lactobacillus strains with targeted aromatic profiles. Belgian kombucha startups are contracting direct with culture houses for bespoke strain development.
- Biofuels:Cellulosic ethanol and biogas operations utilize thermotolerant mesophilic consortia for lignocellulose breakdown.
- Animal Feed:Probiotic feed additives for poultry and swine emphasize spore-forming strains with gastric survival characteristics.
Dairy Products maintains the largest installed base, with Fermented Foods gaining share fastest.
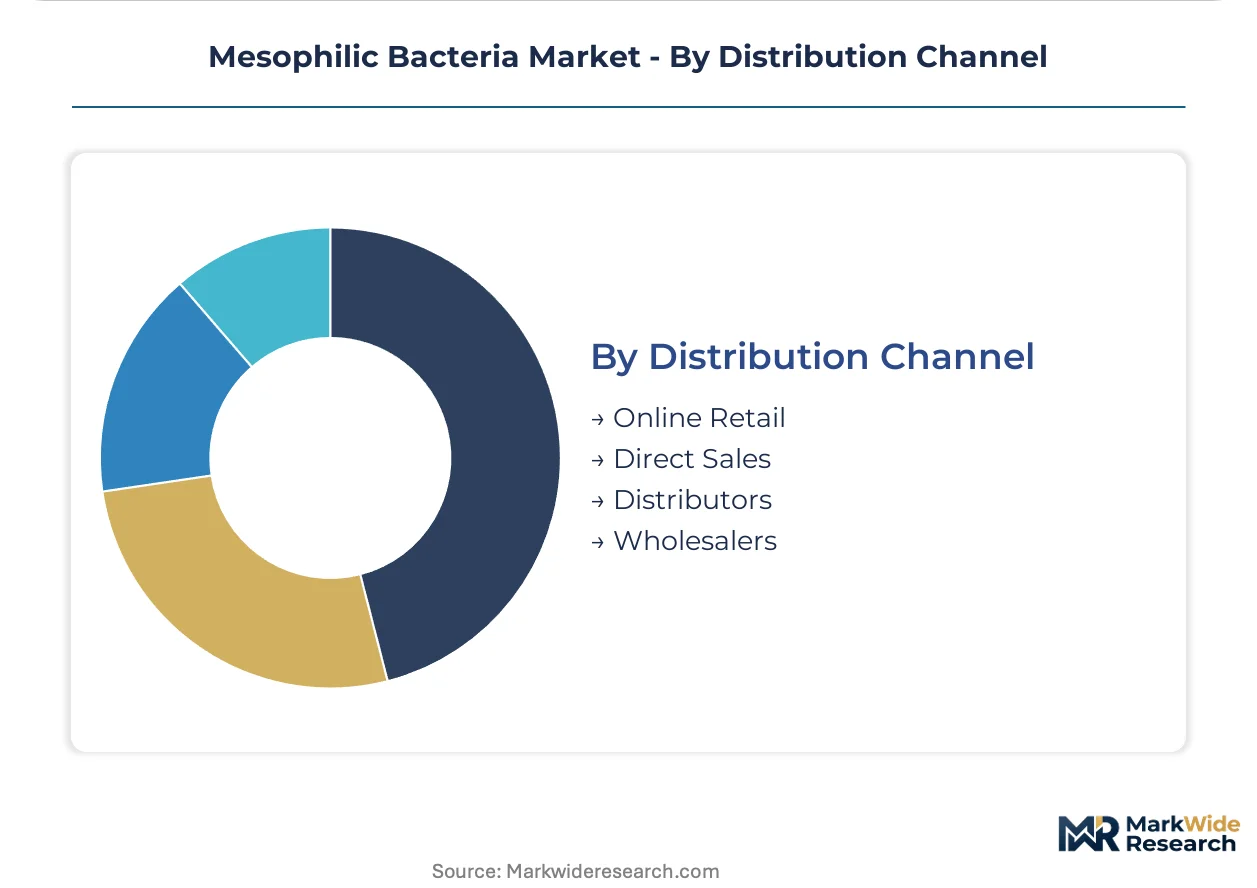
Distribution Channel:
Channel selection reflects customer scale and technical support requirements, with artisan producers bypassing traditional distribution layers.
- Direct Sales:Large dairy cooperatives and multinational food manufacturers negotiate multi-year supply agreements with dedicated technical service support. Spanish cheese consortiums are consolidating procurement through single-source direct contracts.
- Distributors:Regional culture specialists maintain local inventory and application expertise for mid-tier processors. Polish dairy equipment distributors are expanding culture portfolios to capture bundled sales.
- Online Retail:Small-scale artisan producers and home fermentation enthusiasts purchase standardized strains through specialized e-commerce platforms.
- Wholesalers:Broad-line ingredient traders handle commodity-grade cultures with minimal technical support.
Direct Sales commands the highest contract values, with Online Retail expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German dairy fermentation clusters anchor continental demand for mesophilic cultures, with EFSA regulatory pathways and REACH compliance requirements shaping supplier access across Western Europe. France, the Netherlands, Italy, and Switzerland concentrate specialized production capabilities and heritage strain preservation networks.
Germany
Dairy cooperatives in Bavaria and Lower Saxony contract bulk starter volumes for seasonal cheese production peaks. EFSA health claim validation accelerates strain approval for probiotic positioning in premium yogurt segments. Berlin-Brandenburg biotechnology parks host precision fermentation platforms developing next-generation culture manufacturing.
France
Protected designation of origin cheese makers in Auvergne-Rhône-Alpes specify heritage Lactococcus strains with documented regional performance. ANSM oversight of live biotherapeutic products creates parallel regulatory tracks for pharmaceutical-grade cultures. Roquefort-sur-Soulzon and Comté clusters maintain direct contracting relationships with specialized culture houses.
Netherlands
Wageningen University research partnerships accelerate plant-derived peptone development for REACH-compliant fermentation media. Dutch ingredient suppliers consolidate strain supply contracts to secure year-round availability. North Brabant dairy processing corridors pilot carbon-negative anaerobic digester integration for on-site energy capture.
Italy
Parmigiano-Reggiano and Grana Padano consortia mandate specific Lactobacillus strains for protected origin compliance. Emilia-Romagna cheese makers source through regional cooperative networks bypassing distributor layers. Italian fermentation houses specialize in thermotolerant mesophilic consortia for traditional aged cheese categories.
Switzerland
Swissmedic's streamlined strain notification for supplements attracts probiotic formulators establishing Geneva-based regulatory subsidiaries. Nestlé and specialized nutraceutical manufacturers leverage faster commercialization pathways than EU novel food routes. Basel biotechnology corridors concentrate cell-free enzyme production converging with traditional culture manufacturing.
Mesophilic Bacteria Market Competitive Landscape
Global majors compete with regional champions across strain development capabilities and regulatory dossier depth, creating a tiered structure where scale-driven players anchor commodity supply while specialists capture premium positioning. Three archetypes dominate: integrated biotechnology platforms with captive fermentation infrastructure, heritage culture houses with protected designation of origin relationships, and precision fermentation entrants targeting pharmaceutical-grade applications. Competitive moves concentrate on backward integration into culture media production and strategic partnerships with dairy cooperative networks.
Within the integrated biotechnology tier, DSM-Firmenich AG and Chr. Hansen Holding A/S exemplify platform-scale players with diversified strain portfolios spanning starter and probiotic categories. Lallemand Inc. occupies a position as a North American-anchored specialist with captive yeast and bacteria production facilities. These three entities represent distinct geographic and capability positioning archetypes rather than direct substitutability, with each serving as an anchor for industry-level commentary on consolidation patterns and specialization trajectories.
| Leading Market Players |
|---|
| Lallemand Inc. |
| CSK |
| Chr. Hansen Holding A/S |
| Lactina |
| BDF Ingredients |
| DuPont de Nemours, Inc. |
| Sacco System S.R.L. |
| LB Bulgaricum |
| DSM-Firmenich AG |
| Others |
Value Network & Pricing Analysis
Dairy cooperative procurement concentration in Germany and the Netherlands anchors contract-based long-term offtake agreements for bulk starter cultures, with pricing power tilting toward suppliers who control captive fermentation infrastructure.
Pricing Analysis
Phosphate buffer and plant-derived peptone cost pass-through clauses dominate contract renegotiation cycles, with REACH-compliant media inputs commanding premium positioning over standard-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-validated probiotic strains from commodity starter blends and generic silage inoculants. Cost compression in standard-grade cultures intensifies because Moroccan phosphate supply volatility feeds directly into downstream processing economics. Small-scale artisan producers exhibit highest price sensitivity, while pharmaceutical-grade buyers prioritize batch documentation over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from German and Dutch dairy cooperatives require qualified backup suppliers for critical Lactococcus and Lactobacillus strains, fragmenting volume concentration across multiple culture houses. Manufacturing gravity centers on France, Germany, and Denmark, with Swissmedic-regulated Swiss facilities capturing nutraceutical overflow. Raw material dependencies rest on food-grade phosphate salts, soy and pea protein hydrolysates, and cryoprotectant formulations. Single-source vulnerability concentrates in reference strain licensing from French and German public culture collections. Distribution runs through direct sales agreements for large cooperatives, supplemented by regional distributors for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance cost differentials between EU and non-European suppliers create geographic-arbitrage opportunities for manufacturers who secure ECHA-registered fermentation substrates ahead of competitor qualification timelines.
For Market Incumbents: Deploy backward integration into culture media production to neutralize phosphate buffer cost volatility and REACH authorization bottlenecks. DSM-Firmenich AG and Chr. Hansen Holding A/S exemplify this trajectory through in-house peptone manufacturing. Second, lock exclusive heritage strain licensing with French protected designation of origin clusters before precision fermentation entrants replicate regional performance documentation. The threat of cell-free enzyme platforms displacing traditional culture manufacturing demands accelerated R&D in phage-resistant strain engineering. For New Entrants and Emerging Players: The premium-economy price gap in probiotic cultures creates entry space for clinically validated strains positioned below EFSA-backed incumbents but above generic commodity blends. Target Swiss nutraceutical channels through Swissmedic notification pathways, which bypass EU novel food timelines. Belgian kombucha and kefir startups represent the most penetrable segment, with direct contracting models displacing distributor layers. Go-to-market leverage rests on bespoke strain development partnerships with artisan producers seeking differentiated aromatic profiles. For Investors and Strategic Acquirers: Specialized biotechnology platforms are the most active acquirer in this space, seeking precision fermentation capabilities that converge with traditional culture manufacturing. Long-term viability favors targets with dual-use strain portfolios spanning food and pharmaceutical applications, plus captive regulatory dossier depth. Acquisition target archetype: mid-cap culture houses with ISO 22000 certification and established dairy cooperative relationships but limited probiotic validation infrastructure. The signal to watch is EFSA health claim clearance velocity, which separates premium-positioned strains from commodity alternatives.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Culture Media Production | German fermentation houses secure supply independence from REACH-authorized peptone sources. |
| EFSA Health Claim Dossier Investment | Strain-specific validation unlocks premium positioning in German and Dutch dairy channels. |
| Swissmedic Regulatory Subsidiary Establishment | Geneva-based operations accelerate probiotic commercialization versus EU novel food routes. |
| Heritage Strain Cooperative Partnerships | French protected designation of origin clusters lock in traceability-premium supply relationships. |
| Phage Resistance Engineering Program | Continuous strain rotation capabilities defend against virulent Lactococcus lactis phage evolution. |
Research Methodology
Bottom-up dairy fermentation modeling reconciled against top-down biotechnology supply tracking forms the analytical core of this study. Primary interviews with culture house technical directors, dairy cooperative procurement managers, fermentation media suppliers, and regulatory affairs specialists at EFSA and Swissmedic were cross-validated against secondary sources including ECHA registration databases, EFSA novel food opinions, customs trade records for fermentation equipment, and SEC filings of publicly listed ingredient suppliers. This triangulation ensures demand-side consumption patterns align with supply-side capacity disclosures.
Historical trendline analysis of culture volume shipments, strain approval timelines, and input cost indices established baseline growth parameters across the projection horizon. Segmentation dimensions modeled include product format (liquid, freeze-dried), functional specification (starter, probiotic), end-use industry (food processing, biotechnology, pharmaceuticals), and application (dairy, fermented foods, biofuels). CAGRs were derived from slope analysis of normalized growth curves adjusted for regulatory inflection points. Industry-specific forecast inputs incorporated EFSA dossier clearance rates and REACH authorization progression timelines for novel fermentation substrates.
Caveats apply where EFSA health claim rejection rates, phosphate supply disruptions, or precision fermentation technology maturation could materially shift the outlook. Forecasts reflect assumptions about regulatory harmonization progress and strain bank licensing terms that may revise with policy changes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Microbial Seed Treatment Market
Industrial Microbiology
Probiotic Yeast Market
Industrial Microbiology
Antibiotic Resistance Market
Industrial Microbiology
Global Starter Culture Market
Industrial Microbiology
Global Microbiome Therapeutics Market
Industrial Microbiology
Benzoate-Free Enzymes Market
Industrial Microbiology
Global Bacterial Cell Culture Market
Industrial Microbiology
Global Escherichia Coli Testing Market
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Microbial Coagulants Market
Industrial Microbiology
Cultured Dextrose Market
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Mineral Yeast Market
Industrial Microbiology
Ripening Cultures Market
Industrial Microbiology
Microbial-Derived Fiber Market
Industrial Microbiology
Global Microbial Identification Market