
 Galactosidase Market | 2026-2036
Galactosidase Market Size, Share, and Industry Trends Forecast 2026-2036
Galactosidase Market Analysis
REACH is restructuring the cost-of-entry calculus for European galactosidase suppliers by mandating exhaustive substance safety dossiers for enzyme formulations. Novozymes leverages its recombinant production platforms to sustain leadership in high-purity beta-galactosidase supply. Chr. Hansen Holding anchors its position through deep specialization in dairy-application enzymes. Advanced Enzymes Technologies competes aggressively on manufacturing scale across Asian and North American markets.
Galactosidase denotes a class of glycoside hydrolase enzymes that catalyze the hydrolysis of galactose-containing carbohydrates, typically operating at pH ranges between 4.0 and 7.0 and temperatures of 35°C to 55°C depending on the microbial or fungal source; industrially, these enzymes serve primarily to degrade lactose in dairy processing and cleave galacto-oligosaccharides in legume processing and pharmaceutical synthesis. Beta-galactosidase dominates volume flows through its entrenched role in lactose-free milk production, while recombinant galactosidase captures the fastest expansion as biopharmaceutical applications for enzyme replacement therapy multiply. Powder formulations retain margin advantages in bulk industrial procurement, though liquid concentrates are displacing legacy formats in automated dairy processing installations.
The FDA exercises jurisdiction over food-contact and pharmaceutical-grade galactosidase through GRAS notifications and drug master file requirements, while China's SAMR enforces GB standards on enzyme activity thresholds and microbial contamination limits. ISO 22000 and FSSC 22000 certifications function as baseline qualifiers for supplier qualification by multinational food manufacturers. Stakeholders must monitor evolving EMA guidance on enzyme-based therapeutics and assess backward integration into recombinant strain development before regulatory pathways harden.
Market Dynamics
Recombinant production platforms are compressing cost curves for pharmaceutical-grade galactosidase while tightening purity specifications for food-contact enzymes reshape supplier qualification protocols across dairy processing chains.
Growth Catalysts
- Lactose-free dairy expansion:Industrial dairy processors in the United States are retrofitting enzymatic hydrolysis lines to capture consumer intolerance-driven demand, pulling beta-galactosidase volumes upward.
- REACH substance registration:European enzyme suppliers completing exhaustive safety dossiers under ECHA mandates are securing preferential access to EU pharmaceutical formulation contracts.
- Biopharmaceutical enzyme replacement:Recombinant galactosidase manufacturing for Fabry disease and GM1-gangliosidosis therapies is accelerating strain development investments across contract development organizations.
Market Restraints
- Fermentation input volatility:Corn steep liquor and yeast extract price swings compress margin predictability for bulk enzyme manufacturers operating at industrial scale.
- Supplier concentration risk:Recombinant strain IP and high-purity downstream processing capability cluster with a limited cohort of European and North American specialist producers.
- Thermal stability limitations:Native fungal beta-galactosidase formulations require refrigerated transport and storage, elevating logistics costs for liquid concentrate distribution.
Strategic Opportunities
- Plant-based dairy analogues:Enzymatic galacto-oligosaccharide modification for oat and pea protein beverages opens formulation service contracts with alternative dairy startups.
- China GB standard alignment:SAMR food-grade enzyme activity thresholds create first-mover advantages for foreign suppliers achieving dual FDA-GB certification.
- Continuous flow biocatalysis:Immobilized enzyme reactor technology convergence with process analytical technology is enabling real-time lactose conversion monitoring in automated dairy lines.
Industry Challenges
- Recombinant strain development talent scarcity:Molecular biology and fermentation science specialists with mammalian cell culture expertise command premium compensation, constraining in-house platform expansion.
- FSSC 22000 certification timelines:Multinational food manufacturers require 12-18 month supplier qualification cycles, delaying revenue recognition for new market entrants.
- Legacy powder-to-liquid format migration:Dairy processors with established dry-blending infrastructure face capital expenditure burdens to adopt automated liquid dosing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Galactosidase Market |
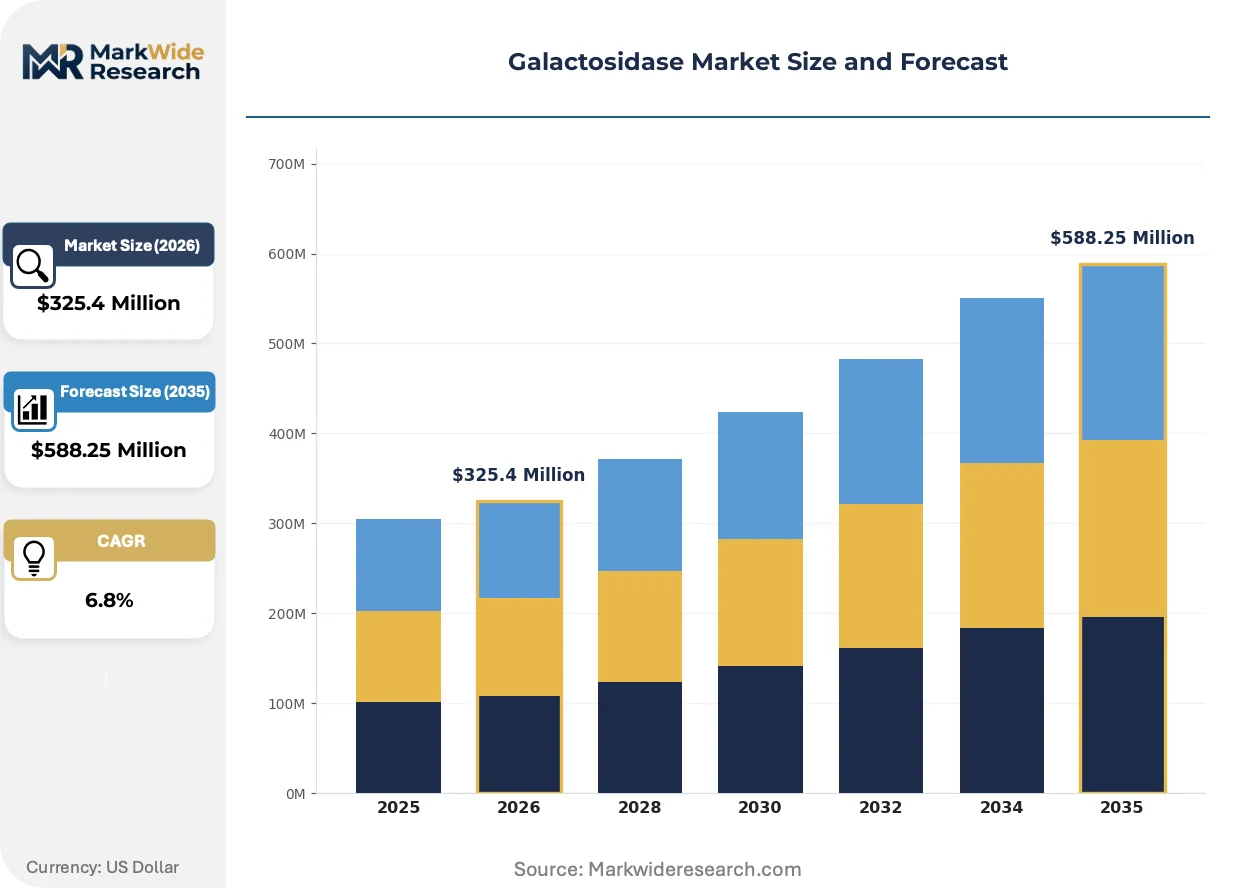
| Market Size in 2026 | $325.4 Million |
| Market Size in 2035 | $588.25 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alpha-Galactosidase, Beta-Galactosidase, Enzyme Formulations, Recombinant Galactosidase Application: Food Industry, Pharmaceutical, Diagnostic Kits, Nutritional Supplements Delivery Mode: Liquid Form, Powder Form, Tablet, Capsules End User: Hospitals, Research Laboratories, Dietary Centers, Biotechnology Firms |
| Companies Covered | Advanced Enzymes Technologies, Chr. Hansen Holding, Novozymes, Codexis, Merck KGaA, DuPont de Nemours, Amano Enzyme, Zhongnuo BioTech, DSM Nutritional Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Galactosidase Market Emerging Trajectories
Enzyme engineering and process intensification are converging to reshape competitive positioning across pharmaceutical and food-grade galactosidase supply tiers.
Cell-free enzyme synthesis utilizing in vitro transcription-translation systems is overtaking traditional microbial fermentation for small-batch therapeutic enzyme production. Biopharmaceutical contract manufacturers in Switzerland and Massachusetts are adopting these platforms to compress development timelines for orphan disease therapies. The technology is overtaking incumbent methods by eliminating strain stability concerns and enabling rapid formulation iteration.
EMA guidance on enzyme replacement therapy immunogenicity monitoring is tightening post-market surveillance requirements for pharmaceutical-grade suppliers. Manufacturers must now maintain extended patient registry data and batch-specific antibody response tracking. European biologics producers are responding by integrating quality-by-design principles deeper into upstream strain development protocols.
Direct enzyme procurement from specialized manufacturers is displacing traditional distributor intermediaries in large-scale dairy processing. Major cooperatives in Wisconsin and Bavaria are negotiating multi-year supply agreements with locked activity specifications and technical service bundling. This pattern is most visible in the United States where processor consolidation has concentrated buying power among fewer procurement decision-makers.
Galactosidase Market Segmentation
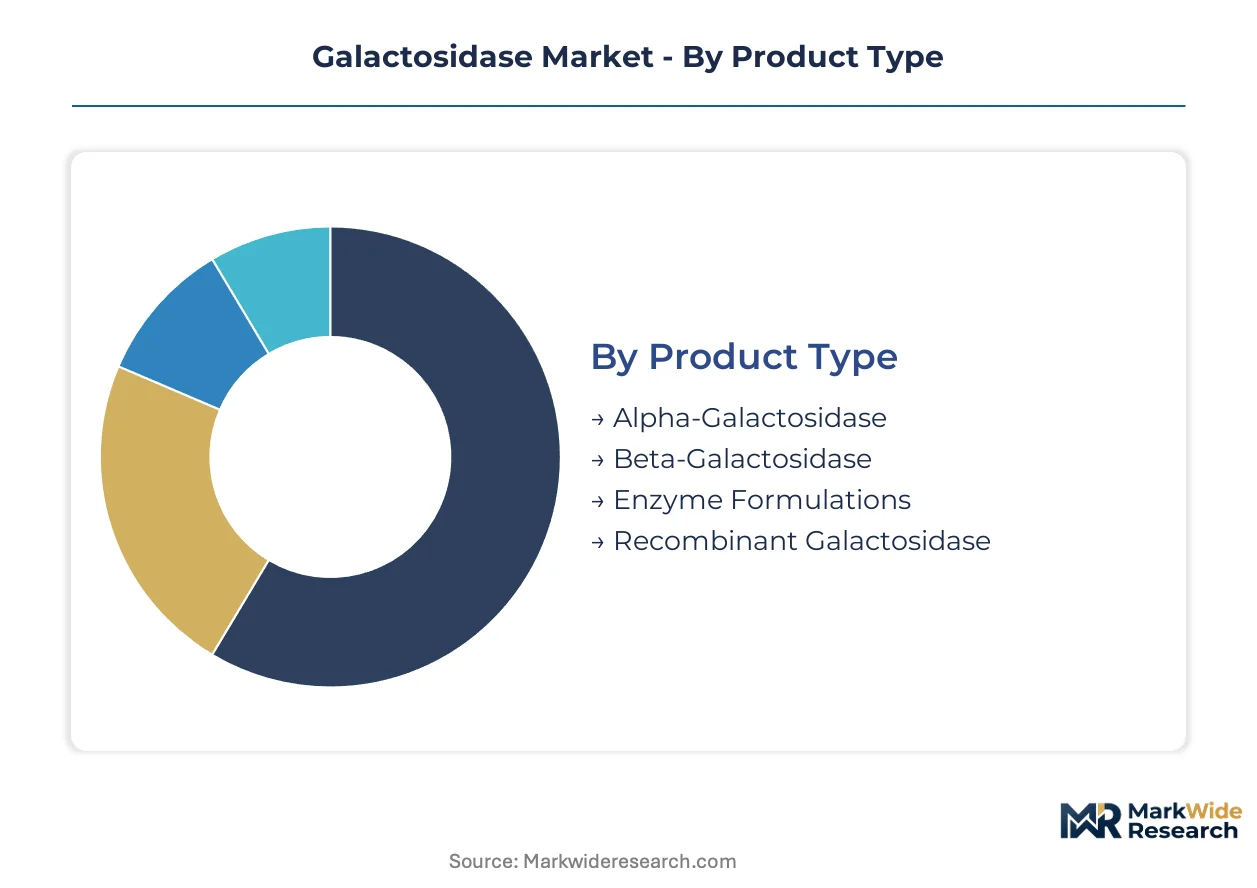
Galactosidase procurement patterns diverge sharply across product grades and delivery formats. Supply-side concentration in recombinant production and pharmaceutical-grade purification creates tiered qualification barriers that reshape competitive access.
Product Type:
Supply concentration clusters with recombinant strain developers holding mammalian cell culture platforms and multi-step chromatography capabilities.
- Beta-Galactosidase:Fungal and yeast-derived formulations dominate dairy hydrolysis applications with activity specifications between 2,000 and 10,000 ALU per gram. Demand concentrates in Wisconsin and Bavaria dairy cooperatives retrofitting enzymatic processing lines for lactose-free milk production.
- Recombinant Galactosidase:CHO-cell and HEK293-derived enzymes achieve >99% purity for enzyme replacement therapy through protein A/G affinity chromatography and endotoxin removal. Biopharmaceutical contract manufacturers in Massachusetts and Switzerland drive procurement as Fabry disease and GM1-gangliosidosis therapeutic pipelines expand.
- Alpha-Galactosidase:Legume processing and flatulence-reduction supplements utilize Aspergillus niger-sourced preparations.
- Enzyme Formulations:Blended preparations combine galactosidase with proteases for multi-enzyme dairy processing.
Today's leader: Beta-Galactosidase. Tomorrow's challenger: Recombinant Galactosidase.
Application:
Cost tier separation emerges between commodity food-grade enzymes and premium pharmaceutical-grade therapeutics with 10-20x price multiples.
- Food Industry:Lactose-free dairy production consumes bulk beta-galactosidase at industrial scale, with processors demanding 50,000+ kg annual volumes and locked activity specifications. United States dairy cooperatives negotiate multi-year technical service bundles with direct manufacturer procurement displacing traditional distributors.
- Pharmaceutical:Enzyme replacement therapy for lysosomal storage disorders requires FDA drug master files and EMA marketing authorization with immunogenicity monitoring protocols. Swissmedic and Health Canada approvals follow EMA reference procedures for orphan disease indications.
- Diagnostic Kits:ELISA and enzymatic assay applications utilize purified galactosidase conjugates.
- Nutritional Supplements:Over-the-counter digestive aids incorporate fungal-derived alpha-galactosidase for legume consumption support.
Food Industry commands volume leadership. Pharmaceutical captures margin supremacy.
Delivery Mode:
Volume concentration in automated dairy processing drives format migration from legacy powder toward liquid concentrate dosing systems.
- Liquid Form:Standardized concentrates at 100,000-500,000 ALU per milliliter enable automated inline dosing with real-time process analytical technology monitoring. Dairy processors with continuous flow biocatalysis infrastructure in Denmark and the Netherlands prefer refrigerated tanker delivery with 4°C cold chain maintenance.
- Powder Form:Spray-dried preparations retain cost advantages in bulk procurement and extended ambient storage stability. Asian enzyme traders and smaller dairy processors without liquid handling infrastructure sustain demand.
- Tablet:Fixed-dose galactosidase for dietary supplement retail channels.
- Capsules:Enteric-coated formulations for intestinal release in nutritional applications.
Liquid Form gains share in industrial procurement. Powder Form defends position in emerging market bulk purchasing.
End User:
Customer type stratification separates multinational food manufacturers with FSSC 22000 supplier qualification from research-scale purchasers with flexible sourcing.
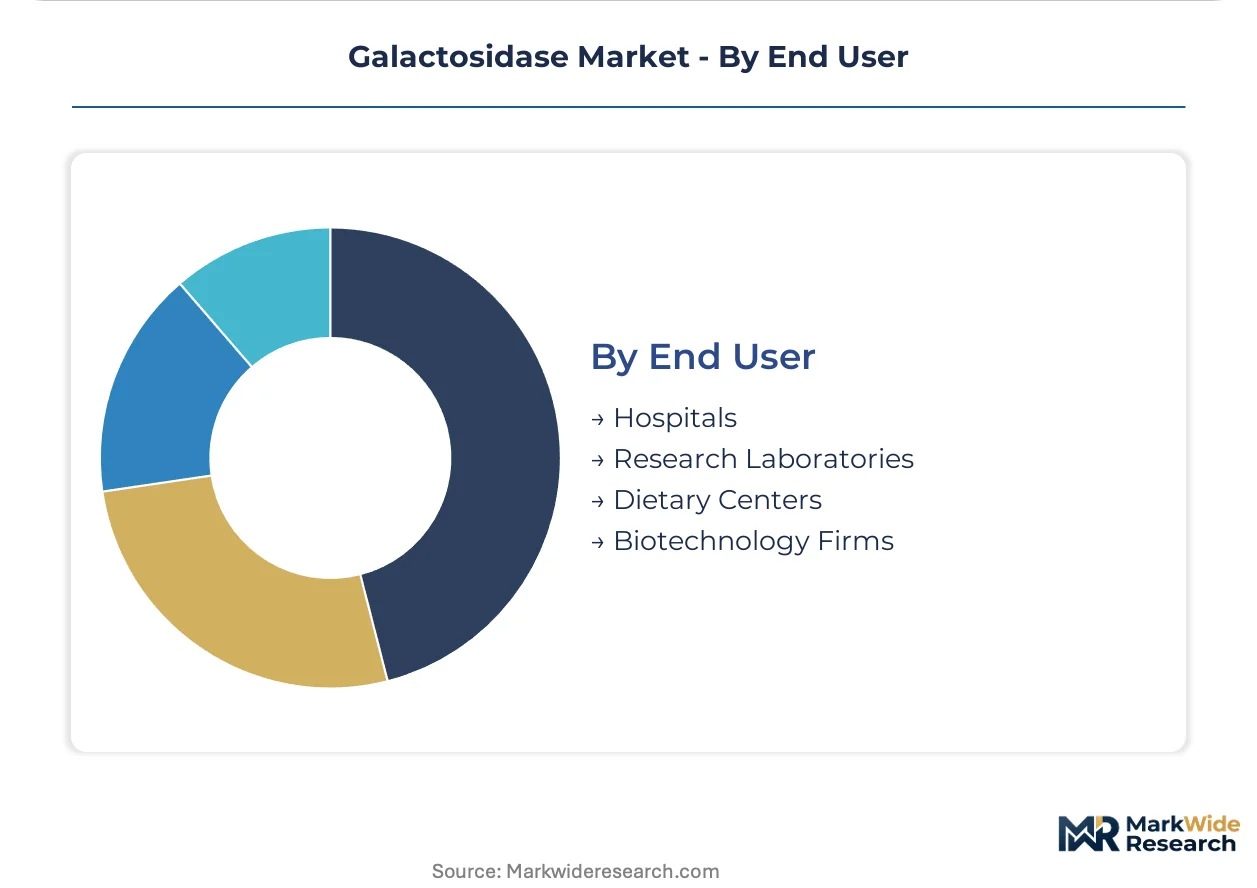
- Biotechnology Firms:Contract development organizations in Cambridge, Massachusetts and Basel, Switzerland procure research-grade and GMP-grade recombinant galactosidase for therapeutic strain development and clinical manufacturing. These firms demand batch-specific certificates of analysis with residual DNA and host cell protein documentation.
- Hospitals:Compounding pharmacies and specialty infusion centers administer FDA-approved enzyme replacement therapies with cold chain distribution through specialty pharmacy networks.
- Research Laboratories:Academic and government institutes purchase small-batch enzymes for glycobiology and carbohydrate chemistry studies.
- Dietary Centers:Clinical nutrition services prescribe alpha-galactosidase supplements for irritable bowel syndrome management.
Biotechnology Firms drive innovation premium. Hospitals anchor therapeutic value capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial enzyme production originated in European fermentation centers during the mid-twentieth century before expanding to North American biotechnology clusters and Asian manufacturing hubs. Today's galactosidase procurement patterns reflect this geographic diffusion across three continents.
United States
Wisconsin dairy cooperatives and Massachusetts biopharmaceutical contract manufacturers drive specialized enzyme sourcing. FDA GRAS notifications and drug master file requirements govern food-contact and therapeutic-grade supply. Greater Boston anchors recombinant strain development for Fabry disease therapies.
Germany
Bavaria's dairy processing industry retrofits enzymatic hydrolysis lines for lactose-free milk production. ECHA REACH substance registration mandates exhaustive safety dossiers for enzyme formulations. The Rhine-Main biotechnology corridor concentrates pharmaceutical-grade purification capabilities.
China
Domestic dairy processors expand lactose-free product lines while SAMR enforces GB standards on enzyme activity thresholds. NMPA oversight extends to recombinant production methods for therapeutic applications. Yangtze River Delta fermentation facilities scale bulk enzyme manufacturing.
Switzerland
Swissmedic approvals for enzyme replacement therapies follow EMA reference procedures for orphan disease indications. Basel-based contract development organizations procure GMP-grade recombinant galactosidase. The country's precision manufacturing heritage supports multi-step chromatography specialization.
Netherlands
Dairy processors with continuous flow biocatalysis infrastructure prefer refrigerated liquid concentrate delivery. FSSC 22000 certifications function as baseline qualifiers for multinational food manufacturer supply. Randstad logistics networks enable cold chain distribution across northwestern Europe.
Galactosidase Market Vendor Landscape
The competitive structure tilts toward recombinant production specialists with mammalian cell culture platforms. European and North American suppliers dominate pharmaceutical-grade purification tiers while Asian manufacturers compete on bulk fermentation scale. Three archetypes define the field: integrated biotechnology conglomerates with diversified enzyme portfolios, dedicated fermentation specialists with deep dairy-application expertise, and contract development organizations with therapeutic-grade GMP capabilities. Capacity expansion in recombinant strain development and strategic partnerships for automated dairy processing technology represent dominant competitive moves.
Among European biotechnology leaders, Novozymes and Chr. Hansen Holding exemplify divergent specialization strategies within the enzyme supply ecosystem. Novozymes occupies a position as a diversified fermentation powerhouse with recombinant platform breadth, while Chr. Hansen Holding represents focused dairy-application expertise. Advanced Enzymes Technologies anchors the Asian competitive vector as a scale-driven manufacturer serving bulk industrial procurement across food-grade segments.
| Leading Market Players |
|---|
| Advanced Enzymes Technologies |
| Chr. Hansen Holding |
| Novozymes |
| Codexis |
| Merck KGaA |
| DuPont de Nemours |
| Amano Enzyme |
| Zhongnuo BioTech |
| DSM Nutritional Products |
| Others |
Supply Flow & Price Mechanics
Recombinant production platform maturation simultaneously compresses manufacturing cost curves for pharmaceutical-grade galactosidase and concentrates supply power among mammalian cell culture specialists with multi-step chromatography capabilities. This technological transition rewards early movers with locked-in pricing advantages while fragmenting bargaining power across food-grade beta-galactosidase procurement tiers.
Pricing Analysis
Bundled technical service contracts with multi-year activity specifications command premium positioning against unbundled spot-market enzyme transactions. Three-tier pricing structure across GMP-certified therapeutic, food-grade certified, and bulk industrial grades reflects FDA drug master file investment recovery and FSSC 22000 compliance cost amortization. Pricing pressure stems from corn steep liquor and yeast extract input volatility squeezing fermentation margin predictability. Contract dairy cooperatives in Wisconsin exhibit lowest price sensitivity due to locked technical service dependencies, while Asian bulk traders face acute cost compression.
Supply Chain Analysis
China's GB standards for food-grade enzyme activity thresholds and microbial contamination limits are reshaping sourcing patterns toward dual-certified suppliers with simultaneous FDA and SAMR compliance. Manufacturing gravity centers on Denmark, the Netherlands, and Massachusetts for recombinant therapeutic production, with Yangtze River Delta facilities scaling bulk fermentation. Corn steep liquor, yeast extract, and protein A/G affinity chromatography resins constitute critical input dependencies. Single-source vulnerability clusters with mammalian cell culture platform operators. Distribution runs through refrigerated tanker networks for liquid concentrates and ambient freight for spray-dried powders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The galactosidase market functions as a regulatory compounder where EMA guidance on enzyme replacement therapy immunogenicity monitoring is tightening qualification barriers and accelerating demand for quality-by-design manufacturing capabilities.
For Market Incumbents: Lock in multi-year supply agreements with Wisconsin and Bavaria dairy cooperatives before automated liquid dosing infrastructure investments harden supplier switching costs. Defend against cell-free enzyme synthesis platforms by deepening mammalian cell culture talent retention and accelerating CHO-cell strain development cycles. Prioritize backward integration into recombinant strain IP to offset contract development organization margin compression. For New Entrants and Emerging Players: Capture formulation service contracts with oat and pea protein beverage startups seeking galacto-oligosaccharide modification expertise for plant-based dairy analogues. Penetrate the China market through dual FDA-GB certification achievement ahead of SAMR enforcement intensification. Deploy continuous flow biocatalysis technology partnerships as the primary go-to-market wedge against legacy powder-format incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among Asian bulk fermentation specialists lacking recombinant therapeutic capabilities but possessing scalable infrastructure. Long-term viability favors contract development organizations with GMP-grade purification assets serving orphan disease pipelines. Watch EMA post-market surveillance requirement expansion as the signal for accelerated quality-by-design investment mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Strain Development Investment | CHO-cell platform expansion secures Fabry disease therapy supply contracts with Massachusetts biopharmaceutical manufacturers. |
| Dual Certification Achievement | Simultaneous FDA GRAS notification and SAMR GB standard compliance unlocks China dairy processor procurement channels. |
| Continuous Flow Biocatalysis Adoption | Immobilized enzyme reactor integration with process analytical technology enables real-time lactose conversion monitoring for Dutch dairy cooperatives. |
| Cell-Free Synthesis Platform Migration | In vitro transcription-translation systems compress development timelines for Swiss biopharmaceutical orphan disease therapy manufacturing. |
| Technical Service Bundling | Multi-year locked activity specifications with Wisconsin dairy processors displace traditional distributor intermediaries in direct procurement relationships. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with fermentation science directors, dairy processor procurement leads, biopharmaceutical regulatory affairs specialists, and contract development organization executives with secondary validation against FDA GRAS notifications, EMA marketing authorization filings, SAMR GB standards documentation, and customs trade data. Bottom-up enzyme volume modeling triangulates against top-down market sizing across pharmaceutical and food-grade application tiers.
Rate-of-change decomposition separates volume expansion from price evolution across beta-galactosidase, recombinant galactosidase, and alpha-galactosidase product segments, with application splits across food industry, pharmaceutical, diagnostic, and nutritional supplement end uses. Modeled dimensions include delivery format migration from powder to liquid concentrate, certification tier stratification, and regional regulatory cluster differentiation. CAGRs derive from enzyme activity demand forecasting tied to lactose-free dairy production line retrofit cycles and enzyme replacement therapy patient population growth trajectories.
Regulatory pathway delays, recombinant strain development timeline extensions, and fermentation input cost volatility constitute the dominant revision risks to modeled outputs. Forecasts embed assumptions around EMA immunogenicity guidance implementation pace and China GB standard enforcement intensity. A concentrated watch list covering SAMR audit frequency acceleration and REACH substance registration completion rates warrants ongoing monitoring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Microbiology
Global Microbial Products Market
Industrial Microbiology
Europe Microbial Based Biological Seed Treatment Market
Industrial Microbiology
B-Glucuronidase Enzymes Market
Industrial Microbiology
Global Microbial Testing Market
Industrial Microbiology
Microbiology Testing Market
Industrial Microbiology
Lipase Market
Industrial Microbiology
Global Arabinogalactan Market
Industrial Microbiology
Microbiology Culture Market
Industrial Microbiology
Microbial Protein Used in Feed Market
Industrial Microbiology
Global Microbial Fermentation Technology Market
Industrial Microbiology
Mesophilic Bacteria Market
Industrial Microbiology
Bacterial Antigens Market
Industrial Microbiology
Automated Microbiology Market
Industrial Microbiology
Microbial Therapeutic Products Market
Industrial Microbiology
Antibiotic Resistance Market
Industrial Microbiology
Global Bacterial Cell Culture Market