
 Industrial I/O Modules Market | 2026-2036
Industrial I/O Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial I/O Modules Market Outlook
Germany is reconfiguring its industrial automation supply base as manufacturers localize I/O module production to reduce lead times. Siemens AG leverages deep vertical integration across PLC and I/O portfolios to dominate European project specifications. Rockwell Automation Inc anchors North American process industries with tightly coupled control-I/O architectures. Phoenix Contact GmbH and Co KG specializes in ruggedized fieldbus termination and signal conditioning modules for harsh-environment deployments.
Industrial I/O modules are signal conversion and conditioning devices that bridge field-level sensors and actuators to programmable logic controllers or distributed control systems, typically handling voltage ranges of 0-10V or 4-20mA with isolation ratings up to 2.5kV. Their primary purpose is to standardize disparate electrical signals into digital process data while protecting upstream control hardware from electrical faults and ground loops. Digital I/O modules occupy the highest volume tier due to their ubiquity in discrete manufacturing, though specialty I/O modules for safety instrumented systems command the strongest margin pools. Ethernet-based technology segments are displacing legacy fieldbus installations as time-sensitive networking protocols mature, while process control applications sustain the longest replacement cycles because of certification lock-in.
The EU's F-Gas Regulation and Machinery Directive (MDR) are tightening material and functional safety requirements for modules deployed in refrigeration and heavy machinery systems. OSHA electrical safety standards in the United States mandate arc-fault protection that increasingly integrates at the I/O level rather than through external relays. China's GB standards for electromagnetic compatibility are raising compliance costs for imported modules while creating protected market access for domestic suppliers. Stakeholders must monitor convergence between functional safety certifications and cybersecurity frameworks as IT-OT integration accelerates module vulnerability exposure.
Market Dynamics
Ethernet-based I/O architectures are virtualizing signal processing layers, collapsing the traditional separation between field devices and control systems while forcing legacy fieldbus infrastructure into accelerated replacement cycles across automotive and process manufacturing installations.
Growth Catalysts
- EU Green Deal industrial decarbonization mandates:Energy-monitoring I/O architectures face compulsory upgrades as carbon accounting requirements tighten for manufacturing facilities across Germany's Ruhr industrial cluster.
- Automotive EV production retooling:Assembly line reconfiguration demands high-density digital I/O modules capable of rapid reconfiguration for mixed-model electric vehicle manufacturing.
- Time-sensitive networking protocol maturation:IEEE 802.1AS synchronization standards enable deterministic Ethernet I/O replacements for legacy Profibus and DeviceNet installations in discrete automation.
Market Restraints
- Semiconductor component concentration:Isolation amplifiers and ADC chipsets rely on concentrated Asian foundry capacity, exposing module lead times to single-source wafer fabrication bottlenecks.
- Functional safety certification lock-in:SIL-rated process control modules face extended recertification timelines under IEC 61508, freezing incumbent architectures in place despite superior alternatives.
- Copper and rare earth magnet price volatility:Terminal block assemblies and isolation transformers absorb commodity swings that module manufacturers struggle to pass through on fixed project contracts.
Strategic Opportunities
- IT-OT cybersecurity convergence:IEC 62443-compliant I/O modules with embedded security stacks capture premium positioning as zero-trust architectures penetrate manufacturing networks.
- Edge computing integration:I/O modules with onboard preprocessing capabilities address latency-critical predictive maintenance applications in wind turbine and semiconductor fabrication deployments.
- India PLI scheme for industrial automation:Domestic manufacturing incentives create localized assembly opportunities for cost-optimized I/O families serving South Asian infrastructure buildouts.
Industry Challenges
- Embedded systems cybersecurity expertise scarcity:Module vendors struggle to recruit firmware engineers capable of implementing secure boot and encrypted fieldbus protocols.
- Legacy system integration complexity:Brownfield installations require protocol gateway layers that increase point-of-failure risk and commissioning duration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial I/O Modules Market |
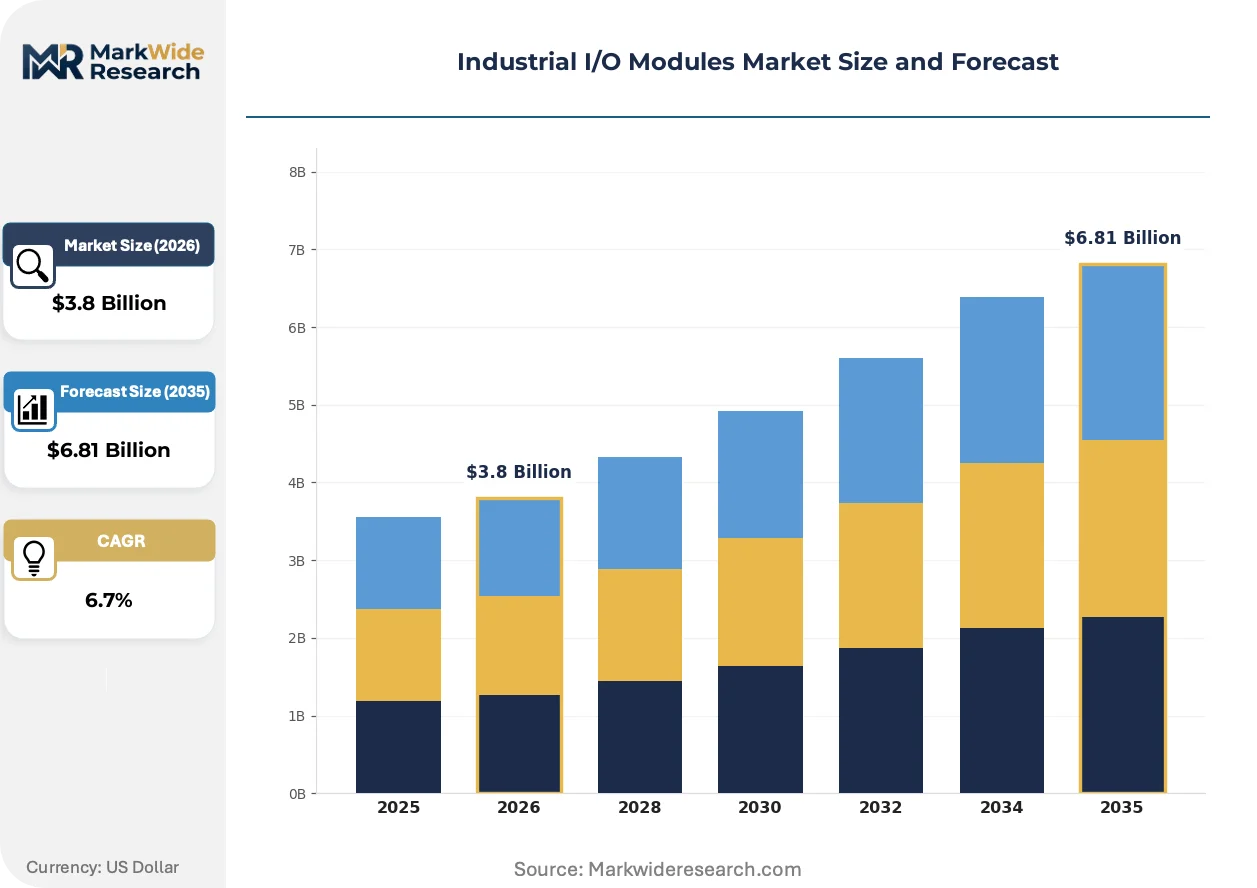
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog I/O, Digital I/O, Relay I/O, Specialty I/O End User: Manufacturing, Oil & Gas, Automotive, Food & Beverage Technology: Fieldbus, Ethernet, Serial Communication, Wireless Application: Process Control, Automation Systems, Environmental Monitoring, Machine Safety |
| Companies Covered | Siemens AG, ABB Ltd, Rockwell Automation Inc, Schneider Electric SE, Emerson Electric Co, Mitsubishi Electric Corporation, OMRON Corporation, Advantech Co Ltd, Phoenix Contact GmbH and Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial I/O Modules Market Strategic Shifts
Software-defined I/O is dissolving hardware boundaries between analog, digital, and specialty signal types, enabling runtime-reconfigurable modules that adapt to changing sensor payloads without physical replacement.
Time-sensitive networking hardware is virtualizing deterministic communication stacks previously implemented in dedicated ASICs. Automotive powertrain test stands and semiconductor lithography equipment adopt TSN-enabled I/O modules to consolidate motion control and safety signals onto unified Ethernet cabling. This virtualization is compressing the traditional three-tier automation hierarchy into flatter architectures with reduced gateway hardware.
The EU Machinery Directive's 2023 recast tightens functional safety documentation requirements for I/O modules deployed in collaborative robot workcells. Manufacturers must now provide structured safety function specifications and failure mode analyses as standardized machine-readable files. Safety I/O module suppliers serving German automotive OEMs have reorganized engineering workflows to generate compliant technical files concurrent with hardware development.
System integrators and end-users increasingly specify I/O modules through consolidated procurement frameworks rather than discrete component purchasing. Large German automotive groups and North American chemical processors negotiate enterprise-wide supply agreements that bundle I/O, cabling, and engineering services. This bundling is marginalizing traditional distribution channels in favor of direct vendor relationships with volume commitment tiers.
Industrial I/O Modules Market Segmentation
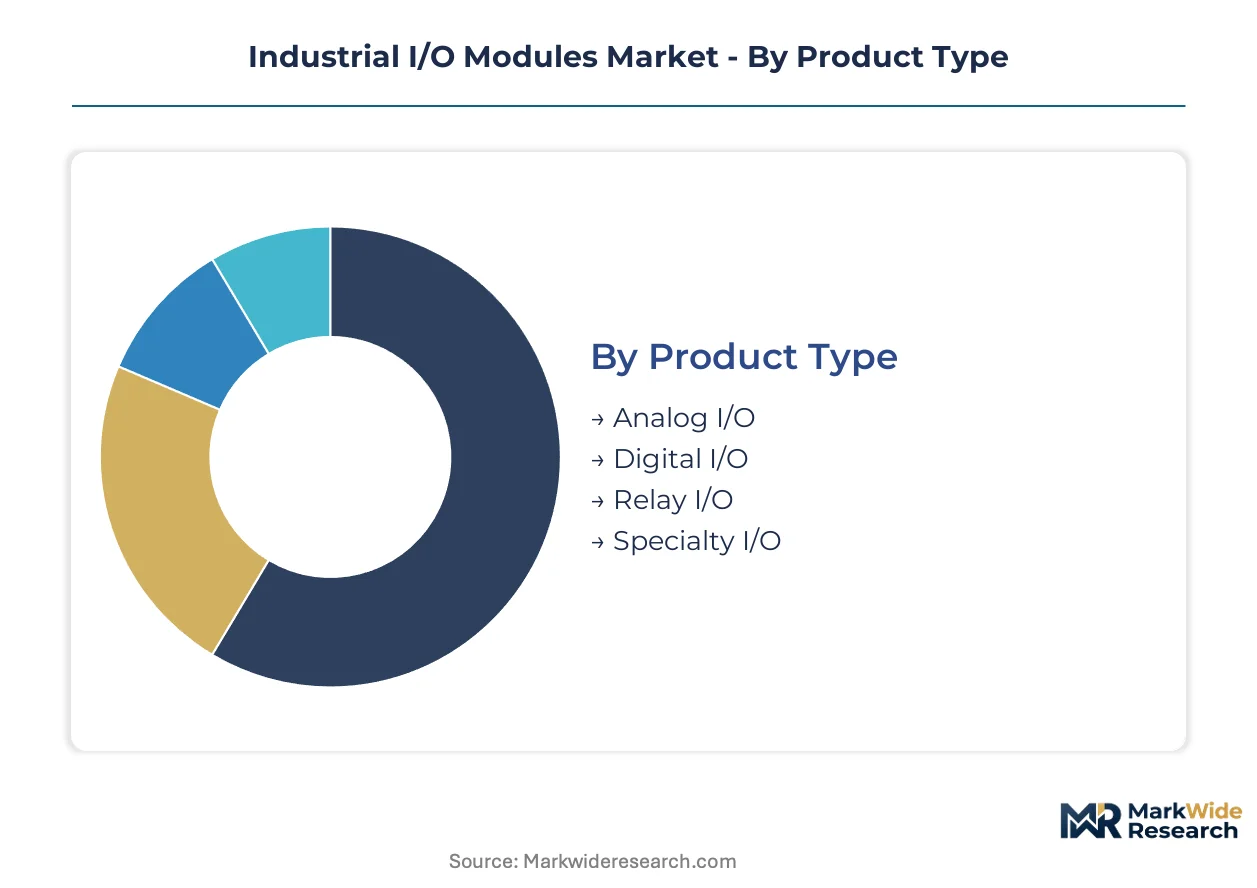
Industrial I/O module procurement patterns diverge sharply across signal types and communication protocols. Discrete manufacturing favors high-channel-density digital configurations, while process industries sustain premium analog architectures. Technology choices increasingly determine total system cost as Ethernet-based architectures collapse traditional gateway layers.
Product Type:
Cost tier differentiation separates commodity digital modules from precision analog and safety-certified specialty variants.
- Digital I/O:High-density transistor and relay output modules handle 24V DC switching signals for discrete manufacturing. Automotive EV retooling in Germany's Ruhr cluster drives demand for reconfigurable digital blocks capable of rapid line changeovers. Channel counts per module continue climbing as semiconductor integration reduces per-point costs.
- Analog I/O:Voltage (0-10V) and current (4-20mA) conversion modules with 16-bit resolution serve continuous process variables. Oil & Gas flow measurement applications in North American shale basins sustain demand for isolated analog inputs with HART protocol integration. Signal conditioning complexity preserves margin premiums against digital commoditization.
- Relay I/O:Electromechanical and solid-state relay modules provide galvanic isolation for high-voltage switching. Heavy machinery motor control applications dominate procurement volumes.
- Specialty I/O:SIL-rated safety modules and ex-certified intrinsically safe barriers address regulated hazardous environments. Functional safety certification timelines constrain supplier entry.
Digital I/O commands the established base. The steepest expansion runs through Specialty I/O as machinery safety mandates tighten.
End User:
Application intensity varies by sector capital expenditure cycles and regulatory compliance burdens.
- Manufacturing:Discrete assembly and packaging lines deploy mixed I/O configurations for material handling and quality inspection. EU Green Deal energy-monitoring mandates force architecture upgrades across German industrial clusters. Brownfield integration complexity favors vendors with legacy protocol gateways.
- Automotive:Powertrain test stands and body-in-white welding cells demand deterministic timing and high channel density. Mixed-model EV production lines require I/O modules supporting rapid tool changeover without rewiring. TSN-enabled Ethernet modules displace DeviceNet in new installations.
- Oil & Gas:Upstream wellhead monitoring and downstream refining sustain long replacement cycles. IEC 61508 certification lock-in protects incumbent suppliers.
- Food & Beverage:Hygienic washdown-rated modules with IP69K sealing address dairy and brewing applications. FDA-aligned material traceability requirements constrain supplier qualification.
Manufacturing anchors current procurement volumes. Automotive is gaining share fastest as electrification retooling accelerates module replacement cycles.
Technology:
Communication protocol maturity determines system architecture flexibility and lifecycle replacement timing.
- Ethernet:Industrial Ethernet with PROFINET, EtherNet/IP, and EtherCAT protocols consolidates control and I/O networks onto unified cabling. IEEE 802.1AS time-sensitive networking enables deterministic motion control previously requiring dedicated fieldbus. Semiconductor lithography equipment in South Korea and Japan adopts TSN-enabled modules for sub-millisecond synchronization.
- Fieldbus:Profibus DP, Foundation Fieldbus, and Modbus RTU installations persist in certified process control environments. Replacement cycles extend due to recertification costs and operator training investments.
- Serial Communication:RS-485 and RS-232 modules serve legacy device integration and cost-constrained remote terminal units. Modbus ASCII protocol support maintains relevance in building automation.
- Wireless:ISA100.11a and WirelessHART modules address rotating equipment monitoring and geographically dispersed assets. Battery life and cybersecurity certification limit deployment scope.
Fieldbus retains the installed base. Ethernet is climbing the fastest as TSN hardware virtualizes deterministic communication stacks.
Application:
Functional requirements dictate isolation ratings, response times, and certification tiers.
- Process Control:Continuous loop control demands analog I/O with high common-mode rejection and temperature stability. Chemical processors in the US Gulf Coast sustain demand for redundant analog input modules.
- Automation Systems:Discrete logic and motion control applications favor digital I/O with sub-millisecond response. Machine tool builders in Japan specify modules with synchronous sampling for multi-axis coordination.
- Environmental Monitoring:Distributed sensor networks for emissions and energy consumption tracking deploy low-power wireless I/O. EU carbon accounting regulations expand addressable market.
- Machine Safety:Safety instrumented systems require SIL 2/3 rated modules with diagnostic coverage and proof-test intervals. Collaborative robot workcells drive growth under recast EU Machinery Directive requirements.
Automation Systems represent the largest deployment category. Machine Safety is expanding most quickly as functional safety integration penetrates collaborative manufacturing environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor's freight rail density underwrites Germany's centrality to European industrial automation supply chains. Germany's Ruhr industrial cluster drives module replacement cycles as legacy factory modernization programs accelerate. The EU Green Deal's industrial decarbonization mandates force energy-monitoring I/O architecture upgrades across manufacturing facilities.
Germany
Automotive EV production retooling and legacy factory modernization dominate demand in the Ruhr industrial cluster. The EU Machinery Directive's 2023 recast tightens functional safety documentation requirements for collaborative robot workcells. Siemens AG leverages deep vertical integration across PLC and I/O portfolios to dominate European project specifications originating from Bavaria and Baden-Württemberg.
United States
OSHA electrical safety standards mandate arc-fault protection integration at the I/O level across process industries. North American chemical processors in the US Gulf Coast sustain demand for redundant analog input modules with IEC 61508 certification. Rockwell Automation Inc anchors regional process industries with tightly coupled control-I/O architectures deployed across Texas and Louisiana refining corridors.
China
GB standards for electromagnetic compatibility raise compliance costs for imported modules while creating protected market access for domestic suppliers. The country's dual carbon goals accelerate energy-monitoring I/O deployments in Yangtze River Delta manufacturing zones. Local suppliers capture share in building automation and infrastructure buildouts across Pearl River Delta industrial cities.
Japan
Machine tool builders specify modules with synchronous sampling for multi-axis coordination in Nagoya's Chubu manufacturing belt. METI industrial policy supports precision automation component development for semiconductor lithography equipment. TSN-enabled modules penetrate automotive powertrain test stands in Kanto region facilities.
India
The PLI scheme for industrial automation creates localized assembly opportunities for cost-optimized I/O families. Domestic manufacturing incentives attract module vendors to Maharashtra and Gujarat industrial corridors. South Asian infrastructure buildouts sustain procurement of serial communication modules for remote terminal units in power distribution networks.
Industrial I/O Modules Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower signal conditioning focus. The vendor base organizes around three strategic archetypes: diversified automation conglomerates with captive I/O portfolios, pure-play connectivity specialists, and embedded computing vendors extending into signal acquisition. Consolidation pressure concentrates among mid-scale European specialists facing Asian cost competition. Competitive moves center on strategic partnerships for TSN protocol stacks and geographic expansion into India PLI-subsidized manufacturing zones.
Among diversified automation conglomerates, Siemens AG and Rockwell Automation Inc exemplify platform-integrated positioning across control and I/O layers. Phoenix Contact GmbH and Co KG occupies the connectivity specialist tier with fieldbus termination and signal conditioning expertise. These three anchors represent divergent approaches to hardware-software bundling and vertical market penetration strategies.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Rockwell Automation Inc |
| Schneider Electric SE |
| Emerson Electric Co |
| Mitsubishi Electric Corporation |
| OMRON Corporation |
| Advantech Co Ltd |
| Phoenix Contact GmbH and Co KG |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Alpine Corridor's freight rail density shapes cost-to-serve differentials across European I/O module distribution, compressing margins for suppliers serving Germany's Ruhr cluster while amplifying price leverage for volume buyers negotiating enterprise-wide procurement frameworks. This logistics architecture concentrates supply-side power among vertically integrated automation conglomerates capable of absorbing transport cost volatility through captive manufacturing footprints.
Pricing Analysis
Volume-discount tiering structures separate premium SIL-certified safety modules from standard digital configurations and economy-grade serial communication units. Certification grade and channel density serve as the primary price differentiation drivers, with SIL 2/3-rated modules commanding substantial premiums over ungraded alternatives. Cost compression in the economy tier is intensifying because Chinese domestic suppliers exploit GB standards compliance to undercut imported equivalents on fixed project contracts. Process industry buyers exhibit the least price sensitivity due to recertification lock-in, while infrastructure contractors in South Asian markets demonstrate acute cost consciousness.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for isolation amplifier and ADC chipset sourcing. Semiconductor fabrication concentrates in Taiwan, South Korea, and mainland China, with module assembly drawing from German, Chinese, and Mexican production hubs. Copper terminal block assemblies and rare earth magnet cores for isolation transformers anchor raw material dependencies. Single-source wafer fabrication vulnerability threatens lead time stability. Distribution runs through direct vendor relationships with large automotive and chemical processors, marginalizing traditional industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial I/O module vendors increasingly monetize through cybersecurity certification services and predictive maintenance software subscriptions, recurring-revenue layers expanding faster than hardware unit sales as IT-OT convergence deepens customer dependency on vendor-managed security stacks.
For Market Incumbents: Harden firmware security architectures against IEC 62443 compliance gaps that emerging Asian competitors exploit through rapid certification cycling. Deepen backward integration into isolation amplifier semiconductor sourcing to neutralize Taiwanese foundry concentration risk. Prioritize captive production capacity in India PLI-subsidized zones to defend margin position against cost-optimized local entrants.
For New Entrants and Emerging Players: Pursue wireless I/O module white space in rotating equipment monitoring applications where battery life constraints have suppressed incumbent investment. Target India's Maharashtra and Gujarat industrial corridors for cost-optimized serial communication module assembly under domestic manufacturing incentives. Lead with ISA100.11a protocol expertise to differentiate against fieldbus-entrenched competitors.
For Investors and Strategic Acquirers: Edge-computing-enabled I/O specialists with onboard preprocessing capabilities represent the most defensible acquisition target archetype as latency-critical predictive maintenance applications expand. Long-term viability hinges on software-defined I/O roadmaps that virtualize hardware boundaries. Watch TSN protocol stack partnership announcements as inflection indicators for architectural consolidation winners.
| Strategic Initiative | Industry Significance |
|---|---|
| TSN Protocol Stack Partnership | IEEE 802.1AS synchronization enables deterministic Ethernet consolidation across automotive powertrain test stands. |
| Backward Integration into Semiconductor Sourcing | Captive isolation amplifier supply neutralizes Taiwanese foundry bottlenecks threatening module lead times. |
| IEC 62443 Security Certification Investment | Embedded security stacks capture premium positioning as zero-trust architectures penetrate manufacturing networks. |
| India PLI Manufacturing Localization | Domestic assembly incentives attract cost-optimized I/O families serving South Asian infrastructure buildouts. |
| Software-Defined I/O Platform Development | Runtime-reconfigurable modules adapt to changing sensor payloads without physical replacement cycles. |
Study Parameters
Desk research of customs trade databases, SEC 10-K automation segment disclosures, and EU Machinery Directive technical documentation preceded structured interviews with plant engineers at German automotive OEMs, procurement leads at North American chemical processors, aftermarket service heads at Japanese machine tool builders, and systems integrators specializing in brownfield modernization projects. Secondary validation drew from IEC certification registries, semiconductor foundry capacity reports, and industrial automation distributor transaction records. Bottom-up channel checks triangulated against top-down sector expenditure models.
Assumptions regarding EU Green Deal implementation timelines, automotive EV retooling completion rates, and TSN hardware adoption curves were held fixed across base-case scenarios while semiconductor supply disruption severity and copper price volatility were stress-tested through sensitivity bands. Segmentation modeling incorporated product type, communication protocol, end-use industry, and regional regulatory cluster dimensions. CAGRs were derived from installed base replacement cycle analysis and greenfield project pipeline tracking.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, central bank interest rate trajectories, or cross-border tariff regimes would shift the trajectory of module replacement demand. Forecasts reflect these documented assumptions and acknowledge that functional safety certification timeline extensions or cybersecurity standard fragmentation could materially revise expansion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
North America Industrial Centrifuge Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Global Pneumatic Actuators Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Europe Industrial Centrifuge Market
Industrial Equipment
Sterile Tubing Welder Market
Industrial Equipment
Laser Processing Market
Industrial Equipment
Electro-Pneumatic Systems Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Industrial Lasers Systems Market
Industrial Equipment
Spot Curing System Market
Industrial Equipment
Industrial Monitor Market
Industrial Equipment
Global Cryostat Market
Industrial Equipment
Asia Pacific Industrial Embedded Systems Market
Industrial Equipment
Europe Fans and Blowers Market
Industrial Equipment
Global Liquid Handling Systems Market