
 Sterile Tubing Welder Market | 2026-2036
Sterile Tubing Welder Market Size, Share, and Industry Trends Forecast 2026-2036
Sterile Tubing Welder Market Intelligence
Polypropylene is restructuring sterile tubing welder economics as manufacturers shift from PVC to meet extractables-and-leachables compliance. Sartorius AG leverages its single-use platform dominance to anchor high-volume bioprocessing accounts. Entegris sustains materials science leadership through fluoropolymer film integration. Terumo BCT competes on closed-system automation for blood component processing.
A sterile tubing welder is a precision thermal or ultrasonic joining device that fuses thermoplastic tubes in ISO 5 cleanroom conditions without compromising internal sterility, operating at temperatures between 200°C and 400°C depending on polymer grade. Bench-top welders occupy the highest installed base across fill-finish suites, while automated welders capture expanding share in continuous bioprocessing lines where operator intervention introduces contamination risk. Ultrasonic welding leads technology adoption for cell therapy applications demanding minimal heat exposure to preserve fluid integrity.
FDA 21 CFR Part 11, EU GMP Annex 1, and ISO 13485 shape validation protocols and equipment qualification burdens for sterile connection devices. These frameworks compel welder manufacturers to document seal-strength reproducibility and particulate generation limits before market authorization. Stakeholders must weigh laser welding R&D commitments against the installed base inertia of thermal platforms as gene therapy manufacturing scales beyond clinical volumes.
Market Dynamics
Single-use bioprocessing infrastructure is displacing stainless steel systems across biopharmaceutical manufacturing, forcing welder suppliers to validate thermal and ultrasonic platforms for polypropylene and fluoropolymer tubing compatibility at commercial scale.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates for aseptic processing equipment drive replacement cycles for legacy welders lacking audit-trail capabilities in US fill-finish facilities.
- Cell therapy manufacturing:Autologous and allogeneic production lines require closed-system sterile connections, expanding ultrasonic welder deployment for minimal heat-exposure fluid handling.
- EMA Annex 1 revisions:Stricter contamination control expectations for sterile medicinal products accelerate equipment upgrades across EU biologics contract manufacturing organizations.
Market Restraints
- Fluoropolymer resin concentration:Perfluoroalkoxy (PFA) supply concentrates among Japanese and US chemical producers, exposing welder manufacturers to input cost volatility and allocation constraints.
- Thermal platform inertia:Installed base of resistance-heating welders creates switching friction against laser alternatives despite superior seal consistency for high-value gene therapy fluids.
- ISO 13485 certification timelines:Equipment qualification documentation requirements extend new entrant market access by 18-24 months versus incumbent refresh cycles.
Strategic Opportunities
- China biologics capacity expansion:NMPA streamlined medical device registration creates first-mover positioning for welder suppliers validating local manufacturing partnerships.
- Continuous bioprocessing integration:Automated inline welding stations enable real-time media and buffer preparation, eliminating hold tanks in perfusion culture systems.
- EU Green Deal alignment:REACH restrictions on PVC plasticizers position polypropylene-compatible welders for sustainability-driven procurement criteria among European pharma operators.
Industry Challenges
- Cleanroom technician scarcity:ISO 5 operator certification requirements constrain deployment velocity for manual bench-top welders in expanding cell therapy facilities.
- Legacy SCADA integration:Brownfield bioprocessing suites require custom protocol bridging for new welder connectivity, complicating automated line retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterile Tubing Welder Market |
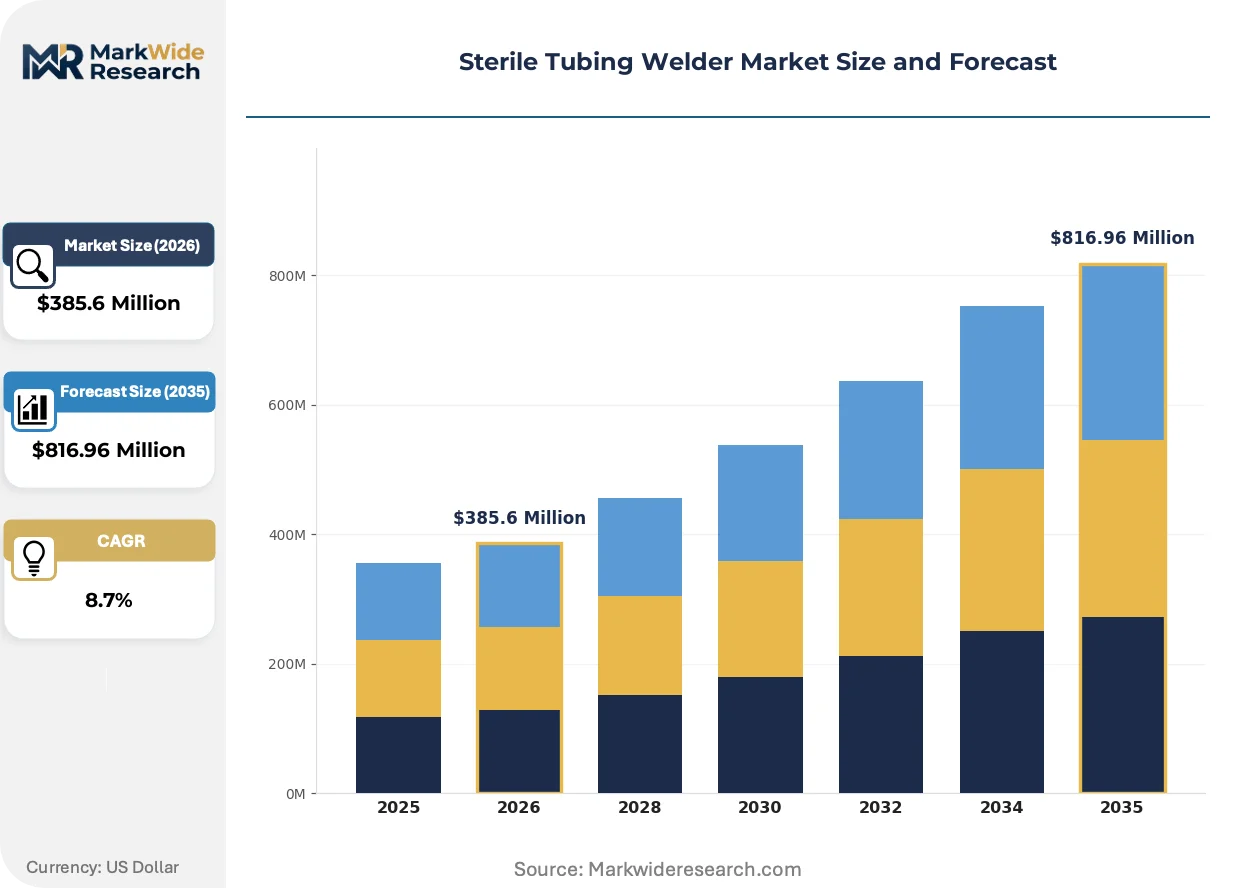
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench-top Welders, Portable Welders, Automated Welders, Handheld Welders Technology: Laser Welding, Ultrasonic Welding, Heat Welding, Radio Frequency Welding End User: Pharmaceutical Companies, Hospitals, Research Laboratories, Biotechnology Firms Application: IV Bag Production, Medical Device Manufacturing, Pharmaceutical Packaging, Sterility Testing |
| Companies Covered | Sartorius AG, Entegris, Terumo BCT, Cytiva, MGA Technologies, Vante/SEBRA, GE Healthcare, LePure, Genesis BPS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterile Tubing Welder Market Strategic Shifts & Innovations
Equipment architectures are converging around modularity and data integrity, with suppliers embedding sensor arrays and edge computing to support real-time process analytical technology in continuous manufacturing environments.
Laser welding systems are consolidating position in gene therapy applications where thermal damage risks compromise viral vector integrity. Gene therapy contract manufacturers in Massachusetts and North Carolina are piloting fiber-delivered diode laser platforms for 0.5-2.0 mm diameter tubing. This technology is consolidating high-value segment share by eliminating particulate generation associated with blade-based thermal methods.
EU MDR device classification expansions now capture sterile connection devices under higher scrutiny levels, compelling welder suppliers to strengthen clinical evidence packages for seal-integrity claims. German and Swiss notified bodies are demanding extended validation data for multi-material welding cycles. Cell therapy equipment buyers in the Netherlands and Belgium are prioritizing MDR-compliant suppliers in procurement specifications.
Service contracting is unbundling from equipment sales as biopharma operators seek predictable validation and maintenance costs. Tier-one CDMOs in California and Massachusetts are negotiating multi-year performance agreements covering seal-strength testing and preventive calibration. This shift compresses capital expenditure recognition while expanding recurring revenue pools for welder vendors with field service density in these clusters.
Sterile Tubing Welder Market Segmentation
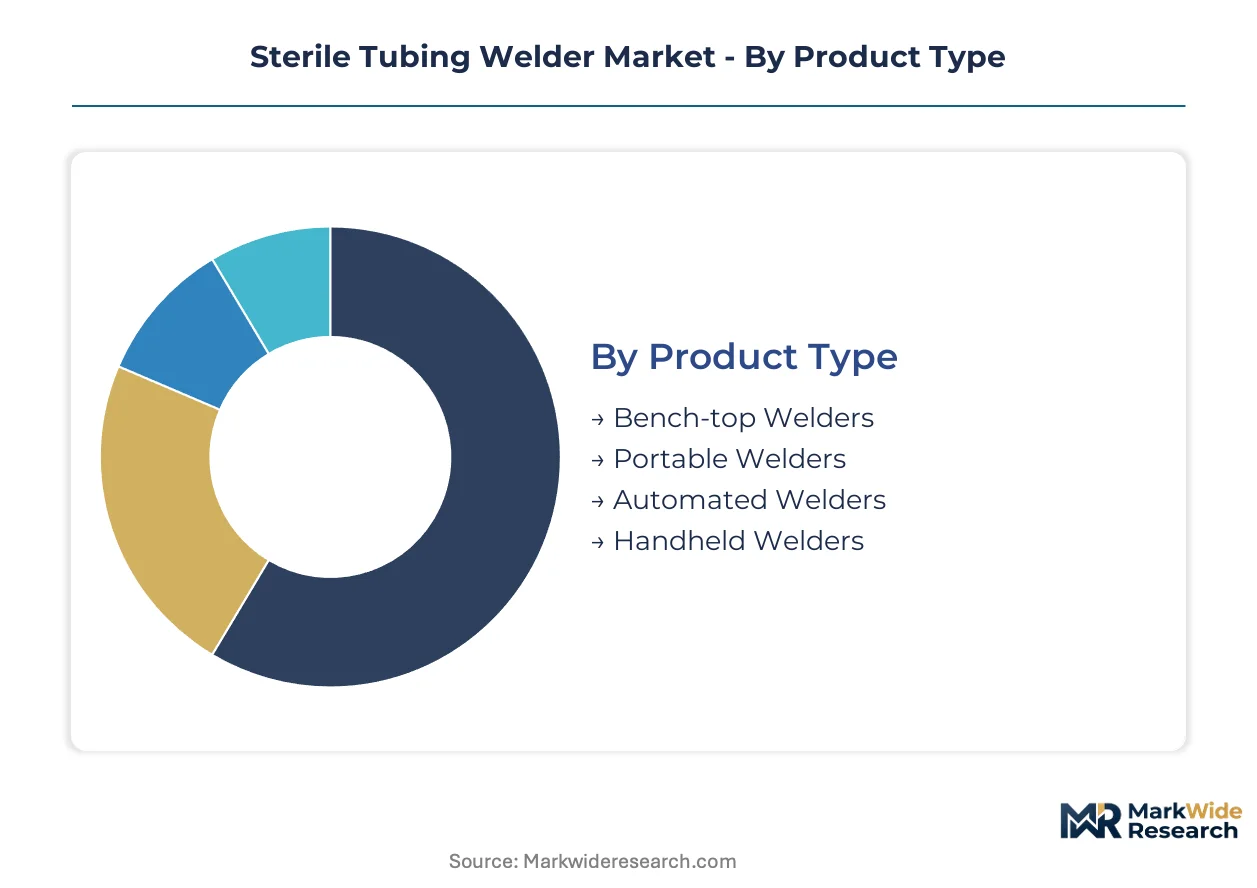
Sterile tubing welder procurement varies sharply by operational scale and contamination risk tolerance. Equipment specifications diverge across fill-finish suites, blood processing centers, and cell therapy cleanrooms, forcing suppliers to maintain parallel validation portfolios for thermal and ultrasonic platforms.
Product Type:
Replacement cycles accelerate as FDA 21 CFR Part 11 audit-trail mandates obsolete legacy units without electronic record capabilities.
- Bench-top Welders:Resistance-heating platforms dominate fill-finish suites for 1.6-3.2 mm diameter tubing. Demand clusters in Massachusetts and North Carolina gene therapy contract manufacturing facilities where operator-attended processing persists.
- Automated Welders:Robotic sealing stations integrate with SCADA systems for continuous bioprocessing lines. North Carolina and California perfusion culture facilities drive adoption to eliminate human-borne contamination in 24-hour operations.
- Portable Welders:Battery-powered units serve field blood collection and military medical applications.
- Handheld Welders:Compact devices address low-volume research settings and clinical trial material preparation.
Volume placements concentrate in bench-top welders; the faster expansion belongs to automated welders.
Technology:
Cost tiers separate validated production platforms from emerging alternatives still accumulating regulatory evidence packages.
- Ultrasonic Welding:Piezoelectric vibration generates frictional heat without blade contact, eliminating particulate generation. Cell therapy manufacturers in the Netherlands and Belgium specify ultrasonic platforms for minimal heat-exposure fluid handling of temperature-sensitive biologics.
- Laser Welding:Fiber-delivered diode systems achieve precise energy delivery for 0.5-2.0 mm fluoropolymer tubing. Massachusetts viral vector producers pilot these units to preserve adeno-associated virus integrity during sterile connection.
- Heat Welding:Resistance-heated blade methods retain the largest installed base across legacy bioprocessing infrastructure.
- Radio Frequency Welding:Dielectric heating suits specialized polymer matrices outside standard biopharmaceutical tubing grades.
Revenue concentrates in ultrasonic platforms; laser welding claims the steepest expansion trajectory as gene therapy manufacturing scales.
End User:
Customer type determines validation burden and service contract attachment rates.
- Biotechnology Firms:Venture-backed cell therapy developers in Cambridge and South San Francisco prioritize closed-system automation. These buyers negotiate multi-year performance agreements covering seal-strength testing and preventive calibration to preserve limited technical staff for core R&D functions.
- Pharmaceutical Companies:Large-cap biologics manufacturers in Germany and Switzerland specify MDR-compliant equipment with extended validation data for multi-material welding cycles.
- Hospitals:Blood bank and transfusion services in the United States deploy portable and bench-top units for component processing.
- Research Laboratories:Academic and government facilities operate lower-duty-cycle equipment with reduced documentation requirements.
Equipment density peaks in biotechnology firms; pharmaceutical companies generate the highest per-unit service revenue.
Application:
Application maturity dictates whether specifications emphasize throughput speed or sterility assurance level.
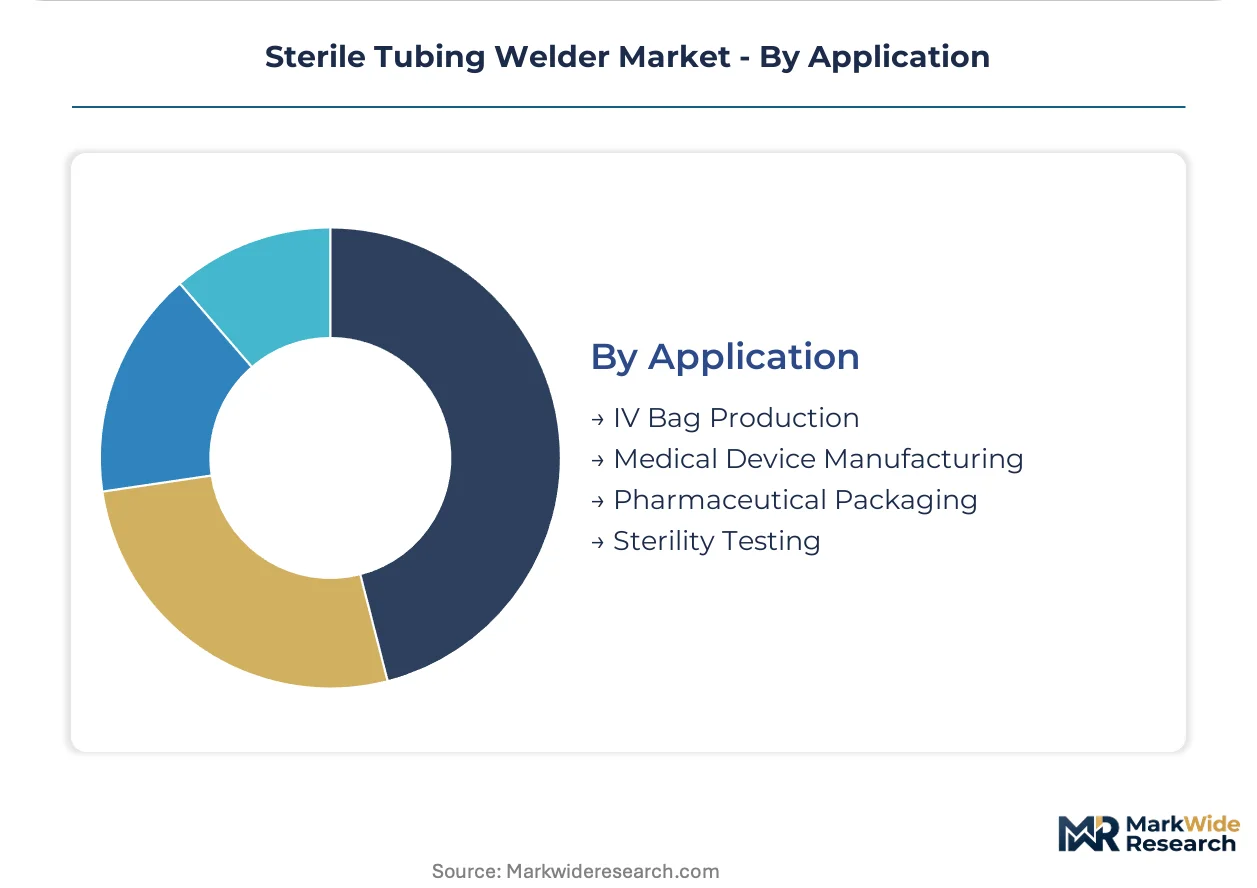
- Pharmaceutical Packaging:Vial and cartridge sealing operations in German fill-finish suites demand validated thermal platforms with documented seal-strength reproducibility. EMA Annex 1 contamination control revisions compel equipment upgrades across EU contract manufacturing organizations.
- Medical Device Manufacturing:Catheter and infusion set producers in Ireland and Costa Rica integrate inline welding stations for continuous production economics.
- IV Bag Production:High-volume polypropylene bag sealing retains established heat welding protocols.
- Sterility Testing:Quality control applications require documented particulate generation limits for regulatory submission support.
Deployment volume clusters in pharmaceutical packaging; medical device manufacturing posts the quickest share gains from reshoring initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturing clusters in the United States, Germany, and China concentrate sterile tubing welder procurement, with cell therapy production scaling and single-use infrastructure replacement driving equipment validation cycles across these three markets.
United States
FDA 21 CFR Part 11 electronic records mandates accelerate replacement cycles for legacy welders lacking audit-trail capabilities. Massachusetts viral vector producers and North Carolina perfusion culture facilities pilot fiber-delivered diode laser platforms for gene therapy applications. California contract manufacturing organizations negotiate multi-year performance agreements covering seal-strength testing.
Germany
EMA Annex 1 contamination control revisions compel equipment upgrades across biologics contract manufacturing organizations. EU MDR device classification expansions capture sterile connection devices under higher scrutiny levels, with notified bodies demanding extended validation data. German fill-finish suites in Bavaria and Baden-Württemberg specify MDR-compliant equipment with documented seal-strength reproducibility.
China
NMPA streamlined medical device registration creates first-mover positioning for welder suppliers validating local manufacturing partnerships. Yangtze River Delta biologics capacity expansion concentrates demand in Shanghai and Suzhou, where domestic and multinational producers scale cell therapy operations. The country's national pharmaceutical regulator tightens sterilization standards for aseptic connections.
Switzerland
Swissmedic oversight of sterile medicinal products drives qualification documentation requirements for multi-material welding cycles. Basel and Zurich anchor high-value bioprocessing accounts where large-cap biologics manufacturers prioritize closed-system automation. REACH restrictions on PVC plasticizers position polypropylene-compatible welders for sustainability-driven procurement criteria.
Netherlands
Cell therapy equipment buyers in Amsterdam and Rotterdam prioritize MDR-compliant suppliers in procurement specifications. Ultrasonic welding platforms capture share for minimal heat-exposure fluid handling of temperature-sensitive biologics. The country's national pharmaceutical regulator aligns with EMA Annex 1 revisions to accelerate equipment upgrade cycles.
Sterile Tubing Welder Market Key Industry Players
Strategic partnerships dominate the current landscape as suppliers align with single-use platform providers to secure high-volume bioprocessing accounts. The vendor base separates into three tiers: multinational conglomerates with integrated bioprocessing portfolios, specialized materials science firms with fluoropolymer expertise, and regional automation specialists. Two strategic archetypes define positioning: platform-anchored suppliers leveraging single-use ecosystem lock-in, and technology-focused competitors betting on laser welding differentiation. M&A activity and capacity expansion constitute the dominant competitive moves, with incumbents acquiring complementary validation capabilities and expanding field service density in Massachusetts-North Carolina-California clusters.
Among Germany-based platform-anchored suppliers, Sartorius AG exemplifies the single-use ecosystem integration archetype. Entegris occupies a position within the materials science leadership tier through its fluoropolymer film capabilities. Terumo BCT represents the closed-system automation specialist archetype, with its geographic origin in Japan reflecting Asia-Pacific bioprocessing infrastructure investments. These three anchors illustrate the competitive tension between platform breadth and technology depth.
| Leading Market Players |
|---|
| Sartorius AG |
| Entegris |
| Terumo BCT |
| Cytiva |
| MGA Technologies |
| Vante/SEBRA |
| GE Healthcare |
| LePure |
| Genesis BPS |
| Others |
Cost & Logistics Intelligence
Backward integration into fluoropolymer resin sourcing anchors supply security for welder manufacturers while insulating premium-tier pricing from raw material volatility. Japanese and US chemical producers concentrate PFA supply, compelling equipment makers to secure long-term offtake agreements or absorb cost pass-throughs that stratify pricing across customer tiers.
Pricing Analysis
High-volume bench-top welders trade on thin margins to capture fill-finish suite placements, while automated laser platforms command premium positioning for gene therapy applications. Three-tier pricing structure across premium, standard, and economy levels separates MDR-validated EU-compliant systems from legacy thermal units and research-grade handheld devices. Cost compression in the standard tier intensifies as Chinese domestic suppliers enter NMPA-registered competition. Biotechnology firms with venture funding cycles prove least price-sensitive; hospital blood banks exhibit highest bargaining leverage on replacement cycles.
Supply Chain Analysis
ISO 13485 certification timelines and FDA equipment qualification documentation create 18-24 month gating barriers that favor incumbent welder manufacturers with established quality management systems. Fluoropolymer resin concentrates among Japanese and US producers, while precision heating elements and piezoelectric transducers draw from German and Japanese component specialists. Single-source vulnerability runs through PFA allocation constraints during semiconductor industry demand spikes. Distribution runs through direct field service teams for automated platforms and authorized distributors for bench-top units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA 21 CFR Part 11 electronic records mandates and EU MDR device classification expansions erect cost-of-compliance barriers that protect validated incumbents while delaying new entrant market access. These regulatory moats concentrate pricing power among suppliers with pre-existing audit-trail capabilities and notified body relationships.
For Market Incumbents: Anchor platform-anchored positioning by deepening single-use ecosystem partnerships with bioprocessing suite providers and expanding field service density in Massachusetts-North Carolina-California clusters. Laser welding R&D commitments counter thermal platform inertia as gene therapy manufacturing scales beyond clinical volumes. Defensive patent filings on fiber-delivered diode configurations protect high-value segment share from emerging photonics specialists. For New Entrants and Emerging Players: Capture white-space opportunity in NMPA-registered equipment for Yangtze River Delta biologics capacity expansion, where streamlined medical device registration reduces incumbent headroom. Portable and handheld welders for military medical and field blood collection applications face lower validation documentation burdens than pharmaceutical-grade systems. Partnership routes through domestic Chinese distributors accelerate local manufacturing qualification timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in platform-anchored acquisitions by multinational bioprocessing conglomerates seeking single-use ecosystem completeness. Long-term viability favors suppliers with fluoropolymer materials science depth and automated welding station integration capabilities. Watch for inflection signals in gene therapy viral vector manufacturing scale-up announcements from Massachusetts and North Carolina contract manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Certification | EU notified body validation unlocks German and Swiss fill-finish suite procurement specifications. |
| Laser Welding R&D Investment | Fiber-delivered diode platforms capture gene therapy viral vector integrity requirements in Massachusetts. |
| China Manufacturing Partnership | NMPA-registered local production secures Yangtze River Delta biologics capacity expansion demand. |
| Field Service Network Expansion | Preventive calibration contracts in California and Massachusetts compress capital expenditure recognition cycles. |
| Fluoropolymer Supply Agreement | Long-term PFA offtake with Japanese producers insulates margin position from resin allocation volatility. |
Research Approach
Multi-period observation of FDA 21 CFR Part 11 enforcement patterns, EMA Annex 1 revision implementation timelines, and NMPA registration streamlining anchored the trend analysis, supplemented by interviews with bioprocessing equipment procurement managers, cleanroom validation specialists, and single-use platform engineering directors. Secondary validation drew from FDA warning letter databases, EU notified body guidance documents, and biopharmaceutical capital expenditure disclosures. Bottom-up equipment shipment tracking across Massachusetts, North Carolina, and California clusters triangulated against top-down biologics manufacturing capacity expansion announcements.
Segment-weighting across product type, technology platform, end-user category, and application maturity shaped the analytical framework over the projection horizon. CAGRs derived from installed base replacement cycle analysis, continuous bioprocessing adoption curves, and cell therapy manufacturing facility buildout pipelines. Modeled inputs included laser welding technology penetration rates in gene therapy applications and ultrasonic platform share in Netherlands-Belgium cell therapy procurement specifications.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to fluoropolymer resin supply disruptions and gene therapy regulatory approval trajectories. A model refresh is warranted upon material change in FDA guidance on closed-system sterile connection validation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Japan Ceramic Roller Bearings Market
Industrial Equipment
Microbubble Cleaning Device Market
Industrial Equipment
Industrial Lasers Systems Market
Industrial Equipment
Spherical Roller Bearings Market
Industrial Equipment
South America Fans and Blowers Market
Industrial Equipment
Industrial Polishing Machine Market
Industrial Equipment
Asia Pacific Industrial Embedded Systems Market
Industrial Equipment
Conveyor Drive Market
Industrial Equipment
Laser Marking Machine Market
Industrial Equipment
Soldering Iron Market
Industrial Equipment
Equipment Cases Market
Industrial Equipment
Asia-Pacific Electro Hydraulic Servo Valve Market
Industrial Equipment
Rotary Scroll Air Compressor Market
Industrial Equipment
Snowrator Market
Industrial Equipment
Precision Dispensing Accessories Market
Industrial Equipment
Linear Transfer System Market