
 Vacuum Concentrators Market | 2026-2036
Vacuum Concentrators Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Concentrators Market Outlook
Buyer concentration in pharmaceutical manufacturing is pivoting toward large-scale contract development and manufacturing organizations that require high-throughput solvent removal capabilities. Thermo Fisher Scientific Inc. leverages its distribution breadth across North American research corridors. Labconco Corporation anchors its position through specialized containment-integrated concentrator designs for biosafety laboratories. Martin Christ Gefriertrocknungsanlagen GmbH dominates freeze-drying adjunct segments with precision vacuum control systems.
Vacuum concentrators are sealed evaporation systems that reduce solvent volume from heat-sensitive samples through controlled pressure reduction, typically operating between 5 mbar and atmospheric pressure with temperature limits below 60°C to preserve biological activity. Their primary purpose centers on sample preparation for chromatography, mass spectrometry, and pharmaceutical quality control workflows. Rotary evaporators sustain the largest installed base across academic and industrial laboratories due to decades of protocol standardization, while freeze dryers command premium positioning in biologics preservation where thermal degradation risks exclude other methods. Short path distillation competes in cannabis and botanical extraction sectors requiring terpene isolation at molecular specificity levels.
The US FDA process analytical technology framework and EPA solvent emission standards shape equipment specifications toward closed-loop recovery and real-time monitoring integration. EMA's good manufacturing practice annexes for sterile production influence vacuum concentrator validation protocols across European pharmaceutical facilities. ISO 9001 quality management and ISO 13485 medical device standards govern supplier qualification criteria, tightening market access for non-certified manufacturers. Stakeholders must monitor evolving green chemistry mandates that prioritize aqueous-based processing over traditional organic solvents.
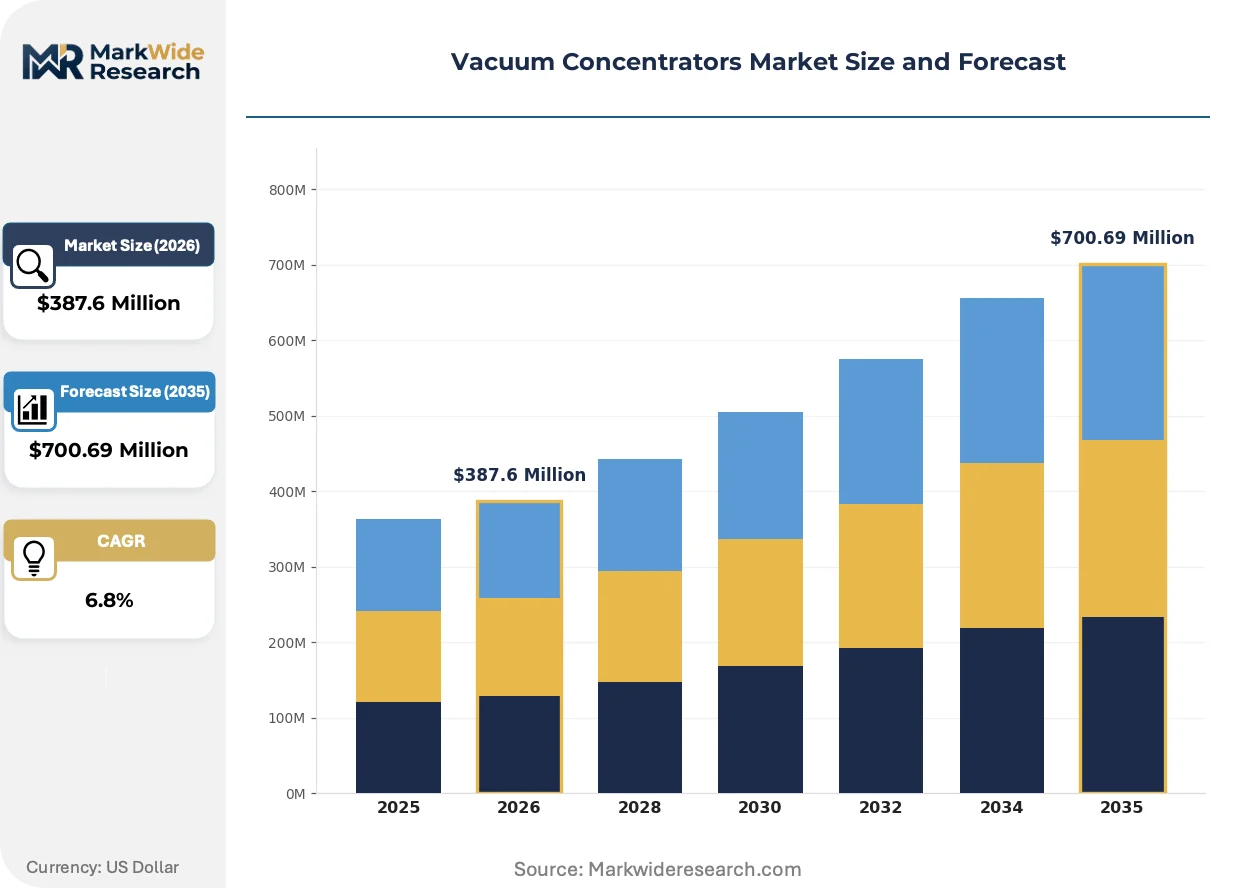
Market Dynamics
Pharmaceutical contract manufacturers are consolidating solvent recovery infrastructure around automated vacuum concentration systems to meet FDA process analytical technology compliance deadlines, compressing procurement cycles for legacy rotary evaporator replacements.
Growth Catalysts
- FDA Process Analytical Technology:The US FDA's PAT framework mandates real-time monitoring integration in pharmaceutical manufacturing, forcing equipment upgrades toward closed-loop vacuum concentration systems with automated solvent recovery capabilities.
- Biologics manufacturing expansion:Contract development and manufacturing organizations in Germany and Switzerland are modernizing laboratory infrastructure to handle heat-sensitive active pharmaceutical ingredients requiring sub-60°C processing protocols.
- Green chemistry mandates:EPA solvent emission standards and REACH restrictions on volatile organic compounds are redirecting R&D workflows toward aqueous-based processing methods compatible with vacuum concentration technology.
Market Restraints
- Stainless steel and borosilicate glass supply:Concentration chamber fabrication depends on specialized corrosion-resistant alloys and precision glassware with extended lead times from German and Japanese suppliers.
- Freeze dryer substitution:Biologics preservation workflows requiring absolute thermal protection continue to specify lyophilization equipment despite higher capital costs, limiting vacuum concentrator penetration in cell therapy applications.
- CE-IVDR compliance complexity:The EU's In Vitro Diagnostic Regulation imposes extended validation timelines on diagnostic laboratory equipment, delaying market access for non-European manufacturers.
Strategic Opportunities
- Indian pharmaceutical clusters:CDSCO's phased manufacturing partnership program and PLI scheme incentives are attracting contract research organizations to Hyderabad and Ahmedabad, creating demand for mid-scale concentration systems.
- Cannabis extraction standardization:State-level regulatory frameworks in California and Colorado are mandating terpene preservation protocols that favor short-path vacuum distillation over conventional evaporation methods.
- AI-driven predictive maintenance:Integration of machine learning algorithms with vacuum pressure sensors and temperature monitoring is enabling outcome-based service contracts that reduce unplanned downtime for high-throughput facilities.
Industry Challenges
- Cross-functional technician shortages:Equipment operation requires simultaneous competency in vacuum physics, thermal engineering, and chromatography sample preparation, constraining deployment velocity at multi-site contract manufacturers.
- ISO 13485 certification timelines:Medical device qualification for diagnostic laboratory applications demands 18-24 month documentation cycles that compress product launch windows for new market entrants.
- Legacy LIMS integration:Proprietary data formats from established concentrator brands create friction when connecting to modern laboratory information management systems, extending commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Concentrators Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Evaporators, Freeze Dryers, Thin Film Evaporators, Short Path Distillation End User: Pharmaceuticals, Food & Beverage, Biotechnology, Research Laboratories Application: Concentration, Solvent Removal, Sample Preparation, Preservation Technology: Mechanical Vacuum, Steam Vacuum, Hybrid Systems, Thermal Vacuum |
| Companies Covered | Thermo Fisher Scientific Inc., Labconco Corporation, Eppendorf AG, Martin Christ Gefriertrocknungsanlagen GmbH, SP Scientific, Buchi Labortechnik AG, Sartorius AG, Genevac Ltd., IKA Works, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Concentrators Market Strategic Shifts
Equipment architecture is pivoting from standalone units to integrated workflow nodes, with vacuum concentrators now positioned as data-generating assets rather than passive sample preparation tools.
Integrated cold trap technology with self-regulating refrigeration circuits is overtaking traditional external chiller configurations in high-throughput pharmaceutical quality control laboratories. CDMOs in Massachusetts and North Carolina are specifying these systems to eliminate cross-contamination risks between sequential sample batches. The shift is compressing maintenance intervals and reducing facility HVAC loads by capturing solvent vapors at point of generation rather than ducting to centralized recovery.
EMA's revised Annex 1 on sterile manufacturing has elevated containment-integrated concentrator designs to mandatory status for European biologics facilities handling cytotoxic or potent compounds. The regulation requires physical isolation of evaporation chambers with HEPA-filtered exhaust, disqualifying open-bench rotary evaporators from GMP workflows. Swiss and German pharmaceutical manufacturers are responding by consolidating procurement around suppliers with pre-validated containment documentation packages.
Service contract unbundling is fragmenting traditional capital equipment sales models across North American academic core facilities. Universities in California and Texas are separating hardware acquisition from preventive maintenance and application support, creating procurement leverage through multi-vendor service aggregators. This pattern is most visible in mass spectrometry core labs where vacuum concentrator uptime directly correlates with instrument utilization rates and chargeback revenue recovery.
Vacuum Concentrators Market Segmentation
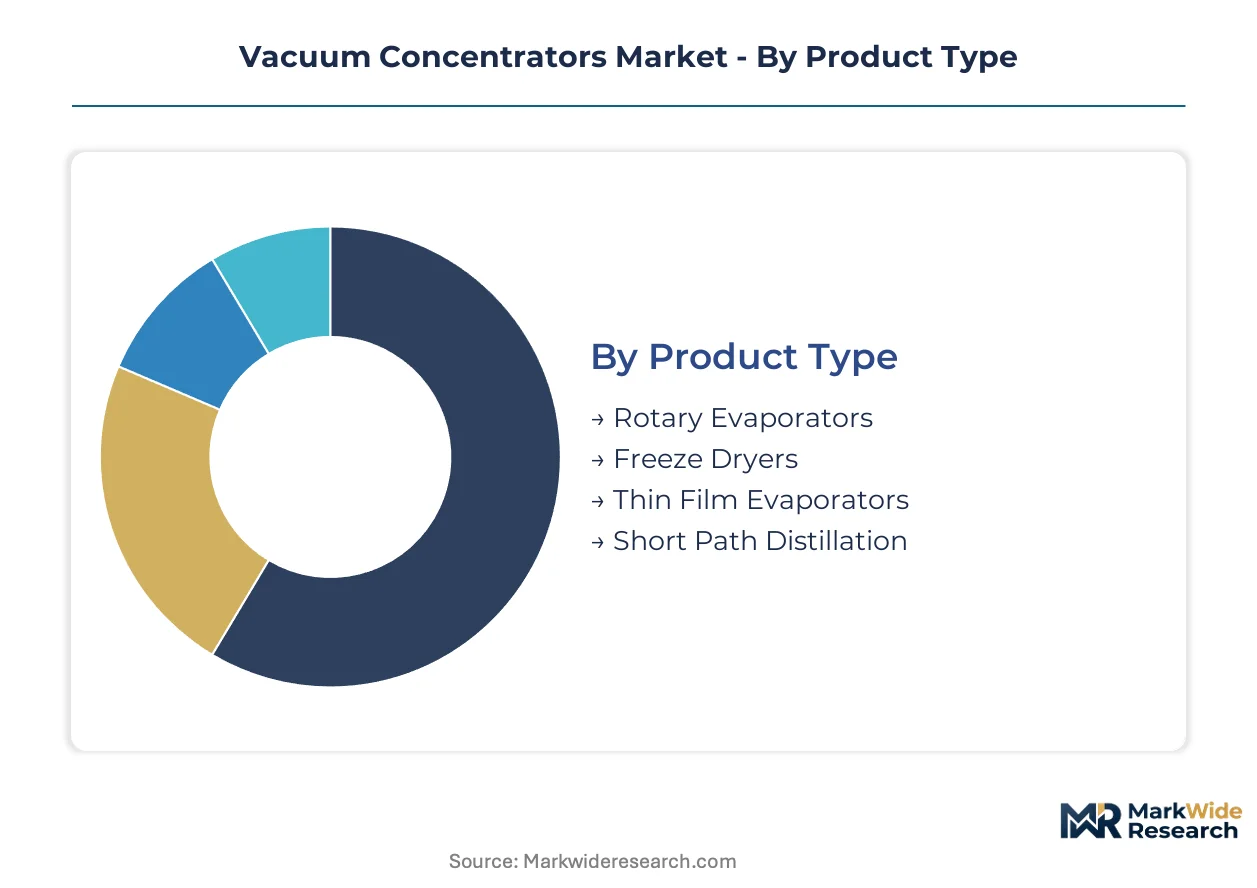
Vacuum concentrator procurement patterns diverge sharply between high-volume academic installations and precision-driven pharmaceutical manufacturing. Equipment specifications in each segment reflect distinct thermal sensitivity requirements, throughput demands, and regulatory compliance burdens that reshape vendor positioning across the value chain.
Product Type:
Volume concentration clusters around standardized rotary evaporator platforms, while premium positioning concentrates in specialized thermal protection systems.
- Rotary Evaporators:These benchtop systems rotate sample flasks under vacuum to distribute heat evenly across solvent films, typically processing 50-3000 mL batches. Demand concentrates in academic core facilities across Germany and the United States where decades of protocol standardization sustain replacement cycles. FDA process analytical technology deadlines are accelerating upgrades toward integrated digital control interfaces.
- Freeze Dryers:Lyophilization equipment operates at sub-zero temperatures with primary drying below -40°C and secondary drying under vacuum, preserving biological activity in protein therapeutics. Contract development and manufacturing organizations in Switzerland specify these systems for cell therapy applications where thermal degradation risks exclude alternative methods. Capital costs run 3-5x above rotary evaporators, limiting deployment to high-value biologics workflows.
- Thin Film Evaporators:Wiped-film and falling-film designs process heat-sensitive viscous materials through continuous feed mechanisms with residence times under 30 seconds.
- Short Path Distillation:Molecular distillation systems separate compounds by boiling point differentials under high vacuum below 0.001 mbar, enabling terpene isolation in California cannabis extraction facilities.
Mature deployment sits with rotary evaporators. Newer deployment is concentrated in short path distillation.
End User:
Customer concentration follows regulatory intensity, with diagnostic-grade manufacturing commanding premium pricing against research-grade installations.
- Pharmaceuticals:Active pharmaceutical ingredient manufacturers deploy closed-loop vacuum concentration systems with automated solvent recovery to meet EPA emission standards and FDA current good manufacturing practice requirements. Massachusetts and North Carolina contract manufacturers are consolidating procurement around containment-integrated designs following EMA Annex 1 revisions on sterile production.
- Biotechnology:Cell and gene therapy developers require absolute thermal protection for viral vectors and mRNA formulations, driving specification of precision vacuum control systems with temperature limits below 4°C. German and Swiss facilities lead adoption of HEPA-filtered exhaust configurations for cytotoxic compound handling.
- Research Laboratories:University core facilities in Texas and California prioritize equipment interoperability with existing mass spectrometry workflows and chargeback revenue recovery systems.
- Food & Beverage:Flavor extraction and natural product concentration applications favor aqueous-based processing methods compatible with green chemistry mandates.
Procurement velocity runs highest in biotechnology. Price compression is most severe in research laboratories.
Application:
Workflow integration determines equipment architecture, with upstream sample preparation demanding higher throughput than downstream preservation steps.
- Sample Preparation:Pre-chromatography concentration steps require rapid solvent removal with minimal sample loss, driving demand for integrated cold trap technology with self-regulating refrigeration circuits. CDMOs specify these systems to eliminate cross-contamination risks between sequential batches.
- Concentration:Volume reduction workflows for quality control testing prioritize reproducibility and documentation compliance with ISO 17025 laboratory accreditation standards.
- Solvent Removal:Organic solvent recovery operations face escalating EPA scrutiny, redirecting investment toward closed-loop systems with real-time monitoring integration.
- Preservation:Long-term biologics storage applications compete directly with lyophilization alternatives, constraining vacuum concentrator penetration in cell banking workflows.
Automation integration is advancing fastest in sample preparation. Manual protocols persist in preservation.
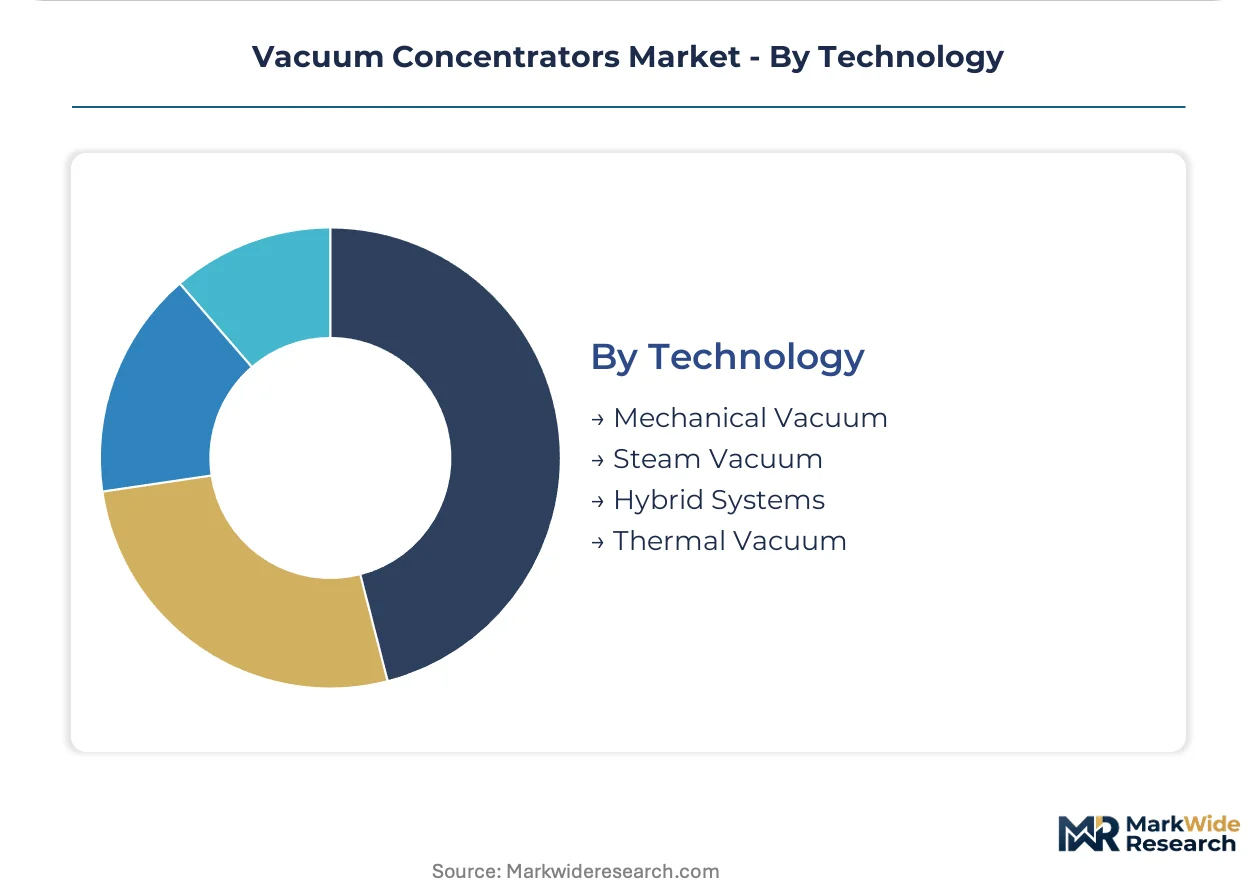
Technology:
Energy intensity separates competitive offerings, with hybrid architectures commanding premium positioning against single-mechanism alternatives.
- Mechanical Vacuum:Oil-sealed rotary vane and dry scroll pumps deliver vacuum levels to 0.1 mbar for routine solvent removal, dominating academic and industrial installations with lower maintenance requirements than steam-based alternatives.
- Hybrid Systems:Combined mechanical and thermal vacuum architectures optimize energy consumption across variable load conditions, gaining traction in high-throughput pharmaceutical quality control laboratories seeking reduced facility HVAC loads.
- Thermal Vacuum:Direct heating methods accelerate evaporation rates for high-boiling-point solvents, deployed in botanical extraction sectors requiring terpene preservation.
- Steam Vacuum:Ejector-based systems handle corrosive vapor streams in specialty chemical applications, though water consumption limits adoption in drought-constrained geographies.
Installed base concentration favors mechanical vacuum. Steepest expansion trajectory belongs to hybrid systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract manufacturing clusters in Germany, Switzerland, and the United States absorb the highest concentration of vacuum concentrator procurement. Massachusetts and North Carolina CDMOs drive North American demand through FDA process analytical technology compliance deadlines.
United States
Massachusetts contract development and manufacturing organizations are consolidating solvent recovery infrastructure around automated vacuum concentration systems. The FDA's process analytical technology framework mandates real-time monitoring integration, compressing procurement cycles for legacy rotary evaporator replacements. North Carolina's Research Triangle biologics corridor is specifying containment-integrated designs for cytotoxic compound handling.
Germany
Baden-Württemberg pharmaceutical manufacturers are modernizing laboratory infrastructure to handle heat-sensitive active pharmaceutical ingredients. EMA's revised Annex 1 on sterile manufacturing elevates containment-integrated concentrator designs to mandatory status for biologics facilities. Bavarian contract research organizations are driving mid-scale system demand through CDSCO partnership programs targeting Indian market expansion.
Switzerland
Basel-region cell and gene therapy developers require absolute thermal protection for viral vectors and mRNA formulations. Swissmedic guidance on sterile production influences vacuum concentrator validation protocols across European facilities. Zurich pharmaceutical clusters are specifying precision vacuum control systems with temperature limits below 4°C for high-value biologics workflows.
India
Hyderabad and Ahmedabad pharmaceutical clusters are attracting contract research organizations through CDSCO's phased manufacturing partnership program and PLI scheme incentives. The national pharmaceutical regulator's quality mandates are redirecting investment toward ISO 13485-certified equipment suppliers. Karnataka's biotech corridor is creating demand for mid-scale concentration systems with automated solvent recovery capabilities.
China
Yangtze River Delta pharmaceutical manufacturers are upgrading equipment to meet NMPA good manufacturing practice requirements for active ingredient processing. The national medical products administration's quality frameworks are pushing toward closed-loop recovery and real-time monitoring integration. Shanghai biologics facilities are consolidating procurement around suppliers with pre-validated containment documentation packages.
Vacuum Concentrators Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized containment and AI-driven predictive maintenance segments. The vendor base organizes around three strategic archetypes: diversified laboratory equipment conglomerates, precision vacuum control specialists, and containment-integrated system fabricators. Market consolidation is accelerating through strategic partnerships between hardware manufacturers and laboratory information management system providers. Geographic expansion into Indian pharmaceutical clusters represents the dominant competitive move alongside portfolio diversification into cannabis extraction applications.
Among diversified laboratory equipment conglomerates, Thermo Fisher Scientific Inc. and Eppendorf AG exemplify the scale-driven archetype with distribution breadth across North American and European research corridors. Labconco Corporation occupies a position within the containment-integrated specialist tier, anchoring market presence through biosafety laboratory applications. Martin Christ Gefriertrocknungsanlagen GmbH represents the precision vacuum control archetype, sitting within the freeze-drying adjunct segment with German engineering positioning. These three company structures illustrate the competitive spectrum from diversified conglomerates to specialized fabricators.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Labconco Corporation |
| Eppendorf AG |
| Martin Christ Gefriertrocknungsanlagen GmbH |
| SP Scientific |
| Buchi Labortechnik AG |
| Sartorius AG |
| Genevac Ltd. |
| IKA Works, Inc. |
| Others |
Value Chain & Pricing Dynamics
ISO 13485 certification tiers bifurcate the vacuum concentrator landscape into premium validated systems and economy research-grade units, with that divergence manifesting in both pricing power and supply chain configurations. Pharmaceutical manufacturers in Massachusetts and North Carolina absorb 40-60% pricing premiums for pre-validated containment documentation packages, while academic core facilities in Texas and California negotiate on hardware-only procurement with service contracts unbundled to third-party aggregators.
Pricing Analysis
Volume concentration in rotary evaporators runs on thin margins, while freeze dryer adjunct segments with precision vacuum control systems capture substantially wider spreads. Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated pharmaceutical equipment from research-grade installations and refurbished secondary market units. Pricing pressure stems from stainless steel and borosilicate glass supply constraints with extended lead times from German and Japanese suppliers. Contract development and manufacturing organizations exhibit lowest price sensitivity given FDA process analytical technology compliance deadlines, while university core facilities face severe budget compression.
Supply Chain Analysis
Regional distribution centers in Germany, Switzerland, and the United States anchor hub-and-spoke patterns for vacuum concentrator fulfillment, with Bavarian and Baden-Württemberg facilities serving European pharmaceutical clusters and Massachusetts-based nodes covering North American demand. Concentration chamber fabrication draws from specialized corrosion-resistant alloys and precision glassware sourced from German and Japanese suppliers. Single-source vulnerability sits with freeze-drying adjunct components where Martin Christ Gefriertrocknungsanlagen GmbH dominates precision vacuum control systems. Distribution runs through direct OEM sales for pharmaceutical manufacturers and laboratory equipment distributors for academic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum concentrator market consolidation accelerates as FDA process analytical technology deadlines compress procurement cycles, forcing smaller non-certified manufacturers toward acquisition or exit.
For Market Incumbents: Anchor market position through backward integration into stainless steel and borosilicate glass supply chains, securing captive supply of corrosion-resistant alloys against Japanese supplier lead time volatility. Deepen vertical integration by acquiring laboratory information management system providers to resolve proprietary data format friction that extends commissioning periods at multi-site contract manufacturers. For New Entrants and Emerging Players: CDSCO's phased manufacturing partnership program in India opens a window for mid-scale concentration system penetration, targeting Hyderabad and Ahmedabad pharmaceutical clusters with automated solvent recovery capabilities. Cannabis extraction standardization in California and Colorado represents the most penetrable application segment, with state-level terpene preservation protocols favoring short-path vacuum distillation over conventional evaporation methods. For Investors and Strategic Acquirers: Re-rating potential sits with containment-integrated system fabricators given EMA's revised Annex 1 on sterile manufacturing elevating physical isolation requirements to mandatory status. Long-term viability over a 5-10 year window favors precision vacuum control specialists with ISO 13485 certification and pre-validated documentation packages. Watch for AI-driven predictive maintenance integration as the inflection indicator for outcome-based service contract adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Containment-Integrated System Development | EMA Annex 1 compliance mandates physical isolation of evaporation chambers with HEPA-filtered exhaust for European biologics facilities. |
| AI-Driven Predictive Maintenance Integration | Machine learning algorithms with vacuum pressure sensors enable outcome-based service contracts reducing unplanned downtime at high-throughput CDMOs. |
| Indian Pharmaceutical Cluster Expansion | CDSCO partnership programs and PLI scheme incentives attract contract research organizations to Hyderabad and Ahmedabad infrastructure. |
| Backward Integration into Precision Glassware | Captive supply of borosilicate glassware mitigates extended lead time risks from Japanese suppliers for concentration chamber fabrication. |
| Laboratory Information Management System Partnership | Integration resolves proprietary data format friction that extends commissioning periods at mass spectrometry core labs. |
Study Parameters
Document review covered FDA process analytical technology guidance documents, EMA Annex 1 sterile manufacturing revisions, and ISO 13485 certification standards, complemented by interviews with pharmaceutical manufacturing executives, laboratory equipment procurement managers, and regulatory affairs specialists at contract development and manufacturing organizations. Secondary validation drew from EPA solvent emission standards, CDSCO partnership program documentation, and NMPA good manufacturing practice requirements. Bottom-up equipment shipment data triangulated against top-down pharmaceutical capital expenditure surveys.
Historical shipment patterns cross-referenced against expert panel input on technology substitution risks and regulatory timeline acceleration. The analytical framework segmented across product type, end user, application, and technology dimensions throughout the forecast period, with CAGRs derived from regression analysis of installed base expansion and replacement cycle compression. Forecast inputs incorporated freeze dryer substitution elasticity, green chemistry mandate adoption curves, and CE-IVDR compliance timeline delays.
The model assumes a particular technology adoption path toward hybrid mechanical-thermal vacuum architectures; alternative pathways for steam vacuum ejector systems would alter the outlook given water consumption constraints in drought-constrained geographies. Forecasts reflect assumptions around FDA enforcement consistency and EMA Annex 1 implementation timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
South America Fans and Blowers Market
Industrial Equipment
Slewing Bearing Market
Industrial Equipment
Global Laser Material Market
Industrial Equipment
Global Integrated Drive Systems Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Europe Vacuum Pump Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Photography Panoramic Tripod Heads Market
Industrial Equipment
Laser Processing Market
Industrial Equipment
Middle-East Fans and Blowers Market
Industrial Equipment
Case Handling Machines Market
Industrial Equipment
Laser Marking Machine Market
Industrial Equipment
Ultrasonic Atomizer Market
Industrial Equipment
Laser Plastic Welding Market
Industrial Equipment
Servo Drive Market
Industrial Equipment
North America Industrial Embedded Systems Market