
 North America Industrial Centrifuge Market | 2026-2036
North America Industrial Centrifuge Market Size, Share, and Industry Trends Forecast 2026-2036
North America Industrial Centrifuge Market Analytics
Buyer concentration across North American wastewater treatment utilities is broadening as municipal districts consolidate operations and private water operators fragment into specialized regional contracts. Alfa Laval AB leverages its decanter technology leadership to anchor large-scale municipal sludge dewatering projects across the Great Lakes region. GEA Group AG sustains competitive positioning through hydraulic drive specialization for high-torque chemical processing applications. Andritz AG dominates the pulp and paper residue segment with customized continuous centrifuge systems engineered for fiber recovery.
An industrial centrifuge is a rotating separation device that generates centrifugal force typically exceeding 1,000 times gravitational acceleration to segregate immiscible liquids or extract solids from slurries, with bowl speeds ranging from 1,600 to 4,000 RPM depending on process viscosity and particle density. Its primary industrial purpose centers on continuous or batch purification, clarification, and dewatering across process industries where gravitational settling proves economically unviable. Decanter centrifuges command the largest installed base in North American oilfield services and petrochemical refining, reflecting mature replacement cycles and established service networks. Disc stack configurations capture expanding share in pharmaceutical bioprocessing as single-use downstream purification protocols demand higher g-force precision and validated clean-in-place compliance.
EPA effluent limitation guidelines and OSHA Process Safety Management standards shape equipment specifications, forcing manufacturers to engineer sealed bowl designs and automated vibration monitoring for hazardous chemical duty. FDA Current Good Manufacturing Practice regulations for pharmaceutical applications mandate material traceability and surface finish documentation that extends procurement timelines but locks in premium supplier relationships. Water utilities in California, Texas, and Ontario face divergent state-level phosphorus discharge rules that fragment standardization and reward centrifuge vendors with configurable control platforms. Stakeholders must monitor how the EPA's emerging PFAS destruction mandates redirect capital from conventional dewatering toward integrated thermal-chemical treatment trains that displace legacy centrifuge-only configurations.
Market Dynamics
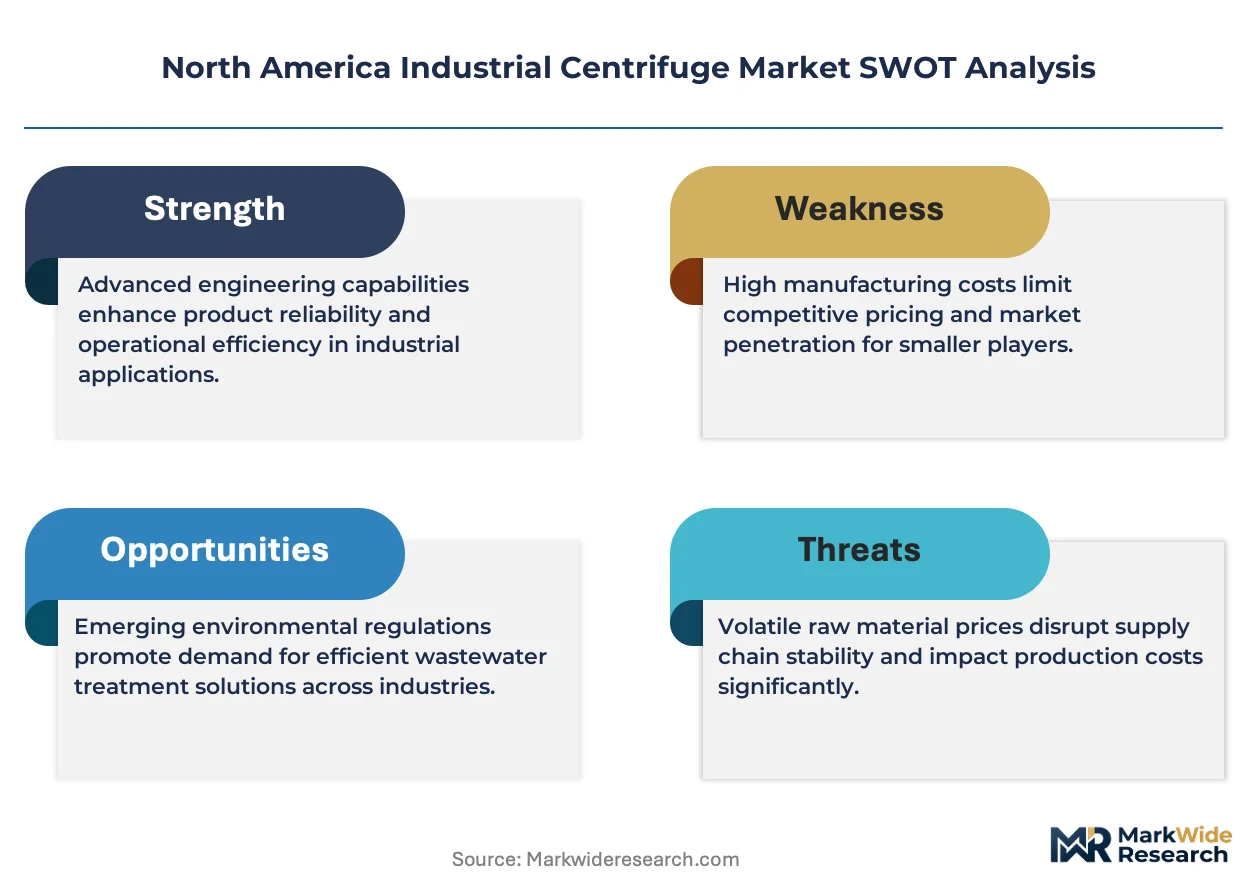
EPA effluent limitation guidelines for PFAS destruction are redirecting municipal capital toward integrated thermal-chemical treatment trains, compressing demand for standalone centrifuge configurations across the United States and Canadian wastewater utilities.
Growth Catalysts
- PFAS Destruction Mandates:EPA enforcement actions against per- and polyfluoroalkyl substances are forcing municipal utilities in Michigan and Ontario to upgrade sludge handling capacity, accelerating decanter centrifuge replacement cycles.
- Texas Petrochemical Expansion:Gulf Coast ethylene crackers and polyethylene facilities are commissioning high-torque hydraulic drive centrifuges for catalyst recovery and polymer dewatering operations.
- Great Lakes Phosphorus Rules:Wisconsin and Ohio state-level nutrient discharge limits are compelling wastewater districts to install disc stack centrifuges for enhanced biological phosphorus removal sludge processing.
Market Restraints
- Specialized Alloy Supply Concentration:Duplex stainless steel and super-duplex casting capacity concentrates among a limited supplier base in Pennsylvania and Ohio, creating 16-24 week lead times for corrosion-resistant bowl assemblies.
- Skilled Technician Scarcity:Vibration analysis and hydraulic drive calibration expertise remains concentrated among retiring field service engineers, constraining deployment velocity for complex chemical-duty installations.
- Thermal Oxidation Substitution:Emerging sludge-to-energy pyrolysis systems in California and Texas are displacing mechanical dewatering as the primary volume reduction method for certain hazardous waste streams.
Strategic Opportunities
- Single-Use Bioprocessing Convergence:Pharmaceutical manufacturers in Massachusetts and North Carolina are integrating disposable disc centrifuges with continuous biomanufacturing platforms, creating demand for validated clean-in-place automation.
- Alberta Oil Sands Tailings:Canadian oilfield service contractors are piloting high-capacity decanter systems for mature fine tailings dewatering under provincial reclamation liability frameworks.
- Remote Monitoring Platforms:Predictive maintenance subscriptions are penetrating the municipal utility segment, displacing time-based service contracts with vibration-sensor-enabled performance guarantees.
Industry Challenges
- FDA Validation Timelines:Pharmaceutical centrifuge qualification under Current Good Manufacturing Practice protocols extends procurement cycles, requiring extensive material traceability documentation and surface finish certification.
- Legacy Control System Integration:Municipal utilities in the Great Lakes corridor face friction retrofitting automated centrifuge controls into aging SCADA architectures, complicating workforce transition and operational continuity.
- Hazardous Duty Certification Delays:OSHA Process Safety Management compliance for chemical processing centrifuges involves extended third-party explosion-proof testing, compressing vendor margins and delivery reliability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Industrial Centrifuge Market |
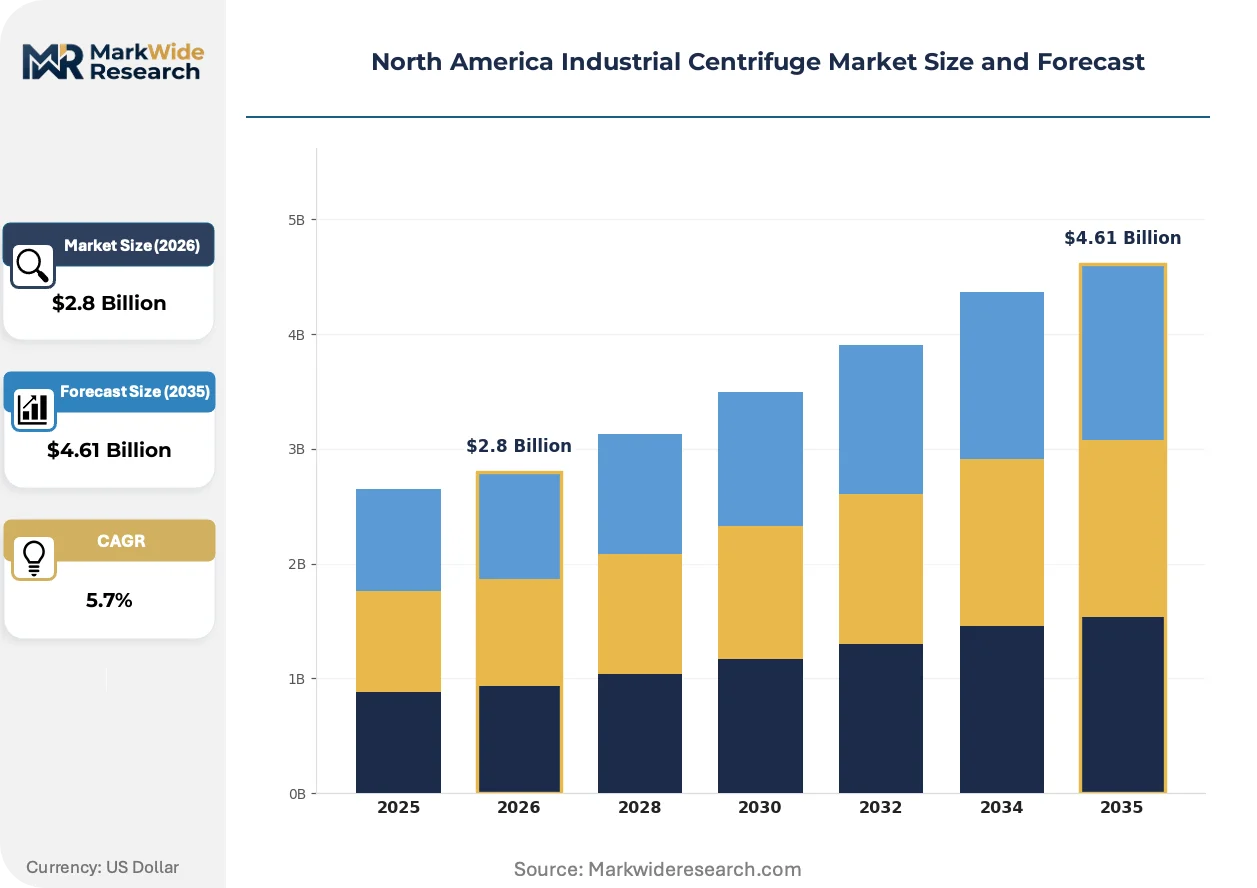
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Batch, Continuous, Disc, Decanter Application: Chemicals, Food & Beverage, Pharmaceuticals, Wastewater Treatment End User: Manufacturing, Energy, Agriculture, Water Utilities Technology: Hydraulic, Mechanical, Centrifugal, Cross-Flow |
| Companies Covered | Centrisys Corporation, Ferrum Ltd, Alfa Laval AB, KUBOTA Corporation, Sartorius AG, Andritz AG, Flottweg SE, Hettich Lab Technology, GEA Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Industrial Centrifuge Market Evolving Landscape
Digital instrumentation and sealed bowl architectures are converging to transform equipment specification criteria across North American process industries, with regulatory compliance and operational visibility now co-equal purchasing priorities.
Variable frequency drive technology paired with real-time torque sensing is unifying process control and energy optimization in decanter centrifuge operations. Petrochemical refiners along the Texas Gulf Coast are adopting these integrated drive systems at accelerating rates. This convergence is compressing the competitive advantage of standalone hydraulic specialists while elevating vendors with embedded automation portfolios.
EPA effluent limitation guidelines for nutrient discharge are tightening phosphorus and nitrogen thresholds in Wisconsin, Ohio, and Ontario watersheds. Municipal utilities must demonstrate continuous compliance through automated solids capture and dewatering verification. The Great Lakes industrial corridor is responding with disc stack centrifuge deployments featuring sealed bowl designs and automated cake dryness sensors.
Performance-based service contracting is displacing traditional time-and-material maintenance arrangements among consolidated water utilities. Private operators in Texas and California are unbundling equipment procurement from operational guarantees, transferring uptime risk to centrifuge vendors. This shift is most visible in the municipal sludge dewatering segment, where district consolidation has concentrated purchasing leverage among fewer procurement decision-makers.
North America Industrial Centrifuge Market Segmentation
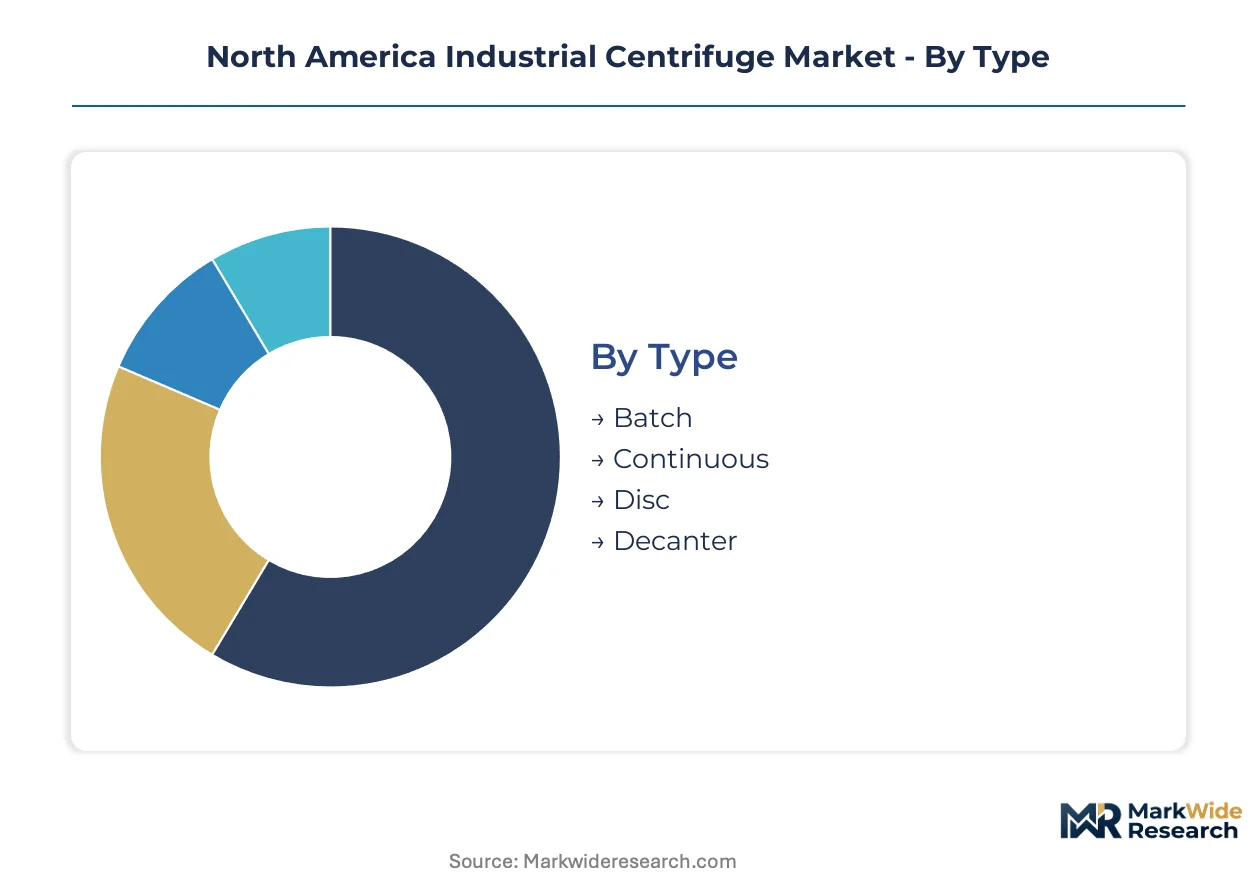
Industrial centrifuge procurement patterns diverge sharply between standalone dewatering installations and integrated process trains. Understanding these configuration preferences enables vendors to align engineering resources with replacement-cycle timing and compliance-driven upgrade windows.
Type:
Standalone batch systems serve intermittent processing needs while continuous configurations embed into automated production lines.
- Decanter:Continuous horizontal bowl designs handle high-solids slurries through differential screw conveyance. Texas Gulf Coast petrochemical clusters and Great Lakes wastewater districts anchor replacement demand as EPA effluent rules tighten.
- Disc:Vertical stack configurations generate extreme g-forces for liquid-liquid separation and fine solids capture. Pharmaceutical bioprocessing in Massachusetts and North Carolina drives specification for validated clean-in-place protocols.
- Batch:Intermittent operation suits small-volume specialty chemical producers with variable feedstocks.
- Continuous:Uninterrupted processing aligns with high-throughput oilfield services and pulp mill fiber recovery operations.
Volume placements concentrate in Decanter configurations; the faster expansion belongs to Disc systems.
Application:
Regulatory intensity varies dramatically across end-use sectors, with effluent mandates in water treatment outpacing process optimization drivers elsewhere.
- Wastewater Treatment:Municipal sludge dewatering consumes the largest installed base across United States and Canadian utilities. Phosphorus discharge limits in Wisconsin, Ohio, and Ontario force continuous compliance investments.
- Pharmaceuticals:Downstream bioprocessing demands validated separation under FDA Current Good Manufacturing Practice protocols. Single-use system integration in North Carolina and Massachusetts accelerates specification turnover.
- Chemicals:Catalyst recovery and polymer dewatering in Texas ethylene crackers favor high-torque hydraulic drive systems.
- Food & Beverage:Edible oil clarification and dairy processing concentrate procurement in California and Wisconsin dairy corridors.
Installed capacity tilts toward Wastewater Treatment; Pharmaceuticals climbs the fastest on biomanufacturing expansion.
End User:
Customer scale and procurement sophistication fragment sharply between consolidated utilities and fragmented industrial operators.
- Water Utilities:Consolidated municipal districts in the Great Lakes corridor and Texas metropolitan areas command volume purchasing leverage. District mergers concentrate decision-making among fewer procurement officers.
- Manufacturing:Diverse chemical, food, and pharmaceutical producers span mid-scale batch operations to continuous process plants.
- Energy:Oilfield services contractors in Alberta and Texas deploy high-capacity decanters for drilling mud and tailings management.
- Agriculture:Regional ethanol producers and biodiesel facilities in Iowa and Nebraska represent intermittent replacement demand.
Procurement volume pools with Water Utilities; Energy shows steepest expansion trajectory on oil sands reclamation liability.
Technology:
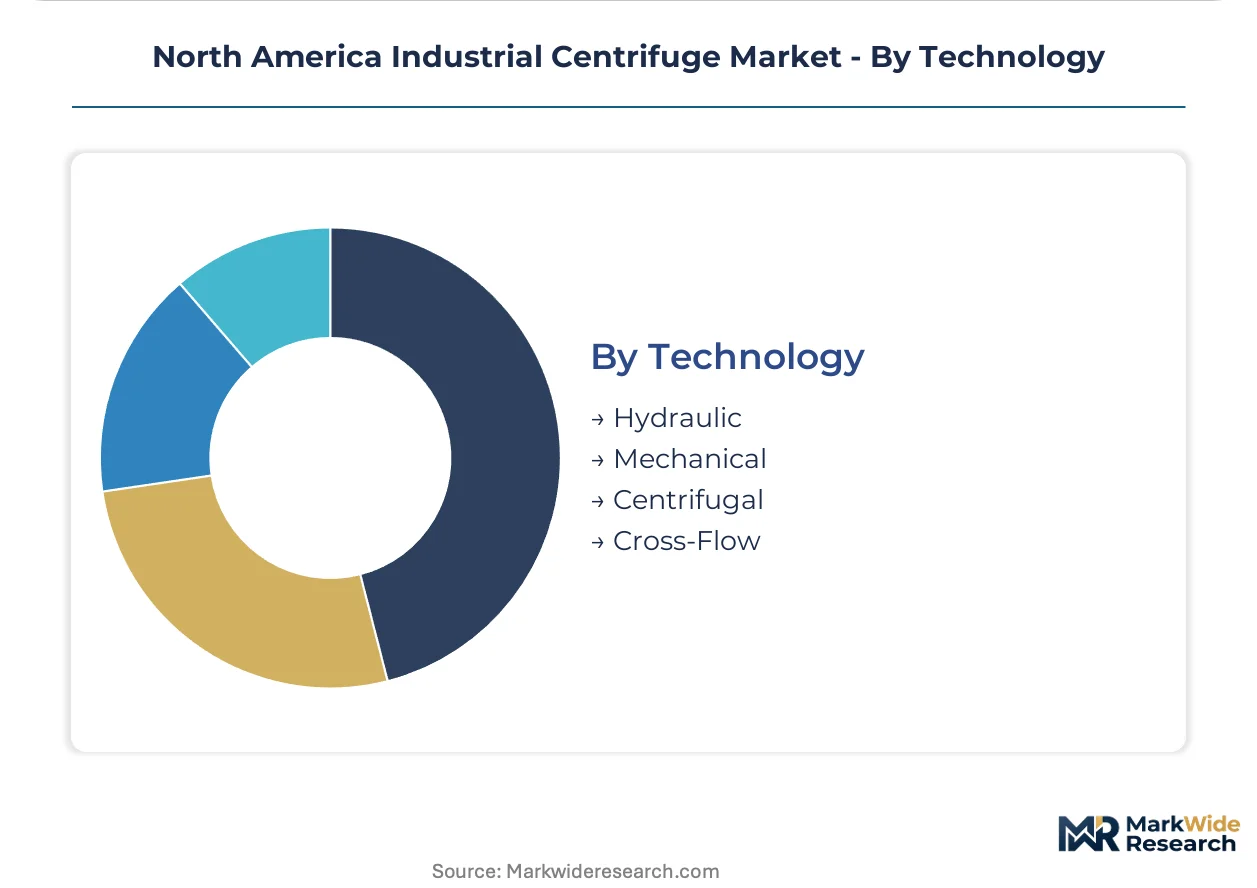
Drive system selection determines maintenance burden and energy efficiency tradeoffs across duty cycles.
- Hydraulic:High-torque transmission excels in variable-load chemical processing where startup inertia and overload protection matter. Texas petrochemical facilities specify these for catalyst recovery reliability.
- Mechanical:Gear-driven systems dominate mature municipal installations with predictable feedstock characteristics and established service networks.
- Centrifugal:Direct-drive electric configurations penetrate food and pharmaceutical applications requiring precise speed control and reduced vibration signatures.
- Cross-Flow:Membrane-coupled hybrid designs emerge in specialized bioprocessing where product integrity demands gentle solids handling.
Mechanical systems retain the largest installed footprint; Hydraulic configurations gain share fastest on petrochemical capacity additions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Duplex stainless steel foundries in Pennsylvania and Ohio supply corrosion-resistant bowl assemblies that anchor centrifuge manufacturing across the continent. The Great Lakes industrial corridor and Texas Gulf Coast petrochemical clusters concentrate replacement demand as EPA effluent standards tighten. Provincial reclamation liabilities in Alberta and state-level phosphorus rules in Wisconsin fragment procurement specifications.
United States
Municipal sludge dewatering utilities in California, Texas, and the Great Lakes corridor drive decanter replacement cycles. EPA effluent limitation guidelines for PFAS destruction redirect capital toward integrated thermal-chemical treatment trains. Wisconsin and Ohio wastewater districts install disc stack centrifuges to meet state-level nutrient discharge limits.
Canada
Ontario water utilities expand centrifuge deployments under provincial phosphorus discharge regulations. Health Canada guidelines shape pharmaceutical bioprocessing specifications in the Toronto-Waterloo corridor. Alberta oil sands contractors pilot high-capacity decanter systems for mature fine tailings dewatering under provincial reclamation liability frameworks.
Mexico
Petrochemical refiners in Tamaulipas and Veracruz commission continuous centrifuge systems for catalyst recovery operations. Mexican environmental regulators tighten industrial wastewater standards along the Gulf Coast. Monterrey-based chemical processors represent emerging demand for corrosion-resistant bowl assemblies.
North America Industrial Centrifuge Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue digital instrumentation and remote monitoring subscriptions. The vendor base stratifies across three maturity tiers: diversified industrial conglomerates with full automation portfolios, hydraulic drive specialists with petrochemical expertise, and regional fabricators serving municipal replacement cycles. Competitive positioning depends on M&A activity consolidating control system capabilities and strategic partnerships embedding predictive maintenance platforms into long-term service contracts.
Among European-based industrial conglomerates, Alfa Laval AB, GEA Group AG, and Andritz AG exemplify distinct archetype strategies. Alfa Laval anchors the decanter technology leadership position visible across Great Lakes municipal sludge projects. GEA Group occupies the hydraulic drive specialization tier serving Texas Gulf Coast petrochemical torque requirements. Andritz represents the pulp and paper residue segment dominance through customized continuous centrifuge engineering.
| Leading Market Players |
|---|
| Centrisys Corporation |
| Ferrum Ltd |
| Alfa Laval AB |
| KUBOTA Corporation |
| Sartorius AG |
| Andritz AG |
| Flottweg SE |
| Hettich Lab Technology |
| GEA Group AG |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between FDA-validated pharmaceutical units and commodity municipal dewatering systems manifests in both pricing power and supply chain complexity across the North American industrial centrifuge market. Premium-tier vendors command extended procurement cycles and captive supplier relationships, while standard-tier competitors compete on replacement-part availability and field service density.
Pricing Analysis
Performance-based service bundling separates premium municipal contracts from unbundled equipment-only transactions in the Texas and Great Lakes utility corridors. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by EPA compliance tier and automation depth. Pricing pressure stems from consolidated water utility purchasing leverage compressing vendor margins on large-scale decanter deployments. Municipal districts in Wisconsin and Ohio exhibit highest price sensitivity due to state phosphorus rule compliance costs, while pharmaceutical manufacturers in Massachusetts show lowest sensitivity given FDA validation lock-in effects.
Supply Chain Analysis
Regional distribution centers in Pennsylvania and Ohio anchor hub-and-spoke patterns serving the Great Lakes industrial corridor and Texas Gulf Coast petrochemical clusters. Duplex stainless steel casting capacity concentrates in the United States and Canada, drawing from nickel and molybdenum feedstocks subject to commodity volatility. Single-source vulnerability in super-duplex bowl assembly suppliers creates procurement risk for corrosion-resistant chemical-duty configurations. Distribution runs through OEM-direct channels for large municipal projects and authorized service networks for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EPA PFAS destruction mandates and performance-based contracting are forcing sub-scale regional fabricators toward exit or acquisition.
For Market Incumbents: Anticipate thermal oxidation substitution threats in California and Texas hazardous waste streams by deepening automation portfolios and predictive maintenance subscriptions. Secure captive supply of Pennsylvania and Ohio duplex casting capacity through long-term offtake agreements or backward integration into bowl assembly fabrication. Lock in consolidated Great Lakes municipal districts with decade-long performance guarantees that transfer uptime risk from utility operators. For New Entrants and Emerging Players: Begin with remote monitoring platform development targeting fragmented municipal utilities in the Great Lakes corridor lacking in-house vibration analysis expertise. The most penetrable white space sits with mid-scale chemical processors in Monterrey and Tamaulipas seeking corrosion-resistant configurations without incumbent service network dependence. Pursue channel partnerships with Alberta oilfield service contractors piloting mature fine tailings dewatering systems under provincial reclamation liability pressure. For Investors and Strategic Acquirers: Re-rating potential sits with hydraulic drive specialists possessing Texas petrochemical torque expertise given Gulf Coast ethylene cracker expansion timelines. Long-term viability over a multi-year window favors vendors with embedded automation portfolios capable of displacing standalone mechanical competitors. Monitor EPA enforcement action velocity against municipal utilities as the inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Duplex Casting | Captive supply of Pennsylvania and Ohio bowl assembly capacity insulates margin from 16-24 week lead time volatility. |
| Predictive Maintenance Platform Launch | Vibration-sensor subscriptions displace time-based contracts among consolidated Great Lakes water utilities. |
| FDA Validation Documentation Investment | Material traceability and surface finish certification locks in premium pharmaceutical supplier relationships. |
| Alberta Oil Sands Pilot Partnership | High-capacity decanter trials for mature fine tailings dewatering open provincial reclamation liability-driven demand. |
| SCADA Control Retrofit Capability | Automated centrifuge integration into aging Great Lakes municipal architectures reduces workforce transition friction. |
Research Methodology
Multi-period observation of EPA enforcement patterns, state-level phosphorus discharge compliance investments, and municipal district consolidation timelines anchored the trend analysis, supplemented by interviews with plant engineers at Texas Gulf Coast petrochemical facilities, procurement leads at Great Lakes water utilities, aftermarket service heads at regional fabricators, and regulatory affairs specialists at pharmaceutical manufacturers. Secondary validation drew from EPA effluent limitation guideline filings, SEC 10-K equipment disclosure segments, American Chemistry Council regional capacity reports, and Health Canada pharmaceutical manufacturing guidance documents. Bottom-up unit placement tracking across decanter, disc, and batch configurations triangulated against top-down industrial capital expenditure flow analysis.
Input-output matrices mapped centrifuge type, application, end user scale, and drive technology segmentation against replacement cycle timing and compliance-driven upgrade windows across the projection horizon. CAGRs derived from regression analysis of historical municipal capital expenditure patterns and petrochemical capacity addition announcements, with bioprocessing expansion in Massachusetts and North Carolina serving as pharmaceutical demand inputs and Alberta reclamation liability framework evolution informing oil sands tailings processing forecasts.
Underlying measurement precision varies by segment; wastewater treatment utility deployments carry tighter precision given public procurement documentation requirements, while pharmaceutical bioprocessing estimates reflect longer FDA validation timeline uncertainty. Forecasts assume continuation of current EPA enforcement intensity and state-level nutrient discharge rule trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Fiber Laser Market
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
Industrial Lasers Systems Market
Industrial Equipment
Middle East and Africa Industrial Centrifuge Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Global Twister Winder Market
Industrial Equipment
Global Laboratory Vacuum Pumps Market
Industrial Equipment
Electric Soldering Iron Gun Market
Industrial Equipment
Medical Laser Marking Machine Market
Industrial Equipment
Global Pneumatic Actuators Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Europe Fans and Blowers Market
Industrial Equipment
Asia Pacific Industrial Embedded Systems Market
Industrial Equipment
Laser Marking Machine Market
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Machine Mounts Market