
 Industrial Monitor Market | 2026-2036
Industrial Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Monitor Market Analysis
The embedded systems engineering talent pool is collapsing across North America and Western Europe, forcing OEMs to redesign monitor architectures for faster deployment with fewer integration hours. Siemens AG leverages its automation ecosystem to bundle industrial monitors with programmable logic controllers, reducing field commissioning complexity. Advantech Co., Ltd. anchors its position through backward integration into board-level computing, while Rockwell Automation Inc. competes via its FactoryTalk visualization platform that locks in recurring software attach rates.
An industrial monitor is a ruggedized display device engineered for continuous operation in harsh environments, typically rated for extended temperature ranges, vibration resistance, and ingress protection against dust and moisture, with screen sizes spanning 7 to 55 inches and brightness levels exceeding 1000 nits for direct sunlight readability. Its primary purpose is to render human-machine interface data for real-time process control, equipment diagnostics, and safety-critical alerting in manufacturing and infrastructure settings. LED-backlit LCD panels dominate unit shipments due to their balance of luminance stability and procurement cost, while OLED technology is penetrating aerospace and medical imaging segments where contrast ratio and viewing angle precision command premium pricing. Touchscreen interfaces lead technology adoption as operators demand gesture-capable interaction for complex workflow navigation, though non-touch variants sustain demand in food processing and chemical plants where glove compliance and caustic cleaning protocols degrade capacitive sensor longevity.
FCC Part 15 emissions compliance shapes product design for US-bound industrial monitors, while CE marking under the EU Machinery Directive governs European market access and mandates fail-safe operational states. China's GB 4943.1 standard, administered by SAMR, enforces electrical safety and fire resistance testing that foreign suppliers must navigate through certified local laboratories. Buyers should monitor how IEC 62443 cybersecurity standards for operational technology networks will soon extend certification requirements beyond hardware durability into firmware integrity and supply chain provenance documentation.
Market Dynamics
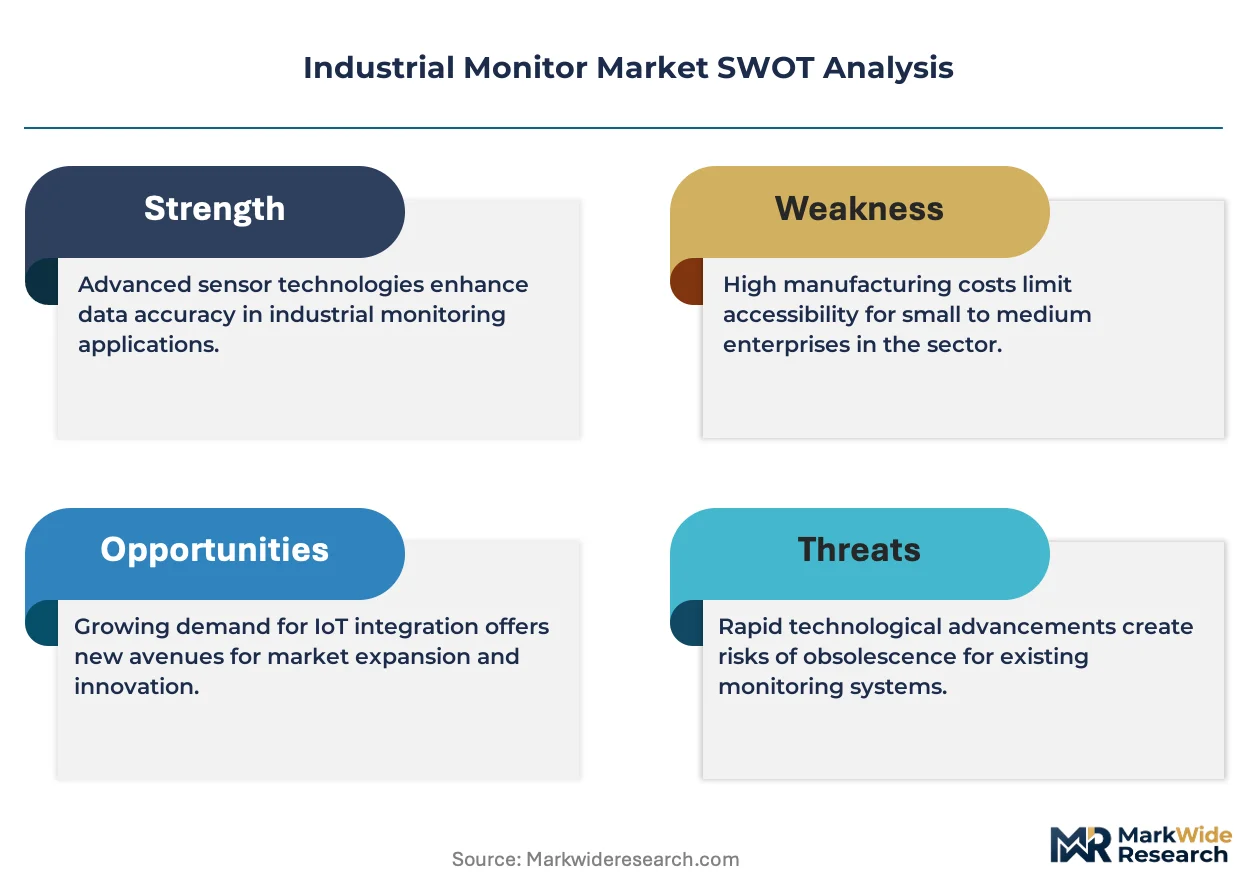
The collapse of embedded systems engineering talent across North America and Western Europe is forcing OEMs to redesign monitor architectures for faster deployment with fewer integration hours, compressing product development cycles and reshaping vendor competitive positioning.
Growth Catalysts
- Factory automation mandates:Automotive assembly plants in Germany and the United States are accelerating procurement of ruggedized displays for real-time process visualization and equipment diagnostics.
- IEC 61010-1 electrical safety standards:Certification requirements under this framework are expanding addressable market access for compliant suppliers across European industrial zones.
- Touchscreen interface adoption:Gesture-capable HMI navigation is displacing traditional button-panel controls in complex workflow environments, particularly in precision manufacturing settings.
Market Restraints
- LED panel supply concentration:Backlight module production clusters in East Asia create vulnerability to logistics disruption and input cost volatility.
- Capacitive sensor degradation:Food processing and chemical plant glove compliance protocols limit touchscreen longevity, sustaining demand for non-touch variants that constrain average selling price expansion.
- FCC Part 15 emissions compliance:US-bound product redesign cycles add certification friction and extend time-to-revenue for foreign suppliers.
Strategic Opportunities
- India manufacturing expansion:Underpenetrated industrial automation infrastructure creates white space for ruggedized display deployment in process industries and infrastructure projects.
- IEC 62443 cybersecurity standards:Operational technology network security mandates will extend certification requirements into firmware integrity and supply chain provenance documentation, creating service attach opportunities.
- OLED-polymer convergence:Aerospace and medical imaging segments command premium pricing for contrast ratio and viewing angle precision, enabling margin expansion beyond commodity LCD volumes.
Industry Challenges
- Embedded firmware integration:Talent scarcity in real-time operating systems and industrial protocol stacks is extending commissioning timelines and inflating engineering costs.
- Multi-standard certification pipelines:Simultaneous navigation of CE marking under EU Machinery Directive, China's GB 4943.1 via SAMR-certified laboratories, and FCC Part 15 creates compliance complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Monitor Market |
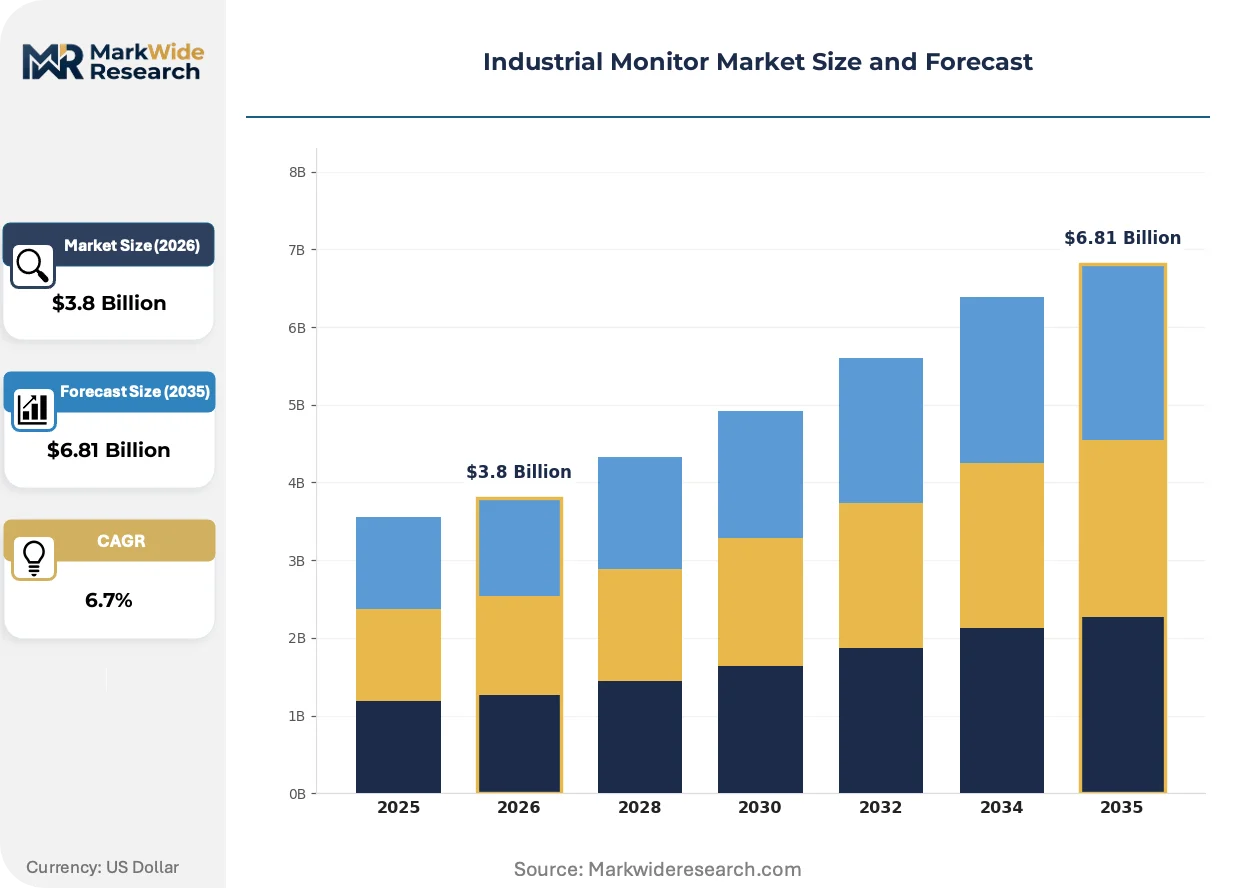
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, LED, OLED, Surface-Mount Technology: Touchscreen, Non-Touch, Embedded, Wall-Mounted End User: Manufacturing, Transportation, Aerospace, Energy Application: Control Room, Production Line, Field Operation, Monitoring Station |
| Companies Covered | Advantech Co., Ltd., Siemens AG, Kontron S&T AG, ADLINK Technology Inc., Sparton Inc., Rockwell Automation Inc., Schneider Electric, LG Display Co., Ltd., Samsung Display Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Monitor Market Emerging Trajectories
Display technology roadmaps and certification frameworks are diverging across end-use verticals, creating specialized product architectures that trade off luminance stability, contrast precision, and environmental hardening against procurement cost and deployment velocity.
Optical bonding is bifurcating the industrial monitor landscape by eliminating air gaps between cover glass and LCD panels to enhance sunlight readability and vibration resistance. Marine and outdoor infrastructure operators are adopting this process at accelerated pace for navigation and control systems. The technology is bifurcating supplier tiers into specialized optical integrators versus standard assembly houses that cannot absorb capital equipment requirements.
China's GB 4943.1 standard administered by SAMR is tightening electrical safety and fire resistance testing protocols for foreign suppliers. Certified local laboratory partnerships have become mandatory for market access, raising fixed compliance costs. Industrial monitor vendors targeting Chinese manufacturing zones are responding by establishing captive testing relationships in Shanghai and Shenzhen.
Specification-driven procurement is compressing vendor evaluation cycles as automotive and energy buyers consolidate supplier panels around pre-qualified platform providers. Distributor technical support roles are displacing direct field application engineering for standard configurations. This pattern is most visible in German automotive supply chains where Tier 1 integrators demand single-source accountability for HMI subsystem performance.
Industrial Monitor Market Segmentation
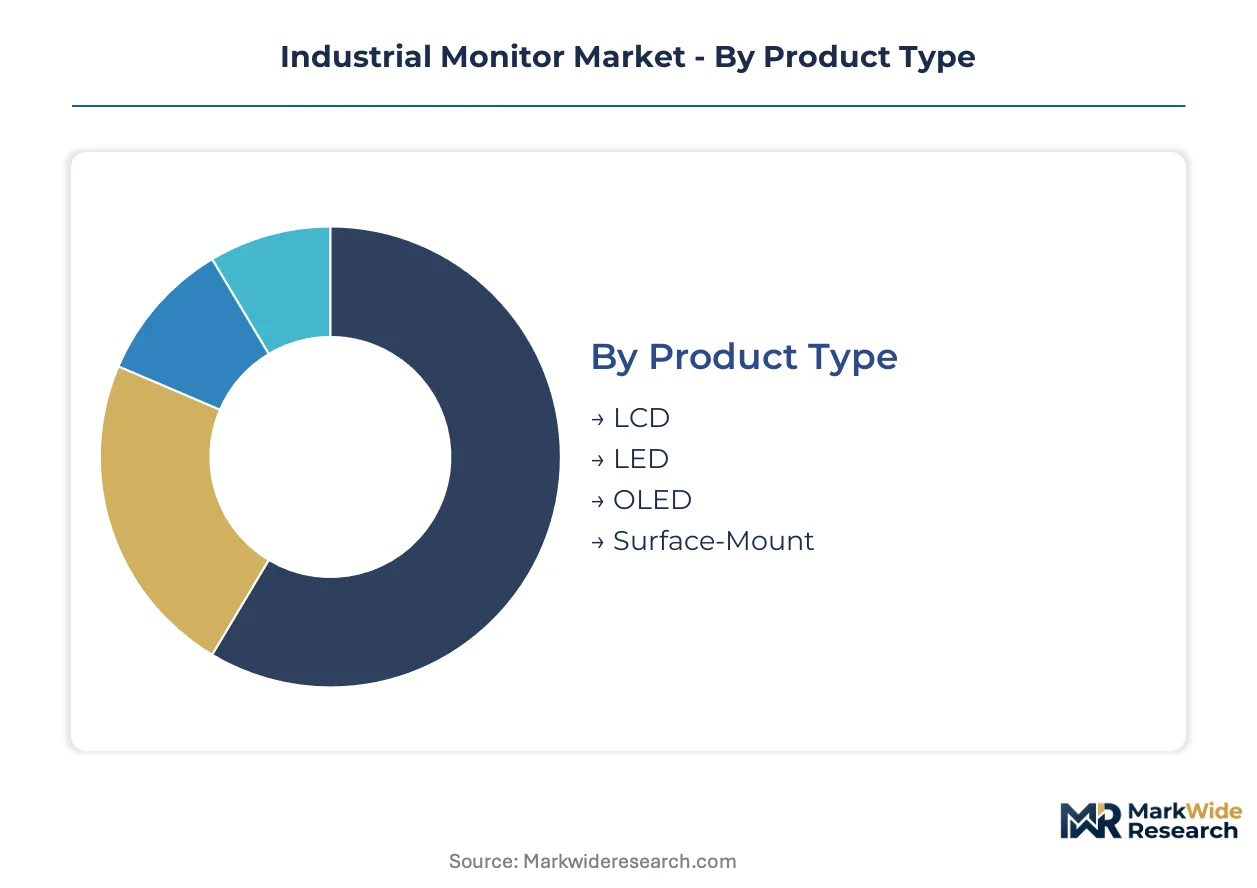
Industrial monitor procurement flows through distinct technical and application channels that reshape vendor go-to-market strategies. Specification requirements diverge sharply between process control environments and mobile field deployments, compressing product development timelines for cross-functional platforms.
Product Type:
Display panel procurement channels bifurcate between high-volume LCD distributors serving cost-sensitive automation integrators and specialized optical bonding houses supplying marine and outdoor infrastructure operators.
- LCD:LED-backlit TFT panels deliver 1000+ nit luminance stability at procurement cost points that dominate automotive assembly plant specifications. German and United States factory automation mandates are channeling procurement through Tier 1 integrators demanding single-source subsystem accountability.
- LED:Direct-lit backlight architectures eliminate edge-lighting uniformity issues for 24/7 control room visualization. Energy sector buyers in China are consolidating supplier panels around pre-qualified platform providers to compress evaluation cycles.
- OLED:Self-emissive pixel arrays command premium pricing in medical imaging segments where contrast ratio precision justifies procurement cost elevation.
- Surface-Mount:Panel-PC integration reduces field cabling complexity for space-constrained embedded deployments in transportation infrastructure.
LCD dominates installed base. OLED is where expansion concentrates for contrast-critical verticals.
Technology:
Interface architecture selection directly determines margin structure, with gesture-capable touch platforms sustaining software attach revenue against commodity non-touch hardware.
- Touchscreen:Projected capacitive arrays enable multi-finger gesture navigation for complex HMI workflows in precision manufacturing settings. Capacitive sensor degradation under caustic cleaning protocols in food processing plants is constraining average selling price expansion.
- Non-Touch:Sealed bezel designs eliminate ingress vulnerability for glove-mandatory chemical plant environments. IEC 61010-1 certification requirements are expanding addressable market access for compliant suppliers across European industrial zones.
- Embedded:Board-level computing integration collapses commissioning complexity as embedded systems engineering talent scarcity forces OEM redesign for faster deployment.
- Wall-Mounted:VESA-standard bracketing accelerates installation velocity in retrofit control room infrastructure.
Touchscreen leads new procurement volume. Non-touch sustains replacement demand in regulated environments.
End User:
Vertical-specific durability requirements are fragmenting product architectures, with aerospace and marine applications demanding optical bonding specialization unavailable from standard assembly houses.
- Manufacturing:Factory floor deployments prioritize vibration resistance and extended temperature operation for continuous process visualization. Automotive assembly plants in Germany and the United States are accelerating ruggedized display procurement for real-time equipment diagnostics.
- Transportation:Mobile installations require shock-hardened enclosures for rail and fleet management applications. Surface-mount panel-PC integration is displacing discrete component assemblies to reduce field failure points.
- Aerospace:Cockpit and cabin systems demand OLED contrast precision and wide viewing angle stability under variable lighting conditions.
- Energy:Outdoor substation and pipeline monitoring applications drive optical bonding adoption for sunlight readability enhancement.
Manufacturing anchors current procurement volume. Energy infrastructure is climbing the fastest for outdoor-hardened platforms.
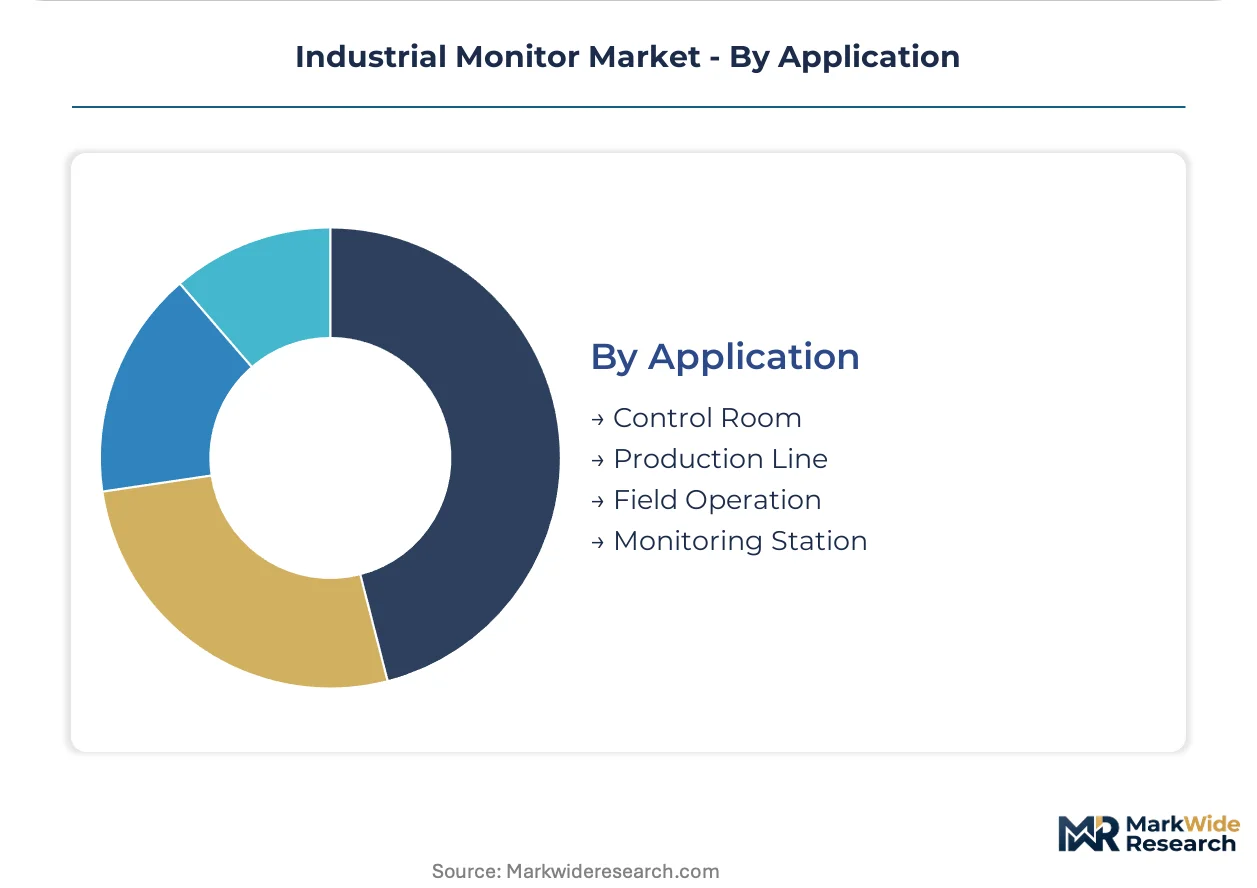
Application:
Deployment environment dictates enclosure rating and brightness specification, with field operation deployments commanding NEMA 4X premiums against climate-controlled control room standards.
- Control Room:Continuous-operation video wall configurations prioritize color calibration stability and bezel minimization for operator fatigue reduction. LED direct-backlight architectures are displacing edge-lit alternatives for uniformity-critical 24/7 visualization.
- Production Line:Arm-mounted and pedestal installations require IP65 ingress protection against coolant spray and metal particulate. Touchscreen gesture navigation is displacing traditional button-panel controls for complex workflow environments.
- Field Operation:Portable and vehicle-mounted deployments demand 1500+ nit brightness for direct sunlight readability. Optical bonding elimination of air gaps between cover glass and LCD panels is accelerating adoption in marine navigation systems.
- Monitoring Station:Unattended remote infrastructure requires fanless thermal management and wide-range DC power input for solar and battery backup compatibility.
Control Room commands premium pricing tiers. Field Operation is gaining share fastest for optical-bonded ruggedization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial monitor consumption patterns diverge sharply by geography, with automotive-heavy economies prioritizing vibration-hardened factory floor units while energy-exporting regions drive demand for sunlight-readable field operation platforms.
United States
Automotive assembly plants in Michigan and Tennessee are accelerating ruggedized display procurement for real-time equipment diagnostics and process visualization. FCC Part 15 emissions compliance shapes product design cycles for US-bound equipment, extending certification timelines for foreign suppliers. Detroit's Tier 1 automotive supply chains consolidate supplier panels around pre-qualified platform providers demanding single-source HMI subsystem accountability.
Germany
Factory automation mandates across Bavaria and Baden-Württemberg channel procurement through Siemens-anchored automation ecosystems bundling monitors with programmable logic controllers. CE marking under the EU Machinery Directive governs market access and mandates fail-safe operational states for industrial equipment. Stuttgart's automotive engineering clusters specification-drive procurement toward optical-bonded variants for precision manufacturing environments.
China
Energy sector buyers in the Yangtze River Delta and Pearl River Delta consolidate supplier panels around pre-qualified platform providers to compress evaluation cycles. SAMR-administered GB 4943.1 standards enforce electrical safety and fire resistance testing through certified local laboratories in Shanghai and Shenzhen. Foreign suppliers establish captive testing relationships to navigate compliance costs for manufacturing zone access.
Japan
Embedded systems engineering talent scarcity forces OEMs in the Chubu and Kansai regions toward board-level computing integration that collapses commissioning complexity. METI industrial policy frameworks support automation infrastructure investment in precision manufacturing segments. Nagoya's automotive supply chains demand gesture-capable touchscreen interfaces for complex HMI workflow navigation.
India
Underpenetrated industrial automation infrastructure in Maharashtra and Gujarat creates white space for ruggedized display deployment in process industries and infrastructure projects. BIS certification requirements shape product qualification pathways for foreign equipment suppliers. Mumbai-Pune manufacturing corridors specification-drive procurement toward cost-optimized LCD platforms for emerging factory automation adoption.
Industrial Monitor Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier bundling monitors into automation ecosystems and the lower tier competing on optical bonding specialization or board-level integration speed. The vendor base spans three strategic archetypes: automation ecosystem bundlers leveraging controller attach rates, optical integrators commanding premiums for marine and outdoor applications, and embedded computing specialists compressing deployment timelines. Dominant competitive moves include backward integration into board-level computing and strategic partnerships with certified testing laboratories for multi-standard compliance.
Within the automation ecosystem tier, Siemens AG and Rockwell Automation Inc. anchor positions through bundled hardware-software platforms that reduce field commissioning complexity. Advantech Co., Ltd. exemplifies the embedded computing archetype through upstream control over board-level production that accelerates deployment velocity for talent-constrained integration environments. These three companies occupy positions that reflect the market's bifurcation between ecosystem lock-in strategies and speed-to-deployment specialization.
| Leading Market Players |
|---|
| Advantech Co., Ltd. |
| Siemens AG |
| Kontron S&T AG |
| ADLINK Technology Inc. |
| Sparton Inc. |
| Rockwell Automation Inc. |
| Schneider Electric |
| LG Display Co., Ltd. |
| Samsung Display Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Panel-level scale economies in LED-backlit TFT manufacturing anchor price floors across the industrial monitor landscape, compressing margins for standard assembly houses while rewarding specialized optical integrators with captive bonding capacity. East Asian backlight module concentration amplifies procurement leverage for volume buyers in automotive and energy verticals, forcing smaller OEMs toward project-based pricing models that pass through input cost volatility.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between Tier 1 automotive integrators and established display vendors, insulating buyers from spot-market LED panel fluctuations while locking suppliers into fixed-margin delivery schedules. Price differentiation hinges on certification grade—IEC 61010-1 and NEMA 4X compliance command 15-25% premiums over uncertified equivalents—and volume scale, with annual procurement thresholds above 10,000 units triggering tiered rebate structures. Cost compression in the standard LCD tier is intensifying as Chinese panel makers expand Gen 8.5 capacity, eroding Korean and Taiwanese incumbent positioning. Food processing and chemical plant buyers exhibit highest price sensitivity, prioritizing sealed non-touch variants over gesture-capable platforms to minimize total cost of ownership under caustic cleaning protocols.
Supply Chain Analysis
Strategic stockpiling of LED driver ICs and optical-grade adhesives characterizes vendor inventory strategy, buffering against 26-week procurement lead times for specialized bonding equipment that constrains optical integrator expansion. Backlight module production clusters in China, South Korea, and Taiwan feed downstream assembly operations, with polarizer films and cover glass drawing from Japanese and German specialty chemical suppliers. Single-source vulnerability concentrates in indium tin oxide sputtering targets for capacitive touch layers, where Korean and Japanese refiners control 80% of merchant supply. Distribution runs through authorized industrial automation distributors in Germany and the United States, with direct OEM relationships dominating high-volume automotive procurement in China and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification tiers and application-specific durability requirements creates niche expansion opportunities for specialists, as automotive and energy buyers consolidate supplier panels around pre-qualified platform providers while leaving white space in medical imaging and marine navigation segments.
For Market Incumbents: Fortify ecosystem lock-in through backward integration into board-level computing and firmware stacks, compressing deployment timelines for talent-constrained integration environments. Prioritize captive testing relationships with SAMR-certified laboratories in Shanghai and Shenzhen to neutralize GB 4943.1 compliance friction for Chinese manufacturing zone access. Certification investment in IEC 62443 cybersecurity standards represents the priority defensive lever against software-attach competitors. For New Entrants and Emerging Players: Anchor in India's underpenetrated industrial automation infrastructure, where Maharashtra and Gujarat process industries lack established ruggedized display supply relationships. Target optical bonding specialization for marine and outdoor energy applications, where standard assembly houses cannot absorb capital equipment requirements. Pursue distributor technical support partnerships to displace direct field application engineering for emerging factory automation adopters. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automation ecosystem bundlers integrating monitors with programmable logic controllers and visualization software, sustaining margin stability across replacement cycles. Long-term viability favors targets with captive board-level production and multi-standard certification pipelines spanning CE marking, FCC Part 15, and GB 4943.1. Watch for IEC 62443 mandate acceleration as the inflection signal elevating firmware integrity and supply chain provenance documentation to competitive differentiation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Board-Level Computing | Advantech's upstream control over embedded computing accelerates deployment velocity for talent-scarce integration environments. |
| Captive Testing Laboratory Partnerships | Foreign suppliers establishing SAMR-certified relationships in Shanghai and Shenzhen neutralize GB 4943.1 compliance barriers. |
| IEC 62443 Cybersecurity Certification | Operational technology network security mandates extend hardware differentiation into firmware integrity and supply chain provenance. |
| Optical Bonding Specialization | Marine and outdoor infrastructure operators adopt gap-elimination processes unavailable from standard assembly houses. |
| Automation Ecosystem Bundling | Siemens leverages controller attach rates to reduce field commissioning complexity and lock in recurring software revenue. |
Methodological Framework
Desk research of SEC 10-K filings, customs and trade databases, and IEC certification registries preceded structured interviews with plant engineers, OEM procurement teams, aftermarket service heads, and industrial automation distributors. Primary fieldwork captured specification requirements across automotive assembly, energy infrastructure, and medical imaging verticals. Secondary validation drew from SAMR administrative announcements, EU Machinery Directive guidance documents, and FCC equipment authorization databases. Bottom-up unit shipment estimates triangulated against top-down procurement spend analysis across the analysis window.
Variance decomposition across product type, technology interface, end-use vertical, and application environment shaped the analytical framework for volume and value outputs over the projection horizon. Segmentation dimensions modeled included display panel architecture, touchscreen versus non-touch interface selection, manufacturing versus aerospace end-use differentiation, and control room versus field operation deployment context. CAGRs were derived from logistic adoption curves fitted to procurement intent survey data and historical replacement cycle patterns. Industry-specific forecast inputs incorporated LED panel price trajectories and embedded systems engineering wage inflation indices.
Material uncertainties—tariff escalation on Chinese-origin components, sudden IEC 62443 mandate acceleration, and automotive production volatility—sit outside the modeled envelope. Forecasts reflect assumptions regarding certification timeline stability and backlight module supply continuity. Revision becomes warranted when LED panel capacity utilization in East Asia crosses 90% thresholds or when GB 4943.1 testing queue durations exceed six months.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Vertical Centrifugal Separator Market
Industrial Equipment
Industrial Marking Equipment Market
Industrial Equipment
Automatic Laser Welding Machine Market
Industrial Equipment
Coil Winding Machine Market
Industrial Equipment
Washdown Scales Market
Industrial Equipment
Global Cold Plate Market
Industrial Equipment
Global Special Purpose Machines Market
Industrial Equipment
Global Safety Relays and Timers Market
Industrial Equipment
Global High Power Laser Systems Market
Industrial Equipment
Global Cryostat Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Fume Extractor Market
Industrial Equipment
Global Servo Motor Market
Industrial Equipment
Dynamic Scales Market
Industrial Equipment
Global Twister Winder Market
Industrial Equipment
Battery Power Tools Market