
 Industrial Lasers Systems Market | 2026-2036
Industrial Lasers Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Lasers Systems Market Intelligence
Precision-grade beam stability is unwinding legacy tolerance thresholds across metal fabrication workflows. TRUMPF Group leverages its captive supply of resonator components to dominate high-power cutting installations in European automotive plants. IPG Photonics Corporation anchors its position through vertical integration of diode manufacturing, sustaining cost advantages in fiber laser architectures. Han's Laser Technology Industry Group Co., Ltd. competes aggressively on standard-system pricing, occupying volume tiers in Asia-Pacific electronics contract manufacturing.
Industrial laser systems integrate gain media, resonator cavities, and beam delivery optics to generate coherent, high-intensity electromagnetic radiation for material processing at wavelengths typically spanning ultraviolet through far-infrared. These systems execute cutting, welding, marking, and surface treatment with micron-scale accuracy and minimal thermal distortion of substrates. Fiber lasers now lead product type dynamics due to superior wall-plug efficiency and maintenance intervals compared to CO2 alternatives, while solid-state platforms retain margin pools in defense and medical device applications. Beam delivery systems represent the fastest-growing technology segment as multi-axis robotic integration and real-time adaptive optics expand addressable tasks in complex geometries.
OSHA in the United States enforces permissible exposure limits on laser radiation in manufacturing environments, compelling OEMs to integrate interlocked enclosures and automated shutoff protocols. The EU Machinery Directive and CE marking requirements shape product access across European member states, while China's SAMR administers GB standards for industrial equipment safety and electromagnetic compatibility. Stakeholders must monitor evolving semiconductor laser diode export controls and rare-earth supply chain certifications, as these inputs determine system availability and compliance trajectories across major manufacturing jurisdictions.
Market Dynamics
Fiber laser architectures are compressing CO2 platform margins while EU F-Gas Regulation and China's dual carbon goals force resonator redesigns and refrigerant phase-outs across installed bases.
Growth Catalysts
- Electric vehicle battery welding:Precision seam tracking for 4680 cylindrical cells and prismatic modules is pulling high-power fiber installations into gigafactory construction pipelines across Germany and China.
- EU F-Gas Regulation phase-down:Mandated reduction in fluorinated greenhouse gas emissions is accelerating replacement cycles for legacy CO2 systems dependent on R744-equivalent cooling loops.
- Stuttgart-Munich automotive corridor:Concentrated OEM and Tier-1 manufacturing footprint in Baden-Württemberg and Bavaria sustains dense service networks and rapid system deployment.
Market Restraints
- Rare-earth supply concentration:Neodymium and ytterbium fiber dopant sourcing depends on Chinese processing capacity, exposing resonator manufacturers to export quota volatility.
- High-power diode cost structure:Kilowatt-class pump diode stacks represent 35-40% of bill-of-materials for fiber platforms, constraining margin expansion at volume tiers.
- Plasma cutting substitution:Thick-section mild steel applications above 25mm retain cost advantages for oxy-fuel and plasma alternatives in shipyard and heavy fabrication.
Strategic Opportunities
- India PLI scheme for specialty steel:Production-linked incentive disbursements for high-grade automotive and electrical steel are priming greenfield laser cutting capacity in Gujarat and Maharashtra.
- Adaptive optics-robotics convergence:Real-time beam steering integrated with six-axis cobot arms opens geometrically complex repair and refurbishment tasks in aerospace MRO.
- China dual carbon retrofit mandate:Provincial energy intensity targets in Jiangsu and Guangdong are forcing 2015-vintage CO2 system replacements with wall-plug-efficient fiber alternatives.
Industry Challenges
- Resonator alignment technician scarcity:Precision cavity mirror calibration requires 2,000+ hour apprenticeship pipelines that German and Japanese vocational systems struggle to replenish.
- Multi-jurisdiction certification timelines:Simultaneous CE marking under EU Machinery Directive, OSHA compliance for US installations, and GB standard SAMR approval stretches product launch windows.
- Legacy beam delivery integration:Retrofitting fiber sources to existing gantry and robot-mounted CO2 optics requires custom collimator redesigns that fragment engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Lasers Systems Market |
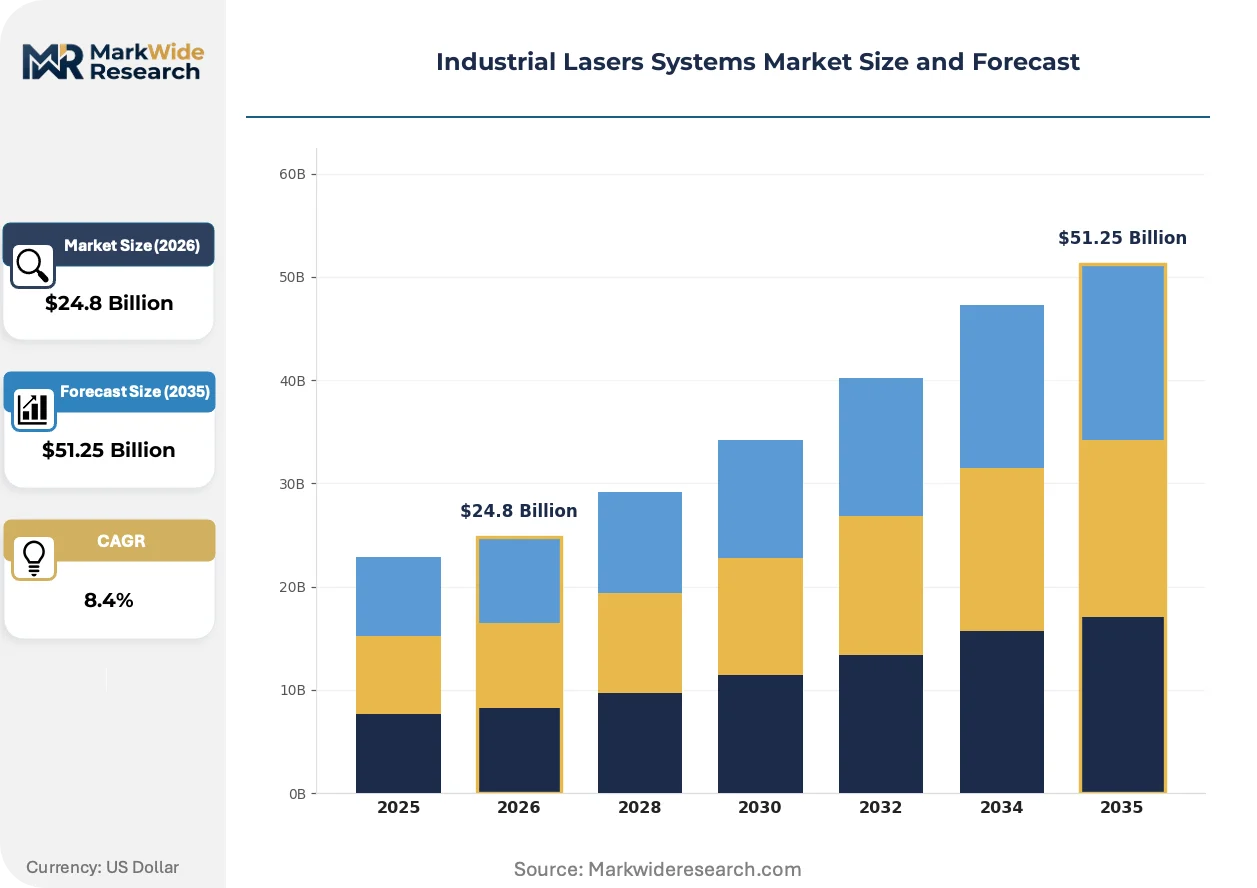
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CO2 Lasers, Fiber Lasers, Nd:YAG Lasers, Solid-State Lasers Application: Cutting, Welding, Marking, Engraving End User: Aerospace, Automotive OEMs, Electronics, Manufacturing Technology: Beam Delivery Systems, Control Systems, Simulation Software, Power Supply |
| Companies Covered | TRUMPF Group, IPG Photonics Corporation, Coherent, Han's Laser Technology Industry Group Co., Ltd., Jenoptik AG, LUMIBIRD, NKT Photonics, Lumentum Holdings, Newport Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Lasers Systems Market Strategic Shifts & Innovations
Beam delivery architectures and control software are fragmenting into modular, application-specific configurations rather than universal platforms. Three developments are compressing traditional equipment margins.
Ultrafast picosecond and femtosecond sources are bifurcating the marking and micromachining segment from nanosecond legacy platforms. Medical device manufacturers in Switzerland and Minnesota are specifying sub-10 picosecond pulse widths for stent cutting and catheter ablation. This pulse-duration stratification is compressing nanosecond system resale values while opening premium service-contract tiers for ultrafast maintenance.
REACH substance restrictions and EU F-Gas Regulation are forcing refrigerant transitions in high-power resonator cooling circuits. OEMs are engineering closed-loop chiller designs using hydrofluoroolefin alternatives or direct liquid cooling to maintain thermal stability. German automotive laser welding lines are absorbing 12-18 month redesign cycles to certify these thermal management architectures.
Contract manufacturers are unbundling after-sales service from capital equipment purchases, pressuring OEMs to compete with independent integrators for maintenance revenue. Electronics assembly houses in Shenzhen and Penang are negotiating performance-based uptime guarantees rather than standard warranty extensions. This service-model fragmentation is most visible in fiber laser populations above 6kW where diode degradation predictability enables outcome-based pricing.
Industrial Lasers Systems Market Segmentation
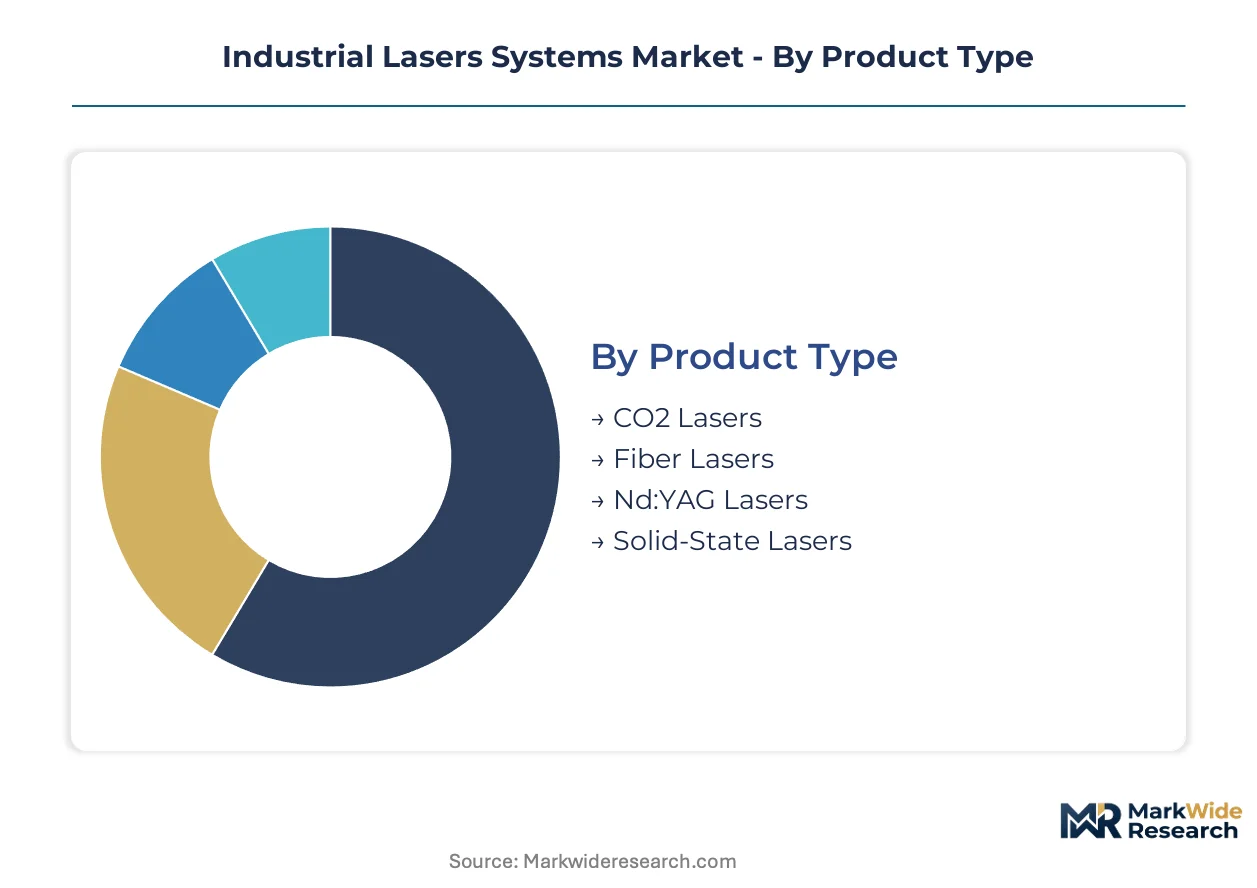
Industrial laser systems fragment across four distinct category axes that shape procurement patterns and margin structures. Product type determines thermal efficiency and maintenance cadence. Application specificity drives beam parameter requirements. End-user verticals impose certification and integration standards. Technology layers separate hardware from software value capture.
Product Type:
CO2 platforms face the most acute substitution pressure as fiber architectures displace their installed base across metal fabrication.
- CO2 Lasers:Gas-discharge resonators operating at 10.6 micrometers wavelength deliver superior edge quality on thick organic materials and coated metals. German automotive stamping plants retain these systems for galvanized steel processing above 6mm thickness, though EU F-Gas Regulation refrigerant phase-outs are compressing replacement timelines.
- Fiber Lasers:Ytterbium-doped silica fiber resonators achieve wall-plug efficiencies exceeding 30% with maintenance intervals stretching beyond 50,000 hours. Gigafactory construction in Germany and China is pulling kilowatt-class fiber installations into battery welding lines, displacing legacy solid-state alternatives.
- Nd:YAG Lasers:Neodymium-doped yttrium aluminum garnet crystals pumped by flashlamps or diodes deliver high peak powers for spot welding reflective metals.
- Solid-State Lasers:Disk and slab geometries using crystalline gain media retain defense and medical device applications requiring exceptional beam quality.
Fiber lasers retain volume leadership; beam delivery systems hold the steepest expansion curve.
Application:
Cost tier stratification separates capital-intensive welding installations from lower-threshold marking equipment.
- Cutting:Multi-kilowatt sources combined with CNC gantries or robotic arms sever metals, ceramics, and composites with kerf widths below 0.3mm. India's PLI scheme for specialty steel is priming greenfield laser cutting capacity in Gujarat and Maharashtra for automotive and electrical steel grades.
- Welding:Seam tracking systems with real-time adaptive optics join dissimilar metals in electric vehicle battery modules and powertrain components. Precision requirements for 4680 cylindrical cells are pulling high-power fiber installations into gigafactory pipelines.
- Marking:Nanosecond and ultrafast sources engrave permanent identifiers on medical devices, electronics, and aerospace components.
- Engraving:Depth-controlled ablation creates tactile patterns and functional surface textures on molds and tooling.
Cutting commands the largest installed base; welding exhibits the steepest expansion trajectory.
End User:
Customer type determines integration complexity and service contract structures.
- Aerospace:Nadcap-accredited MRO facilities specify ultrafast sources for turbine blade cooling hole drilling and composite repair. Real-time beam steering integrated with six-axis cobot arms is opening geometrically complex refurbishment tasks.
- Automotive OEMs:Stuttgart and Munich corridor manufacturers demand 24/7 uptime guarantees with predictive diode replacement schedules. Dense service networks in Baden-Württemberg and Bavaria sustain rapid system deployment.
- Electronics:Contract manufacturers in Shenzhen and Penang negotiate performance-based uptime guarantees rather than standard warranty extensions.
- Manufacturing:General fabrication shops prioritize standard-system pricing and modular upgrade paths.
Automotive OEMs dominate capital deployment; aerospace MRO shows the steepest technology upgrade intensity.
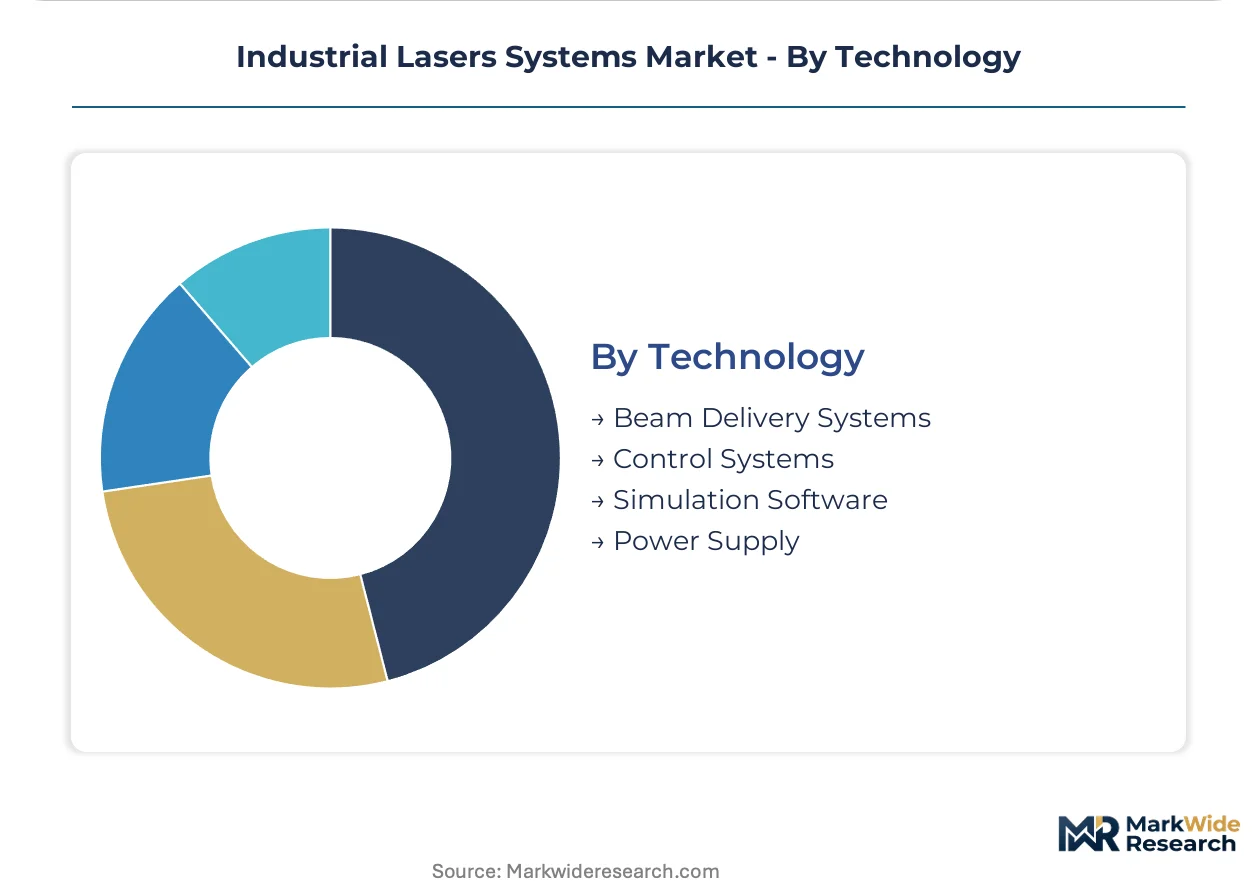
Technology:
Supply concentration in semiconductor laser diodes shapes margin distribution across technology layers.
- Beam Delivery Systems:Multi-axis robotic integration and real-time adaptive optics expand addressable tasks in complex geometries. Fiber-to-robot collimator redesigns for legacy gantry retrofits are fragmenting engineering resources at integration houses.
- Control Systems:Real-time process monitoring and adaptive parameter adjustment maintain quality across varying material thicknesses and surface conditions.
- Simulation Software:Physics-based modeling predicts thermal distortion and melt pool dynamics prior to physical prototyping.
- Power Supply:Kilowatt-class pump diode stacks represent 35-40% of fiber laser bill-of-materials, constraining margin expansion at volume tiers.
Beam delivery systems capture the fastest share gains; power supply costs constrain platform profitability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in laser diode components and rare-earth processing capacity are redistributing manufacturing footprints across major industrial economies. Germany, China, the United States, Japan, and India each exhibit distinct supply chain configurations that shape equipment availability and pricing trajectories.
Germany
Automotive OEM demand from Stuttgart and Munich corridors sustains dense service networks for high-power fiber installations. EU F-Gas Regulation refrigerant phase-outs compress replacement cycles for legacy CO2 systems in Baden-Württemberg stamping plants. The Stuttgart-Munich manufacturing belt absorbs 12-18 month thermal management redesign cycles as OEMs certify closed-loop chiller architectures.
China
Provincial energy intensity targets in Jiangsu and Guangdong force 2015-vintage CO2 system replacements with wall-plug-efficient fiber alternatives. SAMR-administered GB standards for industrial equipment safety and electromagnetic compatibility shape product access. Ytterbium and neodymium fiber dopant processing concentration in Chinese supply chains exposes resonator manufacturers to export quota volatility.
United States
OSHA-enforced permissible exposure limits on laser radiation compel OEMs to integrate interlocked enclosures and automated shutoff protocols in manufacturing environments. Medical device manufacturers in Minnesota specify ultrafast pulse widths for stent cutting applications. The FDA regulates laser-based medical equipment, creating dual compliance burdens for cross-border suppliers.
Japan
METI industrial policy supports precision manufacturing equipment exports while domestic automotive production sustains fiber laser demand. JIS standards govern equipment safety certifications for industrial laser systems. Nagoya-area automotive component suppliers maintain legacy solid-state installations for reflective metal spot welding.
India
PLI scheme disbursements for high-grade automotive and electrical steel prime greenfield laser cutting capacity in Gujarat and Maharashtra. BIS certification requirements extend product launch timelines for imported equipment. Contract manufacturers in Pune and Ahmedabad negotiate performance-based uptime guarantees rather than standard warranty extensions.
Industrial Lasers Systems Market Key Industry Players
Concentration sits with vertically integrated resonator manufacturers and captive diode producers who control 35-40% of fiber laser bill-of-materials. The vendor base stratifies across three tiers: premium specialists with in-house component production, mid-scale system integrators sourcing resonators externally, and volume-tier assemblers competing on standard-system pricing. Two dominant competitive moves define current positioning: backward integration into semiconductor laser diode manufacturing and geographic expansion through localized service network deployment.
Among German- and US-based equipment fabricators, TRUMPF Group and IPG Photonics Corporation exemplify the vertically integrated archetype through captive control over critical resonator and pump diode supply chains. Han's Laser Technology Industry Group Co., Ltd. occupies a position within the volume-tier segment, competing aggressively on standard-system pricing in Asia-Pacific electronics contract manufacturing. These three anchors illustrate how supply chain configuration determines margin sustainability across divergent competitive strategies.
| Leading Market Players |
|---|
| TRUMPF Group |
| IPG Photonics Corporation |
| Coherent |
| Han's Laser Technology Industry Group Co., Ltd. |
| Jenoptik AG |
| LUMIBIRD |
| NKT Photonics |
| Lumentum Holdings |
| Newport Corporation |
| Others |
Cost & Logistics Intelligence
Fiber laser diode stacks replacing legacy CO2 pump modules are redrawing supply geography toward Chinese rare-earth processing corridors while compressing pricing power at volume tiers. This substitution dynamic forces OEMs to absorb ytterbium dopant quota volatility into contract structures or captive sourcing investments.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade—CE-marked systems for EU automotive corridors command 15-20% premiums over BIS-certified equivalents for Indian PLI steel projects—and after-sales bundling density. Cost compression in economy-tier fiber platforms is intensifying because Han's Laser and volume-tier assemblers compete aggressively on standard-system pricing. Contract manufacturers in Shenzhen and Penang exhibit highest price sensitivity, while Stuttgart-Munich automotive OEMs prioritize uptime guarantees over capital cost.
Supply Chain Analysis
Inventory cycles for kilowatt-class pump diode stacks now stretch 16-24 weeks as foundry capacity concentrates in China, Germany, and the United States. Ytterbium and neodymium fiber dopants, gallium arsenide wafer substrates, and precision optical coatings feed resonator manufacturing. Single-source vulnerability in Chinese rare-earth processing exposes resonator manufacturers to export quota disruptions. Distribution runs through captive OEM service networks in Baden-Württemberg and Bavaria, with independent integrators capturing aftermarket maintenance in Asia-Pacific electronics manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as automotive OEMs in the Stuttgart-Munich corridor consolidate procurement across fewer Tier-1 system integrators, squeezing margin pools at mid-scale equipment fabricators.
For Market Incumbents: Secure captive diode manufacturing capacity or long-term offtake agreements with Chinese rare-earth processors to insulate against ytterbium quota volatility. Reinforce service network density in Germany's automotive manufacturing belt where 24/7 uptime guarantees lock out independent integrators. Prioritize CE marking and EU F-Gas Regulation compliance investments to defend premium positioning against volume-tier competitors. For New Entrants and Emerging Players: Aftermarket diode replacement and predictive maintenance services represent underserved white space where incumbents bundle capital equipment with mandatory service contracts. Target India's PLI steel corridors in Gujarat and Maharashtra where greenfield laser cutting capacity lacks established service relationships. Lead with performance-based uptime guarantees rather than equipment-only pricing to differentiate from legacy OEMs. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale beam delivery specialists with adaptive optics IP and established relationships with six-axis cobot manufacturers. Long-term viability favors vendors controlling fiber-to-robot collimator redesign capabilities as legacy CO2 retrofit demand accelerates. Watch for inflection when EU F-Gas Regulation enforcement tightens replacement timelines for refrigerant-dependent resonator cooling systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diode Manufacturing | Captive pump diode production insulates TRUMPF and IPG Photonics from Chinese rare-earth quota volatility. |
| Adaptive Optics-Robotics Convergence | Real-time beam steering with six-axis cobot arms opens aerospace MRO refurbishment tasks in Nadcap facilities. |
| EU F-Gas Compliance Certification | CE-marked closed-loop chiller designs maintain access to German automotive stamping plants facing refrigerant phase-outs. |
| India PLI Corridor Localization | Gujarat and Maharashtra service networks capture greenfield specialty steel laser cutting capacity. |
| Outcome-Based Service Contracting | Performance uptime guarantees displace standard warranties in Shenzhen and Penang electronics contract manufacturing. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and equipment safety certifications. Interviews with plant engineers at German automotive OEMs, procurement leads at Chinese gigafactory operators, aftermarket service heads at European integration houses, and resonator manufacturing directors informed demand-side and supply-side dynamics. Secondary validation drew from OSHA enforcement records, EU Machinery Directive CE marking databases, SAMR GB standard registrations, and SEC 10-K disclosures from listed laser equipment manufacturers. Bottom-up installation counts triangulate against top-down market sizing across product type, application, and end-user verticals.
Segmentation dimensions modeled include product type architecture, application specificity, end-user vertical certification requirements, and technology layer value capture. CAGRs derive from regression analysis of historical installation data, equipment replacement cycle assumptions, and regulatory-driven substitution elasticities across the projection horizon. Fiber laser efficiency curves, CO2 system phase-out timelines under EU F-Gas Regulation, and rare-earth export quota elasticity inform growth trajectory boundaries.
Underlying assumptions cover stable rare-earth processing capacity in China, continued EU F-Gas Regulation enforcement stringency, and automotive OEM consolidation in Baden-Württemberg and Bavaria, with deviation risk concentrated in export quota disruptions and refrigerant transition technology delays. Revision becomes warranted when ytterbium dopant availability or EU regulatory enforcement intensity crosses thresholds that alter equipment replacement economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Global Twister Winder Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
Global Special Purpose Machines Market
Industrial Equipment
Laser Marking Equipment Market
Industrial Equipment
Fiber Laser Coding System Market
Industrial Equipment
Washdown Scales Market
Industrial Equipment
North America Fans and Blowers Market
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
Industrial Tags Market
Industrial Equipment
Sorter Machines Market
Industrial Equipment
Dynamic Scales Market
Industrial Equipment
Chemical Storage Tank and Bottle for Semiconductor Market
Industrial Equipment
Spot Curing System Market
Industrial Equipment
CO2 Laser Market
Industrial Equipment
Pin Marking Machine Market
Industrial Equipment
North America Industrial Embedded Systems Market