
 Laser Processing Market | 2026-2036
Laser Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Processing Market Intelligence
Production capacity for high-power fiber laser components is shifting towards a more concentrated group of specialized manufacturers. IPG Photonics Corporation dominates the high-power fiber laser segment through its significant in-house production of critical components. TRUMPF Group competes with a diversified portfolio spanning multiple laser technologies and machine tools. Coherent Corp. leverages its broad photonics expertise to serve diverse end-markets from electronics to life sciences.
Laser processing involves using a focused beam of high-intensity light, often from sources like fiber or CO2 lasers, to modify materials. The process precisely delivers thermal energy for applications requiring high accuracy and minimal heat-affected zones. Fiber laser technology continues to displace older CO2 and Nd:YAG systems in cutting and welding applications due to higher efficiency. The automotive manufacturing and electronics sectors represent major demand centers, while medical device fabrication shows significant growth potential.
Product safety and performance standards are governed by frameworks like CE marking in Europe and specific IEC standards for laser equipment. In the United States, the FDA's Center for Devices and Radiological Health (CDRH) regulates laser products to control radiation hazards. Navigating these varied international safety classifications and performance requirements remains a critical task for equipment manufacturers seeking market access.
Market Dynamics
The proliferation of high-power fiber lasers and ultrafast pulse systems is the central force shaping the market. This technological shift is displacing legacy CO2 systems and enabling new capabilities in high-precision micro-machining and medical device fabrication.
Growth Catalysts
- Ultrafast Pulse Lasers:Proliferation in medical device manufacturing enables intricate features on implants and surgical tools with minimal thermal damage.
- Advanced Automotive Manufacturing:Demand from Germany's automotive sector for high-power fiber lasers accelerates lightweighting through the welding of advanced materials.
- Government Initiatives:China's support for the new energy vehicle industry stimulates investment in laser systems for battery production.
Market Restraints
- High Capital Outlay:The initial investment for multi-kilowatt fiber laser systems is a significant barrier for small and medium-sized enterprises.
- Regulatory Fragmentation:Navigating divergent safety standards, like the US CDRH and EU CE marking, increases compliance costs for manufacturers.
- Material Processing Challenges:Processing highly reflective materials like copper remains technically difficult, requiring specialized optics and limiting adoption in some electronics applications.
Strategic Opportunities
- Emerging Applications:Micromachining glass and sapphire for consumer electronics, including smartphone displays and camera components, presents a growth vector.
- Geographic Expansion:India’s growing electronics and medical device sectors represent underpenetrated markets for laser cutting and welding systems.
- AI Integration:Combining laser systems with AI-driven machine vision for in-process monitoring enables a shift towards smart manufacturing.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of technicians and application engineers qualified to operate and service sophisticated laser processing equipment constrains growth.
- Compliance Timelines:Obtaining certifications for medical devices produced with laser technology, particularly under the EU's stringent Medical Device Regulation (MDR), is a lengthy process.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Processing Market |
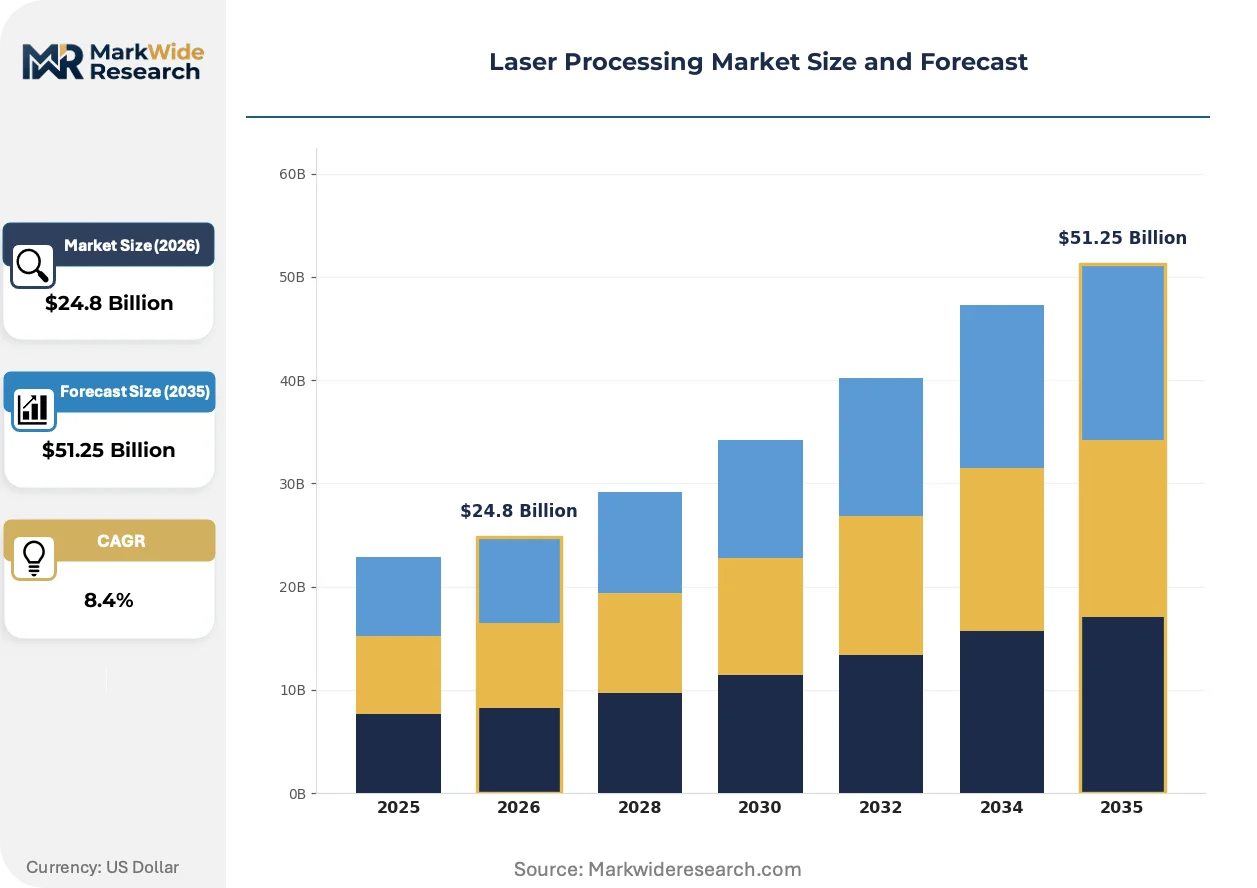
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cutting, Drilling, Marking, Engraving Application: Aerospace, Automotive Manufacturing, Electronics, Medical Devices Technology: Fiber Laser, CO2 Laser, Nd:YAG Laser, Disk Laser End User: Manufacturers, Research Institutes, Automotive OEMs, Tier-1 Suppliers |
| Companies Covered | Lumentum Operations LLC, Laserline GmbH, IPG Photonics Corporation, Finisar, Civan Advanced Technologies Ltd., TRUMPF Group, Jenoptik AG, QPC Lasers, Coherent Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Processing Market Strategic Shifts & Innovations
The market is defined by a push towards intelligent automation and greater process control. This evolution moves beyond raw power, emphasizing real-time feedback and adaptive capabilities to meet demands from advanced manufacturing sectors.
Adaptive beam shaping technology allows for dynamic, real-time modification of the laser spot size and intensity profile. High-volume electronics and battery manufacturers are adopting this technology to optimize welding and cutting processes for dissimilar materials. This capability is automating process parameter adjustments, reducing the need for manual setup and improving yield.
Stricter material traceability mandates, such as those within the European Union's Medical Device Regulation (MDR), are influencing manufacturing processes. This forces medical device fabricators to implement robust data logging for every laser-processed component. The implantable device segment is most affected, investing heavily in validated software and control systems to ensure compliance.
A notable shift is occurring from purchasing standard laser machines to procuring fully integrated, application-specific processing solutions. This trend disrupts the model of selling standalone laser sources, favoring suppliers who offer complete systems with material handling and software. The aerospace industry, with its complex part geometries and stringent certification needs, is at the forefront of this behavioral change.
Laser Processing Market Segmentation
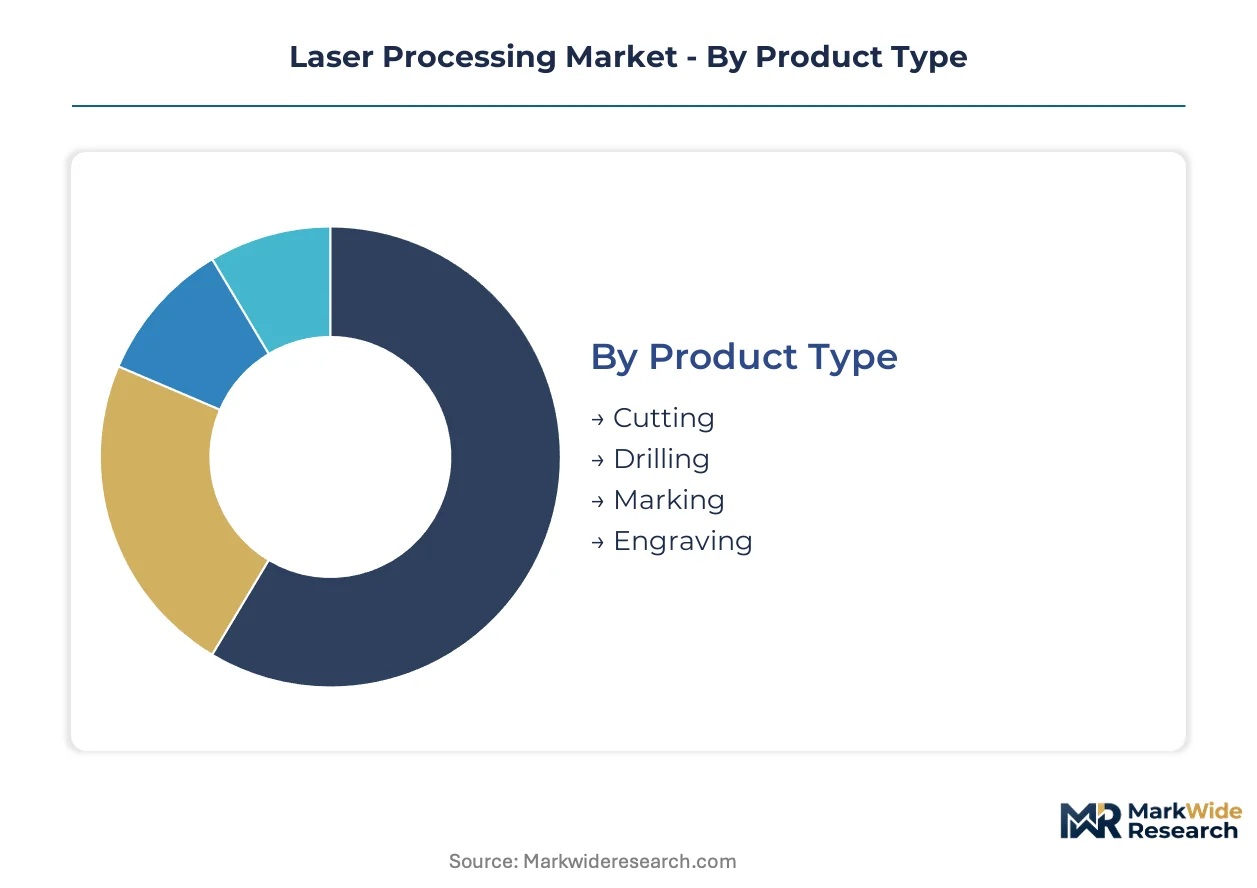
The laser processing market's functional segmentation reveals distinct operational areas where laser technology delivers specialized value. Understanding these segmentations helps manufacturers align product development with specific industry needs and regulatory frameworks. Each category highlights unique demands and technological requirements across the global industrial landscape.
Product Type:
The supply of specialized laser processing equipment often concentrates around specific product functionalities, reflecting the technical expertise required for each application.
- Cutting:Fiber lasers efficiently sever materials, enabling precise contours and minimal material waste in automotive and aerospace manufacturing. Demand for high-speed laser cutting is significant in Germany's advanced manufacturing sector for new energy vehicle components.
- Marking:This process creates permanent, high-contrast identifiers on surfaces without material removal, critical for traceability in medical devices and electronics. India's growing medical device sector requires robust laser marking systems to meet stringent quality standards.
- Drilling:Laser drilling creates fine holes with high aspect ratios, used in semiconductor fabrication and turbine engine components.
- Engraving:Laser engraving removes material to create recessed designs, employed for aesthetic finishes and functional text on industrial parts.
Today's leader: Cutting. Tomorrow's challenger: Marking.
Application:
Volume considerations heavily influence the deployment of laser processing solutions across various industrial applications.
- Automotive Manufacturing:Lasers weld advanced materials for lightweighting and fabricate battery components, driven by demand from Germany's automotive industry. China's new energy vehicle initiatives further stimulate investment in these systems.
- Medical Devices:High-precision lasers create intricate features on implants and surgical tools, ensuring biocompatibility and minimal thermal damage. The EU's MDR mandates robust data logging for laser-processed components in this sector.
- Aerospace:Laser processing fabricates complex parts from superalloys, crucial for turbine components and airframe structures.
- Electronics:Lasers perform micro-machining of delicate components, including glass and sapphire for smartphone displays.
Automotive Manufacturing currently represents the largest volume, while Medical Devices exhibit the steepest expansion trajectory.
Technology:
The maturity level of laser technologies dictates their widespread industrial adoption and integration into existing manufacturing workflows.
- Fiber Laser:These highly efficient solid-state lasers offer superior beam quality and are displacing older systems in cutting and welding applications. IPG Photonics Corporation dominates component supply for high-power fiber lasers.
- CO2 Laser:Older gas-based systems remain prevalent for processing non-metals like plastics and wood, though their market share is declining in metal applications. TRUMPF Group offers a diversified portfolio including CO2 laser technologies.
- Nd:YAG Laser:These solid-state lasers are used for precision spot welding and drilling, particularly in medical device fabrication.
- Disk Laser:Disk lasers provide high power and good beam quality, finding applications in heavy industrial welding and cladding.
Fiber Laser technology steadily displaces legacy CO2 systems, reflecting an industry-wide shift towards higher efficiency.
End User:
Diverse customer types drive specific requirements for laser processing equipment, influencing product configurations and service offerings.
- Manufacturers:This broad category encompasses various industries adopting laser processing for production, from electronics to general fabrication. Small and medium-sized enterprises face high capital outlays for multi-kilowatt fiber laser systems.
- Research Institutes:These organizations utilize laser systems for material science studies, prototyping, and developing new processing techniques.
- Automotive OEMs:Original Equipment Manufacturers integrate laser systems directly into their production lines for vehicle body welding and battery component assembly. Germany's advanced automotive industry represents a major demand center.
- Tier-1 Suppliers:These companies provide components and sub-assemblies to OEMs, using laser processing for precision parts and assemblies.
Manufacturers represent the broadest demand base, while Automotive OEMs drive significant investment in advanced systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence in product safety standards drives strategic manufacturing location decisions for laser processing equipment. Compliance costs, particularly for medical devices, influence where specialized laser processing systems are deployed. This creates a cost-of-compliance gap across different national markets, favoring regions with streamlined regulatory pathways.
Germany
Demand for high-power fiber lasers accelerates lightweighting applications within Germany's automotive sector. The KBA oversees vehicle safety, impacting laser welding processes for structural components in vehicle manufacturing. Stuttgart and Munich host advanced manufacturing clusters, integrating laser systems for sophisticated production lines.
China
China's new energy vehicle industry stimulates substantial investment in laser systems for battery production. The MIIT promotes industrial modernization, including advanced laser manufacturing technologies across various sectors. The Yangtze River Delta region drives adoption of high-speed laser cutting for automotive components and electronics.
India
India's growing electronics and medical device sectors represent underpenetrated markets for laser processing systems. The BIS sets product standards, influencing laser marking requirements for traceability in critical components. Bengaluru's tech hub and Chennai's manufacturing base seek advanced laser solutions for precision fabrication.
United States
Precision manufacturing for medical devices and aerospace components drives demand for ultrafast pulse lasers in the United States. The FDA's Center for Devices and Radiological Health (CDRH) regulates laser products, ensuring radiation hazard control for market access. Silicon Valley and Boston's biotech corridors utilize micro-machining for intricate medical implants and diagnostic tools.
Laser Processing Market Key Industry Players
Germany-based industrial equipment producers anchor one tier; specialized photonics firms across the United States and Europe hold another. The market exhibits a tiered structure, with a few large integrated players alongside numerous niche specialists. Key strategic archetypes include diversified industrial conglomerates and focused laser source manufacturers. Companies are pursuing both portfolio diversification and strategic partnerships to expand market reach.
Within the diversified industrial conglomerate archetype, TRUMPF Group (GmbH) and Coherent Corp. exemplify broad technology portfolios spanning multiple laser applications. IPG Photonics Corporation, a leading fiber laser specialist, sits within the focused laser source manufacturer segment. These companies anchor market segments through their distinct technological offerings and market approaches.
| Leading Market Players |
|---|
| Lumentum Operations LLC |
| Laserline GmbH |
| IPG Photonics Corporation |
| Finisar |
| Civan Advanced Technologies Ltd. |
| TRUMPF Group |
| Jenoptik AG |
| QPC Lasers |
| Coherent Corp. |
| Others |
Cost & Logistics Intelligence
Stricter material traceability mandates within the European Union's Medical Device Regulation (MDR) compel laser processing equipment suppliers to integrate robust data logging, influencing system pricing. This regulatory pressure drives investment in validated software, impacting overall market costs.
Pricing Analysis
Direct-to-OEM discounts are common for large volume contracts in the laser processing market. Pricing stratifies across premium, standard, and economy tiers, often reflecting customization levels, comprehensive after-sales service, and critical certification levels like CE marking or FDA CDRH compliance. Pricing pressure stems from the ongoing displacement of legacy CO2 systems by more efficient fiber laser technology. Small and medium-sized enterprises exhibit higher price sensitivity compared to Automotive OEMs, who prioritize integrated, high-performance solutions.
Supply Chain Analysis
Regional distribution centers facilitate the delivery of complex laser systems to key industrial clusters. Supply concentration for high-power fiber laser components primarily centers on the United States and Germany. The market draws from specialized optics and critical laser components, with IPG Photonics Corporation dominating in-house production. Single-source vulnerability for these advanced components represents a structural risk. Distribution runs through direct sales channels to large Automotive OEMs and specialized system integrators for diverse end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The laser processing market functions as a regulatory compounder, with the European Union's Medical Device Regulation (MDR) driving significant investment in compliant manufacturing solutions. This regulation mandates robust data logging, increasing demand for advanced laser systems.
For Market Incumbents: Lock in long-term contracts with major Automotive OEMs and Aerospace clients, leveraging existing relationships. Invest heavily in adaptive beam shaping technology to counter emerging ultrafast pulse laser specialists by offering superior process control. Deepen vertical integration into critical component manufacturing to secure supply and maintain cost advantages against diversified competitors. Offer fully integrated, application-specific solutions to address customer demand for complete manufacturing ecosystems.
For New Entrants and Emerging Players: Capture niche segments requiring specialized micromachining capabilities for consumer electronics, particularly glass and sapphire. Target India’s growing electronics and medical device sectors as underpenetrated markets for laser cutting and welding systems. Develop AI-driven machine vision integration for in-process monitoring, offering smart manufacturing solutions. A go-to-market angle focusing on modular, cost-effective ultrafast pulse laser systems for smaller enterprises provides entry.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized photonics firms developing next-generation ultrafast pulse laser systems for high-precision applications. Long-term viability over the next decade remains strong, driven by advanced manufacturing requirements across multiple sectors. Identify acquisition targets offering expertise in adaptive beam shaping technology or AI-integrated machine vision for process control. Increased venture funding rounds for micro-machining startups represents a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Fiber Laser Components | Secures supply for advanced Automotive OEMs and electronics manufacturers. |
| AI Integration with Machine Vision | Enhances process control and yield in high-volume battery production. |
| Geographic Expansion into India | Penetrates under-served markets for medical device fabrication and electronics. |
| Product Diversification into Ultrafast Lasers | Addresses demand for micromachining glass and sapphire in consumer electronics. |
| Investment in CE/FDA Certification Support | Ensures equipment compliance with EU MDR for medical device manufacturers. |
Research Approach
Coverage spans Germany, China, India, and the United States, with primary inputs from each region. This study combines in-depth primary interviews with industry stakeholders and rigorous secondary validation. Key interviewees included Automotive OEM engineers, medical device fabricators, laser equipment R&D directors, and materials scientists. Secondary data sources comprised IEC standards, FDA CDRH reports, KBA vehicle safety guidelines, and MIIT industrial modernization reports. The analysis utilized both bottom-up market sizing and top-down validation for comprehensive triangulation.
Volume and value were modeled at a granular level across product type, application, technology, and end-user segments. This structured analytical framework segmented the market by specific functionalities like cutting and marking, major applications, and core technologies. Compound annual growth rates were derived from historical trends and projected technological adoption rates over the projection horizon. New energy vehicle production forecasts and medical device manufacturing output served as key industry-specific forecast inputs.
Regulatory fragmentation, raw material price volatility, and skilled labor scarcity are the dominant revision risks for market forecasts. These forecasts reflect documented assumptions regarding technological advancements and end-market demand shifts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Contour Measuring Machines Market
Industrial Equipment
United States Ball Bearing Market
Industrial Equipment
Global Laser Material Market
Industrial Equipment
Magnetorheological Finishing (MRF) Machine Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Pin Marking Machine Market
Industrial Equipment
Electro-Pneumatic Systems Market
Industrial Equipment
Parts and Equipment Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Microwave Equipment Market
Industrial Equipment
Soldering Iron Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Dust Extraction System Market
Industrial Equipment
Europe Industrial Centrifuge Market
Industrial Equipment
Global Twister Winder Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market