
 Thermoelectric Refrigerator Market | 2026-2036
Thermoelectric Refrigerator Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoelectric Refrigerator Market Insights
Buyer concentration among pharmaceutical distributors and biotech logistics providers is hardening as vaccine cold chain requirements tighten. Ferrotec Corporation leverages its semiconductor-grade thermoelectric module production to anchor supply relationships with medical OEMs. Laird Thermal Systems competes through specialized thermal management assemblies for portable medical refrigeration. TE Technology Inc. differentiates via custom controller integration that extends system efficiency in variable ambient conditions.
Thermoelectric refrigerators employ solid-state Peltier modules to transfer heat without compressed refrigerants, achieving temperature differentials up to 70°C with no moving parts and minimal maintenance. The medical use application dominates value capture due to stringent temperature stability requirements for biologics and vaccines, while the portable product type records the fastest expansion as field diagnostics and mobile healthcare units multiply. Peltier effect cooling technology occupies the core margin pool because module reliability directly determines system lifespan in critical deployments.
FDA 21 CFR Part 11 validation requirements and EU MDR device classification shape product development pathways for medical-grade thermoelectric units, while EPA SNAP program restrictions on hydrofluorocarbon refrigerants accelerate solid-state substitution in commercial segments. Stakeholders must monitor evolving energy efficiency standards from DOE and IEC 62368-1 safety certifications as these frameworks increasingly dictate market access thresholds for cross-border equipment sales.
Market Dynamics
Europe's F-Gas Regulation is compressing demand for vapor-compression systems and forcing pharmaceutical distributors toward solid-state cooling architectures that eliminate hydrofluorocarbon refrigerants entirely.
Growth Catalysts
- Vaccine cold chain mandates:FDA 21 CFR Part 11 validation requirements and WHO temperature stability protocols are hardening procurement specifications for biologics transport among pharmaceutical distributors.
- F-Gas phase-down schedules:The EU regulation's stepped reduction in HFC quotas is accelerating substitution timelines for medical refrigeration units across German precision manufacturing corridors.
- Bismuth telluride module reliability:Advances in semiconductor-grade thermoelectric materials are extending system lifespans in critical medical deployments where compressor failure risks are unacceptable.
Market Restraints
- Input material concentration:Bismuth and tellurium refining capacity concentrates in Chinese processing facilities, exposing module manufacturers to supply disruption and price volatility.
- Energy efficiency ceiling:Peltier coefficient of performance remains structurally below vapor-compression alternatives, limiting addressable market share in cost-sensitive commercial segments.
- Substitution by Stirling cryocoolers:Ultra-low temperature biologics storage below -40°C is migrating toward free-piston Stirling systems that achieve deeper cold chains.
Strategic Opportunities
- Indian pharmaceutical logistics:CDSCO cold chain infrastructure requirements and expanding vaccine production capacity are creating first-mover advantages for solid-state refrigeration deployments.
- Portable diagnostic units:Field-deployable PCR and rapid-test platforms are multiplying demand for battery-integrated thermoelectric cooling in mobile healthcare configurations.
- EPA SNAP program expansion:Hydrofluorocarbon restrictions in commercial refrigeration categories are extending addressable market scope beyond medical into food service and retail segments.
Industry Challenges
- Thermal engineering talent scarcity:Design of optimized heat exchanger geometries and controller algorithms for variable ambient conditions requires specialized expertise concentrated in semiconductor thermal management sectors.
- IEC 62368-1 certification timelines:Safety testing for cross-border medical equipment sales involves extended validation cycles that compress product launch windows.
- Legacy system integration friction:Hospital and laboratory facility managers face retrofit complexity when replacing compressor-based units with solid-state alternatives requiring different electrical and spatial configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoelectric Refrigerator Market |
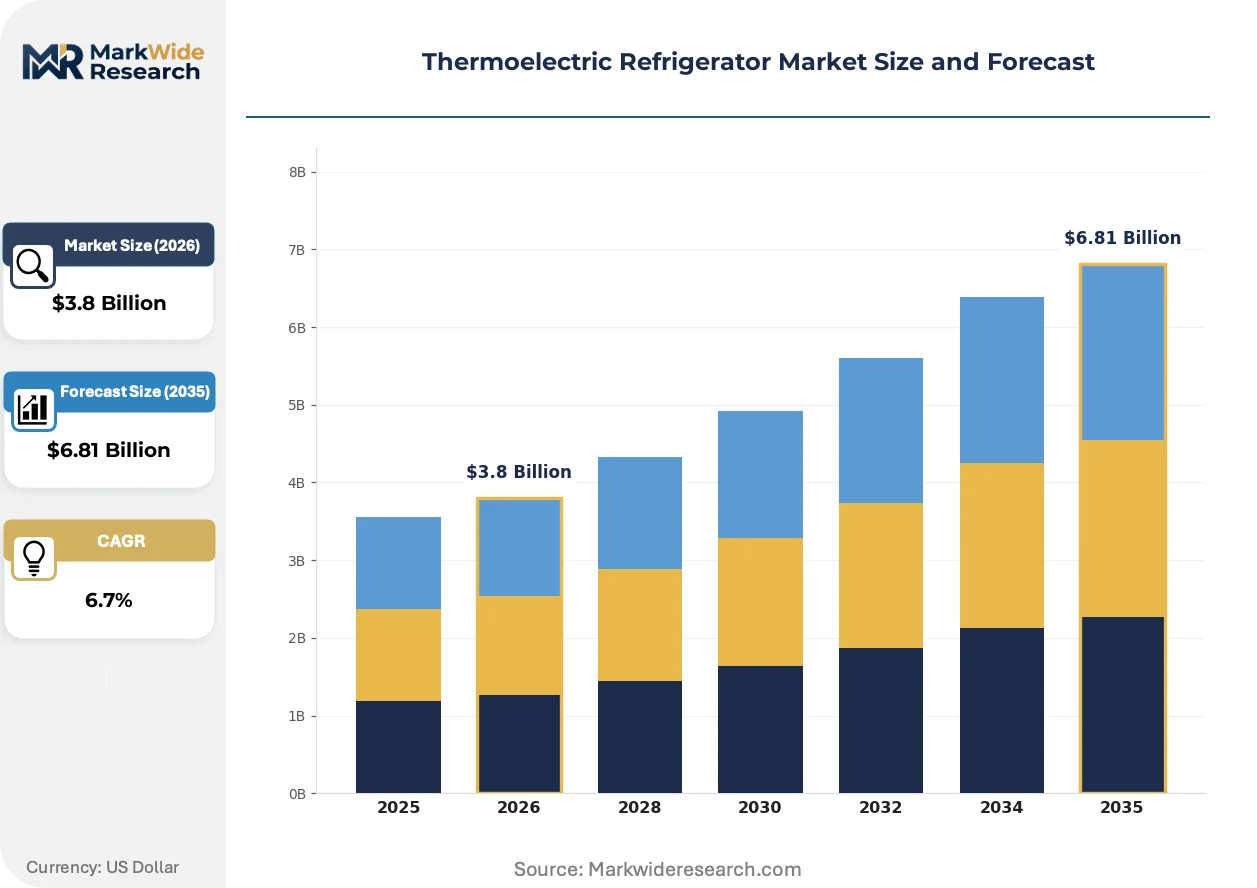
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Mini, Compact, Desktop Application: Food Storage, Medical Use, Automotive Cooling, Scientific Research End User: Consumers, Restaurants, Laboratories, Transport Services Cooling Technology: Peltier Effect, Thermoelectric Modules, Active Refrigeration, Passive Cooling |
| Companies Covered | Ferrotec Corporation, Laird Thermal Systems, TE Technology Inc., II-VI Incorporated, Phononic Inc., Crystal Ltd., Kryotherm Industries, Thermonamic Electronics Corp. Ltd., Xiamen Hicool Electronics Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoelectric Refrigerator Market Trends and Innovations
Solid-state cooling architectures are displacing conventional refrigeration across temperature-sensitive logistics, with module reliability and controller intelligence emerging as the primary axes of product differentiation.
Multi-stage cascaded Peltier modules are expanding into ultra-low temperature biologics storage applications previously dominated by mechanical compression systems. Biotech logistics providers in Germany and Switzerland are adopting these configurations for mRNA vaccine transport at -70°C setpoints. The technology is expanding into addressable market segments that thermoelectric systems could not previously serve.
The EU F-Gas Regulation's stepped HFC quota reductions are forcing equipment manufacturers to eliminate refrigerant-dependent architectures from their medical product portfolios. Compressor OEMs face stranded asset risk as pharmaceutical distributors pre-emptively specify solid-state alternatives. German precision manufacturing clusters are responding fastest, with regulatory compliance timelines compressing product development cycles.
Service contract unbundling is fragmenting traditional equipment-plus-maintenance procurement models in hospital systems. Biotech logistics providers now source thermoelectric modules, controllers, and enclosure assemblies from separate vendors, then integrate in-house. This pattern is most visible in North American academic medical centers and contract research organizations managing decentralized clinical trial supply chains.
Thermoelectric Refrigerator Market Segmentation
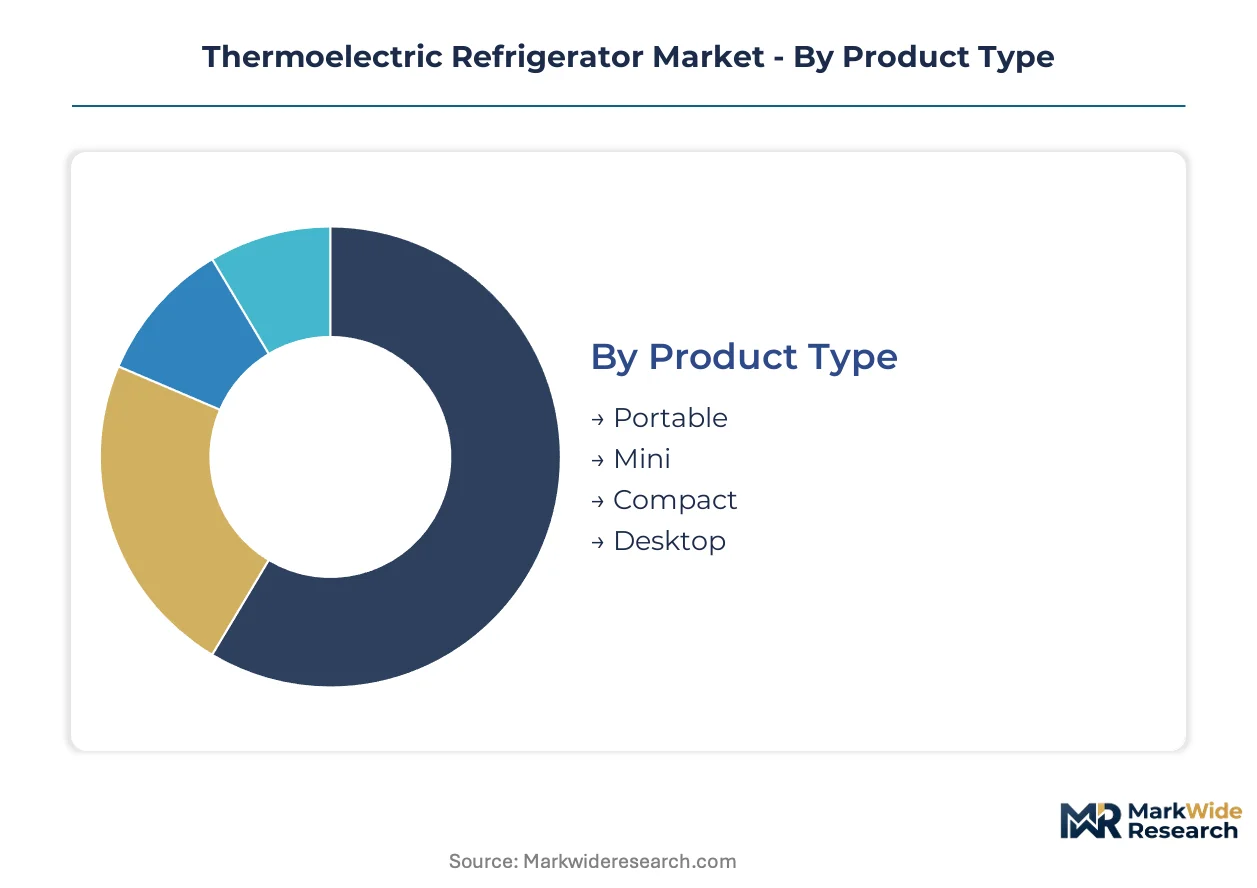
Thermoelectric refrigerator segmentation reflects divergent engineering requirements across mobility constraints, temperature precision demands, and power availability. Procurement patterns fragment sharply between standardized consumer units and heavily customized medical-grade systems with validated cold chain documentation.
Product Type:
Standardization dominates at the compact and mini tiers, while portable configurations demand extensive customization for battery integration and ruggedized enclosures.
- Portable:Battery-integrated units with DC power architectures and shock-resistant housings serve field diagnostics and mobile healthcare deployments. Demand concentrates among biotech logistics providers in Germany's precision manufacturing corridor, where WHO temperature stability protocols mandate validated transport containers for vaccine distribution.
- Mini:Compact thermoelectric modules in sub-20 liter enclosures target countertop medical storage and personal pharmaceutical cooling. Laboratories in Switzerland and academic medical centers in the US specify these for benchtop biologics preservation where space constraints override capacity requirements.
- Compact:Mid-capacity solid-state refrigerators balance thermal performance with footprint efficiency for restaurant back-of-house and small laboratory installations.
- Desktop:Ultra-small form factors integrate directly with analytical instruments and PCR workstations, requiring precise controller calibration for instrument-adjacent thermal stability.
Most installed capacity flows through Compact units. Expansion is steepest in Portable configurations.
Application:
Margin concentration follows regulatory intensity, with medical applications commanding premium pricing for validation documentation and FDA 21 CFR Part 11 compliance.
- Medical Use:Validated cold chain systems for vaccines, biologics, and temperature-sensitive pharmaceuticals employ multi-stage Peltier cascades with redundant temperature logging. German pharmaceutical distributors and Swiss biotech logistics providers anchor procurement volumes as EU MDR device classification tightens quality system requirements.
- Food Storage:Commercial refrigeration in restaurants and retail eliminates hydrofluorocarbon refrigerants through solid-state architectures. EPA SNAP program restrictions on HFCs accelerate substitution in US food service segments.
- Automotive Cooling:Cabin and cargo cooling for electric vehicles leverages thermoelectric efficiency at partial load conditions where compressor cycling wastes energy.
- Scientific Research:Specimen preservation and reagent storage in laboratories demand precise setpoint control with minimal temperature fluctuation.
Medical Use commands the dominant revenue share. Food Storage is gaining share fastest as F-Gas Regulation compliance deadlines approach.
End User:
Procurement sophistication varies dramatically, from price-sensitive consumer purchases to multi-year service contracts with integrated validation support.
- Laboratories:Academic medical centers and contract research organizations specify thermoelectric units with IQ/OQ/PQ documentation for GMP-compliant sample storage. CDSCO cold chain infrastructure requirements in India are creating first-mover procurement opportunities as vaccine production capacity expands.
- Transport Services:Pharmaceutical logistics providers unbundle equipment procurement from service contracts, sourcing modules and controllers separately for in-house integration. This pattern dominates North American decentralized clinical trial supply chains.
- Consumers:Personal medical cooling and cosmetic refrigeration drive volume through retail channels with minimal technical support requirements.
- Restaurants:Commercial kitchen operators prioritize energy efficiency certifications and rapid payback periods over advanced thermal management features.
Laboratories represent the most technically demanding customer base. Transport Services are expanding most quickly as logistics providers internalize integration capabilities.
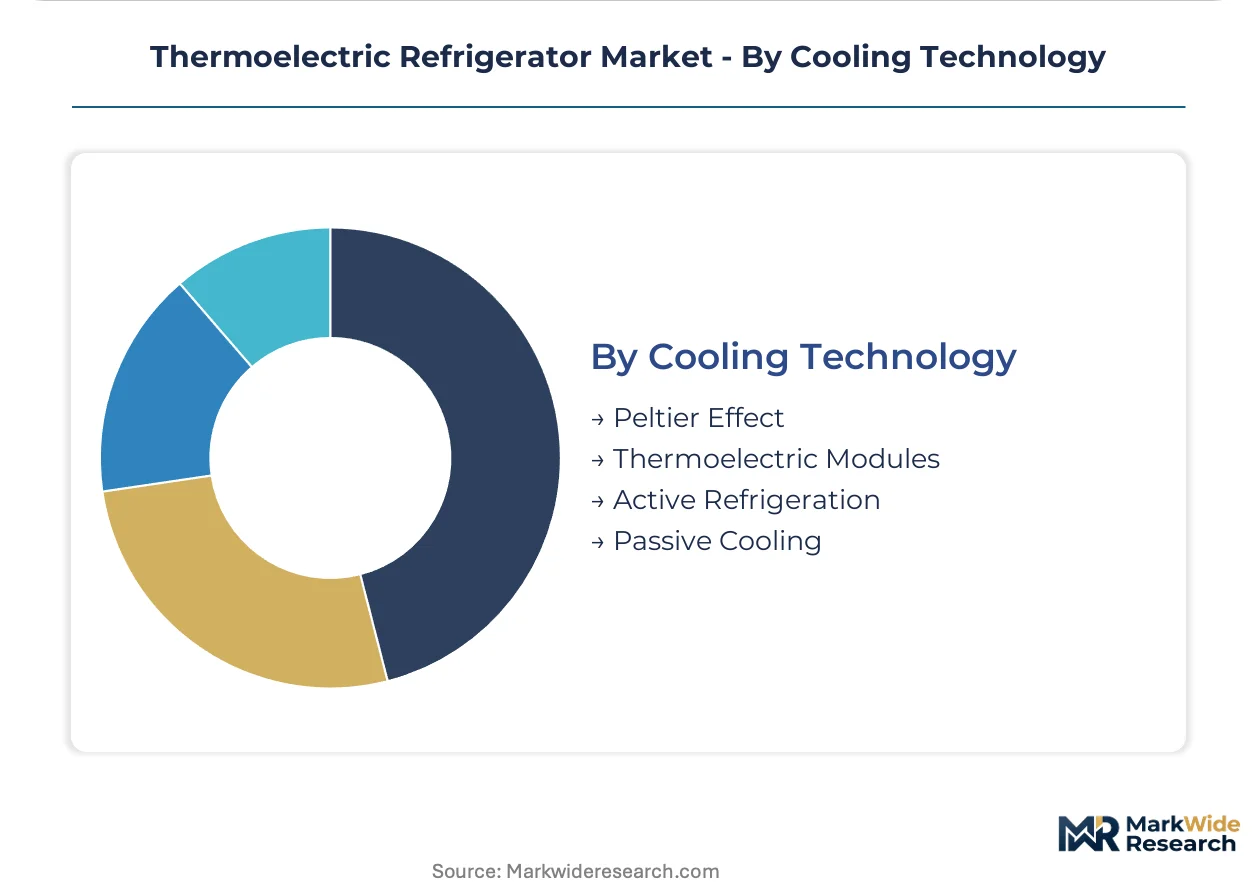
Cooling Technology:
Technology selection determines system efficiency ceiling, maintenance burden, and minimum achievable temperature.
- Peltier Effect:Semiconductor-grade bismuth telluride modules achieve temperature differentials up to 70°C with no moving parts. German precision manufacturing clusters favor these configurations for mRNA vaccine transport at ultra-low setpoints where compressor failure risks are unacceptable.
- Thermoelectric Modules:Multi-stage cascaded arrays extend reachable temperatures below -40°C for biologics storage previously served by mechanical compression.
- Active Refrigeration:Controller-optimized systems with variable power input and adaptive fan speed modulate cooling intensity for ambient temperature variation.
- Passive Cooling:Phase-change materials and insulated enclosures supplement thermoelectric systems for emergency backup and transit applications.
Peltier Effect systems carry the dominant installed base. Thermoelectric Modules are climbing the fastest as ultra-low temperature biologics storage requirements proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision manufacturing corridor drives European adoption of solid-state cooling, while India's vaccine production expansion creates parallel demand corridors for validated cold chain infrastructure.
Germany
Pharmaceutical distributors in Baden-Württemberg and Bavaria specify thermoelectric systems for mRNA vaccine transport at ultra-low temperatures. The F-Gas Regulation's stepped HFC quota reductions compress substitution timelines for medical refrigeration equipment. Stuttgart's precision engineering cluster hosts module integration facilities serving Swiss and Austrian biotech logistics networks.
United States
Academic medical centers and contract research organizations unbundle equipment procurement from service contracts for decentralized clinical trial supply chains. EPA SNAP program restrictions on hydrofluorocarbon refrigerants accelerate solid-state substitution in commercial food service segments. Greater Boston's biotech corridor concentrates demand for portable diagnostic cooling in field-deployable PCR platforms.
India
CDSCO cold chain infrastructure requirements and expanding vaccine production capacity create first-mover procurement opportunities for solid-state refrigeration. The PLI scheme for pharmaceutical manufacturing indirectly supports logistics equipment upgrades. Maharashtra's pharmaceutical manufacturing belt around Mumbai and Pune anchors initial deployments for export-oriented vaccine producers.
Switzerland
Swissmedic device classification requirements and biotech logistics provider concentration drive premium pricing for validated cold chain documentation. Basel's pharmaceutical headquarters cluster sources multi-stage Peltier cascades for temperature-sensitive biologics storage. The country's precision instrument sector generates secondary demand for desktop thermoelectric units integrated with analytical workstations.
China
Bismuth and tellurium refining capacity concentrates in Chinese processing facilities, exposing module manufacturers to supply disruption risks while anchoring upstream material flows. NMPA medical device regulations shape import requirements for foreign equipment manufacturers. Yangtze River Delta electronics manufacturing clusters host thermoelectric module assembly operations serving domestic and export markets.
Thermoelectric Refrigerator Market Competitive Landscape
Japanese and American producers anchor one tier; Chinese fabricators and European specialists hold differentiated positions in module reliability and controller integration respectively. The vendor base distributes across semiconductor-grade material suppliers, thermal management assembly integrators, and custom controller developers. Three archetypes dominate: vertically integrated module manufacturers, specialized thermal assembly providers, and controller-optimization software houses. Capacity expansion in bismuth telluride refining and strategic partnerships between module makers and medical OEMs represent the dominant competitive moves.
Among Japan-anchored material suppliers, Ferrotec Corporation exemplifies the vertically integrated archetype spanning semiconductor-grade thermoelectric production. Laird Thermal Systems occupies a position among thermal management assembly specialists serving portable medical refrigeration configurations. TE Technology Inc. represents the controller-integration tier, with custom algorithm development extending system efficiency across variable ambient conditions. These three companies illustrate the competitive structure without exhausting its participants.
| Leading Market Players |
|---|
| Ferrotec Corporation |
| Laird Thermal Systems |
| TE Technology Inc. |
| II-VI Incorporated |
| Phononic Inc. |
| Crystal Ltd. |
| Kryotherm Industries |
| Thermonamic Electronics Corp. Ltd. |
| Xiamen Hicool Electronics Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Captive bismuth telluride refining in Chinese processing facilities anchors both input cost structures and module manufacturer pricing power, with pharmaceutical distributors absorbing premium tier pricing for validated cold chain documentation while commercial segments face cost compression from efficiency ceilings.
Pricing Analysis
Capacity additions in Yangtze River Delta electronics clusters are reshaping price floors for standard-grade thermoelectric modules. Pricing stratifies across medical-grade FDA-validated systems, industrial-certified configurations, and consumer-tier units with minimal documentation. Cost compression in commercial food storage segments is intensifying because EPA SNAP program restrictions force rapid substitution timelines. Restaurants and retail operators exhibit highest price sensitivity, while biotech logistics providers prioritize reliability premiums over unit economics.
Supply Chain Analysis
Refurbishment flows for failed Peltier modules create secondary material recovery channels that partially offset raw material concentration risks. Bismuth and tellurium refining concentrates in China, with module assembly spreading to South Korea and Japan. German precision manufacturing clusters draw from Asian material flows for medical-grade system integration. Single-source vulnerability in semiconductor-grade thermoelectric materials exposes manufacturers to export restriction risks. Distribution runs through pharmaceutical OEM direct contracts, thermal management assembly specialists, and controller-optimization software houses serving unbundled procurement patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in controller-optimization software and multi-stage cascade architectures, with premium-tier medical validation requirements enabling pricing power that offsets raw material volatility.
For Market Incumbents: Anticipate Stirling cryocooler substitution threats in ultra-low temperature biologics storage below -40°C by deepening controller algorithm development for variable ambient conditions. Secure backward integration into bismuth telluride refining partnerships to reduce Chinese supply concentration exposure. Prioritize IEC 62368-1 certification investments to compress product launch windows against emerging competitors.
For New Entrants and Emerging Players: Enter via Indian pharmaceutical logistics corridors where CDSCO cold chain infrastructure requirements and PLI scheme spillovers create first-mover procurement opportunities for solid-state refrigeration. Target portable diagnostic configurations for field-deployable PCR platforms, where battery-integrated DC architectures demand specialized thermal management assembly capabilities absent from incumbent portfolios.
For Investors and Strategic Acquirers: Roll-up economics work for controller-optimization software specialists because service contract unbundling in North American academic medical centers fragments procurement and creates standalone vendor acquisition targets. Long-term viability hinges on FDA 21 CFR Part 11 validation capabilities and EU MDR device classification expertise. Monitor F-Gas Regulation compliance deadline acceleration as inflection indicator for substitution velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bismuth Telluride Refining | Captive supply from Chinese processing facilities reduces price volatility exposure for module manufacturers. |
| Multi-Stage Peltier Cascade Development | Extends addressable temperature range into mRNA vaccine transport at -70°C setpoints previously served by compression. |
| FDA 21 CFR Part 11 Validation Investment | Enables premium pricing from pharmaceutical distributors requiring documented cold chain compliance for biologics. |
| Controller Algorithm Optimization | Adaptive fan speed and variable power modulation extend system efficiency across variable ambient conditions. |
| Indian Market First-Mover Deployment | CDSCO infrastructure requirements and vaccine production expansion create procurement advantages ahead of competitor entry. |
Research Methodology
Coverage spans Germany, United States, India, Switzerland, and China, with primary inputs from each market cluster combining interviews with biomedical engineers, pharmaceutical logistics procurement managers, thermal management R&D directors, and hospital purchasing committee representatives. Secondary validation draws from FDA 510(k) filings, EU MDR technical documentation, EPA SNAP program rulemakings, and customs trade data for thermoelectric module flows. Bottom-up unit economics and top-down regulatory substitution models triangulate volume and value estimates.
Rate-of-change decomposition separates baseline substitution from regulatory acceleration effects across the projection horizon. Segmentation dimensions modeled include product type mobility constraints, application regulatory intensity, cooling technology temperature reach, and end-user procurement sophistication. CAGRs derive from fitted adoption curves calibrated to F-Gas Regulation phase-down schedules and WHO temperature stability protocol enforcement intensity. Industry-specific inputs incorporate bismuth telluride module reliability testing data and controller efficiency benchmarks.
The model holds under continued F-Gas Regulation enforcement and stable semiconductor-grade material supply; deviation in Chinese export restrictions or Stirling cryocooler cost curves would shift substitution timelines. Forecasts reflect documented assumptions about regulatory compliance deadlines and technology performance ceilings. Practitioners should monitor EPA SNAP program expansion scope and NMPA medical device import requirements for early signals of addressable market boundary shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Asia-Pacific Industrial Centrifuge Market
Industrial Equipment
North America Industrial Centrifuge Market
Industrial Equipment
Global Safety Relays and Timers Market
Industrial Equipment
Battery Power Tools Market
Industrial Equipment
Compositing Equipment Market
Industrial Equipment
Global Temperature Control Units (TCU) Market
Industrial Equipment
Industrial Tags Market
Industrial Equipment
Global Refrigeration Compressor Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Global Strain Wave Gearing Devices Market
Industrial Equipment
Global Industrial Centrifuges Market
Industrial Equipment
Machine Mounts Market
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Grading and Batching Systems Market
Industrial Equipment
Laser Drilling Market
Industrial Equipment
Fluid Dispensing Equipment Market