
 Asia Pacific Industrial Embedded Systems Market | 2026-2036
Asia Pacific Industrial Embedded Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Industrial Embedded Systems Market Insights
China's GB standards for industrial control equipment safety is repositioning the cost-of-entry calculus for foreign module suppliers seeking factory automation contracts. Advantech Co Ltd leverages its Taiwan-based manufacturing scale to dominate edge computing gateway shipments across the region. STMicroelectronics N.V. specializes in automotive-grade microcontrollers that anchor powertrain control modules for Japanese and Korean OEMs. Infineon Technologies competes through in-house silicon carbide expertise that extends its reach into motor drive applications.
Industrial embedded systems integrate dedicated microprocessors, real-time operating systems, and deterministic I/O interfaces into purpose-built computing platforms rated for extended temperature ranges, shock resistance, and continuous operation. These systems execute control algorithms, data acquisition protocols, and machine-to-machine communication functions in environments where consumer-grade hardware fails. Microcontrollers and SoCs capture the largest value pools given their ubiquity across programmable logic controllers and human-machine interfaces, while FPGAs serve high-growth niches in adaptive robotics and machine vision where reconfigurable logic outperforms fixed architectures. Edge Computing and Real-Time Processing technologies are gaining fastest adoption as manufacturers push latency-critical analytics closer to production equipment.
Japan's METI enforces JIS standards for factory automation interoperability, while China's MEE and MIIT layer environmental compliance atop GB equipment safety rules, collectively raising the certification burden for component vendors. South Korea's MFDS and KOSHA frameworks add occupational safety dimensions to semiconductor packaging and module assembly requirements. Stakeholders must track which regulatory convergence patterns between Chinese GB harmonization and Japanese JIS refinement will determine the next generation of cross-border platform compatibility standards.
Market Dynamics
Smart factory retrofits across China's eastern manufacturing belt are compressing replacement cycles for legacy PLCs and HMIs, forcing semiconductor vendors to accelerate ruggedized controller roadmaps while navigating divergent certification requirements across Japanese JIS and Chinese GB standards.
Growth Catalysts
- MIIT Dual Carbon Goals:China's Ministry of Industry and Information Technology mandates are accelerating energy-efficient equipment replacement across steel, cement, and chemical process industries, driving demand for low-power microcontrollers and motor control SoCs.
- Edge Computing Hardware:Deterministic latency requirements for predictive maintenance and quality inspection are pulling GPU-accelerated edge gateways into automotive and electronics assembly lines throughout South Korea and Taiwan.
- Taiwan Semiconductor Cluster:Concentrated advanced packaging capacity for industrial-grade SoCs reduces lead times for Japanese and Korean automation OEMs sourcing automotive-qualified silicon.
Market Restraints
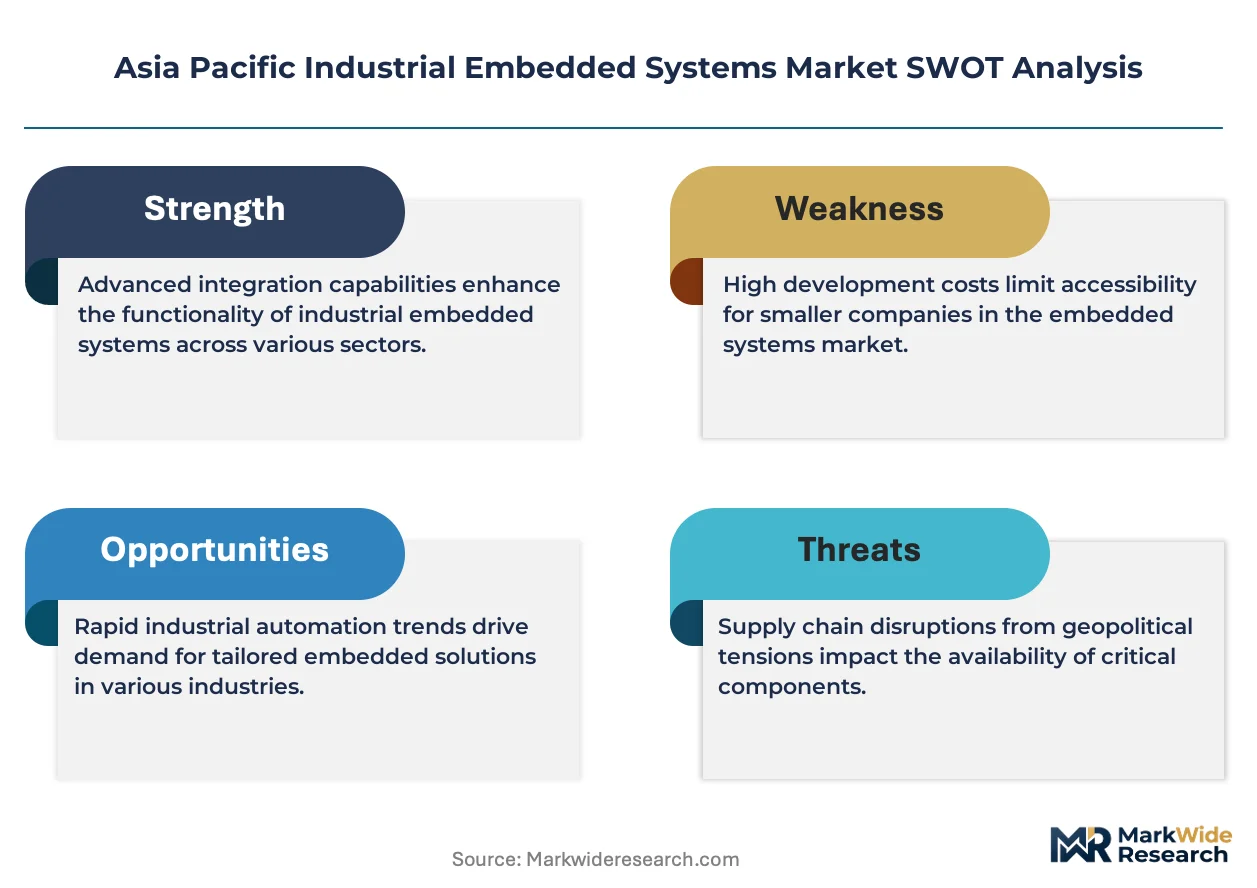
- Silicon Carbide Substrate Costs:Wide-bandgap power semiconductors for motor drives remain 3-4x more expensive than silicon IGBTs, limiting penetration in cost-sensitive Chinese machinery builders despite efficiency gains.
- Japanese JIS Certification Burden:Factory automation interoperability standards require extensive third-party testing cycles that extend time-to-revenue for foreign module suppliers by 8-14 months.
- Legacy PLC Protocol Lock-in:Proprietary fieldbus architectures from established Japanese and European vendors create switching friction that slows adoption of open-standards embedded platforms.
Strategic Opportunities
- Vietnam Manufacturing Expansion:Electronics contract manufacturers relocating from China are importing complete automation lines, creating greenfield demand for embedded control systems without legacy replacement constraints.
- AI Inference at the Edge:Convergence of time-sensitive networking with neural network accelerators enables real-time defect detection in semiconductor wafer fabrication, opening premium pricing tiers for vision-optimized SoCs.
- India PLI Scheme for Electronics:Production-linked incentives for mobile phone and component manufacturing are attracting Foxconn and Dixon to establish automated SMT lines requiring industrial embedded controllers.
Industry Challenges
- Embedded Firmware Talent Scarcity:Real-time operating system expertise and safety-critical coding practices are concentrated among aging engineer cohorts in Japan and Taiwan, constraining vendor expansion.
- Cross-Border Standards Harmonization:Divergent electromagnetic compatibility testing between China's GB/T and Japan's JIS C frameworks forces redundant certification spend for multi-country deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Industrial Embedded Systems Market |
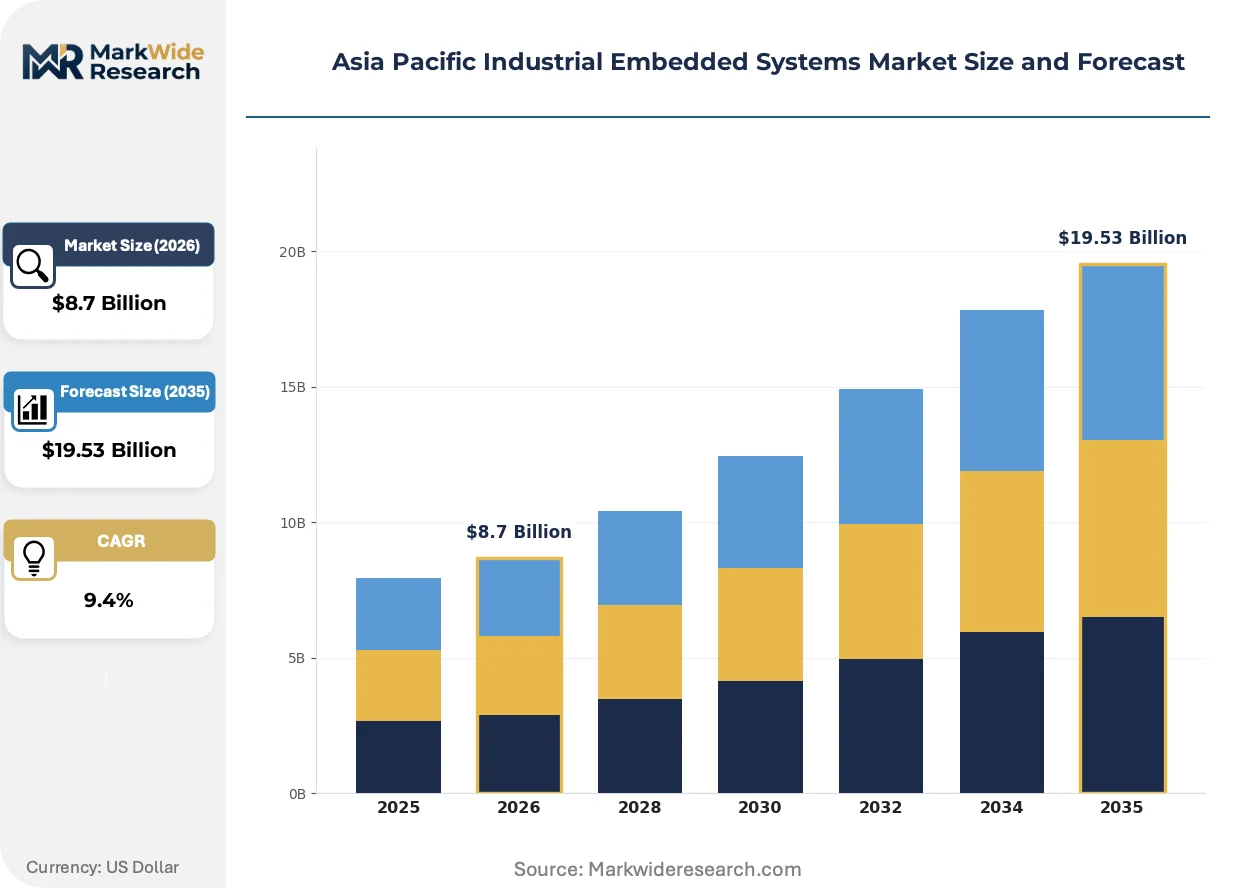
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, DSPs, FPGAs, SoCs Application: Manufacturing Automation, Robotics, Process Control, Energy Management End User: Aerospace, Automotive, Healthcare, Telecommunications Technology: IoT, AI, Real-Time Processing, Edge Computing |
| Companies Covered | Analog Devices Inc, STMicroelectronics N.V., Infineon Technologies, NXP Semiconductors, Renesas Electronics, Intel Corporation, Microchip Technology Inc, Texas Instruments Inc, Advantech Co Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Industrial Embedded Systems Market Trends and Innovations
Deterministic edge analytics and silicon carbide power integration are compressing the traditional boundary between control systems and power electronics, while regulatory pressure on embodied carbon accelerates modular hardware architectures designed for component-level upgrade rather than full-system replacement.
Silicon carbide MOSFETs paired with intelligent gate drivers are electrifying motor control architectures in Japanese robotics and Korean EV battery manufacturing equipment. Fanuc and Hyundai Heavy Industries are qualifying 1,200V SiC modules for spindle drives and conveyor systems. This electrification is collapsing the historical separation between power conversion and motion control into unified embedded platforms.
METI's 2024 amendments to JIS B 3502 safety standards for programmable controllers mandate functional safety certifications equivalent to IEC 61508 SIL 2 for new factory automation deployments. Japanese automotive tier-1s are now requiring SIL-capable microcontrollers from Renesas and Toshiba for welding and painting robots. Korean semiconductor fabs are adopting identical safety architectures to maintain equipment interoperability with Japanese tool suppliers.
Chinese machinery builders are unbundling hardware procurement from software integration services, treating embedded controllers as commodity inputs while retaining system integration in-house. This pattern is most visible in Guangdong province's electronics assembly sector, where OEMs now source STM32 and NXP microcontrollers through distributors rather than accepting turnkey solutions from automation vendors.
Asia Pacific Industrial Embedded Systems Market Segmentation
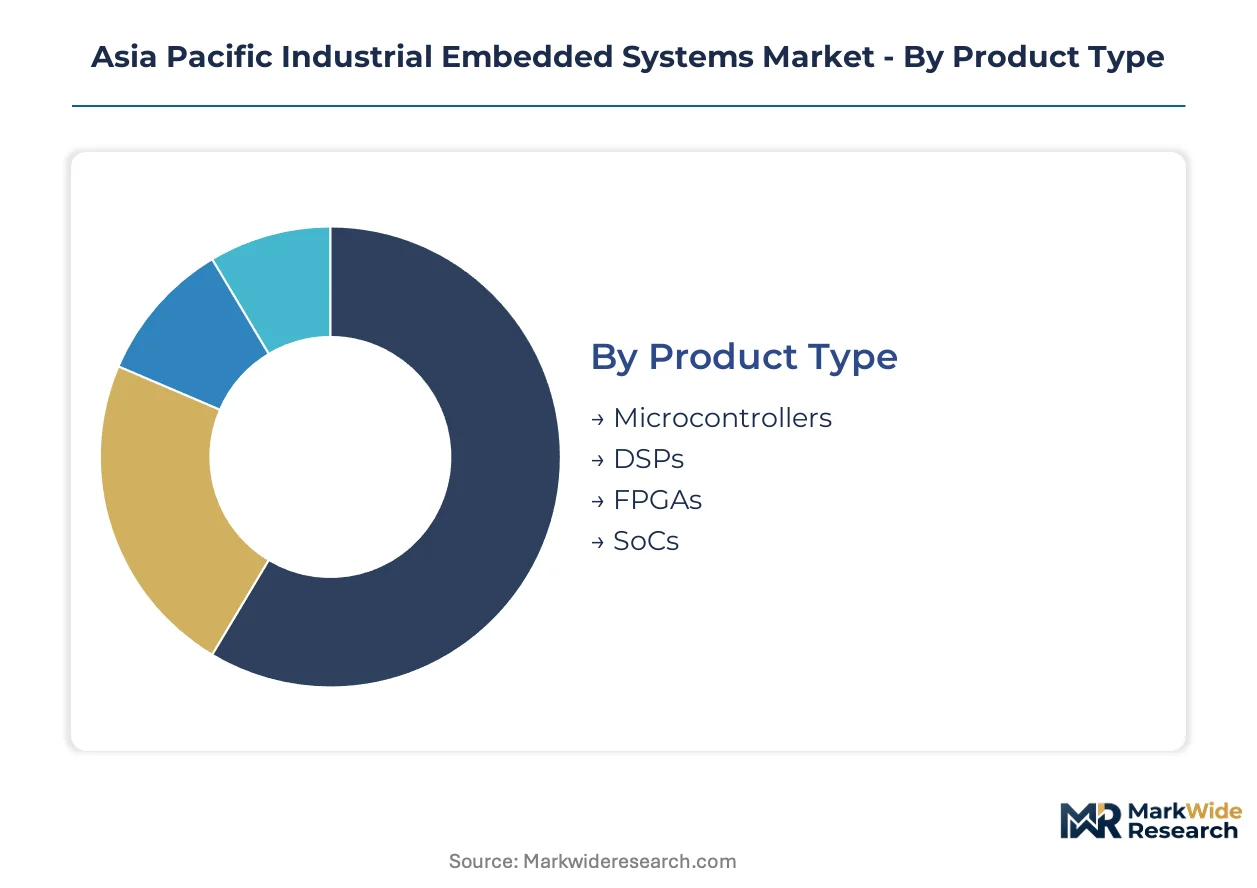
Industrial embedded systems require precise matching of processing architectures to environmental constraints and latency requirements. Segmentation reveals where semiconductor vendors concentrate R&D investment versus where system integrators capture margin through application-specific customization.
Product Type:
Standardized silicon platforms dominate high-volume factory automation, while configurable logic commands premium pricing in adaptive robotics applications requiring field-reprogrammable capabilities.
- Microcontrollers:Arm Cortex-M and RISC-V cores with integrated ADCs and motor control peripherals anchor programmable logic controllers across China's eastern manufacturing belt. Renesas and NXP supply automotive-qualified variants for Japanese welding robots, where METI energy mandates accelerate 32-bit replacements of legacy 8-bit architectures.
- SoCs:Heterogeneous processors combining application cores with real-time coprocessors and hardware security modules enable consolidated human-machine interfaces. Samsung and TSMC foundries prioritize 28nm and 16nm automotive-grade production for Korean battery manufacturing equipment.
- DSPs:Specialized digital signal processors with SIMD instruction sets execute vibration analysis algorithms for predictive maintenance in Taiwanese semiconductor fabs.
- FPGAs:Reconfigurable logic from Xilinx and Intel supports adaptive machine vision pipelines where inspection protocols change frequently.
Most installed capacity flows through Microcontrollers. Expansion is steepest in SoCs.
Application:
Volume concentration follows capital expenditure cycles in discrete manufacturing, while process industries generate replacement demand through regulatory compliance deadlines.
- Manufacturing Automation:Edge gateways with deterministic Ethernet support smart factory retrofits across Guangdong electronics assembly. STM32 and NXP microcontrollers move through distributor channels as Chinese OEMs unbundle hardware from integration services.
- Robotics:Six-axis articulated arms require SIL 2-certified control architectures under amended JIS B 3502 standards. Fanuc and Yaskawa specify Renesas RA6M5 microcontrollers with hardware isolation for safety-critical joint control.
- Process Control:Distributed control systems in Japanese chemical plants deploy redundant controller pairs for continuous operation.
- Energy Management:Building automation controllers integrate with MIIT-mandated carbon monitoring systems in Chinese steel mills.
Manufacturing Automation carries the largest installed base. Robotics is climbing the fastest.
End User:
Automotive qualification requirements create the steepest certification barriers, while telecommunications infrastructure demands extended temperature reliability without safety-critical documentation.
- Automotive:Powertrain control modules require AEC-Q100 Grade 0 silicon rated for 150°C ambient operation. Hyundai and Kia specify Infineon Tricore microcontrollers for motor control in battery manufacturing equipment.
- Aerospace:DO-178C certification for flight control systems limits supplier pools to established Japanese and Korean vendors with in-house verification teams.
- Healthcare:Diagnostic imaging equipment demands deterministic latency for real-time signal processing.
- Telecommunications:5G baseband processing units utilize industrial-grade SoCs for outdoor cabinet deployment.
Automotive absorbs the most silicon volume. Aerospace shows the steepest expansion trajectory.
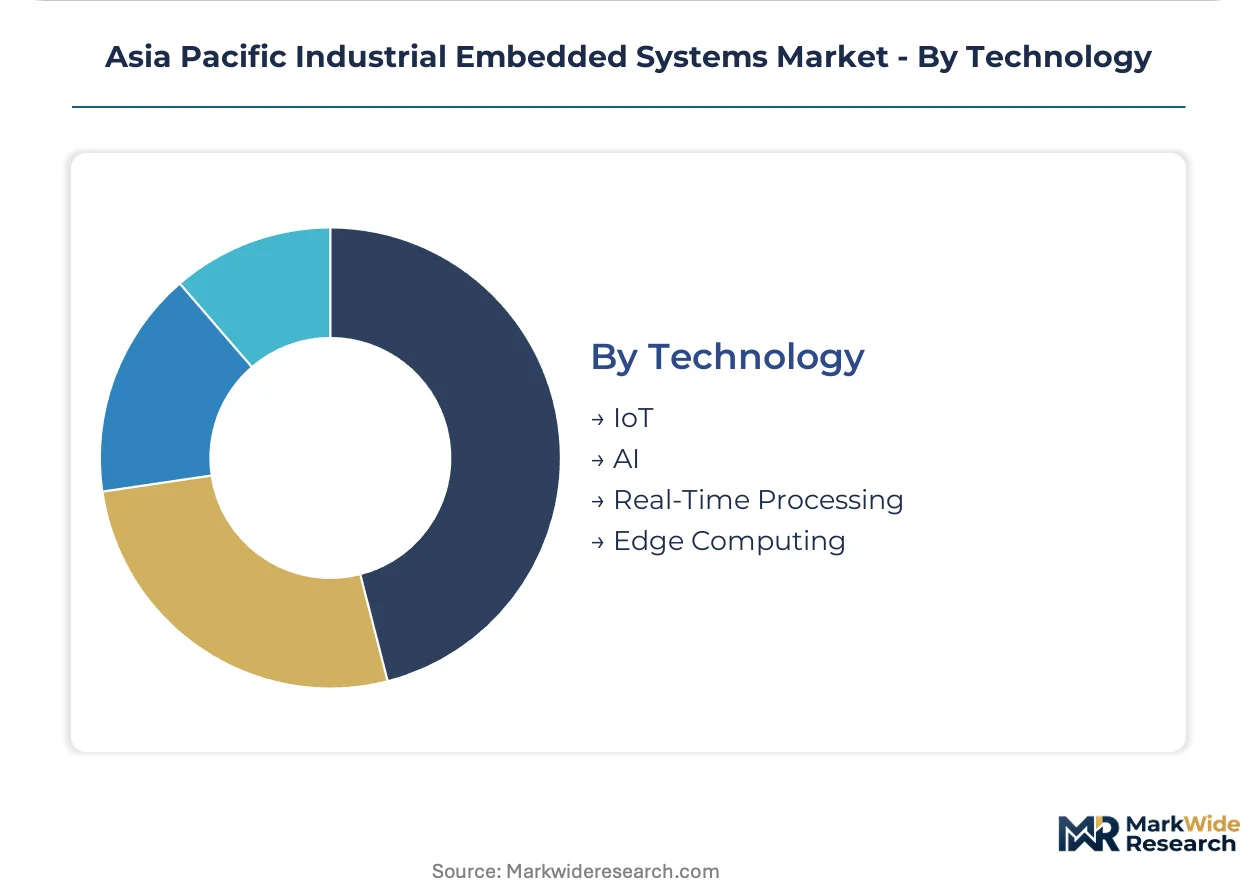
Technology:
Real-time deterministic processing represents mature infrastructure, while AI acceleration hardware attracts venture investment for defect detection applications.
- Edge Computing:GPU-accelerated gateways with time-sensitive networking support millisecond-latency quality inspection. Advantech dominates shipments to South Korean electronics assembly lines where predictive maintenance algorithms run locally.
- Real-Time Processing:RTOS-based controllers with hardware-enforced priority inheritance prevent priority inversion in Japanese automotive welding cells. Green Hills Software and Wind River supply certified kernels for SIL 2 deployments.
- IoT:Wireless sensor networks with MQTT protocol stacks monitor equipment health in Vietnamese contract manufacturing facilities.
- AI:Neural network accelerators enable real-time wafer defect classification in TSMC fabs.
Real-Time Processing underpins most legacy installations. Edge Computing is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial embedded systems manufacturing traces its regional lineage to post-war Japan's automation revolution, subsequently migrating fabrication capacity to South Korea and Taiwan during the 1980s semiconductor boom, with China absorbing final assembly and systems integration during the 2000s manufacturing expansion.
China
Guangdong province's electronics assembly corridor drives microcontroller procurement for smart factory retrofits. MIIT dual carbon mandates compress replacement cycles for legacy PLCs in steel and cement plants. Shenzhen and Dongguan clusters unbundle hardware sourcing from system integration, with OEMs procuring STM32 and NXP silicon through distributors.
Japan
Kanto and Nagoya industrial belts anchor demand for SIL 2-certified control architectures in automotive welding and painting robots. METI's 2024 JIS B 3502 amendments mandate functional safety certifications equivalent to IEC 61508. Fanuc and Yaskawa specify Renesas microcontrollers for safety-critical joint control in six-axis articulated arms.
South Korea
Hyundai and Kia's battery manufacturing equipment specifications pull Infineon Tricore microcontrollers for motor control applications. MFDS and KOSHA frameworks layer occupational safety requirements onto semiconductor packaging. Busan-Ulsan electronics assembly lines deploy GPU-accelerated edge gateways for millisecond-latency quality inspection.
Taiwan
TSMC's advanced packaging capacity reduces lead times for automotive-qualified SoCs serving Japanese and Korean automation OEMs. Hsinchu Science Park concentrates DSP production for vibration analysis in semiconductor fabs. Advantech leverages island-based manufacturing scale to dominate edge computing gateway shipments across the broader region.
Vietnam
Electronics contract manufacturers relocating from China import complete automation lines without legacy protocol constraints. Ho Chi Minh City and Bac Ninh industrial zones create greenfield demand for embedded control systems. Korean and Japanese vendors bypass replacement-cycle friction by specifying open-standards platforms for new facilities.
Asia Pacific Industrial Embedded Systems Market Competitive Landscape
The competitive structure tilts toward diversified semiconductor conglomerates with captive foundry relationships and vertical application expertise. Tier-one positions concentrate among vendors combining silicon design with functional safety certification capabilities. Three archetypes dominate: automotive-qualified microcontroller specialists, industrial edge computing platform integrators, and wide-bandgap power semiconductor innovators. Capacity expansion and strategic partnerships represent the dominant competitive moves, with vendors securing advanced packaging allocation through foundry alliances.
Among diversified semiconductor conglomerates, STMicroelectronics N.V. and Infineon Technologies occupy positions exemplifying the automotive-industrial crossover archetype, while Advantech Co Ltd represents the edge computing platform integrator tier. These three anchors illustrate how geographic proximity to manufacturing clusters—European design heritage with Asian production footprints for the semiconductor pair, Taiwan-based manufacturing scale for the platform specialist—shapes competitive positioning without determining market outcomes.
| Leading Market Players |
|---|
| Analog Devices Inc |
| STMicroelectronics N.V. |
| Infineon Technologies |
| NXP Semiconductors |
| Renesas Electronics |
| Intel Corporation |
| Microchip Technology Inc |
| Texas Instruments Inc |
| Advantech Co Ltd |
| Others |
Pricing and Supply Chain Analysis
Captive foundry relationships anchor competitive positioning for semiconductor vendors serving Japanese and Korean automation OEMs, compressing procurement costs while enabling premium-tier pricing for automotive-qualified silicon. This integration pattern insulates tier-one suppliers from spot-market volatility in mature-node wafers.
Pricing Analysis
The bundled-vs-unbundled service split distinguishes turnkey automation solutions from component-only transactions. Chinese machinery builders in Guangdong increasingly unbundle hardware procurement from integration services, treating STM32 and NXP microcontrollers as commodity inputs sourced through distributors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with SIL 2-certified architectures commanding substantial premiums over uncertified alternatives. Cost compression in standard-tier microcontrollers is intensifying because Chinese OEMs bypass value-added distributors for direct procurement. Contract manufacturers relocating to Vietnam exhibit the highest price sensitivity, while Japanese automotive tier-1s prioritize certification reliability over unit cost.
Supply Chain Analysis
Regional distribution centers in Singapore and Hong Kong anchor hub-and-spoke patterns for microcontroller shipments across Southeast Asian manufacturing zones. Geographic supply concentration centers on Taiwan for advanced SoC packaging, South Korea for memory-integrated controllers, and Japan for automotive-qualified silicon. Raw material dependencies include silicon wafers, ABF substrate for high-density packaging, and rare earth elements for magnetic components in motor drives. Single-source vulnerability in advanced packaging capacity creates exposure to disruption at TSMC's Hsinchu facilities. Distribution runs through authorized distributors for certified product lines, while spot-market channels serve cost-sensitive replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in safety-certified product tiers as METI mandates displace uncertified alternatives, while silicon carbide integration enables premium positioning in motor control applications.
For Market Incumbents: Anchor defensive positioning through captive allocation at TSMC and Samsung foundries for automotive-grade production slots. Accelerate SIL 2 certification roadmaps before JIS B 3502 amendments fully phase in, as emerging Chinese vendors without functional safety expertise threaten standard-tier microcontroller margins. Prioritize backward integration into silicon carbide substrate sourcing to secure wide-bandgap power semiconductor supply chains. For New Entrants and Emerging Players: AI inference accelerators for real-time defect detection offer the most penetrable technology-first wedge, as semiconductor fabs in Taiwan and South Korea seek vision-optimized SoCs without legacy vendor lock-in. Target Vietnam's greenfield electronics manufacturing zones where open-standards adoption bypasses proprietary protocol friction. Pursue distributor partnerships with local system integrators rather than direct OEM engagement to accelerate market access. For Investors and Strategic Acquirers: Consolidation pressure builds where functional safety certification capabilities concentrate among aging engineer cohorts in Japan and Taiwan. Long-term viability favors vendors combining silicon design with vertical application expertise across the 5-10 year automation upgrade cycle. Prioritize acquisition targets with established JIS certification track records and foundry allocation agreements. Watch for inflection when Chinese GB standards harmonization with Japanese JIS frameworks accelerates cross-border platform consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Advanced Packaging | TSMC's automotive-qualified SoC output reduces lead times for Korean battery equipment OEMs. |
| Backward Integration into SiC Substrates | Infineon's captive silicon carbide expertise extends reach into Japanese robotics motor drives. |
| Safety Certification Investment | Renesas RA6M5 SIL 2 microcontrollers capture Fanuc welding robot specifications under METI mandates. |
| Regional Distribution Hub Establishment | Singapore-based inventory positioning serves Vietnamese contract manufacturers without legacy replacement constraints. |
| AI Accelerator Product Launch | Vision-optimized SoCs enable real-time wafer defect classification in TSMC fabrication facilities. |
Research Methodology
Coverage spans China, Japan, South Korea, Taiwan, and Vietnam, with primary inputs from each market cluster. The analysis combines structured interviews with semiconductor vendor product managers, automation OEM procurement directors, and foundry capacity planners with secondary validation through MIIT policy filings, METI regulatory announcements, and customs trade data. Bottom-up triangulation against top-down macroeconomic indicators ensures segment-level consistency across microcontroller, SoC, and FPGA categories.
Rate-of-change decomposition separates volume effects from mix-shift and pricing components across the projection horizon. The analytical framework models product type, application, end user, and technology dimensions alongside regional regulatory cluster alignment. CAGRs derive from installed base replacement cycles, smart factory retrofit penetration curves, and carbon-mandated equipment upgrade timelines. Forecast inputs include foundry capacity expansion announcements, JIS B 3502 amendment implementation schedules, and dual carbon policy enforcement intensity across Chinese provincial governments.
The model holds under steady regulatory enforcement and foundry capacity expansion; deviation in trade restriction escalation or substrate supply disruption would shift replacement cycle timing. Forecasts reflect documented assumptions regarding certification harmonization progress and technology adoption S-curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Dust Extraction System Market
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
Linear Motion (LM) Shaft Market
Industrial Equipment
Industrial Linear Accelerator Market
Industrial Equipment
Europe Tempered Glass Cutting Machine Market
Industrial Equipment
Global Industrial Weighing Machines Market
Industrial Equipment
North America Rental Chillers Market
Industrial Equipment
Battery Power Tools Market
Industrial Equipment
Demagnetizer Market
Industrial Equipment
Global Safety Relays and Timers Market
Industrial Equipment
Dustless Workstations Market
Industrial Equipment
Press-Insertion Systems Market
Industrial Equipment
Europe Ceramic Roller Bearings Market
Industrial Equipment
Industrial Marking Equipment Market
Industrial Equipment
China Ceramic Roller Bearings Market
Industrial Equipment
Magnetorheological Finishing (MRF) Machine Market