
 Global Liquid Handling Systems Market | 2026-2036
Global Liquid Handling Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Liquid Handling Systems Market Foresight
Buyer concentration across contract research organizations is rebalancing as mid-sized CROs diversify procurement beyond traditional pharmaceutical giants. Thermo Fisher Scientific leverages its integrated consumables-instrument portfolio to sustain recurring revenue streams across high-volume screening facilities. Danaher anchors North American supply chains through localized manufacturing of electronic pipettes and automated workstations. Eppendorf competes on precision calibration standards that biopharmaceutical firms specify for GLP-compliant environments.
Liquid handling systems encompass precision-engineered devices that transfer measured volumes of liquid samples with accuracy ranging from microliters to milliliters, employing air displacement or positive displacement mechanisms to maintain reproducibility across repetitive workflows. These systems serve as foundational infrastructure in pharmaceutical manufacturing, biotechnology research, and clinical diagnostics where protocol standardization directly determines experimental validity. Automated pipetting systems command the largest installed base due to throughput advantages in compound libraries and genomic screening, while electronic pipettes capture expanding share among quality control labs seeking ergonomic compliance and digital traceability. Multichannel pipettes occupy a mature niche with stable replacement cycles, whereas peristaltic pump technology differentiates in environmental analysis applications requiring contamination-free fluid paths.
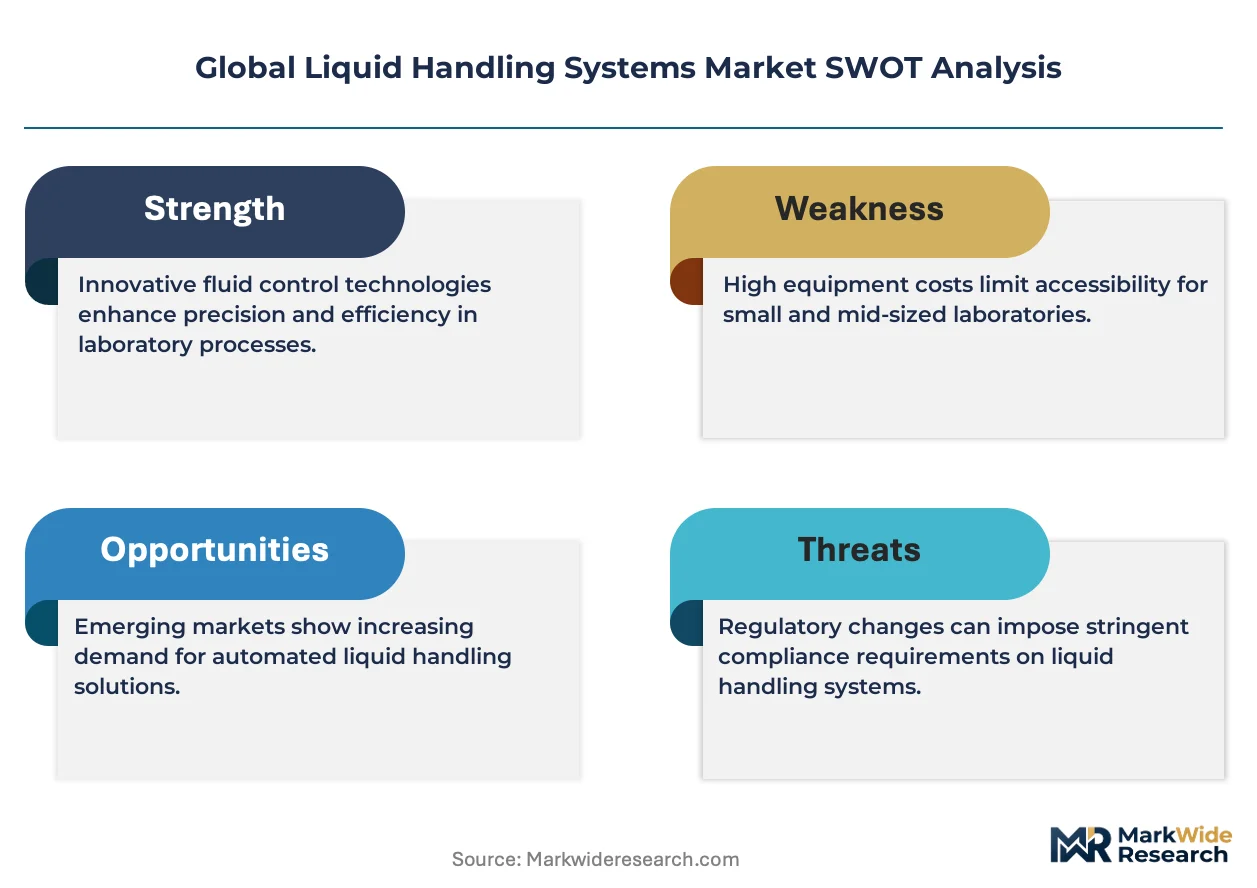
FDA quality system regulations and EU MDR framework mandate design controls and post-market surveillance for laboratory devices used in diagnostic and therapeutic development, compelling manufacturers to maintain ISO 13485-aligned production documentation. EPA methods for environmental testing and OECD Good Laboratory Practice standards further constrain allowable tolerances and calibration intervals, elevating total cost of ownership for end users. Stakeholders must monitor evolving EMA guidance on analytical method validation as automated liquid handling becomes embedded in regulatory submission pathways for biologics and cell therapies.
Market Dynamics
Biopharmaceutical firms are consolidating screening workflows around automated liquid handling platforms that compress compound-to-data timelines from weeks to days, forcing instrument vendors to embed compliance documentation directly into software architectures.
Growth Catalysts
- EU MDR traceability mandates:Diagnostic laboratories across Germany, France, and Italy are replacing manual pipetting systems with automated workstations that generate audit-ready electronic records for regulatory submissions.
- Cell therapy manufacturing scale-up:Commercial production of CAR-T therapies requires sterile, validated liquid handling protocols that only closed-system automated platforms can deliver at clinical-grade consistency.
- Environmental testing protocol proliferation:EPA methods for PFAS and microplastic analysis are expanding sample throughput requirements beyond manual laboratory capacity in the United States.
Market Restraints
- Precious metal input volatility:Platinum-iridium alloys used in high-precision pipette tips face price instability tied to South African mining output fluctuations.
- Single-source optical sensor dependence:Photometric calibration modules for automated workstations concentrate supply among German and Japanese component specialists.
- ISO 13485 certification timelines:New market entrants face 18-24 month quality system implementation periods before achieving regulatory production clearance.
Strategic Opportunities
- India's biologics manufacturing expansion:CDSCO's accelerated approval pathways for biosimilars are attracting contract manufacturing investment requiring GLP-compliant liquid handling infrastructure.
- Laboratory-as-a-service distribution:Equipment leasing platforms in the United Kingdom are bundling automated pipetting systems with consumable replenishment and remote technical support.
- AI-driven predictive maintenance convergence:Machine learning algorithms integrated with electronic pipette fleets are reducing unplanned downtime through component failure anticipation.
Industry Challenges
- Mechatronics engineering scarcity:The intersection of precision fluid dynamics, embedded software, and regulatory documentation requires talent pools concentrated in southern Germany and Switzerland.
- Legacy LIMS integration complexity:Automated workstations must interface with decades-old laboratory information management systems that lack modern API architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Liquid Handling Systems Market |
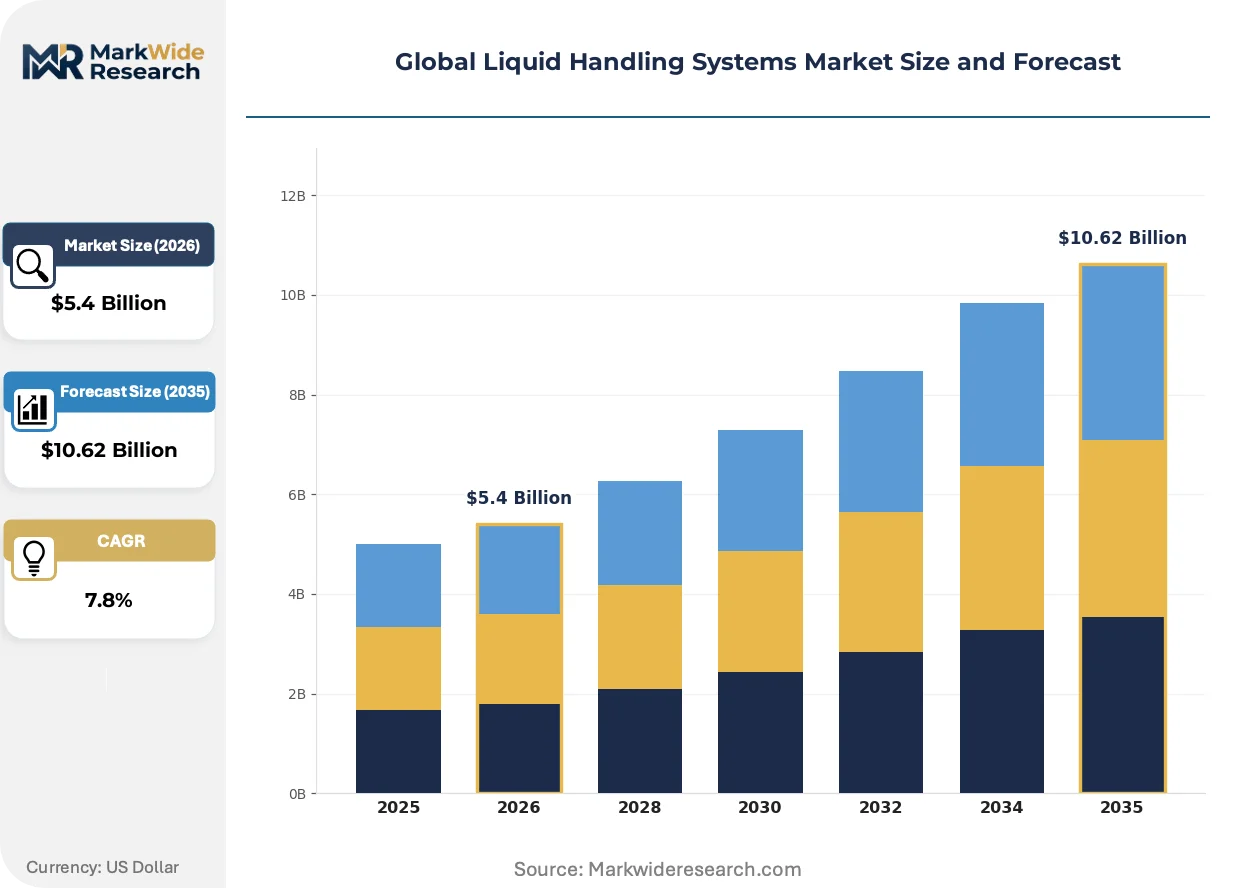
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $10.62 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Pipettes, Electronic Pipettes, Automated Pipetting Systems, Bottle Top Dispensers, Multichannel Pipettes Technology: Positive Displacement, Air Displacement, Syringe Pumps, Peristaltic Pumps, Dosing Pumps Application: Pharmaceutical Manufacturing, Food & Beverage Processing, Environmental Analysis, Biotechnology Research, Chemical Analysis End User: Contract Research Organizations, Academic Laboratories, Quality Control Labs, Biopharmaceutical Firms, Diagnostic Centers |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher, Eppendorf, PerkinElmer Inc., Agilent Technologies, Inc., Tecan Group Ltd., Sartorius AG, Mettler-Toledo International Inc., Hamilton Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Liquid Handling Systems Market Shifts & Advancements
Digital traceability and closed-system automation are converging to redefine laboratory workflow architectures, with vendors competing on software ecosystems rather than hardware specifications alone.
Acoustic liquid handling technology is automating nanoliter-scale transfers without physical contact between pipette and sample. Genomic screening facilities in the United States and United Kingdom are adopting these systems at accelerating pace for high-density compound library preparation. The technology is automating contamination-risk reduction while enabling 1,536-well plate formats that compress screening costs per data point.
REACH substance restriction proposals are expanding disclosure requirements for laboratory plastics containing perfluorinated compounds. European manufacturers are reformulating pipette tip polymers and cartridge materials to maintain CE marking eligibility. Automated workstation suppliers serving EMA-regulated environments are accelerating material certification documentation to preempt 2025 enforcement windows.
Consolidated procurement through group purchasing organizations is displacing direct manufacturer relationships among academic research consortia. University systems in California, Massachusetts, and Texas are centralizing liquid handling acquisitions through shared services frameworks that demand standardized service-level agreements. This concentration is compressing vendor margins while elevating after-sales support performance requirements as competitive differentiators.
Global Liquid Handling Systems Market Segmentation
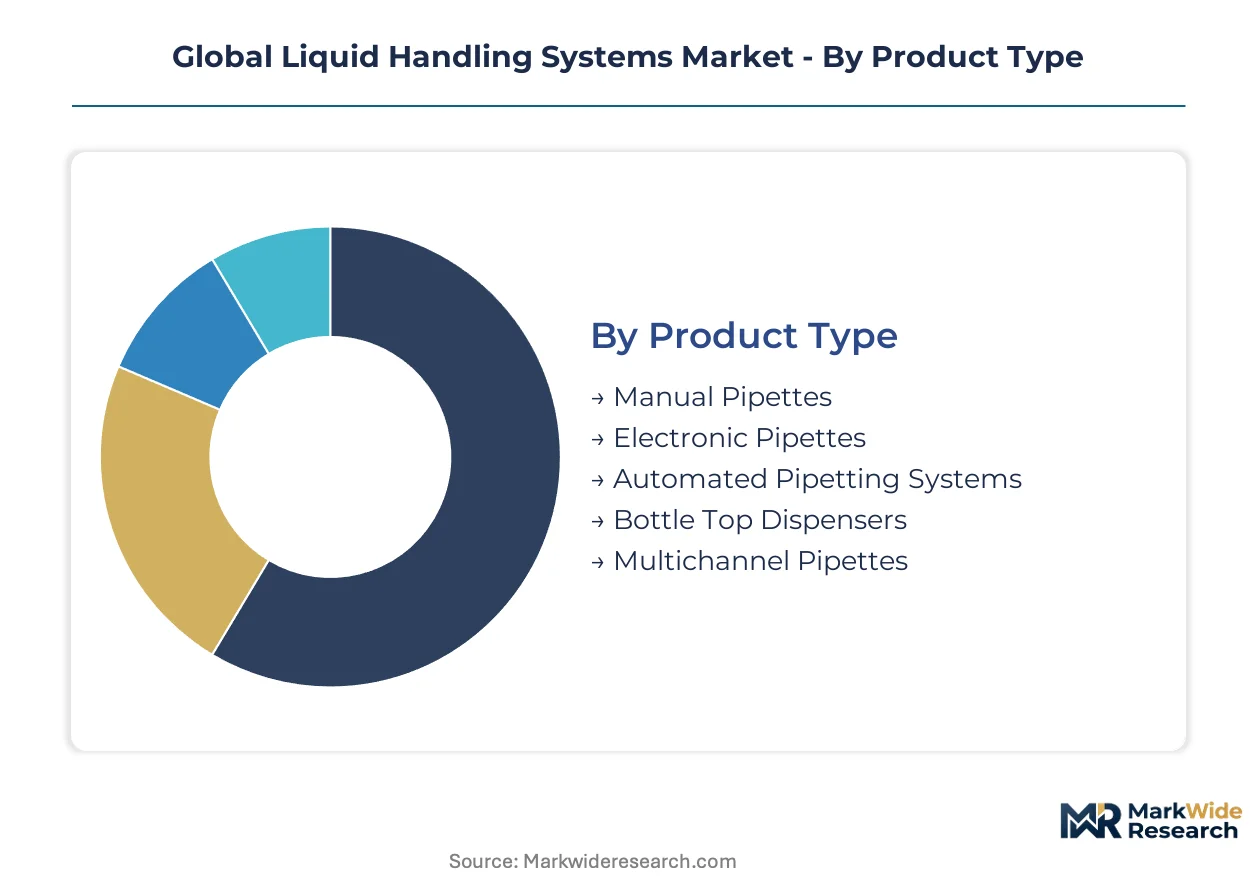
Liquid handling systems fragment across four dimensions that determine procurement priorities. Certification burdens, throughput requirements, and workflow integration needs vary sharply by segment, reshaping vendor positioning and customer switching costs.
Product Type:
ISO 13485 compliance and FDA design controls apply differentially across this category, with automated systems facing the heaviest documentation burdens while manual instruments navigate lighter regulatory thresholds.
- Automated Pipetting Systems:Closed-system platforms integrate robotic arms, optical sensors, and software-controlled calibration for high-throughput screening workflows. Biopharmaceutical firms in Germany and the United States are consolidating compound library management around these systems to compress FDA submission timelines.
- Electronic Pipettes:Motorized piston mechanisms with digital volume displays and ergonomic grips reduce repetitive strain injuries in quality control environments. Demand concentrates in diagnostic centers across France and Italy seeking EU MDR-compliant electronic records for traceability.
- Manual Pipettes:Spring-loaded piston devices with adjustable volume rings serve cost-sensitive academic laboratories with lower throughput requirements.
- Multichannel Pipettes:Eight- or twelve-channel configurations accelerate plate-based assays in biotechnology research facilities with established 96-well workflows.
- Bottle Top Dispensers:Screw-mounted pumps for repetitive dispensing from large reagent containers dominate chemical analysis laboratories handling corrosive or viscous media.
Automated pipetting systems sit at the top of the volume ranking, with electronic pipettes climbing the fastest.
Technology:
Cost tiers separate precision-grade mechanisms from commodity fluid transfer, with platinum-iridium components and optical feedback loops commanding substantial price premiums over basic displacement technologies.
- Air Displacement:Piston-driven vacuum mechanisms achieve microliter precision through compressible air columns between sample and piston. Pharmaceutical manufacturing facilities in Switzerland and the United States specify these systems for GLP-compliant environments where cross-contamination protocols are paramount.
- Positive Displacement:Direct piston-to-sample contact eliminates air interface for viscous or volatile liquids. Cell therapy manufacturing in the United Kingdom and Germany requires these mechanisms for sterile, validated protocols in CAR-T production workflows.
- Peristaltic Pumps:Roller-compressed tubing creates contamination-free fluid paths for environmental analysis applications.
- Syringe Pumps:High-precision linear actuators deliver nanoliter accuracy for chromatography and mass spectrometry sample introduction.
- Dosing Pumps:Diaphragm or gear mechanisms meter reagents in food and beverage processing with hygienic design certifications.
Air displacement commands the largest installed base, though positive displacement is gaining share fastest in biologics manufacturing.
Application:
Customer maturity and protocol standardization create diverging margin structures, with regulated pharmaceutical environments tolerating higher equipment costs than exploratory research settings.
- Pharmaceutical Manufacturing:GMP-validated liquid handling underpins formulation development, stability testing, and quality release workflows. Facilities in Ireland and Singapore are expanding automated platform deployment to meet FDA and EMA submission requirements for biologics.
- Biotechnology Research:Genomic screening and cell culture applications demand flexible, multi-user platforms with rapid protocol switching. Academic consortia in Massachusetts and California are consolidating procurement through shared services frameworks.
- Environmental Analysis:EPA method compliance for PFAS and microplastic testing drives throughput requirements beyond manual capacity in United States contract laboratories.
- Food & Beverage Processing:HACCP-aligned dosing and sampling systems support pathogen detection and nutritional analysis in centralized testing facilities.
- Chemical Analysis:Corrosive reagent handling and solvent extraction workflows prioritize chemical compatibility and operator safety.
Pharmaceutical manufacturing generates the highest equipment revenue per installation, with environmental analysis expanding most quickly on regulatory test method proliferation.
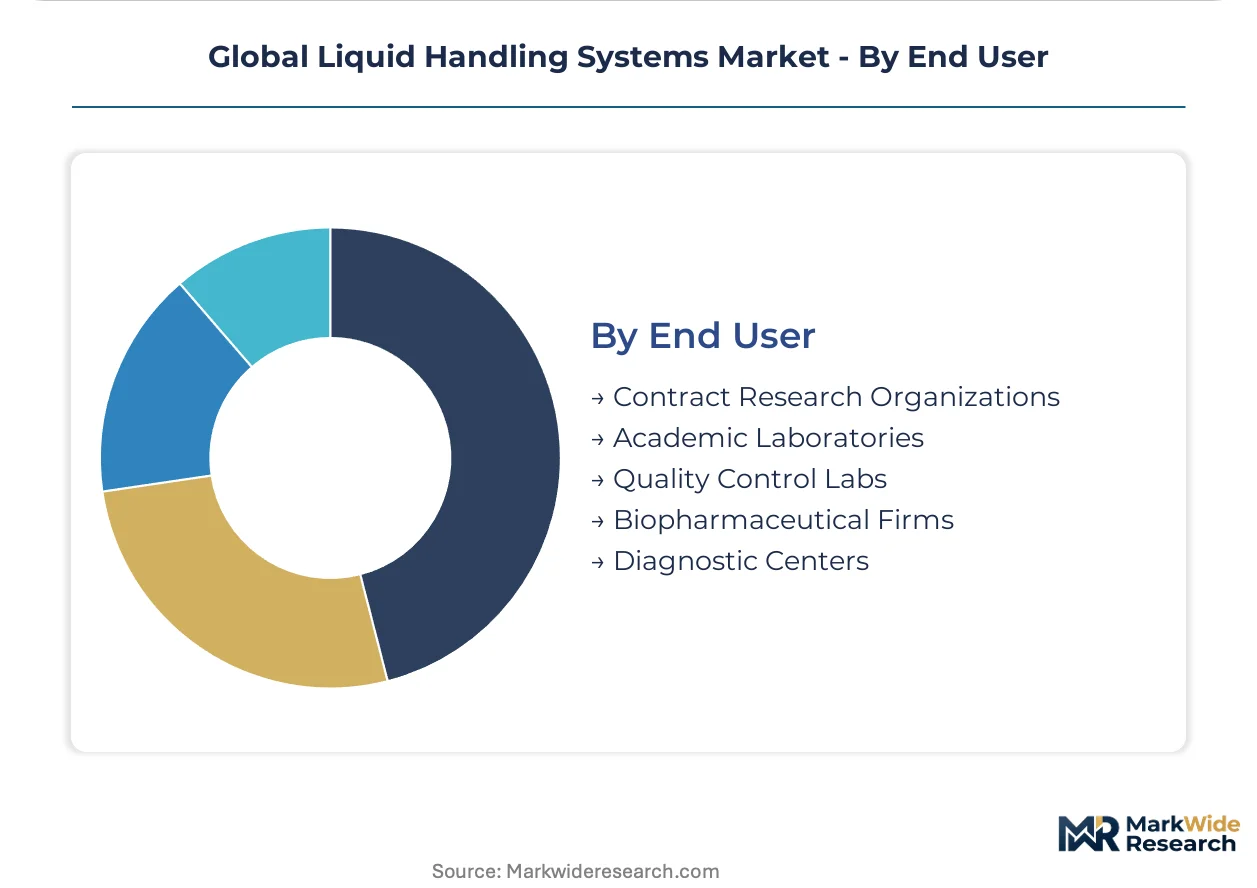
End User:
Procurement authority and replacement cycle timing vary by organization scale, with large biopharmaceutical firms negotiating enterprise frameworks while mid-sized CROs seek flexible leasing arrangements.
- Biopharmaceutical Firms:Integrated drug discovery and manufacturing operations require validated, closed-system automation with embedded compliance documentation. Companies in Basel and Boston are embedding liquid handling platforms directly into regulatory submission pathways.
- Contract Research Organizations:Variable project pipelines demand scalable capacity with rapid instrument redeployment between therapeutic areas. Mid-sized CROs in India and Eastern Europe are diversifying procurement beyond traditional pharmaceutical giant relationships.
- Academic Laboratories:Grant-funded budgets prioritize cost efficiency and multi-user durability over throughput optimization.
- Quality Control Labs:ISO 17025 accreditation requirements drive calibration rigor and audit-ready documentation in industrial testing facilities.
- Diagnostic Centers:High-volume clinical sample processing requires CLIA-compliant automation with minimal operator training burdens.
Biopharmaceutical firms anchor the highest absolute spending, with contract research organizations showing the steepest expansion trajectory on outsourcing growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's precision engineering clusters generate three times the liquid handling system density per capita compared to India's emerging biologics hubs, yet both markets are expanding automated platform deployment under diverging regulatory timelines.
United States
FDA quality system regulations and EPA environmental testing mandates are accelerating automated workstation adoption in Boston and San Diego biotech corridors. The agency's 21 CFR Part 820 design control requirements compel manufacturers to embed compliance documentation directly into software architectures. Genomic screening facilities in Massachusetts consolidate procurement through shared services frameworks.
Germany
EU MDR traceability requirements and ISO 13485 certification standards are reshaping diagnostic laboratory procurement across Baden-Württemberg and Bavaria. The country's national pharmaceutical regulator enforces post-market surveillance protocols that elevate total cost of ownership for end users. Precision engineering clusters around Stuttgart and Munich anchor high-throughput research infrastructure investments.
India
CDSCO accelerated approval pathways for biosimilars and contract manufacturing expansion are attracting GLP-compliant liquid handling infrastructure to Maharashtra and Gujarat. The country's national pharmaceutical regulator has streamlined quality system timelines for imported automated platforms. Hyderabad and Bangalore biologics clusters are diversifying procurement beyond traditional pharmaceutical giant relationships.
United Kingdom
Laboratory-as-a-service distribution models and cell therapy manufacturing scale-up are concentrating demand in Cambridge and Oxford innovation corridors. The MHRA's post-Brexit regulatory alignment with EU MDR frameworks maintains CE marking requirements for diagnostic devices. Equipment leasing platforms in Greater London bundle automated pipetting systems with consumable replenishment contracts.
Switzerland
Swissmedic's stringent analytical method validation requirements and biopharmaceutical manufacturing excellence are sustaining premium-tier equipment demand across Basel and Zurich. The national pharmaceutical regulator mandates ISO 17025-aligned calibration intervals for clinical-grade liquid handling. Precision mechatronics engineering talent pools in the country's northwestern corridor support closed-system automation development.
Global Liquid Handling Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions, with portfolio breadth determining recurring revenue capture against precision calibration differentiation. The vendor base organizes around three strategic archetypes: integrated life science conglomerates with consumables-instrument portfolios, precision engineering specialists with GLP-compliant calibration standards, and automation-focused technology providers with software-centric platforms. Dominant competitive moves include strategic partnerships between instrument manufacturers and laboratory information management system vendors, alongside geographic expansion through localized electronic pipette production.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Danaher occupy positions exemplifying integrated portfolio strategies, while Eppendorf AG represents the precision engineering specialist archetype with calibration-focused market positioning.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher |
| Eppendorf |
| PerkinElmer Inc. |
| Agilent Technologies, Inc. |
| Tecan Group Ltd. |
| Sartorius AG |
| Mettler-Toledo International Inc. |
| Hamilton Company |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between ISO 13485-validated automated platforms and standard electronic pipettes manifests in pricing spreads exceeding three-to-one, with supply chain configurations diverging accordingly. Premium-tier manufacturers anchor production in southern Germany and Switzerland where mechatronics engineering density supports precision calibration infrastructure, while commodity-grade suppliers source piston mechanisms from centralized Asian component foundries.
Pricing Analysis
Capacity additions in China's precision machining sector are reshaping price floors for manual and electronic pipette tiers, compressing margins for mid-market European producers. Three-tier pricing structure across premium, standard, and economy levels separates GLP-compliant automated workstations from diagnostic-grade electronic pipettes and academic-market manual instruments. Pricing pressure stems from consolidated procurement through university shared services frameworks in Massachusetts and Texas. Academic laboratories exhibit highest price sensitivity, while biopharmaceutical manufacturing facilities in Basel and Boston tolerate premium positioning for embedded compliance documentation.
Supply Chain Analysis
Dual-sourcing mandates from FDA-regulated biopharmaceutical buyers compel tier-one vendors to qualify secondary suppliers for platinum-iridium alloy components and optical sensor modules. Manufacturing concentrates in Germany, Switzerland, and the United States for precision-grade automated platforms, with Mexico and Malaysia hosting final assembly for electronic pipette volume production. Critical dependencies include South African platinum-iridium alloys, Japanese photometric sensors, and German linear actuator components. Single-source vulnerability concentrates in optical calibration modules where Japanese and German specialists dominate. Distribution runs through laboratory equipment distributors with field service capabilities, alongside direct enterprise contracts for high-throughput screening facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid handling systems market functions as a regulatory compounder where EU MDR traceability mandates and FDA design control requirements continuously elevate compliance-embedded equipment demand across diagnostic and therapeutic development workflows.
For Market Incumbents: Deepen consumables-instrument integration to capture recurring revenue streams as academic consortia consolidate procurement through shared services frameworks. Fortify calibration service networks in Germany and Switzerland where GLP-compliant environments sustain premium positioning. Counter acoustic liquid handling substitution threats by embedding predictive maintenance algorithms into electronic pipette fleets. For New Entrants and Emerging Players: Laboratory-as-a-service platforms in the United Kingdom represent the most penetrable channel for automated workstation penetration without direct manufacturer competition. Target India's CDSCO-aligned contract manufacturing organizations in Maharashtra and Gujarat seeking GLP-compliant infrastructure for biosimilar production. Pursue white-label electronic pipette supply agreements with European distributors seeking CE-marked alternatives to established brands. For Investors and Strategic Acquirers: Consolidation pressure builds where precision mechatronics engineering scarcity intersects with ISO 13485 certification bottlenecks, favoring acquisition of calibration-specialist firms with established regulatory documentation libraries. Long-term viability centers on software ecosystem control rather than hardware manufacturing scale. Watch EMA guidance evolution on analytical method validation as the inflection signal for automated liquid handling becoming embedded in biologics submission pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Documentation Integration | FDA 21 CFR Part 820 design controls embedded in software architectures accelerate biopharmaceutical customer compliance timelines. |
| Consumables-Instrument Bundling | Recurring revenue capture from pipette tip and cartridge replenishment contracts insulates against capital equipment cyclicality. |
| Precision Calibration Service Expansion | ISO 17025-aligned calibration networks in Basel and Stuttgart reinforce GLP-compliant customer retention. |
| Acoustic Liquid Handling Partnership | Contactless nanoliter transfer technology from genomic screening specialists addresses 1,536-well plate format demand. |
| India Biologics Manufacturing Localization | CDSCO-aligned quality system implementation supports contract manufacturing organization infrastructure deployment. |
Research Methodology
Multiple input streams — primary interviews with biopharmaceutical manufacturing directors, diagnostic laboratory procurement managers, and regulatory affairs specialists; secondary validation through FDA 510(k) filings, EMA device registration databases, and ISO 13485 certification records; alongside customs trade data for precision instrument imports — were reconciled through bottom-up and top-down triangulation. Conversations with contract research organization operations heads and academic shared services administrators informed demand-side segmentation. SEC filings from diversified life science conglomerates and specialized instrument manufacturers provided supply-side capacity and pricing benchmarks.
Data-stream reconciliation across product type, technology mechanism, application workflow, and end-user procurement authority dimensions generated volume and value estimates across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic healthcare R&D spending indicators and regulatory enforcement timeline assumptions. Industry-specific forecast inputs included EPA environmental testing method expansion rates and CDSCO biosimilar approval pathway velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance restriction enforcement timelines for perfluorinated laboratory plastics and South African platinum mining output volatility. Deviation in EMA analytical method validation guidance would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Industrial Polishing Machine Market
Industrial Equipment
Electric Soldering Iron Gun Market
Industrial Equipment
Linear Motion (LM) Shaft Market
Industrial Equipment
Cash Sorting Machines Market
Industrial Equipment
Global Servo Motor Market
Industrial Equipment
South America Fans and Blowers Market
Industrial Equipment
Global Abrasive Waterjet Cutting Machine Market
Industrial Equipment
Linear Shaft Motor Market
Industrial Equipment
Jet Dispenser Market
Industrial Equipment
Global Industrial Enclosures Market
Industrial Equipment
Semiconductor Cartridge Heaters Market
Industrial Equipment
Electrodynamic Shaker Systems Market
Industrial Equipment
Industrial Magnetrons Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Industrial Lasers Systems Market
Industrial Equipment
Pneumatic Strippers Market