
 Europe Industrial Centrifuge Market | 2026-2036
Europe Industrial Centrifuge Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Industrial Centrifuge Market Foresight
Aftermarket service revenue is narrowing toward predictive maintenance contracts and remote diagnostics platforms. Alfa Laval AB anchors its position through extensive European service networks and digital monitoring integration. Flottweg SE differentiates via specialized decanter configurations for food and biofuel applications. GEA Group AG leverages its broad process equipment portfolio to cross-sell centrifuge systems into existing dairy and brewery accounts.
Europe industrial centrifuges are rotating separation devices that apply centrifugal force typically ranging from 1,000 to 20,000 G to separate immiscible liquids or solids from liquids based on density differentials. These machines serve essential functions in process industries requiring continuous or batch clarification, dewatering, and purification operations. Disk stack configurations dominate pharmaceutical and beverage applications where high g-force precision and sanitary design prove critical. Continuous centrifuge systems are gaining share in chemical and wastewater treatment facilities seeking uninterrupted throughput and reduced manual intervention. Basket centrifuges retain relevance in batch-oriented specialty chemical production where product changeover flexibility outweighs speed requirements.
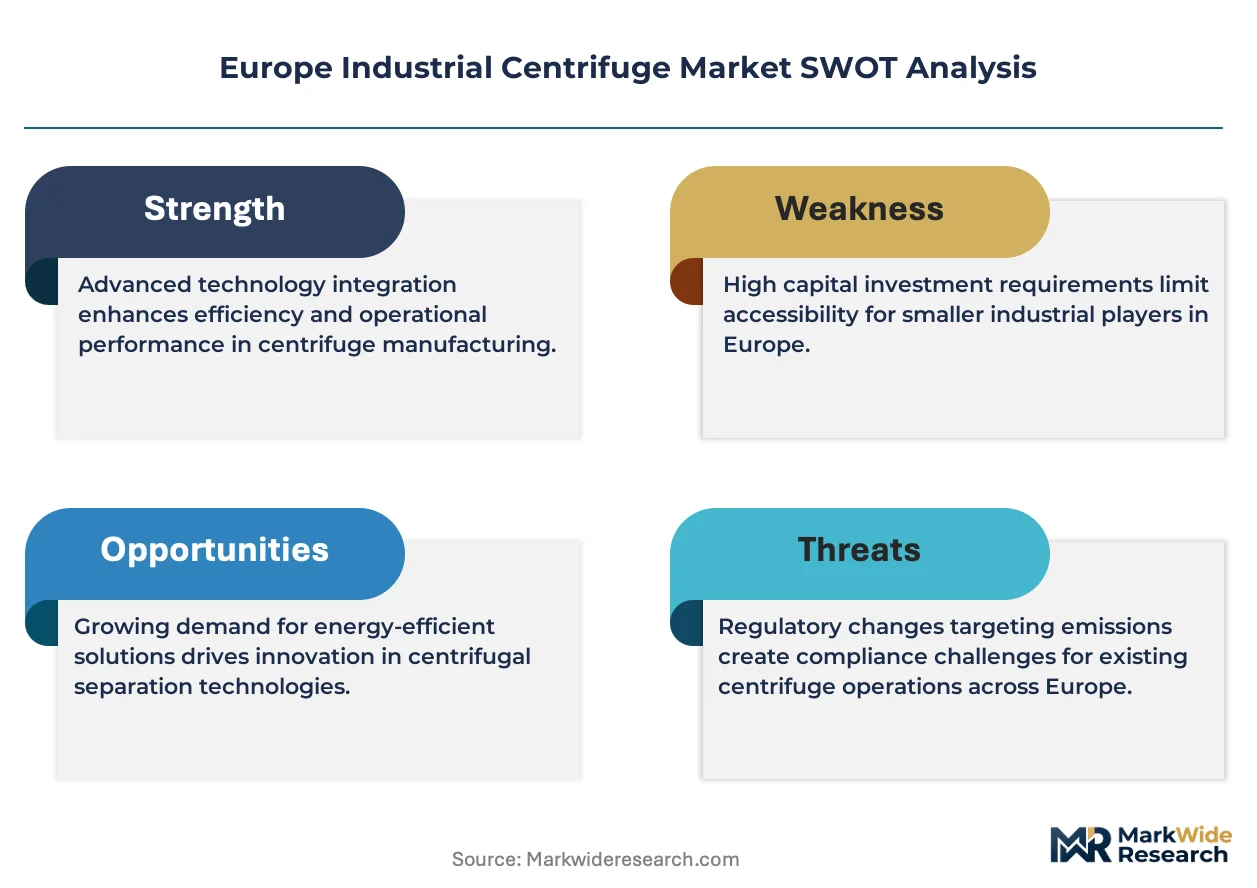
EMA medical device regulations and REACH chemical safety frameworks mandate stainless steel construction standards and seal material traceability for equipment contacting regulated substances. The EU Green Deal effluent directives are pushing wastewater treatment operators toward energy-efficient centrifuge retrofits that reduce sludge volume and disposal costs. Stakeholders must weigh capital replacement cycles against modular upgrade paths as efficiency standards tighten and energy pricing volatility persists.
Market Dynamics
REACH chemical safety frameworks and EU Green Deal effluent mandates are compressing replacement cycles for aging separation equipment across European process industries. Pharmaceutical manufacturers and wastewater operators face simultaneous pressure to cut energy consumption while tightening discharge standards.
Growth Catalysts
- Active pharmaceutical ingredient recovery:German and French pharmaceutical manufacturers are expanding capacity for high-value product recovery, driving demand for sanitary disk stack centrifuges with validated cleaning protocols.
- REACH compliance mandates:ECHA enforcement of stainless steel construction standards and seal material traceability is accelerating equipment replacement among chemical processors handling regulated substances.
- Energy efficiency retrofits:The EU Green Deal's wastewater treatment directives are pushing municipal and industrial operators toward centrifuge upgrades that reduce sludge volume and disposal costs.
Market Restraints
- Specialized alloy cost volatility:Duplex stainless steel and superalloy prices fluctuate with nickel and molybdenum markets, compressing margins for custom-fabricated high-g-force units.
- Component supply concentration:Precision bearings and high-speed drive systems rely on a limited supplier base concentrated in Germany and Switzerland, creating lead time vulnerability.
- Technical service scarcity:Field technicians capable of balancing high-speed rotors and diagnosing vibration anomalies remain concentrated with OEM service networks, limiting third-party maintenance options.
Strategic Opportunities
- Eastern European chemical corridor:Poland and Czech Republic process industries are modernizing Soviet-era separation infrastructure, creating first-mover advantage for vendors offering modular retrofit packages.
- Biofuel refining integration:Advanced biodiesel and renewable diesel facilities require specialized decanter configurations for glycerin separation and catalyst recovery, an application segment with limited incumbent penetration.
- Predictive maintenance platforms:Remote vibration monitoring and AI-driven failure prediction are opening recurring revenue streams beyond traditional spare parts and scheduled service contracts.
Industry Challenges
- Certification timeline compression:EMA medical device regulations and ATEX explosion protection directives impose parallel approval tracks, extending time-to-revenue for new pharmaceutical and solvent-handling designs.
- Legacy control system integration:Brownfield chemical plants operate centrifuges on proprietary PLC architectures from the 1990s, complicating digital retrofit and data extraction for Industry 4.0 upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Industrial Centrifuge Market |
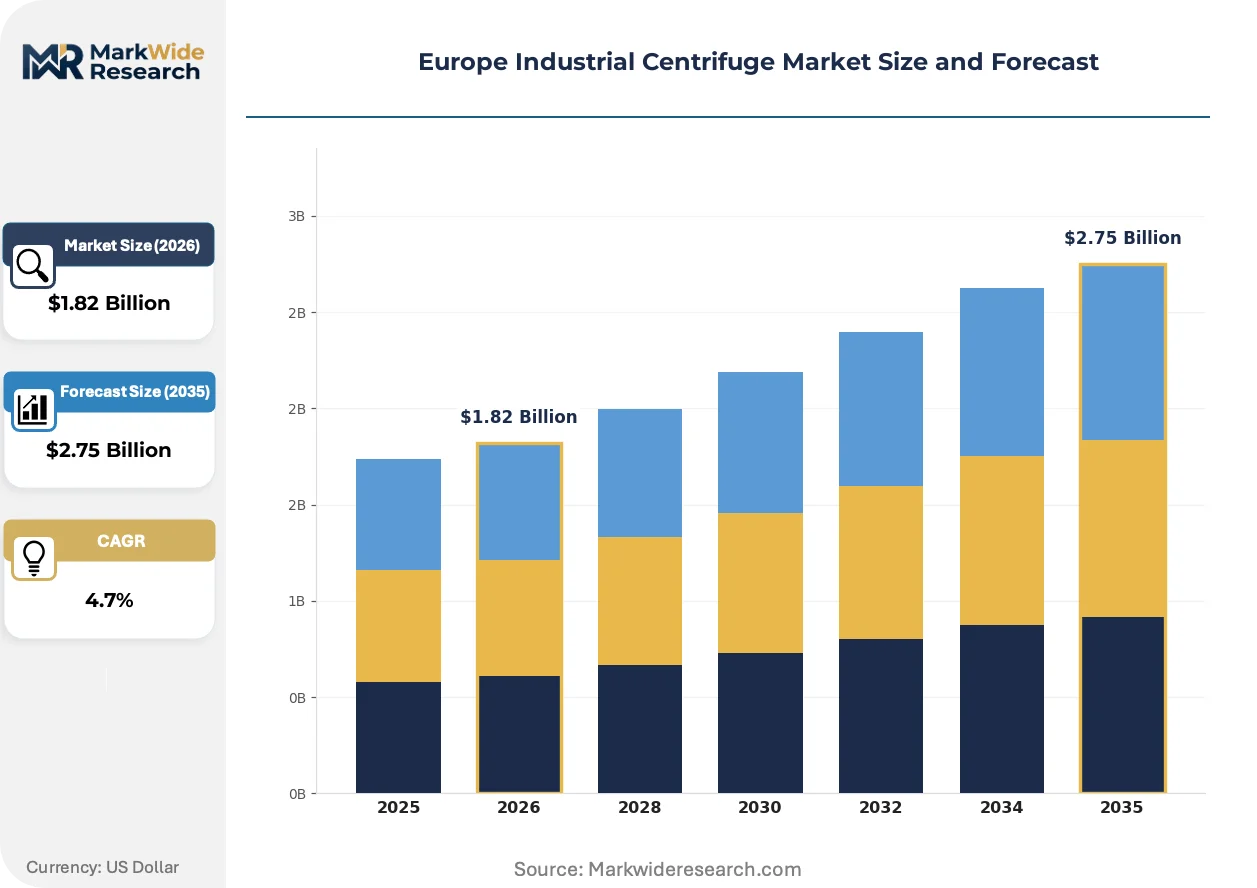
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $2.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary, Disk Stack, Basket, Continuous End User: Food Processing, Chemicals, Pharmaceuticals, Wastewater Treatment Application: Liquid Separation, Solid Separation, Clarification, Dewatering Technology: Mechanical, Electrical, Hydraulic, Pneumatic |
| Companies Covered | Flottweg SE, Hiller Separation & Process GmbH, Alfa Laval AB, Pieralisi S.p.A., Thomas Broadbent & Sons Ltd, GEA Group AG, HAUS Centrifuge Technologies, Vitone Eco SRL, Andritz AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Industrial Centrifuge Market Shifts & Advancements
Digital monitoring integration and energy-optimized rotor designs are redefining competitive differentiation in European industrial centrifuge supply. Equipment vendors are racing to embed predictive capabilities before efficiency mandates tighten further.
Continuous centrifuge systems are migrating from batch-dominant chemical processing toward uninterrupted pharmaceutical and beverage clarification lines. German dairy cooperatives and French winery consortia are adopting these configurations to reduce manual intervention and CIP downtime. The shift is compressing demand for traditional basket centrifuges outside specialty chemical batch operations.
EMA medical device regulations and REACH chemical safety frameworks are mandating stainless steel construction standards and seal material traceability for all equipment contacting regulated substances. Pharmaceutical manufacturers must now document alloy composition and elastomer sourcing through entire supply chains. Disk stack centrifuge suppliers are responding by pre-certifying sanitary designs to accelerate customer qualification timelines.
Service unbundling is fragmenting traditional OEM maintenance relationships across the region. Large chemical processors in the Netherlands and Belgium are negotiating direct contracts with specialized vibration analysis firms rather than purchasing bundled service packages. This procurement pattern is most visible among multinational operators with centralized engineering competencies and captive technical staff.
Europe Industrial Centrifuge Market Segmentation
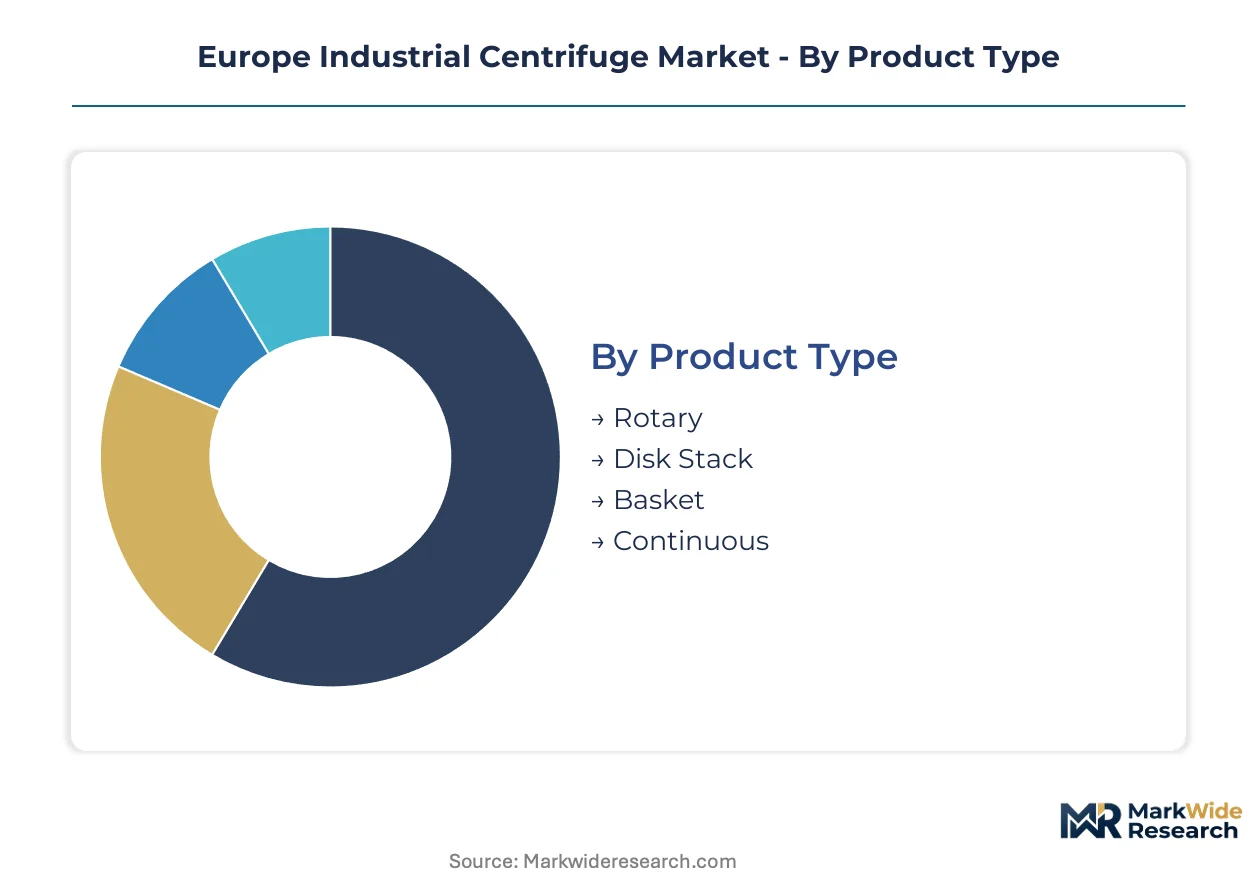
Centrifuge procurement patterns diver sharply across European process industries. Pharmaceutical manufacturers prioritize validated sanitary designs, while chemical processors weigh alloy compatibility against discharge compliance costs.
Product Type:
Rotary configurations span the widest use-case spectrum from batch specialty chemicals to continuous beverage clarification.
- Rotary:These machines deploy a cylindrical rotor spinning at 1,000–8,000 G for general-purpose liquid-solid separation. German chemical processors along the Rhine corridor favor rotary units for flexible batch operations handling multiple feedstock types. REACH-mandated seal material traceability is compressing replacement cycles for aging rotary fleets in solvent-handling applications.
- Disk Stack:Conical disk arrays generate 5,000–15,000 G force for high-precision liquid-liquid separation. French and German pharmaceutical manufacturers specify disk stack centrifuges with CIP-validated designs for active pharmaceutical ingredient recovery. EMA medical device regulations mandate stainless steel construction standards and complete alloy documentation for all product-contact surfaces.
- Basket:Perforated bowl designs retain solids while draining liquids through filter media. Italian specialty dye manufacturers specify basket centrifuges for batch-oriented pigment dewatering where product changeover flexibility outweighs throughput speed.
- Continuous:Uninterrupted feed and discharge systems eliminate manual intervention between cycles. Dutch dairy cooperatives and Belgian brewery consortia are adopting continuous configurations to reduce CIP downtime and labor costs.
Established volume favors Rotary; emerging adoption favors Continuous.
End User:
Capital intensity and regulatory exposure create distinct procurement priorities across customer categories.
- Food Processing:Sanitary centrifuges separate cream, clarify juices, and recover edible oils. French winery consortia and German dairy cooperatives drive specification demand for EHEDG-compliant designs with automated CIP protocols.
- Chemicals:Solvent recovery and catalyst separation operations require corrosion-resistant alloys. Polish and Czech chemical processors are modernizing Soviet-era separation infrastructure, creating retrofit demand for modular disk stack systems.
- Pharmaceuticals:High-value product recovery mandates validated cleaning and complete batch traceability. German and French API manufacturers are expanding capacity for monoclonal antibody and fermentation broth clarification.
- Wastewater Treatment:Sludge dewatering centrifuges reduce disposal volumes and energy consumption. EU Green Deal effluent directives are accelerating municipal operator upgrades across the Netherlands and Belgium.
Pharmaceuticals command premium pricing; Wastewater Treatment offers volume scale through municipal fleet replacement.
Application:
Process objectives determine g-force requirements, rotor geometry, and discharge configurations.
- Liquid Separation:Density differential exploitation splits immiscible phases at 3,000–10,000 G. Biofuel refineries in Poland and the Czech Republic deploy liquid separation centrifuges for glycerin and biodiesel phase splitting.
- Solid Separation:Suspended particle removal clarifies process streams and protects downstream equipment. German brewery operators specify solid separation units for yeast recovery and beer polishing operations.
- Clarification:Fine particle removal achieves optical clarity in beverages and pharmaceutical intermediates. French wine producers and Italian olive oil processors prioritize clarification centrifuges for premium product differentiation.
- Dewatering:Moisture reduction from slurries minimizes disposal costs and enables thermal drying. Belgian and Dutch wastewater treatment authorities are retrofitting dewatering centrifuges to meet tightened EU sludge volume reduction targets.
Clarification dominates beverage and pharma value chains; Dewatering is expanding most quickly under EU Green Deal compliance pressure.
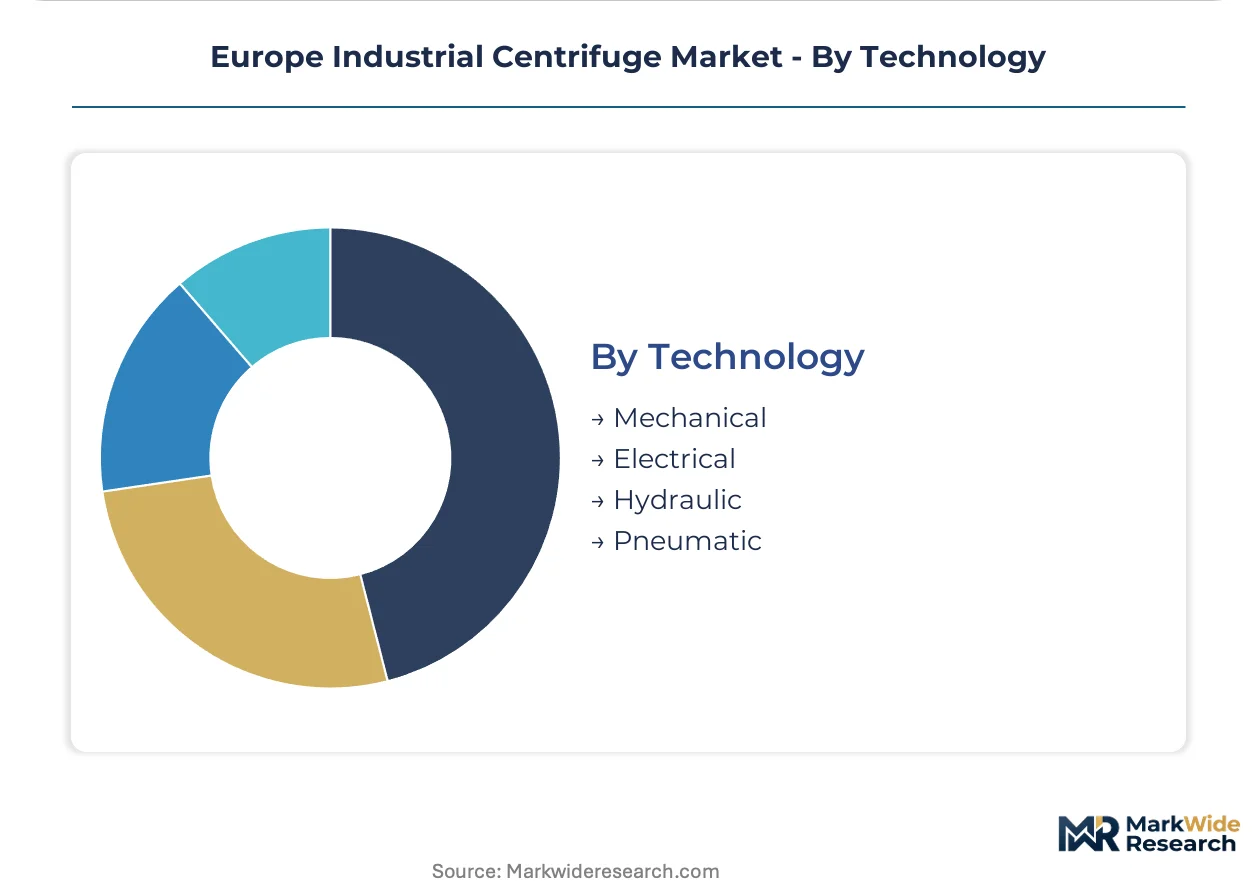
Technology:
Drive system selection balances energy efficiency, speed control precision, and explosion protection requirements.
- Mechanical:Belt and gear drives deliver cost-effective speed multiplication for standard industrial applications. Mature technology dominates Eastern European price-sensitive procurement.
- Electrical:Variable frequency drives enable precise speed control and energy recovery. ATEX-compliant electrical systems are displacing pneumatic alternatives in solvent-handling chemical plants.
- Hydraulic:Fluid power transmission handles high-torque startup and overload protection. Heavy-duty decanter applications in mining and minerals processing specify hydraulic drive resilience.
- Pneumatic:Compressed air systems operate in explosive atmospheres without ignition risk. Pharmaceutical cleanrooms and solvent recovery operations retain pneumatic drives where electrical classification proves costly.
Electrical systems are gaining share fastest through VFD efficiency gains; Pneumatic retains defensive positions in ATEX Zone 0/1 environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Centrifuge deployment patterns across Europe diverge sharply between Western pharmaceutical corridors and Eastern industrial retrofits. Germany and France prioritize high-precision API recovery systems, while Poland and Czech Republic operators modernize Soviet-era separation infrastructure under EU convergence funding.
Germany
Pharmaceutical manufacturers in Baden-Württemberg and North Rhine-Westphalia are expanding monoclonal antibody clarification capacity. EMA medical device regulations mandate complete alloy documentation and validated CIP protocols for all product-contact surfaces. The Rhine chemical corridor from Ludwigshafen to Leverkusen is replacing aging rotary centrifuge fleets with REACH-compliant stainless steel configurations.
France
Wine consortiums in Bordeaux and Champagne are adopting continuous clarification systems to reduce manual intervention and cleaning downtime. EU Green Deal effluent directives are accelerating municipal sludge dewatering upgrades in the Paris metropolitan wastewater authority. The Île-de-France pharmaceutical cluster is specifying disk stack centrifuges with pre-certified sanitary designs to compress qualification timelines.
Netherlands
Dairy cooperatives in Friesland are retrofitting energy-efficient centrifuge systems to cut thermal processing costs. The country's national environmental regulator is enforcing tightened discharge standards under EU wastewater treatment directives. Rotterdam's chemical processing hub is negotiating direct service contracts with specialized vibration analysis firms rather than bundled OEM maintenance packages.
Poland
Chemical processors in the Silesian industrial basin are modernizing separation infrastructure with modular disk stack retrofit packages. EU convergence funding is covering capital replacement cycles for Soviet-era equipment that predates REACH compliance mandates. The Pomeranian biofuel refining corridor is deploying specialized decanter configurations for glycerin separation and catalyst recovery.
Czech Republic
Specialty chemical manufacturers near Prague are replacing batch basket centrifuges with continuous systems to improve throughput consistency. ECHA enforcement of seal material traceability is accelerating equipment replacement among solvent-handling operations. The Ústí nad Labem chemical complex is sourcing ATEX-compliant electrical drive systems to displace pneumatic alternatives in explosive atmosphere zones.
Europe Industrial Centrifuge Market Competitive Landscape
Capability concentration sits with specialized decanter fabricators; scale advantage sits with diversified process equipment conglomerates. The European industrial centrifuge supply base organizes into three functional tiers: full-line process equipment houses with cross-selling leverage, specialized separation technology developers with application-specific expertise, and regional fabrication shops serving price-sensitive Eastern European procurement. Dominant competitive moves include predictive maintenance platform development and modular retrofit package engineering for brownfield chemical plants.
Among German-based specialists, Flottweg SE and Hiller Separation & Process GmbH exemplify the decanter-focused archetype with deep configuration expertise for food and biofuel applications. Alfa Laval AB occupies a position as the diversified Nordic full-line supplier anchoring market presence through extensive European service networks and digital monitoring integration. These three represent distinct strategic postures: specialized engineering depth versus portfolio breadth versus aftermarket platform scale.
| Leading Market Players |
|---|
| Flottweg SE |
| Hiller Separation & Process GmbH |
| Alfa Laval AB |
| Pieralisi S.p.A. |
| Thomas Broadbent & Sons Ltd |
| GEA Group AG |
| HAUS Centrifuge Technologies |
| Vitone Eco SRL |
| Andritz AG |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's volatile container rates amplify cost differentials between German precision fabricators and Eastern European assembly operations, compressing margins for mid-tier centrifuge suppliers while rewarding vendors with captive bearing production and modular retrofit capabilities.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical procurement, with German and French API manufacturers locking in five-year service bundles that embed predictive maintenance platforms and spare parts guarantees. Spot purchasing persists among Polish and Czech chemical processors modernizing Soviet-era infrastructure, where project-based tenders favor lowest capital outlay over lifecycle cost. REACH-mandated stainless steel documentation and EMA-certified sanitary designs command premium positioning against standard industrial configurations. Pricing pressure intensifies from nickel and molybdenum alloy volatility, squeezing custom-fabricated high-g-force units. Municipal wastewater operators exhibit acute price sensitivity, while pharmaceutical cleanroom specifications tolerate substantial premiums for validated CIP protocols and complete batch traceability.
Supply Chain Analysis
Dual-use technology export controls from Germany and Switzerland restrict precision bearing and high-speed drive system flows to non-EU destinations, concentrating critical component sourcing within a limited supplier base. Manufacturing gravity centers on Germany, Switzerland, and Italy, with Flottweg SE and Hiller Separation anchoring Bavarian fabrication clusters. Duplex stainless steel and superalloy feedstock draws from Swedish and Finnish specialty mills. Single-source vulnerability concentrates in precision spindle assemblies and ATEX-certified electrical enclosures. Distribution runs through OEM-direct channels for pharmaceutical accounts, while chemical processors in Eastern Europe procure via specialized industrial distributors with local service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe industrial centrifuge market is recovering from a cyclical trough driven by deferred capital replacement during energy price volatility, with replacement cycles now accelerating under EU Green Deal compliance deadlines.
For Market Incumbents: Entrench service network density through predictive maintenance platform deployment and remote vibration monitoring integration, countering the unbundling threat from specialized third-party analysis firms. Deepen backward integration into precision bearing refurbishment to reduce lead time exposure from Swiss and German component suppliers. Prioritize modular retrofit package engineering for brownfield chemical plants operating legacy PLC architectures, capturing upgrade revenue without full replacement cycles. For New Entrants and Emerging Players: Pursue the Polish and Czech biofuel refining corridor, where glycerin separation and catalyst recovery applications lack entrenched decanter suppliers and EU convergence funding covers capital costs. Target municipal wastewater operators in the Netherlands and Belgium facing sludge volume reduction mandates, offering energy-efficient dewatering centrifuges on performance-based service contracts. Establish direct relationships with vibration analysis specialists to bypass incumbent OEM service bundling. For Investors and Strategic Acquirers: Regional fabrication shops with ATEX certification capabilities and established Eastern European distributor relationships represent the most compelling acquisition archetype, offering platform consolidation potential without full technology development cycles. Long-term viability hinges on exposure to pharmaceutical and biofuel end-markets with regulatory-mandated replacement cycles rather than discretionary chemical processing investment. Watch ECHA enforcement intensity on seal material traceability as the inflection signal accelerating equipment replacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Deployment | Remote vibration monitoring from Alfa Laval anchors recurring revenue streams beyond traditional service contracts. |
| Modular Retrofit Package Engineering | Brownfield chemical plants in Poland and Czech Republic upgrade Soviet-era infrastructure without full replacement capital. |
| Backward Integration into Bearing Refurbishment | In-house spindle assembly capability reduces lead time vulnerability from concentrated Swiss and German suppliers. |
| Biofuel Decanter Configuration Development | Specialized glycerin separation designs capture first-mover advantage in Poland's Pomeranian refining corridor. |
| ATEX Electrical Drive System Certification | Zone 0/1 compliant enclosures displace pneumatic alternatives in solvent-handling chemical operations. |
Research Methodology
Cross-validation between executive interviews at centrifuge OEMs and maintenance directors at German chemical processors anchors the qualitative findings, with secondary validation drawing from ECHA enforcement disclosures, EU Green Deal implementation reports, and trade flow data through the Rhine-Alpine corridor. Primary fieldwork encompassed plant engineers at dairy cooperatives, aftermarket service heads at pharmaceutical manufacturers, and procurement leads at municipal wastewater authorities. Secondary sources included SEC filings from listed process equipment conglomerates, Cefic chemical industry statistics, and customs records for precision bearing imports. Bottom-up unit demand estimates triangulated against top-down industry spend analysis.
Calibration against historical replacement cycles and regulatory compliance timelines shaped the analytical framework across the analysis window. Segmentation dimensions modeled encompass product type, end-use industry, application objective, and drive technology architecture. CAGRs derived from weighted average of equipment shipment growth and aftermarket service expansion. Industry-specific forecast inputs incorporated EU Green Deal sludge reduction targets and EMA medical device regulation implementation phases.
Sensitivities concentrate around nickel and molybdenum alloy price volatility, ECHA enforcement intensity on REACH documentation, and Eastern European chemical sector capital allocation under EU convergence funding availability. Forecasts reflect assumptions on regulatory timeline adherence and energy pricing stabilization. Material shifts in EU effluent directive implementation schedules or superalloy supply disruption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Japan Ceramic Roller Bearings Market
Industrial Equipment
Industrial Joysticks Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Bellows Vacuum Suction Cup Market
Industrial Equipment
Liquid Cold Plates Market
Industrial Equipment
Parts and Equipment Market
Industrial Equipment
Laser Marking Machine Market
Industrial Equipment
Smart Pneumatics Market
Industrial Equipment
Thermal Cleaning System Market
Industrial Equipment
Europe Tempered Glass Cutting Machine Market
Industrial Equipment
UV Conveyor Systems Market
Industrial Equipment
TIG Torch Market
Industrial Equipment
Pin Insertion Machine Market
Industrial Equipment
Global Liquid Handling Systems Market
Industrial Equipment
Actuators Market
Industrial Equipment
Machine Tool Cooling System Market