
 Global Signal Conditioning Modules Market | 2026-2036
Global Signal Conditioning Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Global Signal Conditioning Modules Market Outlook
Asset-light leasing models for precision electronics manufacturing equipment is reconfiguring how mid-sized competitors enter the signal conditioning space. Siemens AG leverages captive semiconductor fabrication to sustain component supply advantages across European industrial corridors. Rockwell Automation, Inc. anchors North American demand through deep integration with automotive assembly line retrofits. Advantech Co., Ltd. dominates embedded computing channels in East Asian factory automation deployments.
Signal conditioning modules are electronic subsystems that filter, amplify, isolate, and convert raw sensor outputs into standardized electrical signals compatible with data acquisition and control systems, typically operating across temperature ranges from minus forty to plus eighty-five degrees Celsius with millivolt-level input sensitivity. Their primary commercial purpose is enabling accurate measurement and reliable process control in noisy industrial environments where unconditioned signals would corrupt downstream decision-making. Analog modules still occupy the largest revenue share due to legacy installed bases in process industries, though hybrid modules that merge electrical and optical isolation are capturing the fastest expansion as semiconductor fabrication and medical instrumentation demand higher noise immunity. Within end-use verticals, industrial automation concentrates the bulk of procurement volume, while aerospace applications generate premium margin pools through extended qualification and traceability requirements.
FDA 21 CFR Part 820 quality system regulations govern signal conditioning modules deployed in medical device manufacturing equipment across the United States, while EU RoHS and REACH frameworks restrict hazardous substance content in products sold throughout Europe. IEC 61010 safety standards for electrical test and measurement equipment shape insulation and creepage requirements for modules used in laboratory and field instrumentation. China's GB standards and MIIT certification protocols create separate conformity pathways for products targeting industrial digitization programs under dual carbon policy implementation. Stakeholders must monitor diverging regional certification timelines and build modular platform architectures that accommodate multiple compliance footprints without full hardware redesigns.
Market Dynamics
Industrial automation architectures are consolidating sensor-to-cloud data pipelines, compressing the traditional multi-vendor signal path into integrated edge-computing nodes that embed conditioning functions directly at measurement points.
Growth Catalysts
- EU RoHS substance restrictions:Manufacturers redesigning legacy analog modules to eliminate restricted cadmium and lead compounds are simultaneously upgrading isolation performance, creating replacement cycles across European process industries.
- Semiconductor fabrication:Wafer processing equipment demands sub-microvolt noise floors for plasma monitoring, pulling high-precision optical isolation modules into cleanroom instrumentation at triple the density of standard industrial deployments.
- German automotive test cells:Powertrain electrification programs require multi-channel temperature and vibration monitoring, concentrating procurement of thermocouple conditioning modules around Stuttgart and Munich engineering corridors.
Market Restraints
- Analog-to-digital converter silicon:Foundry capacity constraints for precision ADC dice extend lead times to 26 weeks, forcing module assemblers to absorb inventory carrying costs or risk line-down situations at OEM customers.
- Technical bandwidth limitations:Legacy 4-20mA current-loop architectures cannot transport the 100kHz-plus sensor data streams required for predictive maintenance algorithms, creating a retrofit liability for installed process control systems.
- REACH authorization delays:ECHA's pending restriction of certain flame retardants used in module housings forces dual-sourcing of polymer compounds, adding qualification overhead before European market entry.
Strategic Opportunities
- India industrial corridors:PLI scheme incentives for electronics manufacturing are attracting module assembly investments to Gujarat and Tamil Nadu, creating localized supply for domestic automation OEMs previously dependent on Chinese imports.
- Medical instrumentation convergence:IEC 60601-1 isolation requirements for patient-connected equipment are merging with industrial signal conditioning specifications, opening cross-certification pathways for hybrid module platforms.
- Edge AI sensor fusion:Combining MEMS accelerometer arrays with conditioning front-ends enables vibration signature analysis at the measurement node, displacing centralized PLC architectures in rotating equipment monitoring.
Industry Challenges
- IEC 61010-2-030 certification timelines:Third-party laboratory testing for measurement category overvoltage ratings extends 14-18 months, compressing product refresh windows and freezing design architectures mid-development.
- Legacy 4-20mA integration:Brownfield process plants operate mixed-vintage control systems spanning three decades of communication protocols, forcing module vendors to maintain obsolete Hart modem interfaces alongside modern IO-Link implementations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Signal Conditioning Modules Market |
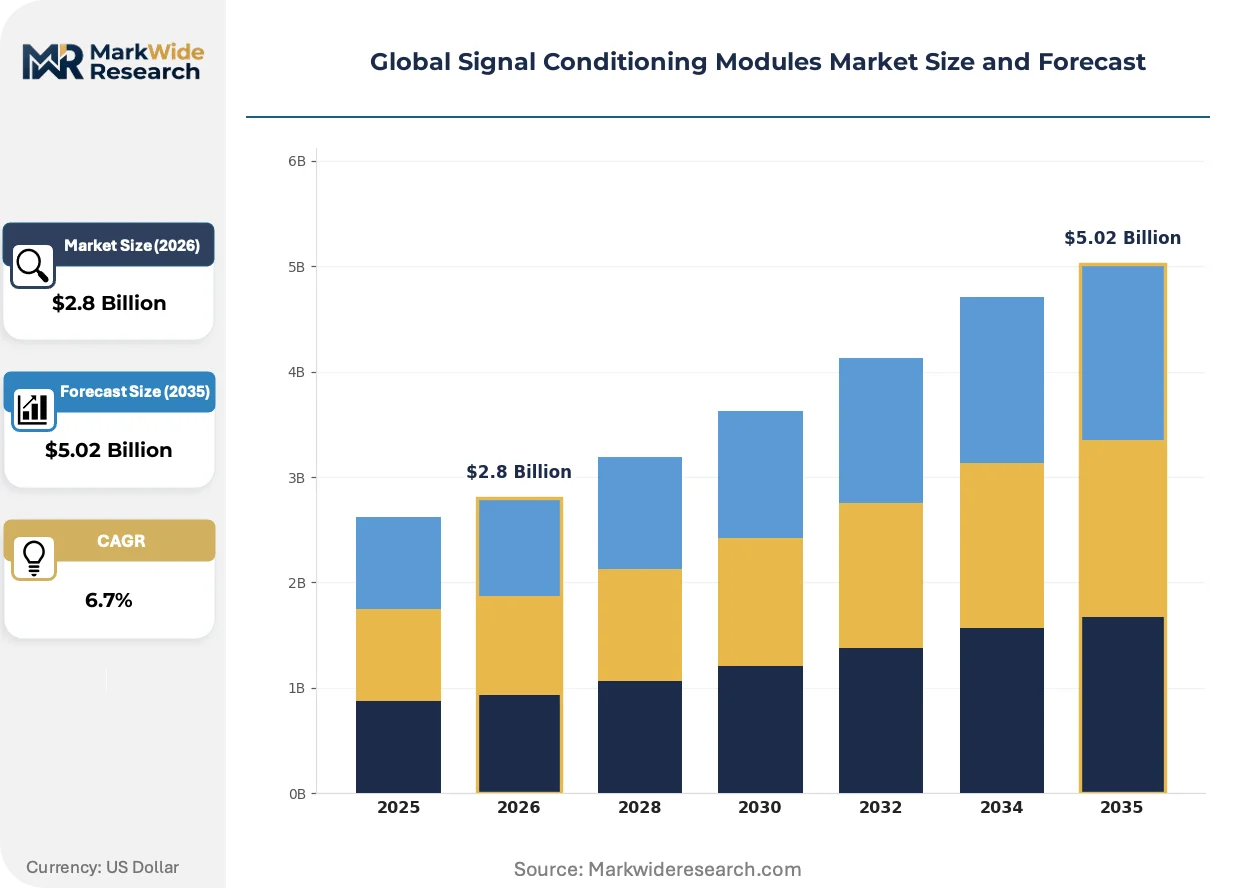
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Modules, Digital Modules, Hybrid Modules, RF Modules End User: Aerospace, Automotive, Telecommunication, Industrial Automation Technology: Mechanical, Electrical, Optical, Hybrid Application: Data Acquisition, Instrumentation, Process Control, Testing Equipment |
| Companies Covered | Rockwell Automation, Inc., Siemens AG, Phoenix Contact GmbH & Co. KG, Schneider Electric, Pepperl+Fuchs, Yokogawa Electric Corporation, TE Connectivity Ltd., Advantech Co., Ltd., ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Signal Conditioning Modules Market Strategic Shifts
Signal conditioning architectures are fragmenting along isolation-technology lines as end-users trade electrical noise immunity against optical transmission bandwidth in mission-critical measurement chains.
Hybrid opto-electrical isolation is hybridizing the traditional separation between galvanic and fiber-optic signal paths. Semiconductor lithography equipment manufacturers in Japan and the Netherlands are adopting these merged architectures for plasma etch monitoring, where nanosecond pulse fidelity must survive kilovolt ground differentials. The technology is hybridizing procurement specifications, collapsing what were separately sourced electrical and optical modules into single-subsystem vendor relationships.
EU F-Gas Regulation phase-down schedules are pressuring manufacturers to eliminate sulfur hexafluoride from high-voltage test equipment used in signal conditioning module certification. Insulation testing laboratories in Germany and France are retrofitting dielectric withstand stations with compressed air alternatives, extending equipment depreciation cycles. Medical device OEMs sourcing conditioning modules for MRI-compatible instrumentation face tightened supplier qualification demands as gas-tracking documentation requirements expand.
Automotive Tier-1 suppliers are unbundling hardware procurement from calibration services, treating signal conditioning modules as commodity substrates while contracting specialized integrators for channel-matching and linearization algorithms. This pattern concentrates in Michigan and Baden-Württemberg, where powertrain test stand operators now source modules through distributor inventories but engage engineering service firms for application-specific firmware. The separation compresses hardware margins while expanding recurring revenue pools for software-enabled accuracy guarantees.
Global Signal Conditioning Modules Market Segmentation
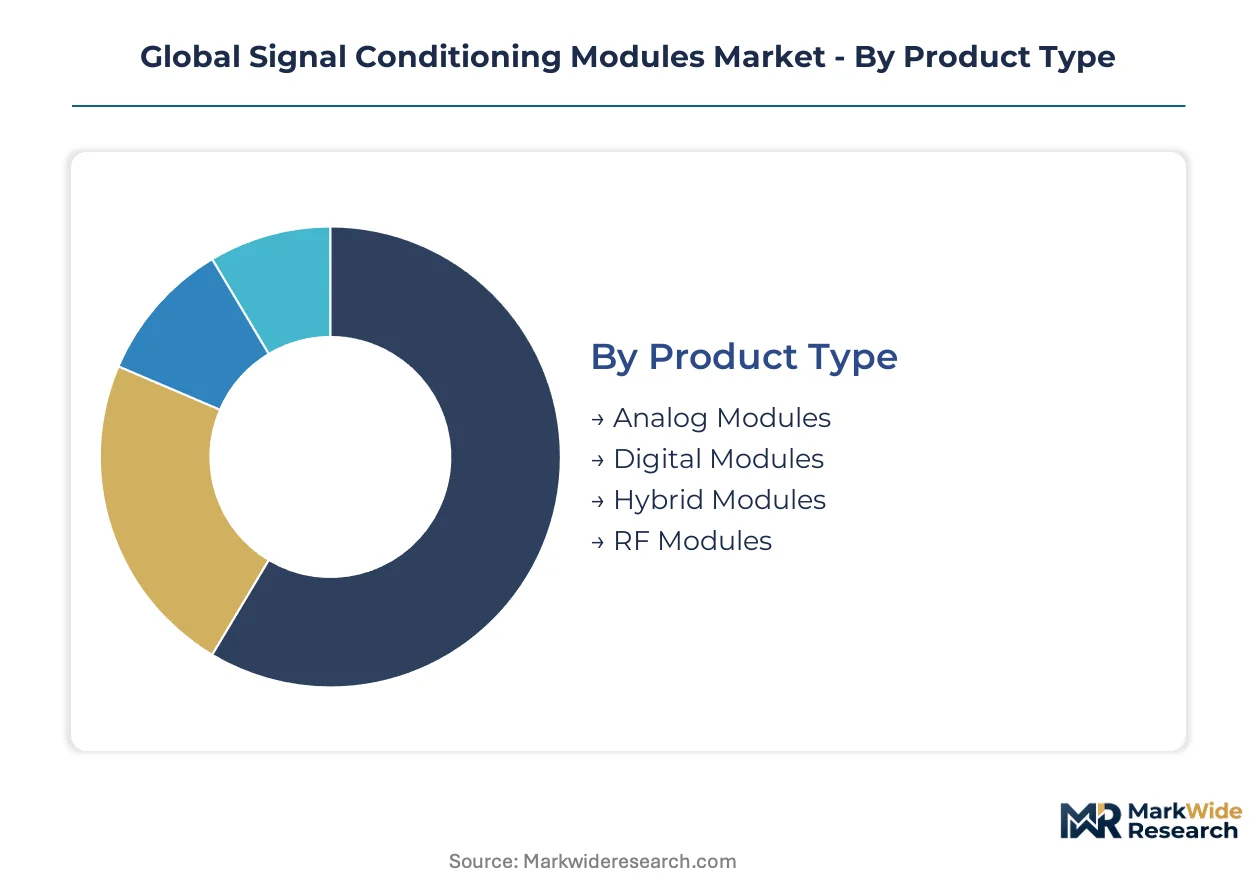
Signal conditioning modules serve radically different support lifecycles depending on segment—analog modules in process plants demand decades of calibration servicing, while digital modules in automotive test cells require rapid firmware refresh cycles. Procurement patterns diverge sharply across these axes, with after-sales contracts representing up to forty percent of lifetime revenue in industrial automation versus under ten percent in consumer-facing electronics integration.
Product Type:
After-sales intensity concentrates in analog and hybrid architectures where drift compensation and isolation degradation monitoring drive recurring service contracts, while digital modules shift margin toward upfront licensing.
- Analog Modules:Continuous-time circuitry with operational amplifiers and passive filtering networks processes millivolt-level sensor outputs without digital conversion latency. Demand clusters in German chemical processing corridors along the Rhine, where BASF and Bayer facilities maintain twenty-year replacement cycles for 4-20mA loop conditioners. IEC 61010 calibration mandates force annual recertification, embedding module vendors deeply in plant maintenance workflows.
- Hybrid Modules:Merge electrical isolation barriers with fiber-optic transmission stages to achieve sub-microvolt noise floors across kilovolt ground differentials. Japanese semiconductor lithography equipment manufacturers in Yokohama and Dutch plasma etch system builders in Eindhoven specify these for cleanroom instrumentation, pulling triple-density deployment rates versus standard industrial configurations. RoHS redesign cycles are accelerating replacement demand as vendors eliminate legacy cadmium-plated housings.
- Digital Modules:Integrated ADC-DSP chains with programmable gain amplifiers and digital filtering algorithms. Automotive test cell integrators in Michigan specify these for powertrain vibration analysis.
- RF Modules:Impedance-matched conditioning front-ends for GHz-range sensor telemetry in radar and communication test systems. 5G base station deployment in South Korea drives procurement.
By volume, Analog Modules leads. By growth pace, Hybrid Modules is ahead.
End User:
Cost tier stratification separates premium-margin aerospace qualification programs from high-volume industrial automation procurement, with automotive occupying an intermediate position on both axes.
- Industrial Automation:Factory floor sensor networks for temperature, pressure, and position monitoring across discrete and process manufacturing. PLC integration demands in Stuttgart engineering corridors concentrate thermocouple and strain-gauge conditioner procurement. Edge-computing consolidation is compressing discrete module counts into embedded multi-channel nodes.
- Aerospace:Extended temperature-range conditioning for flight-test instrumentation and airframe health monitoring. FAA DER traceability requirements and DO-160G environmental qualification extend development timelines to thirty-six months, concentrating procurement with Lockheed Martin and Airbus tier-one instrumentation suppliers in Fort Worth and Toulouse. Extended qualification creates margin premiums of four to six times industrial equivalents.
- Automotive:Powertrain test stand conditioning for electrification program validation. Battery thermal runaway testing in Baden-Württemberg pulls multi-channel thermocouple modules.
- Telecommunication:Signal integrity conditioning for fiber-optic line testing and base station calibration. 5G mmWave deployment in urban China drives demand.
Aerospace commands the highest per-unit margins. Industrial Automation captures the greatest absolute revenue.
Technology:
Application maturity separates entrenched electrical isolation from emerging optical architectures, with hybrid approaches gaining traction in mission-critical measurement chains.
- Electrical:Transformer and capacitive isolation barriers with defined creepage distances for industrial voltage categories. IEC 61010-2-030 measurement category ratings govern insulation coordination in laboratory and field instrumentation sold throughout Europe. Legacy installed base in process industries sustains volume despite bandwidth limitations.
- Optical:Fiber-optic transmission eliminating ground loop susceptibility for high-voltage differential measurements. Semiconductor plasma monitoring in Japan and the Netherlands specifies these for nanosecond pulse fidelity.
- Mechanical:Vibration-isolated mounting and thermal stabilization for precision strain-gauge and piezoelectric sensors. Materials testing laboratories in Switzerland deploy these for microstrain resolution.
- Hybrid:Combined galvanic and fiber-optic stages merging noise immunity with transmission bandwidth. Medical imaging OEMs in Massachusetts and Minnesota specify these for MRI-compatible patient monitoring.
Electrical isolation retains the largest installed base. Hybrid architectures are climbing the fastest.
Application:
Customer type bifurcation separates OEM equipment builders from end-user retrofit procurement, with data acquisition trending toward integrated system sales and process control remaining fragmented.
- Process Control:Real-time signal conditioning for closed-loop regulatory control in chemical, pharmaceutical, and food processing. FDA 21 CFR Part 820 quality system regulations govern modules deployed in US medical device manufacturing equipment, forcing documentation rigor that European process vendors rarely match. Brownfield plants operate mixed-vintage systems spanning Hart, Foundation Fieldbus, and IO-Link protocols, forcing module vendors to maintain obsolete interface support.
- Data Acquisition:Multi-channel scanning and synchronization for research and development test campaigns. National Instruments and Keysight integration in Austin and Santa Rosa concentrates procurement of high-speed synchronized modules. Edge AI sensor fusion is displacing centralized architectures in rotating equipment monitoring applications.
- Instrumentation:Laboratory-grade conditioning for test and measurement equipment. German calibration laboratories specify these for DAkkS-traceable measurement chains.
- Testing Equipment:Production-line functional test and burn-in screening for electronics manufacturing. Contract manufacturers in Vietnam and Mexico deploy these for consumer electronics quality assurance.
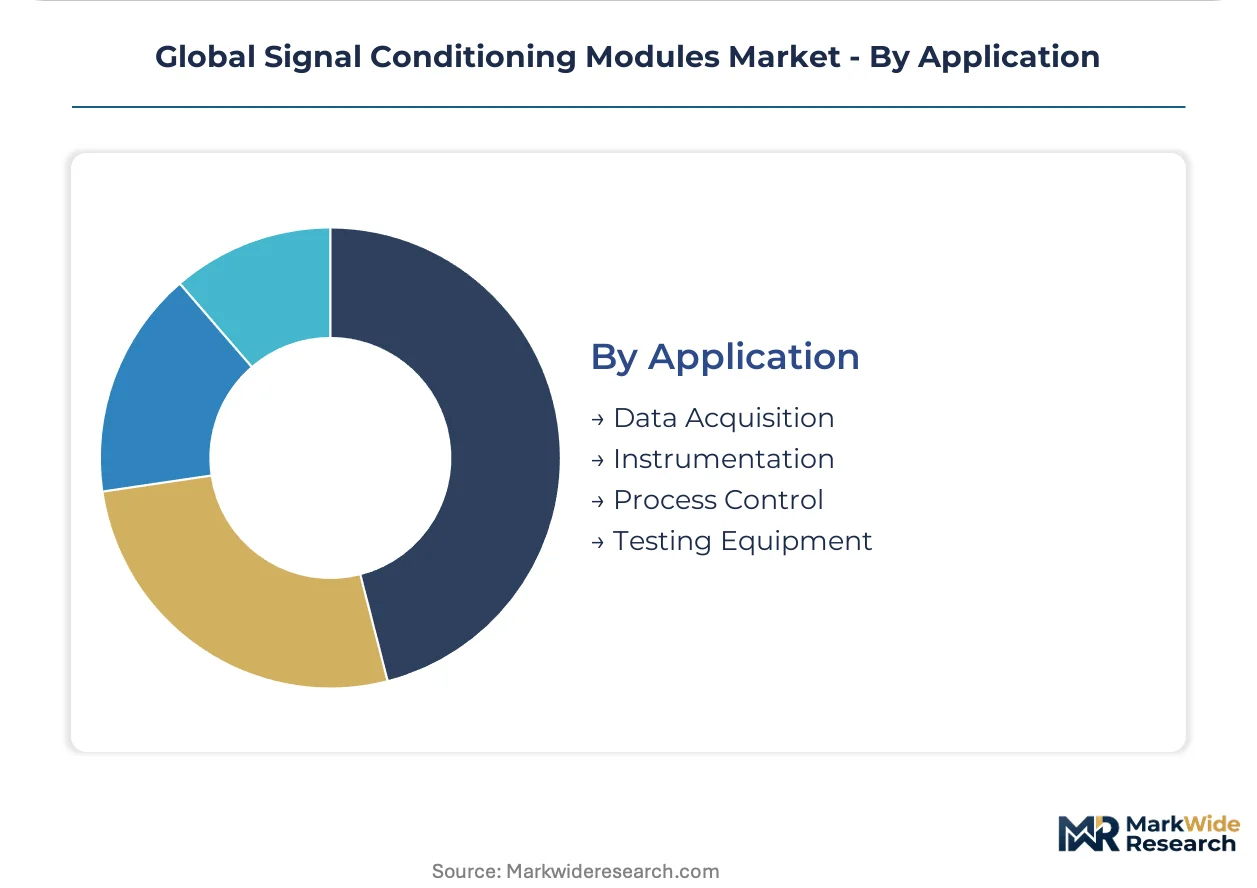
Process Control dominates replacement-driven revenue. Data Acquisition is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and Japanese semiconductor equipment manufacturers concentrate the highest-value procurement, while US industrial automation integrators and Chinese factory digitization programs drive volume expansion.
United States
Automotive assembly line retrofits and medical device manufacturing equipment sustain demand for FDA 21 CFR Part 820 compliant modules. Michigan powertrain test stand operators source through distributor inventories while engaging engineering service firms for calibration algorithms. Austin and Santa Rosa clusters concentrate National Instruments and Keysight integration for high-speed synchronized data acquisition.
Germany
Stuttgart and Munich engineering corridors drive thermocouple conditioning module procurement for battery thermal runaway testing and powertrain electrification programs. EU RoHS substance restrictions and REACH authorization timelines force polymer compound dual-sourcing before market entry. DAkkS-traceable calibration laboratories in Baden-Württemberg specify laboratory-grade instrumentation for measurement chains.
Japan
Yokohama semiconductor lithography equipment manufacturers specify hybrid opto-electrical isolation for plasma etch monitoring with nanosecond pulse fidelity requirements. METI industrial digitization policies align with IEC 61010 safety standards for electrical test equipment. Cleanroom instrumentation deployments run at triple the density of standard industrial configurations.
China
MIIT certification protocols and GB standards create separate conformity pathways for industrial digitization programs under dual carbon policy implementation. Yangtze River Delta factory automation deployments absorb embedded computing channels for sensor-to-cloud data pipelines. Brownfield process plants operate mixed-vintage control systems spanning three decades of communication protocols.
India
PLI scheme incentives for electronics manufacturing attract module assembly investments to Gujarat and Tamil Nadu, creating localized supply for domestic automation OEMs. BIS standards govern product certification while CEA regulations shape electrical equipment safety requirements. Domestic OEMs previously dependent on Chinese imports now source from regional assembly operations.
Global Signal Conditioning Modules Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. The vendor base spans integrated industrial conglomerates with captive semiconductor fabrication and focused module specialists serving single-vertical applications. Strategic archetypes include automation platform integrators, component supply captives, and embedded computing channel dominators. Competitive moves concentrate on backward integration into precision ADC sourcing and geographic expansion through PLI-aligned assembly investments.
Among Germany-based industrial conglomerates, Siemens AG exemplifies the captive semiconductor fabrication archetype sustaining component supply advantages. Rockwell Automation, Inc. anchors North American positioning through automotive assembly line retrofit integration. Advantech Co., Ltd. occupies the embedded computing channel specialist tier in East Asian factory automation deployments.
| Leading Market Players |
|---|
| Rockwell Automation, Inc. |
| Siemens AG |
| Phoenix Contact GmbH & Co. KG |
| Schneider Electric |
| Pepperl+Fuchs |
| Yokogawa Electric Corporation |
| TE Connectivity Ltd. |
| Advantech Co., Ltd. |
| ABB |
| Others |
Value Chain & Pricing Dynamics
Yokohama semiconductor equipment clusters anchor precision ADC sourcing for signal conditioning module assemblers, concentrating component bargaining power among Japanese foundries and compressing hardware margins for European system integrators dependent on optical isolation die.
Pricing Analysis
Certification level creates the primary spread across the pricing spectrum, with IEC 61010-2-030 and FDA 21 CFR Part 820 compliant modules commanding substantial premiums over industrial-grade equivalents. Three-tier pricing structure across premium, standard, and economy levels reflects isolation performance, channel count density, and calibration service bundling. Cost compression in standard analog tiers is intensifying because foundry capacity constraints for precision converter silicon extend procurement cycles. Automotive test cell operators in Michigan exhibit the highest price sensitivity, while aerospace qualification programs in Toulouse and Fort Worth absorb premiums without volume negotiation.
Supply Chain Analysis
Extended payment terms from German automotive OEMs and supply-chain finance facilities from Japanese semiconductor equipment manufacturers reshape working capital requirements for module assemblers. Component sourcing concentrates in Japan, Taiwan, and Germany for precision ADC dice, optocouplers, and isolation transformers. Polymer compound supply for RoHS-compliant housings draws from specialized European and Chinese chemical processors. Single-source vulnerability around precision analog foundry capacity represents the dominant structural risk. Distribution runs through automation distributor networks in North America and direct OEM relationships in European automotive corridors.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Signal conditioning module vendors increasingly capture value through calibration service contracts and firmware licensing, with recurring revenue layers expanding faster than discrete hardware shipments as automotive test cell operators unbundle procurement from integration services.
For Market Incumbents: Harden defensive positions by deepening backward integration into precision ADC sourcing and accelerating IEC 61010-2-030 certification pipelines to freeze competitor design windows. Captive semiconductor fabrication sustains component supply advantages against emerging Asian assemblers. Channel control through automation platform integration anchors replacement part capture.
For New Entrants and Emerging Players: Mid-market industrial automation OEMs in India and Vietnam represent the most penetrable entry point, with PLI scheme incentives reducing import dependency and creating localized supply relationships. Medical instrumentation convergence between IEC 60601-1 and industrial specifications opens cross-certification pathways without full hardware redesign. Go-to-market execution should prioritize distributor partnerships over direct OEM engagement.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid opto-electrical isolation specialists with established cleanroom instrumentation relationships in semiconductor fabrication. Long-term viability hinges on defensible IP around nanosecond pulse fidelity and kilovolt ground differential performance. Acquisition targets should demonstrate recurring calibration revenue streams exceeding twenty percent of total sales. The signal to monitor is edge AI sensor fusion adoption displacing centralized PLC architectures in rotating equipment monitoring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision ADC Sourcing | Captive semiconductor fabrication reduces foundry dependency for Yokohama and Eindhoven equipment builders. |
| Hybrid Module Platform Development | Merged galvanic and fiber-optic architectures address plasma monitoring requirements in Japanese lithography equipment. |
| Calibration Service Contract Expansion | Annual IEC 61010 recertification mandates embed vendors deeply in BASF and Bayer maintenance workflows. |
| PLI-Aligned Assembly Investment | Gujarat and Tamil Nadu facilities supply domestic Indian automation OEMs previously dependent on Chinese imports. |
| Cross-Certification Pathway Construction | IEC 60601-1 and industrial specification merging opens medical imaging opportunities in Massachusetts and Minnesota. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and equipment procurement databases. Plant engineers at BASF and Bayer facilities, procurement leads at Yokogawa and Keysight, aftermarket service heads at Siemens and Rockwell Automation, and technical R&D directors at Advantech provided operational perspectives. Secondary validation drew from IEC 61010 certification registries, EU RoHS compliance declarations, FDA 21 CFR Part 820 quality system records, and SEC filings from listed automation conglomerates. Bottom-up channel checks triangulate against top-down market sizing across product type, end user, and technology segmentation.
Forecast inputs include semiconductor fabrication capacity expansion timelines, automotive electrification program validation schedules, and industrial digitization policy implementation rates across the projection horizon. Segmentation dimensions modeled encompass product architecture, isolation technology, end-use vertical, application function, and regional regulatory cluster. CAGRs derive from historical shipment trajectories adjusted for replacement cycle acceleration and protocol migration patterns. Edge AI sensor fusion adoption curves and REACH authorization timeline uncertainty feed sensitivity bands.
Stress conditions across foundry capacity utilization, polymer compound availability, and certification laboratory backlog were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about semiconductor equipment capital expenditure continuity and automotive test stand buildout pacing. Macroeconomic contraction, accelerated REACH restrictions, or breakthrough wireless sensor architectures would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Machine Control System Market
Sensors and Controls
Asia-Pacific Electric Vehicle Sensor Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Piezoelectric Devices Market
Sensors and Controls
Timing Device Market
Sensors and Controls
Global E-Compass Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Water Cut Monitor Market
Sensors and Controls
Mexico Pressure Sensor Market
Sensors and Controls
APAC Acoustic Sensors Market
Sensors and Controls
Industrial Combustion Control Components and Systems Market
Sensors and Controls
MEMS Pressure Sensors Market
Sensors and Controls
Semiconductor Pyrometers Market
Sensors and Controls
Lighting Control Sensors Market
Sensors and Controls
Global Wireless Sensors Network Market