
 Hydrogen Peroxide Market | 2026-2036
Hydrogen Peroxide Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Peroxide Market Analysis
The gap between premium and commodity tiers is broadening as semiconductor fabs demand sub-ppb metal impurity specifications while pulp mills optimize on cost per active oxygen unit. Solvay leverages its integrated peracetic acid derivatives chain to capture margin in electronics-grade supply. Kemira Oyj anchors Nordic water treatment demand through long-term municipal contracts. Nouryon differentiates via proprietary anthraquinone process technology that cuts energy intensity.
Hydrogen peroxide is an aqueous solution of hydrogen peroxide (H₂O₂), typically manufactured through the anthraquinone auto-oxidation process yielding concentrations from 35% to 70% by weight, serving primarily as an oxidizing agent, bleaching medium, and sterilizing agent across industrial and consumer applications. Industrial grade dominates volume flows into pulp bleaching and textile processing, where margin compression is structural. Pharmaceutical grade commands premium pricing from healthcare sterilization protocols, while electronics manufacturing applications represent the fastest-growing demand pool as wafer fabrication expands.
The EPA regulates hydrogen peroxide under TSCA and FIFRA frameworks governing chemical manufacturing and antimicrobial claims, while OSHA sets permissible exposure limits for worker safety in production facilities. The EU REACH regulation and RoHS directives constrain residual contaminants in grades destined for electronics and consumer goods, reshaping import compliance burdens. Stakeholders must monitor how dual carbon targets in China and the EU Green Deal's industrial emissions benchmarks redirect capital toward lower-carbon production routes.
Market Dynamics
The hydrogen peroxide market pivots on tightening discharge standards under the EPA's Clean Water Act, which compels municipal utilities to replace chlorine-based treatment with advanced oxidation processes that consume industrial-grade volumes.
Growth Catalysts
- EPA enforcement:The Clean Water Act's tightening effluent limits force municipal utilities across the United States to adopt advanced oxidation processes, directly lifting industrial-grade consumption.
- Semiconductor fabrication:Wafer manufacturing in Taiwan and South Korea demands sub-ppb metal impurity specifications, creating a premium demand pool that outpaces commodity-grade growth.
- Anthraquinone process improvements:Energy intensity reductions in the dominant production route lower unit costs and expand supply availability for emerging applications.
Market Restraints
- Anthracene feedstock volatility:Fluctuations in aromatic hydrocarbon pricing compress margins for producers dependent on external anthraquinone precursor supply.
- Chinese production concentration:Over half of global capacity sits in Shandong and Jiangsu provinces, exposing buyers to localized environmental shutdowns and export restriction risks.
- Peracetic acid substitution:Cold sterilization applications in food packaging increasingly favor peracetic acid derivatives that offer equivalent antimicrobial efficacy with lower handling hazards.
Strategic Opportunities
- India water infrastructure:The Jal Jeevan Mission's rural sanitation targets create a municipal procurement pipeline that remains underdeveloped for advanced oxidation chemicals.
- Green hydrogen integration:Electrolytic hydrogen production paired with direct synthesis routes offers a low-carbon alternative to anthraquinone oxidation for carbon-conscious buyers.
- EU Green Deal industrial emissions benchmarks:Capital redirection toward lower-carbon production routes rewards early movers with preferential offtake terms from European electronics manufacturers.
Industry Challenges
- Electronics-grade certification timelines:SEMI-standard qualification protocols for semiconductor fabs extend 18-24 months, locking out new entrants regardless of technical capability.
- Specialized logistics infrastructure:Concentrated hydrogen peroxide requires stainless-steel tanker fleets and temperature-controlled storage that legacy chemical distributors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Peroxide Market |
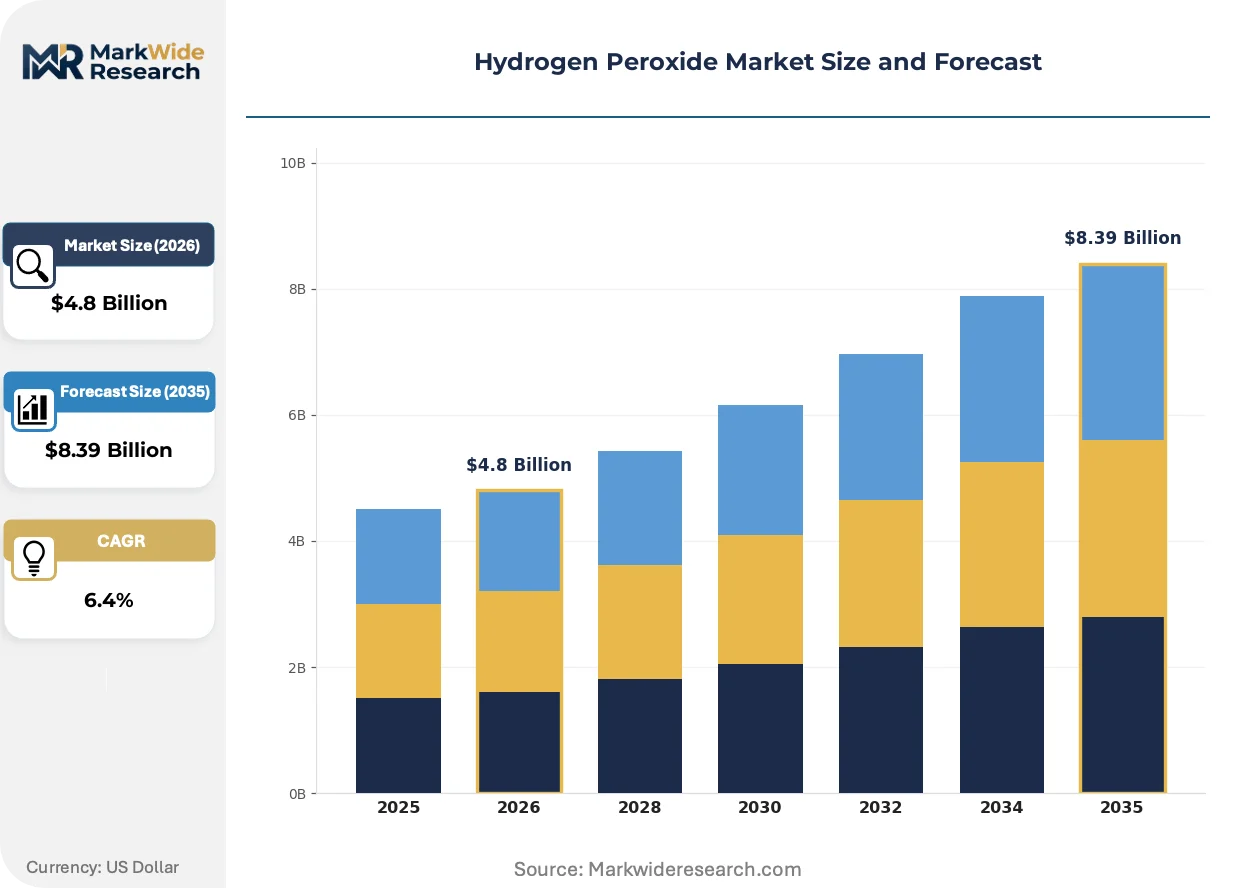
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Cosmetic Grade Application: Textile Processing, Water Treatment, Electronics Manufacturing, Pulp & Paper End User: Healthcare, Food & Beverage, Chemical Industry, Agriculture Packaging Type: Drums, IBC Totes, Bottles, Bulk Containers |
| Companies Covered | Solvay, Evonik Industries AG, Arkema, Nouryon, Mitsubishi Gas Chemical Company Inc., Kemira Oyj, Taekwang Industrial Co., Ltd., OCI Company Ltd., Gujarat Alkalies & Chemicals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Peroxide Market Emerging Trajectories
Production technology and procurement patterns are diverging sharply between premium and commodity tiers, with process innovation concentrating in high-purity segments while bulk applications optimize on cost per active oxygen unit.
Membrane electrolysis for on-site generation is rewriting supply economics for remote industrial users. Mining operations in Western Australia and pulp mills in Scandinavia deploy modular units to eliminate transportation costs from concentrated production hubs. This distributed model compresses the addressable market for bulk merchant supply in peripheral geographies.
REACH regulation amendments on residual contaminants in chemicals destined for electronics and consumer goods are reshaping import compliance burdens for Asian producers. The European Chemicals Agency's tightened substance evaluation protocols force reformulation of stabilizer packages. Electronics-grade suppliers in Germany and the Netherlands invest in dedicated purification trains to maintain CE-marked access.
Buyer consolidation among semiconductor foundries is compressing supplier qualification cycles and consolidating procurement volumes with fewer qualified vendors. TSMC and Samsung Foundry now mandate dual-source redundancy with identical specifications, forcing smaller producers to match the analytical capabilities of integrated majors. This concentration is most visible in Taiwan's Hsinchu Science Park, where three buyers account for the majority of regional high-purity offtake.
Hydrogen Peroxide Market Segmentation
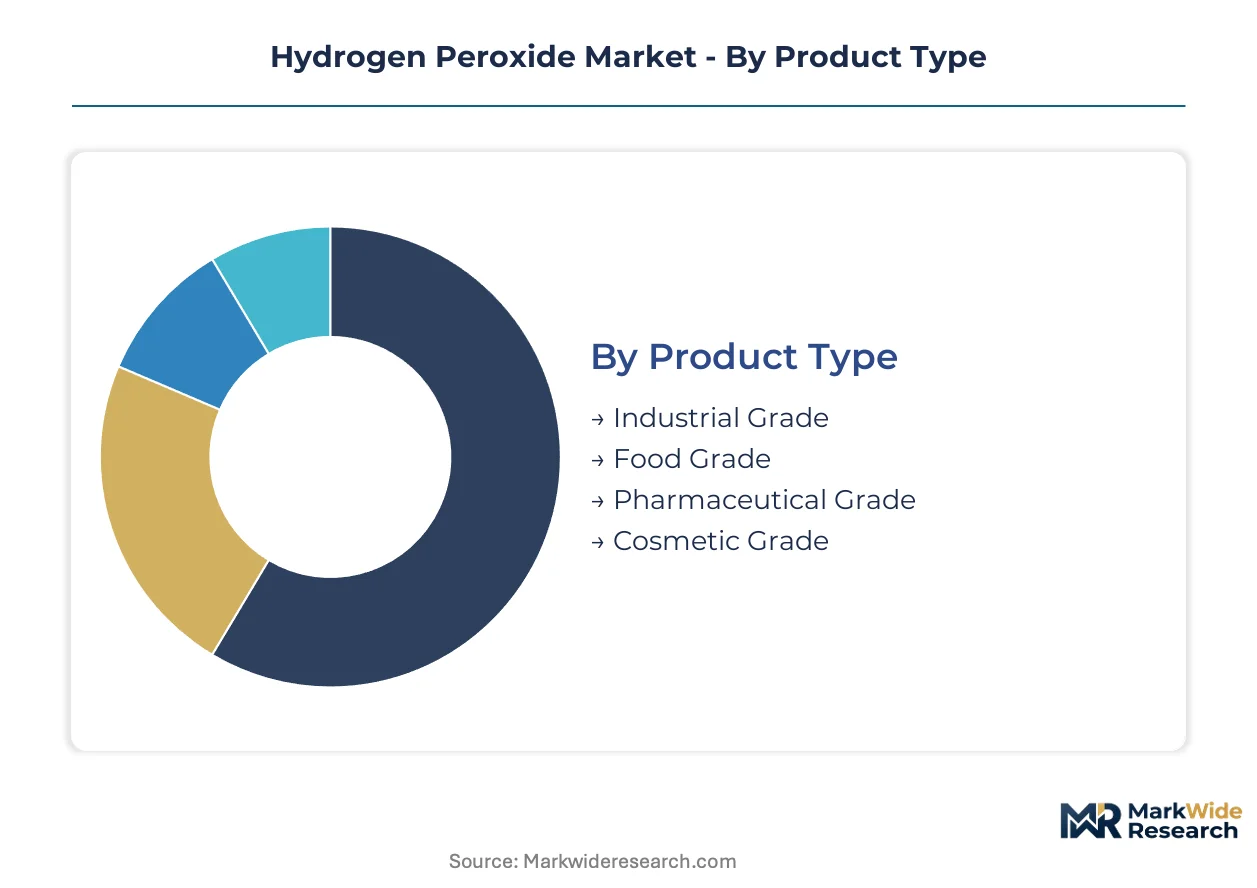
Grade purity requirements diverge sharply between commodity bleaching operations and semiconductor fabrication, creating parallel supply chains with incompatible logistics and pricing structures. Each segment tier commands distinct certification protocols that lock buyers into qualified supplier relationships.
Product Type:
Supply concentrates in industrial-grade capacity while electronics and healthcare applications absorb nearly all margin expansion through purity premiums.
- Industrial Grade:Concentrations from 35% to 70% by weight serve pulp bleaching and textile processing where buyers optimize on cost per active oxygen unit. Chinese mills in Shandong province consume the largest single demand pool, though EPA Clean Water Act enforcement is redirecting municipal procurement toward this grade for advanced oxidation processes.
- Pharmaceutical Grade:USP-compliant specifications with stringent microbial limits command substantial premiums from healthcare sterilization protocols. FDA enforcement of 21 CFR Part 211 drives qualification costs that exclude commodity producers, concentrating supply among dedicated GMP-certified facilities.
- Food Grade:CFR 184.1366 compliance permits use as a bleaching agent in food starch and as a direct food additive.
- Cosmetic Grade:Lower concentration formulations with cosmetic-grade stabilizers serve hair bleaching and personal care applications.
Today's leader: Industrial Grade. Tomorrow's challenger: Pharmaceutical Grade.
Application:
Margin structures invert between volume-heavy commodity segments and purity-driven specialty applications where qualification timelines extend procurement cycles.
- Electronics Manufacturing:Sub-ppb metal impurity specifications for wafer cleaning and etching processes create the steepest expansion trajectory among all application segments. TSMC and Samsung Foundry procurement in Taiwan and South Korea concentrates demand with qualified vendors who maintain SEMI-standard certification.
- Pulp & Paper:Chlorine-free bleaching sequences consume the largest absolute volumes globally, though margin compression is structural as mills optimize on total bleaching cost. Nordic producers anchor European demand through long-term supply contracts with integrated chemical suppliers.
- Water Treatment:Advanced oxidation processes for municipal effluent treatment are expanding most quickly in the United States following EPA enforcement tightening.
- Textile Processing:Bleaching and desizing operations in India and Bangladesh drive procurement of standard industrial grades.
Electronics Manufacturing claims the steepest margin expansion; Pulp & Paper retains volume dominance.
End User:
Customer procurement sophistication varies from spot-market commodity purchasing to multi-year qualification-dependent supply agreements.
- Chemical Industry:Derivatives manufacturing including peracetic acid and propylene oxide integration consumes substantial captive production. Solvay's integrated peracetic acid chain exemplifies backward integration strategies that capture margin downstream.
- Healthcare:Hospital sterilization and pharmaceutical manufacturing demand GMP-certified supply with full batch traceability, creating sticky supplier relationships resistant to price competition.
- Food & Beverage:Aseptic packaging sterilization and food processing applications require FDA-compliant grades with documented residual limits.
- Agriculture:Crop treatment and aquaculture applications represent emerging demand with lower certification barriers.
Healthcare commands the tightest supplier lock-in; Chemical Industry offers the largest volume leverage.
Packaging Type:
Logistics infrastructure requirements scale with concentration levels, fragmenting distribution networks between bulk industrial supply and packaged specialty grades.
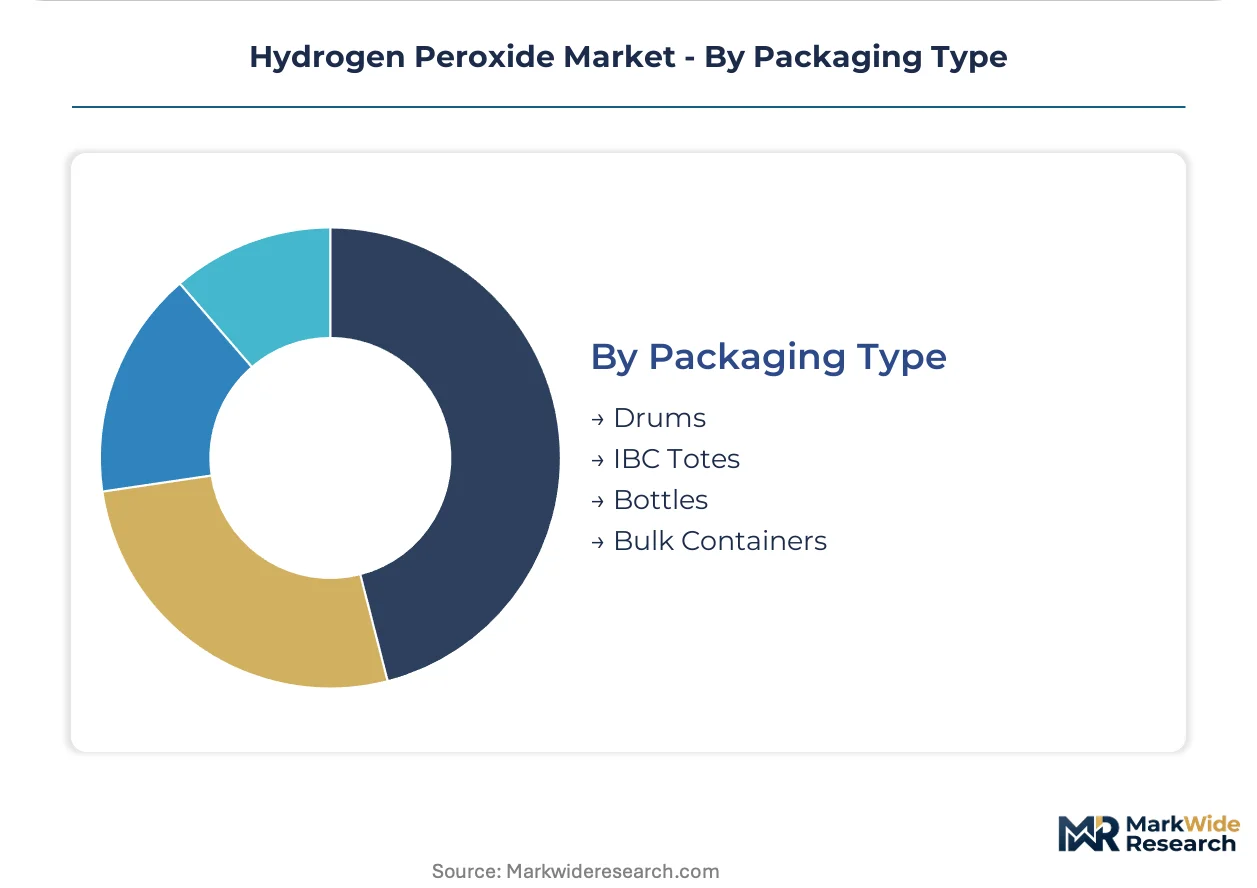
- Bulk Containers:Stainless-stank tanker fleets and dedicated terminal infrastructure serve concentrated industrial users with direct pipeline connections. Pulp mills and large textile processors in China and the United States dominate this procurement mode.
- Drums:Standard 200-liter steel drums serve mid-scale industrial users lacking bulk storage infrastructure.
- IBC Totes:Intermediate bulk containers bridge drum and bulk economics for facilities with limited storage capacity.
- Bottles:Retail and small-scale professional use in cosmetics and healthcare applications.
Bulk Containers anchor industrial economics; IBC Totes capture flexible mid-market demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized process engineers and chemical operations talent cluster in industrial corridors where anthraquinone oxidation capacity has scaled over decades. This workforce concentration shapes where production assets and downstream technical service capabilities locate.
China
Textile mills in Shandong and electronics fabs in Jiangsu province absorb divergent grade specifications. The Ministry of Ecology and Environment enforces dual carbon targets that redirect capital toward lower-emission production routes. Environmental shutdowns in the Yangtze River Delta periodically constrain export availability.
United States
Pulp mills in the Southeast and municipal utilities nationwide drive industrial-grade consumption. EPA Clean Water Act enforcement tightens effluent limits, compelling advanced oxidation process adoption. The Gulf Coast petrochemical corridor hosts integrated peroxide-derivative manufacturing.
Germany
Electronics-grade demand concentrates in Saxony's semiconductor fabrication cluster. EU REACH amendments on residual contaminants force reformulation of stabilizer packages. Dedicated purification trains in the Rhine-Ruhr industrial region maintain CE-marked access for high-purity supply.
South Korea
Samsung Foundry and SK Hynix procurement in the Seoul Capital Area demands sub-ppb metal impurity specifications. The Ministry of Trade, Industry and Energy supports domestic chemical self-sufficiency initiatives. Busan-Ulsan hosts bulk industrial supply for textile and paper processors.
India
The Jal Jeevan Mission's rural sanitation targets create municipal procurement pipelines for advanced oxidation chemicals. Textile bleaching operations in Gujarat and Tamil Nadu drive standard industrial-grade demand. Water infrastructure gaps in tier-2 cities limit immediate uptake of premium treatment technologies.
Hydrogen Peroxide Market Vendor Landscape
Capital-heavy producers compete with asset-light distributors across incompatible logistics requirements. The market structures around three tiers: integrated chemical majors with captive anthraquinone supply, regional specialists serving single industries, and merchant distributors lacking stainless-steel tanker fleets. Consolidation pressure intensifies as semiconductor foundries mandate dual-source redundancy, compressing supplier qualification cycles. Dominant competitive moves include backward integration into peracetic acid derivatives and modular on-site generation deployments.
Within the integrated major tier, Solvay and Nouryon exemplify producers leveraging proprietary process technology and derivative chains to capture margin in premium grades. Kemira Oyj anchors Nordic water treatment demand through long-term municipal contracting positions. Among Asia-Pacific-based suppliers, Mitsubishi Gas Chemical Company Inc. and OCI Company Ltd. occupy positions serving electronics fabrication clusters with high-purity specifications.
| Leading Market Players |
|---|
| Solvay |
| Evonik Industries AG |
| Arkema |
| Nouryon |
| Mitsubishi Gas Chemical Company Inc. |
| Kemira Oyj |
| Taekwang Industrial Co., Ltd. |
| OCI Company Ltd. |
| Gujarat Alkalies & Chemicals Ltd. |
| Others |
Supply Flow & Price Mechanics
Anthracene feedstock pricing volatility cascades through anthraquinone oxidation economics, compressing margins for producers without captive precursor supply while amplifying spreads between industrial-grade spot markets and electronics-grade contract premiums. Buyers in Shandong province and Taiwan's Hsinchu Science Park face divergent procurement economics shaped by these input cost trajectories.
Pricing Analysis
Service bundling separates logistics-inclusive contract terms from unbundled spot transactions. Three-tier pricing structure across electronics-grade, pharmaceutical-grade, and industrial-grade levels reflects certification investment recovery and dedicated purification train costs. Cost compression in industrial-grade supply is intensifying because Chinese mills optimize on cost per active oxygen unit. Municipal utilities exhibit highest price sensitivity; semiconductor foundries demonstrate least.
Supply Chain Analysis
Specialized process engineers and chemical operations talent cluster in Germany's Rhine-Ruhr corridor and South Korea's Ulsan-Busan industrial zone, anchoring high-purity production capabilities. Manufacturing concentrates in China, Germany, and the United States. Anthracene feedstock, hydrogen gas, and palladium catalysts constitute critical inputs. Single-source vulnerability persists where Shandong and Jiangsu provinces host over half of global capacity. Distribution runs through stainless-steel tanker fleets and dedicated terminal infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EPA Clean Water Act enforcement in the United States creates premium pricing for advanced oxidation chemicals against margin-compressed industrial-grade supply in China's Shandong province.
For Market Incumbents: Lock in long-term municipal water treatment contracts before Jal Jeevan Mission procurement accelerates in India. Deepen backward integration into peracetic acid derivatives to defend against substitution threats in food packaging sterilization. Anchor electronics-grade supply through SEMI-standard certification investments that extend 18-24 month qualification timelines. For New Entrants and Emerging Players: The premium-to-economy price-point gap in electronics-grade versus industrial-grade supply creates entry opportunity. Target India's tier-2 municipal water infrastructure where advanced oxidation process adoption lags Jal Jeevan Mission targets. Pursue modular on-site generation deployments for remote mining and pulp operations to bypass concentrated production hub economics. For Investors and Strategic Acquirers: Asymmetric upside sits with regional specialists possessing GMP-certified pharmaceutical-grade capacity and established healthcare sterilization relationships. Five-to-ten year viability favors producers with dual electronics-grade and water treatment qualification capabilities. Watch for EPA enforcement acceleration in the United States as inflection signal for industrial-grade demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive anthracene supply insulates Solvay and Nouryon from feedstock volatility. |
| Electronics-Grade Certification | SEMI-standard qualification locks in TSMC and Samsung Foundry procurement relationships. |
| Modular On-Site Generation | Remote Australian mining and Scandinavian pulp deployments eliminate transportation cost burdens. |
| Green Hydrogen Integration | Electrolytic production routes align with EU Green Deal emissions benchmarks for carbon-conscious buyers. |
| Long-term Municipal Contracting | Kemira Oyj's Nordic water treatment positions capture EPA-driven advanced oxidation process adoption. |
Methodological Framework
Direct dialogue with plant managers at anthraquinone oxidation facilities, procurement leads at pulp and semiconductor foundries, distribution channel partners operating stainless-steel tanker fleets, and technical R&D directors stabilizing high-purity grades grounded qualitative findings. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K chemical segment disclosures, and EPA enforcement action databases. Bottom-up capacity modeling and top-down demand aggregation triangulated volume estimates.
Bottom-up segment modeling across grade tier, end-use industry, packaging format, and regional production hub dimensions generated volume and value outputs across the projection horizon. CAGRs derived from regression analysis against industrial production indices, semiconductor wafer start forecasts, and municipal capital expenditure trajectories. Forecast inputs incorporated anthraquinone process energy intensity improvements and REACH amendment compliance cost pass-through assumptions.
Caveats apply where anthracene feedstock price spikes, Chinese environmental shutdowns, or SEMI-standard protocol revisions could materially shift the outlook. Forecasts embed assumptions regarding EPA enforcement continuity and dual carbon target implementation pace in China. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disinfectants and Preservatives
Disinfectant Fogging and Misting Chemicals for Large Facilities Market
Disinfectants and Preservatives
India Hydrogen Peroxide Market
Disinfectants and Preservatives
Brazil High-Level Disinfectants and Terminal Sterilization Services Market
Disinfectants and Preservatives
Europe Disinfectant Wipes Market
Disinfectants and Preservatives
Hospital Surgical Disinfectant Market
Disinfectants and Preservatives
Chlorine Disinfectant Market
Disinfectants and Preservatives
Global Potassium Sorbate Market
Disinfectants and Preservatives
Chlorinators Market
Disinfectants and Preservatives
Europe Agricultural Disinfectants Market
Disinfectants and Preservatives
Halogen Biocides Market
Disinfectants and Preservatives
Chlorine Dioxide Market
Disinfectants and Preservatives
Deltamethrin Market
Disinfectants and Preservatives
Disinfection Cap Market
Disinfectants and Preservatives
Disinfectant and Cleaning Agents Market
Disinfectants and Preservatives
Electrostatic Disinfectant Sprayers Market
Disinfectants and Preservatives
Calcium Peroxide Market