
 Middle East Industrial Gas Market | 2026-2036
Middle East Industrial Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Industrial Gas Market Analysis
Petrochemical expansion is repositioning demand across the Middle East industrial gas value chain. Gulf Cryo leverages its regional pipeline network to anchor supply security for large-format users along the Arabian Gulf coast. Linde PLC sustains technology leadership through proprietary hydrogen liquefaction and carbon capture integration. Air Liquide competes by extending on-site generation footprints at refinery and chemical complex gates.
Middle East industrial gases encompass atmospheric gases and process gases supplied in compressed, liquid, or gaseous form, typically exceeding purity thresholds of 99.5% for nitrogen and oxygen used in oxidation, inerting, and chemical synthesis. These gases serve as feedstock and process enablers across petroleum refining, metal fabrication, and pharmaceutical manufacturing. Oxygen dominates volume flows into steel and petrochemical operations, while hydrogen captures expanding margin pools tied to ammonia and clean fuel projects. Electronics-grade nitrogen and argon represent the fastest-growing product tier, driven by semiconductor fabrication investments in the UAE and Saudi Arabia. Bulk and pipeline delivery modes command structural preference where large consumers cluster near industrial cities.
Saudi Arabia's SFDA and the UAE's MOHAP enforce pharmaceutical-grade gas certification standards that constrain import pathways and elevate local production requirements. The EU Green Deal's extraterritorial reach through supply chain disclosure rules under CSRD affects export-oriented Middle East chemical producers reliant on European offtake. Stakeholders must monitor how carbon border adjustment mechanisms and domestic hydrogen strategy implementation reshape capital allocation between captive on-site plants and merchant supply models.
Market Dynamics
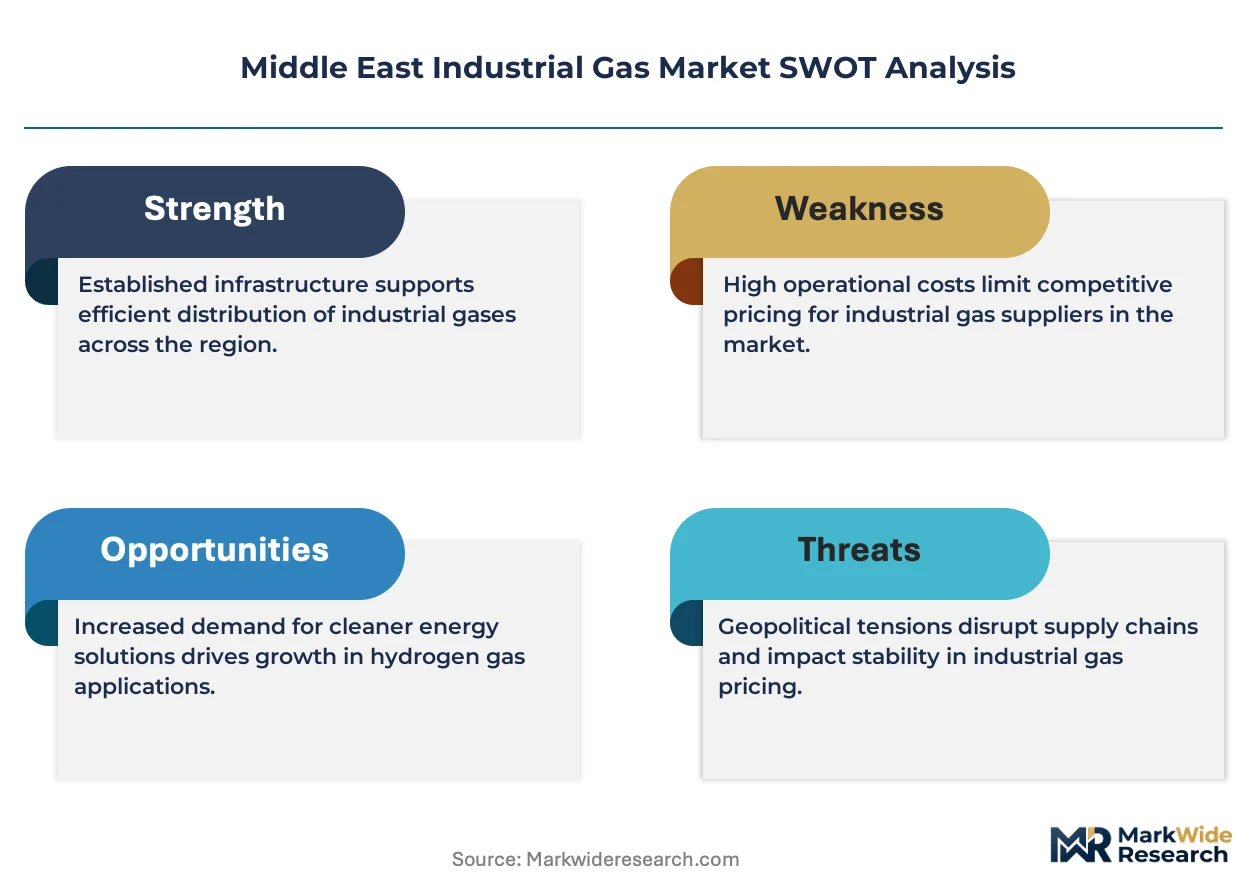
Petrochemical operators across the Arabian Gulf are restructuring supply relationships around hydrogen and nitrogen molecules for ammonia synthesis, forcing merchant gas suppliers to reposition from bulk delivery toward integrated on-site generation partnerships.
Growth Catalysts
- Ammonia synthesis feedstock demand:Petrochemical complexes in Saudi Arabia and the UAE are scaling hydrogen consumption for blue ammonia export projects, pulling nitrogen volumes through dedicated pipeline networks.
- SFDA pharmaceutical-grade certification:Saudi Arabia's tightening purity standards for medical and specialty gases are mandating local production investments that displace import-dependent supply models.
- Net-zero industrial mandates:The UAE's decarbonization pathway and Saudi Vision 2030 diversification targets are embedding carbon capture into hydrogen production, expanding gas treatment infrastructure requirements.
Market Restraints
- Pipeline infrastructure concentration:Bulk delivery economics depend on coastal industrial city clusters, leaving interior demand nodes dependent on higher-cost liquid transport modes.
- Natural gas feedstock price volatility:Steam methane reforming costs for hydrogen production track regional gas benchmark fluctuations, compressing margin visibility for long-term supply contracts.
- Electronics-grade purity thresholds:Semiconductor fabrication nitrogen specifications at 99.9999% purity require cryogenic distillation investments that exceed merchant supply capabilities outside Jebel Ali and Jubail Industrial City.
Strategic Opportunities
- Kuwait on-site generation expansion:Al-Zour refinery and petrochemical complex developments are creating anchor demand for hydrogen and syngas supply partnerships without established pipeline infrastructure.
- Carbon capture integration:Blue hydrogen production mandates under Saudi Vision 2030 are opening engineering contracts for CO2 separation and sequestration bundled with gas supply agreements.
- Qatar pipeline network extension:Ras Laffan Industrial City's concentrated LNG and petrochemical base offers density for nitrogen and hydrogen pipeline investments currently served by liquid bulk.
Industry Challenges
- Cryogenic equipment technician scarcity:Air separation unit maintenance and cold box repair expertise concentrates with original equipment manufacturers, constraining operational uptime for independent operators.
- Pharmaceutical-grade certification timelines:SFDA and MOHAP validation protocols for medical oxygen and nitrous oxide require 18-24 month approval cycles that delay market entry for new production assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Industrial Gas Market |
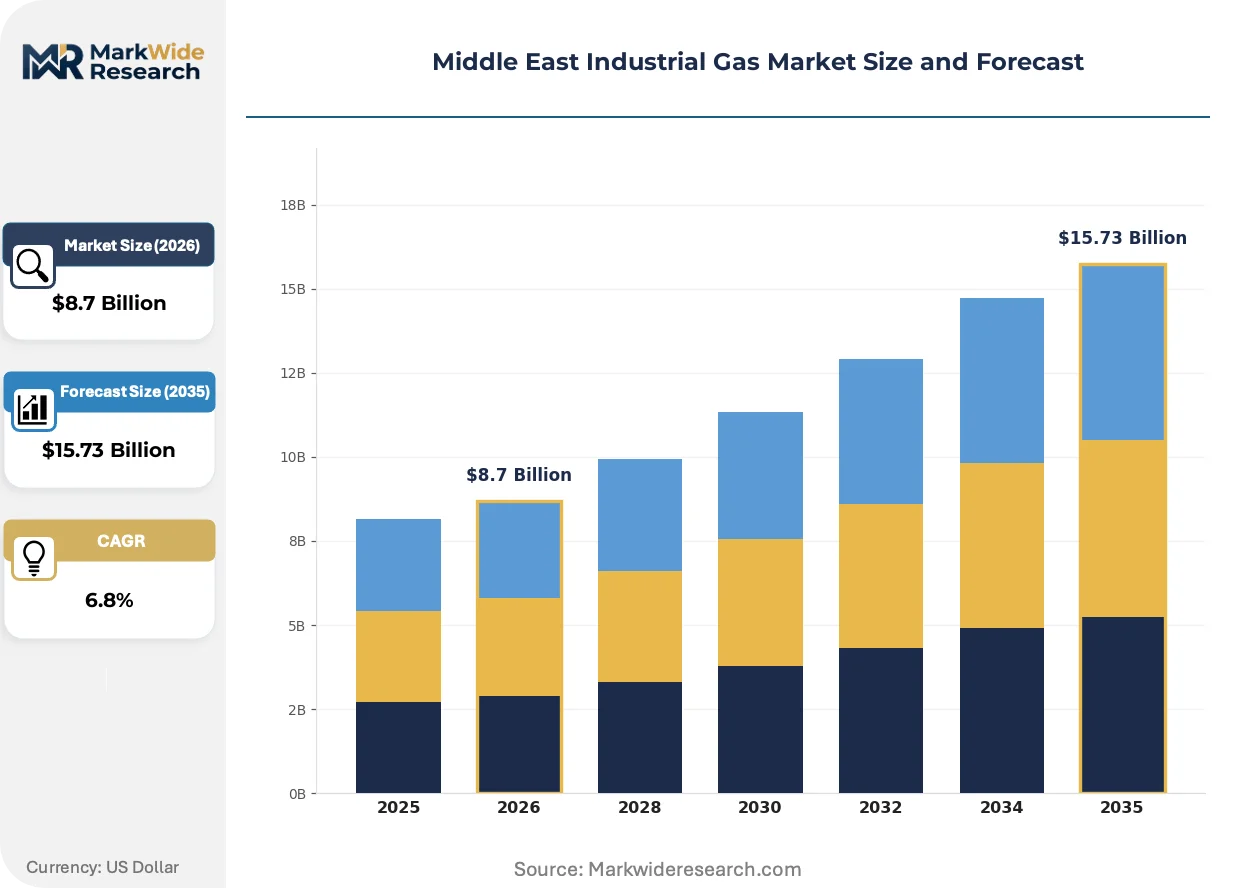
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogen, Oxygen, Argon, Hydrogen Application: Manufacturing, Chemical Processing, Food & Beverage, Electronics End User: Petroleum, Metal Fabrication, Pharmaceuticals, Aerospace Delivery Mode: Cylinders, Bulk, Pipeline, On-site Generation |
| Companies Covered | Gulf Cryo, Abdullah Hashim Industrial Gases, Linde PLC, Messer Group GmbH, Buzwair Industrial Gases Factory, Air Liquide, ADNOC Industrial Gas, Taiyo Nippon Sanso Corporation, Air Products and Chemicals Inc., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Industrial Gas Market Emerging Trajectories
Electrolysis-based hydrogen production and carbon capture retrofits are restructuring investment priorities across Gulf industrial gas supply chains, compressing the viability window for conventional steam methane reforming without abatement.
Modular electrolyzer systems are integrating renewable power directly into hydrogen supply architectures at refinery and ammonia complex gates. Saudi Aramco and ADNOC downstream operations are piloting 20-100 MW units for merchant hydrogen blending. This distributed production model is integrating intermittent renewable offtake with industrial baseload demand, displacing centralized reforming economics for mid-scale consumers.
The EU Green Deal's carbon border adjustment mechanism is reshaping export-oriented chemical producer requirements across the GCC. CSRD supply chain disclosure rules now extend to hydrogen and ammonia offtake contracts with European buyers. Saudi and UAE petrochemical exporters are responding by certifying product carbon intensity through third-party verification to preserve market access.
Long-term take-or-pay contracts are compressing in duration as buyers seek flexibility amid feedstock cost volatility. Five-year agreements are displacing traditional fifteen-year structures at Jubail and Yanbu industrial complexes. This contract fragmentation is most visible in merchant oxygen and nitrogen supply to steel mini-mills across the UAE's northern emirates.
Middle East Industrial Gas Market Segmentation
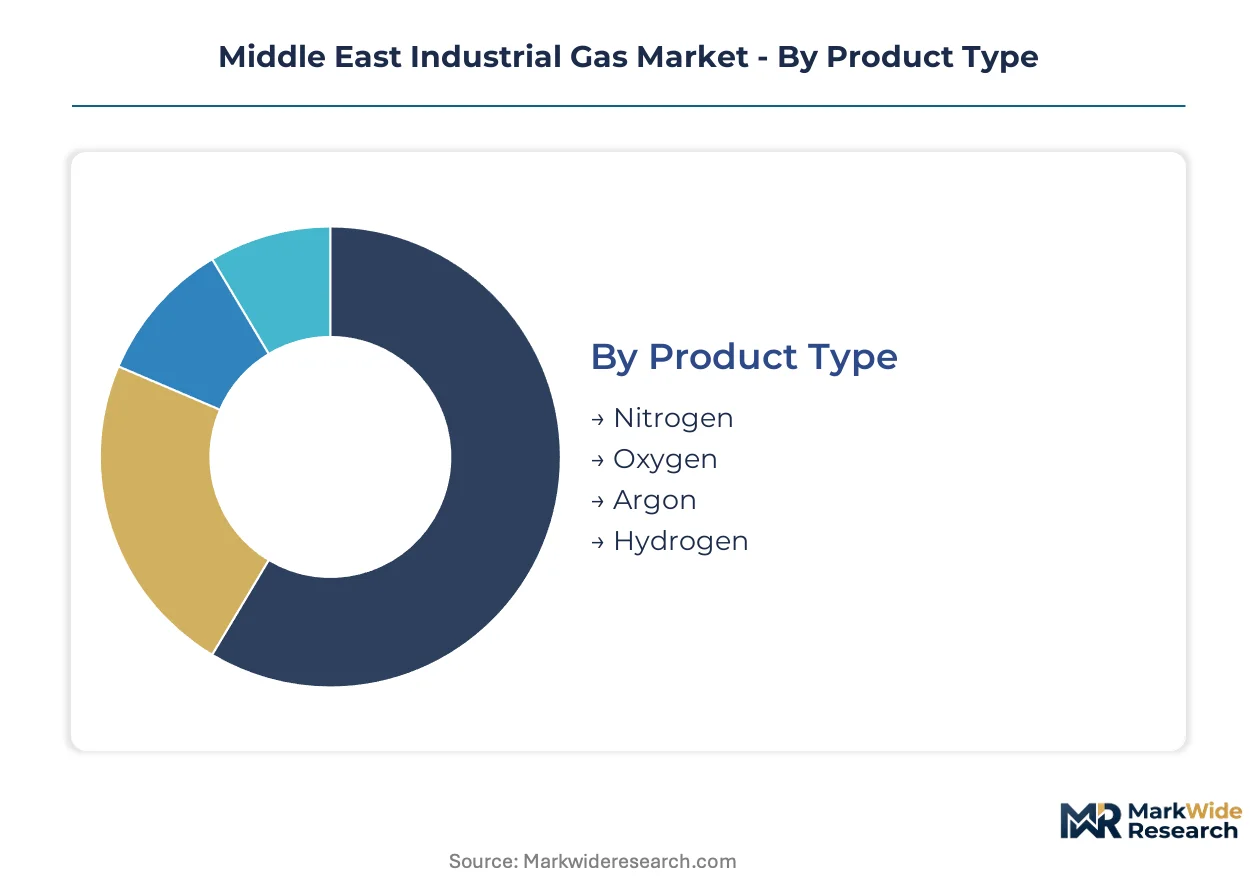
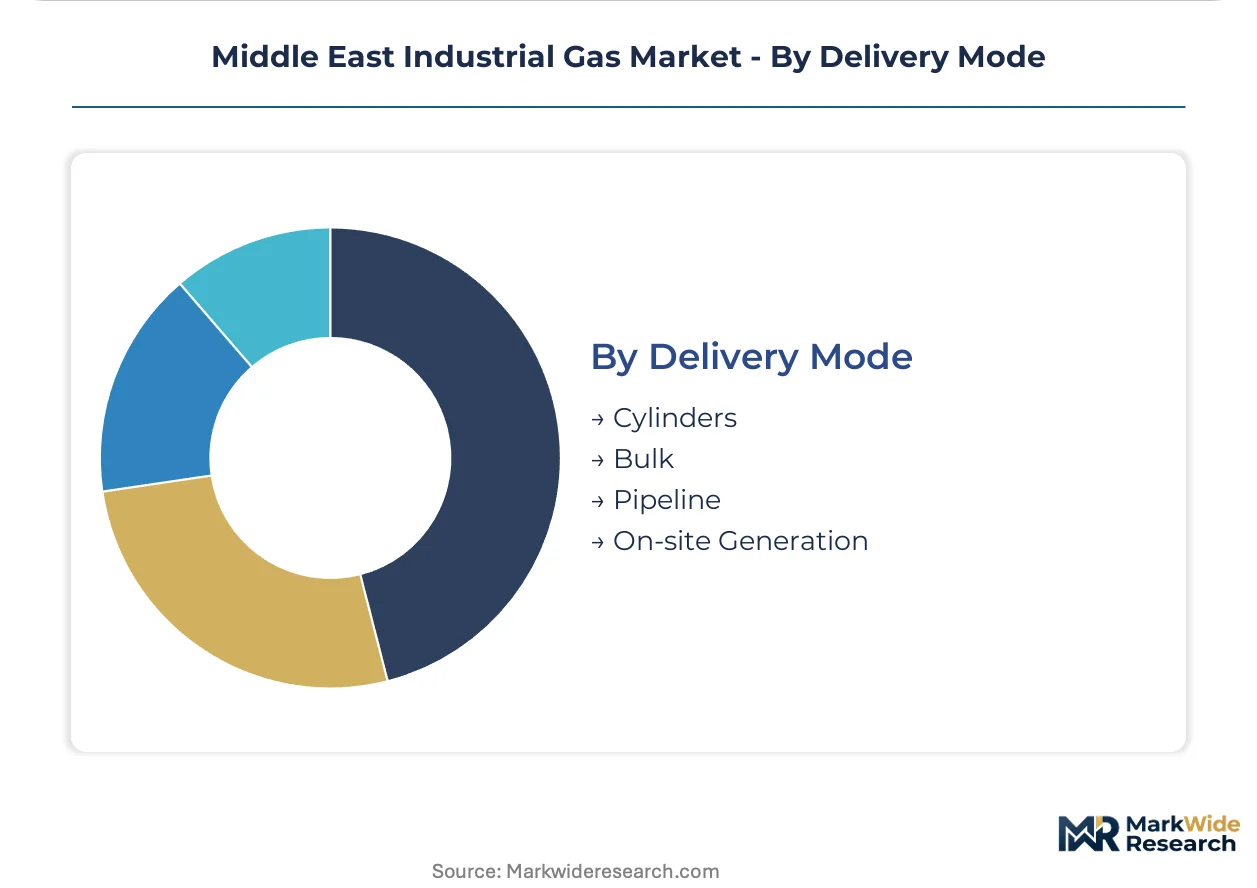
Industrial gas segmentation in the Middle East maps directly to capital deployment patterns and infrastructure lock-in. Product purity thresholds and delivery mode economics determine where producers can extract sustainable margins across the Gulf Cooperation Council corridor.
Product Type:
Capital intensity varies sharply across molecular categories, with cryogenic air separation units demanding the heaviest upfront investment while hydrogen reforming plants carry the longest payback horizons tied to natural gas feedstock contracts.
- Oxygen:Separated through cryogenic distillation of ambient air to achieve 99.5% purity for steel oxidation and petrochemical processes. Saudi Arabia's Jubail Industrial City and the UAE's Jebel Ali cluster anchor regional demand through integrated steel and refining complexes requiring thousand-ton-per-day supply scales.
- Hydrogen:Produced via steam methane reforming or emerging electrolysis pathways, with blue hydrogen variants incorporating carbon capture for ammonia synthesis export projects. ADNOC and Saudi Aramco downstream operations are contracting dedicated hydrogen supply for merchant and captive consumption at Ras Laffan and Yanbu.
- Nitrogen:Inerting and blanketing applications across chemical processing and electronics fabrication.
- Argon:Welding shield gas and semiconductor crystal growth requiring high-purity recovery from air separation tail streams.
Oxygen absorbs the bulk of installed capacity; hydrogen is expanding most quickly.
Application:
Application segmentation tracks customer sophistication tiers, with electronics-grade specifications commanding premium pricing multiples over industrial baseline products.
- Chemical Processing:Hydrogen and nitrogen feedstock for ammonia, methanol, and syngas synthesis at integrated petrochemical hubs. Saudi Arabia's SABIC and UAE's Borouge operations contract pipeline-delivered molecules under long-term take-or-pay structures.
- Electronics:Ultra-high-purity nitrogen at 99.9999% for semiconductor wafer fabrication cleanroom inerting. Dubai Silicon Oasis and King Abdullah Economic City are attracting fabrication investments that outstrip regional merchant supply capabilities.
- Manufacturing:Cutting, welding, and heat treatment operations across metal fabrication and automotive component production.
- Food & Beverage:Modified atmosphere packaging and cryogenic freezing applications with lower purity tolerances.
Chemical processing commands the dominant revenue share; electronics is climbing the fastest as fabrication investments accelerate.
End User:
End user segmentation reveals divergent procurement power, with petroleum sector buyers consolidating supply relationships around integrated on-site generation partnerships.
- Petroleum:Refinery hydrogen demand for hydrocracking and desulfurization, plus nitrogen for tank blanketing and pipeline purging. Saudi Aramco and ADNOC operate the region's largest captive and merchant offtake volumes.
- Pharmaceuticals:Medical oxygen and nitrous oxide subject to SFDA and MOHAP certification requirements that constrain import pathways and mandate local production investments.
- Metal Fabrication:Oxygen-fuel cutting and argon-shielded welding across steel construction and shipbuilding yards concentrated in the UAE and Bahrain.
- Aerospace:Nitrogen for fuel tank inerting and oxygen for aviator breathing systems with stringent traceability requirements.
Petroleum end users absorb the dominant contract volume; pharmaceuticals is gaining share fastest through regulatory localization mandates.
Delivery Mode:
Delivery mode selection locks in cost structures for decades, with pipeline networks creating geographic monopolies and on-site generation transferring operational risk to suppliers.
- Pipeline:Dedicated high-pressure distribution networks serving concentrated industrial city demand at Jubail, Yanbu, and Ras Laffan. Gulf Cryo and Linde PLC anchor regional pipeline infrastructure with multi-decade supply concessions.
- On-site Generation:Air separation units or hydrogen reformers built at customer fence lines under long-term service contracts. Kuwait's Al-Zour refinery development is attracting on-site investment without established pipeline alternatives.
- Bulk:Cryogenic liquid delivery by tanker truck to customers lacking pipeline access or scale for dedicated plants.
- Cylinders:Compressed gas distribution for small-volume users across maintenance, laboratory, and specialty applications.
Pipeline delivery holds the majority of contracted volume; on-site generation is expanding most quickly as new industrial complexes seek supply security.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jubail Industrial City and Ras Laffan anchor hydrogen and nitrogen demand through integrated petrochemical corridors, concentrating pipeline infrastructure investment along the Arabian Gulf coast.
Saudi Arabia
Jubail and Yanbu industrial cities consume thousand-ton-per-day oxygen volumes for steel oxidation and refining operations. SFDA pharmaceutical-grade certification mandates are displacing import-dependent medical gas supply models with localized production requirements. SABIC operations at Jubail are contracting dedicated hydrogen pipeline networks for ammonia synthesis feedstock.
United Arab Emirates
Jebel Ali's refining cluster and Dubai Silicon Oasis semiconductor investments are pulling ultra-high-purity nitrogen demand beyond merchant supply capabilities. MOHAP tightening purity standards for medical oxygen are constraining import pathways and elevating local certification timelines. Borouge operations at Ruwais are anchoring long-term hydrogen offtake contracts with carbon capture integration requirements.
Qatar
Ras Laffan Industrial City's LNG and petrochemical base offers density for nitrogen pipeline investments currently served by liquid bulk delivery. The country's national hydrocarbon regulator enforces process safety standards that shape gas treatment infrastructure specifications. Ras Laffan is attracting merchant hydrogen supply partnerships for ammonia export project feedstock security.
Kuwait
Al-Zour refinery and petrochemical complex developments are creating anchor demand without established pipeline infrastructure, forcing on-site generation investment. The country's environmental protection authority is embedding emissions disclosure requirements into industrial licensing frameworks. Al-Zour is becoming a test case for integrated hydrogen and syngas supply partnerships outside traditional pipeline corridors.
Bahrain
Alba aluminum smelter operations and shipbuilding yards concentrate oxygen and argon demand across metal fabrication applications. The country's central industrial regulator mandates traceability standards for specialty gas procurement in aerospace applications. Sitra and Askar industrial areas are seeing cylinder distribution consolidation as smaller fabricators merge procurement volumes.
Middle East Industrial Gas Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with pipeline infrastructure owners commanding geographic monopolies at industrial city clusters while on-site generation specialists capture new complex developments. The market structure concentrates around three archetypes: integrated global suppliers with proprietary liquefaction technology, regional pipeline network operators with multi-decade concessions, and national oil company affiliates leveraging captive feedstock access. Capacity expansion through air separation unit deployment and carbon capture bundling represent the dominant competitive vectors reshaping contract structures.
Within the integrated global supplier tier, Linde PLC and Air Liquide exemplify technology-led positioning through hydrogen liquefaction and on-site generation footprints at refinery gates. Gulf Cryo anchors regional pipeline infrastructure with coastal concession networks spanning Jubail and Ras Laffan. Abdullah Hashim Industrial Gases occupies a position bridging merchant bulk delivery and pharmaceutical-grade local production certification.
| Leading Market Players |
|---|
| Gulf Cryo |
| Abdullah Hashim Industrial Gases |
| Linde PLC |
| Messer Group GmbH |
| Buzwair Industrial Gases Factory |
| Air Liquide |
| ADNOC Industrial Gas |
| Taiyo Nippon Sanso Corporation |
| Air Products and Chemicals Inc. |
| Others |
Supply Flow & Price Mechanics
The UAE's net-zero pathway and Saudi Vision 2030 industrial diversification mandates gate qualified supply access and premium-tier pricing for carbon-captured hydrogen and pharmaceutical-grade gases. Buyers without verified low-carbon intensity certification face exclusion from European offtake contracts, compressing merchant margins for conventional steam methane reforming.
Pricing Analysis
Short lead-time premiums dominate contract structures, with spot nitrogen and oxygen deliveries commanding substantial markups over scheduled pipeline volumes. Three-tier pricing structure across premium, standard, and economy levels separates electronics-grade nitrogen from industrial baseline and cylinder-packaged alternatives. Pricing pressure stems from natural gas feedstock volatility feeding into hydrogen production costs. Steel mini-mills across the UAE's northern emirates exhibit highest price sensitivity, while semiconductor fabricators absorb premiums for purity-assured supply.
Supply Chain Analysis
Regional distribution centers at Jebel Ali, Jubail, and Ras Laffan anchor hub-and-spoke liquid bulk delivery to interior demand nodes lacking pipeline access. Saudi Arabia, the UAE, and Qatar concentrate atmospheric gas production through coastal air separation units. Cryogenic equipment and specialized cold box components draw from German, Japanese, and US original equipment manufacturers. Single-source vulnerability concentrates with Linde PLC and Air Liquide for hydrogen liquefaction technology. Distribution runs through tanker truck fleets for bulk liquid, with pipeline networks serving anchored industrial city clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated on-site generation partnerships, with carbon capture integration mandates forcing merchant suppliers without pipeline concessions toward acquisition or exit.
For Market Incumbents: Cement pipeline network dominance through carbon capture bundling at Yanbu and Ras Laffan, locking in fifteen-year take-or-pay structures before contract durations compress further. Defend against electrolysis-based entrants by anchoring blue hydrogen supply with verified carbon intensity certification for European ammonia offtake. For New Entrants and Emerging Players: Capture Kuwait's Al-Zour refinery complex developments through modular on-site generation partnerships where pipeline infrastructure remains absent. Target pharmaceutical-grade medical oxygen production under SFDA certification timelines that deter import-dependent competitors, leveraging eighteen-month approval cycles as competitive moats. For Investors and Strategic Acquirers: ADNOC and Saudi Aramco downstream hydrogen offtake announcements are the leading indicator that merchant supply partnerships are restructuring toward integrated service contracts. Position for five-to-ten year viability in regional pipeline operators with coastal concession networks and carbon capture engineering capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Blue hydrogen certification under Saudi Vision 2030 preserves European market access for ammonia exporters. |
| On-Site Generation Partnership | Kuwait's Al-Zour refinery creates anchor demand without established pipeline delivery infrastructure. |
| Pharmaceutical-Grade Certification | SFDA validation protocols displace import-dependent supply models with localized production requirements. |
| Pipeline Network Extension | Ras Laffan Industrial City density supports nitrogen and hydrogen pipeline investments displacing liquid bulk. |
| Electronics-Grade Purity Investment | Dubai Silicon Oasis semiconductor fabrication outstrips regional merchant supply capabilities for ultra-high-purity nitrogen. |
Methodological Framework
Trade flow databases, industrial licensing registries, and petrochemical project announcements formed the secondary backbone, cross-referenced with primary interviews involving air separation unit operators, refinery procurement leads, and carbon capture engineering contractors. Bottom-up and top-down triangulation validated volume estimates across pipeline delivery modes and on-site generation footprints.
Bottom-up modeling built product-specific demand from individual industrial complex offtake, while top-down constraints checked against national hydrogen strategy targets and petrochemical capacity expansion timelines. Segmentation dimensions spanned product purity grade, delivery mode infrastructure, end-use application, and regional regulatory cluster. CAGRs derived from weighted capacity expansion schedules and contract duration trends across the projection horizon. Forecast inputs incorporated natural gas benchmark volatility and electrolyzer deployment pipelines at refinery gates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon border adjustment mechanism implementation and blue hydrogen certification standardization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market
Industrial Gases
Krypton-85 Market
Industrial Gases
Industrial Hydrogen Peroxide Market
Industrial Gases
US and Canada Helium Gas Market
Industrial Gases
Global Laboratory Gas Generators Market
Industrial Gases
North America Syngas Market
Industrial Gases
Global Argon Market
Industrial Gases
Pressure Swing Adsorption Nitrogen Generator Market
Industrial Gases
Europe Industrial Gases Market
Industrial Gases
United States Industrial Gases Market
Industrial Gases
US Industrial Gas Regulator Market
Industrial Gases
Carbon Monoxide Market
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
Middle-East and Africa Syngas Market
Industrial Gases
High Purity Argon Market
Industrial Gases
Europe Syngas Market