
 Global Food-Grade Industrial Gases Market | 2026-2036
Global Food-Grade Industrial Gases Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food-Grade Industrial Gases Market Analysis
ISO 22000 certification is rotating as the decisive qualification filter for food-grade gas suppliers seeking entry into multinational food processor supply chains. Linde plc leverages captive carbon dioxide capture from ammonia plants to secure feedstock cost advantages across European dairy corridors. Air Liquide anchors its position through on-site nitrogen generation contracts with large-scale bakery sector clients. Messer Group differentiates via regional density in Central European meat processing clusters where direct supply pipelines lock in volume.
Food-grade industrial gases are purified atmospheric or process-derived gases meeting food safety purity standards, typically exceeding 99.9% concentration with controlled limits on moisture, hydrocarbons, and particulate contaminants, deployed to displace oxygen, regulate temperature, or modify atmospheric composition during food handling. Carbon dioxide dominates value contribution in beverage industry carbonation and slaughterhouse stunning applications where high-pressure liquid delivery systems create captive infrastructure dependencies. Nitrogen leads growth velocity in modified atmosphere packaging for snack foods and prepared meals, driven by extended shelf-life requirements from retail distribution centers.
FDA food contact substance notifications, EU Regulation 231/2012 on food additives, and ISO 8573-1 compressed air purity classes collectively define the analytical and documentation burden for market participation. EFSA's evolving guidance on recycled carbon dioxide in food applications is reshaping qualification protocols for circular feedstock claims. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's methane reduction targets redirect carbon dioxide sourcing from fermentation versus fossil origins.
Market Dynamics
Modified atmosphere packaging is compressing oxygen displacement cycles across frozen ready meal supply chains, forcing gas suppliers to co-locate production with meat processing clusters in Germany and the Netherlands.
Growth Catalysts
- EU Regulation 231/2012 on food additives:Tightened purity thresholds for carbon dioxide used in beverage carbonation are accelerating certification investments by industrial gas distributors serving European dairy corridors.
- Slaughterhouse stunning applications:High-pressure liquid carbon dioxide delivery systems in German meat processing clusters create captive infrastructure dependencies that lock in long-term supply contracts.
- ISO 22000 certification mandates:Multinational food processors now require supplier qualification filters that exclude uncertified gas providers from tender processes.
Market Restraints
- Ammonia plant feedstock concentration:Carbon dioxide sourcing from ammonia production concentrates in coastal industrial zones, exposing buyers to single-point supply vulnerabilities during plant maintenance cycles.
- FDA Good Manufacturing Practice documentation burden:Updated guidelines for food contact substances impose analytical testing costs that disproportionately burden smaller regional gas distributors.
- Liquid nitrogen transport economics:Cryogenic tanker fleet requirements create capital barriers for entrants seeking to serve dispersed bakery sector clients outside major metropolitan corridors.
Strategic Opportunities
- On-site nitrogen generation:Membrane and pressure swing adsorption technologies enable bakery sector clients in France and Italy to bypass liquid delivery dependencies entirely.
- Recycled carbon dioxide qualification:EFSA's evolving guidance on circular feedstock claims creates first-mover advantages for suppliers with fermentation-derived carbon dioxide capture capabilities.
- Centralized meat processing corridor density:Direct pipeline supply contracts in Poland and Czech Republic offer volume lock-in opportunities unavailable in fragmented retail gas cylinder markets.
Industry Challenges
- ISO 8573-1 compressed air purity compliance:Food-grade gas suppliers must maintain dual certification streams for both gas purity and compressed air systems, extending qualification timelines for new production facilities.
- Cryogenic equipment technician scarcity:Specialized maintenance capabilities for liquid nitrogen storage and vaporization systems concentrate with legacy industrial gas incumbents, constraining operational expansion for mid-tier competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food-Grade Industrial Gases Market |
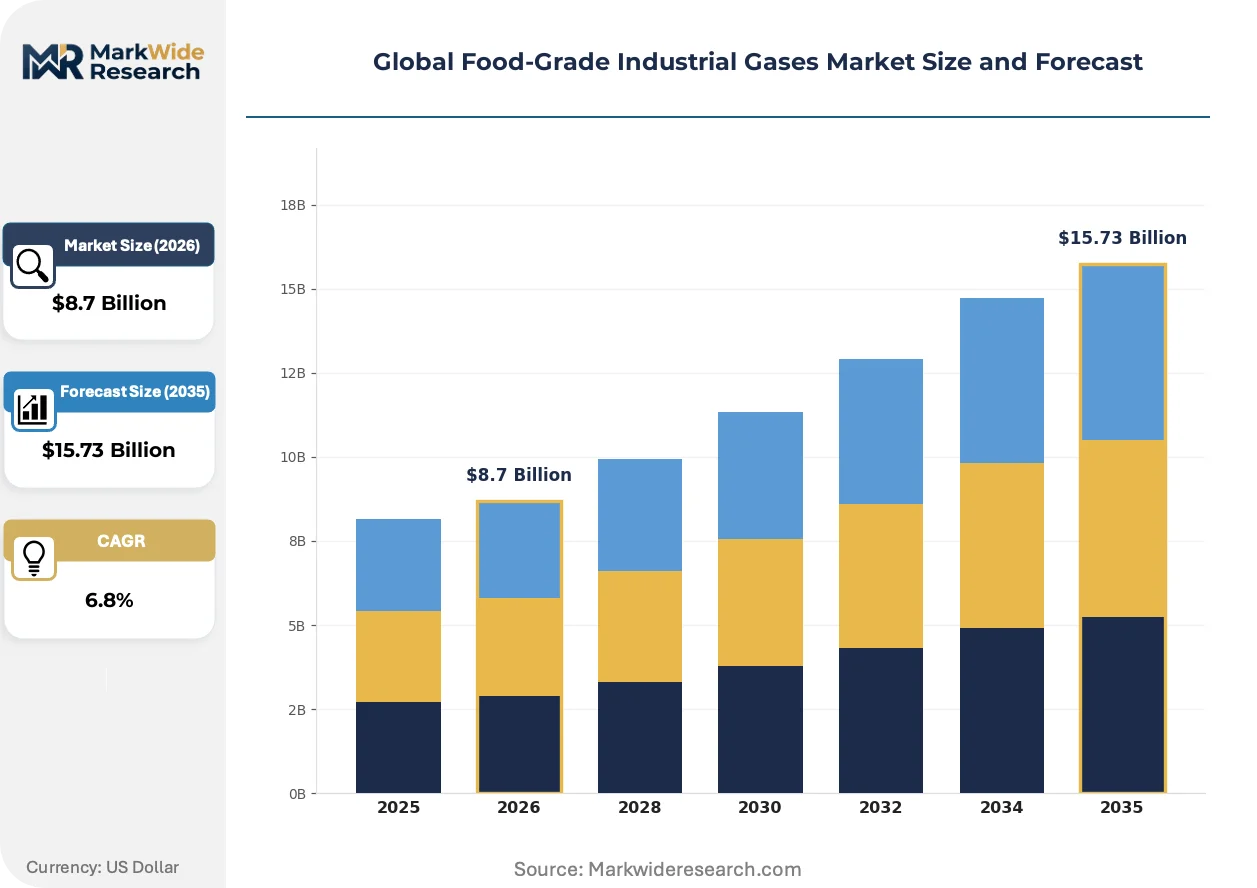
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Gas Type: Carbon Dioxide, Nitrogen, Oxygen, Argon Application: Packaging, Freezing, Modified Atmosphere, Preservation End User: Food Processing, Beverage Industry, Dairy Production, Bakery Sector Distribution Channel: Direct Supply, Distribution Centers, Online Sales, Retail Outlets |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Inc., Messer Group, Taiyo Nippon Sanso Corporation, Wesfarmers Limited, SOL Group, Gulf Cryo, Gruppo SIAD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food-Grade Industrial Gases Market Emerging Trajectories
On-site gas generation technologies are fragmenting traditional liquid delivery models, while regulatory pressure on carbon feedstock origins is bifurcating supplier qualification pathways between fossil-derived and fermentation-based sources.
Membrane nitrogen generation is bifurcating the bakery sector supply base. Large-scale bread and pastry manufacturers in France now deploy skid-mounted systems that eliminate bulk liquid deliveries entirely. This technology compresses operating margins for regional gas distributors who previously captured recurring transport revenue from mid-sized baking facilities.
EFSA's draft guidance on recycled carbon dioxide is tightening documentation requirements for circular feedstock claims. Suppliers must now trace carbon dioxide from fermentation source through purification to final food contact, creating compliance friction for ammonia-plant-dependent producers. German dairy processors are demanding segregated supply chains that exclude fossil-derived carbon dioxide entirely.
Retail distribution centers are consolidating modified atmosphere packaging specifications across frozen ready meal categories. Buyers in the Netherlands now mandate nitrogen-carbon dioxide mixtures with precise residual oxygen limits, compressing supplier flexibility and forcing gas blenders to maintain dedicated production lines for individual retail contracts. This specification tightening favors suppliers with direct pipeline access to meat processing clusters over cylinder-based competitors.
Global Food-Grade Industrial Gases Market Segmentation
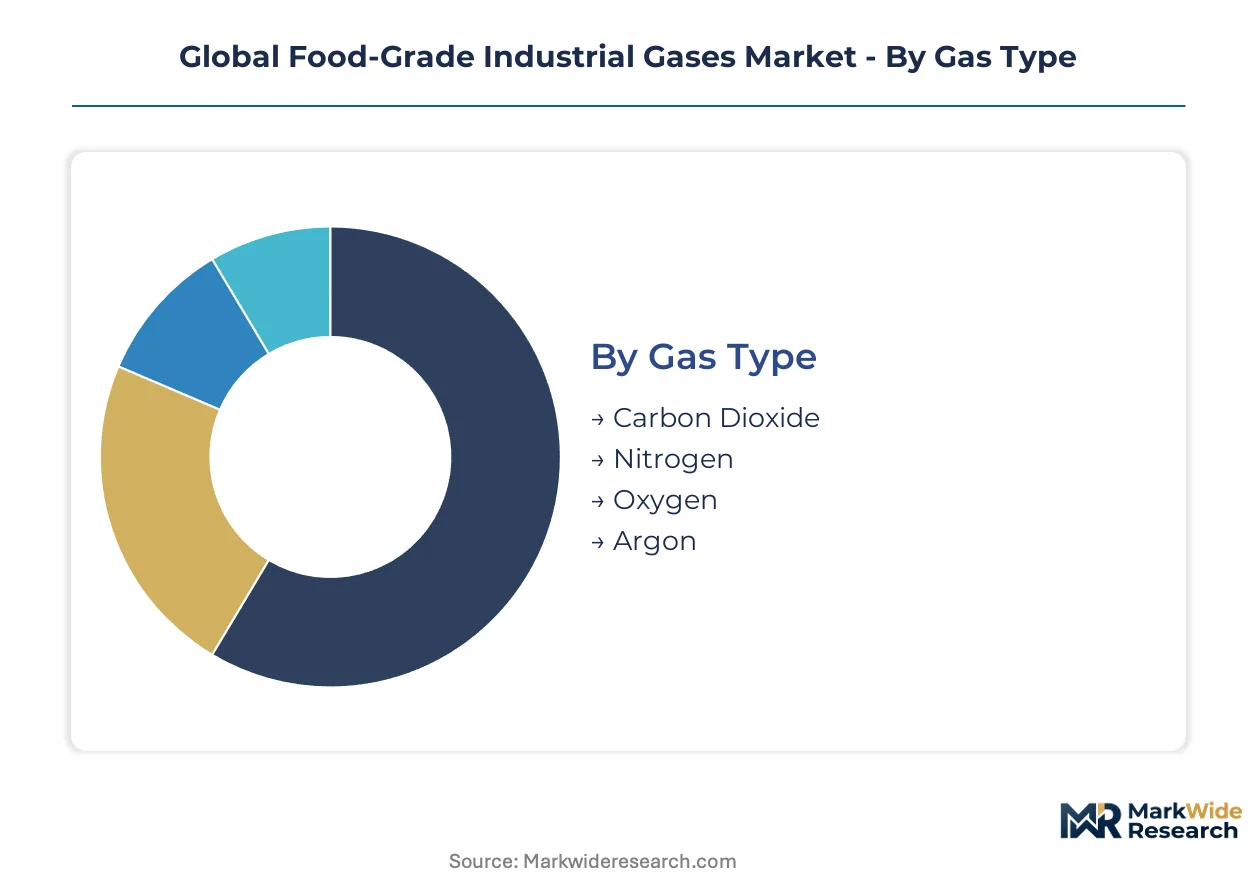
Food-grade industrial gases flow through distinct supply channels shaped by volume scale, purity requirements, and proximity to processing clusters. Segment boundaries determine whether suppliers compete on pipeline density, cryogenic logistics, or on-site generation technology.
Gas Type:
Bulk liquid delivery dominates high-volume carbon dioxide and nitrogen accounts, while cylinder and microbulk channels serve oxygen and argon requirements in smaller processing facilities.
- Carbon Dioxide:Purified to 99.9% with controlled moisture and hydrocarbon limits, this gas deploys primarily in high-pressure liquid delivery systems for beverage carbonation and slaughterhouse stunning. German meat processing corridors and European dairy bottling plants concentrate demand, with EFSA's evolving circular feedstock rules redirecting procurement toward fermentation-derived sources.
- Nitrogen:Inert atmosphere creation drives specification requirements for residual oxygen displacement in modified atmosphere packaging. Netherlands retail distribution centers and French bakery sector clients are compressing delivery cycles, forcing suppliers to co-locate production or deploy on-site membrane generation systems.
- Oxygen:Controlled atmosphere storage applications in fresh produce logistics require food-grade purity with strict particulate limits. Italian fruit export corridors and Spanish vegetable processing clusters maintain steady cylinder-based procurement.
- Argon:Inert shielding properties suit premium wine preservation and specialty packaging applications where oxygen exclusion must be absolute. Niche volume concentrates in French wine cooperatives and Italian prosecco production zones.
Carbon Dioxide dominates installed base. Nitrogen is where expansion concentrates.
Application:
Cost tier stratification separates capital-intensive freezing systems from specification-tight packaging contracts that demand dedicated production lines.
- Packaging:Nitrogen flushing and controlled atmosphere insertion extend shelf-life in snack foods and prepared meals. Netherlands retail chains now mandate residual oxygen thresholds below 1%, forcing gas blenders into contract-specific production commitments.
- Freezing:Cryogenic tunnel and spiral freezing systems deploy liquid nitrogen for rapid temperature reduction in seafood and poultry processing. Coastal processing zones in Norway and Denmark concentrate demand where ammonia-plant carbon dioxide feedstock availability shapes supply economics.
- Modified Atmosphere:Precision gas mixtures balance microbial inhibition with product texture retention in fresh meat and ready-to-eat categories. German centralized slaughterhouse clusters require direct pipeline supply to meet volume and specification consistency.
- Preservation:Controlled atmosphere storage extends post-harvest viability for apples, pears, and stone fruits. Italian Emilia-Romagna and Spanish Catalonia storage cooperatives sustain seasonal demand patterns.
Freezing commands highest capital commitment per installation. Modified Atmosphere is climbing the fastest.
End User:
Customer type determines contract structure, with multinational processors imposing ISO 22000 certification gates that exclude uncertified regional distributors.
- Food Processing:Meat, poultry, and seafood facilities consume bulk nitrogen and carbon dioxide through direct pipeline or microbulk delivery. Polish and Czech Republic processing corridors are consolidating toward single-source supply contracts with volume guarantees.
- Beverage Industry:Carbonation purity requirements under EU Regulation 231/2012 impose analytical documentation burdens that favor integrated suppliers with captive feedstock. European dairy corridors and soft drink bottling networks concentrate procurement scale.
- Dairy Production:Modified atmosphere packaging for cheese and extended shelf-life milk products drives nitrogen demand. French and Italian dairy cooperatives are evaluating on-site generation to reduce liquid delivery dependency.
- Bakery Sector:Inert atmosphere cooling and packaging preservation for bread and pastry products. French industrial bakeries have adopted membrane nitrogen generation at scale, eliminating bulk liquid procurement entirely.
Food Processing anchors volume concentration. Bakery Sector is gaining share fastest.
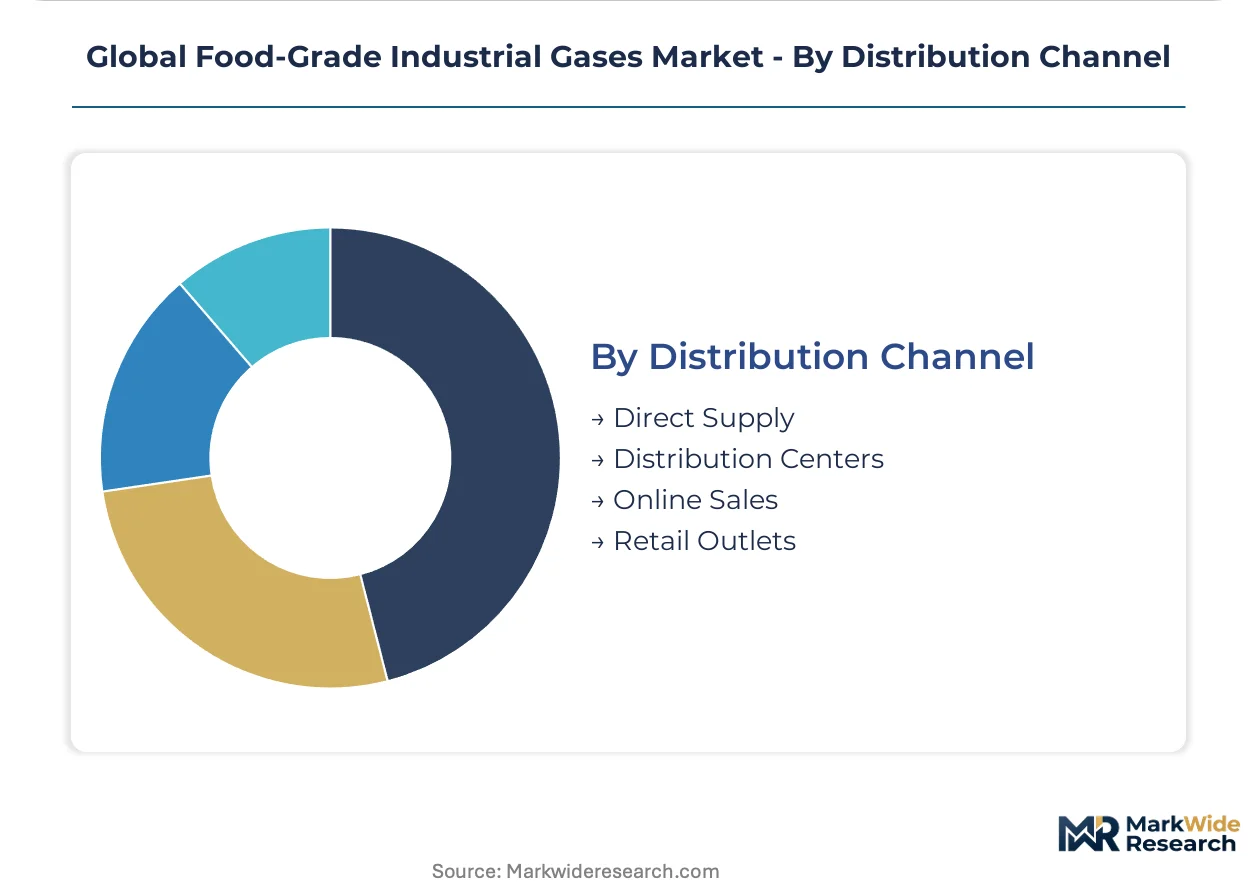
Distribution Channel:
Supply concentration in pipeline corridors versus dispersed cylinder markets creates divergent margin structures and competitive dynamics.
- Direct Supply:On-site production or dedicated pipeline delivery locks in long-term contracts with large-volume processors. German meat clusters and Netherlands retail distribution centers require this channel for specification consistency.
- Distribution Centers:Regional bulk storage and decanting operations serve mid-tier processors without pipeline access. Central European logistics hubs in Poland and Czech Republic concentrate third-party distributor presence.
- Online Sales:Cylinder and small bulk ordering platforms target artisanal producers and replacement gas procurement. Limited penetration outside metropolitan corridors with established industrial gas distributor networks.
- Retail Outlets:Welding supply and general industrial gas retailers serve occasional food-grade demand from small processors and restaurants. Purity documentation gaps restrict this channel for certified food contact applications.
Direct Supply dominates contracted volume. Distribution Centers is where mid-tier competition concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's EU Green Deal methane reduction targets are redirecting carbon dioxide sourcing toward fermentation-based feedstocks. FDA purity mandates in the United States and EFSA circular economy guidance in France are tightening qualification protocols across major supply corridors.
Germany
Centralized meat processing clusters in Lower Saxony and Bavaria drive concentrated nitrogen and carbon dioxide demand. The country's national environmental regulator enforces strict methane emission caps that favor fermentation-derived carbon dioxide capture. Direct pipeline supply contracts lock in volume with slaughterhouse facilities across the Ruhr industrial corridor.
United States
Beverage carbonation and cryogenic freezing anchor carbon dioxide and nitrogen consumption. FDA updated Good Manufacturing Practice guidelines impose analytical testing burdens that reshape distributor qualification. Gulf Coast ammonia plant corridors concentrate carbon dioxide feedstock supply, creating coastal dependency patterns.
France
Large-scale bakery sector adoption of on-site membrane nitrogen generation is eliminating bulk liquid delivery dependencies. EFSA draft guidance on recycled carbon dioxide tightens documentation for circular feedstock claims. French dairy cooperatives in Brittany and Normandy are demanding segregated supply chains excluding fossil-derived carbon dioxide.
Netherlands
Retail distribution centers mandate precise nitrogen-carbon dioxide mixture specifications for modified atmosphere packaging. The country's national food safety authority enforces residual oxygen thresholds below 1% in frozen ready meal categories. Rotterdam logistics hubs concentrate third-party gas distribution infrastructure serving Benelux processing networks.
China
Dual carbon goals redirect carbon dioxide sourcing priorities from fossil to fermentation origins. The Ministry of Ecology and Environment enforces emission intensity standards that reshape industrial gas feedstock economics. Yangtze River Delta food processing zones concentrate demand for high-purity nitrogen in modified atmosphere packaging applications.
Global Food-Grade Industrial Gases Market Vendor Landscape
Listed leaders compete with private specialists across feedstock access and pipeline density dimensions. The supplier base organizes around three archetypes: integrated chemical conglomerates with captive carbon dioxide sources, regional pipeline operators with meat cluster proximity, and technology licensors for on-site generation systems. Capacity expansion in Central European corridors and strategic partnerships for circular feedstock qualification represent dominant competitive moves.
Within the integrated chemical tier, Linde plc and Air Liquide exemplify scale-driven positioning through ammonia plant carbon dioxide capture and on-site nitrogen generation contracting. Messer Group occupies a specialist position anchored in Central European meat processing corridor density. These three entities collectively represent the competitive spectrum from global feedstock integration through regional pipeline lock-in.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Messer Group |
| Taiyo Nippon Sanso Corporation |
| Wesfarmers Limited |
| SOL Group |
| Gulf Cryo |
| Gruppo SIAD |
| Others |
Supply Flow & Price Mechanics
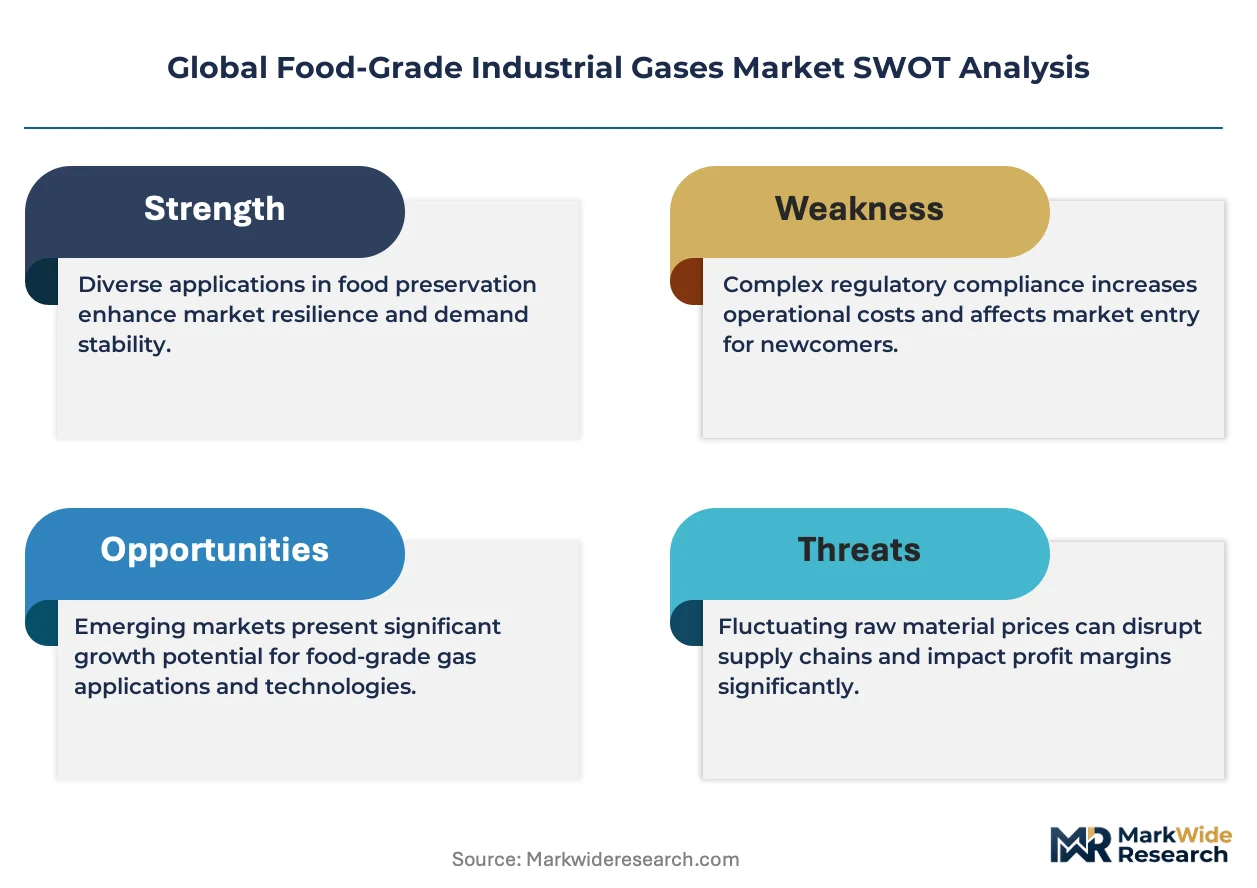
Captive carbon dioxide feedstock from ammonia plants anchors cost structures for integrated suppliers, compressing price floors for distributors without upstream access and locking margin advantages to coastal industrial corridors. Bulk liquid nitrogen delivery economics create step-function cost barriers that protect incumbent positions in German meat processing clusters while exposing cylinder-dependent competitors to volume-based price erosion.
Pricing Analysis
Certification level under ISO 22000 and EU Regulation 231/2012 creates the primary spread between premium pipeline contracts and economy cylinder supply. Three-tier pricing structure across premium, standard, and economy levels reflects purity documentation burdens, with FDA-grade analytical testing costs falling heaviest on smaller regional distributors. Cost compression in standard-tier liquid delivery is intensifying because membrane nitrogen generation eliminates transport revenue from French bakery sector clients. Food processors with direct pipeline access show least price sensitivity, while artisanal producers procuring through retail welding outlets face highest cost volatility.
Supply Chain Analysis
Germany and the Netherlands anchor carbon dioxide and nitrogen production through ammonia plant corridors and centralized meat processing infrastructure. Feedstock draws from natural gas reforming and fermentation capture, with purification equipment and cryogenic tanker fleets constituting critical capital components. Single-source vulnerability concentrates in coastal ammonia plant maintenance cycles, which disrupt carbon dioxide supply to dairy bottling networks. Distribution runs through direct pipeline contracts for large processors, regional bulk storage for mid-tier accounts, and cylinder networks for dispersed small-scale users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modified atmosphere packaging penetration in frozen ready meals represents an early-cycle expansion opportunity, with retail distribution center consolidation driving specification standardization that favors qualified suppliers. EFSA circular feedstock guidance and EU Green Deal methane targets accelerate fermentation-derived carbon dioxide qualification as a structural tailwind.
For Market Incumbents: Fortify pipeline density in Central European meat processing corridors through long-term volume guarantees with Polish and Czech Republic slaughterhouse clusters. Invest in captive fermentation-derived carbon dioxide capture to preempt EFSA documentation requirements that threaten ammonia-plant-dependent competitors. Certification investment in ISO 8573-1 compressed air purity compliance extends qualification timelines for new production facilities, creating defensive moats.
For New Entrants and Emerging Players: On-site membrane nitrogen generation services for mid-sized French and Italian bakery sector clients present a service-layer gap where incumbents under-serve with legacy liquid delivery models. Target dairy cooperatives in Brittany and Normandy demanding segregated fossil-free carbon dioxide supply chains. Go-to-market through technology licensing partnerships with equipment manufacturers bypasses cryogenic tanker fleet capital barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional pipeline operators with meat cluster proximity over integrated chemical conglomerates facing feedstock transition costs. Long-term viability rests on circular feedstock qualification capabilities and on-site generation technology portfolios. Watch EFSA final guidance on recycled carbon dioxide as the inflection indicator for fermentation-derived supply chain premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capture | Secures EFSA-compliant circular feedstock for dairy corridor contracts ahead of fossil-source exclusion mandates. |
| On-Site Nitrogen Generation Deployment | Eliminates liquid delivery dependency for French bakery sector clients while capturing recurring service revenue streams. |
| Direct Pipeline Expansion | Locks volume guarantees with German and Netherlands meat processing clusters where specification consistency is mandatory. |
| ISO 22000 Certification Investment | Qualifies entry into multinational food processor supply chains that exclude uncertified distributors from tender processes. |
| Regional Distribution Center Density | Captures microbulk and cylinder demand from mid-tier Polish and Czech Republic processors without pipeline access. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with gas procurement managers at multinational food processors, technical directors at industrial gas distributors, and regulatory affairs leads navigating FDA and EFSA compliance pathways. Secondary validation incorporated customs and trade data on cryogenic equipment imports, SEC filings from listed industrial gas conglomerates, EU ETS emission registry disclosures, and ISO certification body audit records. Bottom-up volume modeling across gas type, application, and end-user segments was triangulated against top-down market sizing from production capacity databases.
Across the analysis window, the forecasting framework modeled carbon dioxide and nitrogen demand through segmentation by supply channel, purity grade tier, and regional production hub concentration. CAGRs were derived from elasticity-adjusted consumption projections tied to modified atmosphere packaging adoption curves and slaughterhouse stunning regulation compliance timelines. Industry-specific inputs included ammonia plant operating rates, membrane nitrogen generation technology penetration rates in the bakery sector, and EFSA guidance implementation schedules for circular feedstock claims.
Underlying assumptions cover sustained EU Green Deal methane reduction enforcement and EFSA draft guidance finalization, with deviation risk concentrated in ammonia plant feedstock supply disruptions and accelerated on-site generation technology cost reductions. Recalibration cycles align with material shifts in regulatory guidance publication, major processing facility commissioning, and circular carbon dioxide qualification protocol adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Nitrogen Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
Global Sulfur Dioxide Market
Industrial Gases
South-East Asia (SEA) Syngas Market
Industrial Gases
Europe Industrial Gases Market
Industrial Gases
Welding Shielding Gas Market
Industrial Gases
Industrial Hydrogen Market
Industrial Gases
Nitrogen Gas Market
Industrial Gases
Global Industrial Gas Market
Industrial Gases
Noble Gas Market
Industrial Gases
Global Helium Gas Market
Industrial Gases
North America Industrial Gases Market
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
Global Specialty Gas Market
Industrial Gases
Syngas Market
Industrial Gases
Argon Gas Market