
 GCC Industrial Gases Market | 2026-2036
GCC Industrial Gases Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Industrial Gases Market Intelligence
Project finance tied to long-term offtake agreements is tilting competitive dynamics toward capital-heavy operators with balance-sheet depth. Linde leverages its integrated production and distribution footprint across Jubail and Yanbu to sustain pricing power. Air Liquide anchors its position through on-site supply contracts with Saudi Aramco and SABIC affiliates. Gulf Cryo competes as a regional specialist with captive ASU networks in Qatar and Kuwait.
GCC industrial gases encompass atmospheric gases and process gases produced via cryogenic air separation, pressure swing adsorption, or steam methane reforming, with purity grades typically exceeding 99.5% for industrial applications. These gases serve essential functions in oxidation, inerting, cooling, and chemical synthesis across heavy industry. Oxygen dominates volume flows into metal fabrication and petrochemical oxidation, where margin pools concentrate in long-term pipeline supply. Hydrogen within the product mix is expanding fastest, driven by refinery desulfurization and emerging ammonia export projects. Electronics applications remain nascent in the GCC but represent a higher-margin growth vector as semiconductor investments materialize in the UAE and Saudi Arabia.
Saudi Arabia's General Authority for Civil Aviation and the Saudi Standards, Metrology and Quality Organization enforce product purity and cylinder safety protocols, while the UAE's Ministry of Energy and Infrastructure oversees hazardous material transport across emirates. These frameworks elevate compliance costs for new entrants but reinforce incumbent advantages through certified asset bases. Stakeholders must monitor how green hydrogen certification standards reshape contract structures and capital allocation priorities.
Market Dynamics
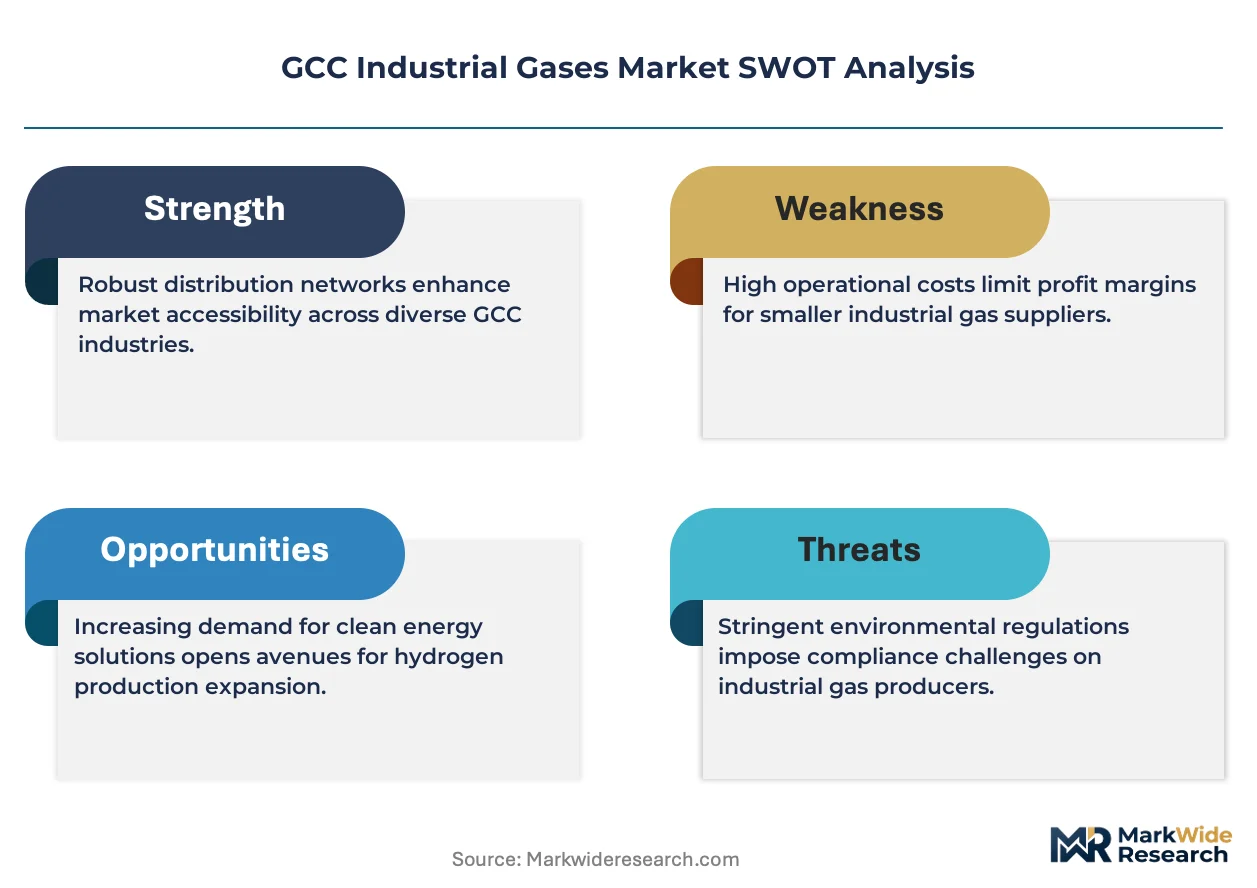
Project finance tied to long-term offtake agreements is tilting competitive dynamics toward capital-heavy operators with balance-sheet depth. Saudi Arabia's dual carbon goals under Vision 2030 are tightening emissions standards for industrial gas production, forcing asset-heavy reconfiguration across the Gulf.
Growth Catalysts
- Jubail Industrial City concentration:The densest cluster of gas-consuming facilities in Saudi Arabia's Eastern Province generates pipeline-scale demand that amortizes fixed production costs across integrated refining and petrochemical complexes.
- Hydrogen desulfurization mandates:Refinery upgrading requirements under tightening fuel quality specifications are expanding hydrogen volume flows for hydrocracking and sulfur removal operations.
- Green hydrogen certification frameworks:Emerging standards for renewable-origin hydrogen are reshaping contract structures and attracting capital toward electrolyzer-integrated production assets.
Market Restraints
- Natural gas feedstock volatility:Steam methane reforming economics remain exposed to regional gas pricing fluctuations that compress hydrogen production margins.
- ASU supply concentration:Cryogenic air separation unit capacity clusters around Jubail and Yanbu, creating geographic single-point vulnerabilities for oxygen and nitrogen supply security.
- Electronics-grade purity barriers:Sub-ppb contamination control for semiconductor applications exceeds current regional technical capabilities, limiting addressable market expansion.
Strategic Opportunities
- UAE semiconductor investments:Emerging fab capacity in Abu Dhabi and Dubai is creating first-mover openings for ultra-high-purity gas supply contracts.
- Carbon capture integration:Blue hydrogen production paired with CCUS infrastructure qualifies for preferential offtake terms under Saudi Arabia's circular carbon economy framework.
- Modular ASU deployment:Containerized air separation units enable rapid market entry into Kuwait's nascent industrial zones without pipeline infrastructure commitments.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized expertise in low-temperature process design and cold-box maintenance remains concentrated among incumbent operators.
- SFDA certification timelines:Product purity approvals for medical oxygen and food-grade gases extend commercialization cycles for new production assets.
- Legacy cylinder fleet integration:Tracking and recertifying existing high-pressure vessel inventories complicates digital supply chain transformation initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Industrial Gases Market |
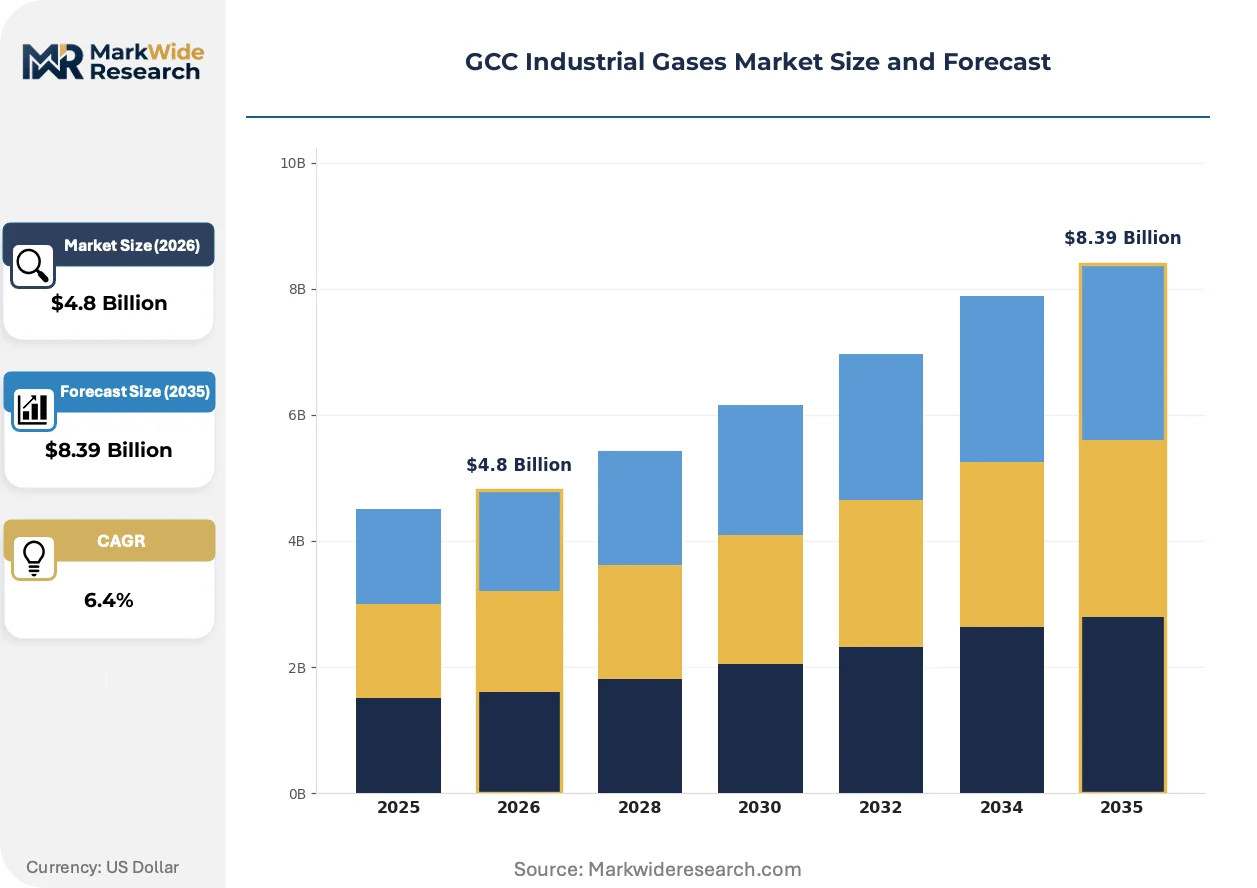
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oxygen, Nitrogen, Argon, Hydrogen Application: Metal Fabrication, Chemical Manufacturing, Food Processing, Electronics End User: Manufacturing, Healthcare, Automotive, Energy Distribution Channel: Direct Sales, Wholesale, Online, Retail |
| Companies Covered | Linde, Air Products and Chemicals, Air Liquide, ADNOC Industrial Gas, Abdullah Hashim Industrial Gases, Gulf Cryo, SIPCHEM, Buzwair Industrial Gases, SABIC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Industrial Gases Market Strategic Shifts & Innovations
Digital infrastructure is virtualizing core operational layers across GCC industrial gas supply chains. Remote monitoring, predictive maintenance, and automated scheduling are compressing traditional service models.
Digital twin technology for cryogenic process simulation is virtualizing plant optimization workflows. Saudi Aramco and SABIC affiliates are piloting virtual commissioning for new ASU installations, reducing startup timelines. This virtualization is compressing the engineering-procurement-construction cycle and enabling faster capacity scaling without proportional staff expansion.
Saudi Arabia's General Authority for Civil Aviation and the Saudi Standards, Metrology and Quality Organization are tightening cylinder safety and transport protocols. These frameworks elevate compliance costs but reinforce incumbent advantages through certified asset bases. Hydrogen pipeline projects in Jubail are most affected, requiring retrofitted safety management systems.
Buyer consolidation among integrated petrochemical operators is compressing supplier negotiation leverage. Long-term take-or-pay contracts are displacing spot market transactions for oxygen and nitrogen volumes. This pattern is most visible in Saudi Arabia's Eastern Province, where SABIC and Aramco affiliates command unified procurement positions.
GCC Industrial Gases Market Segmentation
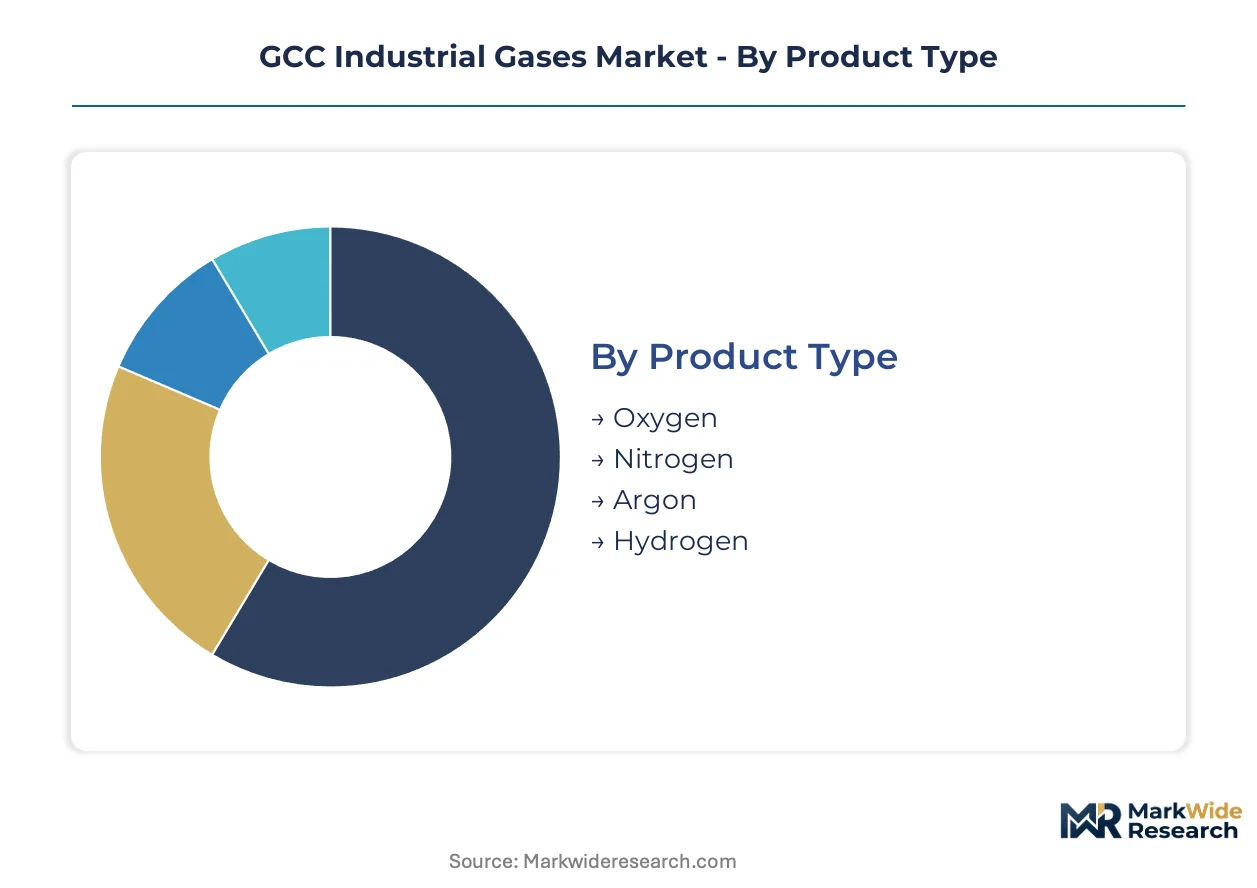
Industrial gas segmentation in the GCC reflects divergent maturity curves across product chemistry, end-use sophistication, and channel infrastructure. Each dimension carries distinct margin profiles and capital requirements that reshape competitive positioning.
Product Type:
Mature atmospheric gases dominate current revenue pools while hydrogen emerges as the structurally expanding category.
- Oxygen:Cryogenic air separation yields purity grades exceeding 99.5% for oxidation and combustion control. Demand concentrates in Jubail Industrial City's steel and petrochemical complexes where pipeline-scale offtake amortizes fixed ASU costs.
- Hydrogen:Steam methane reforming and emerging electrolyzer routes supply refinery desulfurization and ammonia synthesis. Saudi Aramco's blue hydrogen initiatives and NEOM green hydrogen exports are accelerating capacity commitments across the Eastern Province.
- Nitrogen:Inerting and blanketing applications in chemical processing and food packaging.
- Argon:Shielding gas for high-precision welding and semiconductor crystal growth.
Oxygen retains volume leadership; hydrogen holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity oxidation services from premium electronics-grade supply contracts.
- Metal Fabrication:Oxygen-fuel cutting and argon-shielded welding consume the largest atmospheric gas volumes across Saudi Arabia's Eastern Province steel mills. Long-term pipeline contracts with SABIC affiliates lock in predictable offtake with limited pricing volatility.
- Electronics:Ultra-high-purity nitrogen and specialty gas mixtures for semiconductor fabrication require sub-ppb contamination control. Abu Dhabi and Dubai fab investments are creating first-mover openings as regional technical capabilities mature.
- Chemical Manufacturing:Process gas feedstocks and inerting for petrochemical oxidation reactions.
- Food Processing:Modified atmosphere packaging and cryogenic freezing using nitrogen and carbon dioxide.
Metal fabrication anchors current revenue; electronics commands the premium pricing tier.
End User:
Customer type fragmentation spans integrated industrial operators, fragmented healthcare networks, and emerging mobility applications.
- Manufacturing:Integrated refining and petrochemical complexes in Jubail and Yanbu generate pipeline-scale demand with 15-20 year offtake horizons. SABIC and Saudi Aramco affiliates command unified procurement positions that compress supplier negotiation leverage.
- Energy:Hydrogen blending into existing natural gas infrastructure and power generation turbines. Saudi Arabia's circular carbon economy framework qualifies blue hydrogen production for preferential offtake terms when paired with CCUS.
- Healthcare:Medical oxygen for hospital networks and home respiratory therapy.
- Automotive:Hydrogen fuel cell mobility pilot programs and welding applications.
Manufacturing dominates contract value; energy is climbing fastest on hydrogen momentum.
Distribution Channel:
Supply concentration around pipeline infrastructure versus distributed cylinder logistics creates divergent margin structures.
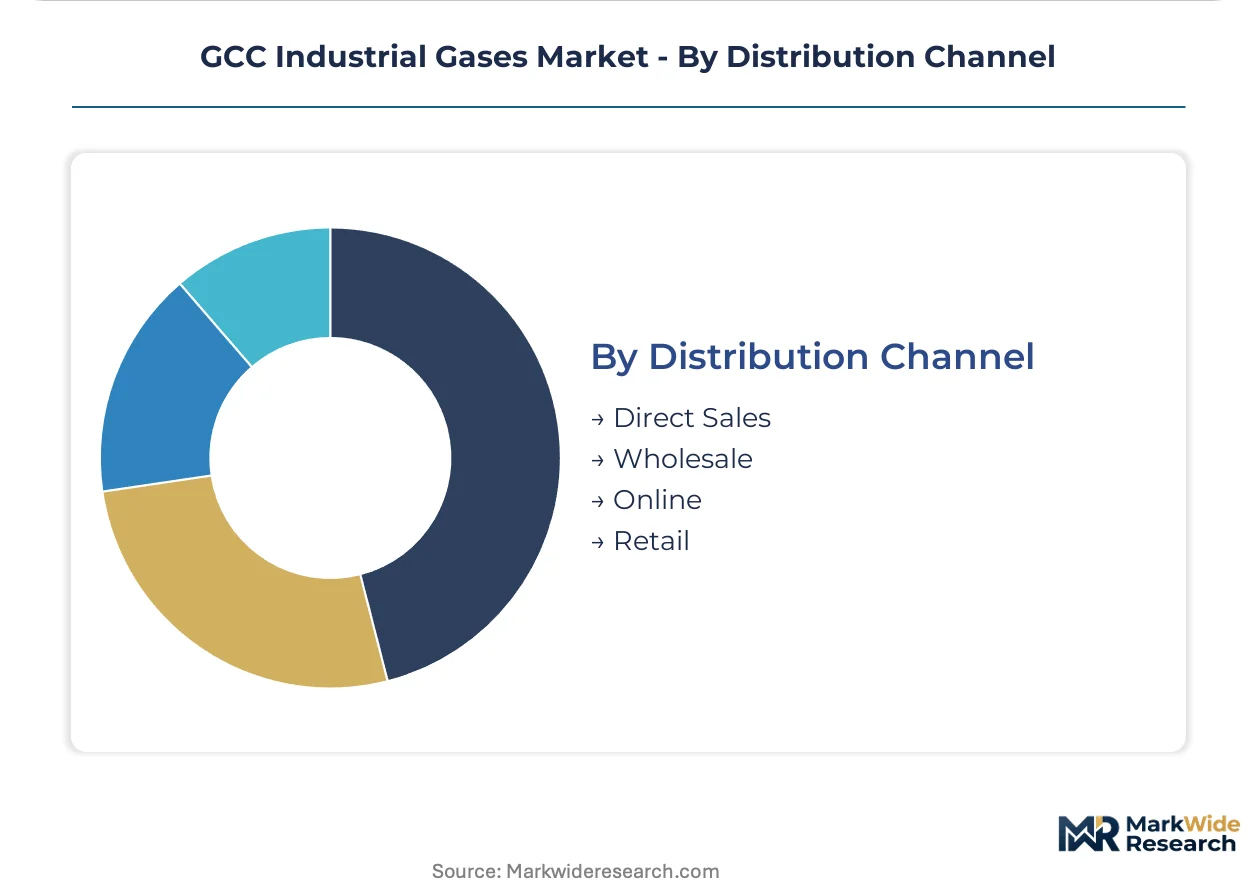
- Direct Sales:On-site production and pipeline supply to integrated industrial complexes eliminates transport costs and locks in 10-15 year take-or-pay contracts. Linde and Air Liquide sustain pricing power through captive ASU installations at Jubail and Yanbu.
- Wholesale:Bulk liquid delivery via cryogenic tanker trucks to mid-scale consumers without pipeline access. Gulf Cryo's regional specialist model competes through density in Qatar and Kuwait.
- Retail:High-pressure cylinder exchange for small industrial and maintenance applications.
- Online:Digital ordering platforms for standardized cylinder and dewar replenishment.
Direct sales capture margin concentration; wholesale channels enable geographic coverage expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The GCC industrial gases trade flows reflect a structural export surplus in hydrogen and atmospheric gases, with intra-regional pipeline networks displacing seaborne imports from European and Asian suppliers. Saudi Arabia and Qatar anchor outbound volumes through dedicated industrial zones, while the UAE and Kuwait remain net importers of specialty gas blends.
Saudi Arabia
Jubail Industrial City's integrated refining complex drives oxygen and nitrogen demand through 15-year pipeline contracts with SABIC affiliates. The Saudi Standards, Metrology and Quality Organization enforces cylinder safety protocols that extend certification timelines for new entrants. Yanbu's petrochemical corridor on the Red Sea coast is absorbing modular hydrogen capacity for export-oriented ammonia synthesis.
United Arab Emirates
Abu Dhabi's Ruwais refining expansion and Dubai's emerging semiconductor investments are bifurcating demand between commodity process gases and ultra-high-purity nitrogen. The Ministry of Energy and Infrastructure oversees hazardous material transport regulations across the seven emirates. Jebel Ali's logistics hub is consolidating bulk liquid distribution for re-export to African markets.
Qatar
The North Field expansion is redirecting natural gas feedstock toward blue hydrogen and ammonia export projects, tightening domestic industrial gas availability. Gulf Cryo's captive ASU networks in Ras Laffan serve LNG train maintenance and petrochemical inerting requirements. The Qatar General Electricity and Water Corporation's industrial tariff structures are influencing on-site versus merchant supply economics.
Kuwait
Al-Zour refinery commissioning and the Clean Fuels Project are accelerating hydrogen demand for hydrocracking and desulfurization operations. The country's national standards body enforces product purity specifications for refinery-grade gases. The Shuaiba industrial area lacks pipeline infrastructure, forcing reliance on cryogenic tanker delivery from Saudi production clusters.
Oman
Duqm Special Economic Zone's green hydrogen export ambitions are attracting electrolyzer-integrated production commitments from international developers. The Authority for Public Services Regulation governs industrial gas pricing and interconnection standards. Salalah's port infrastructure is positioning for transshipment of bulk liquid gases to East African markets.
GCC Industrial Gases Market Key Industry Players
On the supply side, the industry is consolidating around capital-heavy operators with integrated production and distribution footprints. Three strategic archetypes dominate: global majors leveraging balance-sheet depth for long-term offtake financing, regional specialists exploiting geographic density in underserved markets, and national oil company affiliates capturing captive demand from affiliated refining complexes. Competitive moves center on carbon capture integration for blue hydrogen qualification and modular ASU deployment to bypass pipeline infrastructure gaps.
Within the global major tier, Linde and Air Liquide exemplify capital-intensive positioning through on-site supply contracts and cryogenic asset bases. Gulf Cryo occupies a specialist position as a regional operator with concentrated networks in Qatar and Kuwait. These three anchors illustrate how competitive advantage in GCC industrial gases flows from asset specificity and contract duration rather than product differentiation.
| Leading Market Players |
|---|
| Linde |
| Air Products and Chemicals |
| Air Liquide |
| ADNOC Industrial Gas |
| Abdullah Hashim Industrial Gases |
| Gulf Cryo |
| SIPCHEM |
| Buzwair Industrial Gases |
| SABIC |
| Others |
Cost & Logistics Intelligence
Natural gas feedstock volatility compresses hydrogen production margins while simultaneously widening the spread between pipeline-scale and merchant supply pricing tiers across the Gulf. This commodity exposure forces capital-heavy operators to anchor long-term offtake structures around fixed-price clauses that transfer volume risk to integrated petrochemical buyers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing that stratifies across premium, standard, and economy tiers based on purity grade and volume scale. Pricing pressure stems from buyer consolidation among SABIC and Saudi Aramco affiliates, which compress supplier negotiation leverage through unified procurement positions. Merchant buyers lacking pipeline access face the greatest price sensitivity due to cryogenic tanker delivery premiums and ASU capacity scarcity outside Jubail and Yanbu.
Supply Chain Analysis
Export-control restrictions on cryogenic cold-box technology and high-pressure vessel certification limit equipment flows into the GCC, concentrating ASU manufacturing capabilities among incumbent operators with established supplier relationships. Production draws from Saudi Arabia, Qatar, and the UAE, with feedstock dependencies on natural gas, specialized alloys, and precision instrumentation. Single-source vulnerability around cryogenic engineering talent elevates maintenance backlogs and extends commissioning timelines. Distribution runs through pipeline networks to integrated complexes and bulk liquid tanker fleets to mid-scale consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC industrial gases market is entering a cyclical recovery phase as refinery upgrading mandates and ammonia export projects drive hydrogen capacity commitments. Capital expenditure cycles tied to Saudi Vision 2030 infrastructure spending provide the demand floor for this rebound.
For Market Incumbents: Harden asset specificity advantages through carbon capture integration for blue hydrogen qualification under Saudi Arabia's circular carbon economy framework. Expand modular ASU deployment into Kuwait's Shuaiba industrial area to preempt merchant supply gaps. Lock in 15-20 year take-or-pay extensions with SABIC affiliates before buyer consolidation completes.
For New Entrants and Emerging Players: Electronics-grade nitrogen supply contracts for Abu Dhabi and Dubai semiconductor fabs represent the most penetrable entry point given sub-ppb purity barriers that exclude regional merchant operators. Containerized air separation units for Oman's Duqm Special Economic Zone enable rapid market entry without pipeline infrastructure commitments. Pursue joint development structures with international electrolyzer developers to share green hydrogen certification costs.
For Investors and Strategic Acquirers: SFDA medical oxygen certification timelines reshaping the acquisition landscape favor targets with existing certified asset bases over greenfield development plays. Five-to-ten year viability hinges on positioning for hydrogen export corridor economics rather than domestic merchant supply saturation. Watch for green hydrogen offtake agreement announcements from NEOM project developers as the inflection signal for capital reallocation toward electrolyzer-integrated production.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Capture | Qualifies blue hydrogen production for preferential offtake terms under Saudi circular carbon regulations. |
| Modular ASU Deployment | Enables rapid capacity scaling in Kuwait and Oman without pipeline infrastructure commitments. |
| Long-term Supply Agreement | Locks in 15-20 year offtake horizons with SABIC and Aramco affiliates amid buyer consolidation. |
| Joint Venture | Distributes green hydrogen certification costs and electrolyzer technology transfer risks. |
| Green Manufacturing Transition | Positions production assets for emerging renewable-origin hydrogen standards reshaping contract structures. |
Research Approach
The analysis maps atmospheric gases, process gases, and hydrogen sub-sectors, each validated through interviews with ASU plant managers, procurement leads at SABIC affiliates, cryogenic engineering specialists, and SFDA certification officers. Secondary sources include customs and trade flow data, Saudi Standards Metrology and Quality Organization filings, and SEC disclosures from listed industrial gas operators. Bottom-up capacity assessments triangulate against top-down demand projections from petrochemical expansion announcements.
Assumptions held fixed include Saudi Vision 2030 refinery upgrading timelines and existing natural gas pricing frameworks, while hydrogen export volumes and electrolyzer cost curves were varied across sensitivity scenarios. Segmentation modeling spans product chemistry, purity grade tier, end-use industry, and distribution channel structure. CAGRs derive from production capacity build-out schedules correlated with named project development milestones and offtake contract durations.
Practitioners should monitor green hydrogen certification standard finalization and carbon border adjustment mechanism developments for early signals of contract structure disruption. Forecasts reflect these documented assumptions and baseline scenario parameters. Material shifts in Saudi Aramco's blue hydrogen capital allocation or NEOM project delivery timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Global Rare Gases Market
Industrial Gases
Sulfur Recovery Tail Gas Analyzer Market
Industrial Gases
Pressure Swing Adsorption Nitrogen Generator Market
Industrial Gases
Gas and Liquid Argon Market
Industrial Gases
Global Laboratory Gas Generators Market
Industrial Gases
Gas Purifiers Market
Industrial Gases
Gas Sampling Line Market
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
US and Canada Helium Gas Market
Industrial Gases
Oxygen Market
Industrial Gases
Nitrogen Gas Springs Market
Industrial Gases
Low-Carbon Hydrogen Solutions for Industrial Cluster Decarbonization Market
Industrial Gases
Middle-East and Africa Syngas Market
Industrial Gases
Commercial Hydrogen Market
Industrial Gases
LAMEA Industrial Nitrogen Market
Industrial Gases
Global Sulfur Dioxide Market