
 North America Syngas Market | 2026-2036
North America Syngas Market Size, Share, and Industry Trends Forecast 2026-2036
North America Syngas Market Analytics
Buyer concentration among North American chemical and power utilities is broadening as independent hydrogen producers and regional agricultural cooperatives enter the offtake mix. Sasol leverages its Fischer-Tropsch expertise to anchor large-scale syngas-to-liquids projects in the US Gulf region. Air Products and Chemicals Inc. sustains technology leadership through proprietary gasification and carbon capture integration. Linde plc competes by controlling industrial gas distribution networks that feed syngas-derived hydrogen into refinery and ammonia customers.
Syngas refers to a combustible gas mixture comprising primarily carbon monoxide and hydrogen, produced through partial oxidation or steam reforming of carbonaceous feedstocks such as coal, petroleum coke, biomass, or natural gas at temperatures typically exceeding 700°C; its primary industrial purpose is serving as an intermediate feedstock for synthesizing chemicals, liquid fuels, and hydrogen. Hydrogen output from syngas gasification dominates value capture in the current North American landscape, while methanol synthesis occupies mature, high-volume positions tied to formaldehyde and olefin production. Fischer-Tropsch liquids represent the fastest-expanding product category as refiners seek synthetic crude alternatives to supplement conventional barrel supply.
The US EPA enforces emissions thresholds under the Clean Air Act that constrain coal-based gasification expansions, while OSHA mandates process safety management standards for high-pressure syngas handling facilities. Canada's federal carbon pricing framework and Alberta's technology innovation corridor shape project economics for oil sands-derived syngas operations. Stakeholders must monitor how evolving clean hydrogen tax credit eligibility rules under the IRA interact with state-level renewable portfolio standards to determine feedstock and technology commitments.
Market Dynamics
The US Inflation Reduction Act's clean hydrogen production tax credits are redirecting capital flows toward lower-carbon gasification pathways, fundamentally altering project economics across Texas and Louisiana petrochemical corridors.
Growth Catalysts
- IRA Tax Credits:The Inflation Reduction Act's Section 45V credits reward producers achieving sub-4 kg CO2e/kg H2 lifecycle emissions, accelerating renewable natural gas and biomass feedstock adoption in US Gulf Coast clusters.
- Fischer-Tropsch Liquids Demand:Refiners seeking synthetic crude alternatives to supplement conventional barrel supply are expanding offtake contracts for syngas-derived synthetic fuels.
- Canada Carbon Pricing:Alberta's technology innovation corridor and federal carbon pricing framework improve project economics for oil sands-derived syngas with integrated carbon capture.
Market Restraints
- EPA Emissions Thresholds:The Clean Air Act constrains coal-based gasification expansions through stringent permitting requirements for new facilities.
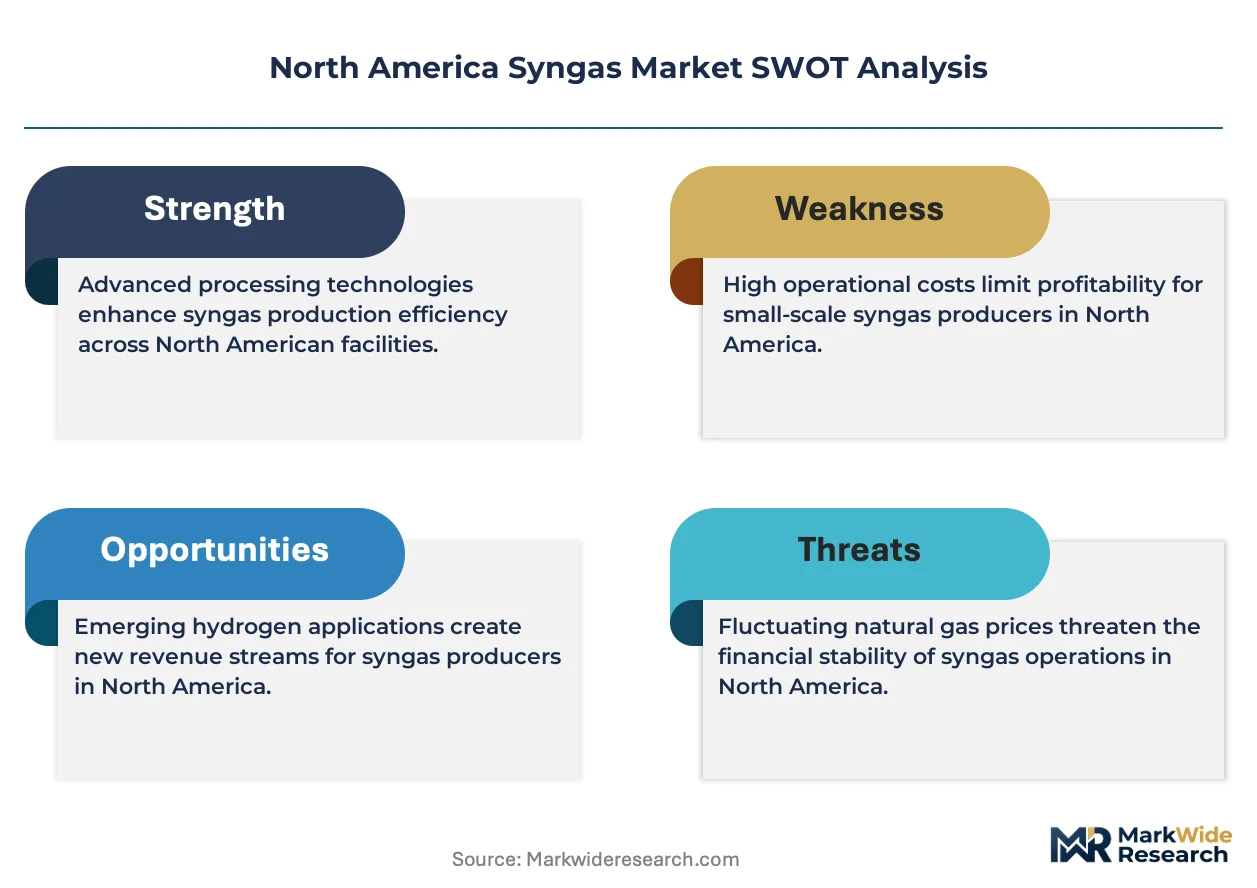
- Natural Gas Price Volatility:Feedstock cost swings in Henry Hub pricing compress margins for steam methane reforming operations dependent on pipeline gas supply.
- Biomass Supply Concentration:Agricultural residue collection infrastructure remains underdeveloped across Midwest feedstock regions, limiting scale-up velocity.
Strategic Opportunities
- Carbon Capture Integration:45Q tax credits for sequestered CO2 create economic headroom for blue hydrogen production at US Gulf Coast ammonia complexes.
- Renewable Natural Gas Pathways:Landfill and anaerobic digester biogas upgrading to pipeline-quality RNG opens feedstock diversification for California and Northeast producers.
- Electrolyzer-Gasification Hybrids:Power-to-gas systems combining grid electricity with biomass gasification enable negative-emission hydrogen certification in Canadian prairie provinces.
Industry Challenges
- High-Pressure Systems Engineering:OSHA process safety management standards for syngas handling facilities require specialized talent pools that remain constrained across Louisiana and Texas industrial corridors.
- Carbon Intensity Certification:Lifecycle assessment methodology disputes between EPA, California Air Resources Board, and third-party verifiers delay clean hydrogen qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Syngas Market |
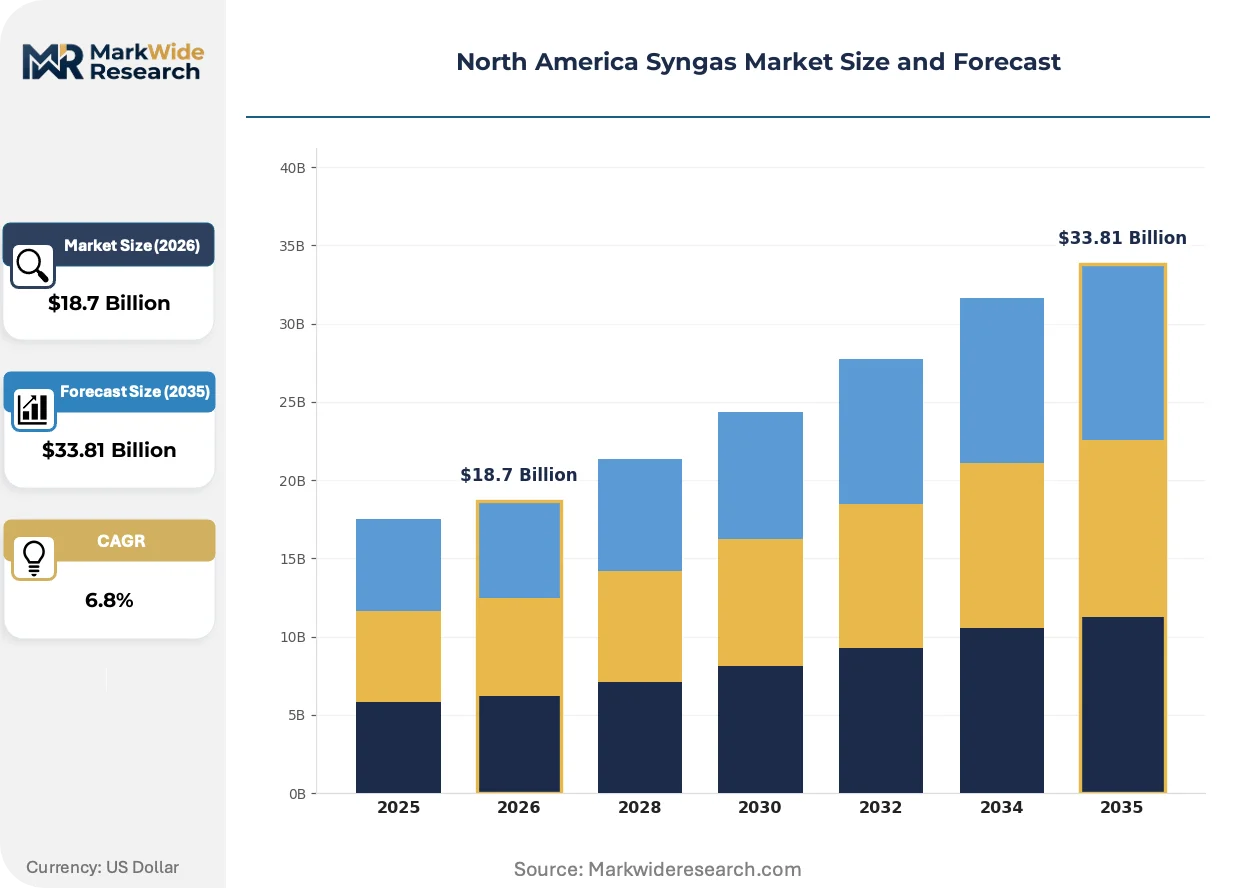
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Methanol, Fischer-Tropsch Liquids, Hydrogen, Ammonia Technology: Gasification, Reforming, Pyrolysis, Anaerobic Digestion End User: Chemical Industry, Power Generation, Fuel Production, Agriculture Application: Energy Generation, Raw Material Synthesis, Fuel Cells, Industrial Heating |
| Companies Covered | Sasol, Haldor Topsoe A/S, Air Products and Chemicals Inc., KBR Inc., General Electric, Linde plc, Royal Dutch Shell plc, TechnipFMC PLC, Air Liquide, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Syngas Market Evolving Landscape
Technology convergence between carbon capture systems and gasification units is compressing project development cycles while regulatory clarity on hydrogen tax credit eligibility is crystallizing investment commitments across North American chemical corridors.
Plasma gasification systems are absorbing residual waste streams from municipal and industrial sources at temperatures exceeding 3,000°C, eliminating tar formation and enabling smaller-scale distributed production. Waste-to-energy developers in Ontario and California are piloting modular units for hydrogen and methanol output. This technology is absorbing stranded feedstock volumes that conventional entrained-flow reactors cannot process economically.
The EPA's proposed revisions to New Source Performance Standards for greenhouse gas emissions from industrial sources are tightening CO2 intensity benchmarks for new gasification facilities. Methanol producers in Texas and Louisiana face accelerated compliance timelines for carbon capture retrofits. Ammonia complexes with pre-combustion capture loops are positioning for priority permitting under the revised framework.
Refinery procurement departments are consolidating hydrogen offtake contracts through multi-year tolling agreements rather than spot market purchases. Integrated producers with captive syngas capacity are capturing margin from merchant hydrogen shortages. This pattern concentrates most visibly in California where Low Carbon Fuel Standard credit values incentivize long-term supply security over price arbitrage.
North America Syngas Market Segmentation
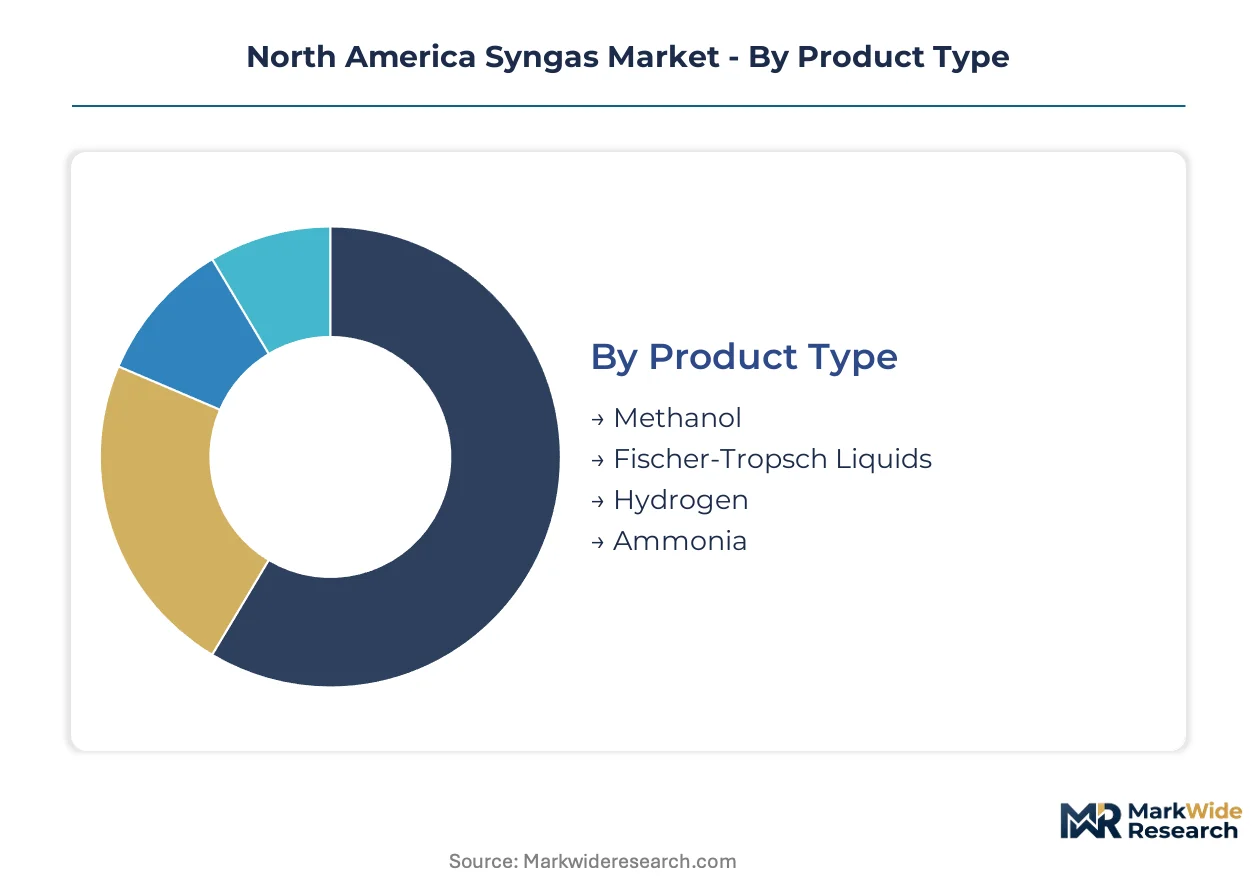
Syngas segmentation reveals how technology choices and end-use specifications dictate feedstock requirements, carbon intensity profiles, and capital deployment patterns across North American chemical corridors. Product type distinctions separate commodity hydrogen from higher-margin synthetic fuels, while technology selection determines project eligibility for IRA production tax credits.
Product Type:
Hydrogen commands volume leadership while Fischer-Tropsch liquids capture premium pricing in refinery offtake contracts.
- Hydrogen:Purified H2 streams from water-gas shift reactions serve ammonia synthesis and refinery hydrotreating units across Texas and Louisiana. Gulf Coast petrochemical clusters absorb the majority of merchant supply as clean hydrogen tax credits reshape project economics.
- Fischer-Tropsch Liquids:Synthetic crude and middle distillates produced via cobalt or iron catalyst systems supply California refiners seeking Low Carbon Fuel Standard compliance. Offtake agreements now stretch five to seven years as conventional barrel availability tightens.
- Methanol:Formaldehyde and olefin production absorbs steady volumes from established Gulf Coast facilities.
- Ammonia:Fertilizer and maritime fuel applications drive demand concentration in agricultural heartlands and coastal export terminals.
Mature deployment sits with methanol and ammonia. Newer deployment is concentrated in Fischer-Tropsch liquids as refiners diversify synthetic crude supply.
Technology:
Cost tier separation distinguishes capital-intensive gasification from lower-capex reforming alternatives.
- Gasification:Entrained-flow and fluidized-bed reactors processing coal, petroleum coke, or biomass at 1200-1500°C dominate large-scale hydrogen and power projects. Integrated carbon capture loops at Alberta oil sands facilities and US Gulf Coast ammonia complexes position for 45Q credit monetization.
- Reforming:Steam methane reforming with autothermal variants supplies 95% of merchant hydrogen in North America. Henry Hub price exposure compresses margins during winter demand spikes, accelerating renewable natural gas feedstock pilots.
- Pyrolysis:Thermal decomposition of waste plastics and biomass generates syngas for smaller-scale distributed production units.
- Anaerobic Digestion:Biogas upgrading to pipeline-quality renewable natural gas creates feedstock pathways for California and Northeast low-carbon hydrogen certification.
Established capacity clusters around gasification and reforming. Pyrolysis and anaerobic digestion are climbing the fastest as waste-to-energy developers scale modular systems.
End User:
Customer type determines contract structure, with chemical majors demanding tolling agreements and agricultural buyers preferring spot flexibility.
- Chemical Industry:Methanol-to-olefins producers and ammonia synthesizers anchor offtake demand with 15-20 year supply contracts. Dow, BASF, and Nutrien facilities along the Gulf Coast specify sub-2 kg CO2e/kg H2 intensity thresholds to qualify for IRA Section 45V credits.
- Fuel Production:Refinery hydrogen demand for hydrocracking and desulfurization absorbs merchant supply during turnaround seasons. Synthetic fuel offtake from Fischer-Tropsch units targets California LCFS credit stacking and maritime bunker fuel specifications.
- Power Generation:Integrated gasification combined cycle plants in Indiana and petroleum coke-to-power facilities in Texas burn syngas for baseload electricity.
- Agriculture:Regional fertilizer cooperatives in Iowa and Illinois purchase ammonia derived from syngas for seasonal application cycles.
Contract maturity sits with chemical industry tolling agreements. Fuel production represents the steepest expansion trajectory as synthetic crude alternatives gain refinery blend mandates.
Application:
Margin structure separates commodity energy sales from high-value chemical synthesis and fuel cell feedstock premiums.
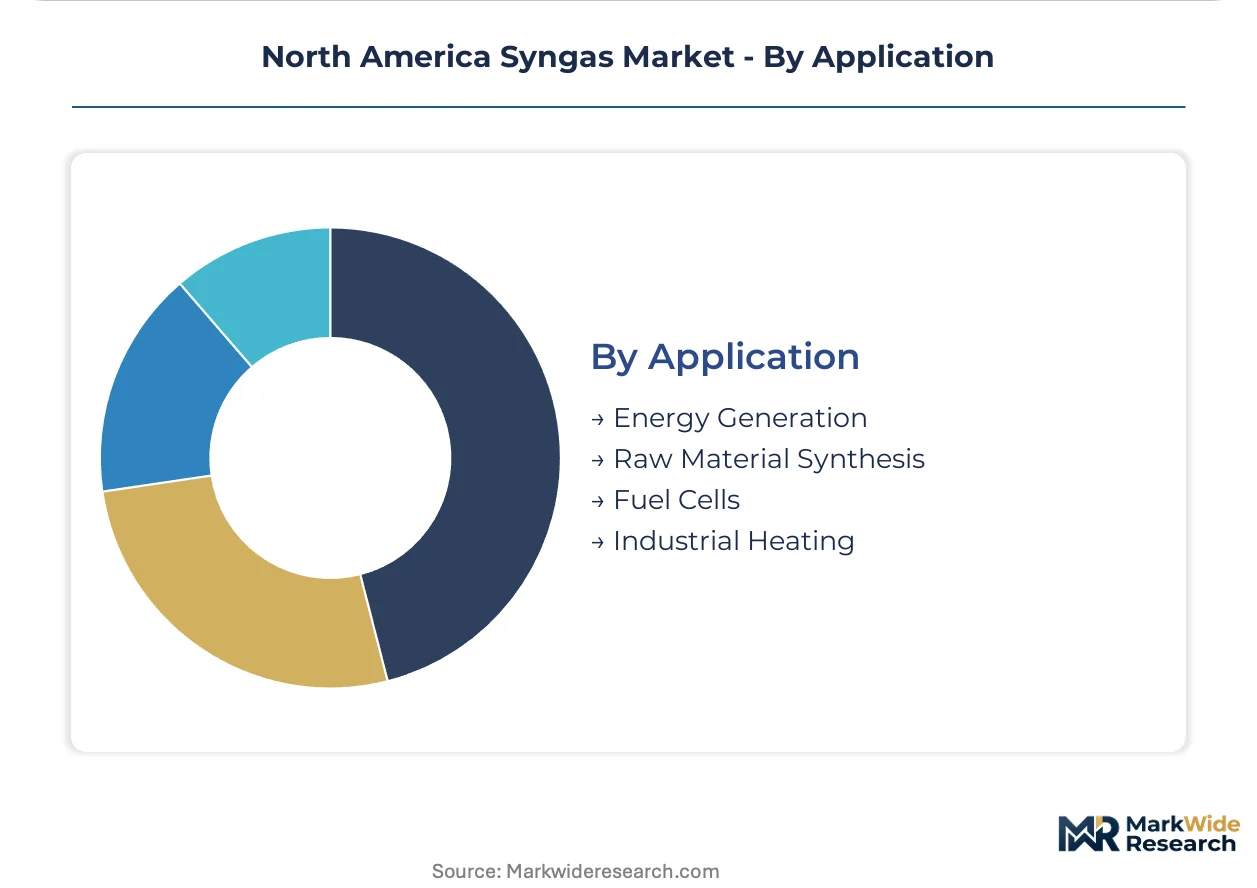
- Raw Material Synthesis:Methanol, ammonia, and synthetic hydrocarbon production consumes the largest syngas volumes. Petrochemical integration at Baytown, Beaumont, and Lake Charles complexes maximizes carbon utilization efficiency through heat and hydrogen co-production.
- Fuel Cells:High-purity hydrogen for proton exchange membrane and solid oxide fuel cells commands purity premiums above 99.97%. California transit agencies and data center operators in Virginia source dedicated supply for zero-emission power backup.
- Energy Generation:Syngas combustion in turbines and boilers serves industrial facilities with captive power needs.
- Industrial Heating:Direct syngas firing in cement kilns and steel reheat furnaces displaces natural gas in carbon-constrained jurisdictions.
Volume concentration sits with raw material synthesis. Fuel cell applications are expanding most quickly as stationary power and mobility deployments scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin's stranded natural gas and petroleum coke reserves anchor North American syngas feedstock availability, while Alberta's oil sands bitumen and biomass residues from Midwest agricultural operations complete the regional supply mosaic.
United States
Texas Gulf Coast refineries and Louisiana ammonia complexes absorb the majority of merchant syngas-derived hydrogen as clean hydrogen tax credits reshape project economics. EPA's Clean Air Act New Source Performance Standards constrain coal-based gasification permitting timelines. Houston-Beaumont-Port Arthur industrial corridor concentrates entrained-flow gasification capacity with integrated carbon capture loops positioning for 45Q credit monetization.
Canada
Alberta oil sands upgraders and Saskatchewan potash producers drive syngas demand for hydrogen and power generation feedstock. Federal carbon pricing framework and provincial technology innovation corridor improve project economics for bitumen-derived syngas with pre-combustion capture. Edmonton-Calgary industrial corridor hosts integrated gasification combined cycle facilities serving oil sands extraction and upgrading operations.
Mexico
Pemex refinery hydrogen demand and emerging ammonia export terminal projects create offtake concentration along Gulf Coast petrochemical corridors. Energy regulatory commission permitting frameworks for combined-cycle gasification projects remain under development. Tamaulipas-Veracruz industrial zone attracts preliminary feasibility studies for petroleum coke-to-syngas facilities serving refinery hydrotreating units.
North America Syngas Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue renewable natural gas and biomass feedstock pathways to qualify for IRA Section 45V credits. The vendor base stratifies across three tiers: integrated industrial gas majors with captive distribution networks, technology licensors with proprietary gasification reactor designs, and regional project developers assembling feedstock-offtake partnerships. Dominant competitive moves include carbon capture integration mandates and renewable natural gas offtake contracting for clean hydrogen certification.
Within the technology licensor tier, Sasol and Haldor Topsoe A/S exemplify Fischer-Tropsch catalyst and reactor system specialization. Air Products and Chemicals Inc. occupies a position spanning industrial gas production and proprietary gasification technology. These three entities anchor competitive positioning across syngas-to-liquids and syngas-to-hydrogen value chains.
| Leading Market Players |
|---|
| Sasol |
| Haldor Topsoe A/S |
| Air Products and Chemicals Inc. |
| KBR Inc. |
| General Electric |
| Linde plc |
| Royal Dutch Shell plc |
| TechnipFMC PLC |
| Air Liquide |
| Others |
Value Network & Pricing Analysis
Henry Hub natural gas pricing transmits directly through steam methane reforming economics to hydrogen offtake contracts, compressing margins for merchant producers while rewarding integrated Gulf Coast operators with captive feedstock supply.
Pricing Analysis
Long-term tolling agreements bundle carbon capture warranties and guaranteed availability clauses, separating premium hydrogen supply from spot-indexed commodity tiers. Price differentiation rests on IRA Section 45V credit eligibility tiers and carbon intensity certification from third-party verifiers. Pricing pressure intensifies in the merchant hydrogen segment as refinery procurement departments consolidate offtake through multi-year contracts. Agricultural cooperatives exhibit highest price sensitivity due to seasonal demand cycles and fertilizer margin constraints.
Supply Chain Analysis
Domestic-content mandates under the US Inflation Reduction Act's bonus credit provisions are reshaping catalyst and equipment sourcing toward North American fabrication facilities. Feedstock supply concentrates in the Permian Basin, Alberta oil sands, and Midwest agricultural corridors. Raw material dependencies include petroleum coke, natural gas, and biomass residues. Tariff exposure on specialized reactor vessels from European suppliers creates procurement risk. Distribution runs through dedicated pipeline networks serving Texas and Louisiana petrochemical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where IRA tax credit eligibility thresholds are forcing sub-scale gasification operators toward acquisition or exit.
For Market Incumbents: Cement technology leadership through proprietary carbon capture integration at existing Gulf Coast ammonia complexes. Acquire distressed biomass gasification assets in the Midwest to secure renewable natural gas feedstock pathways. The emerging threat of electrolyzer-based hydrogen producers demands defensive positioning around existing pipeline infrastructure and refinery relationships.
For New Entrants and Emerging Players: Enter via plasma gasification pilots processing municipal waste streams in Ontario and California regulatory jurisdictions. White-space concentration sits with distributed hydrogen production for data center backup power and California transit agency fuel cell deployments. A go-to-market angle anchored on negative-emission hydrogen certification through biomass-CCS combinations offers the cleanest credit stacking opportunity.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale gasification operators with permitted air rights in Texas and Louisiana industrial corridors but stranded without offtake consolidation. Long-term viability centers on captive carbon sequestration geology and proximity to existing hydrogen pipeline networks. The signal to watch is EPA finalization of New Source Performance Standards tightening, which will accelerate compliance-driven M&A.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit | Positions ammonia complexes for 45Q credit monetization under EPA compliance timelines. |
| Renewable Natural Gas offtake contracting | Secures feedstock eligibility for IRA Section 45V clean hydrogen certification. |
| Fischer-Tropsch capacity expansion | Captures California LCFS credit premiums from synthetic crude refinery demand. |
| Plasma gasification pilot deployment | Enables distributed hydrogen production from stranded waste feedstocks. |
| Pipeline infrastructure control | Locks in merchant hydrogen distribution to Gulf Coast refinery clusters. |
Research Methodology
Independent corroboration across executive interviews at syngas-to-hydrogen producers, procurement leads at Gulf Coast refineries, and carbon capture engineering specialists underwrites the qualitative findings. Primary fieldwork encompassed plant managers at Texas and Louisiana ammonia complexes, EPC contractors specializing in gasification retrofits, and regulatory affairs directors navigating IRA credit eligibility. Secondary validation drew from EPA permitting databases, EIA natural gas flow data, FERC infrastructure filings, and state-level renewable portfolio standard filings. Bottom-up capacity assessments triangulated against top-down end-use demand modeling.
Comparable-period anchoring to historical capacity utilization and feedstock cost regimes informed the projection framework across the analysis window. Segmentation dimensions modeled include technology type, feedstock source, carbon intensity tier, end-use application, and regional regulatory cluster. CAGRs derived from slope-intercept regression against normalized capacity expansion timelines. Industry-specific forecast inputs incorporated Henry Hub price scenario bands and IRA credit rulemaking trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EPA regulatory acceleration or biomass feedstock supply disruptions. Projections reflect documented assumptions on carbon capture deployment rates and clean hydrogen certification methodology standardization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
US and Canada Helium Gas Market
Industrial Gases
High Purity Gas Market
Industrial Gases
Sulfur Recovery Tail Gas Analyzer Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market
Industrial Gases
Asia-Pacific Industrial Gases Market
Industrial Gases
Global Food-Grade Industrial Gases Market
Industrial Gases
Global Nitrogen Market
Industrial Gases
Global Argon Market
Industrial Gases
Global Industrial Gas Market
Industrial Gases
High Purity Methane Gas Market
Industrial Gases
United States Industrial Gases Market
Industrial Gases
Neon Gas Market
Industrial Gases
Gas Sampling Line Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
Global Industrial Nitrogen Generator Market