
 Asia-Pacific Medical Automation Market | 2026-2036
Asia-Pacific Medical Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Medical Automation Market Outlook
Silicon carbide power modules is decoupling medical robot motor drives from legacy silicon-based inverters, cutting thermal losses by half in surgical arm actuators. Siemens Healthcare GmbH leverages captive semiconductor sourcing to secure component supply for imaging-integrated robotics. Intuitive Surgical anchors its Asia-Pacific position through dedicated training centers in Seoul and Shanghai. GE Healthcare competes by extending its Edison AI platform into automated patient monitoring workflows across Indian hospital networks.
Asia-Pacific medical automation encompasses electromechanical systems, intelligent software architectures, and sensor networks that execute clinical tasks with minimal human intervention, typically operating at ISO 13485 quality thresholds and IEC 60601 electrical safety standards. Its primary purpose is to reduce procedural variability, compress diagnostic turnaround times, and offset clinician workforce gaps in high-acuity settings. Robotics dominates capital expenditure allocation among product categories, while Software Solutions captures disproportionate margin expansion through recurring licensing models. Laboratory Testing applications outpace Surgery in volume growth, driven by China's biobank expansion and India's national health screening mandates.
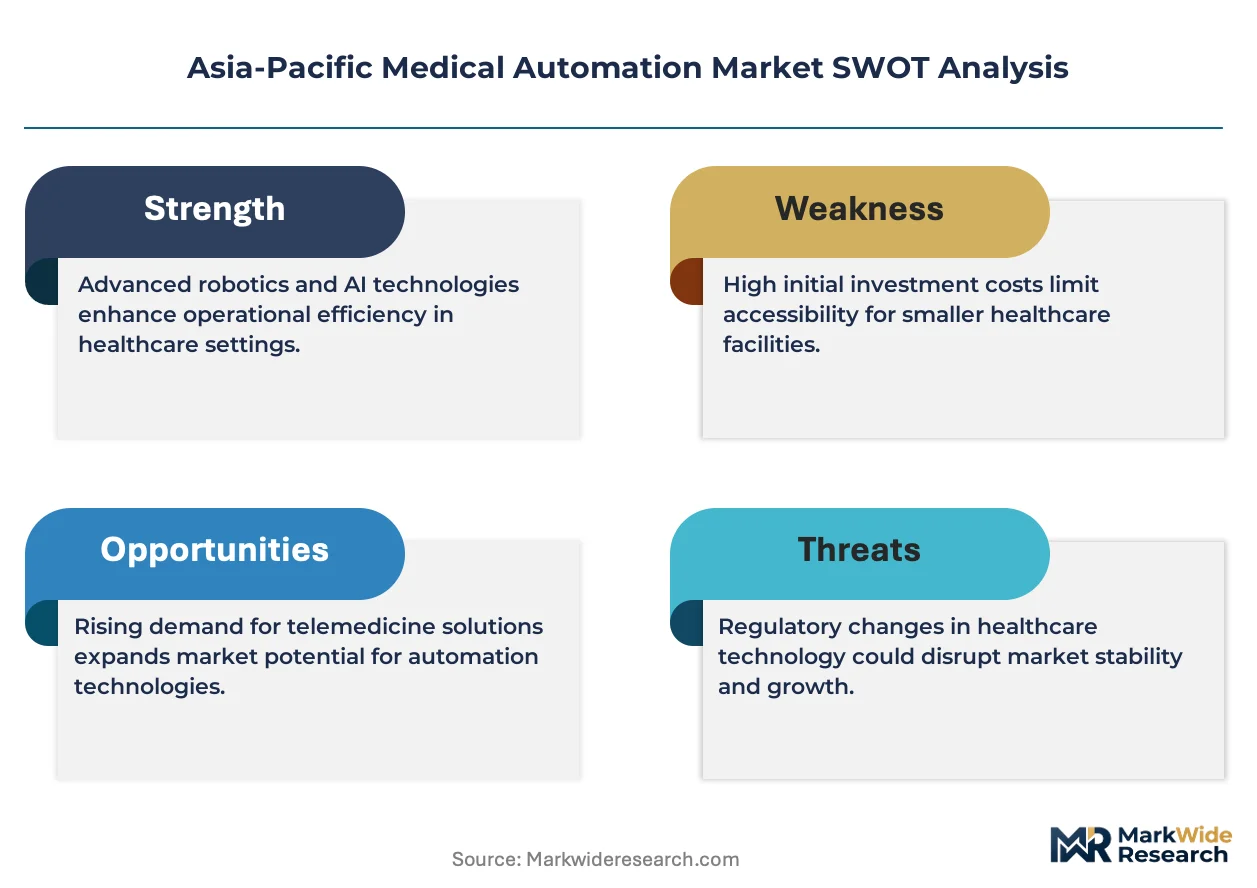
Japan's PMDA, China's NMPA, and Australia's TGA collectively enforce divergent software validation requirements that fragment go-to-market timelines for AI-enabled devices. India's CDSCO recently aligned with IMDRF cybersecurity guidance, tightening pre-market scrutiny for connected diagnostic instruments. Stakeholders must monitor regulatory harmonization negotiations between ASEAN member states, as mutual recognition agreements would reshape competitive access across the region's fastest-deploying hospital automation budgets.
Market Dynamics
China's NMPA reimbursement reform for automated laboratory workflows is redirecting hospital capital expenditure toward integrated diagnostic platforms, compressing procurement cycles for standalone devices across tier-one hospital clusters.
Growth Catalysts
- Silicon carbide power modules:These semiconductors are halving thermal losses in surgical arm actuators, enabling denser motor packaging in robotic platforms deployed across Japanese university hospitals.
- India's national health screening mandates:Mass population screening programs are automating sample processing workflows in district-level laboratories, creating sustained demand for high-throughput analyzers.
- PMDA streamlined AI diagnostic pathways:Japan's regulator accelerated software validation timelines in 2023, reducing time-to-market for machine-learning-enabled imaging tools by collapsing pre-market clinical data requirements.
Market Restraints
- Silicon carbide supply concentration:Captive production at major semiconductor foundries limits third-party access to power modules, constraining surgical robot OEMs without backward integration into wafer fabrication.
- Divergent software validation requirements:Japan's PMDA, China's NMPA, and Australia's TGA enforce non-harmonized cybersecurity and algorithm transparency standards, fragmenting regional product development roadmaps.
- Lithium-ion battery thermal constraints:Mobile medical automation platforms face runtime limitations in surgical settings where continuous power delivery cannot tolerate cell degradation-induced voltage sag.
Strategic Opportunities
- Vietnam's hospital modernization wave:Greenfield private hospital construction in Ho Chi Minh City and Hanoi is specifying robotic surgical suites as differentiation anchors against public sector competitors.
- AI-platform convergence with imaging hardware:Diagnostic software vendors are bundling algorithm licenses with modality purchases, capturing recurring revenue streams from radiology departments in Australian health networks.
- ASEAN mutual recognition negotiations:Pending harmonization agreements between member state regulators would collapse duplicate conformity assessment costs for device manufacturers seeking multi-country market access.
Industry Challenges
- ISO 13485 quality management certification:Medical device manufacturers face 12-18 month implementation timelines for quality system documentation, delaying product registration in multiple Asia-Pacific jurisdictions simultaneously.
- Legacy hospital information system integration:Automated diagnostic platforms require custom middleware development to exchange HL7-formatted patient data with decades-old electronic health record architectures prevalent in Southeast Asian public hospitals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Medical Automation Market |
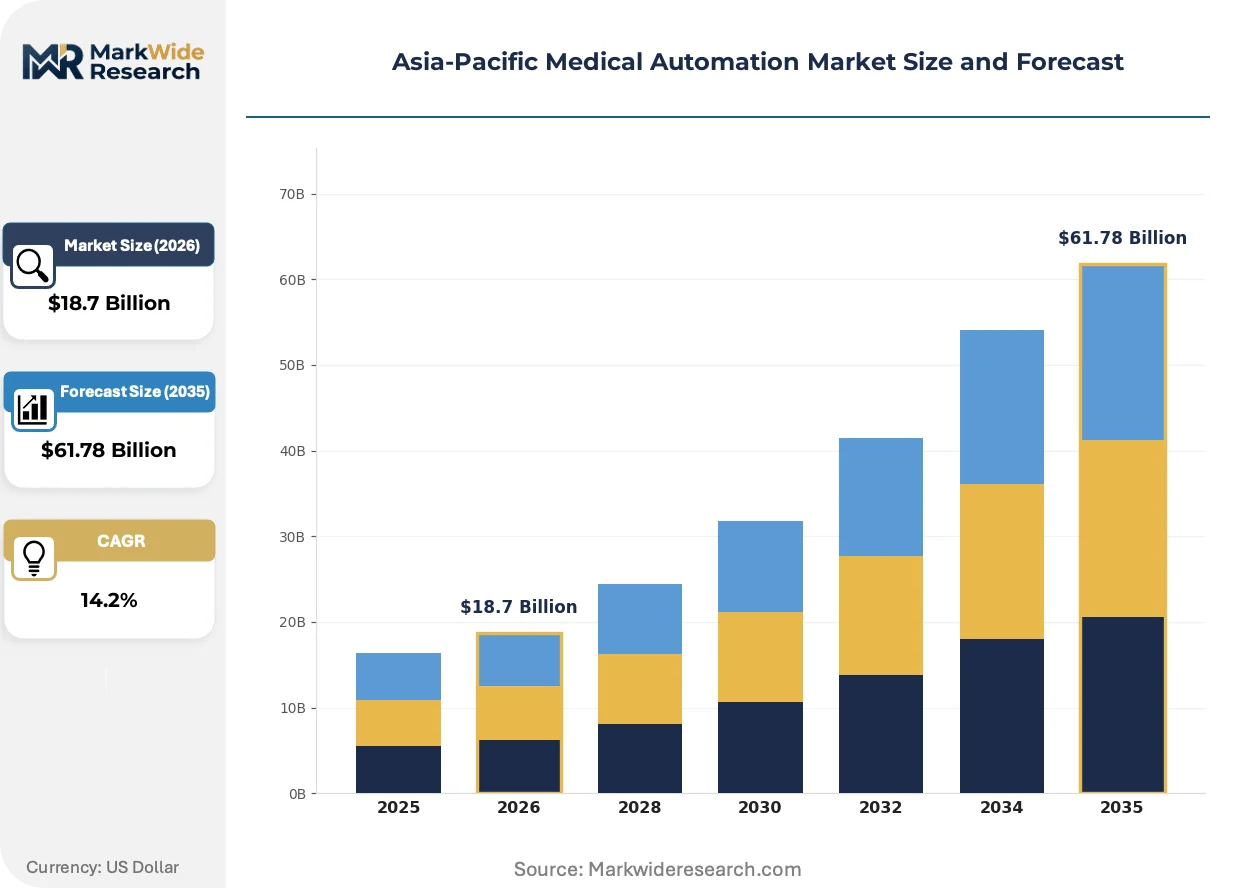
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotics, Software Solutions, Automated Diagnostic Devices, Laboratory Automation Equipment Application: Surgery, Medication Management, Patient Monitoring, Laboratory Testing End User: Hospitals, Clinics, Diagnostic Laboratories, Home Healthcare Technology: Artificial Intelligence, Machine Learning, Robotics Process Automation, Cloud Computing |
| Companies Covered | Siemens Healthcare GmbH, Koninklijke Philips N.V., GE Healthcare, Medtronic, Stryker Corporation, Intuitive Surgical, BD, Brainlab AG, Asahi Kasei Medical Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Medical Automation Market Strategic Shifts
Electrification of surgical platforms and algorithmic diagnostic tools are compressing procedural timelines while expanding the addressable procedure base for automation-enabled interventions across Asia-Pacific health systems.
Silicon carbide power electronics are expanding into motor drive architectures for robotic surgical arms, replacing silicon IGBTs in next-generation platforms. South Korean and Chinese OEMs are adopting these modules fastest, driven by thermal management requirements in compact actuator housings. This transition is expanding into multi-arm collaborative robots where power density directly determines workspace envelope and payload capacity.
China's NMPA implemented differentiated review pathways for AI-enabled diagnostic software in 2023, separating algorithm-only updates from full device re-registration. This regulatory innovation accelerates post-market algorithm iteration for imaging analysis tools. Domestic software vendors are responding by establishing continuous learning pipelines that deploy model improvements without triggering lengthy pre-market submission cycles.
Hospital procurement committees in India's tier-two cities are unbundling service contracts from capital equipment purchases, separating preventive maintenance from software upgrade subscriptions. This purchasing pattern shift pressures OEM margin structures while creating openings for third-party service aggregators. The behavior is most visible in Kerala and Tamil Nadu, where state-level hospital purchasing cooperatives standardize contract terms across multiple facilities.
Asia-Pacific Medical Automation Market Segmentation
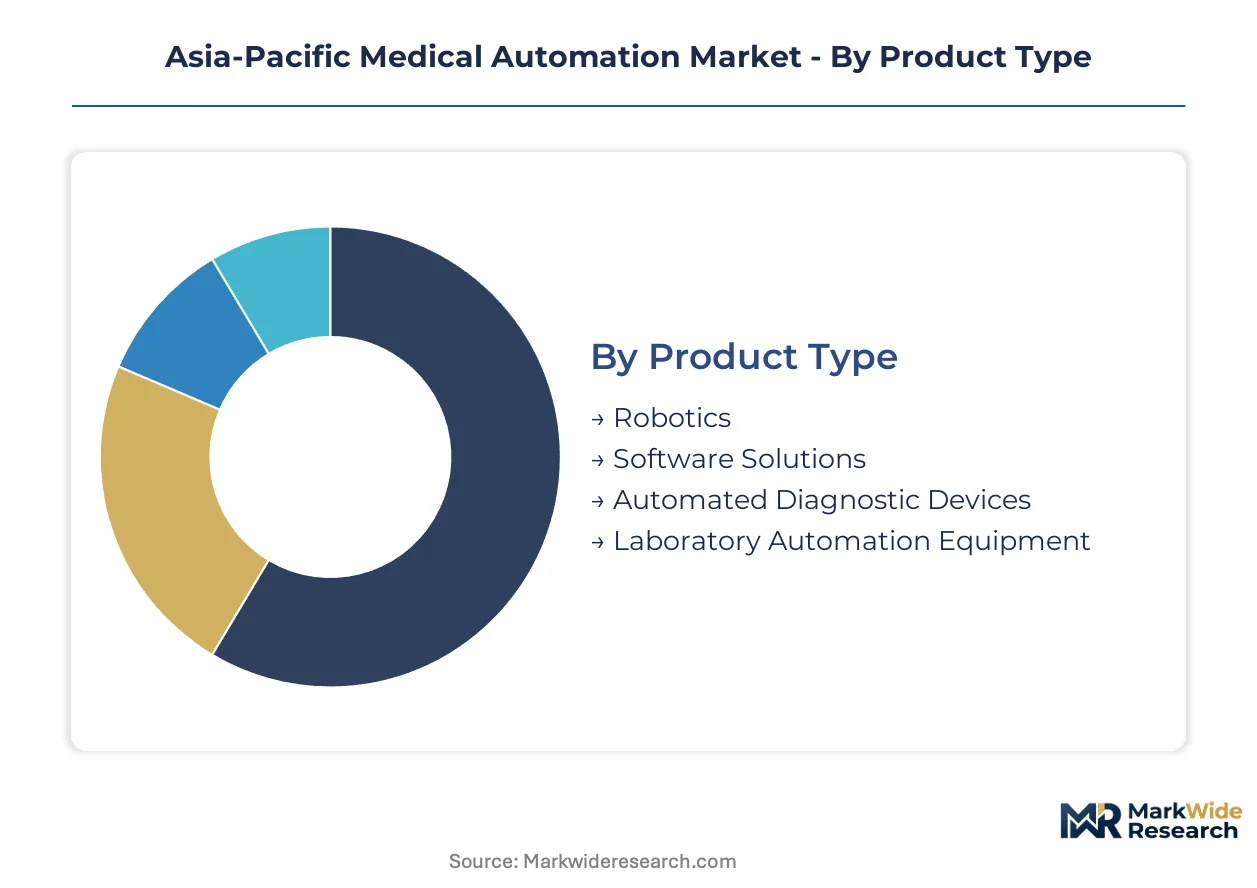
Segmentation in Asia-Pacific medical automation reveals distinct procurement patterns across capital-intensive robotics, recurring software licenses, and consumables-driven diagnostic platforms. Understanding these divisions clarifies where margin pools concentrate versus where volume expansion accelerates.
Product Type:
Customization intensity varies sharply across this category, from fully configurable surgical platforms to standardized laboratory workstations.
- Robotics:Electromechanical systems with multi-axis surgical arms and haptic feedback interfaces dominate capital expenditure in Japanese university hospitals and Korean training centers. Thermal management requirements from silicon carbide power modules are enabling denser actuator packaging in next-generation platforms.
- Software Solutions:Algorithm licensing and cloud-hosted diagnostic tools capture disproportionate margin expansion through recurring revenue models. China's NMPA differentiated review pathways accelerate post-market updates for machine-learning imaging tools without full re-registration.
- Automated Diagnostic Devices:Point-of-care analyzers with integrated sample processing reduce turnaround times in India's district-level facilities.
- Laboratory Automation Equipment:High-throughput liquid handling and specimen tracking systems serve China's biobank expansion and national screening programs.
Most installed capacity flows through Robotics. Expansion is steepest in Software Solutions.
Application:
Volume concentration shifts toward high-throughput workflows versus procedure-by-procedure automation across this dimension.
- Laboratory Testing:Automated sample processing and high-volume analyzer networks address China's biobank infrastructure buildout and India's population screening mandates. Government reimbursement reform in tier-one Chinese hospital clusters compresses procurement cycles for integrated diagnostic platforms.
- Surgery:Robotic-assisted minimally invasive procedures require capital-intensive platform deployment with dedicated training infrastructure. Greenfield private hospital construction in Vietnam specifies robotic suites as competitive differentiators against public sector facilities.
- Medication Management:Automated dispensing cabinets and barcode verification systems reduce dosing errors in high-acuity wards.
- Patient Monitoring:Continuous vital sign surveillance with AI-enabled alarm filtering extends into Australian health network expansions.
Laboratory Testing commands the highest procedure volume. Surgery delivers the steepest revenue per installation.
End User:
Procurement sophistication and budget scale create tiered adoption patterns across this category.
- Hospitals:Integrated automation platforms with enterprise imaging and surgical robotics anchor capital planning in China's tier-one clusters and Japan's university medical centers. Procurement committees increasingly unbundle service contracts from equipment purchases in India's tier-two cooperative purchasing networks.
- Diagnostic Laboratories:Centralized reference labs and biobank facilities drive high-throughput automation demand. China's national biobank expansion and India's health screening mandates concentrate volume in this segment.
- Clinics:Point-of-care diagnostic devices with simplified workflows serve outpatient settings with limited technical staffing.
- Home Healthcare:Remote patient monitoring and connected therapeutic devices extend automation beyond institutional boundaries.
Hospitals absorb the majority of capital deployment. Diagnostic Laboratories are climbing the fastest as biobank and screening infrastructure scales.
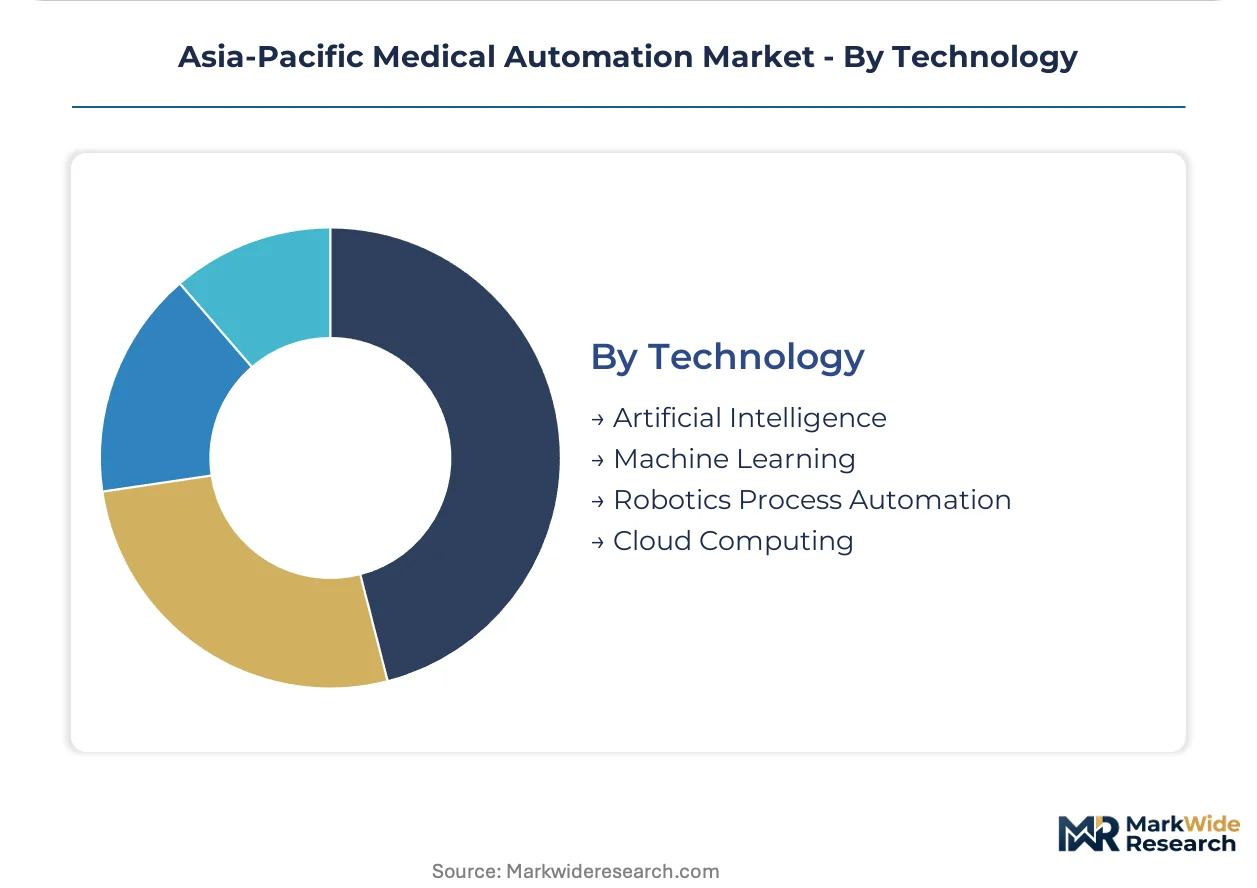
Technology:
Maturity gradients separate proven automation architectures from emerging algorithmic capabilities in this dimension.
- Artificial Intelligence:Machine-learning diagnostic algorithms with continuous learning pipelines exploit China's differentiated regulatory pathways for software-only updates. Imaging analysis tools deploy model improvements without triggering lengthy pre-market submission cycles.
- Machine Learning:Predictive analytics for patient risk stratification and resource allocation penetrate Australian health network automated monitoring workflows.
- Robotics Process Automation:Rule-based workflow orchestration handles repetitive administrative and sample handling tasks in laboratory environments.
- Cloud Computing:Scalable infrastructure for algorithm training and remote platform management supports distributed diagnostic networks.
Artificial Intelligence attracts the steepest R&D allocation. Cloud Computing is gaining share fastest as data sovereignty frameworks mature across the region.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta hospital clusters anchor regional automation procurement, where tier-one facilities integrate robotic surgical suites with AI-enabled diagnostic platforms under NMPA reimbursement reform.
China
Beijing-Tianjin-Hebei biobank infrastructure and Shanghai's medical robotics manufacturing base concentrate demand for laboratory automation and surgical platforms. NMPA differentiated review pathways for AI diagnostic software accelerate post-market algorithm updates without full re-registration. Shenzhen's device OEMs supply high-throughput analyzers to district-level hospitals under national health screening expansion.
Japan
Tokyo and Osaka university medical centers drive capital deployment in multi-arm surgical robotics with silicon carbide power electronics. PMDA streamlined AI diagnostic approval pathways in 2023, collapsing pre-market clinical data requirements for machine-learning imaging tools. Nagoya's precision manufacturing clusters produce compact actuator assemblies for next-generation robotic platforms.
India
Kerala and Tamil Nadu state-level hospital purchasing cooperatives unbundle service contracts from capital equipment procurement, reshaping OEM margin structures. CDSCO alignment with IMDRF cybersecurity guidance tightens pre-market scrutiny for connected diagnostic instruments. Maharashtra's tier-two city diagnostic laboratories automate sample processing under national population screening mandates.
South Korea
Seoul's training centers anchor Intuitive Surgical's Asia-Pacific robotics education infrastructure, feeding specialist pipelines across the region. MFDS enforces software validation requirements for AI-enabled devices that diverge from Japanese and Chinese standards. Busan-Ulsan industrial corridors manufacture precision motor components for surgical robot OEMs.
Australia
Victoria and New South Wales health networks extend GE Healthcare's Edison AI platform into automated patient monitoring workflows. TGA cybersecurity and algorithm transparency standards fragment regional product development timelines for multi-country vendors. Sydney's radiology departments bundle algorithm licenses with imaging modality purchases, capturing recurring revenue streams.
Asia-Pacific Medical Automation Market Competitive Environment
Global majors compete with regional champions across regulatory compliance and captive semiconductor supply. Siemens Healthcare GmbH and Koninklijke Philips N.V. anchor the consolidated top tier through integrated imaging-robotics portfolios, while specialized robotics pure-plays occupy mid-tier niches. Three archetypes dominate: diversified healthcare conglomerates with captive component sourcing, surgical robotics specialists with dedicated training infrastructure, and AI-platform vendors with recurring software licensing models. Competitive moves concentrate on backward integration into power electronics and strategic partnerships for regulatory harmonization across fragmented Asia-Pacific approval pathways.
Among diversified healthcare conglomerates, Siemens Healthcare GmbH exemplifies the captive supply archetype through in-house semiconductor sourcing for imaging-integrated robotics. GE Healthcare occupies a position within the AI-platform tier, extending diagnostic algorithms into automated monitoring workflows. Intuitive Surgical anchors the surgical robotics specialist category through dedicated training centers in Seoul and Shanghai that feed regional specialist pipelines. These three represent distinct competitive vectors: component security, software recurring revenue, and clinical education infrastructure.
| Leading Market Players |
|---|
| Siemens Healthcare GmbH |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Medtronic |
| Stryker Corporation |
| Intuitive Surgical |
| BD |
| Brainlab AG |
| Asahi Kasei Medical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Silicon carbide power module adoption in surgical robot motor drives is simultaneously compressing thermal management costs and concentrating procurement leverage among semiconductor foundries with captive wafer fabrication. This dual effect reshapes how OEMs negotiate component supply against the backdrop of divergent Asia-Pacific regulatory compliance costs.
Pricing Analysis
Input-cost pass-through from silicon carbide wafers and precision actuator assemblies is intensifying margin pressure on mid-tier surgical robot manufacturers lacking backward integration into semiconductor sourcing. Pricing stratifies across ISO 13485-certified premium tiers, NMPA-fast-tracked standard tiers, and economy tiers serving India's district-level laboratories. Cost compression in the economy tier reflects unbundled service contracts and third-party maintenance aggregation. Diagnostic laboratories in India's tier-two cooperative purchasing networks exhibit the highest price sensitivity, while Japanese university hospitals anchor premium tier demand through bundled training and software subscription models.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for silicon carbide power modules, and Japan for precision actuator assemblies. The supply chain draws from rare earth magnet feedstock concentrated in China's Inner Mongolia region, high-purity silicon wafers from Taiwan, and ceramic bearing components from Germany. Tariff exposure on semiconductor imports into ASEAN member states fragments regional assembly strategies. Distribution runs through hospital GPO contracts in Australia, state-level purchasing cooperatives in India, and direct OEM relationships with tier-one Chinese hospital clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific medical automation functions as a stable compounder anchored by irreversible hospital labor shortages and government-mandated screening program expansion across China and India.
For Market Incumbents: Deepen captive semiconductor sourcing through foundry partnerships or in-house wafer fabrication to secure silicon carbide supply against fabless competitors. Expand dedicated training center footprints in Seoul and Shanghai to lock in specialist referral networks before emerging robotics pure-plays replicate Intuitive Surgical's education infrastructure. Regulatory harmonization negotiations between ASEAN member states threaten to collapse conformity assessment cost advantages for early entrants. For New Entrants and Emerging Players: PMDA's streamlined AI diagnostic approval pathways in Japan open a window for algorithm-only software vendors to bypass capital-intensive hardware manufacturing. Target Vietnam's greenfield private hospital construction wave with robotic surgical suite leasing models that convert capital expenditure to operational expenditure. Partner with Australia's radiology networks on algorithm-license bundling with imaging modality purchases to establish recurring revenue traction before GE Healthcare consolidates the Edison AI platform footprint. For Investors and Strategic Acquirers: Valuations sit cheapest among laboratory automation equipment manufacturers serving China's biobank expansion, where volume scale and government reimbursement reform create predictable cash flow visibility. The five-to-ten year viability window favors AI-platform vendors with continuous learning pipeline architectures that exploit NMPA's differentiated software update pathways. Watch for ASEAN mutual recognition agreement ratification as the inflection signal that collapses duplicate conformity assessment costs and accelerates multi-country market access for consolidated players.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Foundry Partnership | Captive silicon carbide supply secures surgical robot motor drive production against fabless competitors. |
| Training Center Network Expansion | Dedicated Seoul and Shanghai facilities feed specialist pipelines across the Asia-Pacific region. |
| AI Diagnostic Software Licensing | Cloud-hosted algorithm bundles capture recurring revenue from Australian radiology department budgets. |
| Biobank Infrastructure Contracting | High-throughput analyzer deployment aligns with China's national biobank expansion mandates. |
| Regulatory Harmonization Advocacy | ASEAN mutual recognition negotiations would collapse duplicate conformity assessment costs for multi-country vendors. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and regulatory affairs leads at device OEMs with secondary validation from NMPA filing databases, PMDA approval registries, hospital procurement records, and ASEAN medical device trade statistics. Bottom-up installation tracking and top-down healthcare expenditure modeling were cross-referenced for triangulation.
Comparable-period anchoring tied projection assumptions to historical reimbursement reform implementation timelines and biobank infrastructure buildout trajectories across the analysis window. Segmentation modeling spanned product type, application, end user, and technology deployment maturity, with CAGRs derived from procedure volume elasticity to labor shortage severity and algorithm update frequency under differentiated regulatory pathways. Forecast inputs incorporated silicon carbide adoption curves in motor drive architectures and AI diagnostic software validation timeline compression under PMDA's 2023 pathway revision.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged ASEAN regulatory fragmentation or sudden lithium-ion battery thermal safety recalls. The analysis assumes continued government reimbursement reform momentum in China's tier-one hospital clusters and sustained national health screening program funding in India. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Smart Sorting Line Market
Industrial Automation
Europe Factory Automation and Industrial Controls Market
Industrial Automation
North America and Europe Retail Automation Market
Industrial Automation
Europe ICS Market
Industrial Automation
Parcel Sortation Systems Market
Industrial Automation
Factory Automation in Japan Market
Industrial Automation
North America Factory Automation and Industrial Controls Market
Industrial Automation
Sortation Systems Market
Industrial Automation
Electric Linear Actuator Market
Industrial Automation
Programmable Logic Controller Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Europe Water Automation and Instrumentation Market
Industrial Automation
Warehouse Automation Solutions Market
Industrial Automation
Smart Elevator Market
Industrial Automation
Smart Warehouse Technologies Market
Industrial Automation
Global System Integrator for Industrial Automation Market