
 Industrial Fieldbus Solution Market | 2026-2036
Industrial Fieldbus Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Fieldbus Solution Market Foresight
Modular I/O bundling with embedded fieldbus gateways is recalibrating how system integrators evaluate total cost of ownership. Schneider Electric leverages its EcoStruxure architecture to anchor hybrid deployments across process industries. Belden Inc. sustains cable and connectivity dominance through Hirschmann industrial Ethernet integration. Siemens AG competes with its Totally Integrated Automation portfolio spanning Profibus and Profinet protocols.
Industrial fieldbus solutions comprise digital communication networks linking sensors, actuators, and controllers through standardized physical layers and protocol stacks, typically operating at 31.25 kbit/s to 12 Mbit/s over twisted-pair or fiber-optic media to enable deterministic real-time data exchange in harsh environments. Wired technology retains the dominant installed base in heavy process applications where electromagnetic immunity and power-over-bus architectures remain critical, while Ethernet-based segments capture the fastest expansion as IEEE 802.3cg single-pair Ethernet displaces legacy physical layers. Factory automation applications generate the deepest margin pools due to high-volume repetitive machine control, whereas process control commands premium pricing through intrinsic safety certification requirements.
IEC 61158 and IEC 61784 standards govern protocol interoperability and device profiles, compelling vendors to maintain multi-protocol engineering tools. The EU Machinery Directive and ATEX certification frameworks constrain product design for hazardous area deployment, filtering market access to qualified suppliers. OSHA electrical safety regulations in the United States mandate arc-flash and isolation protocols that fieldbus architectures must accommodate through energized maintenance capabilities. Stakeholders must monitor the migration tension between legacy fieldbus preservation and Ethernet-APL infrastructure commitment.
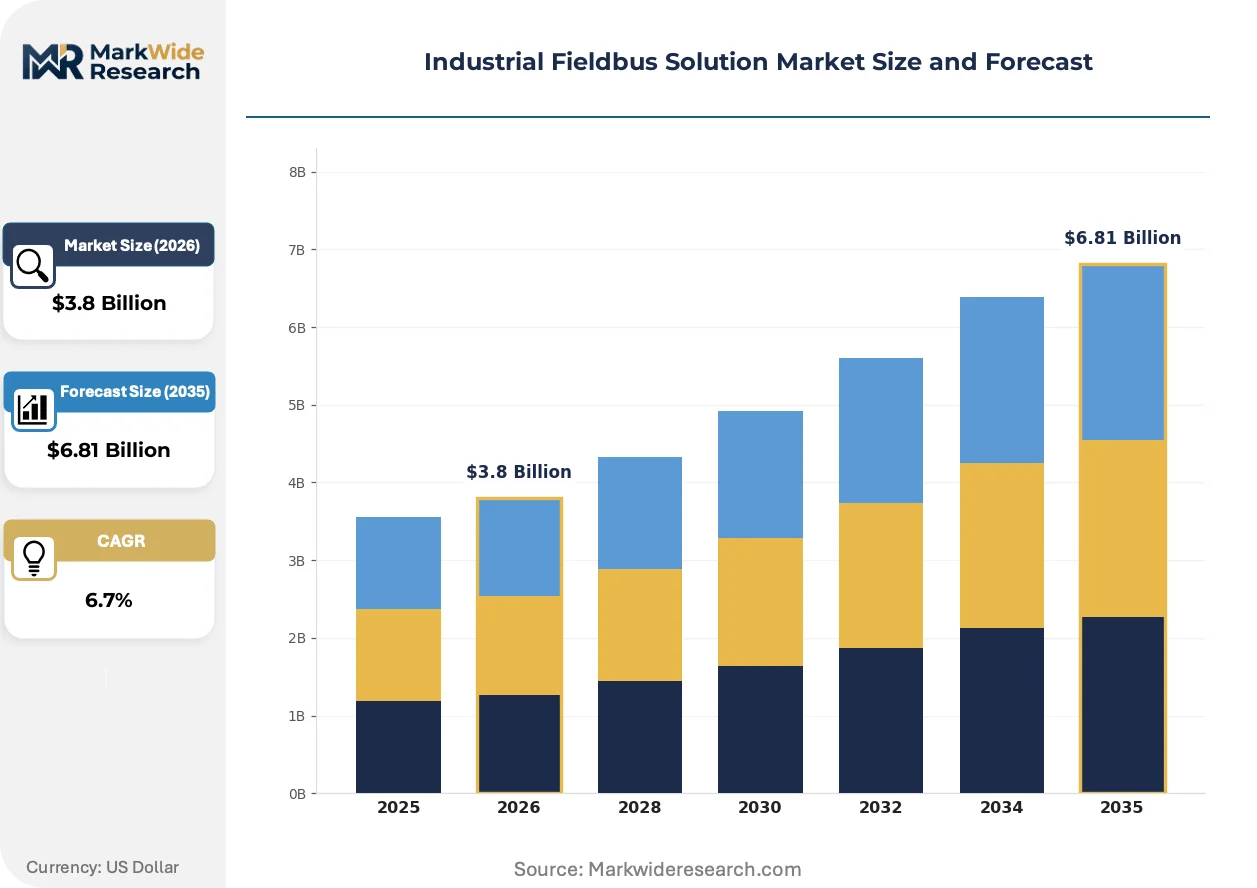
Market Dynamics
Ethernet-APL migration is fragmenting legacy fieldbus architectures as process industries confront dual-protocol engineering burdens and infrastructure replacement cycles.
Growth Catalysts
- IEC 61158 standardization:Protocol harmonization reduces engineering complexity for multi-vendor deployments in petrochemical facilities.
- Intrinsic safety certification:ATEX and IECEx frameworks mandate fieldbus architectures for hazardous area instrumentation in oil and gas extraction.
- Power-over-bus architectures:Two-wire media delivering both power and data cut cabling costs for remote sensor networks in mining operations.
Market Restraints
- Copper price volatility:Twisted-pair cable materials expose installed base economics to commodity swings.
- Legacy protocol lock-in:Profibus and Foundation Fieldbus device populations slow Ethernet-APL migration in German chemical clusters.
- Single-pair Ethernet substitution:IEEE 802.3cg threatens traditional fieldbus physical layers in new greenfield projects.
Strategic Opportunities
- India manufacturing corridors:PLI scheme incentives for industrial automation create first-mover advantage for Ethernet-APL infrastructure.
- Pharmaceutical batch processing:FDA 21 CFR Part 11 compliance requirements favor fieldbus networks with electronic batch record integration.
- Wireless-fieldbus hybridization:ISA100.11a convergence with wired backbones opens brownfield retrofit applications.
Industry Challenges
- Multi-protocol engineering talent scarcity:Profibus, Profinet, and Ethernet-APL fluency requirements strain system integrator staffing.
- Intrinsic safety recertification timelines:ATEX and IECEx approval cycles delay product launches for hazardous area variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Fieldbus Solution Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foundation Fieldbus, Profibus, DeviceNet, AS-Interface Application: Factory Automation, Process Control, Building Automation, Energy Management End User: Manufacturing, Oil & Gas, Chemical, Utilities Technology: Wired, Wireless, Hybrid, Ethernet-Based |
| Companies Covered | Schneider Electric, Belden Inc., Siemens AG, Phoenix Contact GmbH, Moxa Inc., Rockwell Automation, Inc., OMRON Corporation, Emerson Electric Co., ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Fieldbus Solution Market Shifts & Advancements
Physical layer unification around single-pair Ethernet is compressing the traditional fieldbus-Ethernet boundary, while regulatory mandates accelerate digital instrumentation mandates across hazardous industries.
Single-pair Ethernet is decentralizing sensor network architectures by collapsing separate power and data infrastructures into unified two-wire topologies. Offshore platform operators in the North Sea are piloting these configurations for subsea instrumentation. The technology is decentralizing control system hierarchies by enabling direct cloud connectivity from field devices without intermediary gateways.
REACH substance restrictions on halogenated flame retardants are forcing cable compound reformulation for European process industries. Manufacturers must requalify sheath materials under updated CPR construction product regulations. German automotive paint shops and Belgian chemical plants face the tightest compliance windows for legacy cable replacement.
Lifecycle service unbundling is fragmenting traditional system integrator relationships as end-users separate hardware procurement from commissioning contracts. EPC firms now compete directly with automation vendors for brownfield migration projects. This pattern concentrates in US Gulf Coast petrochemical expansions where owner-operators demand fixed-price retrofit guarantees.
Industrial Fieldbus Solution Market Segmentation
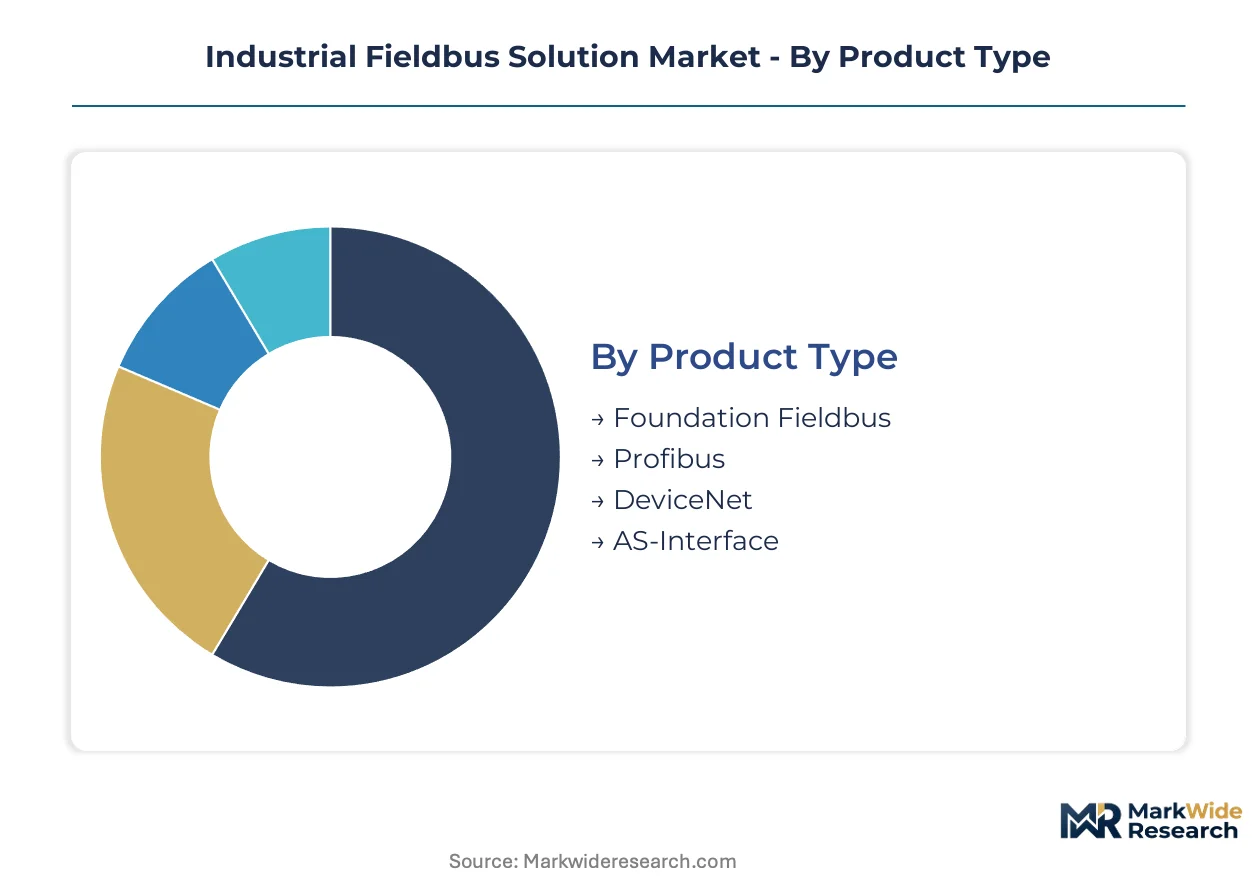
Industrial fieldbus architectures fragment across protocol generations, physical layers, and safety certification tiers. Procurement decisions hinge on legacy infrastructure compatibility, hazardous area requirements, and migration pathways toward Ethernet-APL unification.
Product Type:
Protocol selection determines engineering tool investment, device ecosystem access, and migration trajectory for brownfield facilities.
- Foundation Fieldbus:H1 protocol stack designed for process control with intrinsic safety support through FISCO and FNICO power models. Oil and gas refineries along the US Gulf Coast specify this for tank farm instrumentation where ATEX Zone 1 certification is mandatory.
- Profibus:DP and PA variants dominate discrete manufacturing and process applications respectively, with Siemens ecosystem integration creating vendor lock-in effects. German chemical clusters around Ludwigshafen sustain the deepest installed base, though Ethernet-APL migration is fragmenting new project specifications.
- DeviceNet:CAN-based protocol optimized for factory floor device-level networking with explicit messaging for configuration.
- AS-Interface:Two-wire actuator-sensor bus for binary I/O consolidation at the lowest network tier.
Profibus leads on scale; Ethernet-APL migration is gaining share fastest among greenfield specifications.
Application:
Margin structures diverge sharply between repetitive discrete control and continuous process environments with safety instrumented systems.
- Process Control:Continuous manufacturing environments demand deterministic communication with SIL-rated safety loops and intrinsic safety barriers. Offshore platforms in the North Sea and Middle Eastern petrochemical complexes command premium pricing for subsea and hazardous area variants.
- Factory Automation:High-volume machine control with millisecond cycle times and modular I/O architectures. Automotive assembly plants in Stuttgart and Detroit generate the deepest volume pools through standardized robot cell replication.
- Building Automation:BACnet and Modbus integration points for HVAC and lighting control through fieldbus gateways.
- Energy Management:Substation automation and distributed generation monitoring with IEC 61850 convergence requirements.
Factory Automation dominates volume throughput; Process Control commands the steepest expansion trajectory through safety regulation tightening.
End User:
Capital expenditure cycles and regulatory exposure shape procurement timing across verticals with divergent risk profiles.
- Oil & Gas:Upstream extraction and downstream refining operations with Zone 0/1 hazardous area density. North Sea operators and Middle Eastern national oil companies drive subsea Ethernet-APL pilot deployments.
- Chemical:Batch and continuous processing with FDA 21 CFR Part 11 traceability requirements in pharmaceutical intermediates. Belgian and German chlor-alkali producers face REACH compliance pressure on legacy cable replacement.
- Manufacturing:Discrete production with high-volume I/O counts and short replacement cycles.
- Utilities:Power generation and water treatment with SCADA integration and cybersecurity hardening mandates.
Oil & Gas concentrates the highest per-node spending; Chemical is climbing the fastest through batch processing digitization.
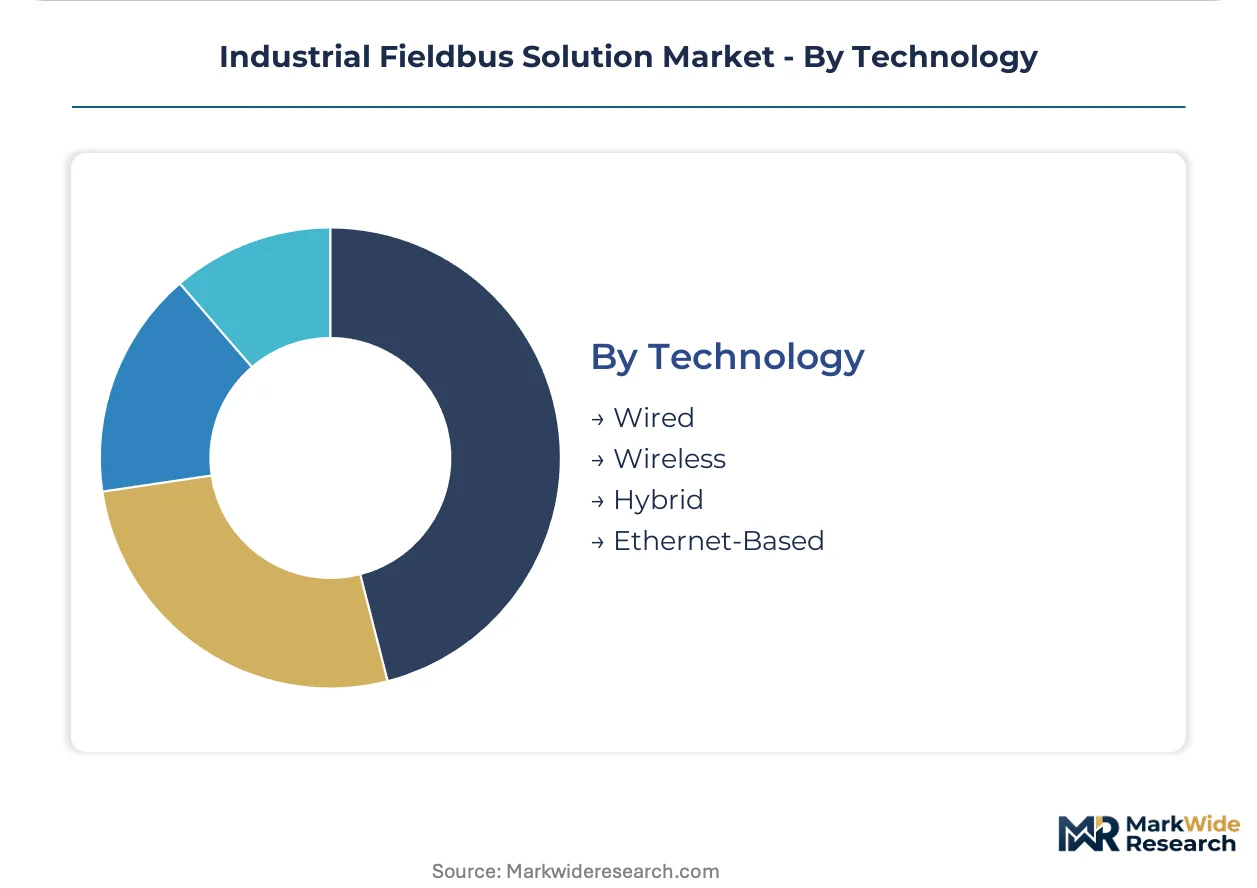
Technology:
Physical layer architecture determines power delivery, cable topology, and gateway complexity for edge-to-cloud pathways.
- Ethernet-Based:IEEE 802.3cg single-pair Ethernet with 10 Mbit/s over 1000m on two-wire media, collapsing separate power and data infrastructures. Greenfield pharmaceutical facilities in India and Ireland specify this for direct cloud connectivity without protocol translation layers.
- Wired:Twisted-pair and fiber-optic deterministic networks with electromagnetic immunity for heavy process environments. Legacy Profibus and Foundation Fieldbus installations in German chemical clusters sustain replacement part demand despite migration pressure.
- Wireless:ISA100.11a and WirelessHART for rotating equipment and remote asset monitoring.
- Hybrid:Wired backbones with wireless field device integration for brownfield retrofit scenarios.
Wired retains the largest installed base; Ethernet-Based is expanding most quickly through physical layer unification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical conglomerates pioneered fieldbus standardization through Profibus in the 1980s, establishing Ludwigshafen and Stuttgart as the industry's foundational engineering clusters. This heritage anchors European protocol dominance while Ethernet-APL migration now reshapes investment patterns across industrial corridors worldwide.
United States
Gulf Coast petrochemical expansions drive Foundation Fieldbus deployments for tank farm instrumentation with Zone 1 hazardous area density. OSHA electrical safety regulations mandate arc-flash protocols that fieldbus architectures accommodate through energized maintenance capabilities. Houston and Beaumont anchor the deepest installed base for process control applications.
Germany
Chemical clusters around Ludwigshafen and Cologne sustain the world's largest Profibus and Profinet device populations despite Ethernet-APL migration pressure. REACH substance restrictions force cable compound reformulation under updated CPR construction product regulations. Stuttgart automotive plants generate high-volume factory automation demand through standardized robot cell replication.
China
MIIT industrial internet initiatives accelerate Ethernet-APL adoption in greenfield pharmaceutical facilities across Yangtze River Delta zones. GB standards compliance requirements shape domestic protocol preferences for state-owned refinery upgrades. Shanghai and Ningbo chemical parks pilot single-pair Ethernet for direct cloud connectivity without gateway layers.
India
PLI scheme incentives for industrial automation create first-mover positioning for Ethernet-APL infrastructure in Gujarat and Maharashtra manufacturing corridors. CEA electrical safety frameworks govern hazardous area instrumentation approvals for oil and gas extraction. Dahej and Hazira petrochemical complexes drive batch processing digitization with FDA 21 CFR Part 11 traceability requirements.
United Kingdom
North Sea offshore platform operators pilot subsea Ethernet-APL configurations for subsea instrumentation in Aberdeen energy corridors. HSE offshore safety regulations mandate SIL-rated safety loops for hazardous area deployment. Grangemouth and Teesside refineries concentrate brownfield migration demand as owner-operators separate hardware procurement from commissioning contracts.
Industrial Fieldbus Solution Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tiers and hazardous area specialization depth. The vendor base stratifies into three tiers: diversified automation conglomerates with protocol-agnostic portfolios, cable and connectivity specialists with electromagnetic immunity expertise, and regional system integrators with local commissioning relationships. Two dominant competitive moves reshape positioning: M&A activity targeting Ethernet-APL engineering talent pools, and strategic partnerships between automation vendors and EPC firms for fixed-price retrofit guarantees.
Among diversified automation conglomerates, Schneider Electric, Siemens AG, and ABB Ltd. occupy positions spanning multiple protocol generations and safety certification tiers. These entities exemplify the premium-tier archetype through their ability to anchor hybrid deployments across process industries. Belden Inc. and Rockwell Automation, Inc. represent connectivity-focused specialists with concentrated exposure to industrial Ethernet migration cycles. The competitive terrain rewards vendors maintaining multi-protocol engineering tools while building Ethernet-APL fluency ahead of infrastructure replacement waves.
| Leading Market Players |
|---|
| Schneider Electric |
| Belden Inc. |
| Siemens AG |
| Phoenix Contact GmbH |
| Moxa Inc. |
| Rockwell Automation, Inc. |
| OMRON Corporation |
| Emerson Electric Co. |
| ABB Ltd. |
| Others |
Supply & Pricing Matrix
Premium-mid-economy pricing differentiation across ATEX-certified hazardous area variants and standard factory automation tiers shapes both margin structures and procurement patterns. German chemical clusters absorb the steepest premiums for intrinsic safety compliance, while volume buyers in Indian manufacturing corridors exploit PLI scheme leverage to compress gateway pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the industrial fieldbus solution market. ATEX and IECEx certification tiers command substantial premiums over uncertified equivalents, with copper commodity exposure and engineering tool licensing fees driving further differentiation. Cost compression in standard-tier gateways is intensifying because single-pair Ethernet substitution collapses separate power infrastructure requirements. System integrators in process industries exhibit the lowest price sensitivity due to safety instrumented system mandates, whereas discrete manufacturing buyers in high-volume automotive applications drive the hardest volume negotiations.
Supply Chain Analysis
Copper conductor supply rests on Chilean mining output and Chinese smelter capacity, with specialty fluoropolymer insulation compounds drawing from Japanese and German chemical producers. Twisted-pair cable assemblies, industrial Ethernet switches, and intrinsic safety barriers constitute the critical component triad. Single-source vulnerability concentrates in halogen-free flame retardant formulations facing REACH substance restrictions. Distribution runs through authorized system integrator channels in European process industries, while direct OEM relationships dominate Asian factory automation procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
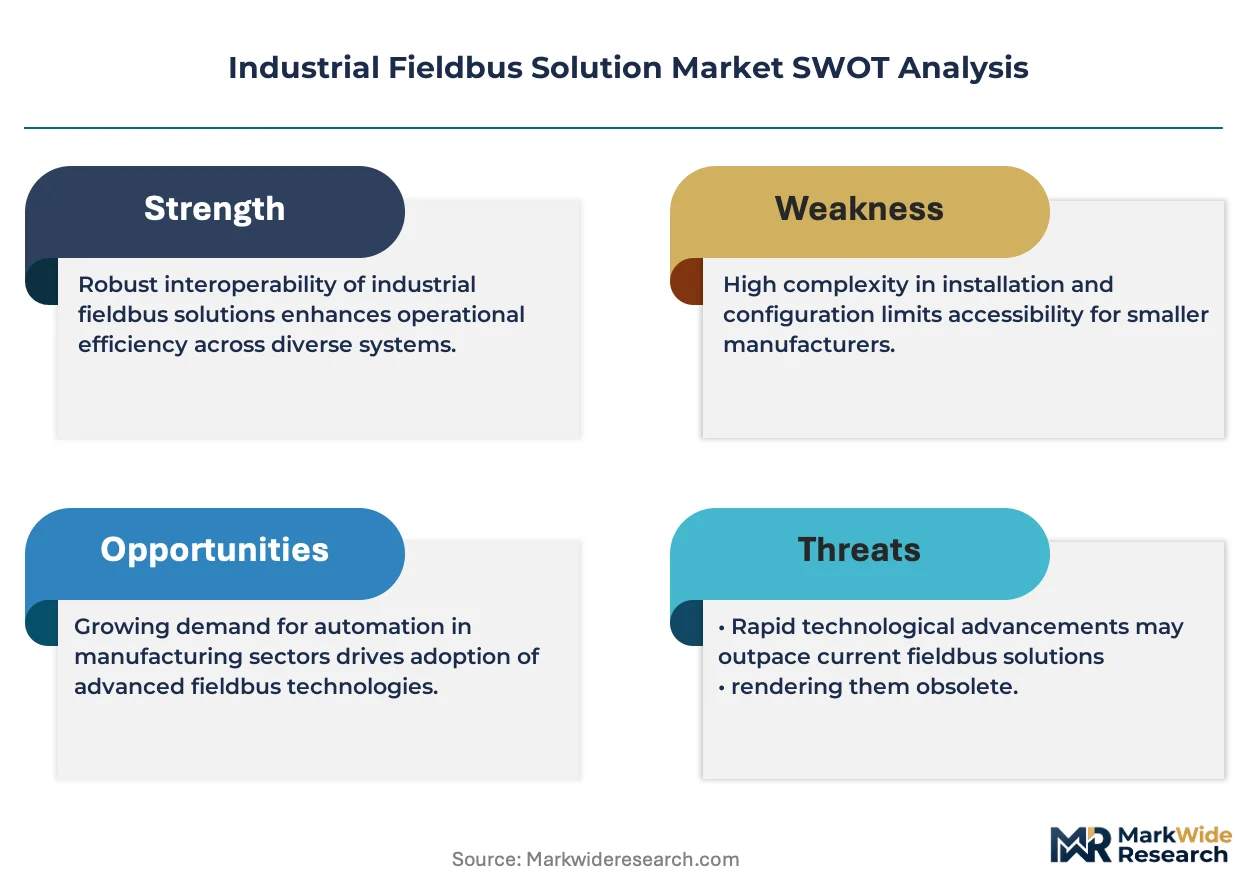
Analyst Recommendations
Ethernet-APL infrastructure commitment unlocks margin expansion as physical layer unification eliminates gateway translation costs and collapses separate power distribution spend.
For Market Incumbents: Cement multi-protocol engineering tool dominance through Profibus-Profinet-Ethernet-APL unified configuration environments. Acquire single-pair Ethernet physical layer specialists ahead of greenfield specification shifts. Prioritize ATEX recertification pipeline acceleration to defend hazardous area premium positioning against emerging connectivity vendors.
For New Entrants and Emerging Players: Capture pharmaceutical batch processing digitization in Indian PLI corridors where FDA 21 CFR Part 11 compliance creates specification entry points. Target wireless-fieldbus hybridization for North Sea brownfield retrofit applications where incumbent cabling replacement costs deter traditional suppliers. Lead with cloud-native edge device management as the go-to-market wedge against legacy gateway architectures.
For Investors and Strategic Acquirers: Consolidation pressure builds where Ethernet-APL engineering talent scarcity fragments system integrator capabilities. Frame five-to-ten year viability around protocol-agnostic platform plays rather than single-protocol pure-plays. Target cable and connectivity specialists with electromagnetic immunity IP as acquisition archetypes. Watch IEEE 802.3cg adoption velocity in German automotive paint shops as the signal for physical layer substitution inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Ethernet-APL Infrastructure Deployment | Collapses separate power and data infrastructures for offshore platform operators in the North Sea. |
| Backward Integration into Cable Compounds | Captures REACH-compliant halogen-free formulation capabilities ahead of German chemical plant replacement cycles. |
| Multi-Protocol Engineering Tool Unification | Reduces system integrator staffing burden across Profibus, Profinet, and Ethernet-APL skill requirements. |
| Wireless-Fieldbus Hybrid Development | Opens ISA100.11a convergence opportunities for rotating equipment monitoring in US Gulf Coast refineries. |
| Intrinsic Safety Recertification Acceleration | Compresses ATEX and IECEx approval timelines for hazardous area variants in Middle Eastern petrochemical complexes. |
Research Methodology
Direct dialogue with automation vendor product managers, system integrator engineering directors, petrochemical plant maintenance heads, and EPC firm procurement leads grounded the qualitative foundation. Secondary validation drew from IEC 61158 and IEC 61784 standards documentation, SEC 10-K filings of listed automation conglomerates, customs trade data for industrial Ethernet switch imports, and OSHA electrical safety regulatory updates. Bottom-up device shipment modeling and top-down infrastructure investment flow analysis were triangulated against end-user procurement pattern surveys.
Segment-level value outputs were generated across protocol type, physical layer architecture, safety certification tier, application environment, and regional industrial cluster dimensions. CAGRs were derived from installed base replacement cycle analysis and greenfield specification trend weighting. Forecast inputs incorporated copper price trajectory assumptions, Ethernet-APL standardization velocity, and hazardous area regulatory tightening schedules.
Copper commodity volatility, single-pair Ethernet substitution pace, and REACH substance restriction enforcement intensity are the dominant revision risks. Forecasts embed assumptions regarding infrastructure replacement timing and protocol migration willingness. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Europe Smart Manufacturing Market
Industrial Automation
Linear Motion System Market
Industrial Automation
UV Curing System Market
Industrial Automation
India Industrial Automation Market
Industrial Automation
Asia Pacific Industrial Communication Market
Industrial Automation
Middle East Programmable Logic Controller (PLC) Market
Industrial Automation
Smart Elevator Market
Industrial Automation
Europe Process Automation Market
Industrial Automation
Monitor Arm Market
Industrial Automation
Assembly Automation Systems Market
Industrial Automation
Global Smart Manufacturing Platform Market
Industrial Automation
Connected Worker Market
Industrial Automation
North America Factory Automation and Industrial Controls Market
Industrial Automation
Industrial Automation Products Market
Industrial Automation
Digital Industrial Scales Market
Industrial Automation
Asia Pacific Warehouse Automation Market