
 Cross-Belt Sorters Market | 2026-2036
Cross-Belt Sorters Market Size, Share, and Industry Trends Forecast 2026-2036
Cross-Belt Sorters Market Analysis
Buyer consolidation among third-party logistics providers is repositioning procurement power toward operators running multi-site fulfillment networks. Vanderlande leverages its European installed base to sustain service revenue streams across aging brownfield sites. Siemens anchors its position through control-system integration that spans sortation hardware and warehouse software layers. Daifuku competes on manufacturing scale in Asia-Pacific assembly plants serving regional integrators.
Cross-belt sorters are continuous-loop conveyor systems employing transverse-mounted belt conveyors on carrier trays, typically achieving throughput rates exceeding 10,000 items per hour with divert precision of ±2 millimeters; their primary purpose is high-speed parcel singulation and destination-coded distribution in automated material handling environments. High-speed product variants capture premium pricing due to throughput thresholds demanded by peak-season e-commerce volumes, while modular configurations attract greenfield fulfillment centers seeking phased capacity expansion without line shutdowns. Fixed installations dominate existing warehouse retrofits where structural steel and pit foundations are already embedded, though mobile deployment models are gaining traction among seasonal operators needing temporary surge capacity.
The EU Machinery Directive and CE marking framework mandate safety-rated control architectures and emergency-stop conformity for sorter installations across member states, while OSHA lockout/tagout standards in the United States shape maintenance access design and guarding specifications. ISO 3691-1 for industrial truck safety and ISO 10218 for robot integration create additional compliance layers for sorters operating alongside autonomous mobile robots in unified workflows. Stakeholders must monitor evolving interoperability standards between sortation equipment and warehouse execution systems as facility automation deepens.
Market Dynamics
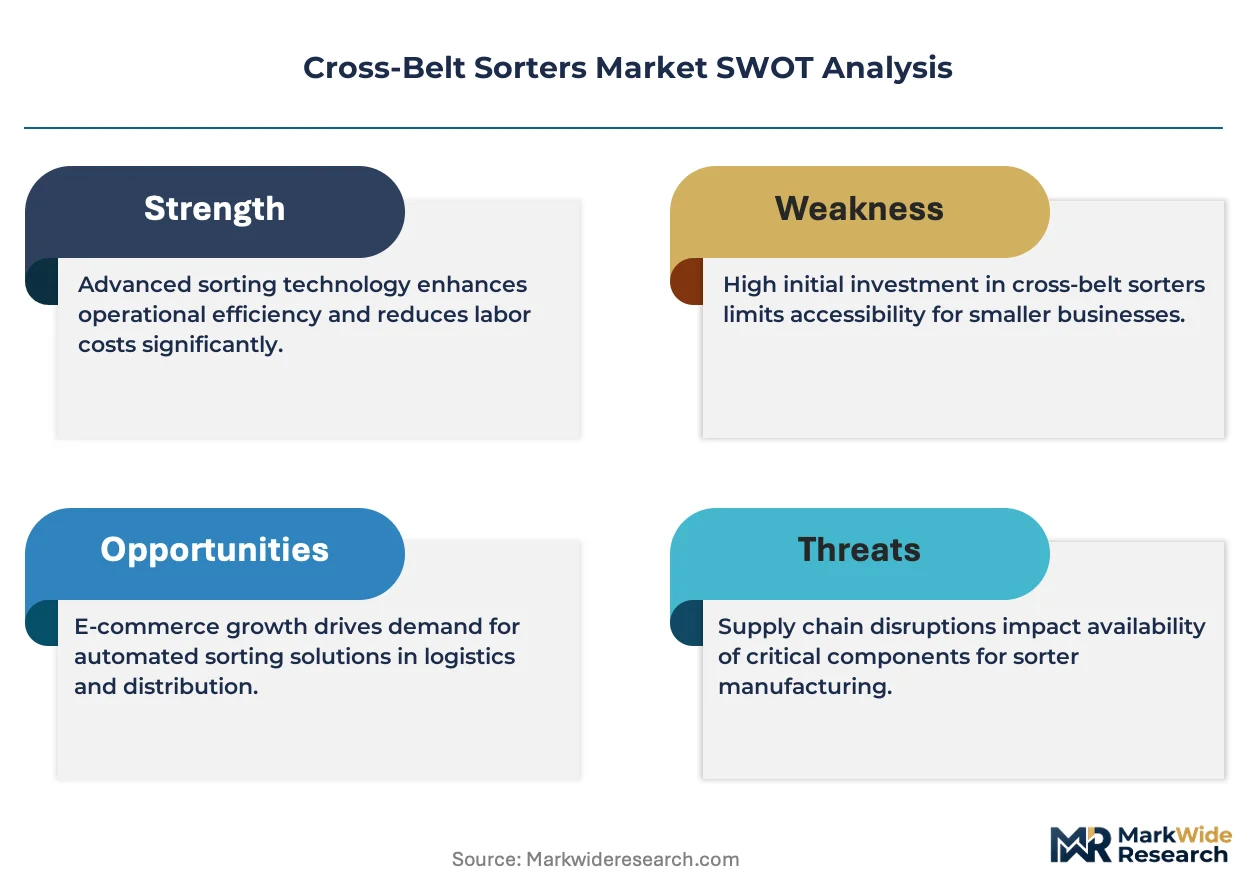
E-commerce parcel volume surges are compressing fulfillment cycle times, forcing warehouse operators to replace legacy tilt-tray installations with cross-belt architectures capable of sub-second divert precision at throughput thresholds exceeding 10,000 items per hour.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for safety-rated control architectures are accelerating replacement cycles among European third-party logistics operators running brownfield facilities.
- Pharmaceutical cold-chain expansion:Temperature-validated cross-belt modules are capturing new installations in vaccine distribution hubs requiring precise handling integrity.
- Seasonal surge capacity models:Mobile deployment configurations are attracting parcel carriers seeking temporary sortation infrastructure without permanent civil works.
Market Restraints
- Steel and aluminum input volatility:Carrier tray fabrication depends on structural metals subject to commodity price swings that compress OEM margin predictability.
- Control system supplier concentration:Safety PLC and servo drive sourcing clusters in German and Japanese industrial automation corridors create single-source exposure.
- AMR substitution pressure:Autonomous mobile robot fleets with onboard singulation are displacing fixed-loop sorters in micro-fulfillment footprints below 50,000 square feet.
Strategic Opportunities
- India warehouse automation lag:Organized retail and e-commerce penetration remains below comparable Asian economies, creating first-mover positioning for modular cross-belt entrants.
- Battery cell logistics:Lithium-ion format diversity and thermal runaway protocols are opening specialized handling requirements unmet by conventional tilt-tray designs.
- CE marking convergence with ISO 3691-1:Unified safety certification pathways are reducing compliance duplication costs for OEMs serving European AMR-integrated installations.
Industry Challenges
- Mechatronics talent scarcity:Cross-belt commissioning requires rare combinations of belt mechanics, servo tuning, and warehouse control software integration that outpace vocational pipeline output.
- Brownfield foundation retrofit complexity:Existing pit depths and structural steel grids rarely match cross-belt carrier pitch specifications, forcing costly civil modifications or custom tray geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cross-Belt Sorters Market |
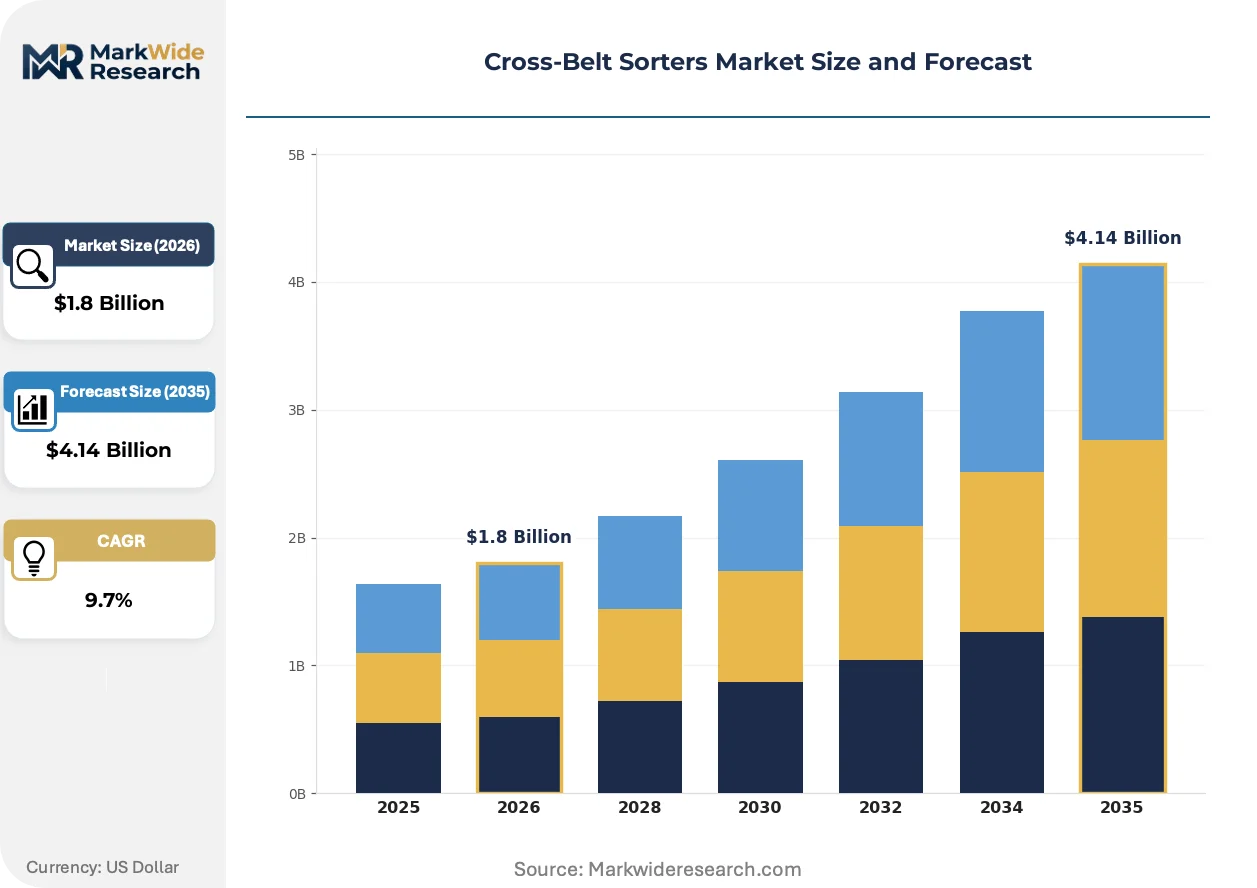
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Modular, Compact, High-Speed Application: Retail, Warehousing, E-Commerce, Manufacturing Installation: Fixed, Mobile, Integrated, Standalone End User: Logistics Providers, Fulfillment Centers, Distribution Hubs, Third-Party Warehouses |
| Companies Covered | Vanderlande, Siemens, BEUMER Group, Interroll Holding, Fives Intralogistics, Dematic, Honeywell Intelligrated, Muratec Machinery, Daifuku, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cross-Belt Sorters Market Emerging Trajectories
Digital twin integration and predictive maintenance architectures are compressing mean-time-to-repair metrics while enabling remote commissioning of multi-site fulfillment networks without travel-dependent deployment teams.
Linear synchronous motor drive technology is electrifying carrier propulsion by eliminating mechanical contact wear, reducing acoustic emissions, and enabling variable-speed zone control. Pharmaceutical distributors and luxury goods fulfillment operators are adopting these configurations for contamination-sensitive environments. The shift is electrifying competitive positioning among European OEMs with captive linear motor R&D programs.
OSHA lockout/tagout standard revisions are tightening maintenance access guarding specifications for sorter installations across US distribution centers. The updated rules mandate redundant energy isolation points and trapped-key interlock architectures that extend commissioning timelines. Parcel carriers with dense US footprints are front-loading compliance engineering to avoid operational shutdowns during enforcement windows.
Buyer consolidation among multi-site third-party logistics networks is compressing vendor rosters and unbundling after-sales service contracts from hardware procurement. Tier-one operators are demanding outcome-based uptime guarantees with penalty clauses, displacing traditional time-and-materials maintenance agreements. This restructuring is most visible in German logistics corridors where Vanderlande and Siemens maintain dense installed bases vulnerable to service contract renegotiation.
Cross-Belt Sorters Market Segmentation
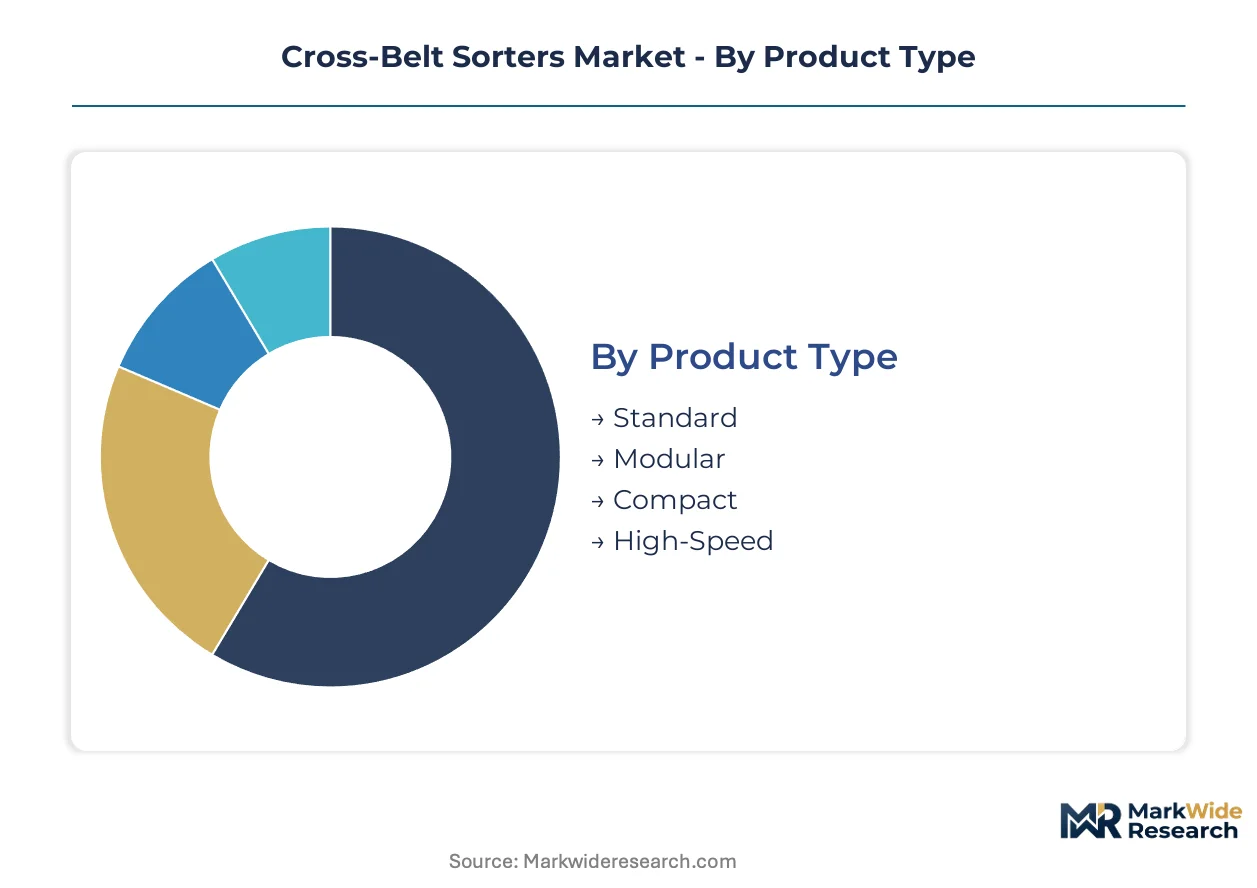
Cross-belt sorter procurement varies sharply by operational scale and infrastructure maturity. Buyers with embedded brownfield assets prioritize retrofit compatibility over raw throughput, while greenfield operators optimize for phased expansion pathways. Understanding these divergent selection criteria illuminates why product and installation categories fragment across customer types.
Product Type:
Cost tier separates buyers most decisively, with capital availability and peak-volume exposure driving specification divergence.
- High-Speed:Linear synchronous motor propulsion eliminates mechanical wear and enables sub-second divert precision at throughput thresholds exceeding 10,000 items per hour. Parcel carriers with dense e-commerce exposure in Germany and the Netherlands specify these configurations to absorb peak-season volume compression without line saturation.
- Modular:Carrier tray segments bolt together without pit excavation, allowing phased capacity expansion during live operations. Greenfield fulfillment centers in India favor this architecture to defer capital commitment until volume justifies full loop completion.
- Standard:Conventional belt-and-pulley mechanics serve mid-scale distribution hubs with predictable daily volume bands below 6,000 items per hour.
- Compact:Reduced carrier pitch and minimized loop radius fit micro-fulfillment footprints below 15,000 square feet where ceiling height restricts vertical clearance.
High-Speed leads volumes today; Modular is gaining share fastest.
Application:
Volume seasonality and SKU diversity reshape sorter specification across end-use environments.
- E-Commerce:Surge-capacity requirements and polybag handling complexity demand divert precision within ±2 millimeters to prevent misreads at barcode tunnels. Fulfillment networks serving fashion and consumer electronics verticals in the United States concentrate procurement here.
- Warehousing:Batch consolidation workflows and pallet-to-piece deaggregation prioritize gentle handling over raw speed, with pharmaceutical cold-chain operators specifying temperature-validated carrier tray materials.
- Retail:Store replenishment cycles with predictable daily rhythms favor standard-speed configurations optimized for carton stability rather than peak throughput.
- Manufacturing:Work-in-progress sequencing and kitting operations require custom tray geometries for irregular component shapes outside parcel norms.
E-Commerce dominates current procurement; Warehousing applications are climbing the fastest.
Installation:
Foundation permanence and relocation frequency separate buyers with seasonal demand spikes from operators with fixed capacity requirements.
- Fixed:Embedded pit foundations and structural steel anchoring maximize stability for 24/7 operations at major distribution hubs. German logistics corridors favor this architecture where land tenure is secure and volume growth is linear.
- Mobile:Skid-mounted frames with plug-and-play power distribution enable temporary deployment for 90-120 day surge windows. Seasonal parcel carriers in the United States lease these configurations to avoid civil works during peak shipping periods.
- Integrated:Tight coupling with upstream induction and downstream dispatch systems requires unified control architecture spanning multiple OEM subsystems.
- Standalone:Self-contained loop operations with independent PLC control suit pilot installations and technology validation programs before network-wide rollout.
Fixed installations command the largest installed base; Mobile deployment is expanding most quickly.
End User:
Consolidation scale and multi-site coordination burden differentiate procurement sophistication across operator categories.
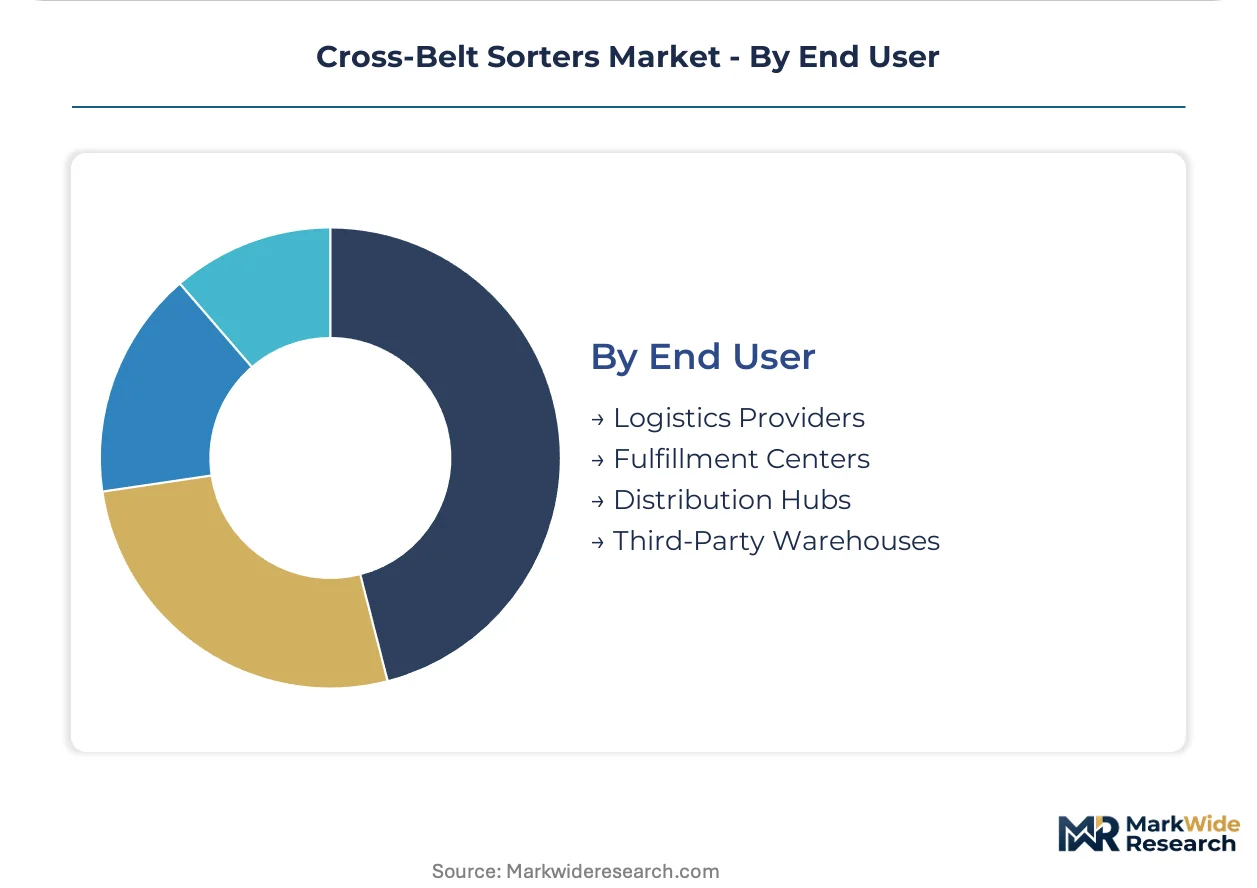
- Logistics Providers:Multi-tenant operations handling heterogeneous client profiles require rapid reconfiguration capability between parcel, carton, and polybag mixes. Third-party networks with German and Benelux footprints concentrate demand here.
- Fulfillment Centers:Single-tenant, high-velocity environments optimize for throughput density per square meter with minimal changeover requirements.
- Distribution Hubs:Regional consolidation points with mixed inbound and outbound flows prioritize gentle handling to minimize damage liability on customer-facing shipments.
- Third-Party Warehouses:Contract operators serving seasonal retail patterns favor modular or mobile configurations to match capacity commitments to client contract durations.
Logistics Providers lead current procurement; Fulfillment Centers are seeing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automation engineering talent clusters in German industrial corridors anchor European demand density, while Asian manufacturing scale and North American e-commerce velocity create divergent procurement patterns across major economies.
Germany
Third-party logistics operators running multi-site fulfillment networks drive replacement of aging tilt-tray systems with cross-belt architectures capable of CE-marked safety compliance. The EU Machinery Directive mandates safety-rated control architectures and emergency-stop conformity for all new installations. The Rhine-Ruhr logistics corridor concentrates procurement activity where Vanderlande and Siemens maintain dense service footprints across brownfield facilities.
United States
Parcel carriers with peak-season volume surges specify mobile deployment configurations to avoid permanent civil works during temporary capacity windows. OSHA lockout/tagout standard revisions mandate redundant energy isolation points and trapped-key interlock architectures that extend commissioning timelines. The Chicago-Indianapolis-Detroit distribution triangle sees concentrated leasing activity for skid-mounted surge capacity during holiday shipping periods.
China
E-commerce fulfillment networks expand automated sortation to compress delivery windows in tier-one and tier-two cities. GB standards for industrial machinery safety and MIIT automation promotion policies shape local procurement specifications. The Yangtze River Delta manufacturing belt generates regional integrator demand for modular cross-belt configurations serving pharmaceutical and consumer electronics verticals.
India
Organized retail and e-commerce penetration below comparable Asian economies creates first-mover positioning for modular cross-belt entrants seeking phased capacity expansion. The PLI scheme for logistics infrastructure and BIS machinery safety certification requirements influence technology selection criteria. The Mumbai-Pune industrial corridor and Delhi-NCR warehousing clusters concentrate greenfield automation investments from international OEMs.
Japan
Precision manufacturing and pharmaceutical distribution networks demand contamination-sensitive handling configurations with linear synchronous motor propulsion. METI industrial automation roadmaps and JIS standards for material handling equipment guide specification development. The Osaka-Nagoya manufacturing belt sustains demand for high-throughput systems serving automotive component and medical device logistics.
Cross-Belt Sorters Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions, with consolidated procurement power among multi-site logistics operators compressing vendor rosters and unbundling service contracts from hardware sales. The vendor base stratifies into three strategic archetypes: European integrators with dense installed bases and captive service revenue streams, Asian manufacturers competing on production scale and regional supply chain proximity, and North American automation houses leveraging control-system integration across hardware and software layers. Dominant competitive moves include geographic expansion through regional integrator partnerships and technology licensing agreements that accelerate local certification pathways.
Among European-based system integrators, Vanderlande and Siemens occupy positions exemplifying divergent strategic postures—one leveraging dense brownfield service footprints, the other anchoring positioning through control-system integration spanning sortation hardware and warehouse software layers. Daifuku represents the Asian manufacturing-scale archetype with regional assembly plant proximity serving integrator networks across Asia-Pacific markets.
| Leading Market Players |
|---|
| Vanderlande |
| Siemens |
| BEUMER Group |
| Interroll Holding |
| Fives Intralogistics |
| Dematic |
| Honeywell Intelligrated |
| Muratec Machinery |
| Daifuku |
| Others |
Supply Flow & Price Mechanics
CE marking mandates under the EU Machinery Directive gate both qualified supply and premium-tier pricing access, as safety-rated control architectures require certified component sourcing that only a subset of European and Japanese automation suppliers can satisfy. OEMs without pre-certified safety PLC partnerships face extended compliance timelines that disqualify them from German third-party logistics procurement, while carriers with captive linear motor R&D programs capture pricing premiums for contamination-sensitive pharmaceutical and luxury goods applications.
Pricing Analysis
The bundled-vs-unbundled service split now defines competitive positioning, with tier-one logistics operators demanding outcome-based uptime guarantees that displace traditional time-and-materials maintenance agreements. Pricing stratifies across premium, standard, and economy tiers based on throughput certification thresholds and after-sales service bundling, with high-speed linear motor configurations commanding substantial premiums due to rare mechatronics talent requirements. Price erosion runs through standard-speed belt-and-pulley mechanics as Asian manufacturers expand regional assembly scale. Third-party logistics providers with multi-site networks exhibit lowest price sensitivity due to consolidated procurement power, while seasonal parcel carriers leasing mobile deployments show highest sensitivity to capital expenditure timing.
Supply Chain Analysis
Warehouse-distribution layer concentration in the Rhine-Ruhr corridor, Chicago-Indianapolis-Detroit triangle, and Yangtze River Delta manufacturing belt shapes component flow patterns for cross-belt sorter OEMs. Safety PLC and servo drive sourcing draws from German and Japanese industrial automation corridors, creating single-source exposure for carrier tray fabrication that rests on structural steel and aluminum inputs. Commodity price volatility in metals compresses margin predictability for tray manufacturers without backward integration into raw material procurement. Distribution runs through regional integrator networks that handle local certification pathways and commissioning labor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cross-belt sorters market functions as a stable compounder, with e-commerce parcel volume surges providing durable replacement-cycle visibility across brownfield fulfillment networks.
For Market Incumbents: Cement service revenue streams across aging European installed bases by front-loading CE marking compliance engineering before enforcement windows tighten. Acquire regional integrator partnerships in India to preempt modular configuration demand, as backward integration into linear motor R&D insulates against Japanese and German safety drive supplier concentration. For New Entrants and Emerging Players: Direct-to-customer digital sales channels bypass established integrator gatekeepers in underpenetrated Indian warehousing clusters. Target pharmaceutical cold-chain verticals with temperature-validated tray geometries that incumbent tilt-tray specialists lack. Pursue outcome-based leasing models for mobile surge-capacity deployments to match seasonal carrier cash-flow patterns. For Investors and Strategic Acquirers: Roll-up economics work for European mechatronics service specialists because brownfield commissioning talent scarcity prevents organic replication of field engineering capabilities. Five-to-ten year viability hinges on AMR substitution thresholds in micro-fulfillment footprints below fifty thousand square feet. Monitor OSHA lockout/tagout enforcement intensity as signal for US maintenance contract repricing windows.| Strategic Initiative | Industry Significance |
|---|---|
| Linear Motor R&D Expansion | Captive propulsion technology eliminates mechanical wear and enables pharmaceutical contamination-sensitive handling configurations. |
| Regional Integrator Partnership | Accelerates local CE marking and BIS certification pathways for modular entrants in Indian greenfield markets. |
| Outcome-Based Service Contract | Aligns vendor incentives with third-party logistics uptime requirements through penalty-guarantee structures. |
| Mobile Deployment Leasing Model | Matches seasonal parcel carrier surge capacity needs without permanent civil works investment. |
| Mechatronics Talent Acquisition | Addresses commissioning bottleneck for belt mechanics, servo tuning, and warehouse control software integration. |
Methodological Framework
Bottom-up e-commerce fulfillment modeling reconciled against top-down safety component supply tracking forms the analytical core of this study. Primary interviews with warehouse automation directors, third-party logistics procurement leads, OEM aftermarket service heads, and mechatronics commissioning engineers combined with secondary validation from EU Machinery Directive filings, OSHA standard revision dockets, SEC 10-K equipment disclosures, and customs trade data for steel and aluminum inputs. Triangulation between demand-side volume projections and supply-side capacity announcements ensures cross-verified output integrity.
Input-output matrices map carrier tray fabrication costs, safety PLC sourcing clusters, and regional labor rates against throughput-tiered pricing bands across the projection horizon. Segmentation dimensions modeled include product type throughput certification, installation foundation permanence, application vertical seasonality, and end-user consolidation scale. CAGRs derive from logistic curve penetration modeling for e-commerce automation intensity and replacement cycle analysis for aging European tilt-tray bases. Forecast inputs incorporate pharmaceutical cold-chain expansion trajectories and AMR displacement thresholds in micro-fulfillment footprints.
The model assumes a particular technology adoption path; alternative pathways for autonomous mobile robot singulation would alter the outlook for fixed-loop sorter demand in sub-fifty-thousand-square-foot facilities. Forecasts reflect documented assumptions regarding EU Machinery Directive enforcement timing and steel input price stabilization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Utility Automation Market
Industrial Automation
Programmable Logic Controller [PLC] Market
Industrial Automation
Middle East and Africa Industrial Automation Market
Industrial Automation
Smart Industries Market
Industrial Automation
Motion Control Market
Industrial Automation
Digital Industrial Scales Market
Industrial Automation
US Smart Manufacturing Market
Industrial Automation
Magnetic Grippers Market
Industrial Automation
Industrial Multiprotocol Gateways Market
Industrial Automation
United States SCADA Market
Industrial Automation
Global Blasting Automation Services Market
Industrial Automation
Factory Automation Platform As a Service Market
Industrial Automation
Global Automated Truck Loading System Market
Industrial Automation
Middle East and Africa Factory Automation and Industrial Controls Market
Industrial Automation
Motion Control Centers Market
Industrial Automation
Europe Intralogistics Automation Market