
 Global Feeder Automation Market | 2026-2036
Global Feeder Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Feeder Automation Market Intelligence
The divergence in R&D investment for advanced robotics and AI integration is bifurcating the competitive landscape. Large-scale providers like Siemens AG leverage extensive industrial automation portfolios to offer integrated solutions. In contrast, specialists such as Schweitzer Engineering Laboratories Inc. concentrate on high-reliability protection systems. ABB Ltd. competes through its leadership in robotics and motion control technology, targeting complex assembly tasks.
Feeder automation involves systems that automatically orient and supply individual components to processing lines. These systems utilize technologies like vibratory bowls or robotic arms to achieve placement accuracies essential for micro-assembly. Within product types, smart feeders integrating computer vision and machine learning are gaining significant traction. The electronics assembly application commands the largest market share, driven by the intricate component handling needs of smartphone and semiconductor manufacturing.
Compliance with machinery safety directives, including the EU’s CE marking and US OSHA regulations, is a prerequisite for market access. In parallel, China's GB standards for industrial equipment influence system design and component sourcing for manufacturers active in that market. Navigating these fragmented international standards while integrating advanced AI and robotics will determine vendor success.
Market Dynamics
The primary structural force shaping the market is the escalating need for sub-micron placement accuracy in electronics manufacturing, clashing with the high cost and complexity of integrating systems that comply with fragmented international safety standards like CE marking and OSHA.
Growth Catalysts
- Smart Feeder Integration:The incorporation of computer vision and machine learning into feeder systems enhances component recognition and reduces errors, directly supporting the intricate assembly requirements of the semiconductor industry.
- Consumer Electronics Miniaturization:Persistent demand for smaller, more powerful devices like smartphones requires feeder automation in advanced manufacturing clusters in China capable of handling increasingly smaller and more delicate components.
- Machinery Safety Mandates:Stricter regulations, including the EU’s CE marking requirements, compel manufacturers to upgrade or replace older, non-compliant feeder systems with modern automated solutions to maintain market access.
Market Restraints
- High Initial Capital Outlay:The substantial investment required for advanced robotic feeders and integrated computer vision systems creates a barrier for small and medium-sized electronics manufacturers, limiting adoption beyond large enterprises.
- Integration Complexity:Integrating new feeder automation systems with legacy manufacturing execution systems (MES) often leads to prolonged downtime and requires specialized engineering expertise, increasing total cost of ownership.
- Specialized Component Scarcity:Critical components for high-precision systems, such as specialized motion controllers and high-resolution sensors, are sourced from a concentrated group of suppliers, creating vulnerability to supply chain disruptions.
Strategic Opportunities
- Medical Device Micro-Assembly:The medical technology sector, particularly in manufacturing implantable devices and diagnostic tools, presents an opportunity for feeder systems designed for sterile environments and ultra-high reliability requirements.
- AI and Digital Twin Integration:Combining AI-driven predictive maintenance with digital twin simulations of the feeder system allows for process optimization and pre-emptive fault detection, creating a new value proposition for service-based contracts.
- Automotive Electronics in Mexico:As automotive manufacturing in Mexico incorporates advanced electronics, there is a nascent opportunity for deploying feeder automation to support local production of control units and infotainment systems.
Industry Challenges
- Skilled Technician Shortage:A deficit of technicians with expertise in both robotics and machine learning hinders the effective maintenance, calibration, and optimization of smart feeder systems on the factory floor.
- Navigating Divergent Standards:Simultaneously complying with China’s GB standards, the EU’s CE marking, and US OSHA regulations adds significant design, testing, and documentation overhead for system vendors operating globally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Feeder Automation Market |
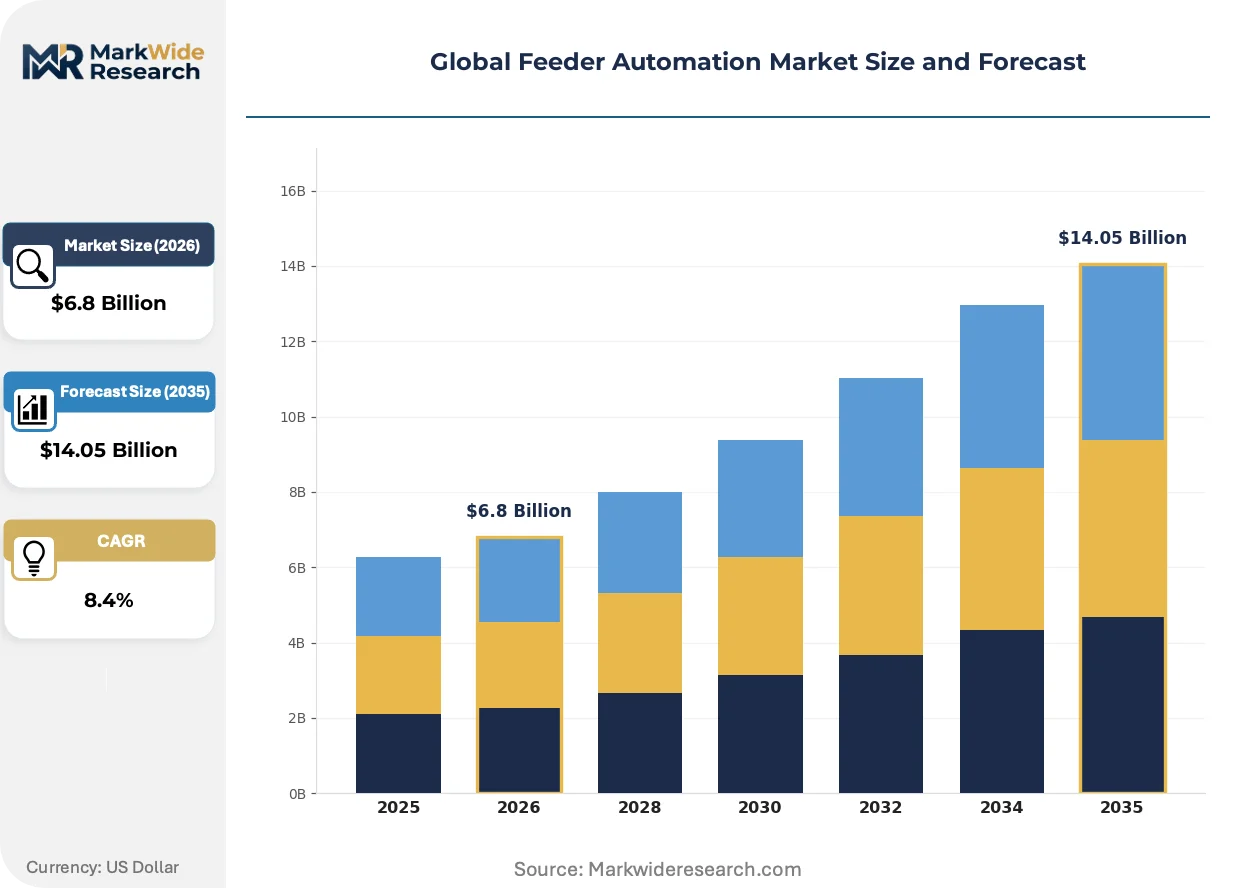
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Feeders, Pneumatic Feeders, Vibratory Feeders, Rotary Feeders, Electromechanical Feeders Technology: Computer Vision, Robotics, Artificial Intelligence, Machine Learning, Motion Control Application: Electronics Assembly, Pharmaceuticals Packaging, Food Processing, Automotive Component Handling, Textile Manufacturing End User Industry: OEMs, Contract Manufacturers, Aftermarket Providers, System Integrators, Research Institutions |
| Companies Covered | Honeywell International Inc., ABB Ltd., Hitachi Ltd., Schweitzer Engineering Laboratories Inc., Eaton Corporation PLC, Siemens AG, GE Vernova Inc., G&W Electric Co., Schneider Electric SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Feeder Automation Market Strategic Shifts & Innovations
System intelligence is becoming the primary axis of competition. The evolution from purely mechanical orientation to AI-enhanced, self-correcting systems defines the next generation of feeder automation, driven by demands for zero-defect production in micro-assembly.
Vibratory bowl feeders with integrated computer vision use high-frequency cameras to orient and inspect components in real-time. The electronics assembly sector is rapidly adopting this technology for microscopic surface-mount devices (SMDs). This fusion of vision and mechanics is miniaturizing the quality control stage by integrating inspection directly into the feeding process.
The forthcoming EU AI Act introduces risk-based classifications for artificial intelligence systems, including those in industrial robotics. This regulation is forcing vendors to invest in auditable, transparent machine learning models for component recognition and predictive maintenance. Vendors targeting Europe are prioritizing explainable AI (XAI) to ensure compliance and demonstrate system reliability.
End-users are moving from procuring standalone feeder units toward acquiring fully integrated, pre-validated assembly line modules. This trend favors large automation providers who can bundle feeders with placement machines, disrupting specialized, single-product manufacturers. This shift is most pronounced in high-volume electronics supply chains in China and Vietnam.
Global Feeder Automation Market Segmentation
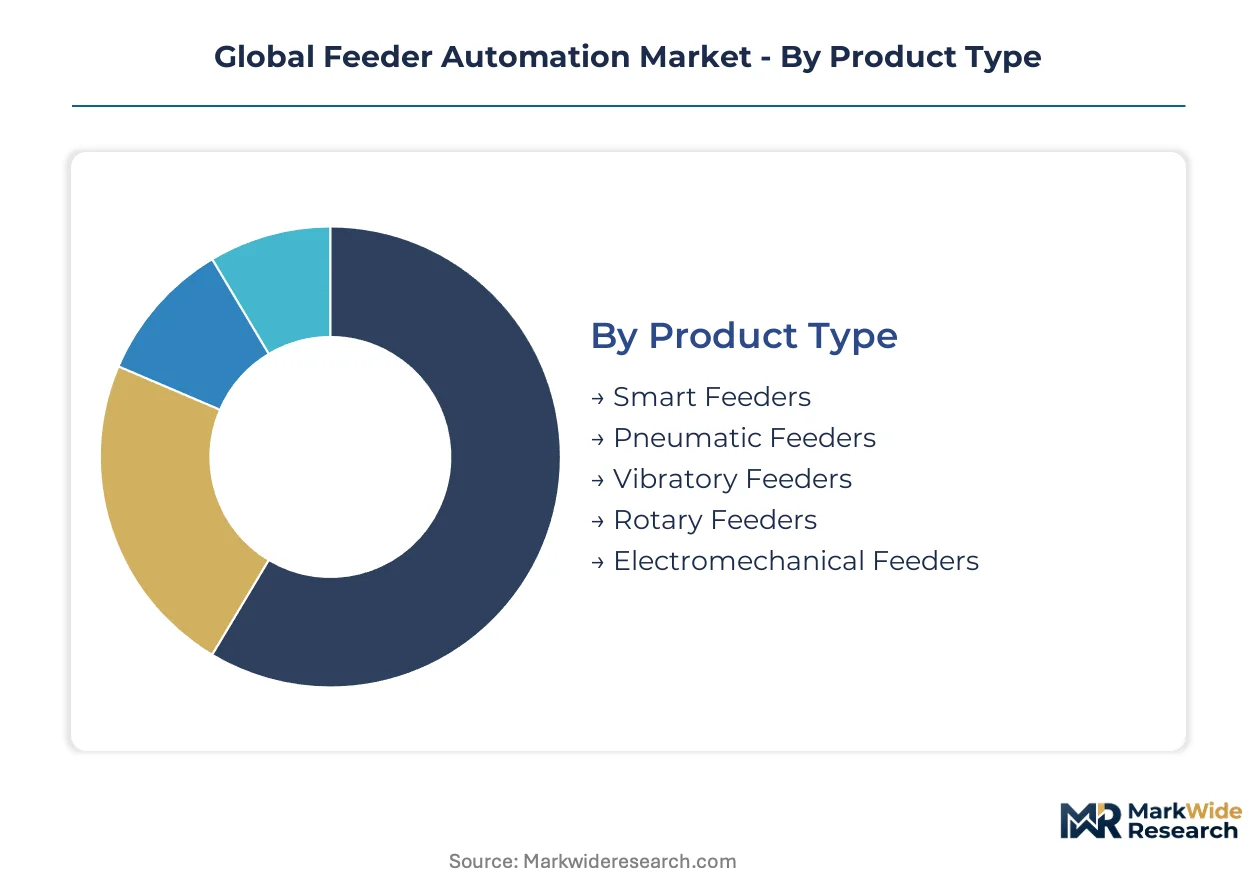
The segmentation of the global feeder automation market reveals the diverse requirements across industrial applications and technological capabilities. Understanding these distinct segments is crucial for identifying areas of concentrated demand and competitive differentiation, especially concerning component precision and system integration.
Product Type:
Feeder automation segments face varying degrees of substitution pressure from manual labor or alternative component handling methods, particularly in less precision-intensive applications.
- Smart Feeders:These advanced systems integrate computer vision, machine learning, and sensor technology for real-time component recognition, orientation, and quality inspection. Demand concentrates heavily within advanced manufacturing clusters in China for smartphone and semiconductor production, supporting sub-micron placement accuracy.
- Vibratory Feeders:Utilizing electromagnetic vibration to orient and feed components, these systems are a foundational technology for high-volume, repetitive tasks. This product type is widely deployed in automotive component handling in North America, driven by the need for consistent supply to assembly lines.
- Pneumatic Feeders:Employing compressed air for component handling, these systems are suitable for delicate or oddly shaped parts where mechanical contact is undesirable. They find use in medical device manufacturing in Germany, where sterile environments and precise, gentle handling are paramount.
- Rotary Feeders:These feeders use a rotating disc to sort and present components, offering a continuous and controlled feeding process. They are common in packaging lines for consumer goods in Mexico.
- Electromechanical Feeders:Combining electrical and mechanical principles for component delivery, these feeders offer precise control and are adaptable to various part sizes. They are often found in general industrial automation settings across Europe.
Vibratory Feeders anchor the volume base while Smart Feeders gain share at the steepest rate.
Technology:
Technology adoption in feeder automation is dictated by specific application requirements, ranging from high-speed sorting to precise micro-assembly.
- Robotics:This technology integrates articulated arms and grippers to pick, orient, and place components with high degrees of freedom and accuracy. Robotics are indispensable for complex assembly tasks in electronics manufacturing in South Korea, where intricate component handling is required.
- Computer Vision:Utilizing cameras and image processing algorithms, computer vision systems enable real-time identification, inspection, and orientation of components. This technology is critical for zero-defect production in micro-assembly operations in Japan, enhancing quality control.
- Artificial Intelligence:AI algorithms enhance feeder systems with capabilities such as predictive maintenance, adaptive process control, and optimized component recognition. AI integration is advancing in high-volume production lines in Taiwan, improving operational efficiency.
- Machine Learning:A subset of AI, machine learning allows feeder systems to learn from data, improving component recognition accuracy and reducing errors over time. This technology supports continuous improvement initiatives in semiconductor manufacturing in the US.
- Motion Control:Precision motion control systems manage the movement of feeder components, ensuring accurate positioning and smooth operation. These systems are fundamental to achieving the high placement accuracies required in precision engineering in Switzerland.
Robotics technology underpins complex assembly tasks, and artificial intelligence integration is expanding into predictive maintenance functions.
Application:
The maturity of feeder automation applications varies significantly, with established sectors driving volume and emerging areas demanding specialized solutions.
- Electronics Assembly:This application segment involves the high-precision feeding of miniature electronic components onto circuit boards and other substrates. It commands the largest market share, driven by the intricate component handling needs of smartphone manufacturing in China.
- Pharmaceuticals Packaging:Feeder automation ensures sterile and accurate handling of pills, vials, and medical devices during packaging processes. This application demands high reliability and adherence to strict regulatory standards, such as those from the FDA in the US.
- Food Processing:Automated feeders handle and sort various food items, from raw ingredients to packaged products, ensuring hygiene and efficiency. This application supports high-volume production in large food manufacturing plants across Europe.
- Automotive Component Handling:Feeder systems supply components like fasteners, sensors, and electronic modules to automotive assembly lines. This application is crucial for maintaining production speed and quality in car manufacturing facilities in Germany.
- Textile Manufacturing:Automated feeders manage the supply of raw materials and components to textile machinery, improving efficiency in fabric production. This application aids in the automation of garment factories in Vietnam.
Electronics Assembly remains the dominant application area, as pharmaceuticals packaging applications demonstrate rapid expansion.
End User Industry:
Different customer types within the feeder automation market prioritize distinct factors, from cost-efficiency for contract manufacturers to integration capabilities for OEMs.
- OEMs (Original Equipment Manufacturers):These manufacturers integrate feeder automation systems directly into their production lines for their own products. OEMs in the electronics sector, particularly in Japan, seek highly customized and seamlessly integrated solutions.
- System Integrators:These companies design, install, and commission complete automation solutions, often combining feeders with other machinery for end-users. System integrators play a critical role in deploying complex assembly lines in Mexico for automotive electronics.
- Contract Manufacturers:Businesses that produce goods for other companies use feeder automation to achieve high throughput and flexibility across diverse product lines. Contract manufacturers in Southeast Asia leverage these systems for cost-effective mass production.
- Aftermarket Providers:These entities supply replacement parts, upgrades, and maintenance services for existing feeder automation systems. Aftermarket services are vital for extending the lifespan of installed equipment in industrial facilities across the US.
- Research Institutions:Universities and corporate R&D centers utilize feeder automation for developing new manufacturing processes and testing advanced materials. These institutions in Germany often focus on developing next-generation robotics and AI applications.
OEMs represent a foundational customer segment, while system integrators increasingly provide comprehensive, customized solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for feeder automation systems varies significantly; high-precision electronics manufacturers exhibit lower price sensitivity due to critical accuracy requirements. This contrasts with more cost-conscious general industrial applications, influencing regional investment patterns and technology adoption rates. Global market dynamics reflect these varied needs.
China
China's electronics assembly sector drives substantial demand for smart feeders, particularly for smartphone and semiconductor production. Compliance with China's GB standards influences system design and component sourcing for manufacturers. Advanced manufacturing clusters in the Yangtze River Delta actively adopt these systems for intricate component handling.
United States
The United States sees strong demand for feeder automation in semiconductor manufacturing, driven by continuous improvement initiatives. US OSHA regulations mandate stringent safety standards for industrial machinery, compelling upgrades to automated systems. Silicon Valley and other tech hubs in California are focal points for machine learning integration in high-precision micro-assembly.
Germany
Germany's automotive and medical device sectors require highly reliable feeder systems for precision manufacturing. The EU’s CE marking requirements and the EU AI Act significantly influence industrial automation design and deployment. Bavaria's strong engineering base and medical technology clusters actively develop next-generation robotics and AI applications.
Japan
Japan's micro-assembly operations prioritize computer vision systems for zero-defect production in electronics manufacturing. METI guidelines encourage advanced manufacturing technologies, including AI-enhanced feeder systems, to maintain competitiveness. Industrial robotics centers in Aichi Prefecture are critical for developing complex assembly tasks requiring intricate component handling.
Global Feeder Automation Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, creating a tiered market structure for feeder automation systems. Large industrial automation providers offer comprehensive, integrated solutions, while specialized firms focus on high-reliability protection systems or niche component handling. The market also includes emerging players concentrating on smart feeder technologies. Companies are broadly pursuing portfolio diversification to capture adjacent market segments and strategic partnerships to integrate advanced AI and robotics capabilities.
Within the integrated solutions tier, Siemens AG, a German industrial automation conglomerate, and ABB Ltd., a Swiss-Swedish multinational robotics leader, exemplify comprehensive portfolio strategies. These firms leverage extensive industrial automation and robotics expertise to offer integrated feeder automation solutions, targeting complex assembly tasks. Schweitzer Engineering Laboratories Inc., a US-based specialist, represents the focused archetype, concentrating on high-reliability protection systems and niche component handling. These companies anchor different competitive vectors, shaping the market's technological direction and service offerings.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| ABB Ltd. |
| Hitachi Ltd. |
| Schweitzer Engineering Laboratories Inc. |
| Eaton Corporation PLC |
| Siemens AG |
| GE Vernova Inc. |
| G&W Electric Co. |
| Schneider Electric SE |
Cost & Logistics Intelligence
The shift from purely mechanical feeder components to smart feeders with integrated computer vision and machine learning reshapes supply geography and pricing economics. This transition pushes component sourcing towards advanced electronics manufacturing hubs in Asia.
Pricing Analysis
Aftermarket service contracts for predictive maintenance and system calibration drive significant lifetime value for feeder automation vendors. The market operates on a project-based pricing model, with customization levels for micro-assembly and integration complexity serving as key differentiation drivers. Pricing softness affects standard vibratory feeders due to increased competition from Asian manufacturers. Contract manufacturers in Southeast Asia exhibit the highest price sensitivity, while OEMs in Japan prioritize performance over initial cost.
Supply Chain Analysis
Concentrated sourcing of specialized motion controllers and high-resolution sensors from a few European and Japanese suppliers creates a chokepoint for high-precision feeder automation systems. The supply chain draws heavily from electronics manufacturing clusters in Taiwan, South Korea, and Germany for critical components. Single-source vulnerability for these advanced sensors poses a significant structural risk. Distribution runs through a network of system integrators and direct sales channels to OEMs globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The feeder automation market presents a capability-scarcity narrative, primarily driven by the deficit of technicians skilled in both robotics and machine learning. This talent gap hinders effective deployment and optimization of advanced smart feeder systems.
For Market Incumbents: Fortify core intellectual property in AI-driven component recognition and precision motion control to counter emerging specialist threats. Invest in localized training programs across key manufacturing hubs like China and Germany to address the skilled technician shortage. This proactive approach mitigates margin erosion from commoditized vibratory feeder systems and strengthens market access against new entrants focusing on niche applications.
For New Entrants and Emerging Players: CE marking fast-track pathways for medical device micro-assembly offer a critical entry point into the European market. Target underpenetrated applications in pharmaceuticals packaging in the US and general industrial automation in Europe, where compliance and reliability are paramount. A value-based go-to-market angle, emphasizing reduced operational errors and enhanced throughput, will resonate with small and medium-sized electronics manufacturers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-sized, private equity-backed specialists in computer vision and robotics integration. These firms often possess niche expertise in micro-assembly or sterile environment applications, offering long-term growth potential over a 5-10 year window. Watch for increased M&A activity driven by large automation providers seeking to acquire advanced AI capabilities as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch XAI-enabled Smart Feeders | Ensures compliance with the EU AI Act and enhances reliability for European customers. |
| Form Strategic MES Integration Partnerships | Reduces integration complexity and total cost of ownership for end-users. |
| Acquire Medical Device Automation Specialist | Expands market reach into high-reliability, sterile micro-assembly applications in Germany. |
| Expand Manufacturing Presence in Mexico | Supports nascent demand for feeder automation in the growing automotive electronics sector. |
| Invest in Global Safety Standard Certifications | Facilitates market access across diverse regions like the US, EU, and China. |
Research Approach
A standing panel of plant engineers, R&D directors, OEM procurement managers, and system integrators provided ongoing calibration for market sizing and trend validation. Primary interviews with these industry stakeholders were triangulated with extensive secondary validation. Secondary data sources included regulatory filings from the EU and US, technical specifications from leading component suppliers, and trade association reports. This approach ensured robust bottom-up and top-down market assessments.
All quantitative outputs underwent rigorous consistency checks against external industry benchmarks and historical growth patterns across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user industry, and regional manufacturing clusters. Compound annual growth rates were derived through a multi-factor regression analysis incorporating technological advancement and regulatory mandates. Forecast inputs included projected electronics miniaturization rates and machinery safety compliance timelines.
Underlying assumptions cover stable global trade policies and sustained electronics manufacturing growth, with deviation risk concentrated in geopolitical disruptions to critical component supply. Forecasts reflect these assumptions. Practitioners should keep alternative scenarios live as international trade relations and technology adoption rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Linear Motion System Market
Industrial Automation
Smart and Connected Elevators and Elevators Control Systems Market
Industrial Automation
India Warehouse Automation Market
Industrial Automation
Cold Storage AGV Market
Industrial Automation
Latin America Process Automation Market
Industrial Automation
Cross-Belt Sorters Market
Industrial Automation
Connected Worker Market
Industrial Automation
North America Machine Control System Market
Industrial Automation
Asia-Pacific Smart Manufacturing Market
Industrial Automation
Intralogistics Market
Industrial Automation
Motion Positioning Stages Market
Industrial Automation
Europe Warehouse Automation Systems Market
Industrial Automation
Pick and Place Machines Market
Industrial Automation
Europe Industrial Automation Software Market
Industrial Automation
Human Machine Interface (HMI) Market
Industrial Automation
Global Operational Technology Market