
 Programmable Logic Controller Market | 2026-2036
Programmable Logic Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Programmable Logic Controller Market Analysis
IEC 61131-3 compliance is reorganizing competitive entry in the programmable logic controller sector by mandating standardized programming languages and structured software architectures. Siemens AG leverages its embedded software ecosystem to sustain deep integration with industrial IoT platforms across European manufacturing bases. Rockwell Automation anchors its position through proprietary Logix control engines that dominate North American automotive assembly lines. Mitsubishi Electric specializes in compact motion-control PLCs that occupy high-speed packaging and semiconductor fabrication niches in East Asia.
A programmable logic controller is an industrial digital computer engineered for electromechanical process automation, typically executing ladder logic or structured text with scan cycles measured in milliseconds to ensure deterministic real-time control. The device integrates input/output modules, a central processing unit, and communication interfaces to govern machinery, assembly lines, and robotic cells in harsh operational environments. Modular PLC architectures capture the dominant share of capital-intensive process industries where scalability and redundancy justify higher unit costs, while compact PLCs penetrate small-to-medium machine builders seeking standardized control without engineering overhead. Safety PLCs represent the fastest-expanding product tier as functional safety certifications become mandatory in automotive welding and pharmaceutical batch operations.
The U.S. Occupational Safety and Health Administration and the European Union's Machinery Directive impose stringent fail-safe and electromagnetic compatibility requirements that force hardware redesigns and extend qualification timelines for new entrants. Japan's Ministry of Economy, Trade and Industry promotes industrial cybersecurity frameworks that reshape how PLC vendors architect network segmentation and encrypted fieldbus protocols. China's Ministry of Industry and Information Technology advances domestic GB standards that condition market access for foreign control-system suppliers. Stakeholders must monitor evolving cross-border certification reciprocity and determine whether regional compliance investments outweigh portfolio standardization benefits.
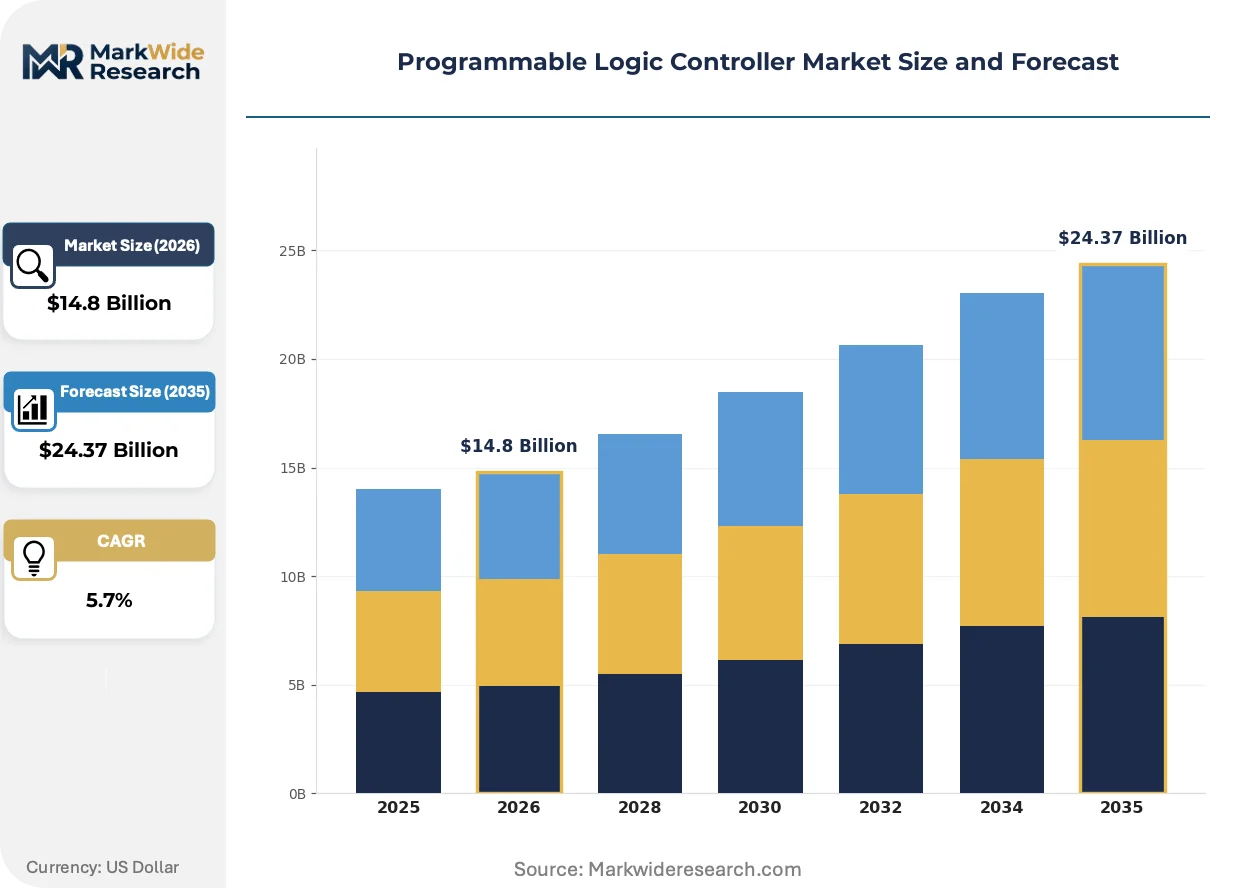
Market Dynamics
IEC 61131-3 compliance mandates and functional safety certifications are compressing product development timelines while elevating engineering qualification thresholds for PLC suppliers entering automotive and pharmaceutical automation contracts.
Growth Catalysts
- EU Machinery Directive:Mandatory fail-safe requirements in automotive welding cells force hardware upgrades across European manufacturing bases, expanding the addressable market for safety-certified control systems.
- Semiconductor fabrication:High-speed packaging lines in East Asia demand compact motion-control PLCs with sub-millisecond scan cycles, pulling specialized architectures into mainstream industrial adoption.
- Industrial IoT convergence:Embedded software ecosystems enabling cloud-native diagnostics are penetrating process industries where predictive maintenance contracts now specify networked control platforms.
Market Restraints
- Silicon supply concentration:Discrete semiconductor sourcing from concentrated East Asian foundries exposes PLC manufacturers to input volatility and extended lead times for processor modules.
- Proprietary protocol lock-in:Rockwell Automation's EtherNet/IP and Siemens' PROFINET create switching costs that fragment customer bases and limit second-source procurement flexibility.
- Legacy hardware persistence:Decades-old installed bases of relay-based controls in mature industrial regions delay replacement cycles and compress pricing power for mid-tier suppliers.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing are attracting control-system vendors to establish domestic assembly operations serving South Asian machine builders.
- Pharmaceutical batch automation:FDA 21 CFR Part 11 compliance requirements for electronic records are creating demand for validated PLC platforms with embedded audit trail functionality.
- Edge-to-cloud architectures:Convergence of time-sensitive networking with containerized runtime environments enables new service revenue streams through software-defined automation subscriptions.
Industry Challenges
- Functional safety engineering scarcity:TUV-certified programming specialists command premium compensation, constraining vendor capacity to deliver SIL-rated systems on contracted timelines.
- Cross-certification reciprocity gaps:Divergent electromagnetic compatibility test protocols between OSHA and EU notified bodies extend qualification timelines for unified product platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Programmable Logic Controller Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular PLC, Compact PLC, Rack-Mount PLC, Safety PLC Application: Manufacturing Automation, Process Control, Building Automation, Machine Control End User: Oil & Gas, Automotive, Food & Beverage, Pharmaceuticals Connectivity: Wired, Wireless, Ethernet, Fieldbus |
| Companies Covered | Siemens AG, Rockwell Automation Inc., Mitsubishi Electric Corporation, Schneider Electric, ABB Ltd., Omron Corporation, Honeywell International Inc., Emerson Electric Co., Delta Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Programmable Logic Controller Market Emerging Trajectories
Deterministic edge computing architectures and standardized runtime environments are dissolving the boundary between traditional PLCs and industrial PCs, forcing vendors to reposition around software value rather than hardware durability.
Time-sensitive networking over standard Ethernet is supplanting proprietary fieldbus protocols in motion-control applications. Automotive assembly integrators in Germany and Japan are specifying TSN-enabled drives to synchronize multi-axis robotics with microsecond precision. This convergence is compressing the market for dedicated motion controllers while elevating PLC vendors with deterministic networking stacks into premium positioning.
Japan's METI cybersecurity framework for critical infrastructure is mandating encrypted communication and network segmentation in control systems deployed to energy and water utilities. PLC vendors must architect hardware trust modules and certificate-based device authentication to qualify for public-sector procurement. East Asian suppliers are responding fastest, embedding security silicon directly into CPU modules rather than bolting on external gateways.
Machine builders are unbundling after-sales service contracts from hardware procurement, purchasing predictive maintenance and remote diagnostics as separate subscription tiers. German automotive OEMs now specify uptime guarantees rather than spare parts availability in control system tenders. This shift compresses upfront hardware margins while extending customer lifetime value for vendors with mature software platforms.
Programmable Logic Controller Market Segmentation
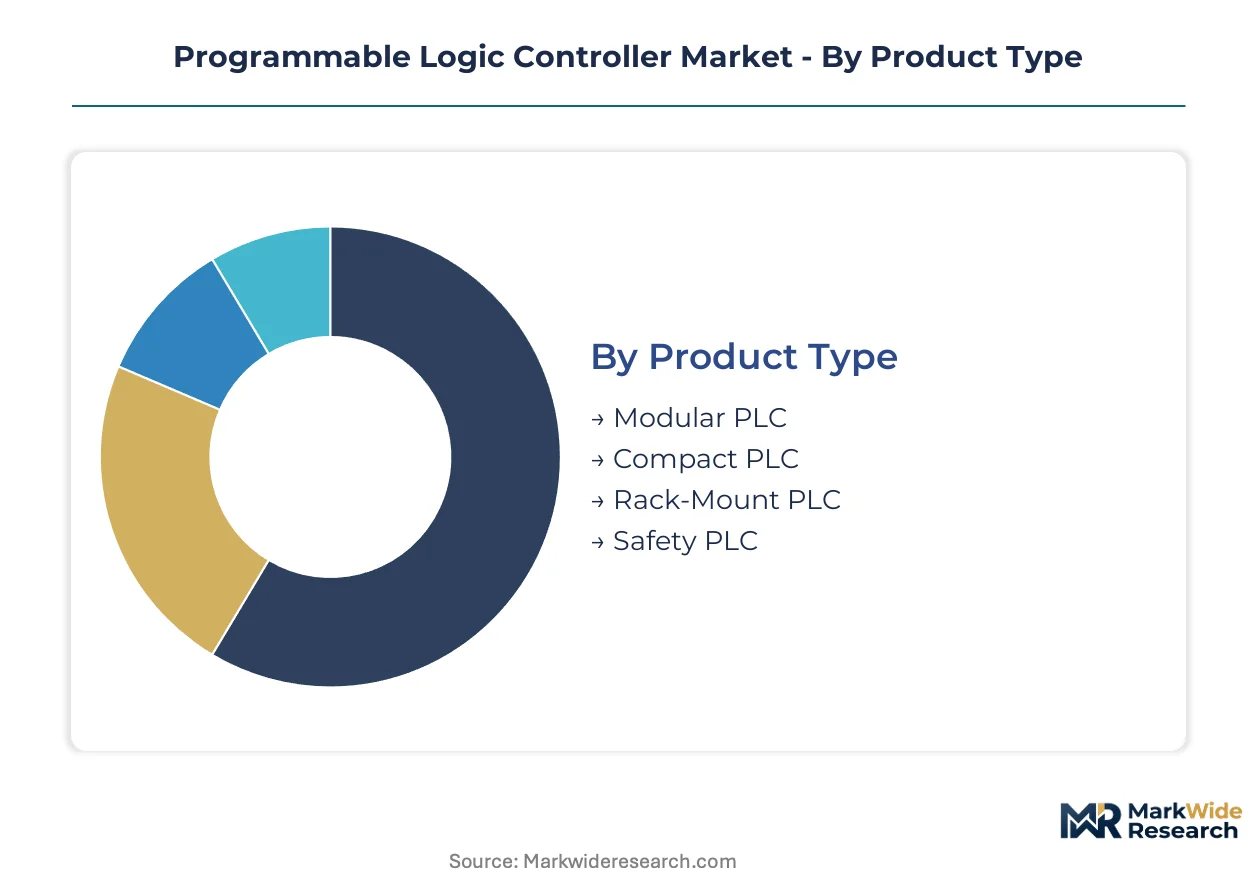
Segmentation in the programmable logic controller market reveals how regulatory mandates and application complexity reshape procurement patterns across industrial verticals. Product architectures diverge sharply based on safety certification requirements, while connectivity choices increasingly hinge on cybersecurity frameworks rather than purely technical performance.
Product Type:
Regulatory differentiation separates product tiers most sharply in functional safety certifications, where SIL ratings and EU Machinery Directive compliance create hardware redesign obligations that modular and safety PLCs must absorb.
- Modular PLC:Scalable chassis-based architectures accommodate redundant power supplies and hot-swappable I/O modules for continuous process industries. Demand concentrates in German chemical plants and US oil refineries where IEC 61511 safety lifecycle mandates justify premium hardware investments.
- Compact PLC:Integrated CPU-I/O units with fixed configurations serve machine builders seeking standardized control without engineering overhead. Japanese packaging OEMs and Italian textile machinery manufacturers specify these for cost-sensitive export equipment where space constraints dominate.
- Safety PLC:Redundant processor architectures with certified fail-safe logic monitor emergency stops and light curtains in automotive welding cells. TUV-certified platforms command engineering premiums as OSHA and EU notified bodies tighten inspection protocols.
- Rack-Mount PLC:Industrial PC form factors with PLC runtime environments bridge IT-OT convergence in semiconductor fabs. South Korean memory chip manufacturers deploy these for recipe management and statistical process control integration.
Modular PLC handles the majority of throughput; Safety PLC is the fastest mover on share.
Application:
Cost tier differentiation separates application segments, where capital intensity and downtime tolerance determine whether customers specify premium safety-certified platforms or standard control hardware.
- Manufacturing Automation:Discrete assembly lines for automotive and consumer electronics require deterministic scan cycles below 10 milliseconds. German OEMs specify TSN-enabled PLCs to synchronize multi-axis robotics with microsecond precision.
- Process Control:Continuous flow operations in petrochemicals and water treatment demand ruggedized hardware with extended temperature ranges. US Gulf Coast refineries prioritize intrinsic safety barriers and explosion-proof enclosures.
- Machine Control:Standalone equipment from packaging to metalworking uses compact PLCs with embedded motion functions. Italian and Taiwanese machine tool builders favor integrated servo control to reduce cabinet complexity.
- Building Automation:HVAC and lighting control in commercial facilities adopts BACnet and Modbus protocols over standard PLCs. Japanese smart building integrators specify low-power units for 24/7 operational efficiency.
Manufacturing Automation absorbs the largest capital allocation; Machine Control is expanding most quickly as OEMs consolidate controller architectures.
End User:
Customer type segmentation reflects how validation requirements and batch record obligations create sticky procurement relationships in regulated industries versus price-sensitive discrete manufacturing.
- Automotive:Welding, painting, and final assembly lines specify safety PLCs with Category 4/PLe ratings for collaborative robot cells. German and US transplant factories drive standardization around PROFIsafe and CIP Safety protocols.
- Pharmaceuticals:FDA 21 CFR Part 11 compliance mandates electronic signatures and audit trails in batch control systems. Irish and Swiss contract manufacturers validate PLC code changes through documented qualification protocols.
- Oil & Gas:Offshore platforms and pipeline compressor stations require hazardous area certifications and marine-grade enclosures. Norwegian North Sea operators specify SIL 3 emergency shutdown systems with 20-year service life guarantees.
- Food & Beverage:Washdown-rated PLCs with IP69K enclosures control filling, capping, and labeling equipment. Danish dairy cooperatives prioritize hygienic design with crevice-free stainless steel housings.
Automotive generates the highest unit volumes; Pharmaceuticals shows the steepest expansion trajectory as biosimilar manufacturing scales.
Connectivity:
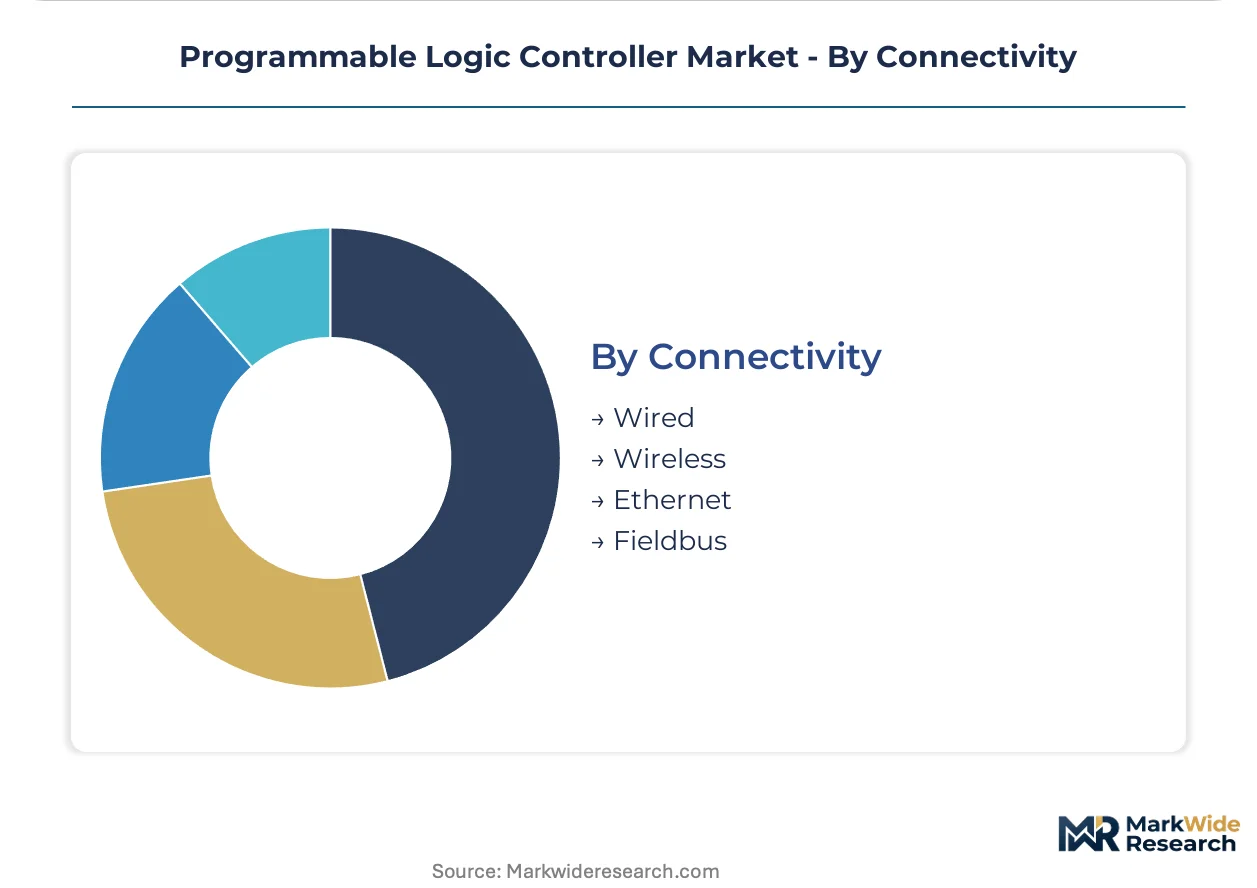
Maturity differentiation separates connectivity architectures, where legacy fieldbus installations persist in brownfield sites while greenfield deployments standardize on Ethernet variants with embedded security.
- Ethernet:PROFINET, EtherNet/IP, and EtherCAT dominate new machine builds with 100 Mbps to 1 Gbps bandwidth. German automotive integrators specify TSN extensions for time-synchronized motion control.
- Fieldbus:PROFIBUS DP and DeviceNet maintain installed bases in process industries where cable replacement costs deter migration. US chemical plants continue fieldbus investments to protect decade-old instrument infrastructure.
- Wireless:IEEE 802.11 Wi-Fi and 5G private networks enable mobile HMI tablets and temporary commissioning access. Japanese automotive plants deploy wireless for AGV fleet coordination.
- Wired:Point-to-point digital I/O and analog signaling persists in safety-critical loops where electromagnetic immunity overrides flexibility. Nuclear power regulators in France and the US mandate hardwired safety channels.
Ethernet carries the majority of new project specifications; Wireless is gaining share fastest as mobile operator interfaces proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs and Japanese semiconductor fabricators concentrate procurement authority for high-specification control systems, while US process industries sustain replacement demand for ruggedized hardware.
United States
OSHA mandates for collaborative robot safety and Gulf Coast refinery modernization sustain demand for SIL-rated modular PLCs. The Department of Energy's cybersecurity directives for critical infrastructure reshape procurement specifications in water and energy utilities. Houston's petrochemical corridor and Detroit's automotive welding clusters absorb premium safety-certified systems with 20-year service guarantees.
Germany
EU Machinery Directive enforcement and automotive export competitiveness drive TSN-enabled control platform upgrades. The country's national standards body and notified bodies under the Machinery Directive accelerate certification reciprocity negotiations with Japanese regulators. Bavaria's automotive assembly belt and Baden-Württemberg's machine tool builders specify PROFIsafe protocols for multi-axis robotics synchronization.
Japan
Semiconductor packaging line expansion and METI's industrial cybersecurity framework pull compact motion-control PLCs into high-volume deployment. The Ministry of Economy, Trade and Industry mandates encrypted fieldbus protocols and hardware trust modules for public-sector procurement qualification. Kyushu's memory chip fabs and Nagoya's automotive component suppliers deploy sub-millisecond scan cycle systems for precision motion tasks.
China
Domestic GB standards advancement and dual carbon goals in manufacturing reshape market access conditions for foreign control-system suppliers. The Ministry of Industry and Information Technology conditions import certification on local cybersecurity compliance testing. Yangtze River Delta electronics assemblers and Pearl River Delta automotive plants drive demand for validated platforms with embedded audit trail functionality.
India
Production-linked incentive schemes for electronics manufacturing attract control-system vendors to establish domestic assembly operations. The Bureau of Indian Standards and central electricity authority impose electromagnetic compatibility requirements that extend qualification timelines for imported hardware. Gujarat's automotive component clusters and Tamil Nadu's electronics manufacturing zones absorb compact PLCs for cost-sensitive export equipment.
Programmable Logic Controller Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with embedded software ecosystems, consolidated around three strategic archetypes: integrated automation platforms with proprietary fieldbus protocols, compact motion-control specialists serving high-speed manufacturing niches, and process industry incumbents with safety-certified hardware portfolios. Dominant competitive moves include strategic partnerships for edge-to-cloud architecture development and geographic expansion through domestic assembly investments in South Asian markets.
Among diversified European industrial groups, Siemens AG anchors the integrated platform tier with deep European manufacturing base penetration. Rockwell Automation Inc. occupies a parallel position in North American automotive assembly markets through proprietary control engine architectures. Mitsubishi Electric Corporation exemplifies the motion-control specialist archetype, serving East Asian semiconductor and packaging automation niches with compact deterministic systems.
| Leading Market Players |
|---|
| Siemens AG |
| Rockwell Automation Inc. |
| Mitsubishi Electric Corporation |
| Schneider Electric |
| ABB Ltd. |
| Omron Corporation |
| Honeywell International Inc. |
| Emerson Electric Co. |
| Delta Electronics Inc. |
| Others |
Supply Flow & Price Mechanics
Forty-five to sixty-day lead times for processor modules concentrate pricing power among East Asian foundry partners while forcing European and North American PLC vendors to absorb margin compression through inventory pre-positioning. This inventory burden elevates working capital requirements and compresses hardware margins for tier-two suppliers lacking volume leverage with semiconductor distributors.
Pricing Analysis
Cost-plus contracts indexed to LME copper and silicon wafer spot prices dominate procurement agreements between PLC vendors and automotive OEMs. Three-tier pricing structure across premium, standard, and economy levels separates TUV-certified safety platforms from general-purpose modular units and compact fixed-I/O controllers. Cost compression in compact PLCs is intensifying because Taiwanese and Korean machine builders are consolidating controller architectures at volume scale. Small-to-medium machine builders in India and Southeast Asia exhibit highest price sensitivity, while German automotive OEMs prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for industrial-grade microcontrollers and FPGA logic devices that feed PLC CPU module assembly. PLC manufacturing draws from concentrated sourcing of ARM-based processors from TSMC foundries, isolated DC-DC converters from Japanese suppliers, and precision resistive networks from Malaysian plants. Single-source vulnerability in 28nm automotive-grade silicon exposes vendors to allocation rationing during capacity crunches. Distribution runs through authorized industrial automation distributors with regional stocking hubs in Germany, the United States, and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against software-defined industrial PCs and edge-computing platforms that are dissolving traditional PLC boundaries through containerized runtime environments.
For Market Incumbents: Secure TUV-certified functional safety engineering capacity through captive training programs or specialist acquisitions before SIL-rated project backlogs constrain revenue recognition. Deepen backward integration into embedded security silicon to satisfy Japan's METI cybersecurity mandates and differentiate against software-centric substitutes. Prioritize PROFINET and EtherNet/IP protocol dominance through developer ecosystem investments that elevate switching costs for automotive and pharmaceutical customers. For New Entrants and Emerging Players: IEC 61131-3 programming certification fast-track through European notified body partnerships enables qualification for German automotive welding cell contracts within compressed timelines. Target India's PLI scheme electronics manufacturing zones for domestic assembly operations serving cost-sensitive South Asian machine builders. Lead with subscription-based predictive maintenance software bundled with compact PLC hardware to bypass entrenched fieldbus protocol lock-in. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because functional safety engineering scarcity and cross-certification reciprocity gaps favor scaled vendors with regulatory affairs infrastructure over fragmented mid-tier competitors. Acquisition targets should display embedded software platform maturity and established TUV/SIL certification pipelines. Watch for inflection when Japanese or European regulators mandate hardware trust modules as baseline procurement requirements, accelerating security-capable vendor concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-to-Cloud Architecture Partnership | Enables predictive maintenance subscriptions for German automotive OEMs specifying uptime guarantees. |
| Domestic Assembly Investment | Qualifies vendors for India's PLI scheme electronics manufacturing incentives serving South Asian exports. |
| Functional Safety Certification Pipeline | Accelerates TUV SIL-rated system delivery for EU Machinery Directive automotive welding cell mandates. |
| Hardware Trust Module Integration | Satisfies Japan METI cybersecurity frameworks for public-sector energy and water utility procurement. |
| TSN-Enabled Control Platform Launch | Captures German automotive multi-axis robotics synchronization specifying microsecond-precision motion. |
Methodological Framework
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this programmable logic controller analysis. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, IEC certification registries, EU Machinery Directive notification databases, and customs trade data for industrial automation equipment. Bottom-up unit economics triangulated against top-down macroeconomic drivers across the analysis window.
Sensitivity analysis tested volume and value outputs against semiconductor supply volatility, regulatory reciprocity scenarios, and industrial capex cycle timing. Segmentation dimensions modeled include product architecture tier, safety certification level, connectivity protocol, end-use vertical, and regional production cluster. CAGRs derived from historical shipment trajectories, replacement cycle analysis, and greenfield automation intensity indices. Forecast inputs incorporated automotive production schedules, pharmaceutical batch automation investment pipelines, and semiconductor fab equipment spending patterns.
Underlying assumptions cover continued IEC 61131-3 standard enforcement, stable East Asian foundry capacity allocation, and sustained EU Machinery Directive compliance tightening, with deviation risk concentrated in cross-border certification reciprocity breakdowns and discrete semiconductor supply disruptions. Recalibration cycles align with material shifts in regulatory mandate timing, foundry capacity expansion announcements, and automotive OEM platform standardization decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
Magnetic Grippers Market
Industrial Automation
Smart Warehouse System Market
Industrial Automation
Latin America Laboratory Automation Market
Industrial Automation
Industrial Automation Software Market
Industrial Automation
Refining Industry Automation and Software Market
Industrial Automation
US Smart Manufacturing Market
Industrial Automation
UK Industrial Automation System Integrator Market
Industrial Automation
Industrial Networking Solutions Market
Industrial Automation
Global Mining Automation Consumption Market
Industrial Automation
Liquid Handling Technology Market
Industrial Automation
Tilt Tray Sorter Market
Industrial Automation
Global Industrial Wireless Automation Market
Industrial Automation
Smart Elevator Automation System Market
Industrial Automation
Middle East and Africa Factory Automation and Industrial Controls Market
Industrial Automation
Industrial Robotic Motors Market
Industrial Automation
Asia-Pacific Smart Manufacturing Market