
 Smart Industries Market | 2026-2036
Smart Industries Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Industries Market Analytics
Industrial-grade AI certification standards are redrawing competitive boundaries in smart manufacturing. Siemens AG leverages its digital twin portfolio to anchor European factory automation. ABB Group sustains technology leadership through its robotics and motion divisions. Honeywell International, Inc. dominates process control systems across North American energy and chemical installations.
Smart Industries encompass cyber-physical production systems that integrate IoT sensors, edge computing nodes, and machine learning algorithms to enable real-time process optimization with sub-millisecond latency requirements. These systems serve the primary commercial purpose of converting operational data into autonomous control decisions that reduce unplanned downtime. IoT Sensors and Robotics together capture the largest share of hardware expenditure, though Data Analytics Platforms generate disproportionate margin pools through recurring software licensing. Edge Computing is expanding fastest among technology segments as manufacturers seek to minimize cloud dependency for safety-critical control loops.
The EU AI Act, GDPR, and ISO/IEC 27001 standards collectively determine product architecture and market access for European deployments, while the FDA and NHTSA shape requirements in US medical device and automotive applications. Compliance costs are filtering smaller platform vendors from tender processes for regulated end users. Stakeholders must evaluate whether to build sovereign cloud infrastructure or partner with hyperscalers as data residency rules tighten across jurisdictions.
Market Dynamics
The EU AI Act and GDPR compliance deadlines are forcing platform vendors to rebuild architecture from sensor firmware to cloud orchestration layers. Automotive predictive maintenance deployments at scale in Germany's industrial corridor demonstrate how regulatory pressure converts into procurement specifications that filter non-compliant suppliers from tender processes.
Growth Catalysts
- Automotive Predictive Maintenance Mandates:German automotive OEMs require sub-millisecond latency for safety-critical control loops, pulling edge computing hardware into factory automation specifications. Munich and Stuttgart industrial clusters anchor this demand concentration.
- EU AI Act Conformity Requirements:High-risk AI system classifications for industrial process control create mandatory certification pathways that favor established platform vendors with compliance infrastructure already deployed.
- ISO/IEC 27001 Integration:Information security management system certification is becoming a table-stakes requirement for smart manufacturing tenders across European energy and chemical installations.
Market Restraints
- Semiconductor Supply Concentration:Edge computing node production depends on advanced foundry capacity concentrated in Taiwan and South Korea, exposing automation projects to geopolitical supply disruption risk.
- GDPR Data Residency Friction:Cross-border data transfer restrictions between EU member states and third countries complicate cloud-based analytics platform architectures, increasing compliance engineering overhead.
- Legacy Brownfield Integration Costs:Retrofitting cyber-physical systems into existing process control environments requires custom protocol gateways that extend deployment timelines and inflate project budgets.
Strategic Opportunities
- France Industrial Corridor Expansion:Lyon and Grenoble manufacturing clusters show underpenetrated demand for digital twin implementations in aerospace and precision equipment sectors.
- CSRD Reporting Integration:Corporate Sustainability Reporting Directive mandates are creating pull for energy optimization analytics that smart manufacturing platforms can embed as differentiated features.
- 5G-TSN Convergence:Time-Sensitive Networking over private 5G cellular infrastructure enables wireless safety-critical control loops previously requiring fixed Ethernet, opening mobile robotics applications.
Industry Challenges
- OT-IT Security Skill Scarcity:Operational technology cybersecurity expertise sits at the intersection of industrial engineering and information security, with qualified practitioners concentrated among systems integrators rather than end users.
- AI Act Certification Timeline Compression:Conformity assessment body capacity for high-risk AI system validation is constrained relative to vendor submission volumes, creating approval bottlenecks.
- Multi-Vendor Interoperability Friction:Proprietary digital twin data formats from competing automation platforms resist standardization, complicating brownfield integration projects that mix supplier ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Industries Market |
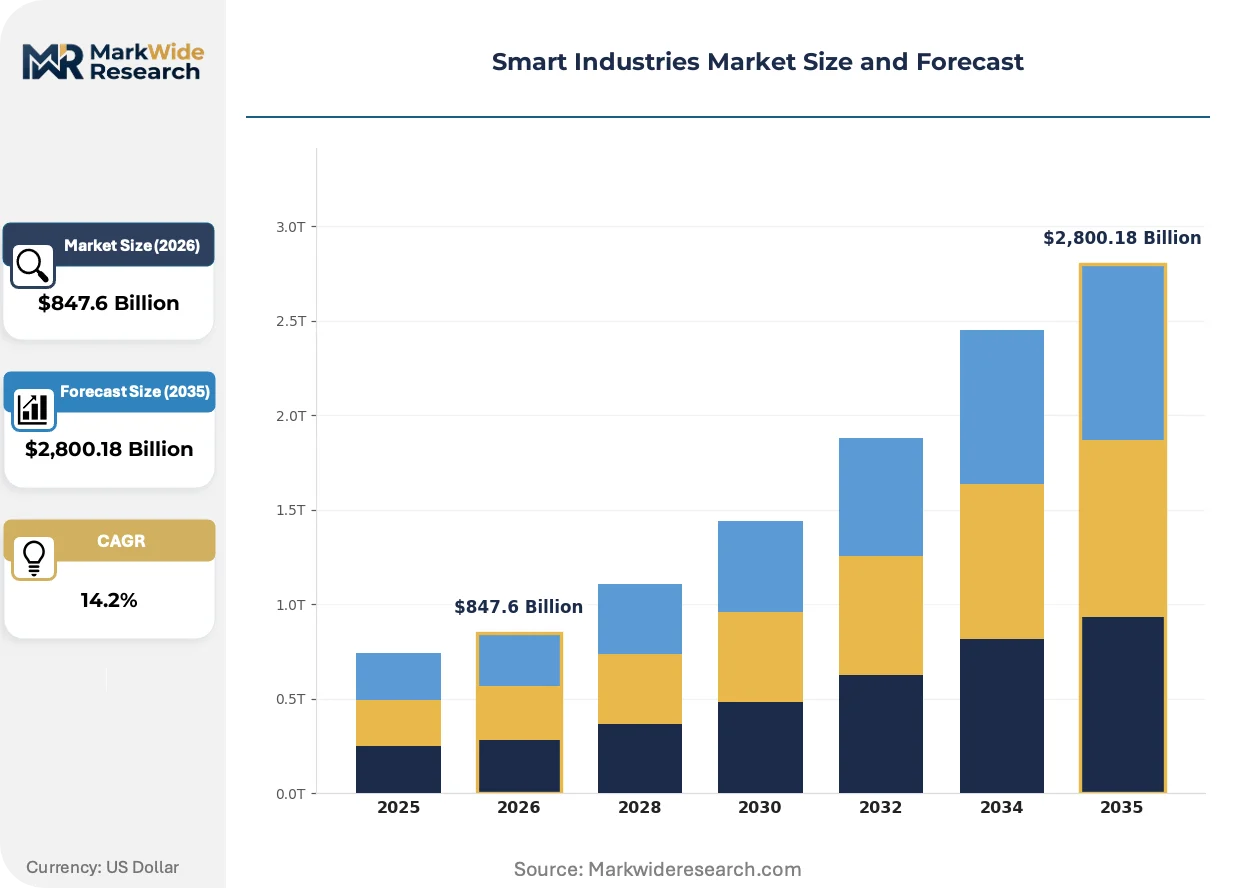
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $2,800.18 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IoT Sensors, Robotics, Automation Software, Data Analytics Platforms Technology: Artificial Intelligence, Machine Learning, Cloud Computing, Edge Computing End User: Manufacturers, Supply Chain, Energy Utilities, Telecommunications Application: Predictive Maintenance, Smart Metering, Asset Tracking, Process Optimization |
| Companies Covered | Siemens AG, ABB Group, Honeywell International, Inc., Rockwell Automation, Inc., Schneider Electric SE, General Electric Co., Emerson Electric Co., Mitsubishi Electric Corporation, Fanuc Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Industries Market Evolving Landscape
Edge-native AI inference is redrawing the boundary between factory floor and cloud infrastructure. Real-time process optimization requirements are compressing decision latency tolerances below what centralized architectures can deliver.
Time-Sensitive Networking over Ethernet is supplanting legacy fieldbus protocols in automotive and aerospace assembly lines. BMW Group and Airbus suppliers are mandating TSN-compatible device profiles in new equipment specifications. This transition is compressing the addressable market for Profibus and Modbus gateway vendors while expanding opportunity for switch and controller suppliers with deterministic scheduling silicon.
The EU AI Act's high-risk system classification for industrial process control entered force with staggered implementation deadlines through 2026. Conformity assessment requirements are reshaping R&D roadmaps toward explainable AI architectures that satisfy human oversight mandates. German automotive and French aerospace suppliers are most affected, with certification engineering now consuming 15-20% of platform development budgets.
Buyers are unbundling predictive maintenance software from hardware procurement, forcing automation vendors to prove standalone analytics value. Automotive OEMs in Stuttgart now license condition monitoring algorithms separately from sensor and edge gateway purchases. This shift is most visible in Germany, where procurement functions have consolidated vendor management under chief digital officer oversight rather than plant engineering.
Smart Industries Market Segmentation
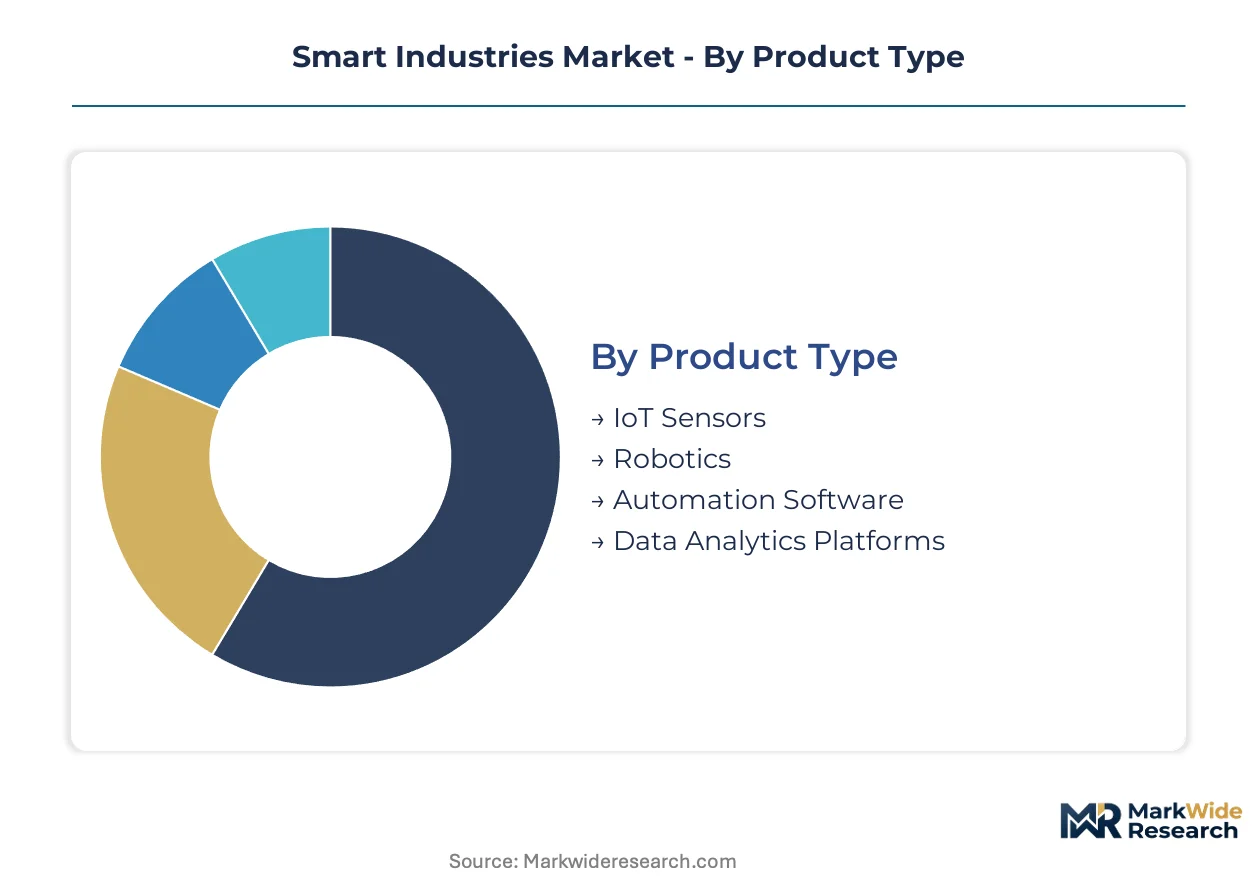
Smart Industries procurement splits across four intersecting dimensions, each carrying distinct margin profiles and compliance burdens. Buyers increasingly unbundle hardware from software licensing, forcing vendors to defend value at every tier independently.
Product Type:
IoT Sensors face acute substitution pressure from integrated edge nodes that embed sensing, compute, and connectivity in single enclosures. Robotics and Automation Software resist this pressure through proprietary kinematics and safety certification lock-in.
- IoT Sensors:Discrete temperature, vibration, and pressure transducers with standardized 4-20mA or digital outputs. German automotive OEMs in Stuttgart and Munich are consolidating sensor specifications to reduce vendor counts, favoring suppliers with pre-certified edge-to-cloud stacks.
- Robotics:Articulated arms, collaborative cobots, and autonomous mobile robots with force-limiting and vision-guidance subsystems. ABB Group and KUKA anchor European demand through automotive welding and assembly deployments that require ISO 10218 safety validation.
- Automation Software:SCADA, MES, and PLC programming environments with deterministic runtime engines. Honeywell dominates North American process control installations with bundled hardware-software procurement.
- Data Analytics Platforms:Cloud-native and edge-deployable inference engines for time-series anomaly detection. Recurring SaaS licensing generates disproportionate margin pools relative to hardware attach rates.
IoT Sensors retain volume leadership; Data Analytics Platforms hold the steepest expansion curve.
Technology:
Cost tiering separates commodity cloud infrastructure from premium edge silicon with deterministic latency guarantees. AI and ML layers command software margin multiples above hardware-centric deployments.
- Artificial Intelligence:Deep learning and symbolic reasoning architectures for vision inspection, predictive diagnostics, and autonomous decisioning. EU AI Act high-risk system classifications are forcing explainability features into industrial AI roadmaps.
- Machine Learning:Supervised and unsupervised statistical models for equipment degradation forecasting. Edge-native ML inference is displacing cloud-dependent training pipelines in safety-critical control loops.
- Cloud Computing:Hyperscaler-hosted data lakes and training clusters with elastic compute scaling. GDPR data residency requirements are fragmenting cloud architectures across EU member state boundaries.
- Edge Computing:Distributed inference nodes with sub-millisecond latency guarantees for real-time process control. Time-Sensitive Networking over Ethernet is expanding addressable applications beyond fixed-cable installations.
Cloud Computing retains volume leadership; Edge Computing holds the steepest expansion curve.
End User:
Application maturity varies sharply across customer types, with Energy Utilities running decade-old AMI deployments while Manufacturers greenfield cyber-physical systems.
- Manufacturers:Discrete and process industry producers deploying digital twins and predictive maintenance across brownfield and greenfield assets. France's Lyon-Grenoble aerospace cluster shows underpenetrated demand for integrated platform rollouts.
- Supply Chain:Third-party logistics providers and contract manufacturers seeking asset visibility across distributed networks. 5G-TSN convergence is enabling mobile robotics applications previously blocked by fixed infrastructure requirements.
- Energy Utilities:Grid operators and generation asset managers with AMI, SCADA, and distributed energy resource management mandates. FERC Order 2222 in the US and EU Clean Energy Package are accelerating platform procurement cycles.
- Telecommunications:Network operators deploying private 5G and edge data centers for industrial verticals. CSRD reporting integration is creating pull for energy optimization analytics as differentiated service offerings.
Manufacturers retain volume leadership; Supply Chain holds the steepest expansion curve.
Application:
Customer procurement patterns favor outcome-based contracts in Predictive Maintenance while Smart Metering remains hardware-centric with long replacement cycles.
- Predictive Maintenance:Condition-based monitoring and failure forecasting algorithms that convert vibration, thermal, and electrical signature data into maintenance schedules. BMW Group and Airbus suppliers are mandating TSN-compatible device profiles in new equipment specifications.
- Smart Metering:AMI endpoints with two-way communication for demand response and outage management. European deployments face GDPR friction on granular consumption data sharing between utilities and third-party energy service providers.
- Asset Tracking:Indoor and outdoor location systems using RFID, UWB, and GPS for inventory and equipment positioning. Brownfield integration costs inflate project budgets through custom protocol gateway requirements.
- Process Optimization:Real-time setpoint adjustment and quality feedback loops using AI-driven control algorithms. ISO/IEC 27001 certification is becoming table-stakes for tender participation in regulated European installations.
Smart Metering retains volume leadership; Predictive Maintenance holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advanced foundry capacity for edge silicon concentrates in Taiwan and South Korea, creating supply vulnerability for automation projects worldwide. Germany's industrial corridor absorbs disproportionate platform investment as EU regulatory deadlines approach. China's state-directed smart manufacturing push accelerates domestic substitution in process control systems.
United States
FERC Order 2222 and grid modernization mandates drive utility procurement of distributed energy resource management platforms. The FDA and NHTSA shape requirements for medical device and automotive AI deployments. Houston's energy corridor and Detroit's automotive cluster anchor process control and predictive maintenance demand respectively.
Germany
Automotive OEMs in Stuttgart and Munich mandate sub-millisecond latency specifications for safety-critical control loops. The EU AI Act and GDPR compliance deadlines filter non-certified vendors from tender processes. Bavaria's industrial automation ecosystem concentrates digital twin implementations at BMW Group and Airbus suppliers.
China
MIIT smart manufacturing directives accelerate domestic platform substitution in steel and chemical process control. GB standards and dual carbon goals reshape R&D roadmaps toward energy optimization analytics. The Yangtze River Delta manufacturing belt anchors greenfield cyber-physical system deployments at scale.
France
The Lyon-Grenoble aerospace cluster shows underpenetrated demand for integrated digital twin rollouts in precision equipment. ANSM and CNIL data governance requirements complicate cross-border platform architectures. Île-de-France hosts headquarters of global automation vendors serving regulated European installations.
Japan
METI Society 5.0 initiatives fund edge-native AI inference for semiconductor and automotive assembly lines. JIS standards and PMDA medical device regulations shape product certification pathways. The Chubu-Nagoya manufacturing corridor concentrates robotics and motion control system demand from Toyota suppliers.
Smart Industries Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated automation platforms commanding premium positioning against modular component suppliers. The vendor base splits between full-stack systems integrators and specialized hardware or software pure-plays. Two dominant archetypes emerge: European industrial conglomerates with century-long factory automation heritage, and Asian electronics manufacturers leveraging semiconductor supply chain proximity. Competitive moves concentrate on M&A for digital twin capabilities and strategic partnerships for edge computing silicon.
Among European-based industrial conglomerates, Siemens AG and ABB Group occupy positions as archetypal full-stack platform vendors, while Honeywell International, Inc. anchors North American process control specialization. These three exemplify how regulatory compliance infrastructure becomes a defensive moat as EU AI Act deadlines approach. Each represents a distinct geographic origin—German, Swiss-Swedish, and American—that shapes their respective regulatory engagement strategies and customer relationship patterns in regulated verticals.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Group |
| Honeywell International, Inc. |
| Rockwell Automation, Inc. |
| Schneider Electric SE |
| General Electric Co. |
| Emerson Electric Co. |
| Mitsubishi Electric Corporation |
| Fanuc Corporation |
| Others |
Value Network & Pricing Analysis
EU AI Act high-risk system certification gates both supplier qualification and price stratification in industrial automation procurement. German automotive OEMs now mandate pre-certified edge-to-cloud stacks that filter uncertified vendors from tender processes while commanding premium pricing for compliant platforms.
Pricing Analysis
EU AI Act conformity requirements dictate the pricing tier structure across European smart manufacturing deployments. Three-tier pricing structure across premium, standard, and economy levels separates certified high-risk AI systems from uncertified alternatives and commodity sensor hardware. Price differentiation rests on ISO/IEC 27001 certification status and edge-native latency guarantees. Cost compression in standard-tier IoT sensors is intensifying because integrated edge nodes are displacing discrete transducers. Small-to-mid manufacturers show highest price sensitivity, while energy utilities prioritize compliance over unit economics.
Supply Chain Analysis
Inventory buffers for edge computing silicon have extended to 26-32 weeks as foundry capacity constraints persist. Advanced node production draws from Taiwan, South Korea, and USA, with 5nm and 7nm wafers feeding AI inference chip architectures. Raw material dependencies span rare earth elements for magnetics, high-purity silicon substrates, and specialty gases for EUV lithography. Single-source vulnerability concentrates in TSMC's leading-edge capacity. Distribution runs through authorized distributors serving systems integrators rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source robotics middleware and cloud-native control platforms threaten incumbent automation vendors with disintermediation. Incumbents must defend against substitution by hardening proprietary value around certification infrastructure and deterministic performance guarantees.
For Market Incumbents: Compound regulatory compliance moats by embedding EU AI Act conformity assessment into platform architectures before deadline compression intensifies. Deepen backward integration into edge silicon supply through strategic foundry partnerships that secure capacity allocation. Prioritize digital twin format standardization to reduce multi-vendor interoperability friction that delays brownfield projects.
For New Entrants and Emerging Players: Anchor in France's Lyon-Grenoble aerospace cluster where digital twin penetration lags German automotive benchmarks. Target predictive maintenance analytics unbundled from hardware procurement, licensing algorithms separately to procurement functions under chief digital officer oversight. Pursue 5G-TSN convergence applications for mobile robotics that incumbent fixed-cable architectures cannot address.
For Investors and Strategic Acquirers: EU AI Act implementation deadlines reshape the acquisition landscape toward targets with deployed conformity assessment infrastructure. Five-to-ten year viability favors mid-cap platform vendors with automotive certification track records and recurring SaaS revenue components. Watch conformity assessment body capacity expansion as the inflection signal for certification timeline normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Acquisition | Siemens and ABB consolidate proprietary data format control across European factory automation ecosystems. |
| Edge Computing Foundry Partnership | Secures advanced node capacity allocation for sub-millisecond inference silicon amid Taiwan supply concentration. |
| EU AI Act Certification Investment | Consumes 15-20% of platform R&D budgets for explainable AI architectures satisfying human oversight mandates. |
| 5G-TSN Infrastructure Deployment | Enables wireless safety-critical control loops previously blocked by fixed Ethernet requirements at BMW suppliers. |
| CSRD Reporting Integration | Embeds energy optimization analytics as differentiated features for corporate sustainability disclosure compliance. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, EU regulatory submissions, and hyperscaler capex disclosures. Primary interviews engaged plant engineers, OEM procurement teams, aftermarket service heads, and integration specialists across Germany, France, and USA manufacturing corridors. Secondary validation drew from customs data, ISO certification registries, and automotive supplier specifications. Bottom-up unit economics triangulate against top-down market sizing across technology and end-user segments.
Segmentation dimensions modeled include product type, technology layer, end-user vertical, and application function across the projection horizon. CAGRs derive from regression analysis of historical procurement cycles and regulatory deadline impacts. Forecast inputs incorporate edge computing node shipment trajectories and EU AI Act implementation phase transitions. Automotive predictive maintenance deployment rates and brownfield integration cost curves inform scenario weighting.
Decision-makers should treat outputs as directional under assumptions of sustained foundry capacity constraints and regulatory timeline adherence; material deviation would warrant model refresh. Forecasts reflect base-case assumptions without contingency for geopolitical supply disruption or certification body capacity collapse. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Automation
North America Industrial Vending Machine Market
Industrial Automation
Supervisory Control and Data Acquisition (SCADA) Market
Industrial Automation
Global Intelligent Completion Market
Industrial Automation
Asia-Pacific Medical Automation Market
Industrial Automation
Global Distribution Feeder Automation System Market
Industrial Automation
North America Process Automation Market
Industrial Automation
Warehousing Automation Equipment Market
Industrial Automation
Industrial Automation Device Manager Software Market
Industrial Automation
Factory Automation in Japan Market
Industrial Automation
Asia Pacific Factory Automation and Industrial Controls Market
Industrial Automation
HMI Market
Industrial Automation
Automatic Screw Feeding System Market
Industrial Automation
Conveyor Sorting Systems Market
Industrial Automation
Human Machine Interface (HMI) Market
Industrial Automation
Material Handling Robotics Market
Industrial Automation
Warehouse Automation Systems Market